
 Rigid Inflatable Boats (RIB) Market | 2026-2036
Rigid Inflatable Boats (RIB) Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Inflatable Boats (RIB) Market Analysis
European hull fabricators is consolidating output around advanced composite tube technologies and modular deck systems. BRIG leverages Ukrainian and Polish manufacturing partnerships to sustain cost-competitive production across mid-size rescue and leisure categories. Zodiac anchors its position through French defense and coast guard contracts, while Highfield Boats dominates aluminum-hull RIB exports to Australasian and North American dealers.
Rigid Inflatable Boats combine a solid hull—typically fiberglass, aluminum, or polyethylene—with pressurized inflatable collar tubes, achieving planing speeds above 40 knots in craft under 8 meters while retaining positive buoyancy if swamped. The product type dimension shows rescue boats and commercial boats commanding the strongest margin pools due to specification-intensive procurement cycles, whereas leisure boats face volume competition from PVC-based entry-level imports. Within the size dimension, medium vessels between 5 and 8 meters represent the fastest-growing configuration, balancing offshore capability with trailerable logistics for government and tour operator buyers.
ISO 6185 sets global inflatable craft construction and pressure-testing benchmarks, while the EU Recreational Craft Directive and CE marking enforce stability and emissions compliance for vessels sold within member states. The US Coast Guard's small passenger vessel regulations and EPA marine engine standards shape product access in North American waters. Stakeholders must track evolving decarbonization mandates for outboard propulsion and the shift toward electric and hydrogen fuel-cell powertrains in coastal patrol specifications.
Market Dynamics
Coastal defense agencies across the Mediterranean and Baltic corridors are accelerating fleet modernization programs, pulling specification-intensive RIB procurement toward modular deck architectures and composite tube systems that accommodate mission reconfiguration.
Growth Catalysts
- EU Recreational Craft Directive:Updated stability and emissions mandates for inflatable hull construction are filtering substandard PVC imports from charter markets, elevating certified manufacturers.
- Maritime patrol agencies:Interdiction and emergency response mandates in Italy, Greece, and Spain are expanding medium-vessel RIB fleets for high-speed boarding operations.
- Aluminum hull fabrication:Polish and Ukrainian metalworking partnerships are sustaining cost-competitive production of trailerable 5-8 meter configurations for government and tour operator buyers.
Market Restraints
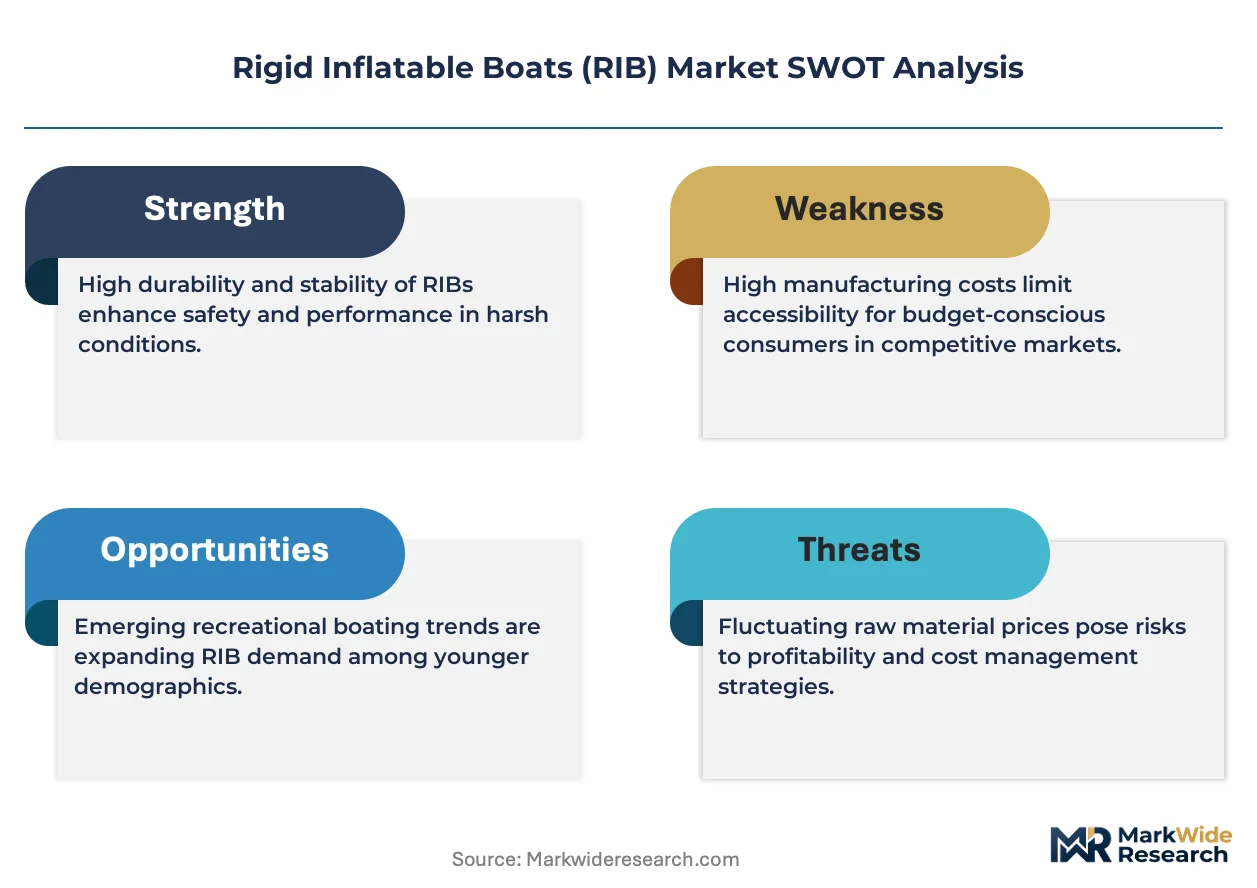
- Hypalon fabric supply concentration:Dependence on a narrow supplier base for chlorosulfonated polyethylene tube material creates vulnerability to petrochemical feedstock volatility.
- ISO 6185 compliance timelines:Pressure-testing and construction certification requirements extend product development cycles, compressing margin recovery windows for new entrants.
- Rigid-hull fishing skiffs:Lower-cost polyethylene workboats are displacing entry-level RIBs in small-scale commercial fishing fleets across North African and Southeast Asian markets.
Strategic Opportunities
- Electric outboard convergence:Battery-electric and hydrogen fuel-cell propulsion trials in Norwegian and Danish coastal patrol specifications are opening early-mover positioning for powertrain-integrated hull designers.
- Modular deck systems:Mission-swappable seating, console, and equipment mounting architectures are penetrating Mediterranean charter hubs seeking off-season rescue-contract revenue.
- CE marking harmonization:Simplified conformity assessment pathways under updated EU directives are reducing market access friction for Baltic and Adriatic fabricators.
Industry Challenges
- Composite technician scarcity:Advanced tube lamination and adhesive bonding expertise concentrates among aging workforces in French and Italian boatyards, constraining output scaling.
- Multi-standard certification:Parallel compliance with US Coast Guard small passenger vessel regulations and EPA marine engine standards fragments engineering resources for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Inflatable Boats (RIB) Market |
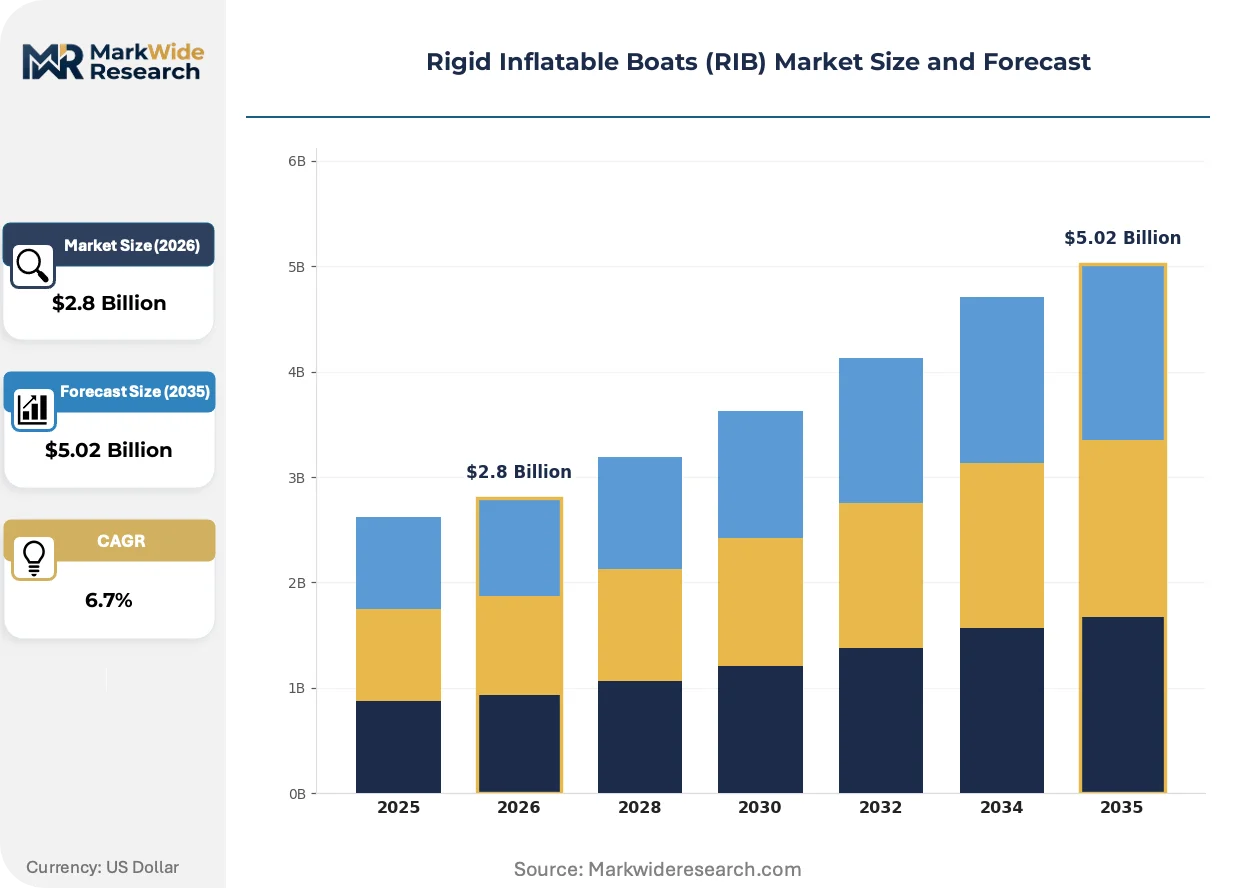
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sport Boats, Rescue Boats, Commercial Boats, Leisure Boats End User: Government Agencies, Marine Research Institutions, Tour Operators, Private Individuals Size: Small Vessels, Medium Vessels, Large Vessels, Super Vessels Material: Hypalon, PVC, Neoprene, Polyethylene |
| Companies Covered | BRIG, Protector, Highfield Boats, Ribcraft, Ribco, Zodiac, GRAND Boats, Sacs Marine, AB Inflatables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Inflatable Boats (RIB) Market Emerging Trajectories
Propulsion decarbonization and mission modularity are compressing traditional hull-propulsion boundaries, forcing fabricators to integrate powertrain architecture into early-stage design rather than treating outboards as bolt-on components.
Carbon-reinforced polyethylene hull laminates are absorbing impact loads previously requiring aluminum or fiberglass structures, enabling weight reductions that extend electric range. Norwegian coast guard procurement teams are piloting these configurations in 6-7 meter patrol craft. The technology is absorbing market share from conventional aluminum hulls in specification-intensive segments where range and payload flexibility dominate selection criteria.
REACH chemical restrictions on persistent organic pollutants are tightening adhesive and coating formulations for inflatable tube construction, elevating water-based polyurethane alternatives. German and French fabricators are reformulating supply chains to maintain CE marking eligibility. Medium-vessel rescue and commercial categories face the steepest reformulation costs due to durability requirements in saltwater environments.
Charter operators in Croatian and Greek island clusters are unbundling vessel ownership from crew provision, shifting toward bareboat leasing models that prioritize trailerable logistics and rapid turnaround maintenance. This rotation is compressing specification cycles toward standardized 5-8 meter configurations with interchangeable tube collars. The pattern is most visible in Adriatic seasonal markets where fleet utilization rates dictate capital recovery timelines.
Rigid Inflatable Boats (RIB) Market Segmentation
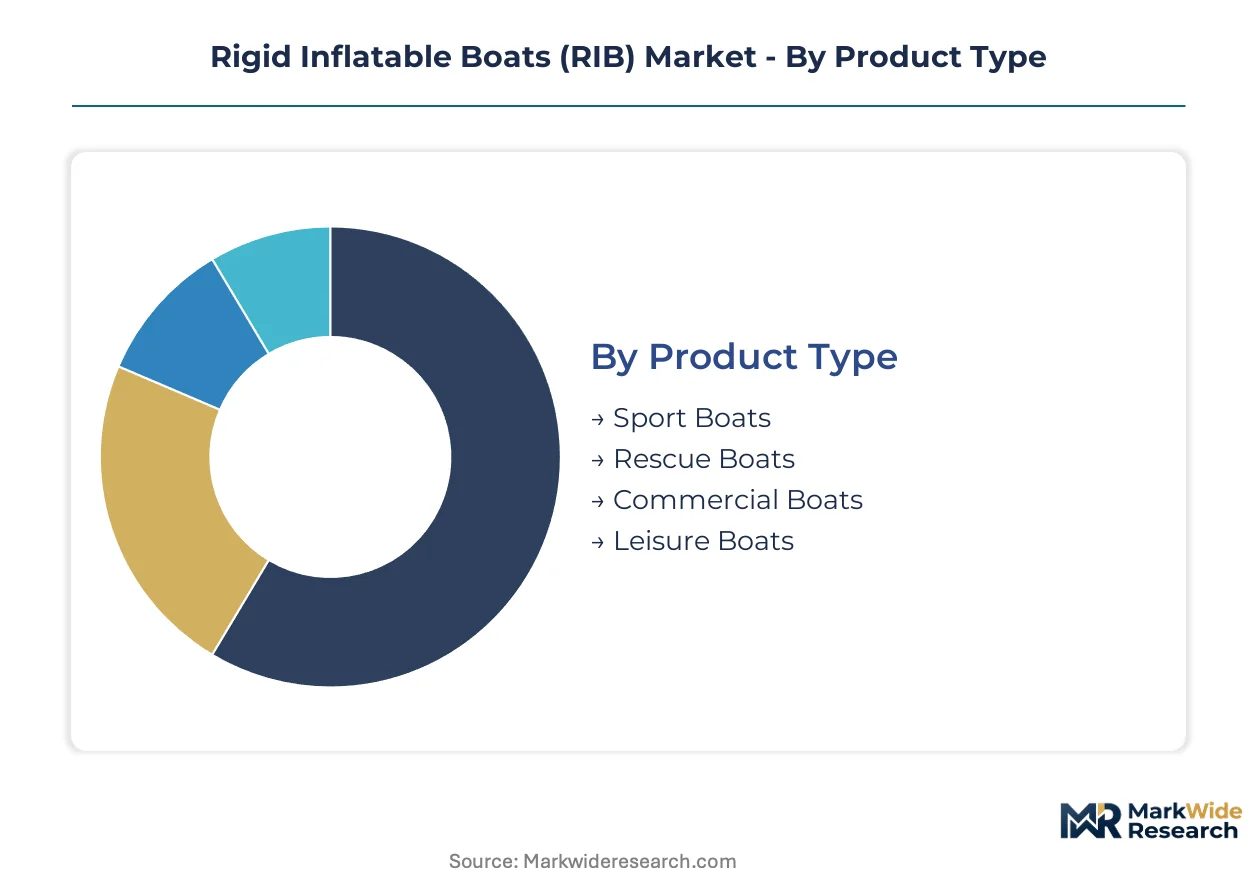
RIB procurement patterns diverge sharply across mission profiles and hull specifications. Fabricators configure tube materials, deck architectures, and propulsion systems to match distinct operational envelopes rather than pursuing universal platforms.
Product Type:
Supply concentrates around specification-intensive categories where procurement cycles extend 18-24 months and certification requirements filter low-cost entrants.
- Rescue Boats:Reinforced collar tubes and self-righting hull architectures withstand repeated impact recovery operations. Italian and Greek coast guard agencies dominate procurement volume, driven by Mediterranean interdiction mandates and Aegean refugee response protocols.
- Commercial Boats:Modular deck systems support mission reconfiguration between cargo transport, crew transfer, and offshore maintenance roles. North Sea energy service operators pull specification development toward 6-8 meter aluminum-hull configurations with shock-mitigating seating.
- Sport Boats:High-power outboard compatibility and planing hull geometries target competitive racing circuits.
- Leisure Boats:PVC-based entry-level imports from Southeast Asian fabricators saturate charter fleet replacement cycles.
Commercial boats absorb the bulk of installed capacity; rescue boats are expanding most quickly.
End User:
Procurement authority and funding mechanisms create tiered demand structures with diverging technical specifications and margin profiles.
- Government Agencies:Defense and coast guard procurement teams enforce ISO 6185 compliance, CE marking, and mission-modular deck standards. Baltic and Mediterranean coastal states are accelerating fleet modernization through multi-vessel framework agreements.
- Tour Operators:Croatian and Greek island clusters drive bareboat leasing standardization, compressing specification cycles toward trailerable 5-7 meter configurations with rapid-turnaround maintenance protocols.
- Marine Research Institutions:Scientific payload integration and acoustic quieting requirements shape hull and propulsion selections.
- Private Individuals:Recreational buyers prioritize storage logistics and tow vehicle compatibility over offshore capability.
Government agencies command the largest committed order pipelines; tour operators are gaining share fastest through fleet outsourcing models.
Size:
Hull length determines regulatory classification, propulsion options, and transport logistics, creating distinct competitive arenas with limited cross-segment substitution.
- Medium Vessels:The 5-8 meter band balances offshore seaworthiness with trailerable road transport, dominating government patrol and commercial crew transfer specifications. Polish and Ukrainian metalworking partnerships sustain cost-competitive aluminum hull production for this configuration.
- Large Vessels:Exceeding 8 meters, these platforms accommodate cabin enclosures and extended-range fuel systems for offshore patrol and interdiction missions. Norwegian coast guard specifications are piloting carbon-reinforced polyethylene laminates to reduce topside weight.
- Small Vessels:Under 5 meters, these serve harbor patrol and beach-launched rescue roles with outboard power limits.
- Super Vessels:Specialized platforms exceeding 12 meters for military special operations and long-range SAR missions.
Medium vessels carry the majority of annual hull production; large vessels are climbing the fastest on defense procurement acceleration.
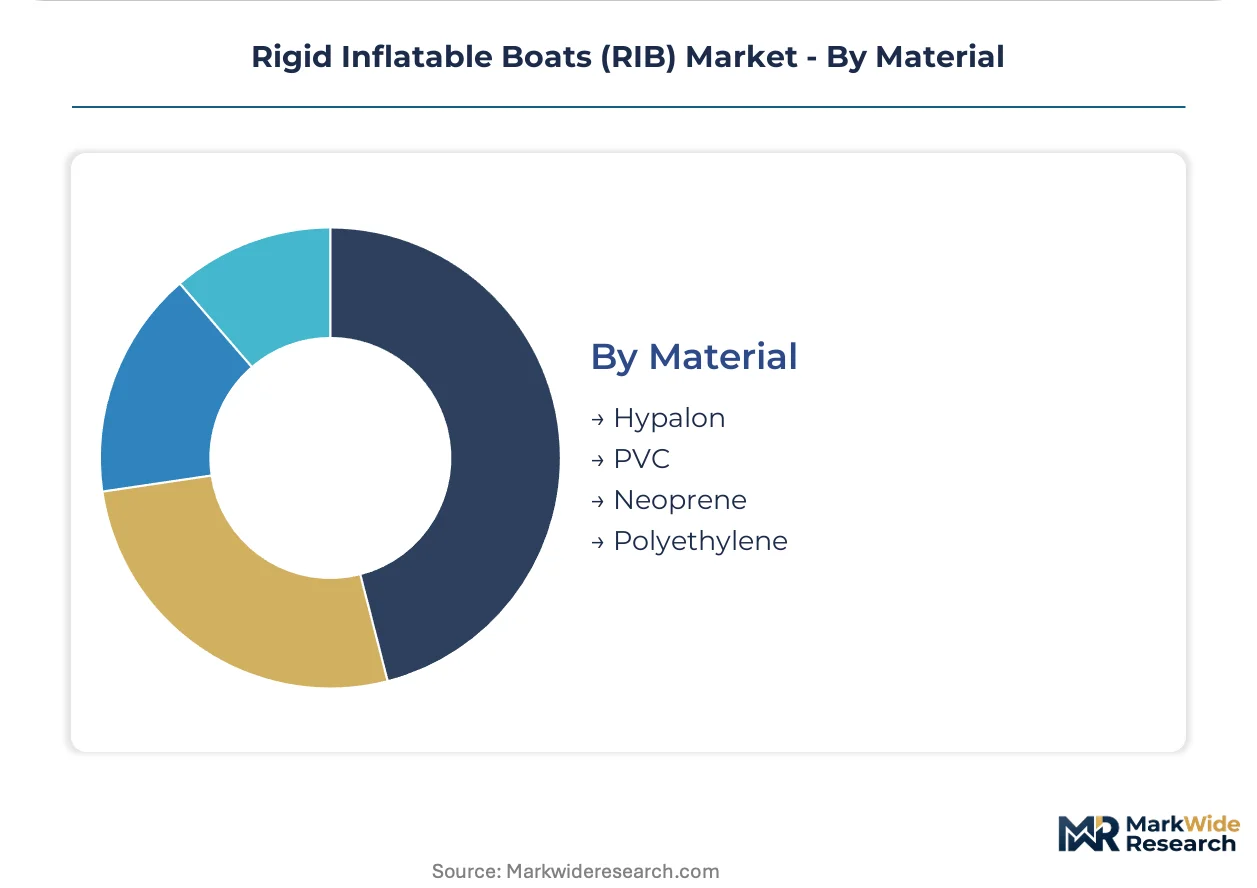
Material:
Tube fabric selection determines durability, repairability, and regulatory compliance trajectories across saltwater and UV exposure profiles.
- Hypalon:Chlorosulfonated polyethylene delivers superior UV resistance and chemical tolerance for military and commercial fleets operating in tropical and high-latitude environments. REACH chemical restrictions are elevating reformulation costs for French and Italian fabricators.
- Aluminum:Rigid hull material enabling planing efficiency and impact recovery in patrol and rescue configurations. Highfield Boats dominates export supply chains for this construction method.
- PVC:Entry-level charter fleets favor this material for cost-sensitive replacement cycles despite shorter service lifespans.
- Neoprene:Specialized applications in cold-water diving support and military stealth coatings.
Hypalon retains the largest installed base in specification-intensive segments; aluminum hulls are gaining share fastest through electric range extension requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hypalon fabric supply chains cluster in French and Italian petrochemical corridors, while aluminum hull fabrication gravitates toward Polish and Ukrainian metalworking districts. These feedstock localities shape regional competitive positioning across rescue, patrol, and commercial segments.
France
French coast guard procurement drives specification-intensive rescue boat demand through Mediterranean interdiction programs. The country's national maritime regulator enforces CE marking and updated EU Recreational Craft Directive stability mandates. Lorient and La Rochelle harbor clusters concentrate composite tube lamination expertise for military and commercial fleets.
Italy
Italian naval agencies accelerate medium-vessel RIB fleet modernization for Aegean refugee response and high-speed boarding operations. REACH chemical restrictions from ECHA tighten adhesive formulations for Hypalon tube construction. Ancona and La Spezia shipyards anchor production of self-righting hull architectures for government buyers.
Poland
Polish metalworking partnerships sustain cost-competitive aluminum hull output for 5-8 meter patrol and tour operator configurations. The country's conformity assessment bodies streamline CE marking pathways under harmonized EU directives. Gdansk and Szczecin industrial zones supply trailerable hull fabrications to Baltic and Adriatic export markets.
Norway
Norwegian coastal patrol specifications pilot carbon-reinforced polyethylene laminates and battery-electric propulsion trials in 6-7 meter craft. The country's national environmental regulator advances decarbonization mandates for outboard powertrains. Bergen and Stavanger maritime clusters integrate powertrain architecture into early-stage hull design for extended electric range.
Greece
Greek island charter operators drive bareboat leasing standardization toward rapid-turnaround 5-7 meter configurations. The country's coast guard expands medium-vessel fleets for Eastern Mediterranean emergency response protocols. Piraeus and Corfu marine service hubs concentrate seasonal fleet maintenance and tube collar interchange operations.
Rigid Inflatable Boats (RIB) Market Vendor Landscape
Global majors compete with regional champions across defense procurement corridors and Mediterranean charter networks. Market structure tilts toward specification-intensive segments where ISO 6185 compliance and CE marking filter low-cost entrants. Three archetypes dominate: defense-anchored system integrators, aluminum-hull export specialists, and charter-optimized volume fabricators. Competitive moves concentrate on strategic partnerships for feedstock security and modular deck system licensing.
Within the defense-contractor tier, Zodiac and BRIG exemplify contrasting geographic strategies. Zodiac occupies a position anchored in French state procurement relationships. BRIG represents the distributed manufacturing archetype through Ukrainian and Polish production partnerships. Highfield Boats sits within the aluminum-hull export specialist category, supplying Australasian and North American dealer networks. Each exemplifies how feedstock access and regulatory proximity shape competitive positioning across rescue, patrol, and commercial segments.
| Leading Market Players |
|---|
| BRIG |
| Protector |
| Highfield Boats |
| Ribcraft |
| Ribco |
| Zodiac |
| GRAND Boats |
| Sacs Marine |
| AB Inflatables |
| Others |
Supply Flow & Price Mechanics
Composite tube lamination specialists in French and Italian boatyards command wage premiums that compress margin recovery at the premium tier while economy-tier imports from Southeast Asian fabricators exploit labor-cost arbitrage, widening the pricing spread across certification grades.
Pricing Analysis
Warranty and service bundling separates premium Hypalon-equipped rescue craft from bare-hull economy configurations. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 6185 certification intensity, CE marking compliance, and after-sales service coverage. Cost compression in the economy tier intensifies as PVC-based imports saturate Mediterranean charter replacement cycles. Tour operators exhibit acute price sensitivity; coast guard procurement teams prioritize lifecycle cost over upfront acquisition.
Supply Chain Analysis
Domestic-content mandates in French and Italian defense procurement are reshaping sourcing patterns for military-specification tube fabrics. Hypalon supply clusters in French petrochemical corridors and aluminum hull fabrication in Polish and Ukrainian metalworking districts anchor production geography. Raw material dependencies center on chlorosulfonated polyethylene tube fabrics, marine-grade aluminum alloys, and carbon-reinforced polyethylene laminates. Single-source vulnerability in Hypalon feedstock exposes fabricators to petrochemical volatility. Distribution runs through Mediterranean charter hubs and Baltic defense procurement corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as REACH chemical restrictions and ISO 6185 compliance timelines force subscale fabricators toward exit or acquisition, concentrating viable production among certified manufacturers with regulatory proximity.
For Market Incumbents: Anticipate margin compression from electric propulsion integration mandates by securing backward control over battery-electric powertrain partnerships and carbon-reinforced laminate supply. Shore up composite technician pipelines through apprenticeship programs in Ancona and La Rochelle clusters to counter workforce aging. CE marking harmonization offers channel control leverage against unbundled imports. For New Entrants and Emerging Players: The price-point gap between premium rescue specifications and economy leisure imports creates white-space opportunity in mid-tier commercial configurations. Target Polish and Ukrainian aluminum hull partnerships for cost-competitive 5-8 meter production. Bareboat leasing standardization in Croatian and Greek markets offers the most penetrable entry vector. Pursue modular deck system licensing to accelerate specification credibility without full certification burden. For Investors and Strategic Acquirers: Re-rating potential sits with aluminum-hull export specialists given electric range extension requirements and carbon-reinforced laminate adoption curves. Long-term viability favors fabricators with integrated powertrain architecture capabilities and Baltic conformity assessment proximity. Monitor Norwegian coast guard procurement signals for hydrogen fuel-cell propulsion inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hypalon Supply | Captive feedstock secures margin against REACH reformulation cost spikes. |
| Modular Deck System Licensing | Revenue streams from Mediterranean charter operators seeking mission flexibility. |
| Electric Propulsion Partnership | Norwegian and Danish patrol specifications reward early powertrain integration. |
| CE Marking Fast-Track Investment | Polish conformity assessment bodies streamline Baltic and Adriatic market access. |
| Composite Technician Apprenticeship | Lorient and La Spezia clusters address workforce scarcity constraining output scaling. |
Methodological Framework
Multi-period observation of fleet procurement volumes, tube fabric pricing spreads, and electric propulsion trial deployments anchored the trend analysis, supplemented by interviews with coast guard procurement officers, charter fleet managers, composite lamination supervisors, and marine equipment distributors. Secondary validation drew from EU Recreational Craft Directive filings, ECHA REACH restriction updates, customs trade data for inflatable hull imports, and ISO 6185 certification registries. Bottom-up vessel production estimates triangulated against top-down defense budget allocations and tour operator fleet replacement cycles.
Segment-weighting across product type, hull size band, tube material, and end-user mission profile shaped the analytical framework across the projection horizon. Modeled dimensions included rescue versus commercial versus leisure categories, 5-8 meter versus 8 meter-plus configurations, Hypalon versus aluminum versus PVC construction, and government agency versus tour operator versus private individual demand. CAGRs were derived from fitted growth curves applied to procurement pipeline data and fleet modernization announcements. Forecast inputs incorporated electric outboard adoption curves in Norwegian patrol specifications and carbon-reinforced laminate weight-reduction coefficients.
Underlying measurement precision varies by segment; government agency procurement pipelines carry tighter precision than private recreational demand. Forecasts reflect documented assumptions regarding defense budget continuity, REACH implementation timelines, and electric propulsion technology maturation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Sea Skimmer Market
Marine
Yacht Painting and Maintenance Market
Marine
Marine Bearings Market
Marine
Ballast Water Management Market
Marine
Europe Recreational Boating Market
Marine
Marine Communication Market
Marine
Unmanned Marine Vehicles Market
Marine
Marine Shackle Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Marine Gas Oil Market
Marine
Marine Turbocharger Market
Marine
Sea Scooter Market
Marine
North Sea Offshore Support Vessels Market
Marine
Marine Spreader Lights Market
Marine
Global Marine Gearbox Market
Marine
Marine Interiors Market