
 Yacht Painting and Maintenance Market | 2026-2036
Yacht Painting and Maintenance Market Size, Share, and Industry Trends Forecast 2026-2036
Yacht Painting and Maintenance Market Insights
IMCA certification is rotating toward mandatory status for contractors performing surface preparation and coating application on superyachts in major refit hubs. Pinmar leverages its geographic dominance across Mediterranean ports to control premium topcoat application volumes. Monaco Marine sustains vertical integration from haul-out through final detailing at its Monaco and La Ciotat facilities. Sansoon Yacht Services differentiates through specialized corrosion repair capabilities for aluminum-hull racing yachts.
Yacht painting and maintenance encompasses the systematic application of protective and aesthetic coatings to marine vessels, involving surface preparation to SA 2.5 standards, multi-layer epoxy primer systems, and polyurethane finish coats engineered for UV resistance and saltwater exposure. The primary purpose is hull protection against biofouling and electrochemical corrosion while preserving aesthetic value for asset resale. Antifouling coatings command the largest product type volume as regulatory pressure on biocide content reshapes formulation R&D priorities. Protective coating application generates the highest service margins due to specialized labor requirements and weather-dependent scheduling constraints. Luxury yachts represent the dominant application segment, with hull cleaning and polishing services tied to seasonal Mediterranean and Caribbean cruising patterns.
REACH in Europe and EPA VGP standards in the United States constrain biocidal antifouling formulations, forcing coating suppliers to reformulate active compounds and yards to document environmental compliance. IMCA and ISO 8501 surface preparation standards govern contractor qualification, creating barriers for uncertified entrants in premium refit segments. Stakeholders must monitor regulatory divergence between jurisdictions to align coating inventories and technician training investments.
Market Dynamics
Superyacht refit yards in Monaco and Fort Lauderdale are expanding capacity to capture rising demand from ultra-high-net-worth owners, while EU REACH regulation on biocidal antifouling compounds pushes yards toward compliant copper-free coating systems. This tension between demand concentration and environmental compliance is restructuring contractor qualification requirements and coating procurement patterns across Mediterranean and Caribbean hubs.
Growth Catalysts
- Regulatory Compliance Mandates:ECHA's REACH regulation on biocidal products is forcing widespread adoption of copper-free antifouling systems, creating upgrade cycles across existing fleets and standardizing formulation R&D priorities among coating suppliers.
- Seasonal Haul-Out Concentration:Mediterranean basin cruising patterns generate predictable maintenance windows, allowing service providers to optimize labor deployment and inventory positioning across Monaco, Antibes, and Barcelona clusters.
- Ultra-High-Net-Worth Fleet Expansion:Superyacht ownership growth above 60 meters is driving demand for specialized surface preparation and premium polyurethane finish coat application at IMCA-certified facilities.
Market Restraints
- Specialized Labor Scarcity:Certified applicators trained to SA 2.5 surface preparation standards and multi-layer epoxy primer systems command premium wages, compressing margins for uncertified entrants.
- Weather-Dependent Scheduling:Humidity and temperature constraints on coating cure times create operational bottlenecks, particularly in tropical refit hubs where seasonal rainfall disrupts application windows.
- Formulation Transition Costs:Copper-free biocide research and environmental compliance documentation impose R&D burdens on coating manufacturers adapting to REACH and EPA VGP standards.
Strategic Opportunities
- Aluminum-Hull Racing Specialization:Corrosion repair capabilities for high-performance racing yachts represent an underserved niche, with demand concentrated in Newport and Auckland regatta circuits.
- Environmental Certification Differentiation:Yards documenting full REACH and EPA VGP compliance can capture premium positioning as regulatory enforcement intensifies in EU and US waters.
- Extended Caribbean Season:Hurricane haul-out patterns in Fort Lauderdale and Palm Beach are lengthening maintenance windows, creating capacity absorption opportunities for Mediterranean yards during off-peak periods.
Industry Challenges
- IMCA Certification Timelines:Contractor qualification requirements for surface preparation and coating application on superyachts are rotating toward mandatory status, creating training backlogs at major refit hubs.
- Multi-Jurisdiction Inventory Complexity:Regulatory divergence between EU REACH and US EPA VGP standards forces yards to maintain parallel coating inventories, increasing working capital requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yacht Painting and Maintenance Market |
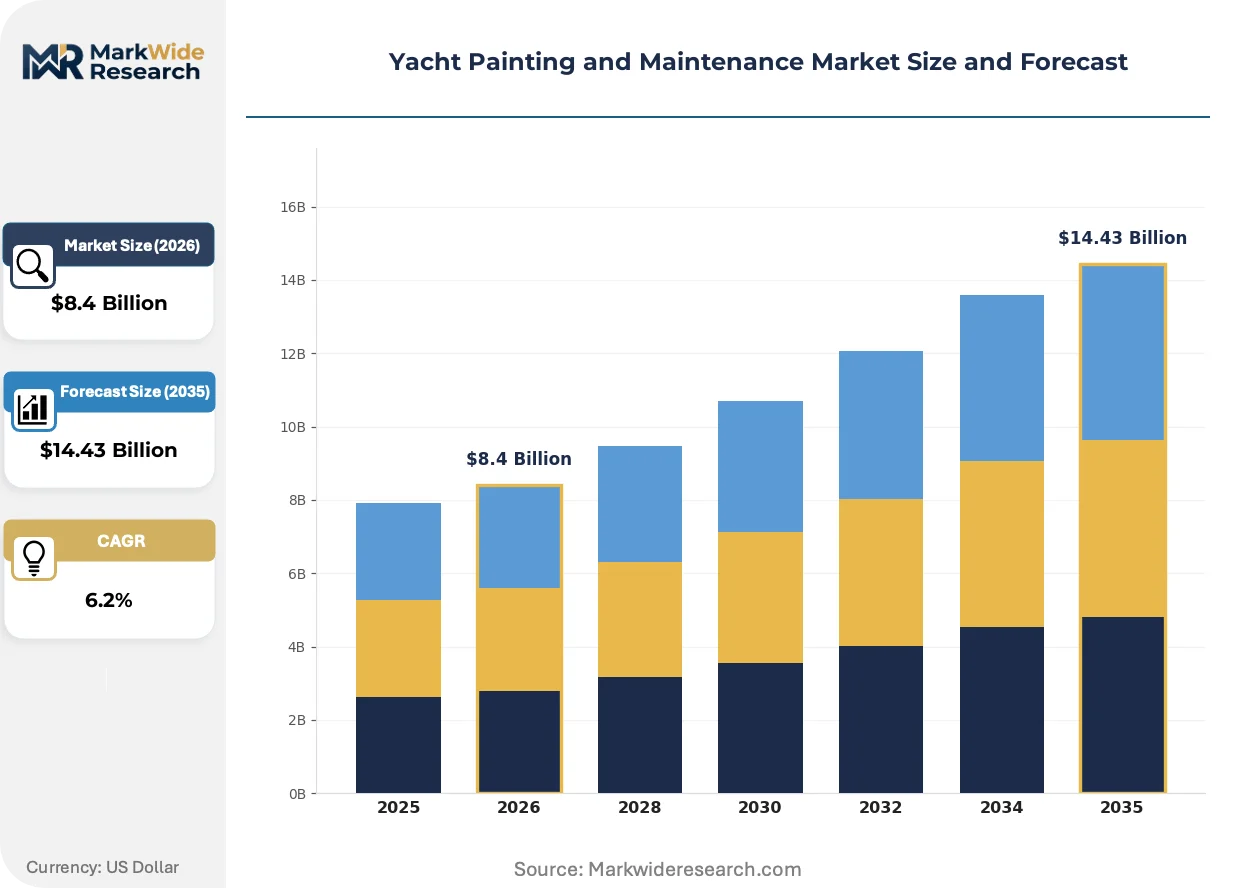
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifouling Coatings, Primer Paints, Topcoats, Sealants, Varnishes Maintenance Service: Hull Cleaning, Surface Preparation, Polishing, Corrosion Repair, Protective Coating Application Application: Luxury Yachts, Racing Yachts, Commercial Vessels, Charter Boats, Research Ships End User: Boat Owners, Shipyards, Marine Outfitters, Vessel Operators, Yacht Management Firms |
| Companies Covered | Yacht Management South Florida, Multitech Marine, Pinmar, Sansoon Yacht Services, Newmil Marine, Monaco Marine, OP Yacht Services, Global Yacht Group, Almar Pro Painting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yacht Painting and Maintenance Market Trends and Innovations
Coating technology and service delivery models are converging around environmental performance metrics and predictive maintenance integration. These shifts are compressing traditional procurement cycles while elevating technical qualification barriers for market participants.
Silicone-based foul-release coatings are miniaturizing application thickness requirements while maintaining biofouling resistance performance. Superyacht owners operating vessels above 40 meters are adopting these systems at accelerated rates to reduce dry-dock frequency. This technology is miniaturizing the trade-off between hull protection and speed performance, enabling thinner film builds that reduce material volume without sacrificing functional outcomes.
REACH authorization procedures for copper-based biocides are tightening permissible active compound concentrations in antifouling formulations. Coating suppliers are reformulating with organic biocides and silicone hybrid systems to maintain efficacy under compliance constraints. Mediterranean-based refit yards face the most acute transition pressure, as seasonal haul-out volumes concentrate regulatory scrutiny in Monaco, Antibes, and Barcelona facilities.
Asset resale value preservation is shifting owner preferences toward documented coating application histories and certified maintenance records. Brokers and surveyors in Fort Lauderdale and Monaco now prioritize vessels with IMCA-certified yard documentation, displacing informal service relationships. This behavioral pivot is most pronounced in the 30-60 meter luxury yacht segment, where provenance documentation directly correlates with transaction velocity and price realization.
Yacht Painting and Maintenance Market Segmentation
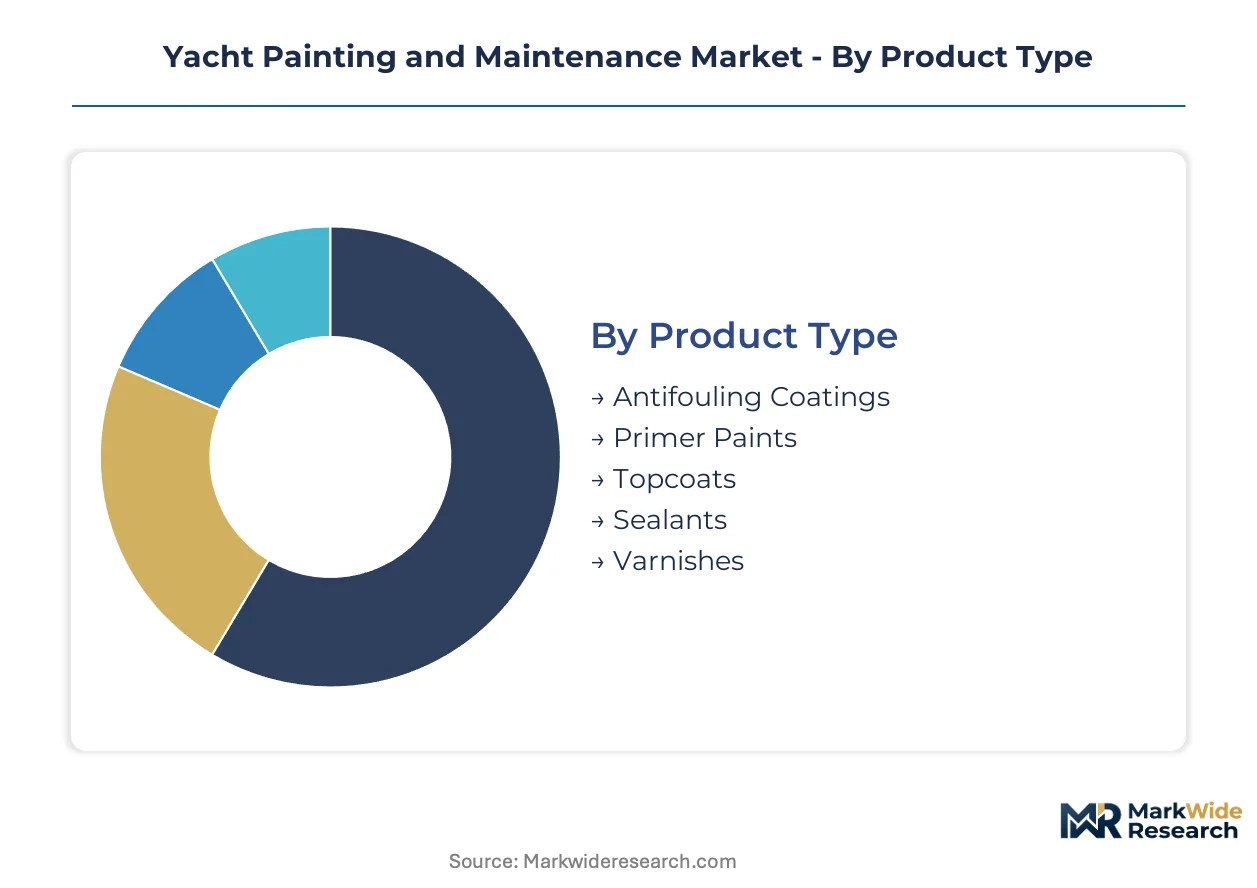
Segmentation in yacht painting and maintenance reveals how regulatory pressure on biocidal compounds and certification requirements reshape procurement patterns across product categories and service tiers. Understanding these divisions exposes where margin concentration aligns with technical barriers versus commodity competition.
Product Type:
ECHA's REACH authorization procedures for copper-based biocides differentiate formulation viability across coating categories, forcing suppliers to maintain parallel product lines for EU and non-EU markets.
- Antifouling Coatings:Multi-layer systems incorporating organic biocides or silicone-hybrid bases deliver biofouling resistance without copper compounds. Demand concentrates in Mediterranean refit hubs where seasonal haul-out schedules and strict environmental enforcement coincide.
- Primer Paints:Epoxy-based formulations engineered for adhesion to fiberglass, steel, and aluminum substrates create the foundation for superyacht finish systems. Shipyards in Monaco and Fort Lauderdale specify SA 2.5 surface preparation compatibility as a mandatory procurement criterion.
- Topcoats:Polyurethane finishes dominate premium aesthetic applications.
- Sealants:Elastomeric compounds address through-hull and deck joint waterproofing.
- Varnishes:UV-resistant clear coats preserve teak and brightwork on classic vessels.
Antifouling coatings handle the majority of throughput; primer paints are climbing the fastest on share as surface preparation standards tighten.
Maintenance Service:
Service margins stratify sharply based on certification requirements, with IMCA-qualified surface preparation commanding premium pricing over commoditized hull cleaning.
- Protective Coating Application:Multi-layer primer and finish coat systems applied under controlled humidity and temperature conditions generate the highest margins in the service portfolio. Superyacht refit yards in Monaco and La Ciotat capture this value through in-house certification rather than subcontracting.
- Surface Preparation:Abrasive blasting to SA 2.5 standards and solvent cleaning protocols establish coating adhesion performance. Demand clusters at IMCA-certified facilities where documentation requirements for vessels above 40 meters have become non-negotiable.
- Corrosion Repair:Specialized aluminum and steel hull remediation addresses electrolytic damage.
- Polishing:Gelcoat and paint restoration services support resale value documentation.
- Hull Cleaning:In-water and dry-dock biofouling removal operates at commodity pricing tiers.
Protective coating application captures the steepest margin expansion; corrosion repair is gaining share fastest as aluminum-hull racing fleets expand.
Application:
Vessel category determines maintenance frequency, coating specification complexity, and the documentation standards required for asset resale.
- Luxury Yachts:Vessels from 30 to 100+ meters require scheduled haul-out cycles tied to Mediterranean and Caribbean cruising patterns. Monaco and Fort Lauderdale brokers now mandate IMCA-certified maintenance records as a transaction prerequisite.
- Racing Yachts:High-performance carbon and aluminum hulls demand specialized corrosion monitoring and lightweight coating systems. Newport and Auckland regatta circuits concentrate demand for rapid turnaround refit services between competitive seasons.
- Commercial Vessels:Fishing and workboat fleets prioritize cost-minimized protection cycles.
- Charter Boats:High-usage profiles accelerate wear and drive recurring maintenance contracts.
- Research Ships:Scientific instrumentation integration creates unique coating compatibility requirements.
Luxury yachts absorb the dominant share of premium service capacity; racing yachts are expanding most quickly as regatta investment intensifies.
End User:
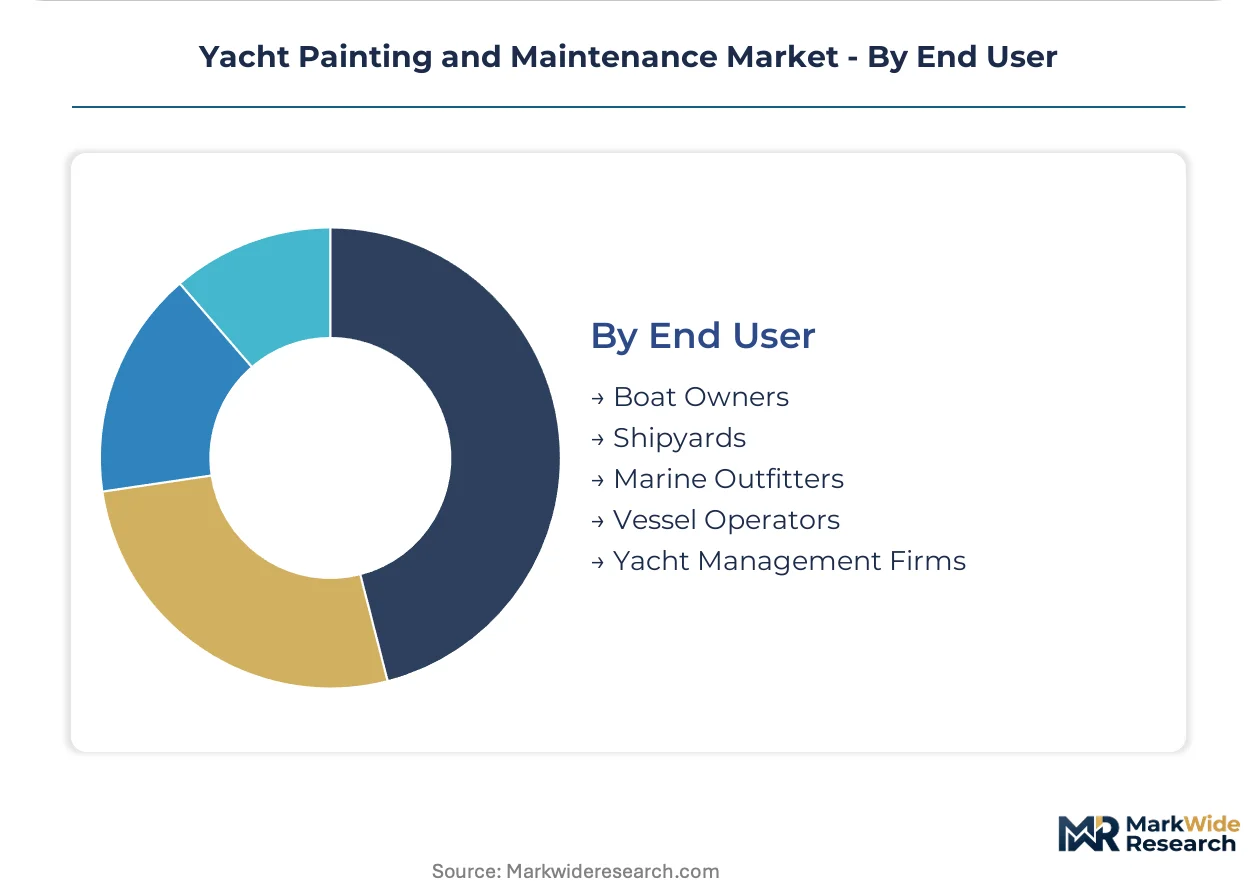
Procurement authority and technical sophistication vary dramatically across customer types, shaping how coating suppliers and service yards structure their sales approaches.
- Shipyards:Vertically integrated refit facilities in Monaco, La Ciotat, and Fort Lauderdale control premium application volumes through captive surface preparation and coating teams. These entities specify formulation compliance with both REACH and EPA VGP standards as baseline procurement requirements.
- Yacht Management Firms:Professional fleet operators aggregate maintenance scheduling across multiple owner vessels. Mediterranean-based managers leverage seasonal haul-out predictability to negotiate volume pricing with Antibes and Barcelona service providers.
- Boat Owners:Individual proprietors below 30 meters often select on price.
- Marine Outfitters:Independent contractors supply specialized services to uncertified facilities.
- Vessel Operators:Charter and commercial captains prioritize minimal downtime.
Shipyards direct the largest contract values; yacht management firms are the fastest-growing procurement channel as superyacht fleet professionalization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH authorization procedures on copper-based biocides are redirecting maintenance investment toward compliant coating systems across major yachting jurisdictions. Regulatory divergence between EU and US standards is fragmenting procurement patterns while concentrating service demand in certified refit hubs.
United States
Ultra-high-net-worth fleet expansion above 60 meters is concentrating refit demand in Fort Lauderdale and Palm Beach. EPA VGP standards constrain biocidal antifouling formulations, forcing yards to document environmental compliance for in-water cleaning operations. South Florida's hurricane haul-out patterns are lengthening seasonal maintenance windows and absorbing Mediterranean off-peak capacity.
Monaco
Vertical integration from haul-out through final detailing captures premium pricing at facilities serving the 30-100 meter luxury segment. REACH compliance mandates have accelerated copper-free coating adoption at La Ciotat and Monaco Marine facilities. The principality's seasonal cruising calendar generates predictable haul-out scheduling that optimizes labor deployment across surface preparation and finish coat application.
France
Antibes and La Ciotat anchor Mediterranean refit capacity for IMCA-certified superyacht work. ECHA's tightening biocide authorization timelines are pressuring coating inventories toward silicone-hybrid and organic biocide systems. Provence-Alpes-Côte d'Azur facilities are expanding documentation capabilities to satisfy broker requirements for certified maintenance records.
Spain
Barcelona's refit cluster is capturing overflow demand from saturated French and Monegasque yards during peak Mediterranean seasons. REACH alignment through EU membership standardizes formulation procurement with French and Italian counterparts. Catalan facilities are investing in humidity-controlled application sheds to address weather-dependent cure time constraints.
Italy
Genoa and Viareggio maintain specialized capabilities for aluminum-hull racing yachts serving Newport and Auckland regatta circuits. REACH compliance documentation is becoming mandatory for transactions brokered through Mediterranean sales channels. Ligurian and Tuscan yards are differentiating through rapid-turnaround corrosion repair services between competitive seasons.
Yacht Painting and Maintenance Market Competitive Landscape
Player mix skews toward geographically entrenched refit yards and specialized coating applicators with IMCA certification. Market structure concentrates premium volumes within vertically integrated facilities controlling captive surface preparation teams. Three archetypes dominate: Mediterranean port-based full-service yards, regional multi-site coating specialists, and niche aluminum-hull repair technicians. Capacity expansion and certification acquisition represent the dominant competitive moves as regulatory barriers rise.
Among Mediterranean-dominant service providers, Pinmar exemplifies geographic concentration across premium topcoat application volumes, while Monaco Marine occupies a position as a vertically integrated facility operator. Sansoon Yacht Services represents the specialized corrosion repair archetype for high-performance racing hulls. These three entities anchor distinct strategic positions without overlapping core competencies.
| Leading Market Players |
|---|
| Yacht Management South Florida |
| Multitech Marine |
| Pinmar |
| Sansoon Yacht Services |
| Newmil Marine |
| Monaco Marine |
| OP Yacht Services |
| Global Yacht Group |
| Almar Pro Painting |
| Others |
Pricing and Supply Chain Analysis
Ninety-day coating formulation lead times from REACH-compliant suppliers to Mediterranean yards compress pricing power for uncertified applicators while elevating margins at IMCA-certified facilities. This inventory-to-certification linkage concentrates procurement authority within vertically integrated refit hubs that control captive surface preparation teams.
Pricing Analysis
Certification level (IMCA/ISO 8501-grade) creates the primary spread between commodity hull cleaning and premium protective coating application. Three-tier pricing structure across IMCA-certified, yard-affiliated, and independent contractor levels stratifies service procurement. Cost compression in the independent tier is intensifying because REACH documentation requirements displace uncertified operators from superyacht refit contracts. Individual boat owners below 30 meters exhibit highest price sensitivity, while shipyards directing fleet maintenance contracts demonstrate lowest sensitivity due to resale value documentation requirements.
Supply Chain Analysis
Strait of Gibraltar transit underwrites just-in-time coating deliveries to Monaco and Antibes facilities during compressed Mediterranean haul-out windows. Formulation supply concentrates in Germany, the Netherlands, and the United Kingdom for epoxy primer systems, with silicone-hybrid foul-release coatings drawing from Italian and Spanish specialty chemical producers. Single-source vulnerability runs through copper-free biocide active compound suppliers adapting to ECHA authorization timelines. Distribution runs through refit yard procurement departments that maintain parallel REACH and EPA VGP-compliant inventories for transatlantic vessel movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward yacht management firms that aggregate fleet maintenance scheduling, consolidating procurement authority previously fragmented across individual owners. This concentration elevates volume pricing leverage and documentation standardization demands.
For Market Incumbents: Secure IMCA certification acquisition at La Ciotat and Fort Lauderdale facilities to defend against emerging specialized corrosion repair entrants targeting aluminum-hull racing segments. Backward integration into copper-free formulation R&D partnerships with German and Dutch suppliers anchors compliance positioning as ECHA authorization timelines tighten. For New Entrants and Emerging Players: Lead with aluminum-hull racing specialization in Newport and Auckland regatta circuits, the most penetrable segment given rapid-turnaround service gaps between competitive seasons. Target IMCA certification as the go-to-market angle to displace informal yard relationships in the 30-60 meter documentation-sensitive segment. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because environmental certification barriers compound faster than capacity expansion. Acquisition target archetype: Mediterranean port-based yards with captive surface preparation teams and existing ECHA documentation infrastructure. The signal to watch is REACH enforcement intensity at Monaco Marine and Pinmar facilities as indicative of compliance premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| IMCA Certification Acquisition | Establishes mandatory contractor qualification for superyacht refit contracts above 40 meters. |
| Copper-Free Formulation Partnership | Secures REACH-compliant coating supply from ECHA-authorized German and Dutch suppliers. |
| Humidity-Controlled Application Infrastructure | Addresses Barcelona and Antibes weather-dependent cure time constraints. |
| Aluminum-Hull Racing Specialization | Captures underserved Newport and Auckland regatta circuit corrosion repair demand. |
| Dual-Jurisdiction Inventory Positioning | Maintains parallel REACH and EPA VGP coating stocks for transatlantic vessel movements. |
Research Methodology
Operator-level perspectives from refit yard managers, IMCA certification officers, coating procurement directors, and superyacht brokers anchored the qualitative base for this analysis. Primary fieldwork with Monaco Marine and Pinmar technical staff combined with secondary validation from ECHA biocide authorization databases, EPA VGP compliance filings, and IMCA training records. Customs data on coating imports to France, Italy, and Spain plus SEC filings from listed marine service providers supported volume triangulation through bottom-up service provider interviews and top-down trade flow analysis.
Sensitivity analysis across regulatory enforcement scenarios, seasonal haul-out timing variations, and fleet expansion rates shaped the projection framework. Segmentation dimensions modeled include coating product type, maintenance service tier, vessel application category, and end-user procurement channel, with regional regulatory cluster as the industry-specific overlay. CAGRs were derived through trend extrapolation of certification penetration rates and fleet composition shifts, incorporating ECHA authorization timeline assumptions and superyacht length-class delivery patterns as forecast inputs across the analysis window.
The analysis sits within stated boundaries; outcomes outside sustained ECHA enforcement intensity or accelerated EPA VGP adoption would require recalibration. Forecasts reflect documented assumptions on certification mandate timing and copper-free formulation efficacy. Practitioners should keep alternative scenarios live as REACH authorization procedures and hurricane haul-out pattern shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Exhaust Systems Market
Marine
Marine Shaft Power Meter Market
Marine
GCC ROV Market
Marine
Global Foldable Inflatable Boats Market
Marine
Marine Fasteners Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Furnace Boats Market
Marine
Tele-Operated Marine Drone Market
Marine
Yacht Shell Doors Market
Marine
Mooring Ropes Market
Marine
Marine Filter Market
Marine
Trim Tabs Market
Marine
Marine Asset Integrity Services Market
Marine
Marine Engine Cooling Systems Market
Marine
Marine Diesel Engine Market
Marine
Europe Marine Communication Systems Market