
 Marine Airbags Market | 2026-2036
Marine Airbags Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Airbags Market Intelligence
A widening capability gap between integrated rubber compounders and assembly-only operators is unwinding competitive stability in the marine airbags sector. Yokohama Rubber Co. leverages captive polymer research to command premium positioning in heavy-lift salvage applications. Qingdao Luhang Marine Airbag and Fender Co., Ltd. anchors its cost structure through backward integration into nylon fabric reinforcement weaving. MAX Group specializes in modular airbag architectures for offshore platform support, differentiating where standard designs fail.
Marine airbags are reinforced elastomeric lifting and flotation devices, typically constructed from multiple layers of rubber-coated synthetic cord fabric with end-sealing steel fittings, designed to distribute hydrostatic pressure across vessel hulls during launching, docking, or recovery operations. Ship launching applications dominate volume throughput, though salvage operations capture disproportionate margin pools due to emergency-response premiums and technical certification requirements. Docking airbags face maturity pressures in established East Asian shipyard clusters, while modular airbags represent the fastest-growing configuration as offshore decommissioning projects multiply. Polyurethane coating technology leads durability specifications, with UV resistant treatment gaining traction in tropical port environments where ozone degradation accelerates.
China's SAMR enforces GB standards for marine rubber product safety, compelling domestic manufacturers to maintain certified burst-pressure ratios that exceed baseline ISO requirements. Japan's METI coordinates with JIS standards bodies to validate airbag performance for seismic-zone shipyard operations, creating a dual-compliance burden for exporters. South Korea's MFDS-aligned maritime safety protocols extend to salvage contractor equipment certification, filtering market access. Stakeholders must monitor how evolving national pressure-vessel classifications reshape testing regimes and determine whether regional certification mutuality agreements emerge or fragment procurement further.
Market Dynamics
GB standards enforcement by China's SAMR is compressing supplier margins while elevating certified manufacturers, creating a bifurcation between compliant compounders and uncertified assemblers across Southeast Asian supply chains.
Growth Catalysts
- Offshore decommissioning mandates:Aging North Sea and Gulf of Mexico platforms require specialized modular airbag configurations for safe removal, expanding addressable demand beyond traditional shipyard applications.
- Synthetic fiber layering advances:Nylon-66 and aramid reinforcement weaving improvements extend burst-pressure tolerances, enabling heavier vessel classes to adopt airbag launching.
- Indonesia's shipbuilding corridors:Batam and Surabaya yard expansions concentrate procurement volume, creating localized economies of scale for regional suppliers.
Market Restraints
- Natural rubber price volatility:RSS3 and STR20 grade rubber fluctuations in Bangkok and Kuala Lumpur spot markets destabilize compounder cost structures without forward-contract hedging.
- Polyurethane feedstock concentration:MDI and TDI supply concentrates among four Asian chemical producers, exposing airbag coaters to allocation risk during petrochemical turnarounds.
- ISO 14409 testing burden:Third-party certification for burst-pressure validation adds twelve-to-eighteen month product development cycles, freezing smaller assemblers out of salvage-grade contracts.
Strategic Opportunities
- Sub-Saharan port modernization:Lamu, Tema, and Durban container terminal expansions lack established airbag supplier relationships, creating first-mover positioning for certified exporters.
- UV-resistant coating technology:Tropical port operators in Singapore and Cartagena now specify ozone-degradation protection as mandatory, premiumizing specification tiers.
- Dual-carbon compliance services:China's MEE carbon accounting requirements for heavy industrial equipment create adjacent revenue streams for lifecycle documentation and retrofit consulting.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing elasticity, tensile strength, and UV resistance command premium wages, constraining R&D throughput at mid-tier manufacturers.
- Multi-standard certification complexity:Simultaneous GB, JIS, and MFDS compliance requires parallel testing protocols, extending engineering validation timelines.
- Synthetic cord fabric integration:Automated weaving-to-rubber bonding equipment demands seven-figure capital outlays, freezing assembly-only operators from backward integration paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Airbags Market |
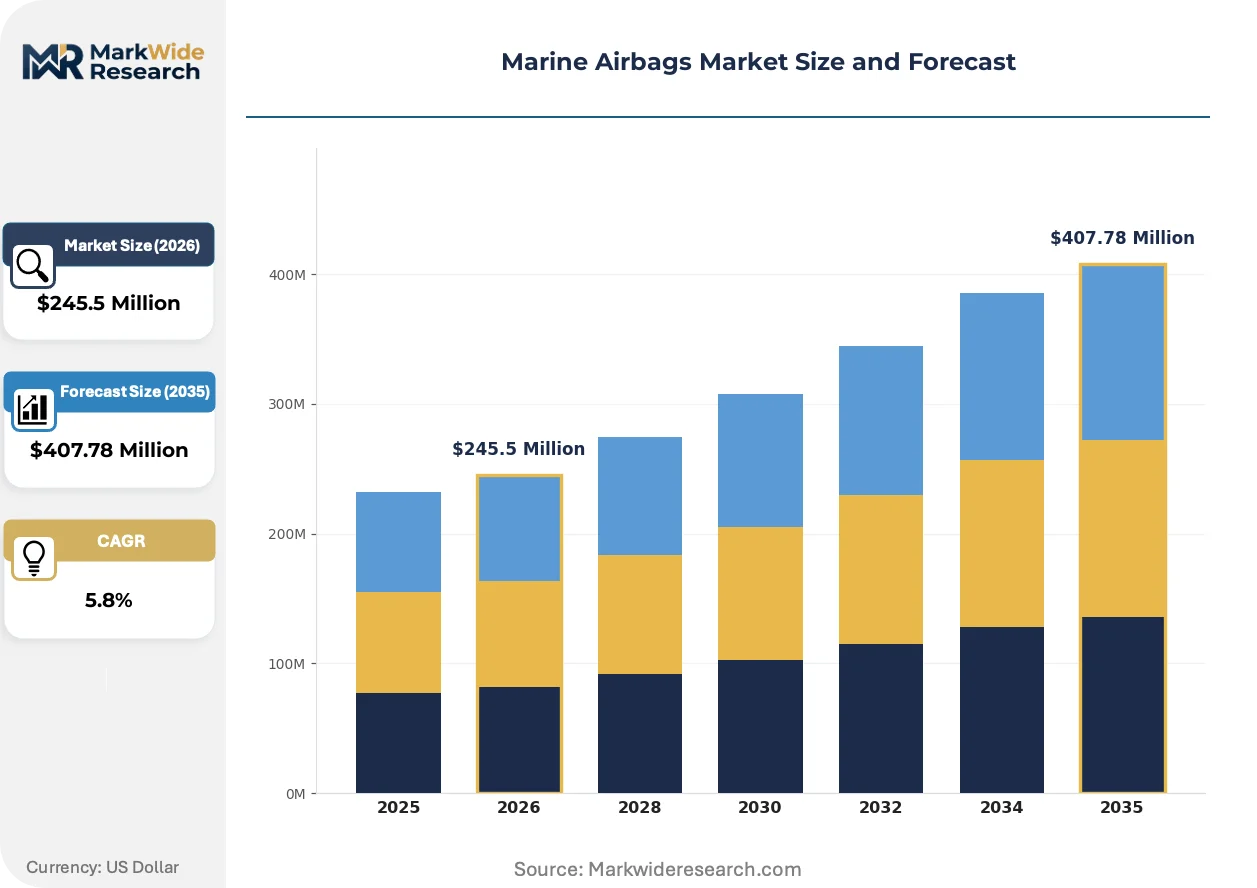
| Market Size in 2026 | $245.5 Million |
| Market Size in 2035 | $407.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airbags for Ship Launching, Docking Airbags, Salvage Airbags, Submarine Rescue Bags, Floating Airbags, Modular Airbags Technology: Polyurethane Coating, Nylon Fabric Reinforcement, Rubber Composite, Synthetic Fiber Layering, High-Strength Weaving, UV Resistant Treatment Application: Ship Launching, Vessel Docking, Salvage Operations, Offshore Platform Support, Heavy Load Transportation, Marine Construction End User: Shipyards, Marine Construction Firms, Salvage Companies, Offshore Service Providers, Port Authorities, Heavy Transport Operators |
| Companies Covered | Yokohama Rubber Co., Bridgestone Corporation, MAX Group, Qingdao Luhang Marine Airbag and Fender Co., Ltd., Shanghai Tojoy Airbags, Beihai Marine Rubber Products, HI-SEA Marine, Eversafe Marine Engineering Co., Ltd., Shandong Nanhai Airbag Engineering Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Airbags Market Strategic Shifts & Innovations
Material science convergence with regulatory pressure is reconfiguring competitive advantage around certified compounders rather than assembly scale, compressing the viable supplier base.
Aramid fiber reinforcement is displacing conventional nylon in high-pressure salvage applications, with North Sea contractors specifying hybrid cord constructions for emergency-response equipment. Norwegian and UK operators now mandate burst-pressure ratios exceeding baseline ISO thresholds by forty percent, compressing procurement to compounders with captive polymer research. This specification escalation is miniaturizing the qualified supplier pool to integrated manufacturers.
Japan's METI coordination with JIS standards bodies now requires seismic-zone validation for shipyard airbag deployments, extending testing protocols for exporters serving Osaka and Nagoya clusters. Domestic manufacturers absorb compliance costs through keiretsu relationships, while foreign suppliers face dual-certification burdens. Heavy-lift salvage contractors bear the steepest compliance penalties, passing costs through emergency-response premiums.
Service unbundling is fragmenting traditional supply relationships, with Indonesian and Vietnamese yards separating airbag procurement from installation supervision. Specialist engineering firms now contract directly for launch geometry calculations and pressure-monitoring protocols, disintermediating equipment vendors from high-margin advisory services. This pattern concentrates most visibly in Batam's free-trade zone, where European shipowners specify third-party marine warranty surveyor oversight.
Marine Airbags Market Segmentation
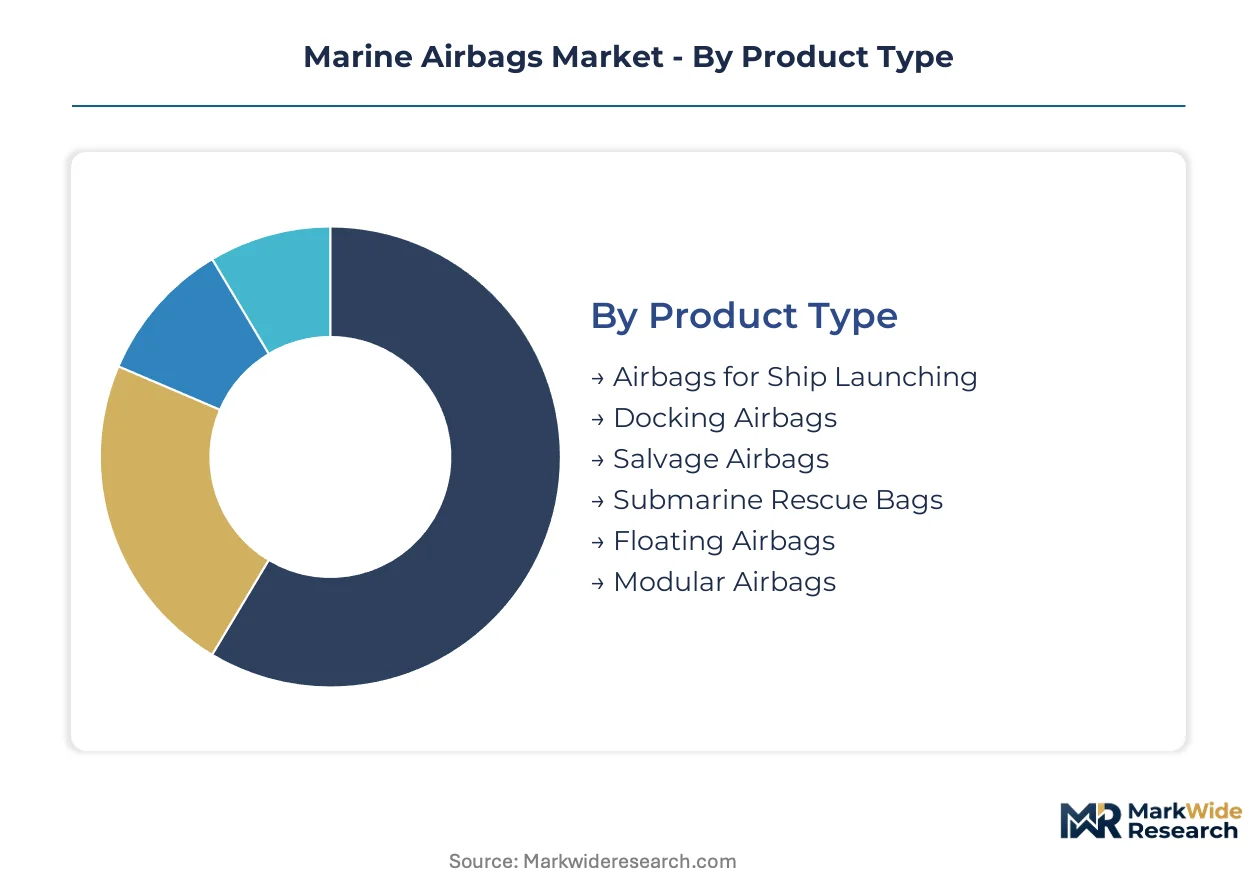
Marine airbag segmentation reveals how margin pools concentrate in certified compounders versus assembly-only operators. Technical differentiation across product architectures and coating technologies determines supplier viability in regulated procurement environments.
Product Type:
Salvage airbags command the steepest margin premiums due to emergency-response certification requirements and burst-pressure ratio specifications exceeding baseline ISO thresholds.
- Airbags for Ship Launching:Multi-layer rubber-coated synthetic cord fabric constructions distribute hydrostatic pressure across vessel hulls during gravity-based launches. Indonesian shipyards in Batam and Surabaya drive procurement volume for container vessel and bulk carrier construction programs.
- Salvage Airbags:Aramid fiber reinforcement and hybrid cord constructions withstand extreme burst-pressure demands. North Sea and Gulf of Mexico contractors specify these for platform decommissioning and emergency vessel recovery where failure carries catastrophic liability.
- Docking Airbags:Standard elastomeric configurations for routine vessel positioning face maturity pressures in established East Asian clusters.
- Submarine Rescue Bags:Specialized pressure-rated designs for naval and research submarine operations.
- Floating Airbags:Buoyancy-focused architectures for temporary flotation and load stabilization.
- Modular Airbags:Interconnectable units for offshore platform support and heavy-lift operations.
The dominant share belongs to Airbags for Ship Launching, while Modular Airbags are expanding most quickly through offshore decommissioning mandates.
Technology:
Cost tiers separate captive polymer researchers from coating-dependent assemblers, with integrated compounders capturing specification-escalation premiums.
- Polyurethane Coating:MDI and TDI-based formulations deliver superior abrasion resistance and hydrolytic stability. Tropical port operators in Singapore and Cartagena now mandate UV-resistant polyurethane variants as mandatory specifications.
- Synthetic Fiber Layering:Nylon-66 and aramid reinforcement weaving extends burst-pressure tolerances for heavier vessel classes. China's GB standards enforcement by SAMR compels domestic manufacturers to maintain certified burst-pressure ratios.
- Nylon Fabric Reinforcement:Conventional weaving-to-rubber bonding for standard-duty applications.
- Rubber Composite:Blended elastomer formulations balancing elasticity and tensile strength.
- High-Strength Weaving:Automated cord fabric production for precision reinforcement alignment.
- UV Resistant Treatment:Ozone-degradation protection additives for tropical and high-solar environments.
Polyurethane Coating holds the largest installed base, though Synthetic Fiber Layering is gaining share fastest through heavy-lift salvage specification escalation.
Application:
Volume concentrates in routine shipyard operations while margin pools shift toward emergency-response and offshore decommissioning deployments.
- Ship Launching:Gravity-based vessel deployment from inclined shipways using distributed airbag arrays. Southeast Asian yard expansions sustain procurement throughput despite automation alternatives.
- Salvage Operations:Emergency-response vessel recovery and wreck removal commanding premium pricing. Japan's METI seismic-zone validation requirements and South Korea's MFDS-aligned protocols filter contractor equipment certification.
- Vessel Docking:Routine positioning and dry-docking support in established port infrastructure.
- Offshore Platform Support:Modular configurations for platform installation, maintenance, and decommissioning.
- Heavy Load Transportation:Land-based and marine heavy-lift logistics applications.
- Marine Construction:Temporary flotation and positioning for coastal and harbor works.
Ship Launching dominates procurement volume, while Salvage Operations captures margin expansion through certification barriers and emergency-response premiums.
End User:
Customer type determines procurement sophistication, with shipyards separating equipment purchase from installation supervision and third-party engineering oversight.
- Shipyards:Primary volume purchasers across newbuild construction and repair programs. Indonesian and Vietnamese yards increasingly unbundle procurement from installation supervision, disintermediating equipment vendors from advisory services.
- Salvage Companies:Emergency-response specialists bearing steepest compliance penalties for multi-standard certification. ISO 14409 third-party validation adds twelve-to-eighteen month product development cycles.
- Marine Construction Firms:Coastal and harbor infrastructure contractors.
- Offshore Service Providers:Platform installation, maintenance, and decommissioning specialists.
- Port Authorities:Public and private terminal operators specifying equipment standards.
- Heavy Transport Operators:Land-based logistics and marine heavy-lift contractors.
Shipyards retain the largest procurement scale, though Salvage Companies drive the steepest specification escalation and premium pricing tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian shipyards exhibit the highest price elasticity as procurement unbundling intensifies, while North Sea salvage contractors absorb steep premiums without volume reduction. Chinese manufacturers face compressed margins from GB standards enforcement even as export volumes expand.
China
SAMR's GB standards enforcement compels domestic compounders to maintain certified burst-pressure ratios exceeding baseline ISO requirements. The Yangtze River Delta and Shandong Peninsula clusters concentrate synthetic fiber weaving and rubber coating capacity. Qingdao-based manufacturers anchor cost structures through backward integration into nylon fabric reinforcement production.
Japan
METI coordinates with JIS standards bodies to validate airbag performance for seismic-zone shipyard operations, creating dual-compliance burdens for foreign suppliers. Osaka and Nagoya clusters absorb compliance costs through keiretsu relationships. Domestic manufacturers leverage captive polymer research to command premium positioning in heavy-lift applications.
South Korea
MFDS-aligned maritime safety protocols extend to salvage contractor equipment certification, filtering market access for non-compliant exporters. Busan-Ulsan shipyard clusters face maturity pressures as docking airbag demand stabilizes. Heavy-lift salvage contractors bear steepest compliance penalties, passing costs through emergency-response premiums.
Indonesia
Batam and Surabaya yard expansions concentrate procurement volume, creating localized economies of scale for regional suppliers. Service unbundling fragments traditional supply relationships as yards separate equipment purchase from installation supervision. European shipowners specify third-party marine warranty surveyor oversight in Batam's free-trade zone.
United Kingdom
North Sea platform decommissioning mandates drive demand for specialized modular airbag configurations. Contractors specify burst-pressure ratios exceeding baseline ISO thresholds by forty percent, compressing procurement to integrated manufacturers. Aberdeen-based offshore service providers anchor emergency-response equipment certification requirements.
Marine Airbags Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with compounders capturing specification-escalation premiums while assembly-only operators face margin compression. Three archetypes define competitive positioning: captive polymer researchers commanding heavy-lift salvage premiums, backward-integrated weavers anchoring cost structures, and modular architecture specialists differentiating in offshore decommissioning. Dominant competitive moves include strategic partnerships with synthetic fiber suppliers and geographic expansion into underpenetrated Sub-Saharan port markets.
Among Japanese industrial conglomerates, Yokohama Rubber Co. exemplifies the captive research archetype, while Bridgestone Corporation occupies a parallel position in elastomer formulation. Qingdao Luhang Marine Airbag and Fender Co., Ltd. represents the backward-integrated Chinese tier, and MAX Group anchors the modular specialization vector. These four names illustrate how competitive advantage concentrates around certified compounders rather than assembly scale.
| Leading Market Players |
|---|
| Yokohama Rubber Co. |
| Bridgestone Corporation |
| MAX Group |
| Qingdao Luhang Marine Airbag and Fender Co., Ltd. |
| Shanghai Tojoy Airbags |
| Beihai Marine Rubber Products |
| HI-SEA Marine |
| Eversafe Marine Engineering Co., Ltd. |
| Shandong Nanhai Airbag Engineering Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Shandong Peninsula weaving clusters shapes both supply concentration and price floors for certified compounders. GB standards enforcement by SAMR elevates certified manufacturers above uncertified assemblers, compressing margins at the lower tier while preserving premium positioning for integrated producers.
Pricing Analysis
Installation supervision and lifecycle documentation services drive lifetime value beyond equipment sale. Three-tier pricing structure across premium, standard, and economy levels separates salvage-grade aramid-reinforced units from ship-launching nylon configurations and basic docking bags. Cost compression in economy tiers is intensifying because Indonesian yards unbundle procurement from advisory services. Shipyards exhibit highest price sensitivity through competitive bidding, while North Sea salvage contractors absorb premiums without volume reduction.
Supply Chain Analysis
Inventory cycles for MDI and TDI feedstocks extend lead times during Asian petrochemical turnarounds. Manufacturing concentrates in China, South Korea, and Japan, with synthetic cord fabric weaving anchored in Shandong and Jiangsu provinces. Compounders draw from natural rubber spot markets in Bangkok and Kuala Lumpur, plus captive nylon-66 production. Single-source vulnerability concentrates among four Asian chemical producers for polyurethane precursors. Distribution runs through shipyard procurement consortia in Batam and Surabaya, with salvage contractors sourcing direct from certified compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against synthetic sling systems and hydraulic lift platforms that threaten airbag adoption in heavy-lift applications.
For Market Incumbents: Shield salvage-grade positioning by deepening captive polymer research capabilities and securing dual GB-JIS certification ahead of specification escalation. Anchor cost structures through backward integration into aramid weaving capacity. Counter service unbundling by bundling installation supervision with equipment procurement in Indonesian yards.
For New Entrants and Emerging Players: Lifecycle documentation and carbon accounting advisory gaps create entry points where incumbents under-serve China's MEE compliance requirements. Target Sub-Saharan port modernization in Lamu and Tema where supplier relationships remain unformed. Lead with certified compounder partnerships rather than assembly-only positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated compounders with captive fiber weaving and polymer research capabilities over assembly-scale operators. Long-term viability rests on certification moats widening through multi-standard compliance burdens. Watch for regional certification mutuality agreements as inflection indicators for procurement fragmentation versus consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aramid Weaving | Captive fiber supply secures burst-pressure specification premiums in North Sea salvage contracts. |
| Dual GB-JIS Certification Investment | Dual-compliance capability unlocks seismic-zone shipyard procurement in Osaka and Nagoya clusters. |
| UV-Resistant Coating R&D Program | Tropical port mandates in Singapore and Cartagena premiumize specification tiers for ozone protection. |
| Sub-Saharan Distribution Partnership | First-mover positioning in Lamu and Tema terminal expansions captures unformed supplier relationships. |
| Lifecycle Documentation Service Launch | China's MEE carbon accounting requirements create adjacent revenue streams beyond equipment sales. |
Research Approach
Initial hypotheses were tested against primary input from shipyard procurement directors, salvage contractor operations managers, marine warranty surveyors, and synthetic fiber technical sales leads and refined through secondary validation. Shipyard association membership directories, SAMR certification registries, customs trade data for rubber-coated textile exports, and offshore decommissioning project databases anchored quantitative sizing. Bottom-up equipment procurement volumes and top-down addressable market calculations were triangulated against manufacturer capacity disclosures.
Variance decomposition across product architecture, coating technology, application severity, and end-user procurement sophistication shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit escalation patterns. Modeled inputs included GB standards compliance timelines, aramid fiber adoption curves in salvage specifications, and Indonesian shipyard expansion schedules.
Forecasts assume regulatory continuity in China's SAMR enforcement, Japan's METI-JIS coordination, and South Korea's MFDS-aligned protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Global Foldable Inflatable Boats Market
Marine
Marine Fuel Injector Market
Marine
Shipbuilding Market
Marine
Marine Navigation System Market
Marine
Jet Boat Market
Marine
Marine Bearings Market
Marine
Unmanned Marine Vehicles Market
Marine
Singapore Container Transshipment Market
Marine
Yacht Painting and Maintenance Market
Marine
Marine Elevators Market
Marine
Electric Outboard Engines Market
Marine
Rigid Inflatable Boats (RIB) Market
Marine
Sailboat Market
Marine
Europe Recreational Boating Market
Marine
Marine Propeller Market
Marine
Europe ROV Market