
 Electric Outboard Engines Market | 2026-2036
Electric Outboard Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Outboard Engines Market Intelligence
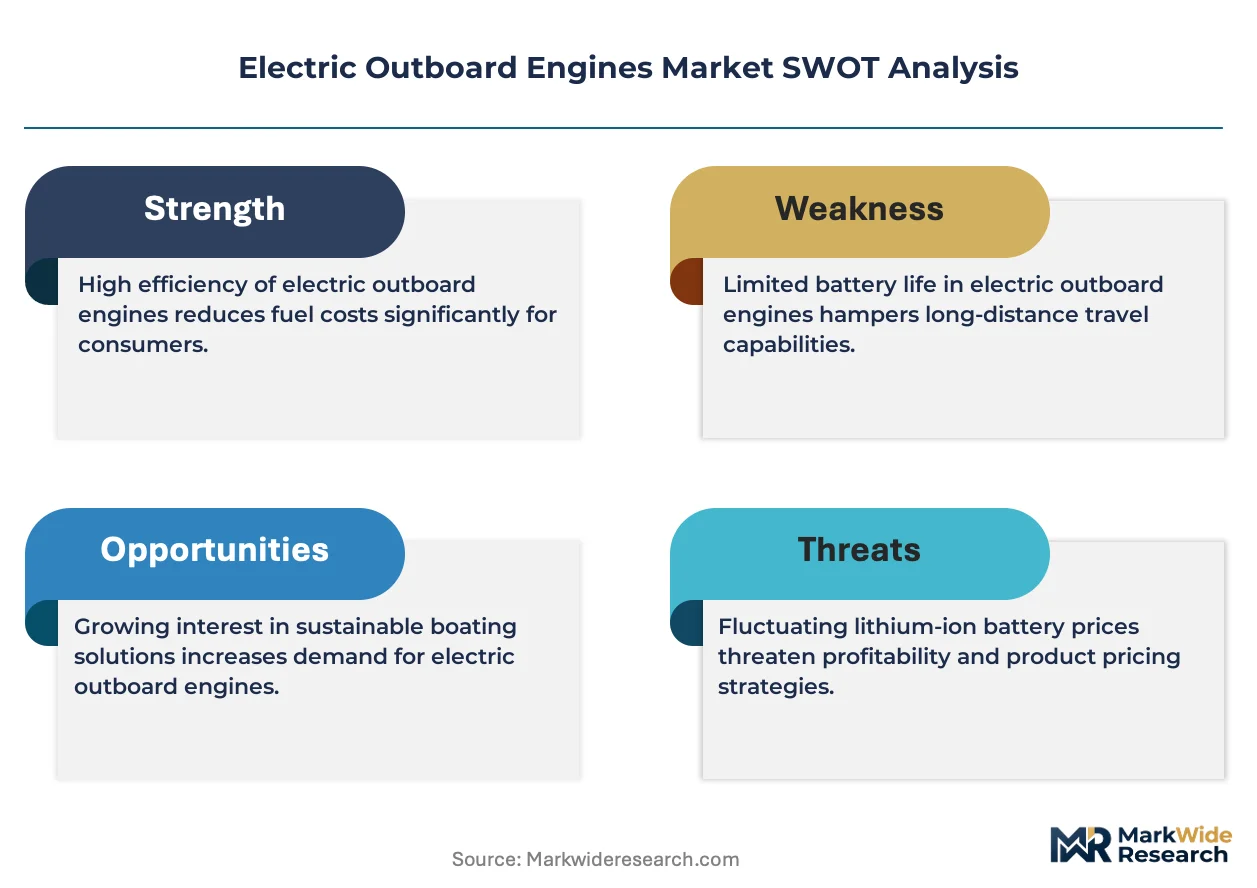
Recreational boating is realigning toward silent, emission-free propulsion as marina operators restrict fossil-fuel access. Torqeedo leverages its integrated battery-motor systems to dominate German and Austrian lake markets. Mercury Marine anchors its position through deep distribution networks in North American freshwater regions. ePropulsion competes aggressively on price in the Asian dinghy and tender segments.
Electric outboard engines convert stored electrical energy into mechanical thrust via submerged propellers, typically delivering 1–80 kW through brushless DC motors with lithium-ion battery packs rated for 500–2,000 charge cycles. Their primary purpose is to replace internal combustion propulsion in vessels where noise, emissions, or fuel logistics constrain operational flexibility. Portable engines and compact models occupy the highest volume tier, while high-power units capture concentrated margin pools in commercial fishing retrofit programs. GPS integration and regenerative braking represent the fastest-growing technology layer, though brushless DC motors remain the foundational architecture across all power classes.
The EPA enforces marine engine emissions standards under the Clean Air Act, while the EU Green Deal and F-Gas Regulation constrain fluorinated greenhouse gas use in cooling systems adjacent to propulsion electronics. California Air Resources Board rules now extend to pleasure craft under 100 horsepower, tightening product certification requirements for any vendor selling into U.S. waters. Stakeholders must monitor how battery safety standards from ISO and IEC evolve alongside national coast guard electrical system certifications, as compliance breadth will determine which suppliers retain market access across multiple jurisdictions.
Market Dynamics
Scandinavian marina operators are enforcing zero-emission access rules that force diesel-to-electric conversions across recreational fleets, compressing adoption timelines and rewiring procurement patterns toward integrated battery-motor systems.
Growth Catalysts
- EU Green Deal marine mandates:Binding emissions targets for coastal waters accelerate hull electrification requirements across Norwegian, Swedish, and Finnish fjord zones.
- Lithium-ion energy density improvements:Pack-level gains extend operational range for commercial fishing retrofits, opening high-power segments previously reserved for combustion engines.
- Fjord access restrictions:Norway's zero-emission vessel requirements in UNESCO-protected waterways create captive demand for electric propulsion in tour and leisure craft.
Market Restraints
- Battery raw material concentration:Cobalt and lithium refining capacity clusters in limited jurisdictions, exposing supply chains to geopolitical friction and input cost volatility.
- Energy storage weight penalties:Lithium-ion packs impose mass burdens that reduce payload capacity in smaller craft, constraining adoption in tender and dinghy categories.
- California Air Resources Board certification:Pleasure craft rules under 100 horsepower tighten product approval timelines and testing costs for vendors entering U.S. waters.
Strategic Opportunities
- German and Austrian lake markets:Inland waterway operators in Bavaria and Tyrol are retrofitting rental fleets ahead of anticipated national emissions standards.
- GPS-regenerative braking convergence:Integrated navigation-thrust systems enable route-optimized energy recovery, differentiating premium offerings in charter segments.
- Asian tender segments:Dinghy markets in coastal Thailand and Indonesia remain underpenetrated by electric alternatives, presenting volume expansion potential for price-optimized entrants.
Industry Challenges
- Marine electrical certification timelines:ISO and IEC battery safety standards evolve asynchronously with national coast guard electrical system rules, creating compliance fragmentation.
- Brushless DC motor repair skill scarcity:Specialized maintenance expertise for submerged propulsion systems concentrates in coastal manufacturing clusters, limiting service network density.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Outboard Engines Market |
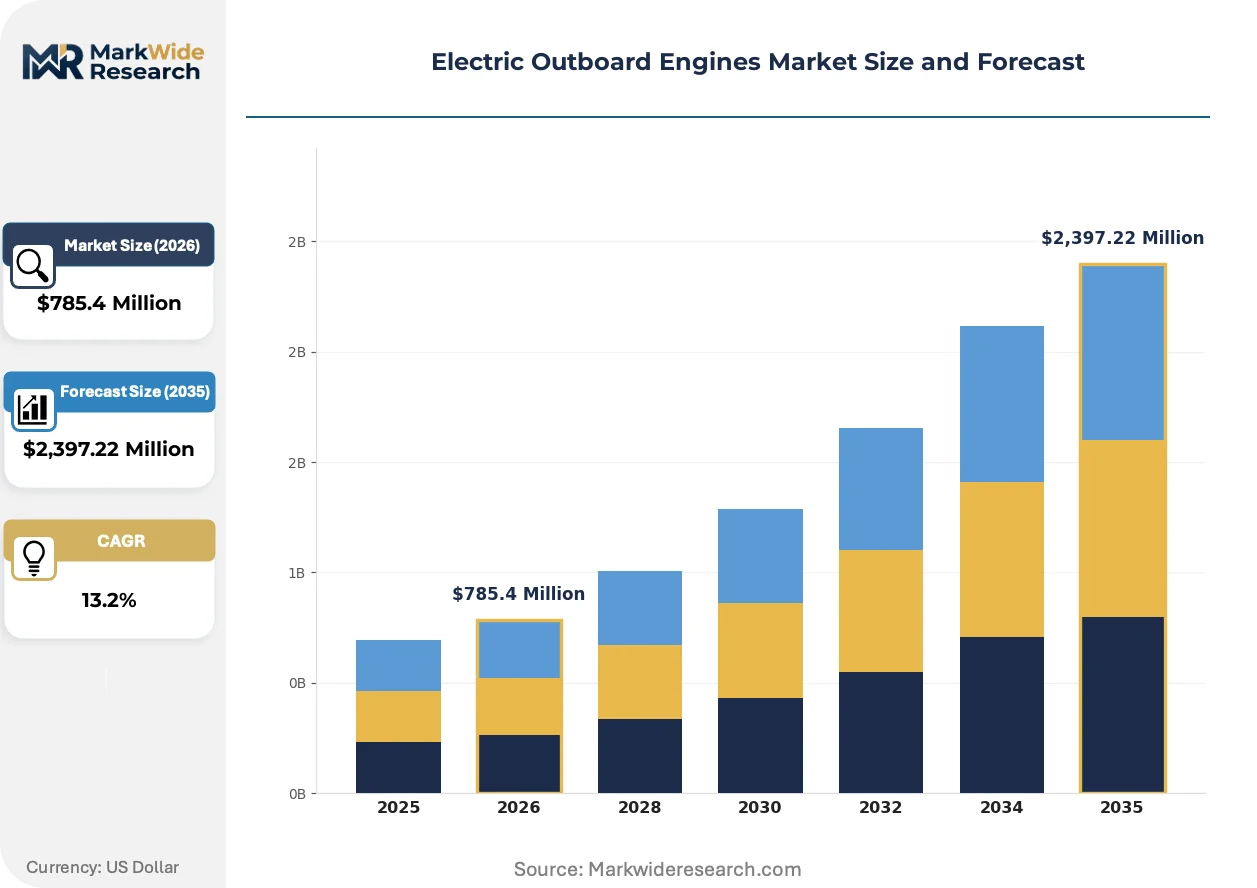
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $2,397.22 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Engines, Mid-Range Motors, High-Power Units, Compact Models Technology: Brushless DC Motors, Lithium-Ion Batteries, Regenerative Braking, GPS Integration Application: Recreational Boating, Commercial Fishing, Water Sports, Rental Fleets End User: Boat Manufacturers, Marine Service Providers, Rental Operators, Private Boat Owners |
| Companies Covered | ePropulsion, Oceanvolt, Torqeedo, Tohatsu, VETUS, Mercury Marine, TEMO, Green Marine, Vision Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Outboard Engines Market Strategic Shifts & Innovations
Battery-motor integration is compressing supplier tiers and shifting competitive advantage toward system-level optimization rather than component specialization.
Modular battery architectures are modularizing across the electric outboard sector. Swappable pack designs allow operators to extend range through hot-swap protocols rather than single large installations. Charter fleets in Scandinavian marinas are adopting these configurations fastest. This architecture is modularizing supply relationships, enabling third-party energy service providers to insert themselves between motor OEMs and end-users.
The EU F-Gas Regulation constrains fluorinated greenhouse gas use in cooling systems adjacent to propulsion electronics. Motor controllers and battery management systems require thermal management that previously relied on restricted refrigerants. Vendors are redesigning thermal architectures to comply. High-power commercial units face the steepest redesign costs and longest recertification timelines.
Silent propulsion is becoming a priced amenity in premium recreational segments. Buyers in Norwegian fjord tourism markets now specify noise thresholds in procurement contracts, displacing decibel-based specifications with experiential ratings. Marina operators are responding by restricting combustion engine access during peak visitor hours. This preference shift is most visible in Sognefjord and Geirangerfjord charter concessions.
Electric Outboard Engines Market Segmentation
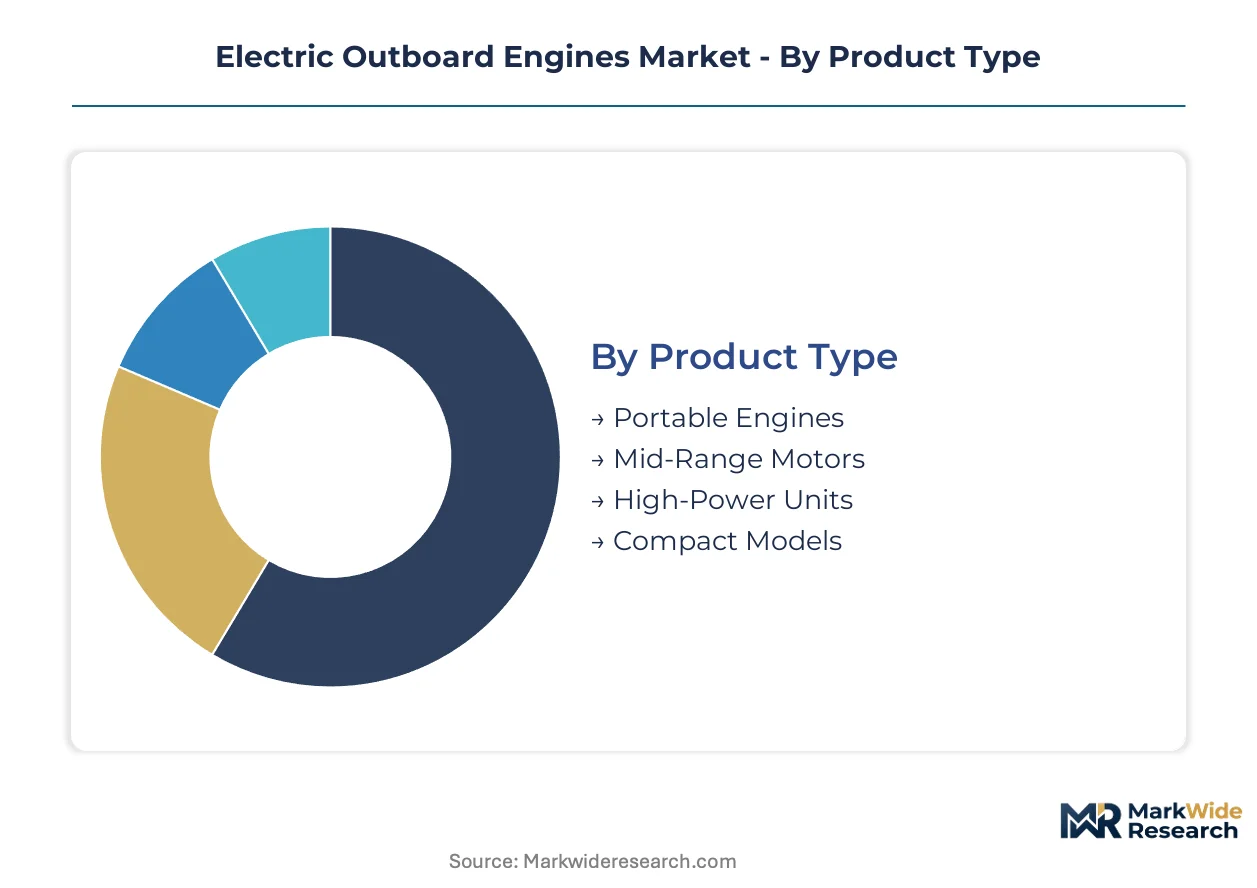
Electric outboard engines fragment across power classes and integration architectures that determine pricing flexibility and retrofit complexity. Understanding these divisions reveals where battery-motor bundling commands premium positioning versus where modular competition erodes margins.
Product Type:
Portable engines dominate unit volumes while high-power units capture concentrated margin pools in commercial retrofit programs.
- Portable Engines:These sub-5 kW units integrate sealed lithium-ion packs with tiller-steered brushless motors for dinghies and tenders. Scandinavian rental operators in Oslo and Bergen fjords are standardizing these for zero-emission fleet conversions ahead of marina access restrictions.
- High-Power Units:Systems delivering 20-80 kW through liquid-cooled brushless architectures replace diesel auxiliaries on commercial fishing vessels. Norwegian and Icelandic retrofit programs are absorbing these units fastest as fjord access rules tighten for diesel craft above 15 meters.
- Mid-Range Motors:5-20 kW shaft-drive systems target leisure cruisers in German and Austrian lake districts where noise ordinances now prohibit combustion operation after 2200 hours.
- Compact Models:Ultralight sub-3 kW units sacrifice range for portability in Asian tender markets where shore power access remains intermittent.
Today's leader: Portable Engines. Tomorrow's challenger: High-Power Units.
Technology:
Brushless DC architectures anchor every power class while GPS-regenerative convergence differentiates premium charter offerings.
- Brushless DC Motors:Permanent magnet synchronous designs deliver 85-92% efficiency across 1,000-6,000 RPM ranges with sealed stator housings rated for continuous saltwater immersion. All Norwegian commercial operators now specify IP67 minimum ingress protection for warranty eligibility.
- GPS Integration:Route-optimized thrust algorithms reduce energy consumption 12-18% on predictable charter circuits. Sognefjord tour operators are mandating these systems for new concession awards.
- Lithium-Ion Batteries:NMC and LFP chemistries at 150-200 Wh/kg pack density impose 15-40% weight penalties versus equivalent diesel fuel energy storage.
- Regenerative Braking:Kinetic recovery during deceleration extends range 8-14% in stop-start harbor maneuvering, most valued in Swedish archipelago shuttle services.
Brushless DC Motors anchor current procurement. GPS Integration is climbing the fastest as charter specifications harden.
Application:
Recreational boating absorbs the highest unit volumes while commercial fishing retrofits justify system-level pricing premiums.
- Recreational Boating:Leisure craft under 8 meters drive portable and compact segment demand, particularly in Finnish lakeland regions where combustion engine bans now cover 340 protected water bodies.
- Commercial Fishing:Diesel-to-electric auxiliary conversions on coastal trawlers concentrate in Norway's Lofoten and Senja districts where UNESCO fjord access restrictions now prohibit fossil fuel propulsion during tourist season.
- Water Sports:Wakeboarding and waterskiing tow boats require sustained high-thrust output that strains battery thermal management, limiting electric penetration to sub-20 kW niche applications.
- Rental Fleets:Bavarian and Tyrolean inland operators are pre-empting anticipated Austrian national emissions standards with full-fleet electrification programs.
Recreational Boating holds volume dominance. Commercial Fishing presents the steepest expansion trajectory as regulatory deadlines approach.
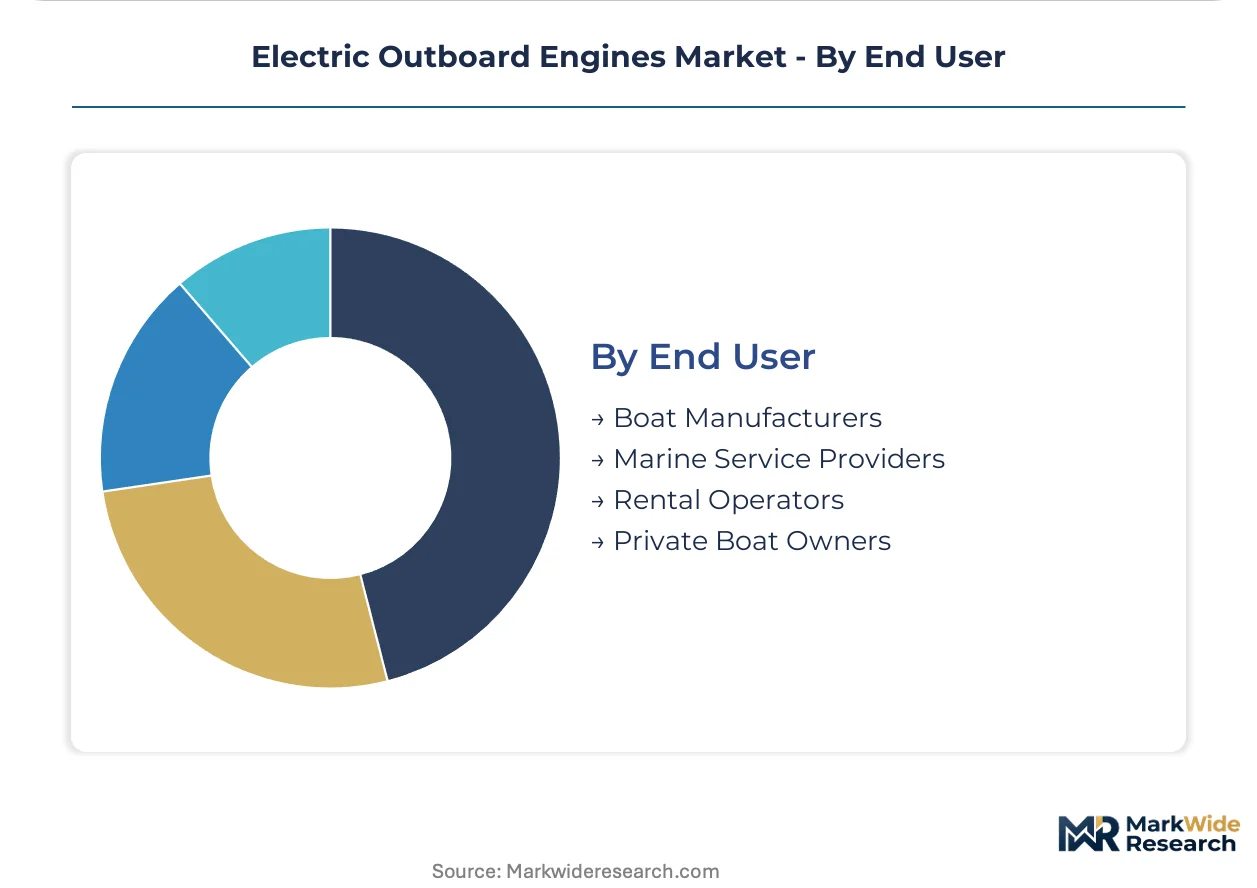
End User:
Rental operators move fastest on standardized procurement while private owners fragment across price-performance tradeoffs.
- Rental Operators:Fleet-scale purchasing enables volume negotiations for integrated battery-motor systems with hot-swap protocols. Geirangerfjord concessionaires are consolidating procurement through cooperative purchasing agreements.
- Boat Manufacturers:Hull-integrated electric propulsion from production is gaining share in Swedish and Finnish aluminum boat exports to EU markets with tightening marina access rules.
- Marine Service Providers:Retrofit specialists in Stavanger and Bergen are certifying for high-voltage marine electrical work as ISO battery safety standards evolve.
- Private Boat Owners:Individual purchasers concentrate in German lake districts and Norwegian coastal municipalities with existing shore power infrastructure.
Rental Operators currently dictate procurement standards. Boat Manufacturers are gaining share fastest through OEM integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scandinavian fjord zones anchor demand concentration for electric outboard engines, with regulatory pressure cascading into German lake districts and Asian tender markets as supply chains adapt to zero-emission mandates.
Norway
UNESCO-protected fjord access restrictions and zero-emission vessel requirements in Sognefjord and Geirangerfjord drive diesel-to-electric conversions across tour and leisure craft. The Norwegian Maritime Authority enforces strict coastal emissions protocols that prohibit fossil fuel propulsion during tourist season. Stavanger and Bergen harbor clusters host retrofit specialists certifying for high-voltage marine electrical work.
Germany
Bavarian lake rental operators pre-empt national emissions standards with full-fleet electrification programs targeting inland waterway compliance. The Federal Motor Transport Authority (KBA) coordinates with EU Green Deal implementation timelines for pleasure craft certification. Munich and Lake Constance industrial zones concentrate integrated battery-motor system assembly for Central European distribution.
Sweden
Archipelago shuttle services and Stockholm marina operators enforce combustion engine bans after 2200 hours, accelerating silent propulsion procurement. The Swedish Transport Agency aligns with EU F-Gas Regulation constraints on cooling systems adjacent to propulsion electronics. Gothenburg and Malmö coastal manufacturing clusters specialize in brushless DC motor repair networks.
United States
California Air Resources Board rules extending to pleasure craft under 100 horsepower tighten product certification requirements for vendors entering U.S. waters. The EPA enforces marine engine emissions standards under the Clean Air Act across coastal and freshwater jurisdictions. Pacific Northwest and Great Lakes metropolitan areas concentrate private owner demand where shore power infrastructure exists.
Thailand
Coastal dinghy and tender markets remain underpenetrated by electric alternatives, presenting volume expansion potential for price-optimized entrants targeting intermittent shore power access. The country's national maritime regulator develops battery safety standards alongside ISO and IEC evolution. Phuket and Pattaya harbor zones absorb compact ultralight units for tourism fleet diversification.
Electric Outboard Engines Market Key Industry Players
Capacity expansion dominates the current landscape as vendors race to secure lithium-ion supply agreements and brushless DC motor manufacturing scale ahead of regulatory deadlines. The market structures around three tiers: integrated battery-motor system specialists, component-focused motor manufacturers, and price-optimized Asian fabricators. Strategic archetypes include system-level optimizers pursuing GPS-regenerative convergence, regional champions leveraging local certification relationships, and volume players targeting modular hot-swap architectures. M&A activity concentrates on battery technology access, while geographic expansion targets Scandinavian marina procurement consolidation.
Among integrated system specialists, Torqeedo GmbH and ePropulsion Technology Ltd. exemplify divergent geographic positioning strategies. Torqeedo anchors the premium tier through German engineering credibility and Austrian lake market penetration. ePropulsion occupies the volume-driven segment with Asian manufacturing scale targeting underpenetrated tender markets. Vision Marine Technologies Inc. represents North American regulatory compliance specialization, navigating EPA and California Air Resources Board certification complexity. Mercury Marine sits within the established marine propulsion conglomerate archetype, leveraging deep distribution networks across freshwater regions. Oceanvolt Oy exemplifies the Nordic system integrator model, capitalizing on fjord access restriction timing in Finnish and Swedish home markets.
| Leading Market Players |
|---|
| ePropulsion |
| Oceanvolt |
| Torqeedo |
| Tohatsu |
| VETUS |
| Mercury Marine |
| TEMO |
| Green Marine |
| Vision Marine |
| Others |
Cost & Logistics Intelligence
Lithium-ion cell costs cascade through three distinct pricing tiers as cobalt and nickel refining concentrates in Chinese, South Korean, and Japanese processing facilities. Battery pack integration premiums separate integrated system vendors from component assemblers across Scandinavian procurement contracts.
Pricing Analysis
Distributor margins compress most severely in portable engine segments where ePropulsion and compact Asian fabricators compete on landed cost. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—EU Green Deal compliance commands 15-25% premiums over baseline CE-marked units. Pricing pressure stems from raw material volatility in lithium carbonate markets, with Norwegian rental operators squeezing procurement through cooperative purchasing agreements. Charter fleet buyers exhibit lowest price sensitivity, prioritizing GPS-regenerative integration and hot-swap protocols over unit economics.
Supply Chain Analysis
Regional distribution centers in Hamburg, Gothenburg, and Singapore anchor hub-and-spoke patterns serving marina clusters and inland waterway operators. Manufacturing draws from Chinese lithium refining, South Korean cathode production, and German motor controller assembly. Brushless DC stators, battery management systems, and thermal management hardware constitute critical component dependencies. Single-source vulnerability concentrates in rare earth magnet supply for permanent motor architectures. Distribution runs through marine specialty distributors with deep relationships to Scandinavian harbor authorities and German lake fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric outboard market compounds regulatory momentum as EU Green Deal marine emissions deadlines harden procurement timelines across Norwegian, Swedish, and Finnish fjord zones.
For Market Incumbents: Deepen backward integration into lithium-ion pack assembly to defend margin position against modular hot-swap entrants eroding system-level pricing. Secure ISO 16315 and IEC 62619 certification ahead of evolving coast guard electrical standards to maintain marina access eligibility. Capacity expansion in Baltic manufacturing clusters reduces logistics exposure to Asian supply disruption. For New Entrants and Emerging Players: Capture underpenetrated Asian tender markets in coastal Thailand and Indonesia where shore power infrastructure gaps favor ultralight compact designs over integrated systems. Price-optimized direct distribution bypassing marine specialty channels unlocks volume in dinghy replacement cycles. Partner with local tourism operators for fleet trial programs that generate specification influence. For Investors and Strategic Acquirers: Roll-up economics work for regional service networks because brushless DC motor repair skill scarcity concentrates in coastal manufacturing clusters, creating captive aftermarket revenue streams. Target mid-cap system integrators with established Scandinavian certification relationships and existing lithium supply agreements. Watch for inflection when Norwegian Maritime Authority extends zero-emission requirements beyond UNESCO fjords to commercial fishing harbors.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Motor System Integration | Compresses supplier tiers and shifts competitive advantage toward route-optimized energy recovery algorithms. |
| Modular Hot-Swap Architecture | Enables third-party energy service providers to insert between motor OEMs and Scandinavian charter operators. |
| Scandinavian Certification Investment | Secures access to Sognefjord and Geirangerfjord concession procurement as zero-emission rules tighten. |
| Asian Manufacturing Scale-Up | Captures cost-position in underpenetrated Thailand and Indonesia tender markets with intermittent shore power. |
| GPS-Regenerative Convergence | Differentiates premium offerings in Swedish archipelago shuttle services through route-optimized thrust algorithms. |
Research Approach
Multiple input streams — regulatory filing analysis, marina operator procurement records, and motor OEM technical documentation — were reconciled against primary fieldwork with Scandinavian fleet managers, German inland waterway authorities, and Asian tender market distributors. Secondary validation drew from EU Green Deal implementation timelines, Norwegian Maritime Authority enforcement protocols, and ISO/IEC battery safety standard evolution. Bottom-up unit shipment estimates from power class and application segments were cross-referenced against top-down market value reconstructions.
Historical adoption curves in Scandinavian fjord zones were cross-referenced against expert panel assessments of regulatory acceleration timelines across the projection horizon. Segmentation modeling incorporated power class, integration architecture, application category, and end-user procurement pattern. CAGRs were derived from slope-consistency checks against lithium-ion energy density improvement trajectories and fjord access restriction implementation schedules.
Underlying measurement precision varies by segment; high-power commercial fishing retrofits carry tighter precision than fragmented private owner categories. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and lithium supply chain stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
GCC ROV Market
Marine
Marine Spreader Lights Market
Marine
Offshore AUV and ROV Market
Marine
Boat Hook Market
Marine
Azimuth Thrusters Market
Marine
Marine Fasteners Market
Marine
Steel Ship Plate Market
Marine
Autonomous Ships Market
Marine
Marine Fuel Injector Market
Marine
China Controllable Pitch Marine Propeller Market
Marine
Marine Electronics Market
Marine
Europe ROV Market
Marine
Marine Engine Cooling Systems Market
Marine
Asia-Pacific Electric Boat Market
Marine
Singapore Container Transshipment Market
Marine
Marine Base Steering Gear Market