
 Marine Navigation System Market | 2026-2036
Marine Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Navigation System Market Outlook
Marine electronics distribution is fragmenting as direct-to-fleet procurement and specialized maritime integrators displace traditional chandlery networks. Furuno leverages its transducer manufacturing depth to sustain premium positioning in commercial radar. Garmin competes aggressively in recreational multifunction displays, while Wärtsilä Transas dominates integrated bridge system contracts through its simulation-to-live-platform continuity.
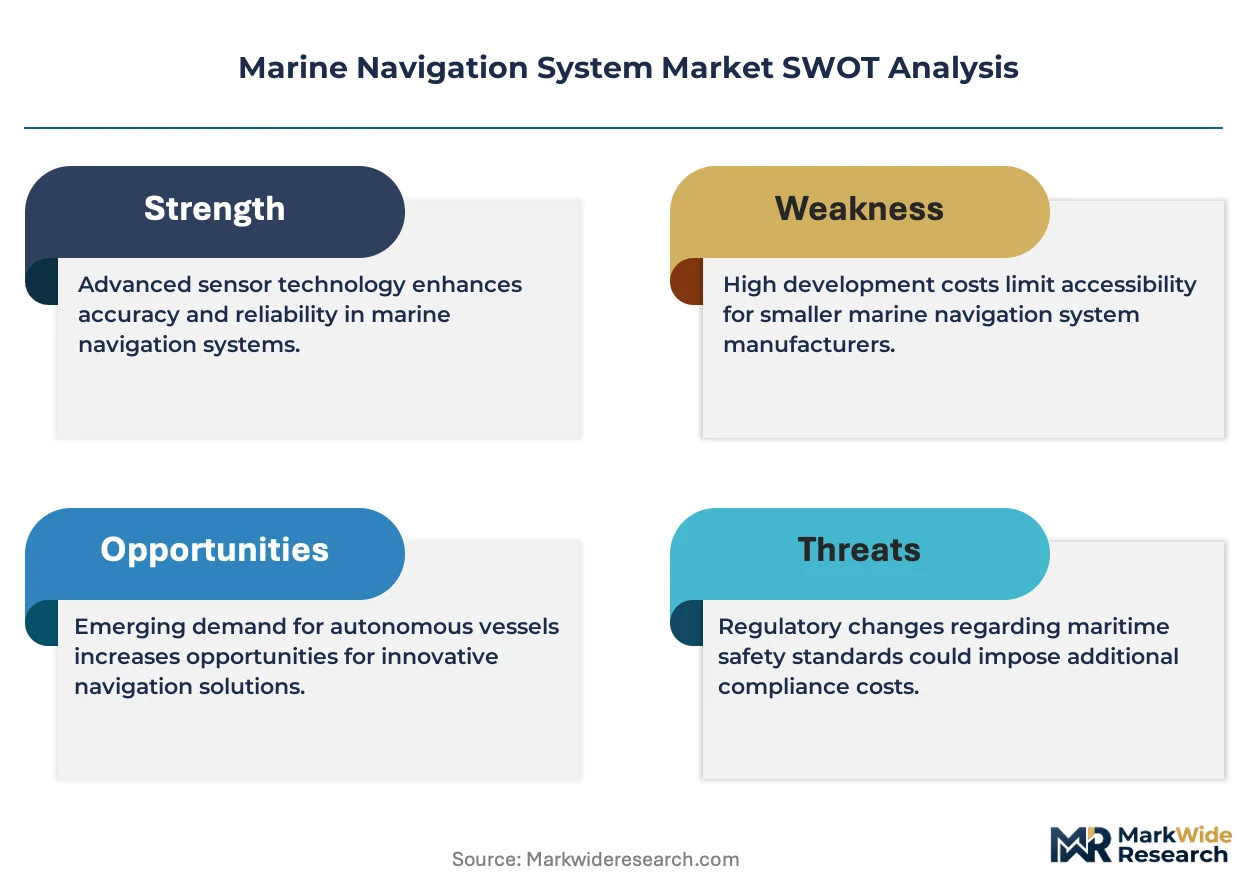
A marine navigation system integrates position-fixing sensors, electronic charting, collision avoidance, and voyage planning into a unified bridge environment, typically processing GNSS signals within sub-meter accuracy while integrating gyrocompass heading data for dynamic positioning. ECDIS and AIS product lines command the deepest replacement cycles as regulatory mandates enforce standardized carriage requirements across tonnage classes. Satellite-based and hybrid technology segments attract the fastest upgrade velocity as operators layer GNSS augmentation with inertial backup to counter jamming vulnerabilities.
The International Maritime Organization's SOLAS conventions, the EU MRV regulation, and the US Coast Guard's NVIC standards collectively mandate minimum navigation equipment carriage while shaping product certification pathways. These frameworks force manufacturers to maintain multi-jurisdiction type-approval pipelines, elevating compliance costs that favor established suppliers with dedicated regulatory affairs capacity. Stakeholders must monitor emerging cyber-security notation requirements from classification societies as these will soon dictate system architecture decisions and supplier qualification criteria.
Market Dynamics
ECDIS refresh cycles are compressing as shipowners front-load replacements ahead of IMO's cyber-security notation deadlines, forcing bridge architecture decisions years before mandatory enforcement dates.
Growth Catalysts
- SOLAS Chapter V:The International Maritime Organization's carriage requirements for electronic chart display and information systems on cargo vessels above 3,000 gross tonnage sustain replacement demand across aging commercial fleets.
- GNSS augmentation layering:Commercial operators in the Strait of Malacca and Singapore anchorage zones are deploying multi-constellation receivers with inertial backup to counter spoofing incidents.
- East Asian shipbuilding:South Korean and Chinese yards are specifying integrated bridge packages on newbuild container vessels and LNG carriers, concentrating demand in Ulsan and Ningbo-Zhoushan clusters.
Market Restraints
- Semiconductor supply concentration:Specialized GNSS receiver chipsets and marine-grade gyrocompass sensors depend on fabrication capacity concentrated in Taiwan and South Korea, exposing lead times to geopolitical friction.
- Type-approval pipeline costs:Manufacturers must maintain parallel certification tracks with the US Coast Guard's NVIC standards, Japan's Ministry of Land, Infrastructure, Transport and Tourism, and the EU's Marine Equipment Directive, elevating fixed compliance overhead.
- Extended asset lives:Bridge electronics on deep-sea vessels routinely operate fifteen to twenty years, stretching replacement intervals beyond technology refresh rates in adjacent industrial sectors.
Strategic Opportunities
- Unmanned surface vessels:Autonomous cargo platforms and offshore survey craft require redundant navigation architectures with no human backup, opening specification windows for sensor fusion stacks.
- Indian coastal fleet:The country's national shipping regulator is tightening local vessel equipment standards under revised Merchant Shipping Act provisions, creating compliance-driven upgrade cycles for domestic tonnage.
- Remote maintenance channels:Satellite connectivity improvements are enabling predictive diagnostics and over-the-air software updates, unbundling traditional service contracts and opening recurring revenue streams.
Industry Challenges
- Cyber-security certification timelines:Classification societies including Lloyd's Register and DNV are introducing notation requirements that lack harmonized test protocols, forcing manufacturers to run parallel validation programs.
- Integration complexity:Legacy autopilot and dynamic positioning systems from 1990s installations resist seamless data exchange with modern ECDIS networks, demanding costly middleware development or full bridge replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Navigation System Market |
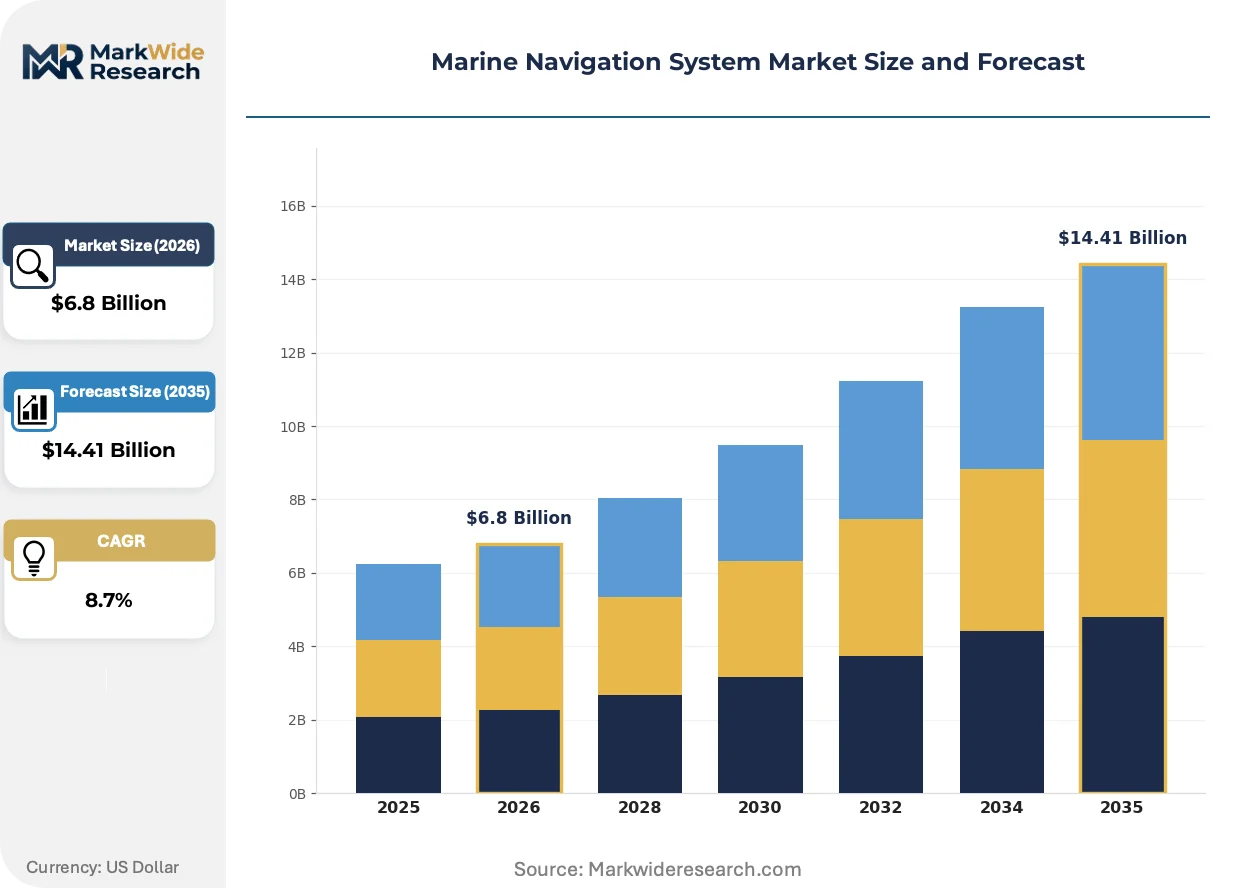
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radar Systems, GPS Receivers, ECDIS, AIS Technology: Inertial Navigation, Satellite-based, Optical Systems, Hybrid Systems Application: Commercial Shipping, Recreational Boating, Offshore Oil & Gas, Fishing Vessels End User: Shipping Companies, Government Agencies, Defense Forces, Private Yacht Owners |
| Companies Covered | Simrad, Navionics, Furuno, Humminbird, C-MAP, Raymarine, Wärtsilä Transas, Lowrance, Garmin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Navigation System Market Strategic Shifts
Synthetic sensor environments are displacing discrete hardware modules across commercial bridge architectures, compressing physical footprint while elevating software dependency. This shift redefines supplier value capture and fleet upgrade economics.
Software-defined radar is virtualizing the signal processing chain that historically required dedicated hardware arrays. Container lines operating on Asia-Europe routes are piloting these systems to reduce below-deck electronics volume and simplify spare parts logistics. The technology is virtualizing maintenance workflows, allowing shore-based technicians to diagnose antenna performance without vessel boarding.
The EU's CSRD disclosure requirements are extending to maritime equipment suppliers, mandating lifecycle emissions documentation for bridge systems sold into European-flagged fleets. Component manufacturers must now track embedded carbon in gyrocompass housings and display assemblies. Radar and ECDIS suppliers serving Hamburg and Rotterdam-based ship managers are restructuring supply chains to capture this data.
Fleet operators are consolidating vendor relationships to reduce interface complexity, favoring suppliers offering integrated position-fixing, charting, and collision avoidance under unified software platforms. Specialized maritime integrators in Singapore and Oslo are displacing traditional chandlery procurement for deep-sea vessel classes. This concentration is most visible among Greek and German tanker owners seeking single-point accountability for bridge system performance.
Marine Navigation System Market Segmentation
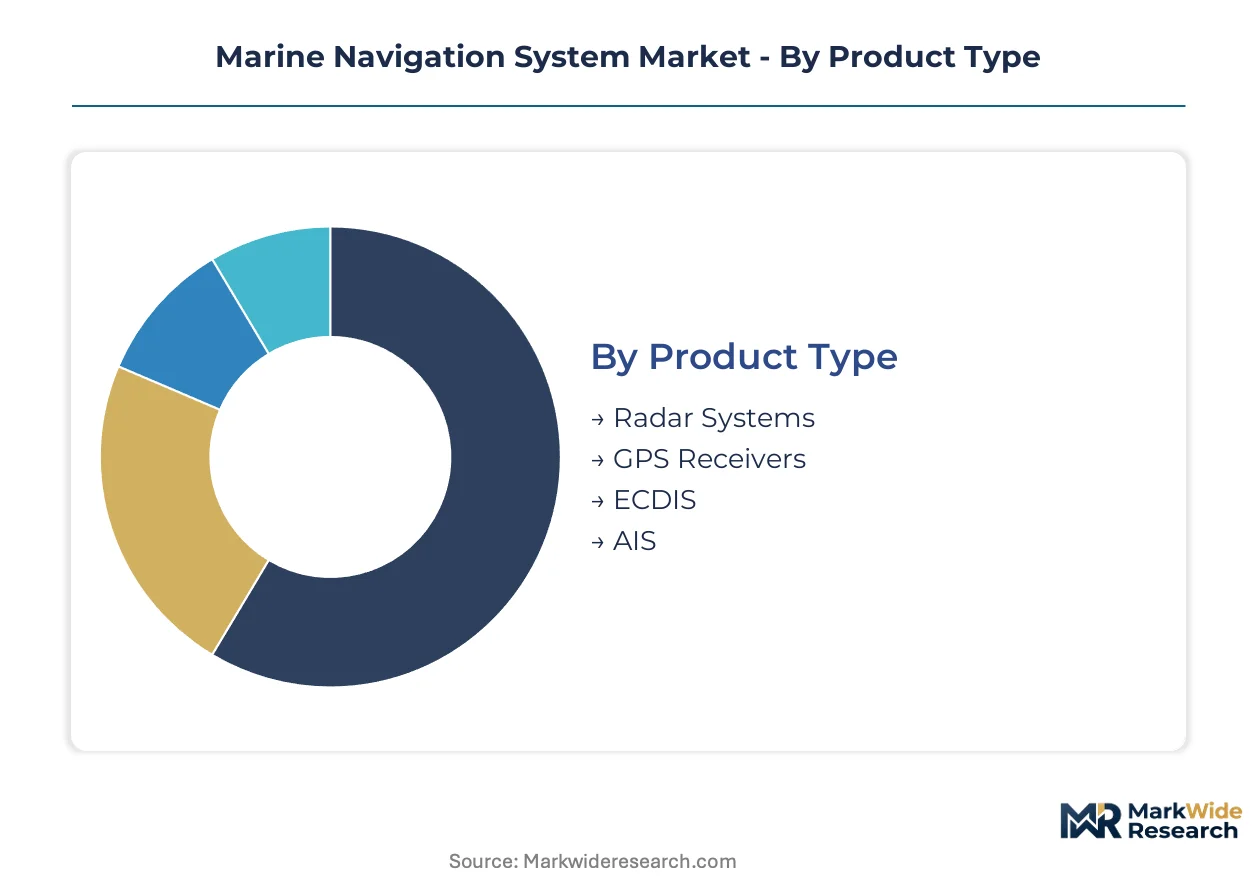
Marine navigation system procurement splits across regulatory mandates, vessel operating profiles, and technology refresh cycles. Segment boundaries blur as integrated bridge architectures consolidate formerly discrete product categories.
Product Type:
Commercial fleets prioritize carriage compliance over performance differentiation, while recreational buyers emphasize display integration and ease of use.
- ECDIS:Electronic chart display and information systems process vector chart data with mandatory type-approval under SOLAS Chapter V. Container lines operating Asia-Europe routes front-load replacements ahead of cyber-security notation deadlines from Lloyd's Register and DNV.
- AIS:Automatic identification systems broadcast vessel position, course, and speed to shore stations and nearby traffic. Demand concentrates in Singapore and Rotterdam port zones where VTS integration mandates drive Class A transponder upgrades for cargo vessels above 300 gross tonnage.
- Radar Systems:X-band and S-band arrays provide collision avoidance in reduced visibility; software-defined variants are gaining trial deployments.
- GPS Receivers:Multi-constellation units with Galileo and BeiDou augmentation now standard for commercial installations.
Established volume favors ECDIS; emerging adoption favors software-defined radar.
Technology:
Cost tier determines architecture choices, with premium vessels layering redundant systems while coastal fleets minimize equipment spend.
- Satellite-based:GNSS receivers leveraging GPS, GLONASS, Galileo, and BeiDou constellations deliver meter-level accuracy with WAAS or EGNOS augmentation. Operators in the Strait of Malacca deploy multi-frequency units with inertial backup following documented spoofing incidents.
- Hybrid Systems:Fused GNSS-inertial configurations maintain position fixes during satellite denial events. Offshore oil and gas platforms specify these for dynamic positioning redundancy in the North Sea and Gulf of Mexico.
- Inertial Navigation:Ring laser gyro and fiber optic gyro systems provide dead-reckoning capability independent of external signals.
- Optical Systems:Celestial and horizon-reference units serve military applications requiring emission control.
Volume concentration sits with satellite-based; hybrid configurations are climbing the fastest.
Application:
Customer type shapes specification intensity, with asset value and crew size driving redundancy requirements.
- Commercial Shipping:Deep-sea cargo fleets face mandatory ECDIS and AIS carriage with classification society oversight. Greek and German tanker owners are consolidating vendor relationships to secure single-point accountability for integrated bridge performance.
- Offshore Oil & Gas:Drillships and production platforms require redundant dynamic positioning with sub-meter accuracy. South Korean yards in Ulsan specify integrated packages for newbuild LNG carriers.
- Recreational Boating:Multifunction displays with charting and sonar integration dominate private yacht installations.
- Fishing Vessels:Smaller tonnage faces emerging equipment mandates under revised national regulations.
Commercial shipping anchors procurement volume; offshore oil and gas commands premium pricing tiers.
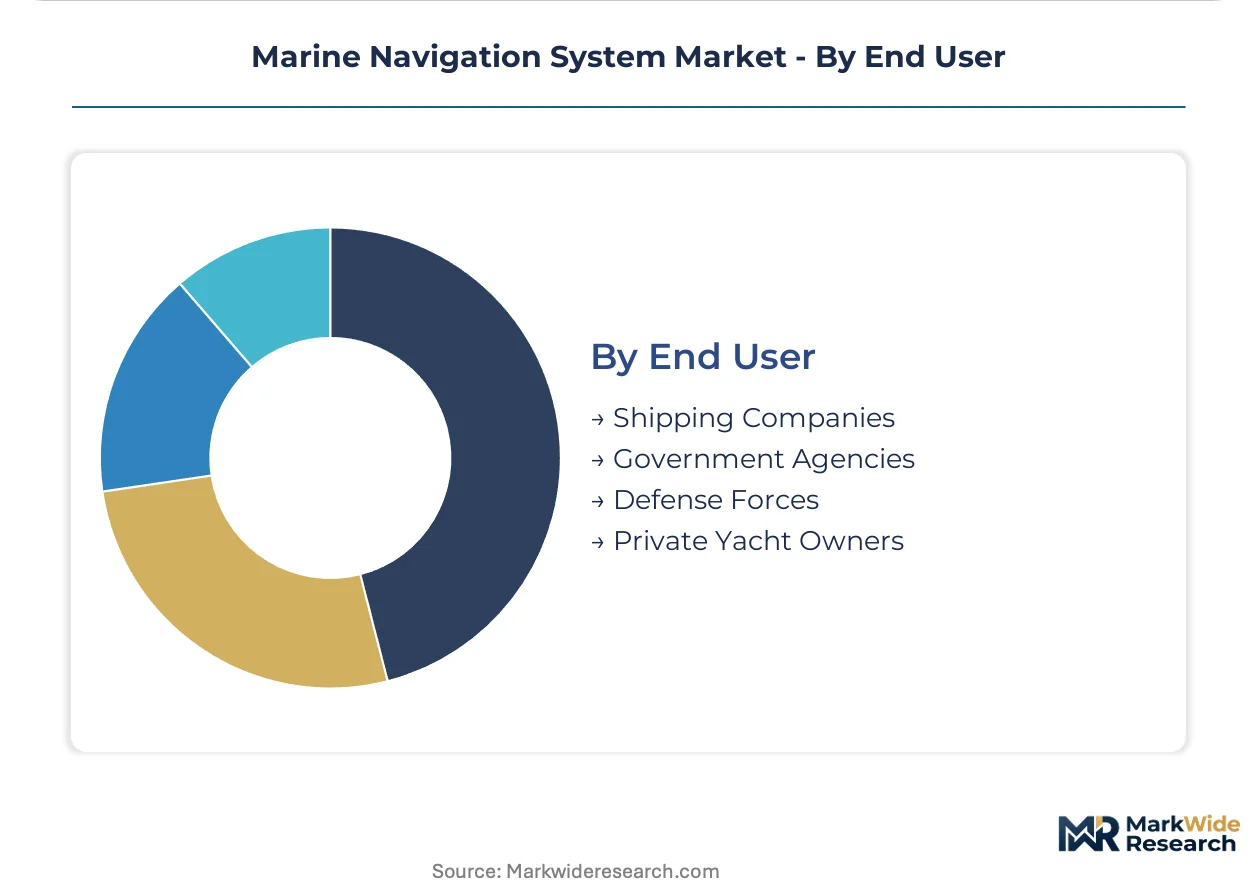
End User:
Procurement authority determines contract structure, with fleet operators favoring framework agreements and government buyers requiring tender compliance.
- Shipping Companies:Container lines and bulk operators negotiate multi-vessel packages with service bundling. Direct-to-fleet procurement is displacing traditional chandlery channels for deep-sea classes.
- Government Agencies:Coast guards and maritime administrations specify mission-critical systems with extended support obligations. The US Coast Guard's NVIC standards and Japan's Ministry of Land, Infrastructure, Transport and Tourism approvals create parallel certification requirements.
- Defense Forces:Naval specifications emphasize emission control and anti-jam resilience.
- Private Yacht Owners:Individual buyers prioritize brand recognition and display aesthetics over technical differentiation.
Shipping companies drive aggregate volume; government agencies impose the most stringent qualification barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shipyards in South Korea command premium pricing for integrated bridge packages, while Chinese manufacturers compete on cost efficiency for coastal fleet retrofits. This asymmetry shapes procurement patterns across East Asian clusters. Regulatory divergence between the US Coast Guard's NVIC standards and Japan's Ministry of Land, Infrastructure, Transport and Tourism type-approval requirements fragments vendor qualification pipelines.
South Korea
HHI and Samsung Heavy Industries drive demand for redundant dynamic positioning systems on LNG carriers and ultra-large container vessels. The country's national shipping regulator enforces stringent equipment certification under revised maritime safety provisions. Ulsan shipyards specify integrated bridge packages that fuse ECDIS, radar, and autopilot functions into unified control architectures.
China
State-owned COSCO and China Merchants Energy Shipping are front-loading ECDIS replacements ahead of cyber-security notation deadlines. The Ministry of Transport's domestic vessel equipment standards create compliance-driven upgrade cycles for coastal tonnage. Ningbo-Zhoushan and Shanghai clusters concentrate newbuild specification activity for container vessels and bulk carriers.
Japan
NYK Line and Mitsui O.S.K. Lines prioritize sensor fusion stacks with inertial backup for Strait of Malacca transits. METI's industrial standards harmonization efforts streamline type-approval processes for domestic manufacturers. Nagoya and Kobe maritime districts host specialized integrators serving deep-sea tanker and car carrier fleets.
United States
Matson and Crowley Maritime are deploying multi-constellation GNSS receivers with anti-spoofing firmware for Pacific route operations. The US Coast Guard's NVIC 01-16 and subsequent amendments mandate specific ECDIS performance standards for Jones Act vessels. Houston and Seattle house maritime integrators specializing in offshore supply vessel and tugboat bridge retrofits.
Germany
Hapag-Lloyd and Oldendorff Carriers consolidate vendor relationships to secure single-point accountability for integrated bridge performance. The EU's Marine Equipment Directive and CSRD disclosure requirements impose dual compliance burdens on equipment procurement. Hamburg and Bremen clusters concentrate ship management firms driving specification decisions for global tanker and bulk fleets.
Marine Navigation System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying sensors, transducers, and display modules. The vendor structure concentrates around three to four full-bridge suppliers while fragmenting across niche sensor manufacturers. Strategic archetypes include simulation-to-live-platform continuity providers, transducer-integrated radar specialists, and recreational multifunction display aggregators. Dominant competitive moves encompass direct-to-fleet procurement channel development and regulatory affairs capacity expansion to manage multi-jurisdiction type-approval pipelines.
Among Japanese electronics manufacturers, Furuno anchors the premium commercial radar segment through transducer manufacturing depth. Garmin occupies a position within recreational multifunction displays, competing aggressively on charting and sonar integration. Wärtsilä Transas exemplifies the integrated bridge system archetype, leveraging simulation platform continuity to secure live-vessel contracts. These three represent distinct competitive vectors: component-integrated premium positioning, consumer-facing display aggregation, and enterprise-scale platform integration.
| Leading Market Players |
|---|
| Simrad |
| Navionics |
| Furuno |
| Humminbird |
| C-MAP |
| Raymarine |
| Wärtsilä Transas |
| Lowrance |
| Garmin |
| Others |
Value Chain & Pricing Dynamics
The Asia-Europe container corridor's freight rate volatility compresses margins for bridge electronics procurement, concentrating pricing power with South Korean and Taiwanese component suppliers while forcing shipowners toward configured-to-order ECDIS packages that bundle cyber-security certification premiums.
Pricing Analysis
Configured-to-order pricing for integrated bridge systems commands spreads of 40-60 percent above standard ECDIS configurations, with differentiation driven by Lloyd's Register cyber-security notation tier and volume-scale procurement frameworks. Price erosion runs through entry-level GPS receiver segments as Chinese manufacturers saturate coastal fleet retrofits. Container lines exhibit lowest price sensitivity given regulatory mandate deadlines, while independent fishing vessel operators face acute budget constraints.
Supply Chain Analysis
Export-control restrictions on ring laser gyro technology limit flows from Japanese and European suppliers to Chinese yards, forcing procurement shifts toward South Korean alternatives. Marine-grade GNSS chipsets draw from fabrication capacity concentrated in Taiwan and South Korea, with gyrocompass sensors and phased-array radar modules sourced from Japan and Germany. Single-source vulnerability in gyroscope MEMS fabrication creates chokepoint exposure. Distribution runs through specialized maritime integrators in Singapore and Hamburg rather than traditional chandlery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine navigation systems sit in early-cycle expansion as unmanned surface vessel architectures create specification windows for redundant sensor fusion stacks before regulatory mandates harden.
For Market Incumbents: Harden cyber-security certification pipelines against DNV and Lloyd's Register notation fragmentation by embedding validation engineers within classification society working groups. Deepen in-house production of marine-grade gyrocompass housings to offset Taiwan semiconductor foundry concentration risk.
For New Entrants and Emerging Players: India's coastal fleet underpenetration by integrated bridge suppliers offers white-space access through compliance-driven retrofit cycles under revised Merchant Shipping Act provisions. Target remote diagnostics software layers as the most penetrable segment, leveraging satellite connectivity improvements to unbundle traditional service contracts.
For Investors and Strategic Acquirers: Sensor fusion specialists with existing military emission-control credentials represent the highest-conviction acquisition archetype for commercial autonomous vessel crossover. Long-term viability hinges on 5-10 year regulatory harmonization timelines. Monitor IMO e-navigation framework implementation velocity as the critical inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies ECDIS, radar, and autopilot under Wärtsilä Transas simulation-to-live continuity. |
| Regulatory Affairs Expansion | Builds parallel US Coast Guard NVIC and EU Marine Equipment Directive approval capacity. |
| Remote Diagnostics Development | Enables over-the-air software updates through Inmarsat satellite connectivity improvements. |
| Sensor Fusion Stack Investment | Positions for unmanned surface vessel redundant navigation architectures without human backup. |
| Geographic Manufacturing Footprint | Establishes South Korean presence to serve Ulsan LNG carrier and container vessel newbuilds. |
Study Parameters
The analysis maps ECDIS replacement cycles, software-defined radar adoption curves, and autonomous vessel sensor architectures, each validated through shipowner fleet managers, bridge system integrators, and classification society technical officers. Primary fieldwork combined structured interviews with secondary validation against IMO SOLAS amendment records, US Coast Guard NVIC standards filings, and EU Marine Equipment Directive certification databases. Bottom-up vessel-class procurement modeling triangulated against top-down shipyard output projections.
Assumptions held cyber-security notation deadlines fixed at classification society announcement dates while varying Strait of Malacca spoofing incident frequency and East Asian shipbuilding output across scenarios. Segmentation dimensions spanned product type, technology tier, vessel application, and procurement authority. CAGRs derived from regression against historical ECDIS carriage compliance waves and newbuild specification patterns, with inputs including GNSS augmentation adoption rates and inertial backup penetration in offshore fleets.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor foundries would shift component pricing dynamics. Material shifts in IMO e-navigation mandatory enforcement timelines or classification society cyber-security test protocol harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Chartplotter Market
Marine
Marine Elevators Market
Marine
North Sea Offshore Support Vessels Market
Marine
Ship Rudders Market
Marine
Electric Ferry Market
Marine
Marine Suspension Seat Bases Market
Marine
Submarine Propulsion Systems Market
Marine
Marine Auxiliary Engine Market
Marine
Marine Winch Motors Market
Marine
Marine Asset Integrity Services Market
Marine
Boat Cleat Market
Marine
Shipbuilding Market
Marine
Mooring Ropes Market
Marine
Marine Engine Cooling Systems Market
Marine
Trim Tabs Market
Marine
Unmanned Marine Vehicles Market