
 Marine Fuel Injector Market | 2026-2036
Marine Fuel Injector Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fuel Injector Market Analytics
The International Maritime Organization's MARPOL Annex VI is repositioning marine engine architecture toward high-pressure common rail systems. Cummins Inc. leverages its integrated powertrain footprint to serve commercial vessel operators transitioning to Tier III-compliant engines. Robert Bosch GmbH anchors its marine division with piezoelectric injector platforms engineered for heavy fuel oil compatibility. Yanmar Co., Ltd. specializes in compact common rail systems for mid-range auxiliary engines across Asian shipyards.
A marine fuel injector is a precision-machined component that atomizes fuel at pressures exceeding 2,000 bar into combustion chambers, enabling controlled ignition timing and complete fuel burn in two-stroke and four-stroke marine engines. Common rail systems now dominate newbuild propulsion contracts because they deliver the pressure stability required for selective catalytic reduction integration. Electromechanical technology leads the installed base, though piezoelectric actuation is capturing premium segments where nanosecond injection timing improves fuel efficiency. Commercial vessels represent the deepest demand pool, driven by container line fleet renewal and exhaust gas cleaning retrofits.
The IMO's Energy Efficiency Existing Ship Index and the EU MRV Regulation are tightening compliance windows for vessel operators, directly shaping injector replacement cycles and R&D priorities at engine makers. The US EPA and China's MEE enforce parallel emission limits that fragment certification requirements across major shipbuilding jurisdictions. Japan's METI coordinates domestic yard consortia to align JIS standards with IMO decarbonization timelines. Stakeholders must track how ammonia-ready engine programs reshape injector material specifications and nozzle geometries before retrofit commitments lock in.
Market Dynamics
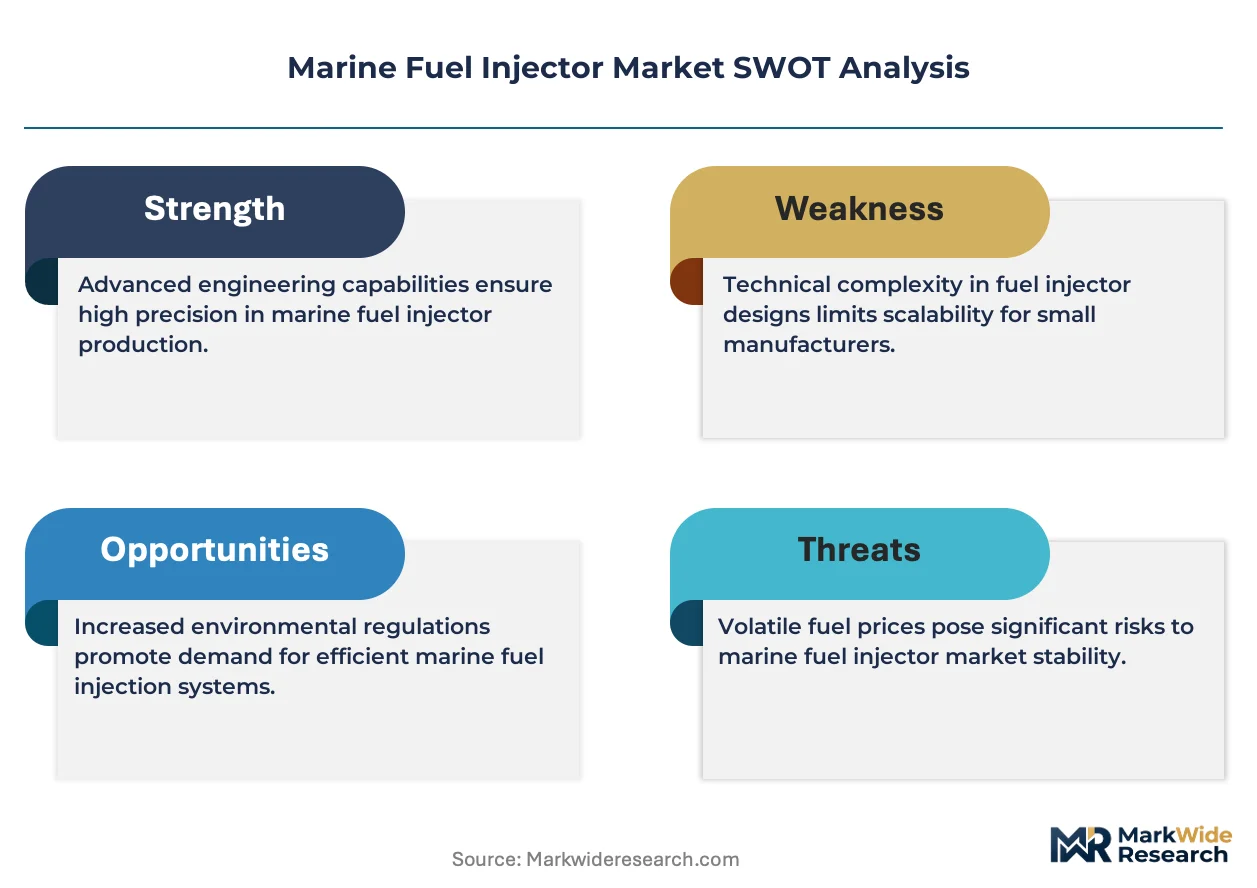
The International Maritime Organization's MARPOL Annex VI is compressing engine upgrade cycles, forcing vessel operators toward high-pressure common rail architectures that demand precision-machined injector components with tighter tolerances than legacy mechanical systems.
Growth Catalysts
- IMO 2020 Sulphur Cap:The global sulphur limit on marine fuels has accelerated exhaust gas cleaning system installations, which require stable high-pressure injection to function effectively.
- Container Fleet Renewal:Major shipping lines are replacing aging tonnage with dual-fuel-ready vessels, each carrying multiple injector sets for diesel and alternative fuel modes.
- German Marine Engineering Clusters:Concentrated R&D infrastructure around Hamburg and Augsburg is shortening prototype-to-production timelines for next-generation injector platforms.
Market Restraints
- Tungsten Carbide Price Volatility:Nozzle needle and seat materials face supply pressure from aerospace and mining competition, squeezing foundry margins for precision carbide components.
- Specialized Machining Concentration:Five-axis grinding capacity for injector bodies clusters in Switzerland and southern Germany, creating single-source vulnerability for tier-two suppliers.
- Legacy Engine Lock-in:Two-stroke slow-speed engines from the 1990s lack common rail retrofit compatibility, fragmenting addressable vessel populations.
Strategic Opportunities
- Ammonia-Ready Engine Programs:Ammonia combustion chemistry demands redesigned nozzle spray patterns and corrosion-resistant materials, opening white space for first-mover injector specialists.
- EU Green Deal FuelEU Maritime:The bloc's well-to-wake carbon intensity mandate creates regulatory pull for methanol-compatible injection systems in intra-European short-sea shipping.
- Digital Twin Integration:Real-time injector wear monitoring via embedded pressure sensors is converging with predictive maintenance platforms, enabling subscription-based service models.
Industry Challenges
- Metallurgical Talent Scarcity:Precision grinding of high-pressure fuel passages requires skills concentrated among aging European and Japanese technician cohorts with limited apprenticeship pipelines.
- Type Approval Compression:IMO Tier III and EPA Tier 4 certification timelines for new injector designs now exceed eighteen months, delaying revenue recognition for R&D-heavy product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fuel Injector Market |
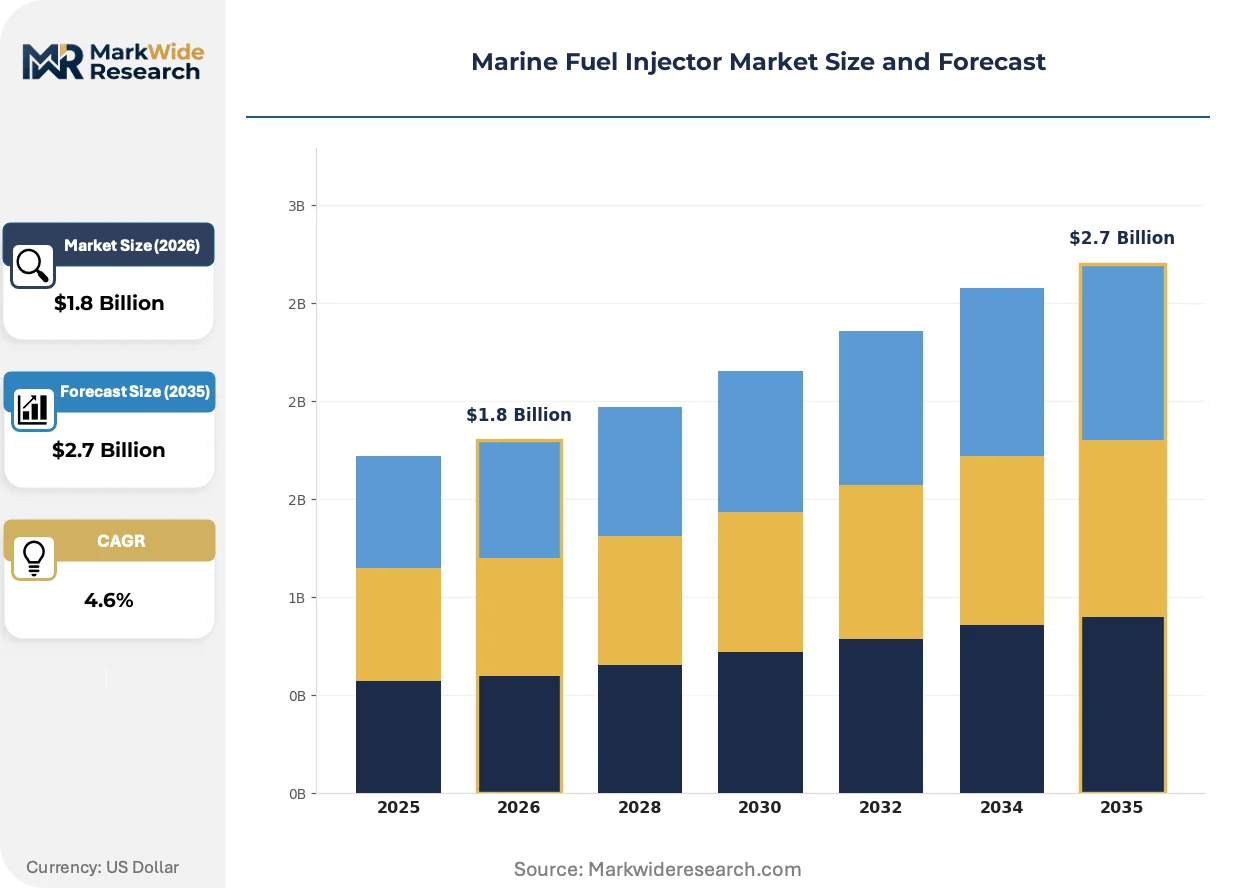
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Common Rail, Unit Injector, Direct Injection, Port Fuel Injection Technology: Electromechanical, Piezoelectric, Hydraulic, Solenoid End User: Commercial Vessels, Recreational Boats, Fishing Boats, Military Vessels Application: Engine Performance, Emission Control, Fuel Efficiency, Maintenance |
| Companies Covered | Caterpillar Inc., Cummins Inc., Robert Bosch GmbH, Rolls-Royce Holdings plc, Yanmar Co., Ltd., Liebherr International AG, MAN SE, DENSO Corporation, Woodward Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fuel Injector Market Evolving Landscape
Marine propulsion engineering is pivoting toward electromechanical precision control, with actuator technologies and combustion modeling advancing in parallel to squeeze efficiency from heavy fuel oils and emerging alternatives alike.
Piezoelectric injector actuation is automating nanosecond injection timing adjustments that mechanical systems cannot achieve. Container lines operating ultra-large crude carriers are adopting these platforms fastest, driven by fuel economy guarantees in charter party agreements. The technology is automating the compression of pilot injection quantities below two milligrams, enabling stable combustion across wider load ranges.
The EU's FuelEU Maritime regulation is binding shipping operators to declining carbon intensity thresholds from 2025 onward. This framework forces engine manufacturers to optimize injection profiles for biofuel blends and synthetic e-fuels with divergent combustion properties. Short-sea ro-ro operators in the Baltic and North Sea corridors are responding with accelerated injector replacement schedules to maintain compliance margins.
Charter party fuel clauses are restructuring how vessel operators evaluate injector lifecycle costs. Long-term time charter contracts now pass fuel efficiency risk to shipowners, who in turn demand extended injector service intervals and performance guarantees from suppliers. This recalculation is most visible among Greek and Singapore-based tanker fleets managing spot market exposure through fuel hedging instruments.
Marine Fuel Injector Market Segmentation
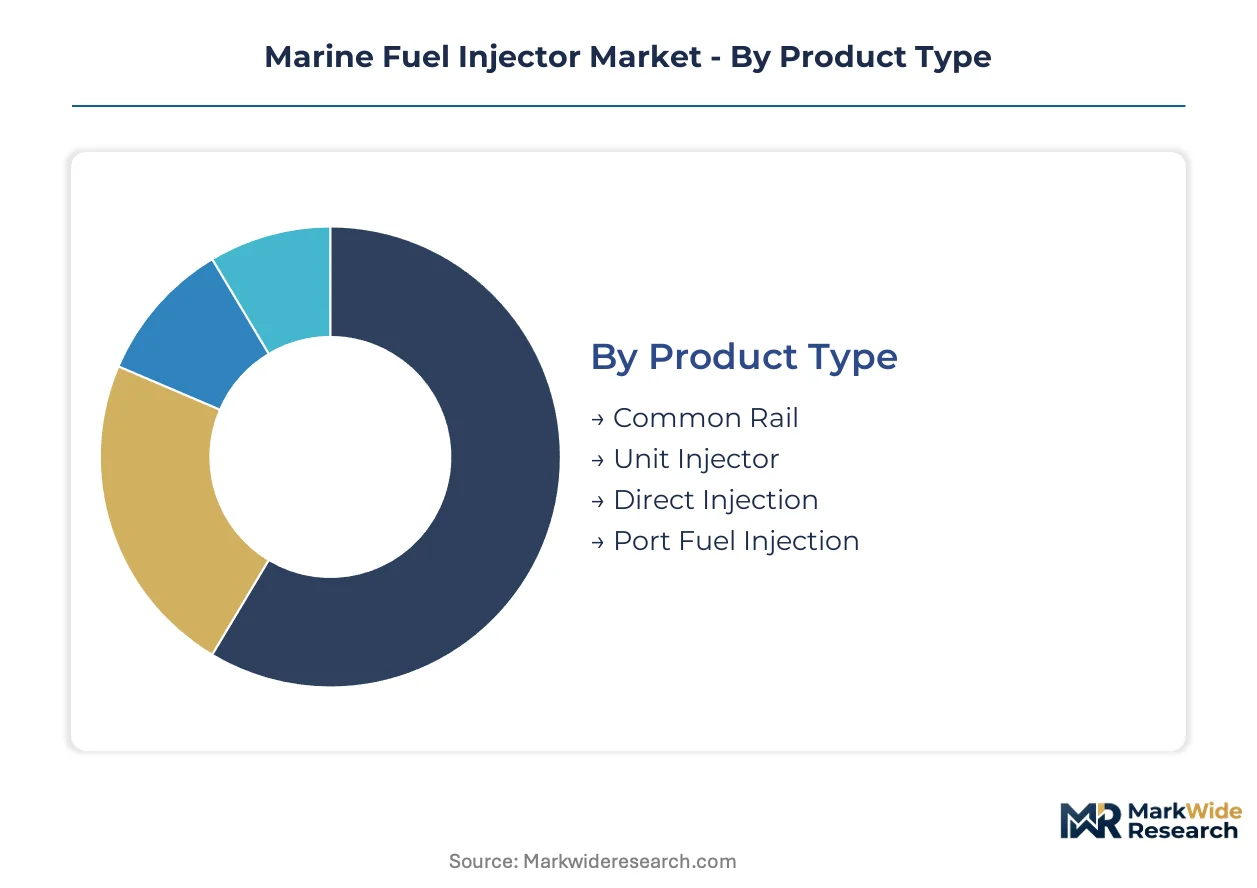
Marine fuel injector procurement decisions hinge on pressure architecture compatibility, regulatory compliance tier, and vessel operational profile. Understanding segment boundaries clarifies where technology investments concentrate and where retrofit opportunities fragment.
Product Type:
Engine manufacturers select injector architectures based on fuel injection pressure requirements and MARPOL Annex VI compliance tier.
- Common Rail:High-pressure accumulator systems deliver fuel at 2,000+ bar through shared rail manifolds, enabling precise multiple-injection events. Container lines operating ultra-large crude carriers in Hamburg and Singapore anchor demand as charter party fuel clauses pass efficiency risk to shipowners.
- Unit Injector:Integrated pump-nozzle assemblies combine fuel metering and pressurization in single compact units suited to auxiliary engines. Asian shipyards in South Korea and Japan specify these for mid-range propulsion where space constraints outweigh common rail efficiency gains.
- Direct Injection:Fuel delivery straight into combustion chambers supports two-stroke slow-speed engine architectures.
- Port Fuel Injection:Lower-pressure premix systems serve smaller auxiliary gensets and harbor craft with lighter duty cycles.
Common Rail leads on scale; Unit Injector leads on momentum in auxiliary engine retrofits.
Technology:
Actuation mechanism determines injection timing precision, energy consumption, and maintenance interval economics.
- Electromechanical:Solenoid-driven valve trains dominate the installed base with proven reliability across heavy fuel oil grades. Greek tanker fleets managing spot market exposure through fuel hedging instruments favor these for predictable service costs.
- Piezoelectric:Ceramic actuator stacks enable nanosecond injection timing adjustments and sub-two-milligram pilot quantities. Baltic and North Sea short-sea operators under FuelEU Maritime pressure adopt these fastest for biofuel blend optimization.
- Hydraulic:Pressure-amplified systems serve legacy two-stroke engines lacking electronic control retrofit compatibility.
- Solenoid:Simplified electromagnetic actuation occupies economy-tier replacement markets.
Electromechanical systems retain volume leadership; Piezoelectric platforms are climbing the fastest on regulatory pressure.
End User:
Vessel category dictates injector duty cycle severity, fuel quality exposure, and replacement frequency.
- Commercial Vessels:Container ships, bulk carriers, and tankers operate continuous high-load cycles demanding 30,000+ hour injector lifespans. Exhaust gas cleaning retrofits on Singapore and Hamburg-registered tonnage are accelerating common rail conversions.
- Recreational Boats:Pleasure craft with intermittent usage patterns prioritize cold-start reliability over peak efficiency.
- Fishing Boats:Trawlers and longliners face salt-air corrosion and biofuel contamination challenges in deck-level engine rooms.
- Military Vessels:Naval specifications demand battle-hardened electromagnetic interference resistance and multi-fuel compatibility.
Commercial Vessels dominate absolute demand; Military Vessels show steepest expansion trajectory on fleet modernization programs.
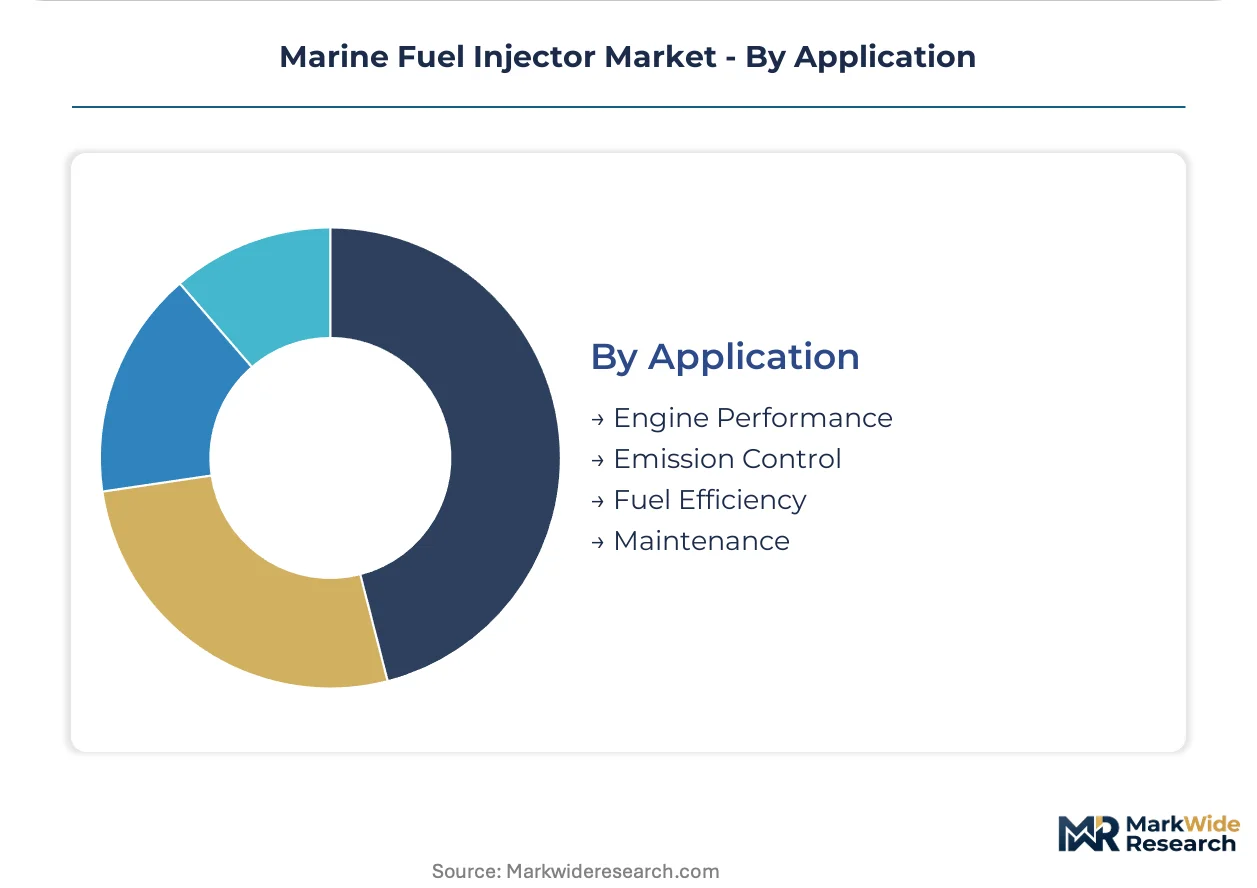
Application:
Functional deployment determines whether injectors are specified for newbuild integration or aftermarket replacement.
- Engine Performance:Power density and load response optimization drives specification for high-speed ferry and offshore support vessel operators.
- Emission Control:Selective catalytic reduction and exhaust gas recirculation integration demands stable high-pressure injection timing. IMO Tier III compliance deadlines in German and South Korean yards are concentrating procurement here.
- Fuel Efficiency:Charter party fuel consumption guarantees push shipowners toward piezoelectric upgrades.
- Maintenance:Scheduled replacement cycles and emergency spares procurement supports aftermarket service networks.
Emission Control commands premium pricing; Fuel Efficiency is gaining share fastest on carbon intensity regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine fuel injector manufacturing traces its industrial lineage to German precision engineering traditions established in Augsburg and Hamburg during the early twentieth century, when MAN SE pioneered high-pressure diesel injection for ocean-going vessels. German clusters remain the technical benchmark for common rail architecture development.
Germany
Container fleet renewal at Hamburg and Bremerhaven ports drives demand for Tier III-compliant injector systems. The EPA and IMO MARPOL Annex VI enforcement through German-flag registries mandates high-pressure common rail retrofits. Augsburg and Hamburg engineering clusters host prototype-to-production pipelines for piezoelectric actuator platforms serving Mediterranean and Baltic routes.
South Korea
Daewoo and Hyundai Heavy Industries orderbooks for dual-fuel LNG carriers require redundant injector sets for diesel-ammonium switching modes. The country's national maritime regulator aligns KSA certification with IMO decarbonization timelines. Ulsan and Geoje shipyard complexes concentrate procurement for ultra-large crude carrier newbuilds with integrated exhaust gas cleaning.
Japan
METI coordinates domestic yard consortia to harmonize JIS injector standards with FuelEU Maritime carbon intensity benchmarks. Short-sea ro-ro operators in Osaka Bay retrofit auxiliary engines with compact common rail systems. Nagoya and Kobe manufacturing belts supply precision-machined nozzle components to Southeast Asian ship repair facilities.
Singapore
The Maritime and Port Authority's green shipping program accelerates exhaust gas cleaning installations on bunker-fuel-dependent tanker fleets. Greek and Singapore-based shipowners demand extended injector service intervals under charter party fuel clauses. Tuas Port expansion concentrates aftermarket spare parts logistics for Indonesian and Malaysian flagged tonnage.
United States
EPA Tier 4 certification deadlines compress R&D timelines for Great Lakes bulk carrier engine upgrades. Jones Act compliance preserves domestic build requirements for injector integration at Wisconsin and Louisiana assembly plants. Houston-Galveston petrochemical export growth drives harbor tug fleet modernization with emission-controlled auxiliary gensets.
Marine Fuel Injector Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the marine fuel injector value chain. Foundry-dependent manufacturers controlling tungsten carbide nozzle production face margin pressure from aerospace and mining demand, while specialized engineering houses license high-pressure architecture IP to tier-two assemblers. Three archetypes dominate: integrated engine builders with captive injector divisions; independent precision component specialists; and aftermarket service networks with regional stocking depots. Competitive moves concentrate on five-axis grinding capacity expansion in Switzerland and southern Germany, plus strategic partnerships for ammonia-ready material qualification.
Among German-anchored engineering conglomerates, MAN SE and Robert Bosch GmbH exemplify the integrated-systems archetype, combining fuel injection R&D with engine platform development. Japanese precision manufacturers including DENSO Corporation and Yanmar Co., Ltd. occupy positions emphasizing compact common rail architectures for auxiliary engine segments. These named entities represent distinct geographic and technical positioning rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Robert Bosch GmbH |
| Rolls-Royce Holdings plc |
| Yanmar Co., Ltd. |
| Liebherr International AG |
| MAN SE |
| DENSO Corporation |
| Woodward Inc. |
| Others |
Value Network & Pricing Analysis
IMO Tier III certification deadlines for new injector designs are compressing procurement timelines for vessel operators, forcing foundries to prioritize precision-machined nozzle components over standard grades and compressing margins across tier-two assemblers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates piezoelectric platforms with extended service intervals from electromechanical replacements and unbranded aftermarket alternatives. Price differentiation rests on MARPOL Annex VI certification grade and five-axis grinding precision. Cost compression in economy-tier solenoid injectors is intensifying because Asian shipyards are consolidating supplier lists. Greek tanker fleets managing spot market exposure exhibit highest price sensitivity; container lines under charter party fuel clauses show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Swiss and southern German five-axis grinding capacity for injector bodies. Manufacturing concentrates in Germany, Japan, and South Korea. Raw material dependencies include tungsten carbide for nozzle needles, ceramic actuator stacks, and high-alloy steel for rail manifolds. Supply chain risk centers on aerospace and mining competition for tungsten carbide feedstock. Distribution runs through Hamburg, Singapore, and Ulsan port logistics hubs serving regional ship repair networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in marine fuel injectors is achievable through piezoelectric platform premiumization and captive control over tungsten carbide nozzle production.
For Market Incumbents: Extend service interval guarantees to container lines operating under charter party fuel clauses. Deepen backward integration into tungsten carbide foundry capacity to defend against aerospace demand competition. Anchor R&D investments in ammonia-ready nozzle geometries before retrofit commitments lock in vessel populations. For New Entrants and Emerging Players: Capture white space in ammonia-compatible injector materials for dual-fuel engine programs. Target short-sea ro-ro operators in the Baltic corridor under FuelEU Maritime pressure with methanol-optimized spray pattern designs. Lead with digital twin integration for predictive maintenance subscription models. For Investors and Strategic Acquirers: Asymmetric upside sits with precision grinding specialists holding five-axis capacity in Switzerland and southern Germany. Long-term viability favors acquisition targets with captive tungsten carbide supply and IMO Tier III certification pipelines. Watch ammonia-ready engine program announcements from MAN SE and Rolls-Royce Holdings as inflection indicators for material specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Foundries | Captive nozzle production defends margins against aerospace and mining demand competition. |
| Piezoelectric Platform Premiumization | Extended service intervals attract container lines under charter party fuel efficiency clauses. |
| Ammonia-Ready Nozzle Qualification | First-mover corrosion-resistant materials capture dual-fuel engine program specifications. |
| Digital Twin Integration Partnership | Embedded pressure sensors enable predictive maintenance subscriptions for Greek and Singapore tanker fleets. |
| Five-Axis Grinding Capacity Expansion | Southern Germany and Swiss machining clusters reduce single-source vulnerability for tier-two suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from marine engine procurement officers at Hamburg and Singapore shipping lines, precision grinding technicians at Augsburg and Nagoya manufacturing clusters, regulatory affairs leads at classification societies, and aftermarket service heads at Baltic port repair facilities. Secondary validation drew from IMO MARPOL Annex VI amendment filings, Lloyd's Register engine certification databases, German and Japanese customs trade records, and SEC 10-K disclosures from listed marine engineering conglomerates. Bottom-up vessel fleet analysis and top-down macroeconomic modeling were cross-checked for triangulation.
Segment-weighting distributed volume and value estimates across common rail and unit injector architectures, electromechanical and piezoelectric actuation technologies, and commercial vessel versus auxiliary engine applications throughout the forecast period. CAGRs were derived from regression analysis against IMO regulatory compliance deadlines and container fleet renewal orderbooks. Industry-specific forecast inputs included exhaust gas cleaning retrofit penetration rates and dual-fuel LNG carrier newbuild schedules at South Korean yards.
Regulatory timeline delays, tungsten carbide price spikes, and ammonia engine program cancellations are the dominant revision risks for injector demand projections. Forecasts reflect assumptions about MARPOL Annex VI enforcement consistency and charter party fuel clause standardization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Sliding Fender Market
Marine
Ballast Water Management Market
Marine
Marine Fender Systems Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Trenchers Market
Marine
Furnace Boats Market
Marine
Marine Elevators Market
Marine
Submarine Propulsion Systems Market
Marine
Swamp Boat Market
Marine
Unmanned Marine Vehicles Market
Marine
Sea Skimmer Market
Marine
Electric Boat Market
Marine
Marine Fender Market
Marine
Marine Bearings Market
Marine
Europe Recreational Boating Market
Marine
Marine Turbocharger Market