
 Europe ROV Market | 2026-2036
Europe ROV Market Size, Share, and Industry Trends Forecast 2026-2036
Europe ROV Market Foresight
A shortage of certified subsea robotics engineers is unwinding project timelines across the North Sea. DeepOcean leverages its integrated vessel-and-ROV fleet to capture turnkey decommissioning contracts. Kongsberg Gruppen anchors Norwegian supply chains through its in-house sonar and navigation technology stack. Saab Seaeye specializes in electric work-class systems that reduce topside power demands for offshore wind clients.
Remotely operated vehicles are tethered underwater robots typically rated to depths exceeding 3,000 meters, employing hydraulic or electric propulsion with manipulator arms and sensor payloads for intervention tasks. Their primary purpose is to perform subsea inspection, maintenance, and construction in environments too hazardous or deep for human divers. Work Class ROVs dominate revenue pools due to tooling-intensive oil and gas decommissioning scopes, while Light Work ROVs are gaining share in offshore wind where lower lift capacity matches turbine foundation inspection needs. Electric ROV technology is displacing hydraulic architectures in renewable energy applications where emissions compliance and topside footprint constraints tighten.
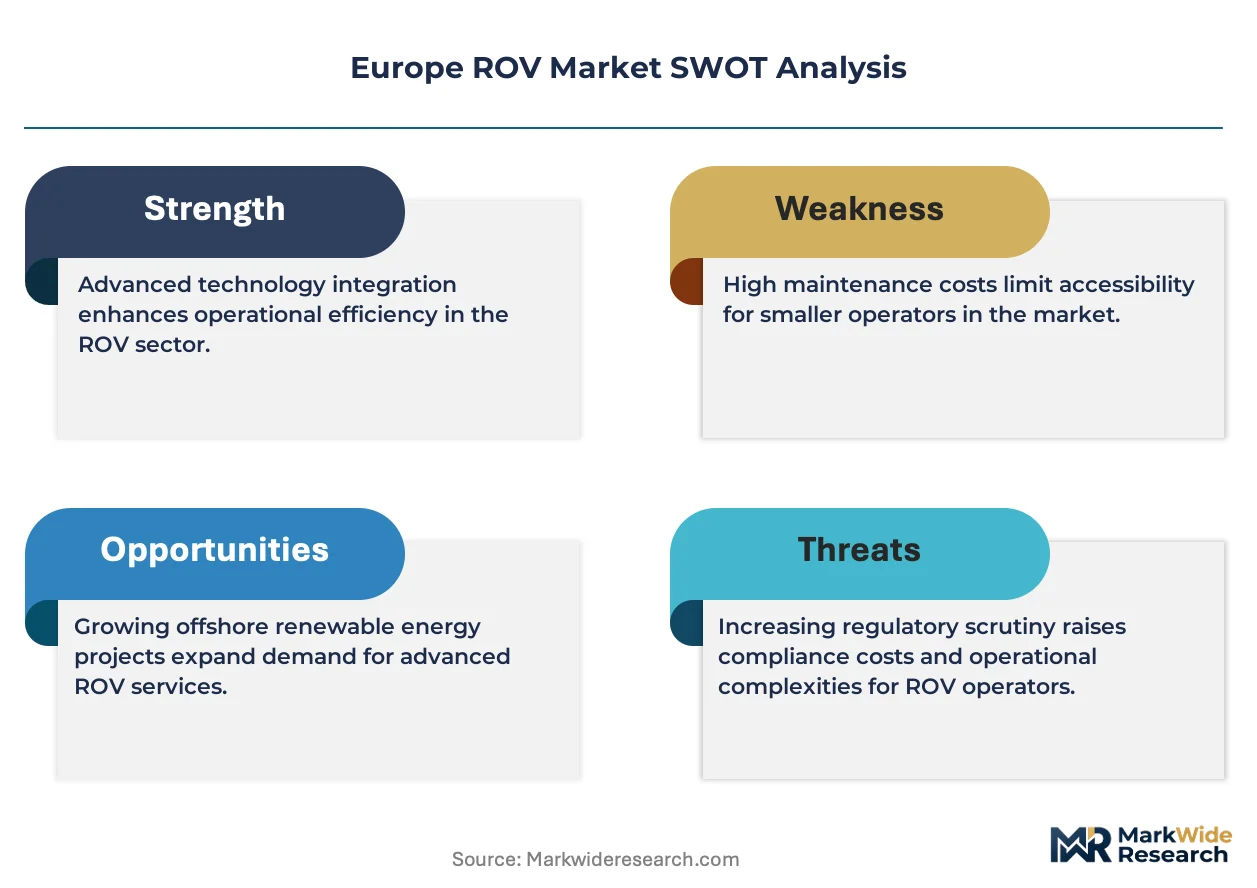
The EU Green Deal, F-Gas Regulation, and CE marking under the Marine Equipment Directive shape product standards and market access for ROV systems deployed in European waters. ECHA chemical restrictions on hydraulic fluids are accelerating electric propulsion adoption, while CE marking requirements enforce electromagnetic compatibility for tethered operations near offshore wind infrastructure. Stakeholders must weigh decommissioning demand volatility against renewable energy procurement pipelines when calibrating fleet composition and regional service base placement.
Market Dynamics
Electric propulsion architectures are decomposing hydraulic system dominance across European offshore wind procurement, driven by F-Gas Regulation phase-down schedules and topside emissions constraints at crowded North Sea lease areas.
Growth Catalysts
- EU Green Deal offshore targets:Binding renewable capacity mandates are redirecting capital expenditure from oil and gas decommissioning toward marine electrification infrastructure across the North Sea basin.
- Foundation inspection automation:Light Work ROV tooling optimized for monopile and jacket foundation surveys is accelerating deployment cycles at turbine arrays.
- ECHA hydraulic fluid restrictions:Chemical hazard classifications on mineral oil-based fluids are forcing fleet operators to specify electric actuation for newbuild ROV systems.
Market Restraints
- High-voltage tether supply concentration:Copper conductor and fiber optic cable production clusters in Germany and Norway create single-source vulnerability for deep-rated work-class systems.
- Battery energy density ceiling:Lithium-ion pack limitations constrain electric work-class ROV endurance below hydraulic equivalents for extended trenching operations.
- CE marking electromagnetic compatibility delays:Marine Equipment Directive testing backlogs at notified bodies extend delivery timelines for wind farm operators with seasonal installation windows.
Strategic Opportunities
- Baltic Sea lease expansion:Polish and Lithuanian offshore wind auctions are opening service base locations outside saturated North Sea corridors.
- Autonomous underwater vehicle convergence:Hybrid ROV-AUV architectures are reducing tether dependency for repetitive cable survey routes between turbine strings.
- Outcome-based charter contracts:Wind farm operators are shifting from day-rate vessel hire to fixed-price inspection deliverables that reward fleet utilization efficiency.
Industry Challenges
- Subsea robotics engineer scarcity:Certified pilot-technician training pipelines at Norwegian and UK maritime academies cannot match North Sea fleet expansion rates.
- Multi-vessel integration complexity:ROV systems from different OEMs require custom topside control interfaces when deployed from chartered third-party vessels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe ROV Market |
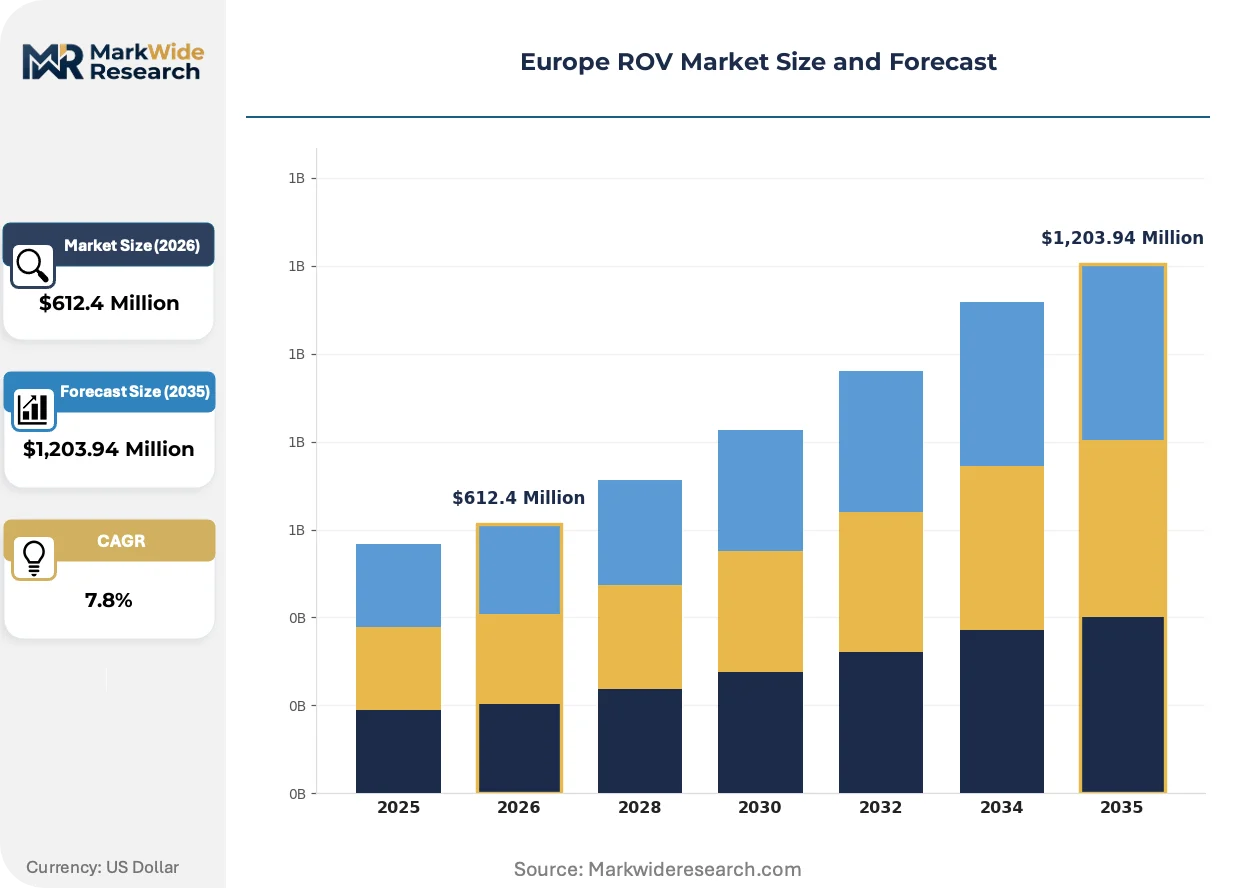
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,203.94 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inspection ROVs, Work Class ROVs, Light Work ROVs, Heavy Duty ROVs End User: Oil & Gas, Aquaculture, Renewable Energy, Maritime Research Technology: Electric ROVs, Hydraulic ROVs, Hybrid ROVs, Autonomous Underwater Vehicles Application: Underwater Inspection, Maintenance, Surveying, Construction |
| Companies Covered | DeepOcean, Forum Energy Technologies, TechnipFMC, ECA Group, Kongsberg Gruppen, BAE Systems, Exail Technologies, Saab Seaeye, Saipem S.p.A., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe ROV Market Shifts & Advancements
Digital twin integration and resident subsea systems are compressing operational models for European offshore energy infrastructure. These shifts are reconfiguring fleet ownership structures and service delivery economics.
Modular electric thruster packages are decomposing centralized hydraulic power unit architectures in work-class ROV designs. Offshore wind farm operators in the German Bight and Dogger Bank zones are specifying all-electric systems for foundation cleaning and cable burial support. This propulsion transition is collapsing topside hydraulic fluid inventory requirements and reducing deck footprint constraints on compact service vessels.
EU F-Gas Regulation hydrofluorocarbon phase-down schedules are tightening permissible greenhouse gas emissions from subsea refrigeration and thermal management systems. Manufacturers serving North Sea oil and gas decommissioning scopes must redesign thermal control loops to comply with 2027 reduction targets. Electric work-class ROV variants with solid-state thermal management are capturing preference in Norwegian and UK tender processes.
Charter contracting is consolidating around fixed-scope deliverables rather than time-based vessel hire. Wind farm asset managers in Denmark and the Netherlands are unbundling inspection data products from vessel provision, creating direct procurement relationships with ROV operators. This disintermediation compresses margin capture for integrated vessel owners while expanding addressable market for specialized robotics service providers.
Europe ROV Market Segmentation
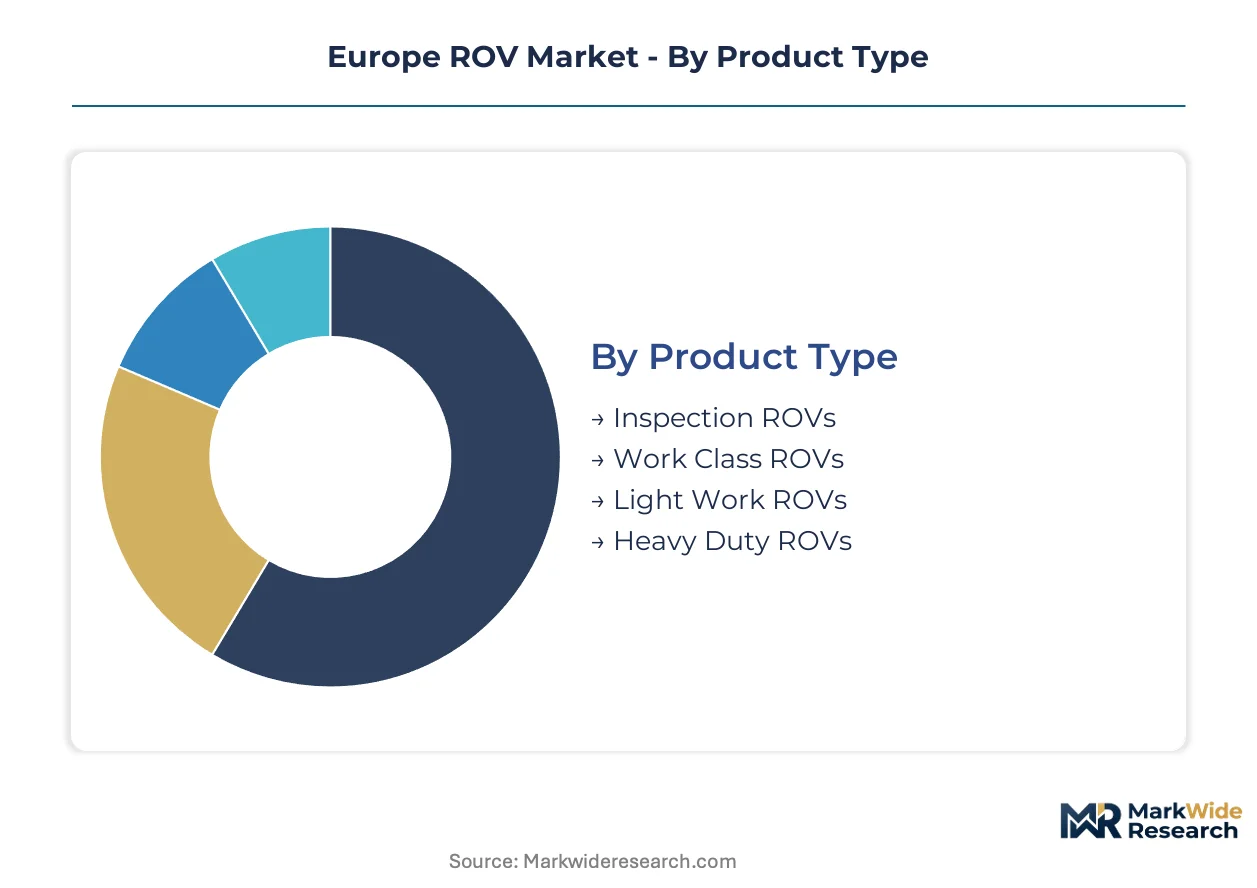
ROV procurement patterns diverge sharply across European offshore sectors. Regulatory frameworks and operational constraints reshape fleet specifications by depth rating, power architecture, and mission profile.
Product Type:
CE marking under the Marine Equipment Directive and ECHA hydraulic fluid restrictions create divergent compliance burdens across depth and power classes.
- Work Class ROVs:Rated for 1,000-3,000 meter operations with tooling-intensive hydraulic or electric propulsion. North Sea oil and gas decommissioning contracts in Norwegian and UK waters concentrate demand for manipulator-arm systems capable of pipeline cutting and wellhead severance. F-Gas Regulation phase-down timelines accelerate electric retrofit specifications for newbuild units.
- Light Work ROVs:Compact electric systems rated to 500 meters with reduced lift capacity optimized for monopile inspection. German Bight and Dogger Bank wind farm operators specify these units for foundation cleaning and cable burial support where topside footprint constraints dominate vessel selection.
- Inspection ROVs:Observation-class platforms with minimal tooling for visual survey missions.
- Heavy Duty ROVs:Ultra-deep systems exceeding 3,000 meter ratings for trenching and heavy-lift intervention.
Established volume favors Work Class ROVs; emerging adoption favors Light Work ROVs.
End User:
Capital allocation shifts between fossil decommissioning and renewable buildout reshape fleet deployment patterns.
- Renewable Energy:Offshore wind farm operators across the North Sea and Baltic Sea drive procurement of electric ROV systems for subsea cable inspection and foundation monitoring. EU Green Deal binding capacity mandates redirect service vessel contracting from oil and gas corridors toward marine electrification infrastructure.
- Oil & Gas:Decommissioning programs in UK and Norwegian waters sustain demand for work-class hydraulic systems in well abandonment and pipeline removal. ECHA chemical restrictions on mineral oil-based fluids force gradual fleet electrification despite established maintenance protocols.
- Maritime Research:Academic and governmental oceanographic institutions deploy ROVs for seabed mapping and biological sampling.
- Aquaculture:Norwegian and Scottish salmon farm operators utilize observation-class systems for net inspection and predator monitoring.
Legacy infrastructure sustains Oil & Gas procurement; Renewable Energy climbs the fastest.
Technology:
Power architecture selection hinges on emissions compliance, endurance requirements, and topside space constraints.
- Electric ROVs:Solid-state propulsion eliminating hydraulic fluid inventory and reducing deck footprint. Danish and Dutch wind farm tenders specify all-electric systems for foundation inspection where F-Gas Regulation compliance and crowded North Sea lease areas tighten emissions constraints.
- Hydraulic ROVs:Centralized power unit architectures with proven endurance for extended trenching operations. Established Norwegian and UK oil and gas contractors retain hydraulic fleets for decommissioning scopes where battery energy density limitations constrain electric alternatives.
- Hybrid ROVs:Dual-mode systems switching between electric efficiency and hydraulic power for demanding interventions.
- Autonomous Underwater Vehicles:Untethered platforms reducing surface vessel dependency for repetitive cable survey routes.
Operational familiarity preserves Hydraulic ROV share; regulatory pressure accelerates Electric ROV transition.
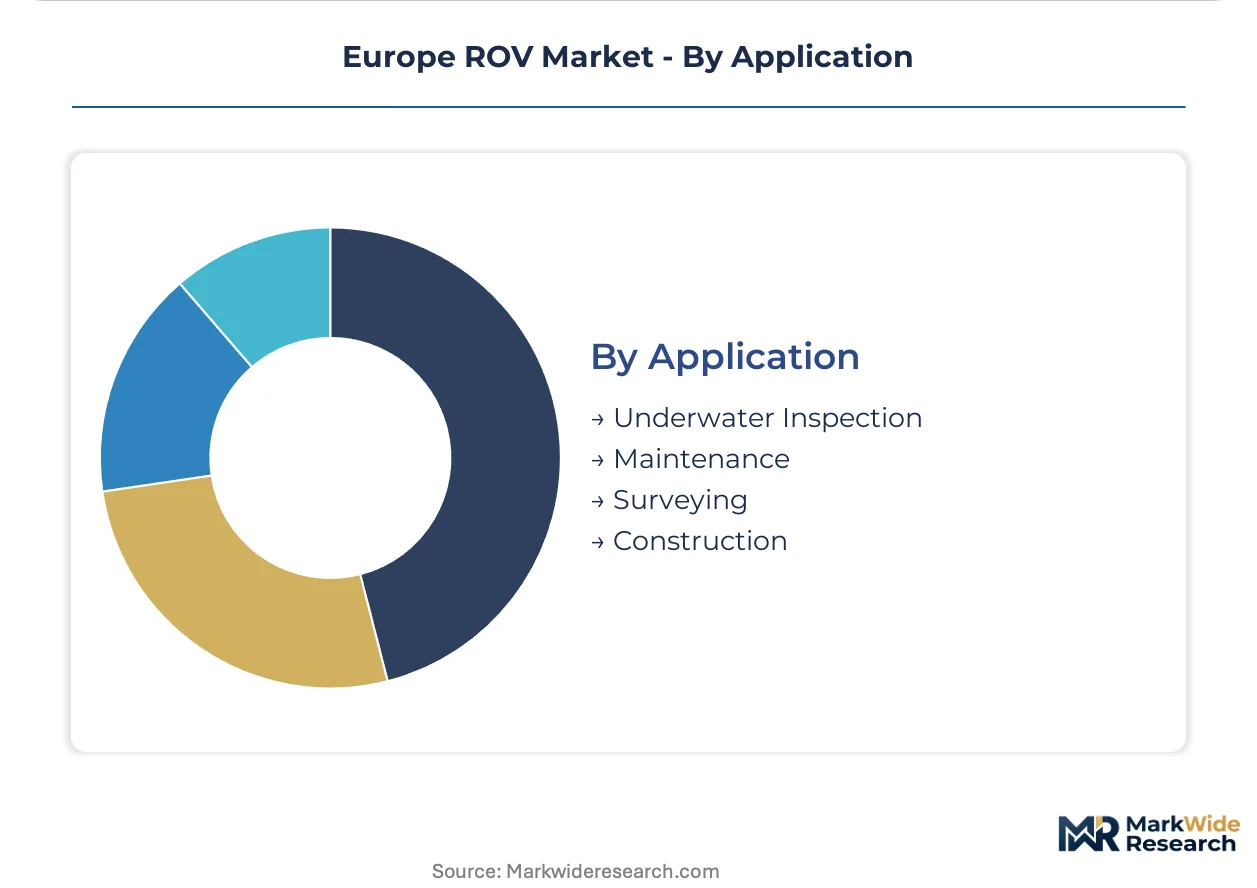
Application:
Mission complexity and repeatability determine ROV specification and contracting structure.
- Underwater Inspection:Visual and sonar-based survey missions for asset integrity verification. Fixed-price outcome-based contracts in Danish and Dutch markets unbundle inspection data products from vessel provision, creating direct procurement relationships with specialized robotics operators.
- Maintenance:Intervention tasks including cleaning, anode replacement, and minor repairs. Offshore wind foundation maintenance in German waters drives seasonal deployment peaks aligned with installation windows.
- Construction:Cable burial, pipeline laying, and substructure installation support.
- Surveying:Seabed mapping and geophysical data acquisition for route planning.
Repetitive scope favors Inspection; project-based demand favors Construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea lease areas consume Work Class ROVs for oil and gas decommissioning, while Baltic Sea wind farm operators favor Light Work electric systems for foundation inspection. This consumption-mix differential separates mature hydrocarbon markets from electrification corridors.
Norway
Stavanger and Bergen harbor clusters sustain demand for ultra-deep work-class systems serving North Sea well abandonment. The Norwegian Petroleum Directorate mandates zero-discharge standards that accelerate electric ROV specifications for new decommissioning tenders. Kongsberg Gruppen anchors domestic supply chains through in-house sonar and navigation technology production in Horten.
United Kingdom
Aberdeen and Great Yarmouth service bases concentrate fleet deployment for UKCS decommissioning programs and Dogger Bank wind construction. The North Sea Transition Authority coordinates lease rounds that redirect vessel contracting from hydrocarbon corridors toward offshore electrification infrastructure. DeepOcean leverages integrated vessel-and-ROV positioning to capture turnkey removal contracts in Scottish waters.
Germany
Wilhelmshaven and Bremerhaven emerging as Baltic Sea wind staging points for Polish and Lithuanian export markets. The Federal Maritime and Hydrographic Agency enforces strict electromagnetic compatibility certification under the Marine Equipment Directive that extends delivery timelines for electric system integrators. Saab Seaeye specializes in electric work-class configurations that reduce topside power demands for German Bight turbine operators.
Denmark
Esbjerg maintains its position as North Sea offshore wind service hub with direct procurement relationships between asset managers and ROV operators. The Danish Energy Agency unbundles inspection data products from vessel provision through fixed-scope charter contracts. Esbjerg harbor expansion accommodates electric work-class fleets serving Kriegers Flak and future Baltic interconnectors.
Netherlands
Rotterdam and IJmuiden clusters support Hollandse Kust wind zones with seasonal deployment peaks aligned to installation windows. The Netherlands Enterprise Agency structures offshore wind tenders that specify emissions-compliant electric propulsion for foundation maintenance scopes. Port of Rotterdam infrastructure investments target all-electric ROV service vessel electrification through shore power integration.
Europe ROV Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in European ROV supply. Tier-one participants combine in-house sensor manufacturing with captive vessel fleets, while tier-two operators focus on niche tooling or regional service density. Three archetypes dominate: integrated energy service companies, defense-electronics conglomerates with marine divisions, and pure-play robotics specialists. Competitive moves concentrate on fleet electrification retrofit programs and outcome-based contracting restructuring.
Among Norwegian and UK-based integrated service providers, DeepOcean and TechnipFMC exemplify the vessel-captive archetype with combined deployment capabilities across decommissioning and wind construction. Saab Seaeye occupies a position within the pure-play electric specialist tier, representing the technology transition away from hydraulic architectures. Kongsberg Gruppen anchors the defense-industrial crossover segment, leveraging in-house acoustic and navigation technology stacks that reduce external subsystem dependency.
| Leading Market Players |
|---|
| DeepOcean |
| Forum Energy Technologies |
| TechnipFMC |
| ECA Group |
| Kongsberg Gruppen |
| BAE Systems |
| Exail Technologies |
| Saab Seaeye |
| Saipem S.p.A. |
| Others |
Supply & Pricing Matrix
Ninety-day lead times for high-voltage tether assemblies concentrate pricing power with German and Norwegian cable manufacturers, compressing margins for electric work-class ROV integrators while amplifying cost pass-through to offshore wind operators with seasonal installation windows.
Pricing Analysis
Project-based charter contracting dominates European ROV procurement, with fixed-scope deliverables replacing day-rate vessel hire across Danish and Dutch offshore wind markets. Price differentiation separates premium-tier electric work-class systems with CE marking and F-Gas compliance from standard hydraulic fleets facing ECHA fluid restrictions. Cost compression in the inspection-class segment intensifies as outcome-based contracts unbundle data products from vessel provision. Offshore wind asset managers exhibit highest price sensitivity due to procurement commoditization, while oil and gas decommissioning contractors retain tolerance for tooling-intensive premiums.
Supply Chain Analysis
Germany and Norway anchor high-voltage tether and fiber optic cable production for deep-rated work-class systems, with copper conductor drawing from Norwegian smelters and jacketing compounds sourced from German chemical clusters. ROV manufacturing draws from lithium-ion battery packs, solid-state thruster modules, and sonar sensor arrays. Single-source vulnerability in fiber optic terminations creates exposure to notified body certification backlogs under the Marine Equipment Directive. Distribution runs through Stavanger, Aberdeen, and Esbjerg harbor clusters serving North Sea lease areas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity opens across the European ROV market as charter contracting unbundles vessel provision from robotics services, creating niche positions for specialized electric system integrators outside integrated energy service company structures.
For Market Incumbents: Shield installed base relationships by accelerating electric fleet retrofit programs ahead of F-Gas Regulation phase-down deadlines. Deepen backward integration into solid-state thermal management subsystems to capture margin from hydraulic-to-electric transition demand. Counter threat from pure-play electric specialists through captive certification capacity at notified bodies, compressing delivery timelines for CE-marked systems. For New Entrants and Emerging Players: Resident subsea robotics services represent the most penetrable white-space target, as incumbent integrated vessel owners under-serve automated inspection demand at Baltic Sea wind farms. Polish and Lithuanian lease areas offer geographic entry points with lower harbor slot competition than saturated North Sea corridors. Pursue direct procurement relationships with wind farm asset managers by unbundling inspection data products from vessel charter. For Investors and Strategic Acquirers: Carve-out targets emerge from defense-electronics conglomerates with under-monetized marine divisions holding in-house acoustic and navigation technology stacks. Long-term viability centers on electric propulsion architecture control and resident subsea system deployment capability across the renewable energy buildout horizon. Monitor Baltic Sea auction award announcements as inflection indicator for regional service base placement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Fleet Retrofit Program | F-Gas Regulation compliance secures tender eligibility for Norwegian and UK decommissioning contracts. |
| Resident Subsea System Deployment | Automated turbine inspection reduces vessel-day requirements at Dogger Bank wind arrays. |
| Backward Integration into Sonar Manufacturing | In-house acoustic technology reduces external subsystem dependency for Kongsberg Gruppen. |
| Baltic Sea Service Base Establishment | Polish and Lithuanian lease awards create harbor capacity outside congested North Sea corridors. |
| Outcome-Based Charter Contracting | Fixed-price deliverables reward fleet utilization efficiency for Danish wind farm operators. |
Research Methodology
Cross-validation between primary interviews with ROV fleet managers, offshore wind procurement officers, and subsea robotics engineers and secondary validation through EU auction award databases, ECHA regulatory filings, and Marine Equipment Directive certification records anchors the qualitative findings. Bottom-up triangulation aggregates vessel deployment patterns across Stavanger, Aberdeen, and Esbjerg harbor clusters, while top-down verification benchmarks capital expenditure flows against EU Green Deal offshore wind capacity targets.
Sensitivity analysis around battery energy density improvement trajectories and F-Gas Regulation enforcement timing shapes the projection framework across the analysis window. Segmentation dimensions model power architecture migration, depth rating class, end-use sector allocation, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and newbuild procurement pipelines, with electric ROV adoption curves calibrated to ECHA hydraulic fluid restriction timelines and topside emissions constraints at crowded North Sea lease areas.
Forecasts assume regulatory continuity in EU Green Deal implementation and F-Gas Regulation phase-down schedules; material policy shifts would require re-modeling renewable energy procurement trajectories and decommissioning program pacing. Specific risks include CE marking electromagnetic compatibility testing backlogs at notified bodies and subsea robotics engineer training pipeline shortfalls. Recalibration cycles align with material shifts in offshore wind auction award announcements and hydrocarbon decommissioning tender releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Marine Engines Market
Marine
Sea Skimmer Market
Marine
North America Naval Vessels Market
Marine
Jet Boat Market
Marine
Marine Pipes Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Filter Market
Marine
North Sea Offshore Support Vessels Market
Marine
Tele-Operated Marine Drone Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Sliding Fender Market
Marine
Integrated Bridge System for Ships Market
Marine
Global Submarine Market
Marine
Global Marine Gearbox Market
Marine
Marine Glass Market