
 Automotive Airbags Market | 2026-2036
Automotive Airbags Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Airbags Market Analysis
Supplier consolidation toward dual-source inflator procurement is shifting how tier-1 safety module vendors manage catastrophic risk. Autoliv Inc. sustains the broadest geographic manufacturing footprint among dedicated safety suppliers. ZF Friedrichshafen AG leverages its chassis-electronics integration to bundle airbag control units with active safety architectures. Joyson Safety Systems anchors its position through captive capacity in Asian vehicle assembly corridors.
Automotive airbags are gas-inflated restraint cushions constructed from woven nylon or polyester fabrics coated with neoprene or silicone, designed to deploy within milliseconds of crash detection via accelerometer-based sensing algorithms. Their primary purpose is to reduce occupant kinetic energy transfer during frontal, lateral, or rollover collisions by extending deceleration distance. Frontal airbags dominate unit volume as regulatory baselines mandate driver and passenger positions across all passenger vehicle classes. Curtain airbags represent the fastest-expanding product category as side-impact and pole-crash protocols intensify in major testing regimes. Pyrotechnic inflator technology still occupies the largest installed base, though hybrid systems are gaining share where OEMs seek to modulate deployment force across occupant size classes.
NHTSA in the United States, ECE R94/R95 in Europe, and China's GB standards collectively shape airbag design specifications, sensor thresholds, and out-of-position occupant protection requirements. These frameworks directly determine whether vehicle platforms qualify for type approval and star-rating eligibility in their respective jurisdictions. Stakeholders must monitor evolving pedestrian-protection integration rules that may redirect frontal airbag geometry and hood-lift deployment strategies.
Market Dynamics
Dual-source procurement mandates from passenger vehicle OEMs are compressing inflator supplier margins while forcing tier-1 safety module vendors to reconfigure catastrophic risk management frameworks across their manufacturing footprints.
Growth Catalysts
- FMVSS 208 Calibration Requirements:NHTSA's updated deployment thresholds in the United States are mandating sensor hardware refreshes across legacy vehicle platforms, pulling replacement demand forward.
- Curtain Airbag Adoption:Side-impact and pole-crash testing protocols are expanding curtain airbag fitment from premium segments into mass-market vehicle classes.
- China Domestic Production Scale:GB standards alignment with international benchmarks is accelerating airbag content per vehicle as local OEMs target export eligibility.
Market Restraints
- Inflator Raw Material Concentration:Sodium azide and guanidine nitrate supply chains cluster in specific Asian chemical processing corridors, exposing tier-2 suppliers to input volatility.
- Pyrotechnic System Obsolescence Risk:Hybrid inflator architectures are displacing pure pyrotechnic units, stranding capital equipment at dedicated propellant manufacturers.
- Multi-Source Certification Burden:OEMs now require duplicate homologation testing across inflator variants, extending development timelines and freezing engineering resources.
Strategic Opportunities
- Pedestrian Protection Integration:Hood-lift deployment strategies and external airbag prototypes are creating new product categories ahead of anticipated regulatory mandates in European testing regimes.
- Active Safety Convergence:Pre-crash sensing algorithms from advanced driver-assistance systems are enabling predictive airbag priming, opening software-content revenue streams for module vendors.
- Aftermarket Channel Development:Independent repair networks in Brazil and Mexico present untapped replacement demand as vehicle age profiles extend beyond warranty coverage periods.
Industry Challenges
- Accelerometer Calibration Talent Scarcity:Crash-sensor algorithm development requires rare cross-disciplinary expertise spanning MEMS physics and automotive functional safety standards.
- Out-of-Position Testing Complexity:FMVSS 208's expanded occupant size and position matrices are multiplying validation scenarios, consuming proving ground capacity and simulation compute resources.
- Legacy Platform Integration Friction:New inflator generations must maintain electrical and mechanical backward compatibility with decade-old airbag control unit architectures still in production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Airbags Market |
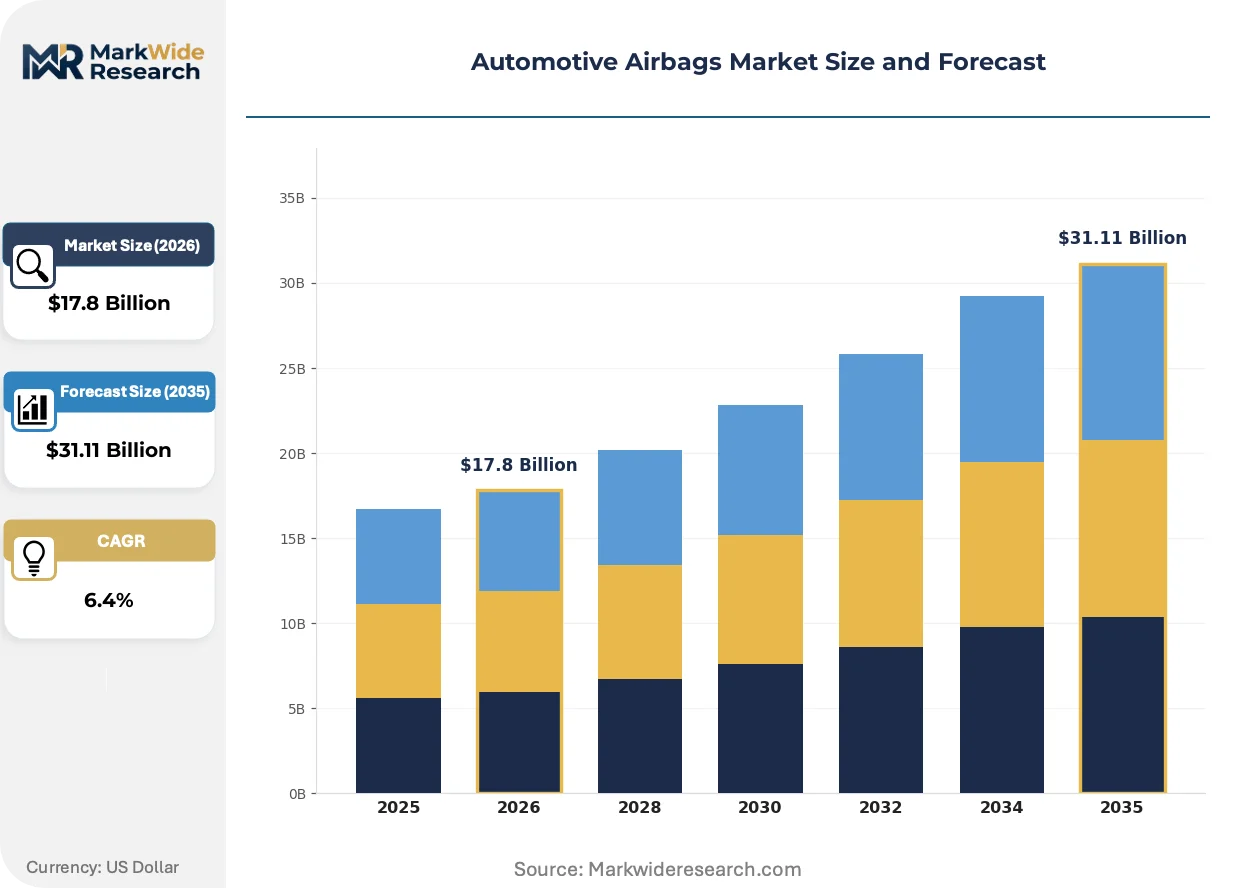
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $31.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frontal Airbags, Side Airbags, Curtain Airbags, Knee Airbags Technology: Electromechanical, Pyrotechnic, Hybrid, Inflatable End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Deployment Mode: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Off-Road Vehicles |
| Companies Covered | Autoliv Inc., ZF Friedrichshafen AG, Joyson Safety Systems, Toyoda Gosei Co. Ltd., Hyundai Mobis Co. Ltd., Continental AG, Robert Bosch GmbH, Denso Corporation, Daicel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Airbags Market Emerging Trajectories
Occupant classification systems are merging with adaptive inflation algorithms to enable force-modulated deployment, transforming airbags from passive restraints into sensor-rich safety nodes.
Hybrid inflator architectures are integrating pyrotechnic and stored-gas elements to enable multi-stage pressure curves. Mid-size OEMs in North America and Europe are adopting these systems fastest to satisfy divergent occupant size requirements without dual inflator inventory. This convergence is integrating crash-sensor data streams with seat-position and belt-tension inputs to compress deployment decision windows below ten milliseconds.
ECE R95 side-impact protocols are expanding testing severity parameters across European type-approval frameworks. The regulation now mandates head protection in pole-crash scenarios, forcing module vendors to extend curtain airbag coverage into third-row positions. Luxury vehicle platforms are responding first, with mass-market deployment following as cost curves flatten.
Fleet procurement centralization is consolidating safety system specification authority at holding-company levels rather than individual brand engineering teams. Tier-1 suppliers now negotiate multi-brand contracts directly with Volkswagen Group, Stellantis, and Hyundai Motor Group platform councils. This concentration is most visible in Germany and South Korea, where captive financing arms accelerate standardization across model ranges.
Automotive Airbags Market Segmentation
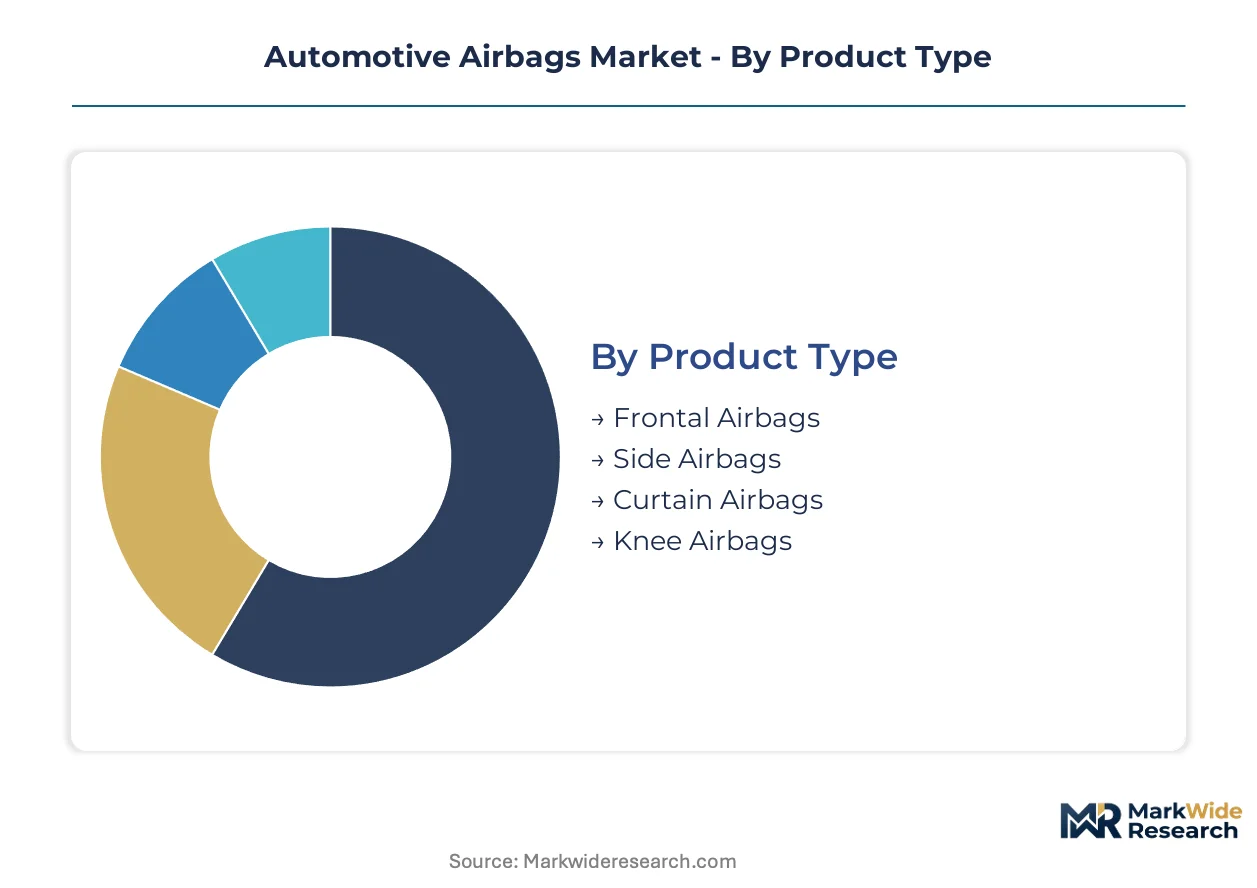
Airbag market segmentation reveals how capital allocation and technical complexity concentrate across distinct manufacturing tiers. Each dimension—product architecture, propulsion chemistry, channel structure, and vehicle application—carries divergent tooling requirements and margin profiles that reshape supplier strategy.
Product Type:
Capital intensity peaks with multi-chamber designs requiring precision weaving and coating infrastructure, while single-chamber units demand less specialized equipment.
- Frontal Airbags:Dual-chamber cushions woven from high-tenacity nylon 6,6 with silicone coating withstand temperatures exceeding 300°C during gas generation. Demand concentrates in China's domestic OEM sector as GB standards mandate driver and passenger positions across all passenger vehicle classes, pulling capacity toward Asian assembly corridors.
- Curtain Airbags:Extended-coverage tubular structures deploy from roof rails to protect head zones in side-impact and rollover scenarios. Fitment is accelerating fastest in European premium segments where ECE R95 pole-crash protocols now extend into third-row positions.
- Side Airbags:Seat-mounted or door-integrated units protect thorax regions in lateral collisions.
- Knee Airbags:Lower-dash modules prevent femur and pelvis injuries in frontal crashes.
Frontal airbags absorb the bulk of installed capacity; curtain airbags are expanding most quickly.
Technology:
Pyrotechnic chemistry dominates legacy installed base, though hybrid architectures now command premium positioning through force-modulation capabilities.
- Pyrotechnic:Sodium azide or guanidine nitrate propellants generate nitrogen gas through controlled combustion, occupying the largest historical footprint. Sodium azide supply chains cluster in specific Asian chemical processing corridors, exposing tier-2 suppliers to input volatility.
- Hybrid:Combined stored-gas and pyrotechnic elements enable multi-stage pressure curves for adaptive deployment force. Mid-size OEMs in Germany and the United States are adopting these systems fastest to satisfy divergent occupant size requirements without dual inflator inventory.
- Electromechanical:Compressed gas release without combustion, favored in specific commercial vehicle applications.
- Inflatable:Cold-gas systems for specialized restraint configurations.
Pyrotechnic systems retain the deepest manufacturing footprint; hybrid architectures are climbing the fastest as OEMs refresh sensor-calibrated platforms.
End User:
Channel power concentrates at vehicle assemblers and their captive tier-1 modules, while aftermarket networks remain fragmented.
- OEMs:Passenger vehicle manufacturers specify airbag content per vehicle through platform engineering teams. Volkswagen Group, Stellantis, and Hyundai Motor Group platform councils now negotiate multi-brand contracts directly with tier-1 suppliers, consolidating specification authority at holding-company levels.
- Tier-1 Suppliers:Dedicated safety module vendors integrate inflators, sensors, and control units. Autoliv Inc. sustains the broadest geographic manufacturing footprint among dedicated safety suppliers.
- Vehicle Assemblers:Contract manufacturers and joint-venture production facilities.
- Aftermarket Providers:Independent repair networks in Brazil and Mexico present untapped replacement demand as vehicle age profiles extend beyond warranty coverage periods.
OEMs command the largest procurement volume; aftermarket channels are gaining share fastest in extended-vehicle-life markets.
Deployment Mode:
Passenger vehicle platforms generate unit economics that subsidize development costs for smaller-volume applications.
- Passenger Vehicles:Sedans, SUVs, and light trucks represent the dominant installation base. NHTSA's updated FMVSS 208 deployment thresholds in the United States are mandating sensor hardware refreshes across legacy platforms, pulling replacement demand forward.
- Commercial Vehicles:Heavy trucks and buses carry specialized rollover protection requirements.
- Two-Wheelers:Motorcycle airbag systems remain nascent, concentrated in premium Japanese and European models.
- Off-Road Vehicles:Agricultural and construction equipment with specialized cab protection.
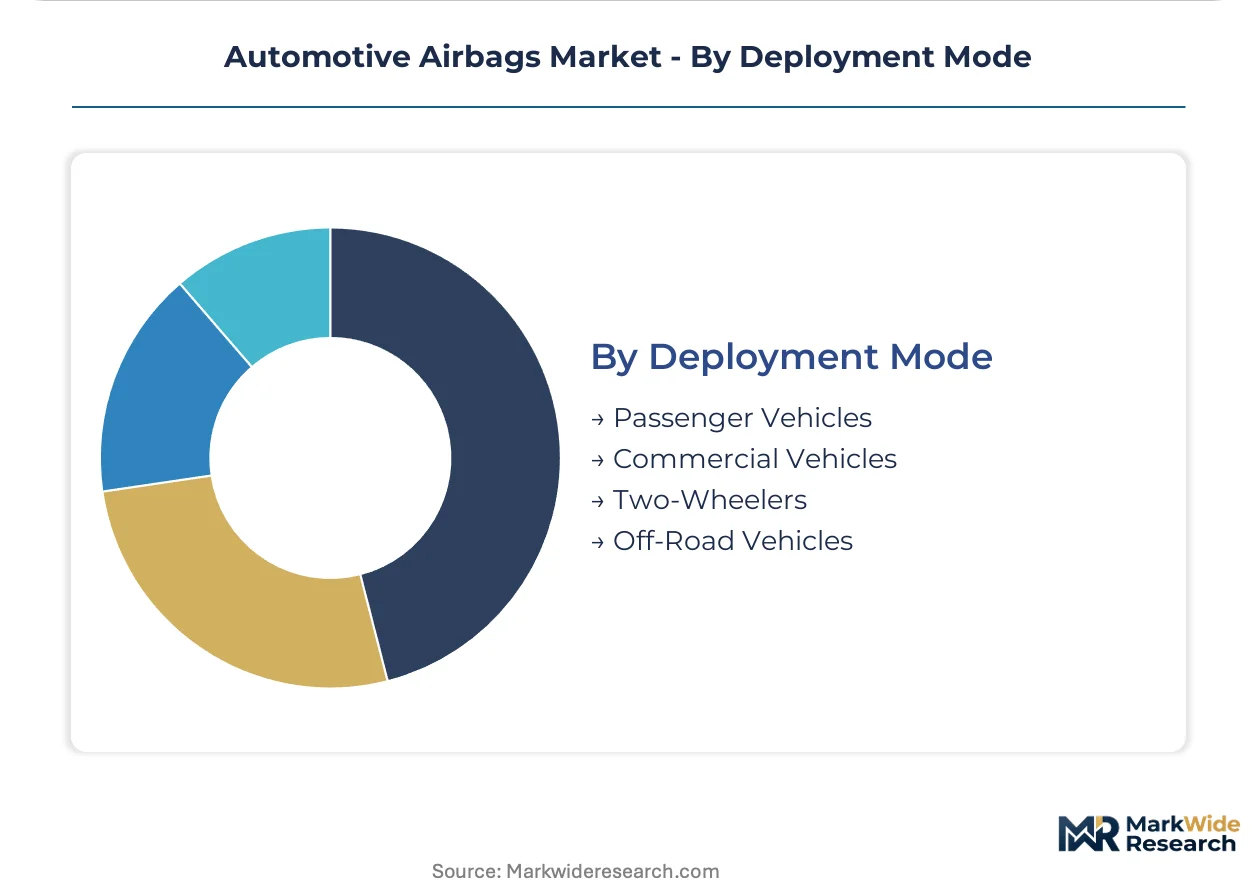
Passenger vehicles anchor manufacturing scale; commercial vehicle applications are expanding fastest as fleet safety specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sodium azide and guanidine nitrate processing corridors in eastern China supply the chemical propellants that feed airbag inflator manufacturing across Asia, Europe, and North America. This feedstock geography shapes where tier-2 suppliers locate and how OEMs manage catastrophic risk in their procurement networks.
United States
NHTSA's updated FMVSS 208 deployment thresholds are forcing sensor hardware refreshes across legacy vehicle platforms still in production. The regulation mandates stricter accelerometer calibration and out-of-position occupant protection matrices. Detroit's automotive engineering corridor hosts concentrated proving ground capacity where tier-1 suppliers validate these refreshed systems against expanded crash scenarios.
China
Domestic vehicle production scaling and GB standards alignment with international benchmarks are accelerating airbag content per vehicle as local OEMs target export eligibility. The country's national automotive safety regulator enforces these standards through type-approval frameworks that mirror ECE protocols. Shanghai and the Yangtze River Delta cluster the densest concentration of inflator manufacturing capacity serving both domestic brands and joint-venture assembly plants.
Germany
ECE R95 side-impact and pole-crash protocols are extending curtain airbag coverage requirements into third-row positions across European premium segments. The KBA enforces these testing severity parameters through type-approval frameworks that determine star-rating eligibility. Stuttgart and Munich anchor the engineering corridors where tier-1 suppliers integrate these extended-coverage designs with active safety architectures.
Japan
Occupant classification systems merging with adaptive inflation algorithms are advancing fastest among Japanese tier-1 suppliers serving domestic OEMs. METI coordinates safety technology roadmaps that align domestic standards with evolving UN regulations. Nagoya's industrial corridor concentrates weaving and coating infrastructure for high-tenacity nylon fabrics used in multi-chamber cushion designs.
South Korea
Fleet procurement centralization at holding-company level is consolidating safety system specification authority across Hyundai Motor Group platform councils. The country's national automotive regulator enforces alignment between domestic standards and ECE frameworks for export-bound vehicles. Seoul Capital Area engineering centers negotiate multi-brand contracts directly with dedicated safety module vendors, accelerating standardization across model ranges.
Automotive Airbags Market Vendor Landscape
Global majors compete with regional champions across manufacturing footprint breadth and captive capacity depth in Asian vehicle assembly corridors. The structure tiers into three supplier archetypes: dedicated safety specialists with full-system integration capability, diversified automotive conglomerates bundling airbag modules with chassis electronics, and regional fabricators serving domestic OEMs through joint-venture structures. Consolidation pressure is forcing dual-source procurement mandates and duplicate homologation testing across inflator variants.
Within the dedicated safety specialist tier, Autoliv Inc. and Joyson Safety Systems exemplify contrasting geographic strategies. Autoliv sustains manufacturing breadth across multiple continents, while Joyson anchors position through captive capacity concentration in Asian assembly corridors. ZF Friedrichshafen AG occupies a position among diversified conglomerates, leveraging chassis-electronics integration to bundle airbag control units with broader active safety architectures. These three patterns represent the dominant competitive configurations shaping procurement negotiations with Volkswagen Group, Stellantis, and Hyundai Motor Group platform councils.
| Leading Market Players |
|---|
| Autoliv Inc. |
| ZF Friedrichshafen AG |
| Joyson Safety Systems |
| Toyoda Gosei Co. Ltd. |
| Hyundai Mobis Co. Ltd. |
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| Daicel Corporation |
| Others |
Supply Flow & Price Mechanics
Accelerometer calibration talent scarcity in Germany's Stuttgart engineering corridor widens pricing spreads between premium sensor-integrated modules and economy-tier pyrotechnic units. Labor-cost differentials between European algorithm development centers and Asian propellant manufacturing clusters translate into tiered procurement economics for OEM platform councils.
Pricing Analysis
Warranty-bundled sensor recalibration services separate premium tier-1 supplier contracts from unbundled aftermarket transactions. Three-tier pricing structure across premium, standard, and economy levels reflects divergent certification grades under FMVSS 208 and ECE R95 protocols. Price differentiation hinges on homologation testing depth and out-of-position validation matrices. Cost compression in mid-tier hybrid inflator segments is intensifying because OEMs demand duplicate certification across dual-source procurement mandates. Fleet procurement managers at holding-company level exhibit highest price sensitivity; luxury platform engineering teams prioritize adaptive deployment capabilities over unit cost.
Supply Chain Analysis
Homologation qualification gates restrict inflator supply to certified propellant chemistry processors meeting UN transport and storage protocols. Sodium azide and guanidine nitrate feedstock draws from eastern China chemical processing corridors, with secondary weaving and coating capacity clustering in Japan's Nagoya industrial zone and South Korea's Seoul Capital Area. Single-source vulnerability concentrates in Asian pyrotechnic chemical supply given limited alternative qualified processors. Distribution runs through captive tier-1 module vendor networks directly into OEM platform engineering specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where NHTSA's FMVSS 208 deployment threshold updates erect barrier-to-entry moats favoring incumbents with validated sensor calibration infrastructure.
For Market Incumbents: Lock in accelerometer algorithm talent pools through targeted recruitment in Stuttgart and Munich engineering corridors. Extend backward integration into sodium azide chemical processing to deflect raw material volatility threatening tier-2 supplier stability. Fortify position against hybrid inflator technology substitution by accelerating multi-stage pressure curve patent filings. For New Entrants and Emerging Players: Independent aftermarket repair networks in Brazil and Mexico represent the most penetrable buyer archetype given extended vehicle age profiles beyond warranty coverage. Target untapped curtain airbag retrofit demand in Latin American commercial vehicle fleets facing tightening rollover protection specifications. Pursue white-label supply agreements with regional distributors lacking direct tier-1 vendor relationships. For Investors and Strategic Acquirers: Re-rating potential sits with adaptive inflation algorithm developers given convergence between pre-crash sensing and predictive airbag priming architectures. Long-term viability favors specialists bridging MEMS physics expertise with automotive functional safety certification. Monitor pedestrian-protection integration rule advancement in European testing regimes as inflection signal for external airbag prototype commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Inflator Certification | Duplicate homologation testing under FMVSS 208 and ECE R95 secures OEM platform eligibility. |
| Hybrid Architecture Scale-Up | Multi-stage pressure curve production capacity captures mid-size OEM refresh cycles in Germany and the United States. |
| Pedestrian Protection R&D | Hood-lift deployment prototypes position suppliers ahead of anticipated ECE regulatory mandates. |
| Accelerometer Talent Acquisition | Cross-disciplinary MEMS physics recruitment in Stuttgart engineering corridors defends algorithm development capacity. |
| Aftermarket Channel Partnership | Independent repair network agreements in Brazil and Mexico unlock replacement demand beyond warranty periods. |
Methodological Framework
Independent corroboration across OEM platform engineering directors, tier-1 supplier procurement leads, aftermarket distributor operations managers, and national automotive safety regulators underwrites the qualitative findings. Primary interviews with these stakeholders combined with secondary validation against NHTSA rulemaking dockets, ECE R94/R95 type-approval frameworks, and vehicle production databases established baseline assumptions. Bottom-up content-per-vehicle modeling and top-down market sizing triangulate volume estimates.
Comparable historical reference periods anchored the projection horizon to observed regulatory compliance cycles and OEM platform refresh cadences. Segmentation dimensions span product architecture, propulsion chemistry, channel structure, and vehicle application class across the modeling period. CAGRs derive from fitted growth curves calibrated to regulatory mandate effective dates and technology substitution elasticities. Forecast inputs incorporate sensor hardware refresh pull-forward effects and curtain airbag fitment expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pedestrian-protection rule finalization and hybrid inflator adoption velocity. Projections reflect assumptions on chemical propellant supply stability and accelerometer calibration talent availability. A model refresh is warranted upon material change in NHTSA deployment threshold enforcement or ECE R95 testing severity parameter expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Global Motorcycle Advanced Driver Assistance System (ADAS) Market
Automotive Safety and Security Systems
Automotive Airbag Inflator Market
Automotive Safety and Security Systems
Automotive Seatbelt Market
Automotive Safety and Security Systems
Airbag Sensor Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Smart Motorcycle Helmet Market
Automotive Safety and Security Systems
Global Automotive Knee Airbags Market
Automotive Safety and Security Systems
Automotive Brake Pad Wear Sensor Harness Market
Automotive Safety and Security Systems
Automotive Occupant Sensing System Market
Automotive Safety and Security Systems
United States Automotive Collision Avoidance Systems Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Automotive Rear Occupant Alert System Market
Automotive Safety and Security Systems
LAMEA Hill-Start Assist System Market
Automotive Safety and Security Systems
Driver Monitoring System (DMS) Market
Automotive Safety and Security Systems
AI in-Vehicle Surveillance Market