
 ISO Shipping Container Market | 2026-2036
ISO Shipping Container Market Size, Share, and Industry Trends Forecast 2026-2036
ISO Shipping Container Market Outlook
A shift from single-source steel procurement to multi-source alloy and composite sourcing is repositioning how container manufacturers manage input cost volatility. China International Marine Containers leverages its captive steel rolling capacity to insulate margins from spot price swings. Maersk Container Industry anchors its competitiveness through integrated reefer engineering and controlled-atmosphere technology leadership. CXIC Group Containers sustains volume dominance across standard dry box production through scale economies at its Changzhou and Qingdao facilities.
An ISO shipping container is a standardized intermodal freight container built to ISO 668 and ISO 1496 specifications, typically fabricated from Corten steel with corner castings designed to withstand stacking loads and crane handling across ship, rail, and truck modes. Its primary purpose is to enable seamless cargo transfer between transportation modes without unloading contents. Dry containers occupy the largest volume share but face margin compression from commoditization, while reefer containers command premium pricing due to integrated refrigeration unit complexity and tighter certification requirements. Modular construction usage represents the fastest-growing demand vector as architects and developers repurpose retired boxes for affordable housing and commercial structures.
The International Maritime Organization enforces the CSC Convention for structural safety certification, while China's SAMR administers GB/T 1413 dimensional compliance and the EU's CE marking governs machinery-integrated reefer units sold into European ports. These frameworks elevate compliance costs for new entrants but protect incumbent manufacturers with established testing laboratory relationships. Stakeholders must monitor evolving carbon border mechanisms and recycled content mandates that will reshape material specifications and supplier qualification criteria.
Market Dynamics
Cold chain logistics operators are accelerating reefer container procurement as pharmaceutical and fresh food corridors expand, while China's GB standards and the EU's CSRD tighten material traceability requirements that favor incumbent manufacturers with established testing laboratory relationships.
Growth Catalysts
- EU CSRD lifecycle reporting:Mandatory environmental disclosures for container fleets sold into European ports are creating compliance-driven replacement cycles among leasing companies seeking certified inventory.
- Controlled-atmosphere reefer engineering:Precision gas modulation technology extends perishable shelf life, drawing investment from pharmaceutical cold chain operators serving temperature-sensitive biologics corridors.
- Southeast Asian port cluster expansion:Manufacturing relocation to Vietnam and Indonesia is generating concentrated demand for standard dry boxes and specialized reefers at Ho Chi Minh City and Jakarta terminals.
Market Restraints
- Corten steel price volatility:Alloy input costs fluctuate with Chinese steel mill output curbs, compressing margins for manufacturers without captive rolling capacity.
- Refrigerant regulatory friction:The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in reefer units, forcing engineering redesigns and recertification timelines.
- Modular construction substitution:Retired container repurposing for affordable housing diverts secondary market supply, reducing available refurbishment stock for traditional resale channels.
Strategic Opportunities
- Carbon border mechanism alignment:The EU Carbon Border Adjustment Mechanism creates first-mover advantage for manufacturers with verified low-emission steel sourcing and lifecycle documentation systems.
- India pharmaceutical cold chain:CDSCO temperature-control mandates for vaccine distribution are opening reefer procurement opportunities at Mumbai and Chennai pharmaceutical hubs.
- Digital twin integration:IoT sensor convergence with fleet management platforms enables predictive maintenance contracts, shifting revenue from unit sales to performance-based service models.
Industry Challenges
- Reefer technician scarcity:Specialized refrigeration and controlled-atmosphere system maintenance skills lag fleet expansion, extending downtime and service response intervals at remote port locations.
- ISO 1496-2 recertification complexity:Structural testing and refrigeration unit compliance renewal timelines create administrative bottlenecks, delaying lease fleet rotation and revenue recognition.
- Multi-source alloy qualification:Supplier diversification for Corten steel alternatives requires extensive weld testing and corner casting compatibility validation, slowing procurement agility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ISO Shipping Container Market |
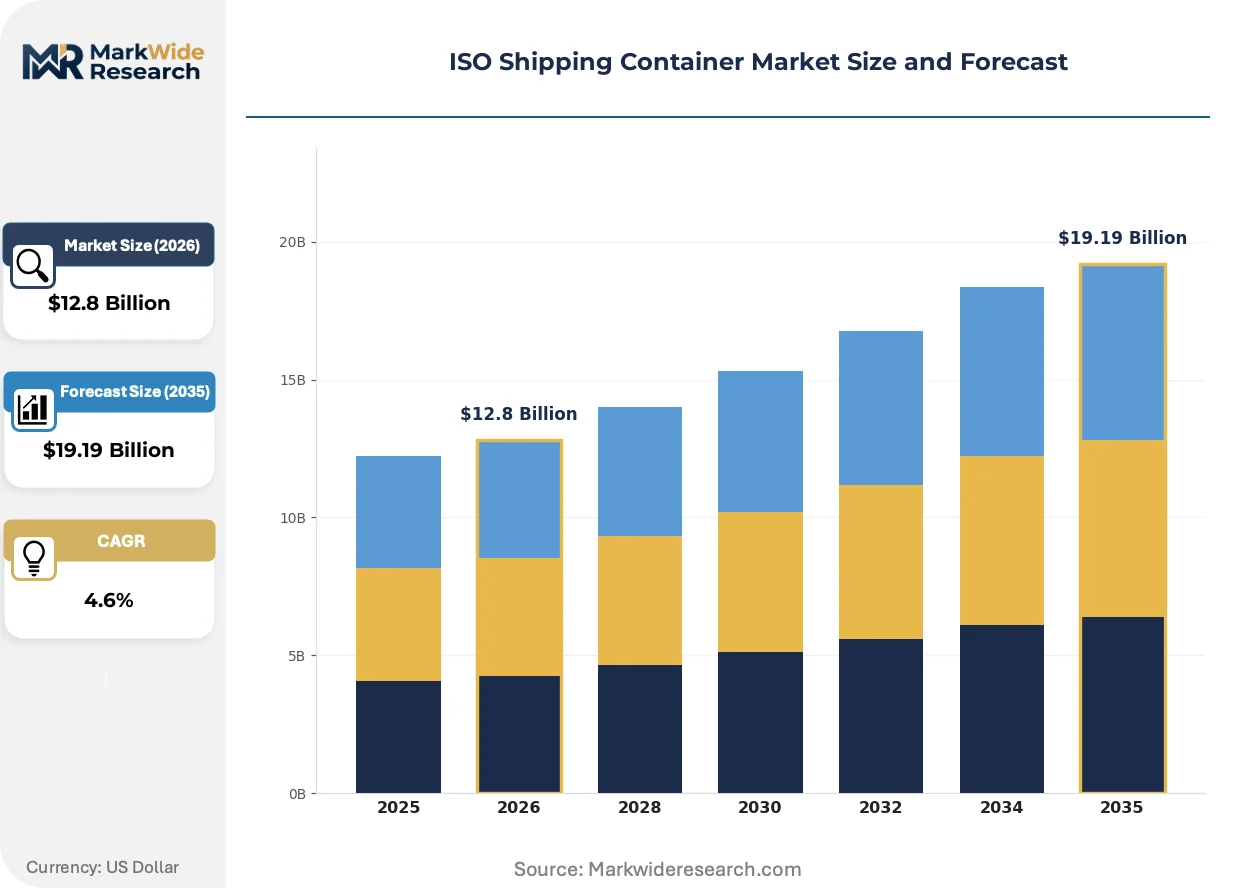
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Dry Container, Reefer Container, Open Top Container, Flat Rack Container Material: Steel, Aluminum, Fiberglass, Composite Usage: Storage, Transport, Shipping, Modular Construction End User: Logistics Companies, Retailers, Manufacturers, Construction Firms |
| Companies Covered | China International Marine Containers, Maersk Container Industry, CXIC Group Containers, Singamas Container Holdings, Dong Fang International Container, TLS Offshore Containers, W&K Containers, Sea Box, Danteco Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ISO Shipping Container Market Strategic Shifts
Container fabrication and fleet management are undergoing material and digital transformation simultaneously, with sustainability mandates and operational efficiency pressures converging to reshape competitive positioning across manufacturing and service layers.
Composite panel sandwich construction combining fiberglass-reinforced polymer skins with aluminum honeycomb cores is overtaking traditional Corten steel sidewalls in lightweight reefer applications. Pharmaceutical logistics operators in the EU and Japan are specifying these units for temperature-sensitive biologics corridors where payload optimization offsets higher unit costs. The technology is overtaking conventional steel fabrication in premium reefer segments by enabling thicker insulation layers without weight penalties, compressing energy consumption per refrigerated ton-mile.
China's SAMR enforcement of updated GB/T 1413 dimensional compliance and the EU's machinery directive integration with CE marking for reefer units are elevating documentation burdens. Manufacturers must now maintain batch-level material certificates and welding procedure specifications across production facilities. Reefer-integrated container categories face the most intensive scrutiny, with notified body involvement extending type-approval timelines and favoring established testing laboratory relationships.
Leasing companies are consolidating procurement under multi-year framework agreements with embedded fleet refresh obligations, displacing spot-market purchasing. Large container lessors at Singapore and Rotterdam hubs now specify performance guarantees covering residual value and maintenance cost caps. This concentration is most visible in the trans-Pacific pharmaceutical corridor, where temperature excursion liability has shifted risk allocation toward manufacturers with integrated service networks and real-time monitoring capabilities.
ISO Shipping Container Market Segmentation
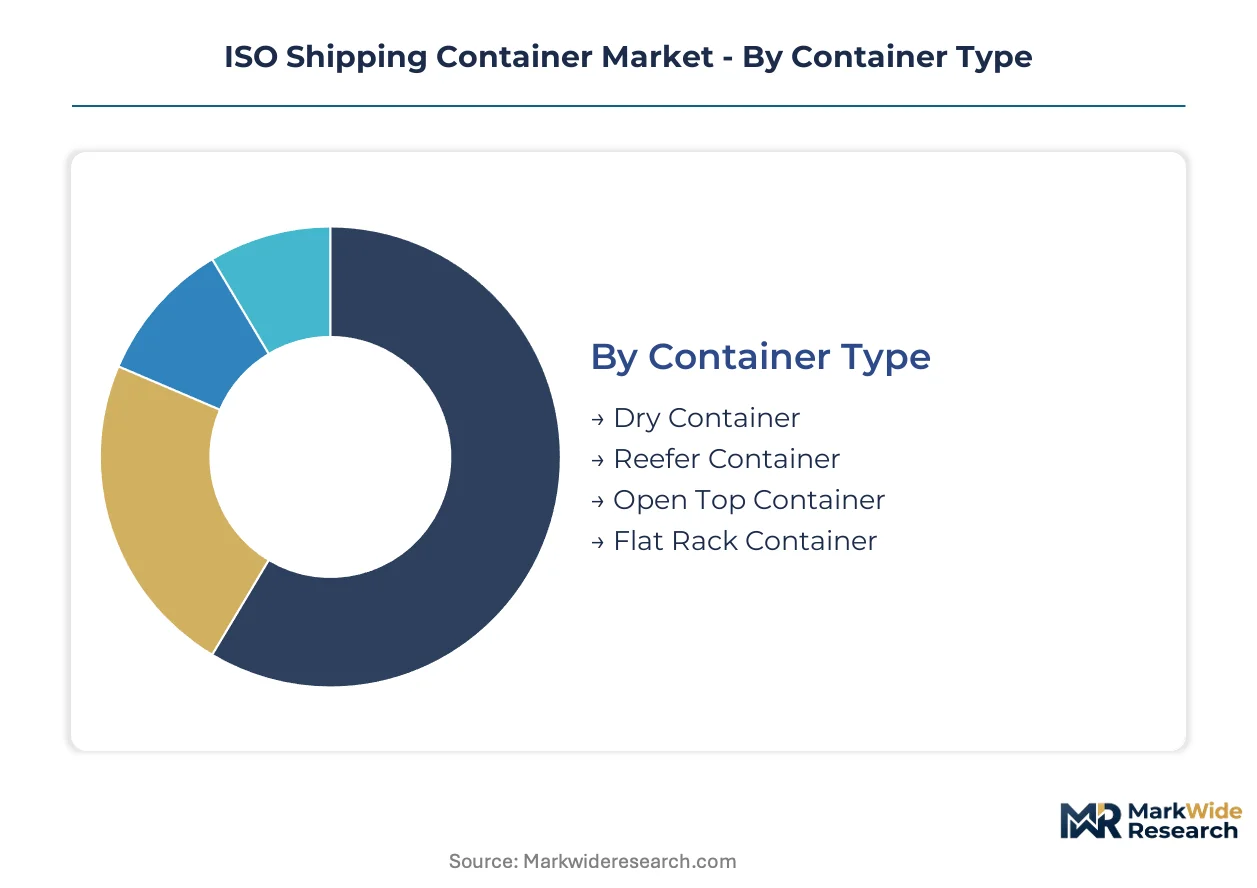
Container procurement patterns diverge sharply between high-volume commodity segments and premium-engineered categories requiring specialized certification. Understanding these splits reveals where margin protection concentrates and where price compression threatens manufacturer profitability.
Container Type:
Dry containers dominate unit volumes but face narrowing margins, while reefer variants capture premium pricing through integrated engineering complexity.
- Dry Container:Fabricated from Corten steel with corner castings rated for stacking loads, these units serve standard cargo corridors across Vietnam and Indonesia manufacturing clusters. Procurement concentrates at Ho Chi Minh City and Jakarta terminals as production relocation accelerates, though spot-market purchasing faces margin compression from commoditization.
- Reefer Container:Integrated refrigeration units with controlled-atmosphere gas modulation extend pharmaceutical and fresh food shelf life. Demand from EU cold chain operators is tightening around units with F-Gas Regulation compliance and real-time temperature monitoring, drawing premium pricing relative to standard dry boxes.
- Open Top Container:Removable tarpaulin roofs accommodate heavy machinery and bulk mineral cargo loading from above.
- Flat Rack Container:Collapsible end walls enable oversized cargo transport including industrial equipment and vehicle chassis.
Mature deployment sits with dry containers across established manufacturing corridors. Newer deployment is concentrated in reefer units serving temperature-sensitive biologics and pharmaceutical distribution networks.
Material:
Steel maintains cost-position dominance while composite alternatives penetrate premium insulation applications.
- Steel:Corten weathering steel remains the baseline specification for structural sidewalls and corner casting fabrication. Chinese mill output curbs create spot price volatility that favors manufacturers with captive rolling capacity or multi-source alloy qualification.
- Composite:Fiberglass-reinforced polymer skins bonded to aluminum honeycomb cores enable thicker insulation layers without weight penalties. EU and Japanese pharmaceutical logistics operators specify these units for energy-efficient temperature control, though unit costs run higher than conventional steel fabrication.
- Aluminum:Lightweight corrosion-resistant panels reduce tare weight for air-freight intermodal applications.
- Fiberglass:Molded reinforced plastic components serve specialized chemical-resistant and non-conductive cargo requirements.
Volume procurement clusters around steel specifications. Composite fabrication is expanding most quickly in premium reefer segments where payload optimization justifies higher capital outlay.
Usage:
Traditional cargo movement applications face diversion pressure from secondary-market repurposing trends.
- Transport:Intermodal freight movement across ship, rail, and truck modes remains the core revenue base for leasing companies and shipping lines. Fleet refresh obligations under multi-year framework agreements now specify residual value guarantees and maintenance cost caps at Singapore and Rotterdam hub operations.
- Modular Construction:Retired container repurposing for affordable housing and commercial structures is accelerating fastest among architects and developers seeking standardized building modules. This demand vector diverts secondary market supply and reduces available refurbishment stock for traditional resale channels.
- Storage:Static on-site inventory holding serves construction sites and agricultural harvest buffering.
- Shipping:Maritime cargo carriage represents the original application segment with established CSC Convention certification requirements.
Transport and shipping applications hold established deployment scale. Modular construction is gaining share fastest as sustainability mandates and housing cost pressures reshape end-of-life container economics.
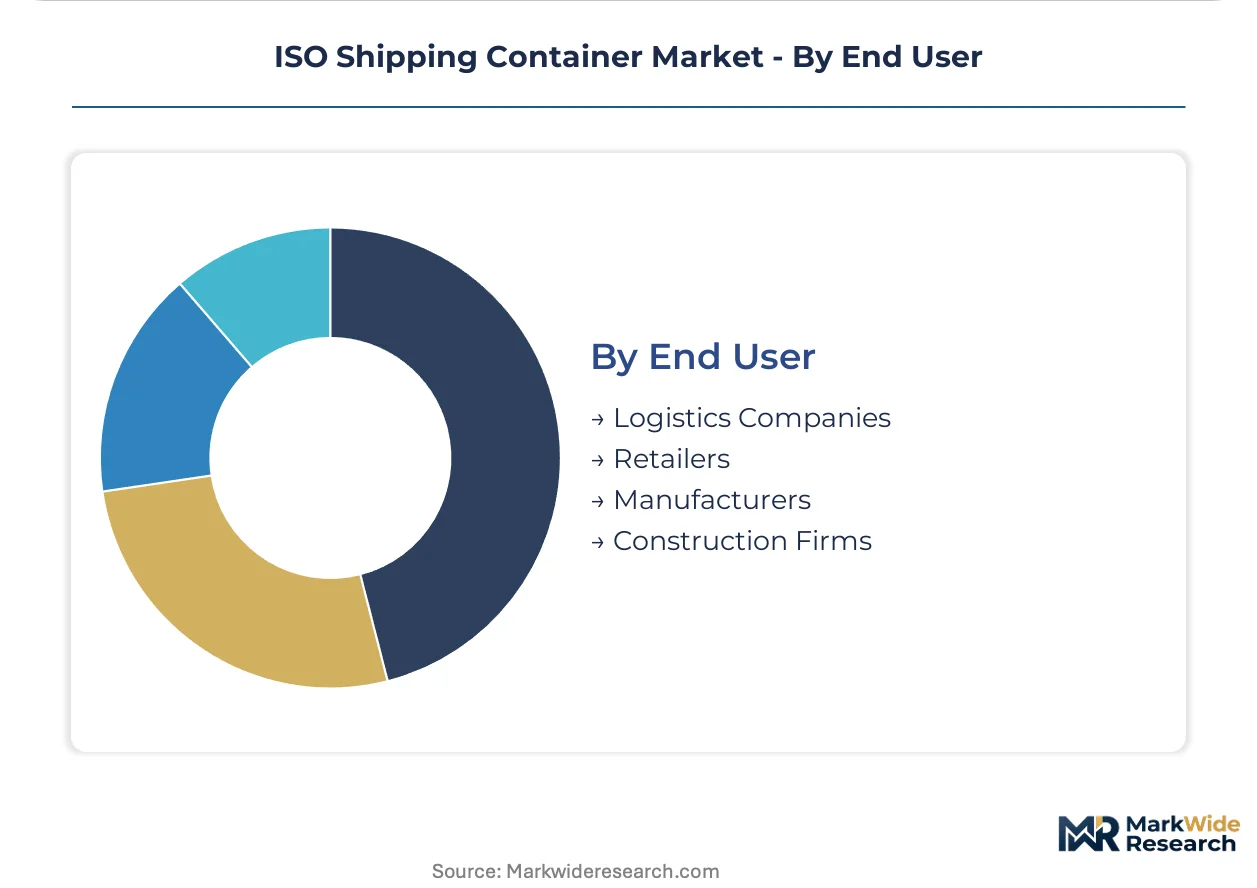
End User:
Logistics operators consolidate procurement leverage while construction firms emerge as non-traditional demand sources.
- Logistics Companies:Cold chain operators and container lessors drive fleet standardization through framework agreements with embedded refresh cycles. Temperature excursion liability in pharmaceutical corridors has shifted risk allocation toward manufacturers with integrated service networks and IoT-enabled monitoring platforms.
- Construction Firms:Non-traditional procurement for modular building projects is reshaping demand patterns, with developers specifying retired box conditions and structural certification for permanent installation applications.
- Retailers:Private fleet ownership for inventory positioning and seasonal demand buffering.
- Manufacturers:Captive container pools for just-in-time component supply and finished goods export.
Logistics companies anchor procurement volume through leasing and fleet management contracts. Construction firms represent the steepest expansion trajectory as modular building codes mature and secondary market supply chains formalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Container procurement concentrates in Asian manufacturing corridors where port infrastructure expansion and cold chain logistics investment are accelerating simultaneously. Vietnam and Indonesia are absorbing manufacturing relocation from higher-cost hubs, while China's domestic fleet renewal and India's pharmaceutical distribution mandates reshape regional demand patterns.
China
SAMR enforcement of updated GB/T 1413 dimensional compliance is elevating documentation burdens for domestic manufacturers. The regulator now requires batch-level material certificates across production facilities. Changzhou and Qingdao container fabrication clusters are consolidating output under state-supported capacity rationalization programs.
Vietnam
Ho Chi Minh City terminal operators are expanding dry container storage yards to accommodate electronics and textile export growth. The Ministry of Transport has accelerated port deepening projects to handle post-Panamax vessel calls. Manufacturing park developers in Binh Duong and Dong Nai provinces are specifying captive container pools for just-in-time component supply.
Indonesia
Jakarta's Tanjung Priok port complex is generating concentrated reefer demand from palm oil and seafood export corridors. The national logistics council has mandated temperature-control infrastructure investment for pharmaceutical distribution. Surabaya and Makassar secondary hubs are emerging as transshipment alternatives to Singapore.
India
CDSCO temperature-control mandates for vaccine distribution are opening reefer procurement opportunities at Mumbai and Chennai pharmaceutical hubs. The DGFT has streamlined containerized export certification timelines for agricultural commodities. Gujarat's Mundra port is expanding dedicated reefer plug infrastructure to capture cold chain traffic from Nhava Sheva.
United States
Los Angeles-Long Beach port complex congestion is driving chassis and container repositioning investment inland to Dallas and Chicago intermodal terminals. The EPA has tightened refrigerant leak detection requirements for reefer units operating at US ports. Savannah and Charleston terminal operators are expanding controlled-atmosphere storage capacity for agricultural export seasons.
ISO Shipping Container Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers respond to Southeast Asian demand concentration and fleet renewal cycles. The vendor base clusters around three strategic tiers: integrated steel-producers with captive rolling mills, specialized reefer engineering houses with controlled-atmosphere certification, and scale-driven dry box fabricators serving commodity procurement. Strategic archetypes include backward-integrated conglomerates insulating margin volatility through upstream steel control, technology-differentiated refrigeration specialists commanding premium pricing, and volume-focused producers leveraging Changzhou and Qingdao production scale. Competitive moves center on multi-source alloy qualification programs and digital twin service model development.
Among Chinese fabricators, China International Marine Containers and CXIC Group Containers exemplify scale-driven archetypes with established production base positioning. Maersk Container Industry represents the technology-differentiated tier through integrated reefer engineering specialization. These three anchors illustrate how competitive positioning stratifies across steel integration depth, refrigeration complexity, and manufacturing scale.
| Leading Market Players |
|---|
| China International Marine Containers |
| Maersk Container Industry |
| CXIC Group Containers |
| Singamas Container Holdings |
| Dong Fang International Container |
| TLS Offshore Containers |
| W&K Containers |
| Sea Box |
| Danteco Industries |
| Others |
Value Chain & Pricing Dynamics
Corten steel alloy costs cascade from Chinese mill output curbs through three distinct pricing tiers for dry container procurement, with captive rolling capacity insulating integrated manufacturers from spot volatility that compresses margins at commodity fabricators.
Pricing Analysis
Volume procurement concentrates at economy-tier dry box specifications where margin compression runs deepest, while premium reefer units with controlled-atmosphere certification and F-Gas Regulation compliance capture substantial price premiums. Price differentiation hinges on refrigeration unit complexity and material certification grade, with EU-bound units requiring CE-marked machinery integration commanding higher tiers. Pricing pressure stems from multi-source alloy qualification timelines that delay procurement agility for non-integrated manufacturers. Logistics operators and container lessors exhibit highest price sensitivity in standard dry box spot markets, whereas pharmaceutical cold chain operators demonstrate lowest sensitivity due to temperature excursion liability costs.
Supply Chain Analysis
Specialized corner casting and refrigeration unit supply rests on German engineering houses, Chinese steel rolling capacity, and South Korean compressor technology for integrated reefer systems. Raw material feeds draw from Chinese Corten steel production, Japanese corrosion-resistant alloy formulations, and European refrigerant gas suppliers facing F-Gas phase-down restrictions. Supply chain risk centers on single-source vulnerability for controlled-atmosphere gas modulation components where qualified alternative suppliers remain limited. Distribution runs through Singapore and Rotterdam hub terminals where leasing companies consolidate procurement under multi-year framework agreements with embedded fleet refresh obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corten steel rolling capacity constraints in China prop pricing power for backward-integrated manufacturers, while reefer technician scarcity creates service-network bottlenecks that sustain premium capture for incumbents with established maintenance infrastructure.
For Market Incumbents: Hedge margin volatility through multi-source alloy qualification programs spanning Vietnamese and Indonesian steel mill partnerships, while accelerating digital twin integration to shift revenue toward predictive maintenance contracts. Refrigerant regulatory friction under EU F-Gas Regulation threatens engineering redesign costs that favor manufacturers with established testing laboratory relationships and notified body access. For New Entrants and Emerging Players: Launch via modular construction supply partnerships targeting retired container refurbishment channels in Southeast Asian affordable housing corridors, where formalized secondary market supply chains remain underdeveloped. India's pharmaceutical cold chain expansion under CDSCO temperature-control mandates offers the most penetrable reefer procurement entry point, with Mumbai and Chennai hub specifications still consolidating around service-integrated vendor models. For Investors and Strategic Acquirers: EU Carbon Border Adjustment Mechanism implementation timeline is the leading indicator that low-emission steel sourcing and lifecycle documentation capabilities will separate acquisition targets with stranded asset risk from those with compliance-ready inventory. Long-term viability across the analysis window favors manufacturers with verified supplier qualification systems and IoT-enabled fleet management platforms over commodity fabricators exposed to spot-market pricing. Watch for consolidation signals among Changzhou and Qingdao production clusters as state-supported capacity rationalization programs mature.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Alloy Qualification | Diversified Corten steel sourcing insulates margins from Chinese mill output curbs and spot price swings. |
| Controlled-Atmosphere Certification Investment | F-Gas Regulation compliance and CE marking access sustain premium reefer pricing in EU pharmaceutical corridors. |
| Digital Twin Platform Development | IoT sensor integration enables predictive maintenance contracts shifting revenue from unit sales to service models. |
| Southeast Asian Hub Expansion | Ho Chi Minh City and Jakarta terminal proximity captures manufacturing relocation demand for dry and reefer boxes. |
| Secondary Market Supply Chain Formalization | Retired container refurbishment channel control addresses modular construction demand diverting traditional resale stock. |
Study Parameters
Trade flow databases, customs export records, and container fleet registration data formed the secondary backbone, supplemented by SEC filings from listed manufacturers and SAMR certification registries. Primary fieldwork encompassed interviews with container leasing procurement directors, reefer engineering technical leads, port terminal operations managers, and cold chain logistics operators across Singapore, Rotterdam, and Shanghai hub markets. Bottom-up unit demand estimates from manufacturing cluster expansion projects triangulated against top-down fleet replacement cycle analysis.
Bottom-up modeling segmented volume and value projections across container type, material specification, end-use application, and regional port cluster demand patterns throughout the forecast period. CAGRs were derived from weighted average growth trajectories across pharmaceutical cold chain investment cycles, manufacturing relocation timelines, and modular construction adoption curves. Industry-specific inputs incorporated reefer plug infrastructure expansion data, GB/T 1413 compliance certification volumes, and EU CSRD disclosure preparation rates among leasing companies.
The model assumes a particular technology adoption path for composite panel sandwich construction; alternative pathways for fiberglass-reinforced polymer reefer fabrication would alter the outlook for energy-efficient temperature control market capture. Forecasts reflect assumptions regarding Chinese steel mill capacity rationalization, F-Gas Regulation phase-down compliance timelines, and India pharmaceutical distribution infrastructure investment rates. A small set of named triggers warrants ongoing watch: EU Carbon Border Adjustment Mechanism enforcement scope, CDSCO temperature-control mandate expansion beyond vaccine distribution, and reefer technician training program graduation volumes at Southeast Asian maritime academies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
United Kingdom Third Party Logistics (3PL) Market
Logistics and Shipping
Myanmar Freight and Logistics Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
South Korea Third-Party Logistics (3PL) Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Spare Part Logistics Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Saudi Arabia Contract Logistics Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
US FTL Brokerage Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Iraq Logistics Market