
 Automotive Bushing Technologies Market | 2026-2036
Automotive Bushing Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Bushing Technologies Market Analysis
The capital-intensity divergence between fully integrated rubber compounders and assembly-only bushing specialists is unwinding competitive stability in the supply base. Continental AG leverages captive mixing operations and polymer science centers to sustain margin control across OEM contracts. Vibracoustic GmbH anchors its position through acoustic testing capabilities that differentiate polyurethane bushing formulations for premium chassis programs. ZF Friedrichshafen AG competes by extending vertical reach into forged metal sleeves and bonded-rubber assemblies for electric axle modules.
Automotive bushing technologies comprise cylindrical or sleeve-shaped compliance elements manufactured from elastomeric compounds, thermoplastic polymers, or sintered metals, typically bonded to inner and outer metal tubes through vulcanization or press-fit assembly, functioning to isolate vibration, accommodate angular deflection, and maintain positional tolerance in vehicle kinematic chains. The primary industrial purpose centers on managing noise-vibration-harshness transmission while permitting controlled movement in suspension linkages, steering columns, and powertrain mounts subjected to multi-axis dynamic loading. Rubber bushings occupy the mature volume tier where natural rubber and styrene-butadiene formulations dominate cost-sensitive chassis applications, while composite bushings represent the fastest-expanding segment as hybrid fiber-reinforced thermoplastics displace conventional metals in electric vehicle subframes seeking mass reduction. Polyurethane bushings concentrate margin pools in aftermarket performance channels where Shore hardness customization commands pricing premiums over standard OEM specifications.
EPA tailpipe and evaporative emission standards, NHTSA federal motor vehicle safety standards for suspension integrity, and REACH chemical restrictions on aromatic process oils collectively tighten material qualification pathways and accelerate substitution toward bio-based synthetic elastomers. The EU Green Deal's embedded carbon requirements for automotive components are reshaping supplier certification demands across European OEM sourcing protocols. Stakeholders must monitor regulatory divergence between EPA durability testing cycles and EMA chemical substance authorizations when selecting compound formulations for multi-region platform programs.
Market Dynamics
The shift from internal combustion powertrains to electric vehicle architectures is fundamentally reconfiguring bushing load profiles, material specifications, and supplier qualification pathways across OEM sourcing programs.
Growth Catalysts
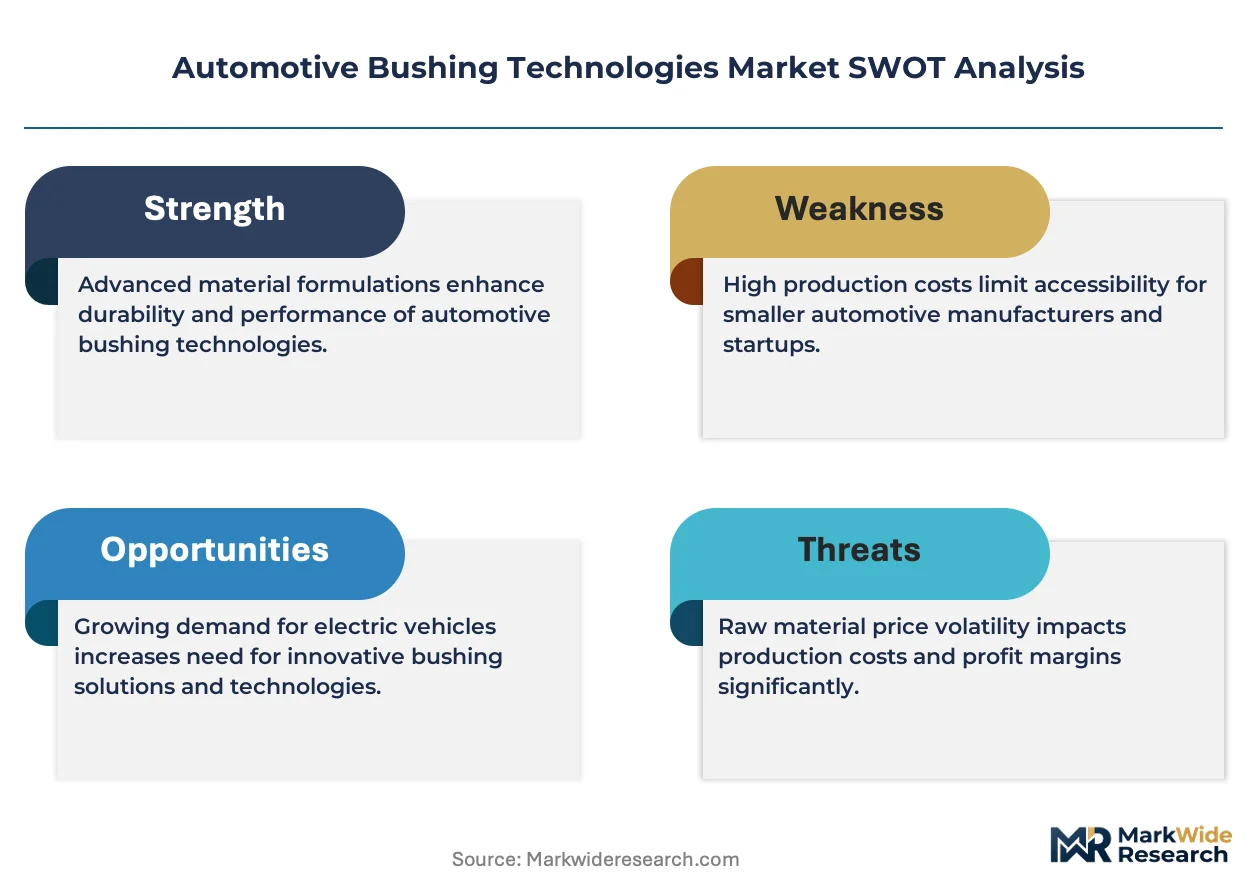
- EPA Tier 3 emission standards:These regulations mandate stricter NVH controls that accelerate adoption of advanced polyurethane and composite bushing formulations in chassis systems.
- Electric vehicle subframes:Battery-electric platforms from manufacturers like Tesla and BYD generate concentrated demand for lightweight, fiber-reinforced thermoplastic bushings that reduce unsprung mass.
- German automotive production clusters:Dense tier-1 supplier ecosystems around Stuttgart and Munich sustain innovation spillovers in bonded-rubber assembly techniques.
Market Restraints
- Natural rubber price volatility:Southeast Asian supply disruptions and climate-driven harvest variability compress margins for rubber bushing specialists dependent on spot market sourcing.
- REACH chemical restrictions:Aromatic process oil limitations under ECHA authorization procedures force costly reformulation of SBR compounds for European OEM contracts.
- Steel sleeve forging concentration:Captive forging capacity at major tier-1 suppliers creates supply bottlenecks for independent bushing assemblers seeking forged metal substrates.
Strategic Opportunities
- India automotive manufacturing expansion:PLI scheme incentives for electric vehicle production create entry points for bushing suppliers establishing localized compound mixing operations.
- Aftermarket performance channels:Shore hardness customization for polyurethane bushings commands pricing premiums from enthusiast segments seeking chassis tuning solutions.
- EU Green Deal embedded carbon requirements:Supplier certification protocols favor bio-based synthetic elastomers, rewarding early movers with preferred vendor status.
Industry Challenges
- Multi-axis dynamic simulation expertise:OEMs now require predictive modeling capabilities for bushing fatigue life that exceed traditional supplier skill bases in rubber rheology.
- Dual-chemistry qualification timelines:Parallel validation of conventional rubber and thermoplastic formulations for shared platforms extends program development cycles.
- Cross-platform specification harmonization:Divergent EPA durability testing cycles and EMA chemical substance authorizations complicate compound selection for global vehicle programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Bushing Technologies Market |
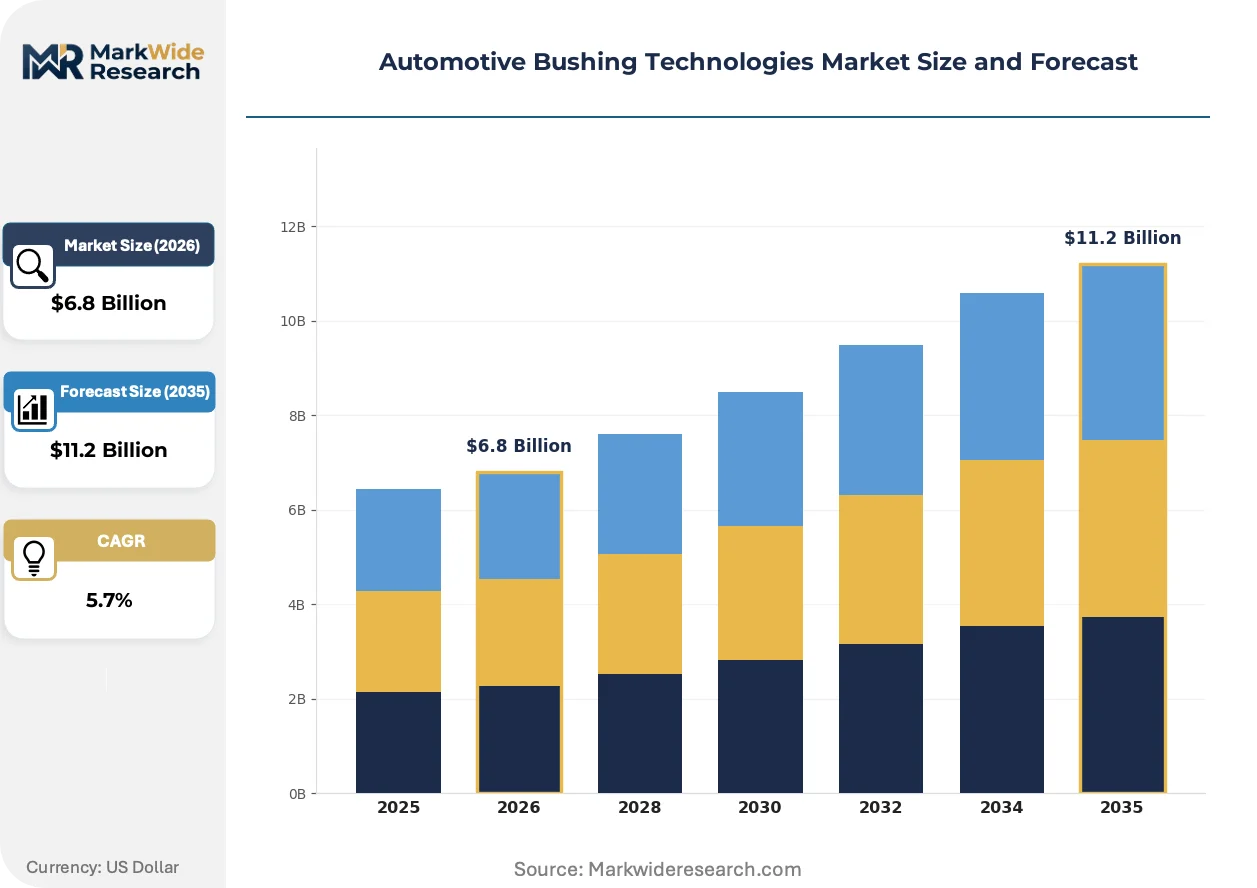
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Bushings, Metal Bushings, Polyurethane Bushings, Composite Bushings Application: Suspension Systems, Steering Systems, Powertrain Components, Chassis Systems End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Natural Rubber, Synthetic Rubber, Plastics, Metals |
| Companies Covered | Continental AG, Vibracoustic GmbH, ZF Friedrichshafen AG, Sumitomo Riko Co. Ltd., Trelleborg AB, Freudenberg Sealing Technologies GmbH & Co. KG, MAHLE GmbH, BOGE Rubber & Plastics, Cooper-Standard Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Bushing Technologies Market Emerging Trajectories
Material science advances and regulatory stringency are converging to reshape bushing performance specifications, supplier capabilities, and buyer procurement criteria across automotive value chains.
Hybrid fiber-reinforced thermoplastic bushings are supplanting conventional steel-rubber assemblies in electric vehicle subframes seeking mass reduction targets. BYD and Tesla platform engineering teams specify these composites for control arm and cradle applications where NVH isolation must coexist with weight minimization. The substitution is compressing incumbent metal-forming capacity while elevating polymer science capabilities among qualified suppliers.
REACH chemical restrictions on aromatic process oils are forcing compounders toward bio-based synthetic elastomers and alternative plasticizer systems. ECHA authorization timelines now determine qualification windows for European OEM sourcing decisions, with non-compliant formulations excluded from new platform bids. Rubber bushing specialists with captive polymer research centers capture specification-setting influence earlier in development cycles.
Buyer consolidation among electric vehicle pure-plays is compressing supplier bases and elevating technical collaboration requirements. Tesla and Rivian procurement teams now mandate joint simulation workflows and shared fatigue databases rather than transactional component supply. This behavioral shift is most pronounced in California and Texas engineering centers where platform development cycles have compressed below traditional OEM timelines.
Automotive Bushing Technologies Market Segmentation
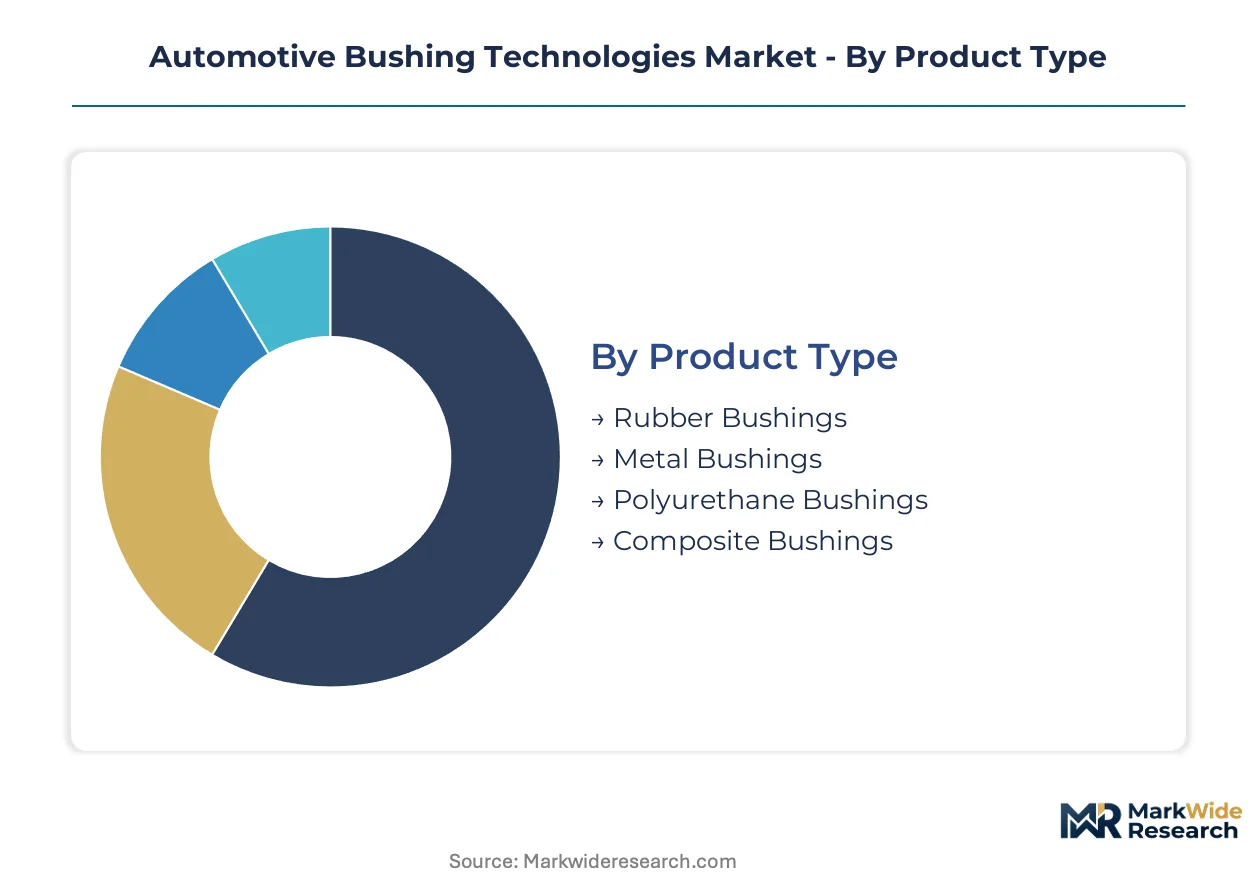
Bushing specification pathways diverge sharply across product categories, with regulatory pressure on NVH performance and chemical composition fragmenting supplier qualification tiers. Material selection and application architecture determine margin structures, contract duration, and technical collaboration intensity with platform engineering teams.
Product Type:
EPA Tier 3 and Euro 7 stringency separates qualified compounders from commodity assemblers across each formulation class.
- Rubber Bushings:Vulcanized natural rubber and SBR compounds bonded to steel sleeves dominate high-volume chassis applications where cost efficiency outweighs performance customization. Demand concentrates in Germany and Japan where tier-1 suppliers maintain captive mixing operations for OEM contracts, though REACH aromatic oil restrictions are forcing costly reformulation cycles.
- Composite Bushings:Hybrid fiber-reinforced thermoplastic constructions displace conventional metals in electric vehicle subframes where mass reduction targets collide with NVH isolation requirements. Tesla and BYD platform specifications for control arm and cradle applications are accelerating supplier qualification timelines for polymer science capabilities.
- Metal Bushings:Sintered bronze and steel sleeve assemblies persist in heavy-duty commercial applications and legacy internal combustion powertrain mounts where load-bearing capacity exceeds elastomer limits.
- Polyurethane Bushings:Castable formulations with tunable Shore hardness concentrate in aftermarket performance channels where chassis tuning enthusiasts pay premiums over OEM specifications.
Established volume favors rubber formulations; emerging adoption favors composite architectures.
Application:
Load profile complexity and multi-axis deflection requirements stratify supplier technical capabilities across vehicle kinematic chains.
- Suspension Systems:Control arm, cradle, and subframe bushings manage wheel motion isolation while maintaining geometric precision under dynamic loading. Electric vehicle platforms generate concentrated demand for lightweight solutions in Stuttgart, Munich, and California engineering centers where unsprung mass reduction targets have tightened.
- Powertrain Components:Engine mounts and transmission bushings face shrinking addressable market as battery-electric architectures eliminate conventional powertrain isolation requirements, though hybrid programs sustain residual demand.
- Steering Systems:Column and rack bushings prioritize torsional stiffness and angular compliance for precision feedback, with specifications tightening under NHTSA federal motor vehicle safety standards for steering integrity.
- Chassis Systems:Structural isolation elements span multiple attachment points where NVH transmission paths converge, requiring system-level simulation capabilities beyond component-level testing.
Suspension applications command the deepest supplier collaboration; powertrain exposure carries electrification risk.
End User:
Procurement behavior and technical integration depth vary dramatically across buyer consolidation levels and platform development autonomy.
- OEMs:Volkswagen, Toyota, and Ford platform engineering teams specify bushing performance targets and validate compound formulations through proprietary durability cycles, retaining direct supplier relationships for strategic chassis programs.
- Tier-1 Suppliers:Continental AG and ZF Friedrichshafen AG aggregate component sourcing across multiple OEM contracts, leveraging volume concentration to justify captive polymer research and acoustic testing capabilities.
- Vehicle Assemblers:Contract manufacturers and electric vehicle pure-plays with compressed development timelines rely on tier-1 integration for specification compliance and logistics coordination.
- Aftermarket Providers:Enthusiast distributors and performance shops source polyurethane formulations with hardness customization, operating outside OEM qualification protocols.
Direct OEM engagement demands simulation capabilities; tier-1 channels reward scale and vertical integration depth.
Material:
Embedded carbon accounting and chemical authorization timelines are reordering compound selection hierarchies across sourcing geographies.
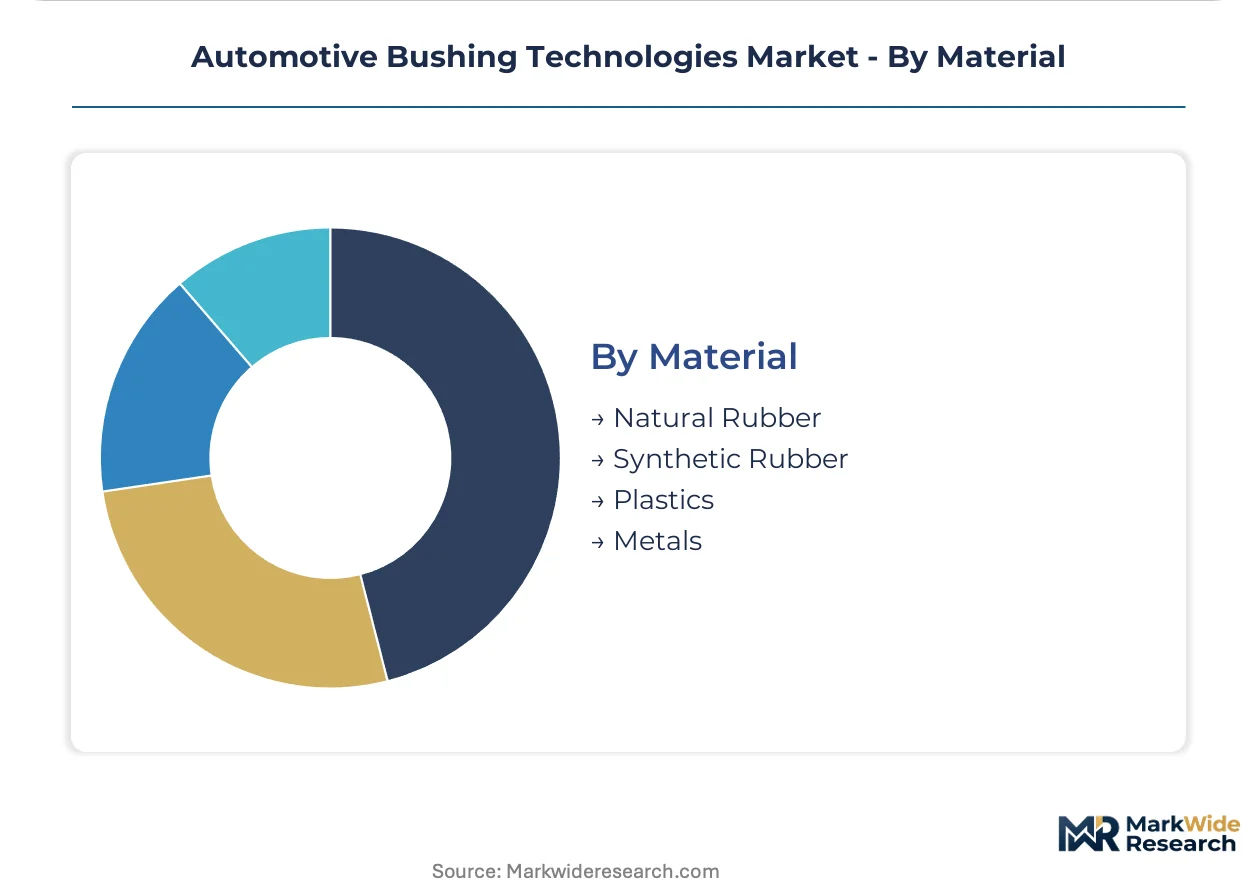
- Natural Rubber:Southeast Asian supply chains face climate-driven harvest variability and price volatility, compressing margins for specialists dependent on spot market sourcing rather than contracted plantation relationships.
- Synthetic Rubber:Bio-based SBR and EPDM formulations gain preferred vendor status under EU Green Deal certification protocols, rewarding early movers with European OEM sourcing decisions.
- Plastics:Fiber-reinforced thermoplastic compounds from BASF and DuPont portfolios enable mass reduction in electric vehicle structures where traditional elastomer density limits performance.
- Metals:Forged steel sleeves and sintered bronze retain load-bearing roles where thermoplastic creep resistance fails, though forging capacity concentration at major tier-1 suppliers creates supply bottlenecks for independent assemblers.
Natural rubber anchors cost-sensitive volume; synthetic bio-based formulations are climbing the fastest on regulatory preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive clusters where captive polymer science capabilities command specification-setting authority, while Southeast Asian rubber sourcing regions face margin compression from harvest volatility and spot market dependency.
United States
EPA Tier 3 emission standards mandate stricter NVH controls that accelerate adoption of advanced polyurethane formulations in chassis systems. NHTSA federal motor vehicle safety standards for suspension integrity tighten qualification pathways for steering and control arm bushings. Detroit and California engineering centers generate concentrated demand for lightweight solutions as Tesla and Rivian compress platform development timelines below traditional OEM cycles.
Germany
EU Green Deal embedded carbon requirements reshape supplier certification demands across Volkswagen and BMW sourcing protocols. ECHA REACH restrictions on aromatic process oils force costly reformulation of SBR compounds for European OEM contracts. Stuttgart and Munich tier-1 supplier ecosystems sustain innovation spillovers in bonded-rubber assembly techniques and acoustic testing capabilities.
China
BYD and Tesla platform engineering teams specify fiber-reinforced thermoplastic bushings for control arm and cradle applications seeking mass reduction. MIIT dual carbon goals and GB standards for automotive component durability accelerate substitution toward bio-based synthetic elastomers. Yangtze River Delta manufacturing clusters concentrate electric vehicle subframe production where polymer science capabilities determine supplier qualification.
Japan
Toyota and Honda platform teams retain direct supplier relationships for strategic chassis programs requiring proprietary durability cycle validation. METI industrial policy supports domestic compound mixing operations against Southeast Asian rubber price volatility. Kanto and Kansai automotive production clusters anchor demand for high-precision suspension bushings with tight geometric tolerance requirements.
India
PLI scheme incentives for electric vehicle production create entry points for bushing suppliers establishing localized compound mixing operations. BIS automotive component standards and DGFT import substitution policies favor domestic manufacturing capacity. Maharashtra and Tamil Nadu automotive corridors concentrate demand as Maruti Suzuki and Tata Motors expand battery-electric platform sourcing.
Automotive Bushing Technologies Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated rubber compounders commanding specification-setting influence while assembly-only specialists compete on contract manufacturing scale. The vendor base stratifies across three tiers: captive polymer science centers at major tier-1 suppliers, independent compounders with acoustic testing differentiation, and regional assemblers dependent on spot market metal sleeve sourcing. Dominant competitive moves include backward integration into forged metal substrates and strategic partnerships for shared fatigue database access.
Among German-based integrated suppliers, Continental AG, Vibracoustic GmbH, and ZF Friedrichshafen AG exemplify archetypes spanning captive mixing operations, acoustic testing capabilities, and upstream control over forged metal sleeves respectively. These three occupy positions where vertical reach into polymer research or bonded-rubber assembly determines margin retention across OEM contract renewals.
| Leading Market Players |
|---|
| Continental AG |
| Vibracoustic GmbH |
| ZF Friedrichshafen AG |
| Sumitomo Riko Co. Ltd. |
| Trelleborg AB |
| Freudenberg Sealing Technologies GmbH & Co. KG |
| MAHLE GmbH |
| BOGE Rubber & Plastics |
| Cooper-Standard Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between tier-1 suppliers and German OEMs lock in compound supply access while dampening price volatility exposure for both parties. These arrangements concentrate pricing power among vertically integrated rubber compounders with captive mixing operations, leaving assembly-only specialists exposed to spot market metal sleeve costs.
Pricing Analysis
The customization-premium spread separates standard rubber bushing formulations from engineered polyurethane and composite solutions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with REACH-compliant bio-based elastomers commanding preferred vendor premiums. Cost compression in commodity rubber tiers is intensifying because of Southeast Asian natural rubber harvest variability. Aftermarket performance channels show the least price sensitivity, while high-volume OEM contracts face relentless procurement pressure.
Supply Chain Analysis
Inventory buffers and extended lead times for forged steel sleeves from Germany and Japan constrain responsiveness for independent assemblers lacking captive forging capacity. Raw material flows draw from Malaysian natural rubber plantations, Chinese synthetic elastomer plants, and European aromatic process oil alternatives. Single-source vulnerability concentrates in bonded-rubber assembly equipment where German and Japanese machinery suppliers dominate. Distribution runs through tier-1 supplier consolidation hubs before reaching OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in multi-axis dynamic simulation expertise and predictive fatigue modeling capabilities is concentrating specification-setting influence among suppliers with captive polymer research centers. This capability gap rewards early investment in joint simulation workflows with OEM platform engineering teams.
For Market Incumbents: Secure backward integration into forged metal substrates to eliminate supply bottlenecks from concentrated steel sleeve forging capacity. Defend margin pools by accelerating bio-based synthetic elastomer certification under EU Green Deal protocols before REACH aromatic oil restrictions tighten further. For New Entrants and Emerging Players: Anchor in India's PLI scheme corridors where electric vehicle production incentives create localized compound mixing opportunities with lower incumbent saturation. Target aftermarket polyurethane performance channels where Shore hardness customization commands pricing premiums and OEM qualification barriers do not apply. For Investors and Strategic Acquirers: Independent compounders with acoustic testing differentiation and established European OEM relationships represent the most defensible acquisition archetype. Long-term viability hinges on bio-based formulation pipelines and shared fatigue database access with electric vehicle pure-plays. Watch for inflection when Tesla or Rivian procurement teams mandate joint simulation workflows as standard contract terms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forged Metal Substrates | Eliminates supply bottlenecks from German and Japanese forging concentration for tier-1 suppliers. |
| Bio-Based Synthetic Elastomer Certification | Secures preferred vendor status under EU Green Deal embedded carbon requirements for European OEMs. |
| Joint Simulation Workflow Partnerships | Meets Tesla and Rivian procurement mandates for shared fatigue databases and predictive modeling capabilities. |
| Localized Compound Mixing Operations | Captures PLI scheme incentives in Maharashtra and Tamil Nadu corridors for India electric vehicle production. |
| Acoustic Testing Capability Expansion | Differentiates polyurethane formulations for premium chassis programs at Stuttgart and Munich engineering centers. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, tier-1 supplier procurement leads, aftermarket distribution managers, and polymer research directors anchored the qualitative base. These primary inputs combined with secondary validation from vehicle production databases, IHS Markit registration data, customs trade flows, and SEC filings from listed automotive suppliers. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Sensitivity analysis around natural rubber price volatility scenarios and electric vehicle platform adoption curves tested forecast robustness across the projection horizon. The analytical framework modeled segmentation across propulsion architecture, vehicle class, material formulation tier, and regional production cluster. CAGRs derived from regression analysis of historical content-per-vehicle trends and OEM sourcing pipeline visibility. Forecast inputs incorporated EPA Tier 3 NVH compliance timelines and ECHA REACH authorization windows.
Material uncertainties — regulatory divergence between EPA durability cycles and EMA chemical authorizations, Southeast Asian rubber harvest disruption events — sit outside the modeled envelope. Forecasts reflect assumptions about electric vehicle platform ramp schedules and bio-based elastomer substitution rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Global Automotive Fifth Wheel Coupling Market
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Automobile AC Condensers Market
Automotive Components
Automotive Transaxle Market
Automotive Components
Automotive Glass Film Market
Automotive Components
Europe Automotive Relay Market
Automotive Components
Electric Vehicle Fluid Lubricants Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Automobile Accessories Market
Automotive Components
Middle East and Africa Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Bearing Market
Automotive Components
GCC Automotive Lubrication Services Market