
 Italy Electro Hydraulic Power Steering Market | 2026-2036
Italy Electro Hydraulic Power Steering Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Electro Hydraulic Power Steering Market Foresight
Light commercial vehicle demand is rebalancing the Italy electro hydraulic power steering landscape as fleet operators prioritize fuel efficiency and load-handling precision. JTEKT Corporation leverages its steering system specialization to serve Italian commercial vehicle producers with column-assisted architectures. Robert Bosch GmbH sustains broad technology leadership across integrated hydraulic-electric modules for passenger and utility platforms. ZF Friedrichshafen AG anchors high-volume supply relationships with Turin-based automotive manufacturers through rack-assisted production lines.
Electro hydraulic power steering combines hydraulic actuation with electronic control units to modulate steering assistance based on vehicle speed, load, and driver input, typically operating at hydraulic pressures of 70-100 bar with motor-driven pumps that displace 5-20 cc per revolution. The system reduces parasitic engine losses versus conventional hydraulic steering while maintaining tactile road feedback. Rack-assisted configurations dominate Italian OEM procurement due to their packaging efficiency in front-wheel-drive platforms and compatibility with compact engine bays. Integrated systems represent the fastest-growing technology segment as manufacturers consolidate ECU, motor, and pump assemblies to reduce assembly complexity. Passenger cars remain the largest vehicle type category, though electric vehicle demand is reshaping supplier development priorities toward steer-by-wire compatible architectures.
Italy's Ministry of Enterprise and Made in Italy oversees automotive component certification under EU type-approval frameworks aligned with UNECE regulations, while REACH compliance governs hydraulic fluid formulations and sealing material chemistry. The EU Green Deal's 55% CO2 reduction target for 2030 forces steering system suppliers to demonstrate lifecycle emissions reductions through lightweight materials and regenerative pump designs. Stakeholders must monitor Italy's transition timeline for Euro 7 emission standards and assess how steer-by-wire interoperability requirements will redefine electro hydraulic system relevance in next-generation vehicle platforms.
Market Dynamics
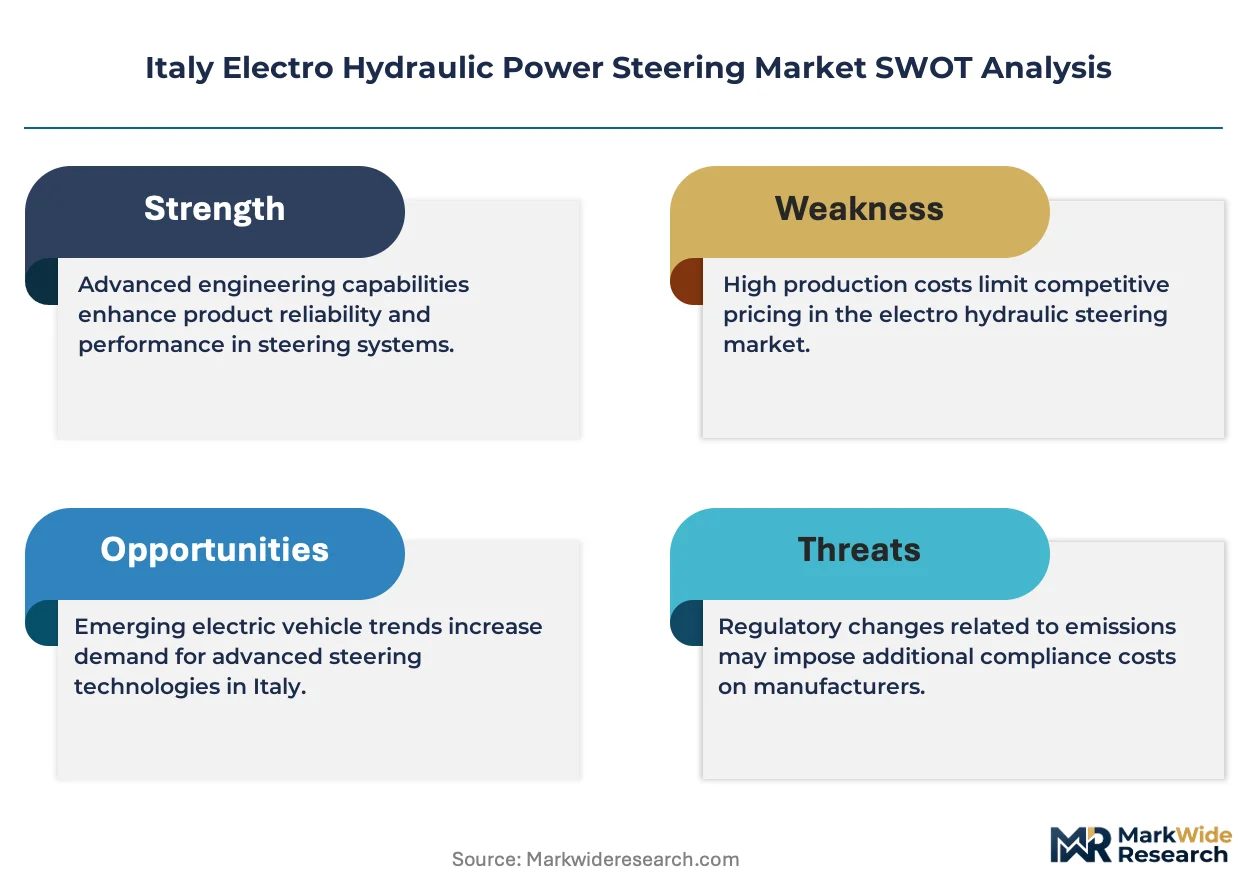
Italy's electro hydraulic power steering sector is being restructured by the collision of EU Green Deal carbon mandates with Turin-Milan OEM procurement consolidation, forcing tier-1 suppliers to reconfigure hydraulic-electric architectures for lighter commercial vehicle platforms.
Growth Catalysts
- EU Green Deal CO2 targets:The 55% reduction mandate for 2030 compels Italian fleet operators to retrofit existing light commercial vehicles with electro hydraulic systems that cut parasitic engine losses by 15-20% versus conventional hydraulic steering.
- Turin-Milan manufacturing corridor concentration:Proximity to Fiat Stellantis and Iveco assembly plants creates dense supplier ecosystems where just-in-time delivery of rack-assisted steering modules reduces logistics costs and warranty response times.
- Electrification-compatible architectures:Steer-by-wire readiness in next-generation electro hydraulic designs allows OEMs to future-proof platforms without complete steering system redesigns during mid-cycle facelifts.
Market Restraints
- Input cost volatility in rare-earth magnet supply:Neodymium price swings for brushless pump motors squeeze margin predictability for Italian component suppliers dependent on Chinese magnet processors.
- Steer-by-wire substitution trajectory:Pure electric steering systems eliminate hydraulic fluid entirely, threatening electro hydraulic relevance in premium passenger EV segments where weight reduction takes priority over road feedback preservation.
- REACH compliance burden on hydraulic fluids:ECHA restrictions on phosphate ester formulations force reformulation cycles that extend type-approval timelines by 8-14 months for Italian suppliers.
Strategic Opportunities
- Southern Italy aftermarket penetration:Campania and Sicily commercial vehicle fleets lag northern regions in electro hydraulic retrofits, creating white space for service network expansion.
- Integrated system consolidation:Convergence of ECU, variable-displacement pump, and torque sensor into single supplier modules reduces OEM assembly line complexity and captures value previously lost to multiple vendors.
- National Recovery and Resilience Plan automotive incentives:Italy's PNRR allocates direct grants for steering system electrification R&D, subsidizing prototype-to-production transitions for domestic suppliers.
Industry Challenges
- Mechatronics engineering talent scarcity:Italian technical universities produce insufficient hydraulic-electric hybrid system specialists, forcing suppliers to recruit from German and Polish competitor pools.
- Euro 7 certification timeline compression:Pending emission standard finalization leaves steering system suppliers with 14-18 month validation windows that conflict with OEM platform launch schedules.
- Legacy hydraulic system interoperability:Aftermarket electro hydraulic retrofits must interface with 1990s-era hydraulic racks in aging commercial fleets, requiring adaptive mounting kits that multiply SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Electro Hydraulic Power Steering Market |
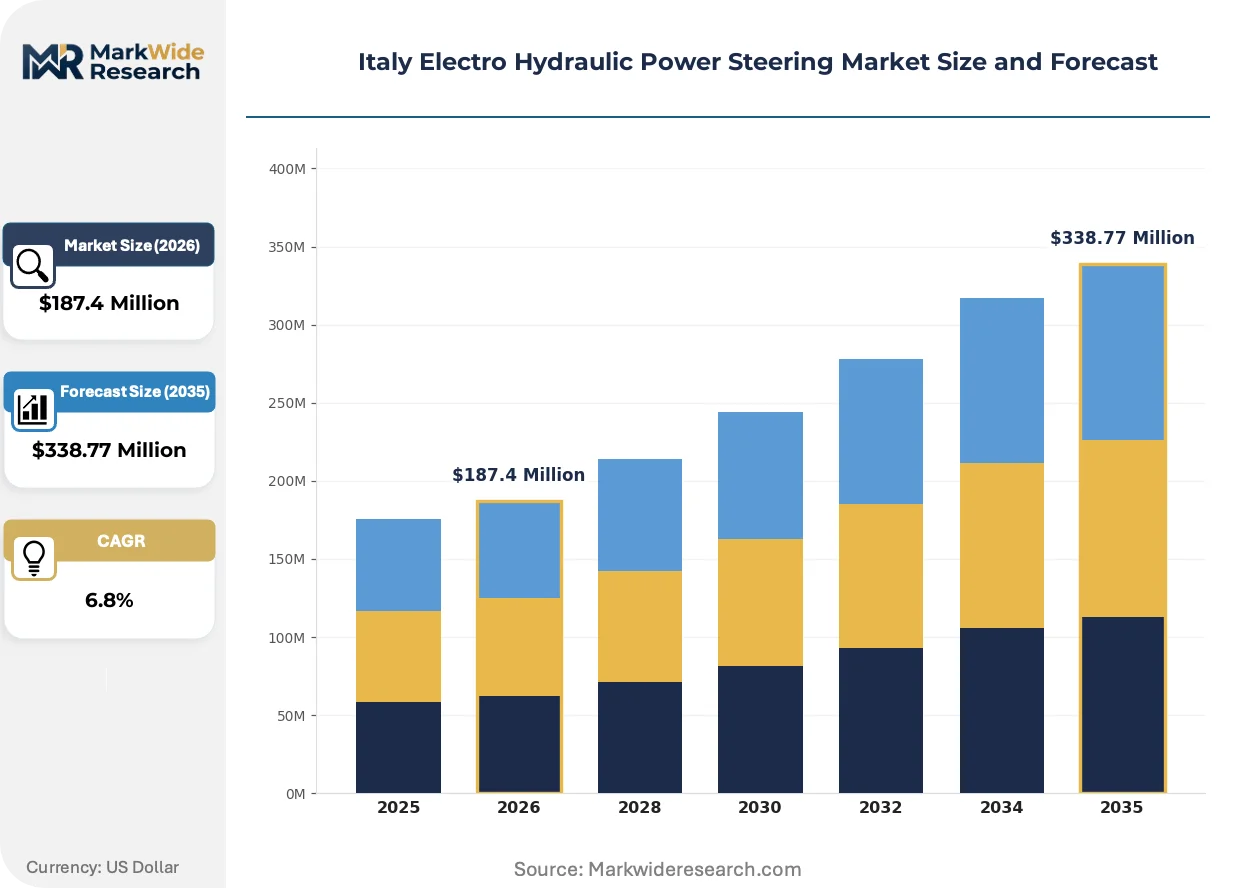
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Column-Assisted, Rack-Assisted, Integrated Systems, Modular Systems End User: OEMs, Aftermarket Providers, Fleet Operators, Automotive Manufacturers Technology: Variable Ratio, Active Steering, Assisted Systems, Direct Control Vehicle Type: Passenger Cars, Commercial Vehicles, Motorcycles, Electric Vehicles |
| Companies Covered | JTEKT Corporation, Nexteer Automotive Group Ltd, Robert Bosch GmbH, ZF Friedrichshafen AG, NSK Ltd, Mando Corporation, Hyundai Mobis, Thyssenkrupp Presta AG, Hitachi Astemo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Electro Hydraulic Power Steering Market Shifts & Advancements
Steering system architecture is being redefined by the tension between preserving hydraulic road feel and eliminating engine-driven parasitic losses, with Italian suppliers caught between OEM demands for modularity and regulatory pressure for full electrification.
Variable-displacement vane pumps with brushless DC motor drives are rewriting efficiency benchmarks in light commercial vehicle applications. Iveco and Fiat Professional have specified these units for 2024-2026 platform refreshes, compressing the addressable market for fixed-displacement legacy pumps to price-sensitive aftermarket segments only.
REACH Annex XVII restrictions on organophosphate hydraulic fluids are forcing Italian formulators to submit alternative chemistries for ECHA authorization. Suppliers using legacy phosphate ester bases face 18-24 month transition timelines, while early movers with polyol ester formulations have secured provisional approvals that lock in OEM supply contracts through 2027.
Commercial fleet procurement departments are consolidating steering system sourcing under total-cost-of-ownership frameworks that weight fuel savings over upfront component price. This behavioral shift favors Turin-based integrated system suppliers who can demonstrate lifecycle carbon reduction certificates, displacing fragmented multi-vendor procurement patterns that dominated Italian commercial vehicle markets through 2020.
Italy Electro Hydraulic Power Steering Market Segmentation
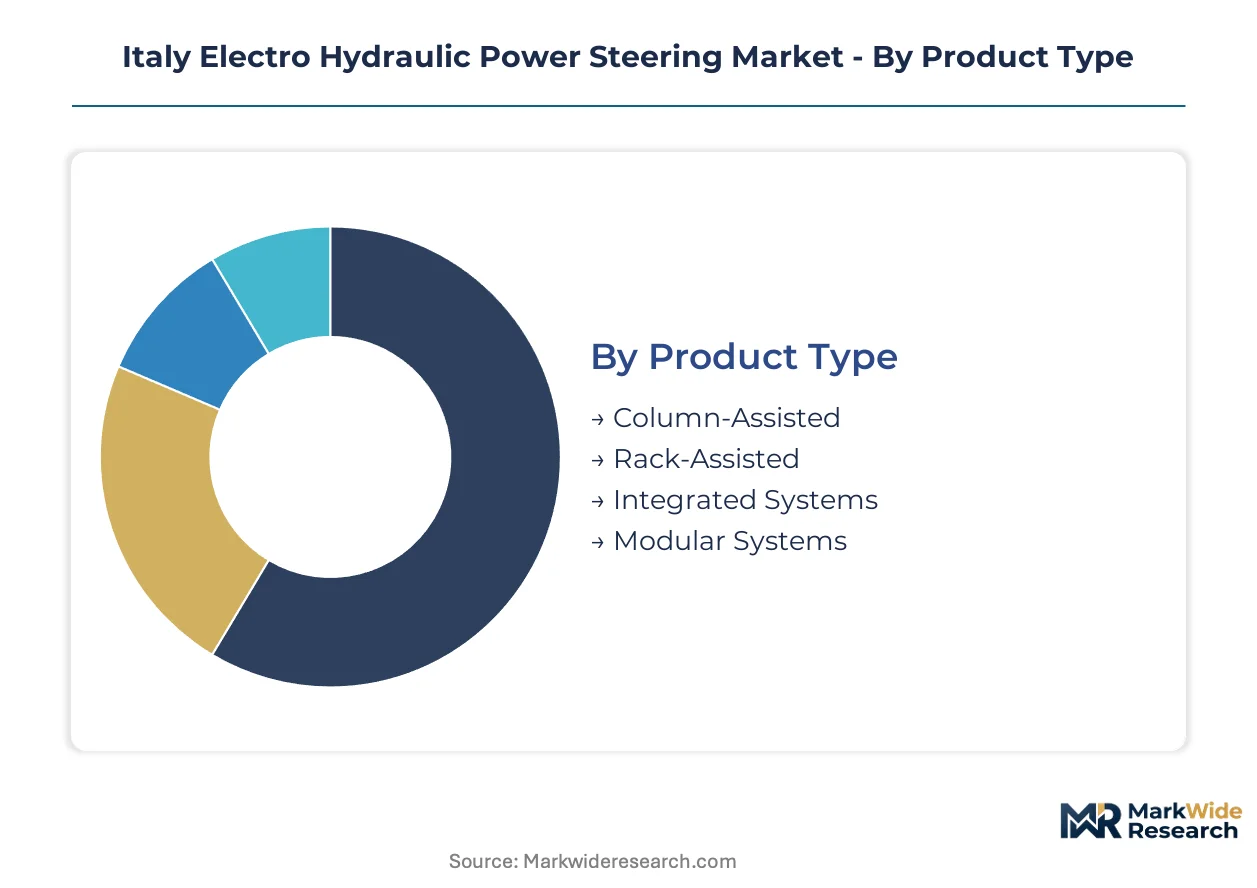
Electro hydraulic power steering procurement in Italy fragments across four distinct dimensions that determine supplier positioning and margin capture. OEMs in Turin and Milan corridors prioritize integrated architectures, while southern fleet operators drive aftermarket retrofit demand with different technical specifications.
Product Type:
Supply concentration among Turin-based tier-1 suppliers has locked in rack-assisted and integrated architectures as the dominant procurement categories for Italian OEM platforms.
- Rack-Assisted:Hydraulic assistance applies directly at the steering rack via motor-driven pump modules, delivering precise load-handling for front-wheel-drive commercial vehicles. Fiat Stellantis procurement in Turin anchors volume demand for this configuration.
- Integrated Systems:Consolidated assemblies fuse ECU, variable-displacement pump, and torque sensing into single supplier modules, reducing OEM assembly complexity. Iveco has specified these units for light commercial vehicle platforms, accelerating supplier R&D investment under Italy's National Recovery and Resilience Plan incentives.
- Column-Assisted:Motor and pump units mount on the steering column, serving compact passenger car platforms where packaging space is constrained.
- Modular Systems:Separable pump, motor, and control components allow aftermarket configurability for aging commercial fleet retrofits in southern Italy.
Rack-Assisted absorbs the bulk of installed capacity; Integrated Systems is expanding most quickly.
End User:
Customer type determines pricing architecture and service intensity, with OEM relationships commanding technical collaboration premiums over transactional aftermarket supply.
- OEMs:Direct supply contracts with Fiat Stellantis and Iveco assembly plants in Turin-Milan corridors require just-in-time delivery frameworks and co-development liability terms.
- Fleet Operators:Light commercial vehicle fleets in Campania and Sicily prioritize total-cost-of-ownership procurement that weights fuel efficiency gains against upfront retrofit investment.
- Aftermarket Providers:Service networks source adaptive mounting kits for 1990s-era hydraulic rack compatibility, multiplying SKU complexity for Italian component distributors.
- Automotive Manufacturers:Niche vehicle producers in northern Italy specify custom electro hydraulic architectures for low-volume specialty platforms.
OEMs command the dominant procurement volume; Fleet Operators are gaining share fastest as carbon reduction mandates restructure commercial vehicle specifications.
Technology:
Control sophistication tiers separate premium integrated architectures from assisted configurations, with variable ratio systems capturing value from precision steering demand.
- Variable Ratio:Electronically modulated rack geometry adjusts steering response based on vehicle speed and load conditions, serving premium passenger car platforms where road feedback preservation matters.
- Active Steering:Superposition gearsets enable independent front wheel angle control, supporting advanced driver assistance compatibility in next-generation vehicle architectures.
- Assisted Systems:Conventional speed-sensitive hydraulic boost without independent angle authority dominates price-sensitive commercial vehicle specifications.
- Direct Control:Steer-by-wire-ready electro hydraulic designs future-proof platforms for full electric steering transition without complete system redesign.
Assisted Systems retains the largest installed base; Variable Ratio is climbing the fastest as OEMs differentiate premium passenger car offerings.
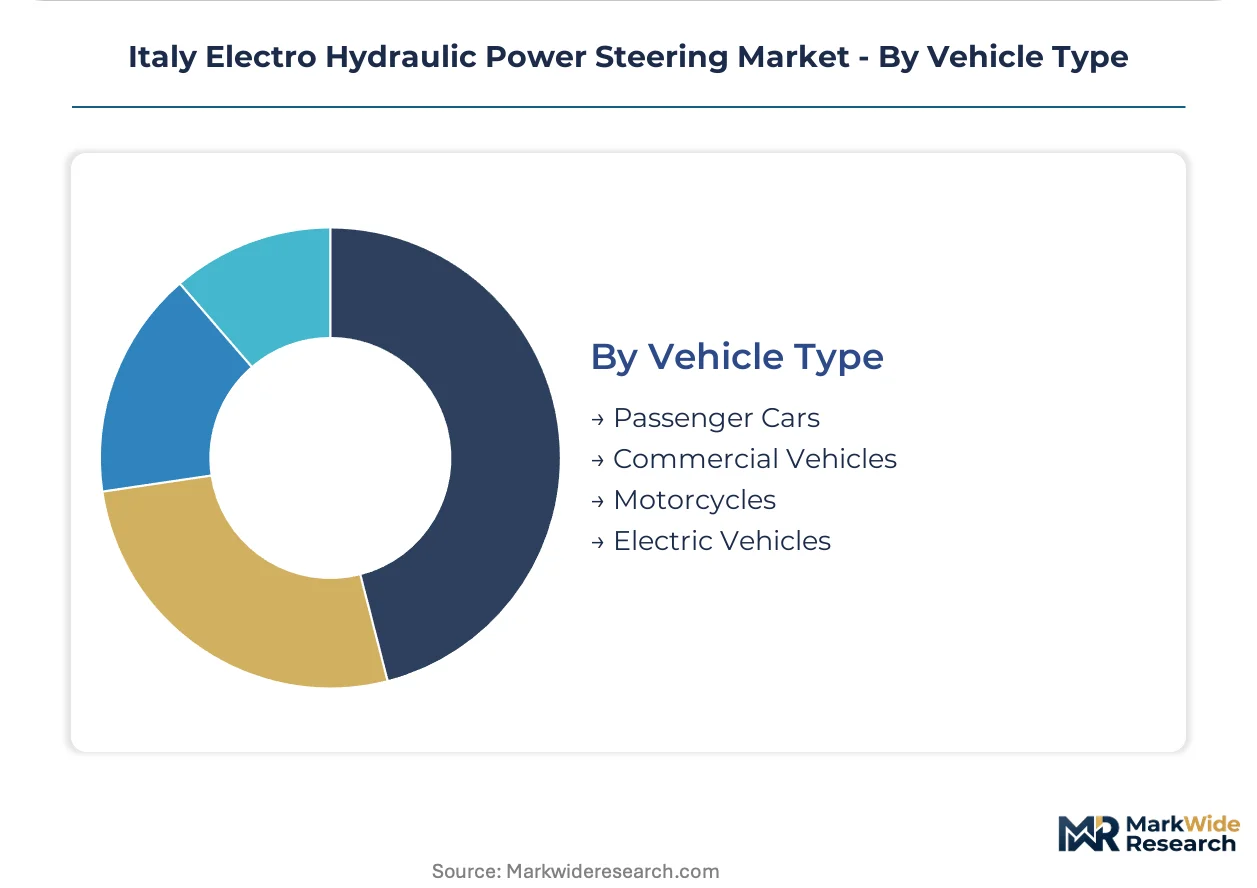
Vehicle Type:
Platform electrification trajectories are segmenting demand, with commercial vehicle specifications diverging from passenger car steer-by-wire preparation priorities.
- Commercial Vehicles:Light commercial fleets expanding across Italy prioritize electro hydraulic retrofits that cut parasitic engine losses by 15-20% versus conventional hydraulic steering.
- Electric Vehicles:Battery electric platforms demand steer-by-wire compatible architectures that eliminate hydraulic fluid entirely in premium segments where weight reduction dominates.
- Passenger Cars:Front-wheel-drive platforms in Turin-Milan production corridors sustain rack-assisted procurement volumes despite electrification pressure.
- Motorcycles:Low-displacement two-wheeler applications represent minimal addressable volume for Italian electro hydraulic suppliers focused on four-wheel platforms.
Passenger Cars maintains the largest production volume; Commercial Vehicles is expanding most quickly under EU Green Deal fleet retrofit incentives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piedmont's Automotive Innovation Hub tax incentives concentrate electro hydraulic power steering R&D investment around Turin, drawing tier-1 suppliers into dense supplier ecosystems serving Fiat Stellantis and Iveco assembly operations.
Lombardy
Milan's financial services sector funds fleet electrification retrofits for commercial vehicle operators prioritizing total-cost-of-ownership frameworks. Italy's National Recovery and Resilience Plan directs automotive innovation grants toward Lombardy-based component engineering centers. Bergamo and Brescia manufacturing clusters host precision machining suppliers producing torque sensor housings for integrated steering modules.
Piedmont
Turin anchors OEM procurement volume through Fiat Stellantis and Iveco platform specifications demanding just-in-time rack-assisted steering delivery. EU Green Deal CO2 mandates accelerate light commercial vehicle fleet retrofits across the region. The Automotive Innovation Hub designation channels tax relief toward electro hydraulic system electrification R&D facilities concentrated in the metropolitan area.
Veneto
Commercial vehicle fleet operators in Verona and Padua procurement districts specify fuel efficiency gains over upfront component pricing. REACH compliance timelines for hydraulic fluid reformulation extend type-approval processes for Veneto-based chemical formulators. Vicenza's industrial automation sector supplies assembly line robotics for steering module production.
Emilia-Romagna
Bologna's automotive engineering universities produce mechatronics specialists recruited by steering system suppliers facing talent scarcity. The region's machine tool builders manufacture variable-displacement pump testing equipment. Modena and Parma niche vehicle producers specify custom electro hydraulic architectures for low-volume specialty platforms.
Campania
Naples commercial vehicle fleets lag northern regions in electro hydraulic adoption, creating aftermarket retrofit expansion opportunities. Southern Italy service networks source adaptive mounting kits for aging hydraulic rack compatibility. Regional procurement departments weight carbon reduction certificates in supplier selection criteria under EU fleet emission mandates.
Italy Electro Hydraulic Power Steering Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated system suppliers capturing premium OEM contracts while modular component vendors serve fragmented aftermarket demand. The vendor base concentrates among multinational tier-1 automotive suppliers with established Turin-Milan corridor relationships. Three archetypes dominate: full-system integrators consolidating ECU-pump-sensor assemblies; hydraulic component specialists supplying variable-displacement pump modules; and rack-assisted architecture providers. Competitive dynamics center on strategic partnerships with OEM platform engineering teams and geographic expansion into southern Italy aftermarket networks.
Among Germany-based diversified automotive suppliers, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify full-system integration archetypes with broad technology portfolios spanning passenger and commercial vehicle platforms. Japan's JTEKT Corporation represents the steering system specialization archetype, leveraging column-assisted architecture expertise. These three companies anchor the competitive structure, with Bosch and ZF occupying positions tied to Turin-based OEM procurement consolidation while JTEKT serves commercial vehicle producers through distinct technical approaches.
| Leading Market Players |
|---|
| JTEKT Corporation |
| Nexteer Automotive Group Ltd |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| NSK Ltd |
| Mando Corporation |
| Hyundai Mobis |
| Thyssenkrupp Presta AG |
| Hitachi Astemo |
| Others |
Supply & Pricing Matrix
Mechatronics engineering talent scarcity in Turin's Automotive Innovation Hub widens pricing-tier spreads between integrated system suppliers commanding technical collaboration premiums and modular component vendors serving price-sensitive aftermarket demand in southern Italy.
Pricing Analysis
Short lead-time premiums for just-in-time rack-assisted steering modules command pricing advantages over spot inventory held by aftermarket distributors. Three-tier pricing structure across premium integrated systems, standard rack-assisted architectures, and economy modular retrofits stratifies by certification grade and OEM co-development liability terms. Cost compression in the economy tier intensifies because REACH-compliant hydraulic fluid reformulation extends type-approval timelines and squeezes margin predictability. Fleet operators in Campania and Sicily exhibit highest price sensitivity, while Fiat Stellantis procurement in Turin demonstrates lowest sensitivity due to total-cost-of-ownership frameworks weighting fuel efficiency gains.
Supply Chain Analysis
Rare-earth magnet supply rests on Chinese neodymium processors, German precision machining clusters, and Japanese torque sensor manufacturers as the dominant input dependencies for Italian electro hydraulic production. Variable-displacement vane pumps, brushless DC motor drives, and REACH-compliant polyol ester hydraulic fluids constitute critical component inputs. Single-source vulnerability in Chinese magnet processing creates structural supply risk for brushless pump motor production. Distribution runs through Turin-Milan corridor just-in-time delivery frameworks for OEM supply, with fragmented aftermarket channels serving southern Italy through adaptive mounting kit distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's electro hydraulic power steering market operates as a cost-of-compliance story where REACH Annex XVII restrictions on hydraulic fluid formulations create a barrier-to-entry moat for suppliers with provisional ECHA approvals locking in OEM contracts.
For Market Incumbents: Anchor high-volume supply relationships through backward integration into variable-displacement pump testing equipment and in-house production of torque sensor housings. Consolidate ECU-pump-sensor assemblies to capture value previously fragmented across multiple vendors, defending against steer-by-wire substitution in premium passenger EV segments by demonstrating lifecycle carbon reduction certificates. For New Entrants and Emerging Players: Launch via aftermarket service network partnerships targeting Campania and Sicily commercial vehicle fleets with adaptive mounting kits for 1990s-era hydraulic rack compatibility. White space exists in southern Italy retrofit demand where procurement departments weight carbon reduction certificates under EU fleet emission mandates, with direct fleet operator sales bypassing fragmented distributor channels offering the most penetrable go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors integrated system suppliers with steer-by-wire-ready architectures and provisional REACH-compliant fluid approvals. Long-term viability hinges on acquisition targets possessing ECHA authorization timelines compressed versus legacy phosphate ester formulators, with Euro 7 certification finalization serving as the critical inflection signal to watch for platform launch schedule alignment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Testing Equipment | In-house production of variable-displacement pump testing equipment reduces reliance on Emilia-Romagna machine tool builders. |
| REACH-Compliant Fluid Reformulation | Polyol ester hydraulic fluid formulations secure provisional ECHA approvals that lock in Fiat Stellantis supply contracts. |
| Southern Italy Aftermarket Expansion | Campania and Sicily service network partnerships capture white space in commercial fleet retrofit demand. |
| Steer-by-Wire Architecture Development | Future-proof electro hydraulic designs enable OEM platform electrification without complete system redesign. |
| Turin-Milan Corridor Capacity Consolidation | Integrated system production co-location with Fiat Stellantis and Iveco assembly plants compresses logistics costs. |
Research Methodology
Document review covered EU type-approval frameworks, ECHA REACH authorization databases, and Italy's National Recovery and Resilience Plan automotive incentive disclosures, complemented by interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and hydraulic fluid formulators. Secondary validation drew from vehicle production databases, customs trade records for rare-earth magnet imports, and SEC filings of multinational steering system suppliers. Bottom-up segment sizing triangulated against top-down market value estimates derived from OEM procurement volume analysis.
Installed base projections and value trajectories across the analysis window reflect segment-specific modeling of rack-assisted, integrated, column-assisted, and modular system architectures. Vehicle type segmentation incorporated commercial vehicle fleet retrofit incentives, passenger car steer-by-wire preparation timelines, and electric vehicle platform electrification trajectories. CAGRs were derived from regression analysis of historical OEM procurement patterns and forward-looking carbon mandate compliance requirements, with input from mechatronics engineering talent supply constraints and Euro 7 certification timeline assumptions.
Pending Euro 7 emission standard finalization, ECHA hydraulic fluid restriction amendments, and steer-by-wire technology cost curves are the dominant revision risks that could compress or extend electro hydraulic system relevance across the projection horizon. Forecasts reflect documented assumptions regarding OEM platform launch schedules and fleet operator procurement behavior shifts. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Transmission Shift Actuator Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Europe Automatic Transmission for Passenger Car Market
Powertrain
Tuning Box Market
Powertrain
Automotive Camless Engine Market
Powertrain
Transmission Oil Filters Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Global Automotive Torque Vectoring Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Automotive Hydrostatic Fan Drive System Market
Powertrain
New Energy Vehicle Scroll Compressor Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Transmission Sales Market