
 Marine Propeller Market | 2026-2036
Marine Propeller Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Propeller Market Intelligence
China's Yangtze River Delta shipyard expansion is rewriting regional supply dynamics for large-diameter propulsion systems. Wärtsilä Corporation leverages integrated powertrain capabilities across cruise and cargo segments. MAN Energy Solutions SE anchors its position through low-speed two-stroke engine-propeller packages. SCHOTTEL GmbH specializes in azimuth thruster configurations for dynamic positioning offshore.
A marine propeller is a hydrodynamic device with typically three to seven blades mounted on a central hub, machined from nickel aluminum bronze or molded from fiber-reinforced polymer composites, designed to convert rotational shaft power into axial thrust for vessel propulsion through water. Controllable pitch propellers dominate commercial vessel applications where fuel efficiency across variable operating profiles commands premium positioning. Composite materials represent the fastest-expanding segment as shipyards seek weight reduction and corrosion resistance for high-speed ferries and naval craft. Fixed pitch configurations retain cost-driven volume in fishing boats and smaller coastal traders where operational simplicity outweighs efficiency optimization.
The International Maritime Organization's Energy Efficiency Existing Ship Index and the EU MRV regulation compel retrofit demand across European-flagged fleets, while China's MEE enforces domestic green shipping corridors. ISO 484 propeller manufacturing tolerances and classification society rules from Lloyd's Register and DNV govern dimensional accuracy and material certification for newbuild acceptance. Stakeholders must weigh capital allocation between electrified propulsion architectures and conventional efficiency upgrades as regulatory thresholds tighten without uniform regional pacing.
Market Dynamics
Composite blade fabrication is collapsing cost premiums for high-performance propulsion, forcing nickel aluminum bronze suppliers to defend position through integrated casting-to-machining service bundles.
Growth Catalysts
- IMO Energy Efficiency Existing Ship Index:European-flagged fleets face mandatory retrofit deadlines, accelerating replacement cycles for fixed-pitch configurations with controllable-pitch alternatives that optimize fuel burn across variable load profiles.
- South Korea's Ulsan-Geoje shipbuilding cluster:Concentrated newbuild activity for LNG carriers and container vessels generates concentrated demand for large-diameter, high-thrust propulsion systems with precision-machined hubs.
- Fiber-reinforced polymer composites:Naval craft and high-speed ferry operators specify carbon-glass hybrid blades for weight reduction and magnetic signature suppression, opening specification battles previously dominated by copper alloys.
Market Restraints
- Nickel price volatility:Aluminum bronze alloy feedstock costs swing with LME nickel contracts, compressing foundry margins on long-delivery propeller castings where price locks expire before shipment.
- Single-source forging capacity:Large-diameter monobloc hubs exceeding six meters depend on a concentrated set of German and Japanese open-die forging presses, creating bottleneck risk for naval and cruise ship programs.
- Classification society rule fragmentation:Lloyd's Register, DNV, and Bureau Veritas maintain divergent fatigue testing protocols for composite blades, forcing manufacturers to maintain parallel certification tracks for international fleets.
Strategic Opportunities
- Brazil's pre-salt offshore expansion:Dynamic positioning vessel demand at Santos Basin creates specification windows for azimuth thruster packages with integrated electric drive, bypassing conventional shaft-line architectures.
- EU Green Deal maritime funding:Retrofit subsidies for battery-hybrid propulsion create pull-through demand for contra-rotating propeller configurations optimized for partial-load electric operation.
- Digital twin convergence with additive repair:Laser powder deposition remanufacturing of cavitation-damaged blade sections, validated against hydrodynamic simulation models, unlocks service revenue from installed base.
Industry Challenges
- Computational fluid dynamics talent scarcity:Propeller designers with coupled CFD-FEA expertise for cavitation and vibration prediction command premium compensation, constraining smaller foundries from specification-grade newbuild work.
- ISO 484 tolerance compliance:Dimensional verification for pitch distribution and section thickness requires coordinated measurement campaigns across machining and finishing stages, extending delivery schedules for complex geometries.
- Legacy shaft-line integration:Controllable-pitch hydraulics must interface with decades-old engine control systems aboard retrofitted vessels, forcing custom actuator engineering on fragmented ship-specific architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Propeller Market |
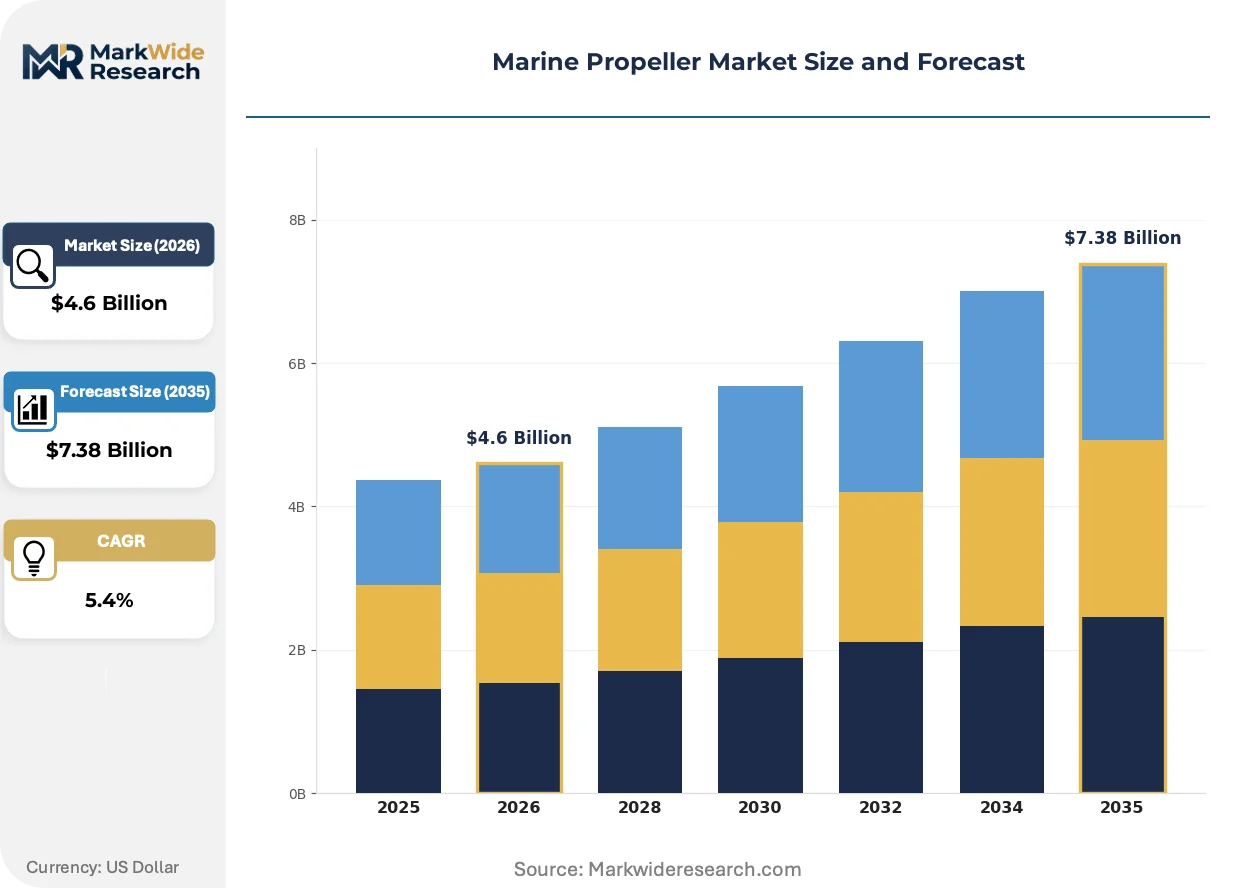
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $7.38 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Pitch, Controllable Pitch, Ducted, Azimuth, Surface Piercing Material: Bronze, Stainless Steel, Aluminum, Composite, Nickel Aluminum Bronze Application: Commercial Vessels, Fishing Boats, Passenger Ferries, Defense Ships, Research Vessels End User: Shipbuilders, Retrofit Suppliers, Offshore Operators, Marine Repair Yards |
| Companies Covered | Wärtsilä Corporation, Rolls-Royce Holdings plc, MAN Energy Solutions SE, Hyundai Heavy Industries Co., Ltd., Brunvoll AS, SCHOTTEL GmbH, Kongsberg Maritime AS, Caterpillar Inc., Nakashima Propeller Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Propeller Market Strategic Shifts & Innovations
Propulsion architecture is bifurcating between electrified podded drives and optimized conventional shafts, with material science and regulatory enforcement determining competitive positioning across vessel categories.
Carbon fiber reinforced polymer blade manufacturing is collapsing the weight-performance tradeoff that previously constrained high-speed naval and ferry applications. Scandinavian and East Asian shipyards now specify hybrid composite-metal hubs for patrol craft and passenger vessels where acceleration and fuel efficiency compete. The technology is collapsing order thresholds for copper alloy suppliers, who must now bundle hydrodynamic design services to defend specification slots.
The EU MRV regulation and China's MEE enforcement are tightening emissions verification requirements for existing vessels, creating documented retrofit obligations. Shipowners must now install fuel monitoring and propulsion efficiency sensors to demonstrate compliance, generating hardware demand beyond the propeller itself. European short-sea shipping and China's Yangtze River inland fleet face the most immediate compliance deadlines, driving 2024-2025 procurement concentration.
Naval architects are unbundling propulsion system procurement from vessel construction contracts, creating direct specification relationships between end-users and component suppliers. Cruise lines and container operators now retain hydrodynamic consultants to validate propeller designs independently from shipyard recommendations. This pattern is most pronounced in Germany's Hamburg and Norway's Oslo maritime clusters, where owner-engineering capabilities have deepened over two decades of specialized vessel development.
Marine Propeller Market Segmentation
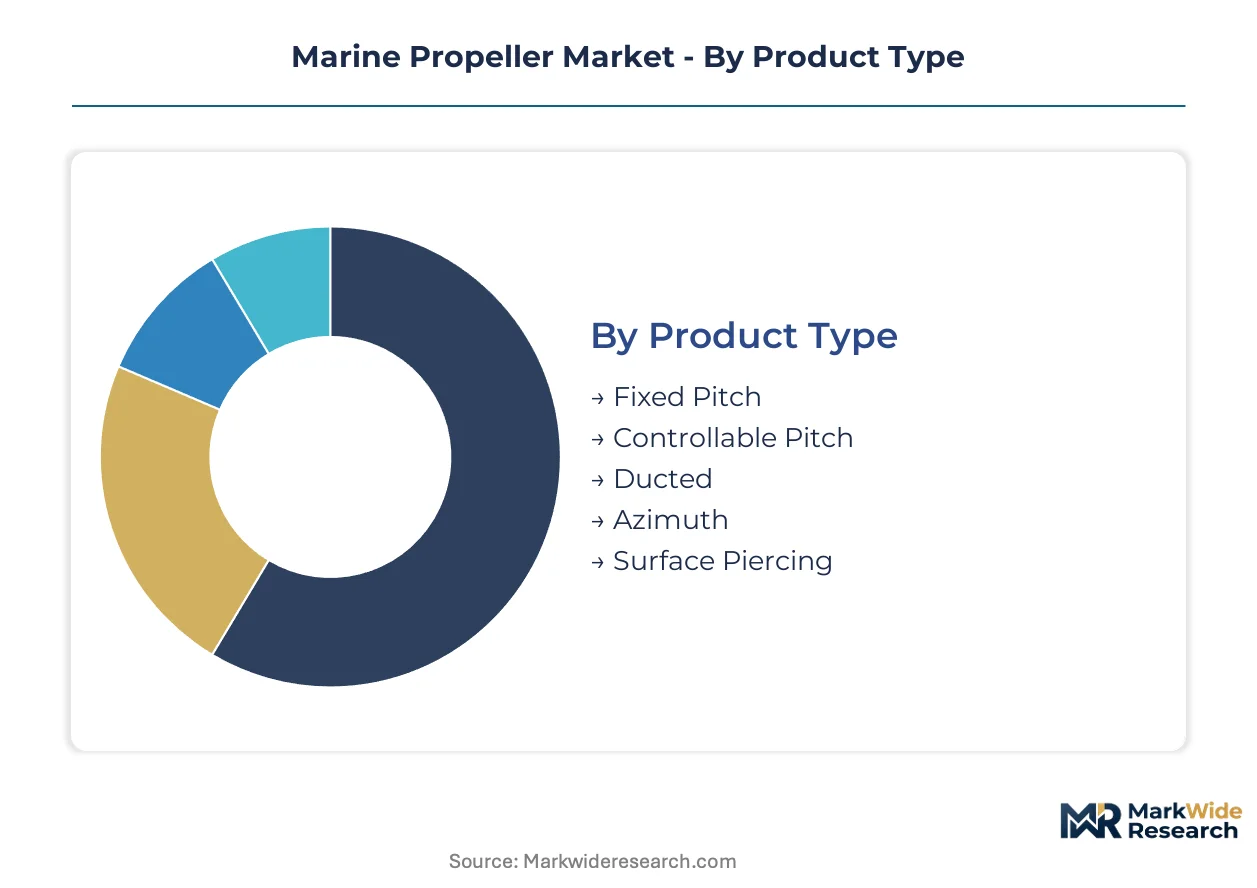
Marine propeller segmentation reveals divergent service intensity across product architectures. Controllable-pitch systems demand continuous hydraulic maintenance, while fixed-pitch configurations concentrate replacement revenue in cyclical dry-dock intervals.
Product Type:
After-sales-service intensity varies dramatically across propulsion architectures, with hydraulically actuated systems generating recurring maintenance contracts and fixed geometries relying on episodic replacement cycles.
- Fixed Pitch:Cast monobloc construction from nickel aluminum bronze dominates fishing fleets and coastal traders where operational simplicity outweighs efficiency optimization. South Korea's Ulsan-Geoje cluster sources these for bulk carrier newbuilds where capital constraints limit specification upgrades.
- Controllable Pitch:Hub-mounted hydraulic mechanisms enable real-time blade angle adjustment for fuel optimization across variable load profiles. Cruise operators and container lines specify these for IMO Energy Efficiency Existing Ship Index compliance, creating concentrated demand for OEM service networks at Rotterdam, Singapore, and Shanghai.
- Ducted:Shrouded configurations improve thrust efficiency in bollard-pull and towing applications. Harbor tugs and offshore supply vessels at Brazil's Santos Basin specify these for dynamic positioning precision.
- Azimuth:360-degree steerable thrusters eliminate rudder requirements and enable vessel maneuvering without forward motion. Offshore construction vessels and icebreakers depend on these for station-keeping in harsh environments.
- Surface Piercing:Partially submerged operation reduces drag in high-speed applications. Naval patrol craft and luxury yacht builders specify these for planing hull configurations where cavitation resistance commands premium engineering.
Controllable Pitch holds the largest share; momentum sits with Azimuth as offshore electrification accelerates.
Material:
Cost tier stratification separates commodity alloys from engineered composites, with procurement patterns diverging between price-sensitive volume buyers and performance-driven specification engineers.
- Bronze:Traditional manganese bronze alloys serve smaller craft and inland waterway vessels where corrosion resistance requirements remain moderate. European short-sea shipping fleets specify these for cost-driven replacement cycles.
- Stainless Steel:Martensitic grades offer cavitation erosion resistance for high-speed ferries operating in shallow, sediment-laden waters. Scandinavian shipyards favor these for archipelago routes where blade damage frequency elevates lifecycle costs.
- Aluminum:Cast alloys dominate outboard motor propellers and small commercial craft where weight reduction justifies reduced durability. Recreational boating distributors in Florida and the Mediterranean basin stock these for seasonal replacement demand.
- Composite:Carbon-glass hybrid laminates enable weight reduction and magnetic signature suppression for naval mine countermeasures and high-speed patrol craft. Fiber-reinforced polymer fabrication is expanding most quickly as shipyards seek corrosion immunity and acoustic stealth.
- Nickel Aluminum Bronze:The maritime industry standard for large-diameter propellers combines strength, corrosion resistance, and anti-fouling properties. Foundries in Germany, Japan, and South Korea cast these for naval and commercial newbuild programs requiring classification society certification.
Nickel Aluminum Bronze commands the dominant revenue position; Composite gains share fastest as defense procurement prioritizes signature management.
Application:
Volume concentration tracks fleet renewal cycles, with merchant shipping and naval procurement operating on distinct budgetary calendars and specification standards.
- Commercial Vessels:Bulk carriers, tankers, and container ships specify large-diameter, slow-turning propellers optimized for continuous operation at design speed. China's Yangtze River Delta shipyards concentrate output for this segment under compressed delivery schedules.
- Fishing Boats:Trawlers and purse seiners demand robust, damage-tolerant propellers for debris-laden coastal waters. Spanish and Portuguese fleets in the North Atlantic drive seasonal replacement demand.
- Passenger Ferries:High-speed craft require lightweight, cavitation-resistant blade designs for frequent acceleration cycles. Japan's domestic ferry operators and Greece's island services specify these for fuel efficiency under stop-start operational profiles.
- Defense Ships:Naval specifications prioritize acoustic quieting, shock resistance, and magnetic signature control. Frigate and destroyer programs in the United Kingdom, France, and Australia generate demand for precision-machined, classified-grade propulsion systems.
- Research Vessels:Oceanographic and polar expedition craft demand ice-class rated propellers with reinforced blade sections. Norwegian and German scientific fleets specify these for year-round Arctic access.
Commercial Vessels generate the largest order volume; Defense Ships show the steepest specification escalation as stealth requirements tighten.
End User:
Customer type determines procurement channel structure, with shipbuilders integrating propulsion into newbuild contracts and repair yards capturing fragmented aftermarket demand.
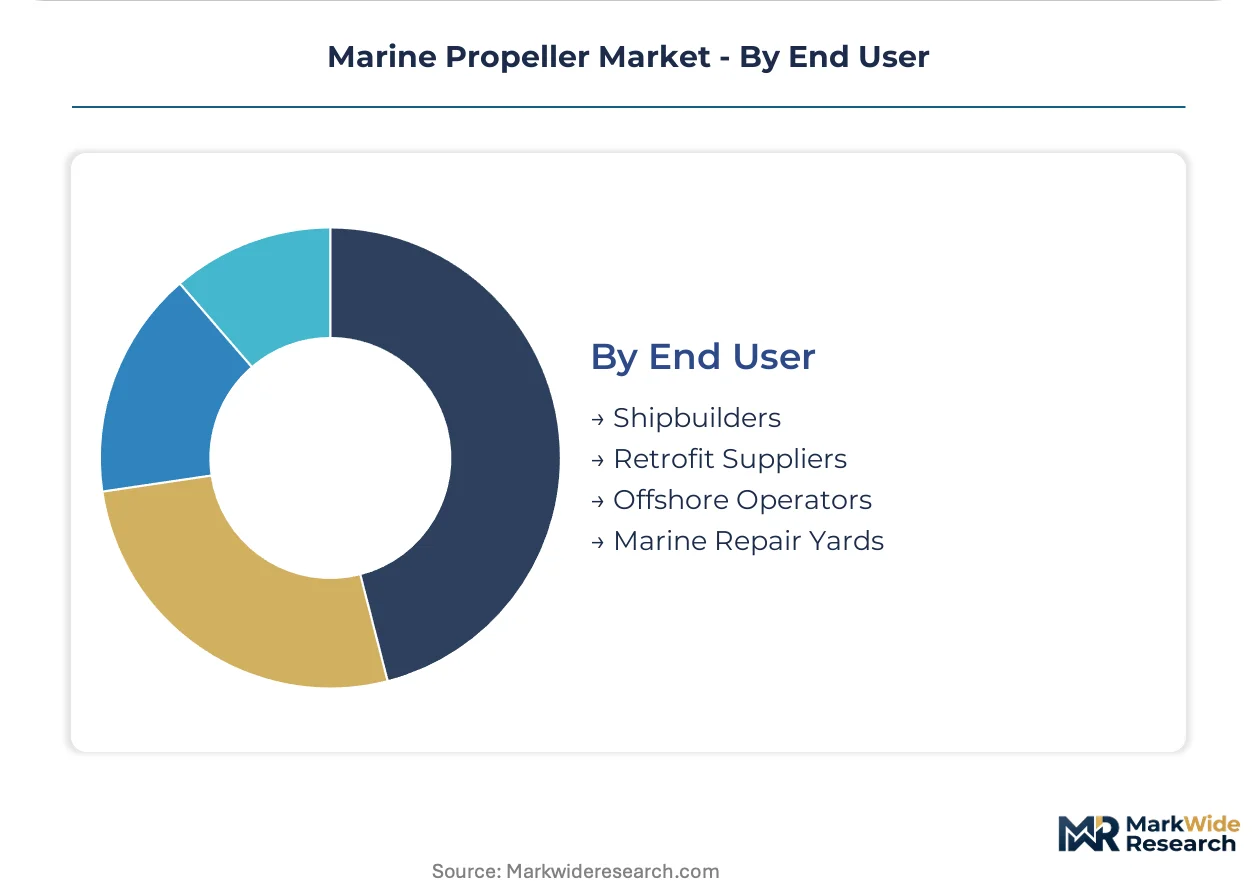
- Shipbuilders:Hyundai Heavy Industries, Samsung Heavy Industries, and China's state-owned yards specify propellers during vessel construction, leveraging volume purchasing power for direct OEM relationships. Newbuild procurement concentrates in South Korea's Ulsan-Geoje corridor and China's Jiangsu province.
- Retrofit Suppliers:Specialist engineering firms source controllable-pitch conversions for IMO compliance deadlines. European short-sea operators contract these services at Hamburg, Rotterdam, and Antwerp ahead of regulatory enforcement.
- Offshore Operators:Drillship and FPSO contractors demand azimuth thruster packages with integrated dynamic positioning. Brazil's pre-salt development and Norway's North Sea decommissioning programs drive specification activity.
- Marine Repair Yards:Dry-dock facilities perform blade reconditioning, pitch adjustment, and emergency replacement for operational vessels. Singapore's Tuas yard cluster and Dubai's Jebel Ali facility capture traffic on major shipping lanes.
Shipbuilders dominate newbuild value; Retrofit Suppliers expand fastest as regulatory deadlines compress replacement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea concentrates newbuild procurement for large-diameter propulsion systems, while European operators drive retrofit demand under emissions enforcement. China's shipyard expansion and Brazil's offshore development create divergent specification requirements across vessel categories.
China
The Yangtze River Delta shipyard cluster generates concentrated demand for bulk carrier and container vessel propulsion systems under compressed delivery schedules. The MEE enforces domestic green shipping corridors through emissions verification protocols. Jiangsu province foundries supply nickel aluminum bronze castings for both domestic fleets and export contracts.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries anchor global newbuild output for LNG carriers requiring precision-machined, high-thrust propellers. The government supports maritime competitiveness through targeted shipyard financing. The Ulsan-Geoje corridor concentrates foundry and machining capacity for naval and commercial programs.
Germany
Specialist engineering firms supply controllable-pitch systems and azimuth thrusters for European retrofit compliance deadlines. The KBA oversees maritime equipment certification alongside classification society protocols. Hamburg's maritime cluster integrates hydrodynamic design services with propulsion manufacturing for cruise and cargo segments.
Brazil
Pre-salt offshore expansion at Santos Basin creates specification windows for dynamic positioning vessels with integrated electric drive architectures. ANVISA regulates occupational safety equipment aboard offshore platforms. Local content requirements shape procurement patterns for drillship and FPSO propulsion packages.
Japan
Domestic ferry operators specify lightweight, cavitation-resistant blade designs for archipelago routes with frequent acceleration cycles. METI coordinates maritime technology development through national shipbuilding programs. Osaka and Nagoya industrial zones maintain precision machining capabilities for naval and commercial propeller production.
Marine Propeller Market Key Industry Players
Capability concentration sits with integrated powertrain specialists; scale advantage sits with diversified heavy engineering conglomerates. The market structures around three tiers: full-system integrators owning engine-propeller packages, component specialists focused on hydrodynamic design, and shipyard-captive foundries serving captive demand. Strategic moves center on composite material certification and service network expansion for retrofit compliance deadlines.
Among European-headquartered system integrators, Wärtsilä Corporation and MAN Energy Solutions SE exemplify the full-propulsion-package archetype, bundling engine and propeller specification. SCHOTTEL GmbH occupies a position within the azimuth thruster specialization tier. These entities represent divergent competitive vectors: integrated powertrain ownership versus thruster configuration expertise.
| Leading Market Players |
|---|
| Wärtsilä Corporation |
| Rolls-Royce Holdings plc |
| MAN Energy Solutions SE |
| Hyundai Heavy Industries Co., Ltd. |
| Brunvoll AS |
| SCHOTTEL GmbH |
| Kongsberg Maritime AS |
| Caterpillar Inc. |
| Nakashima Propeller Co., Ltd. |
| Others |
Cost & Logistics Intelligence
German and Japanese open-die forging presses for monobloc hubs exceeding six meters anchor upstream scarcity, concentrating margin capture with foundries that bundle precision machining with casting services. Nickel price volatility on LME contracts feeds directly into aluminum bronze alloy feedstock costs, compressing foundry margins where long-delivery castings outlast price locks.
Pricing Analysis
Long-term offtake contracts dominate naval and cruise ship programs where single-source forging capacity creates allocation scarcity. Pricing stratifies across classification-grade certification, composite material specification, and integrated hydrodynamic design service bundling. Cost compression in nickel aluminum bronze tier is intensifying because composite blade fabrication is collapsing performance premiums. Fishing fleets and coastal traders exhibit highest price sensitivity; naval procurement shows lowest sensitivity due to signature management requirements.
Supply Chain Analysis
Export control regimes on carbon fiber prepreg and advanced resin systems limit composite blade technology flows to naval contractors. Supply concentration rests in Germany, Japan, and South Korea for large-diameter casting and forging; China dominates fiber-reinforced polymer raw material production. Feedstock draws from LME nickel contracts, copper cathode, and carbon-glass hybrid laminates. Single-source vulnerability at German and Japanese forging presses creates bottleneck risk. Distribution runs through shipbuilder direct procurement for newbuilds and specialist retrofit engineering firms for compliance-driven replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite blade certification and IMO emissions enforcement are accelerating a material transition that restructures competitive advantage around hydrodynamic design ownership rather than foundry scale.
For Market Incumbents: Harden integrated service bundles by anchoring casting-to-machining capabilities with captive composite fabrication lines. Defend specification slots against carbon-glass hybrid entrants by deepening classification society relationships for parallel certification tracks. Priority lever: ISO 484 tolerance compliance as a service differentiator for complex geometries. For New Entrants and Emerging Players: Retrofit engineering firms in Hamburg, Rotterdam, and Antwerp ahead of EU MRV enforcement deadlines represent the most penetrable entry point. Brazil's pre-salt dynamic positioning vessel demand and China's Yangtze River green shipping corridor compliance create specification windows bypassing incumbent shipbuilder relationships. Go-to-market angle: laser powder deposition remanufacturing services validated against hydrodynamic digital twins. For Investors and Strategic Acquirers: Capital is best deployed toward hydrodynamic design boutiques with coupled CFD-FEA expertise and established classification society certification pathways. Long-term viability favors entities controlling composite material qualification protocols rather than commodity foundry capacity. Signal to watch: naval procurement prioritization of magnetic signature suppression specifications over traditional nickel aluminum bronze performance metrics.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Certification Investment | DNV and Lloyd's Register parallel qualification unlocks naval and high-speed ferry specification slots. |
| Integrated Powertrain Packaging | Wärtsilä and MAN Energy Solutions anchor market position through engine-propeller bundling for LNG carriers. |
| Service Network Expansion | OEM service presence at Rotterdam, Singapore, and Shanghai captures controllable-pitch maintenance contracts. |
| Digital Twin Convergence | Laser deposition remanufacturing validated against CFD models unlocks installed base service revenue. |
| Azimuth Thruster Specialization | SCHOTTEL GmbH configuration expertise targets Brazil pre-salt and Norway North Sea decommissioning demand. |
Research Approach
Cross-validation between primary interviews with propeller design engineers, foundry operations managers, naval procurement officers, and shipyard technical directors anchors the qualitative findings. Secondary validation draws from Lloyd's Register classification databases, DNV technical reports, SEC filings of listed marine engineering conglomerates, and IMO regulatory enforcement documentation. Bottom-up vessel fleet analysis triangulates against top-down shipyard output data.
Calibration against historical replacement cycles and regulatory deadline clustering shapes the projection framework across the analysis window. Segmentation dimensions include propeller architecture, material grade tier, vessel application category, and end-user procurement channel. CAGRs derive from shipyard orderbook analysis and retrofit obligation tracking under IMO EEXI and EU MRV enforcement. Industry-specific inputs encompass nickel price volatility patterns and composite blade qualification timeline data.
Macroeconomic conditions sit as an overlay; deviation in LME nickel contract pricing and shipyard financing availability would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement pacing and classification society rule convergence. Material shifts in naval procurement prioritization toward acoustic signature metrics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Ship Heat Exchanger Market
Marine
Marine Electronics Market
Marine
Azimuth Thrusters Market
Marine
Pneumatic Marine Fender Market
Marine
Buoys and Beacon Market
Marine
Marine Navigation System Market
Marine
Sailboat Market
Marine
Japan Marine Composites Market
Marine
Marine Strip Market
Marine
Hydrogen Ships Market
Marine
Marine Chronometers Market
Marine
Boat Ladder Market
Marine
Marine Shackle Market
Marine
Trim Tabs Market
Marine
Marine Beacon Market
Marine
Marine Fender Market