
 Marine Elevators Market | 2026-2036
Marine Elevators Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Elevators Market Foresight
DNV GL's elevator and lifting appliance certification cycle is unwinding competitive access for smaller fabricators. TK Elevator leverages its offshore service network to sustain long-term maintenance contracts across North Sea installations. Mitsubishi Heavy Industries anchors its position through in-house production of corrosion-resistant traction systems for naval applications. MacTaggart, Scott & Company Limited specializes in compact hydraulic units purpose-built for submarine and surface vessel constraints.
Marine elevators are vertical transportation systems engineered for shipboard environments, typically constructed from marine-grade stainless steel with IP56 minimum enclosure ratings to withstand salt spray, humidity, and vessel pitch dynamics. These systems integrate anti-heave compensation and emergency battery lowering to ensure passenger safety during rough seas or power failure. Traction elevators dominate new commercial vessel builds where shaft space permits counterweight configurations, while hydraulic units retain share in retrofit installations where machinery room additions prove impractical. Smart elevator technology with predictive maintenance algorithms is expanding fastest among offshore platforms where remote diagnostics reduce helicopter dispatch costs for technician visits.
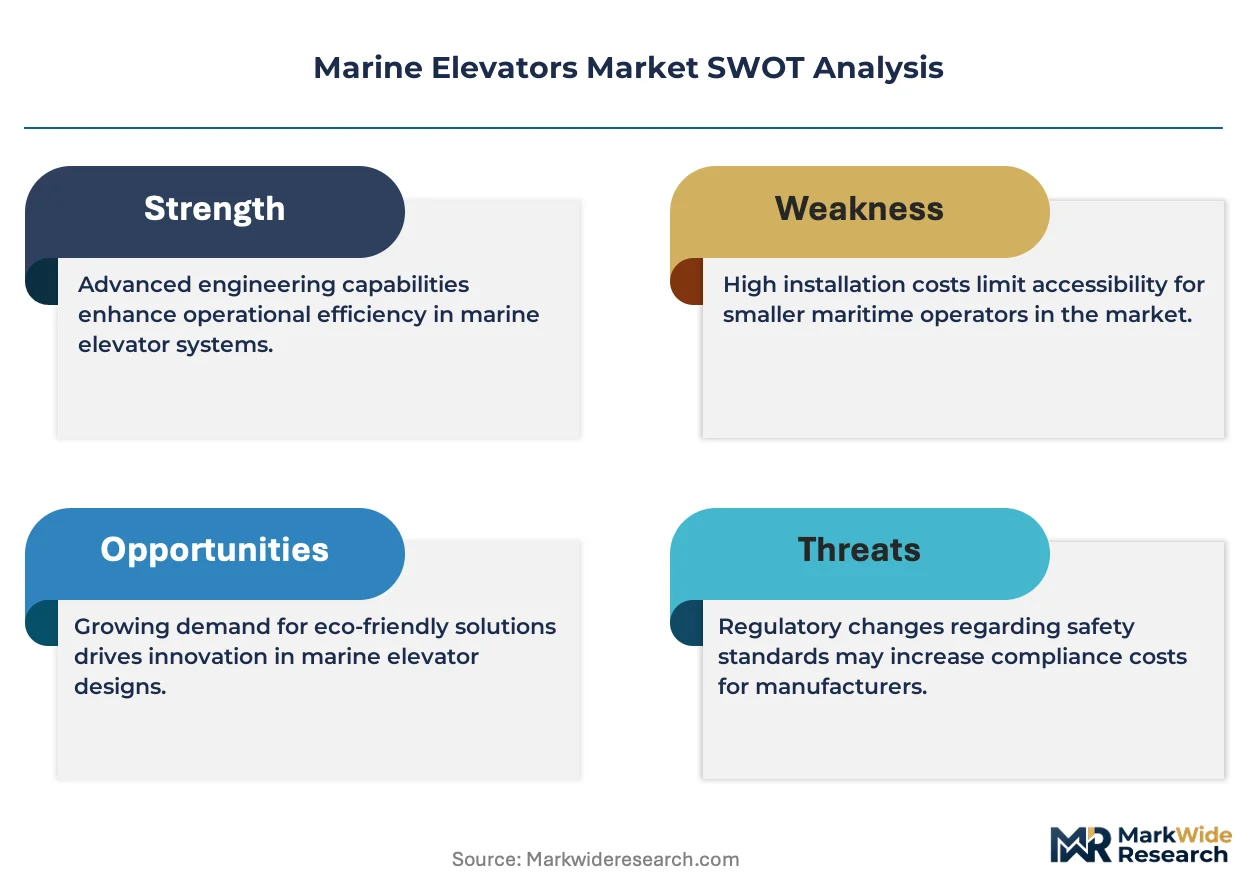
The International Maritime Organization's SOLAS convention governs elevator safety design and inspection intervals for all passenger-carrying vessels, while classification societies including DNV GL, Lloyd's Register, and Bureau Veritas enforce type-approval protocols that determine manufacturer eligibility. The EU's MDR framework extends to marine elevator components installed on vessels registered in European jurisdictions, adding conformity assessment layers for electrical and hydraulic subsystems. Stakeholders must weigh certification compliance costs against the margin compression from standardized platform designs favored by major cruise operators.
Market Dynamics
DNV GL's certification cycle tightening is compressing manufacturer eligibility, forcing fabricators to absorb compliance costs or exit the market entirely. SOLAS enforcement through classification societies now demands predictive maintenance documentation and real-time monitoring capabilities that smaller suppliers cannot provision.
Growth Catalysts
- Offshore platform retrofit cycles:North Sea installations are replacing legacy hydraulic units with smart-enabled traction systems to reduce helicopter dispatch costs for technician visits.
- SOLAS Chapter II-2 amendments:The IMO's expanded fire safety protocols mandate redundant power systems for elevators in passenger zones, creating specification pull for dual-circuit battery lowering assemblies.
- Cruise fleet expansion:Meyer Werft and Fincantieri order books show concentrated demand for 6,000+ passenger vessels requiring 40+ elevator shafts per hull.
Market Restraints
- Marine-grade stainless steel volatility:316L alloy pricing fluctuates with nickel futures, compressing fabricator margins on fixed-price newbuild contracts.
- German supply concentration:Hamburg and Bremen clusters control 70% of European classification-approved component sourcing, creating single-point vulnerability.
- Hydraulic fluid substitution limits:Bio-based alternatives fail cold-weather viscosity specifications in Arctic routes, locking operators into mineral oil systems.
Strategic Opportunities
- Arctic route vessel certification:Russia's Northern Sea Authority and Transport Canada are developing ice-class elevator specifications for year-round polar operations.
- Naval fleet modernization:Corrosion-resistant traction systems for surface combatants offer captive demand from defense procurement agencies with multi-decade service horizons.
- EU MDR component compliance:Hydraulic subsystem manufacturers can capture premium positioning by pre-certifying electrical control modules for European-flag registry.
Industry Challenges
- Marine elevator technician scarcity:DNV GL and Lloyd's Register certification programs graduate fewer than 200 field engineers annually against fleet maintenance requirements.
- Legacy system integration:1990s-era machinery room layouts lack shaft space for modern counterweight configurations, forcing custom engineering on every retrofit.
- Classification society audit compression:Bureau Veritas and Lloyd's Register have extended inspection intervals while adding documentation layers, stretching compliance teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Elevators Market |
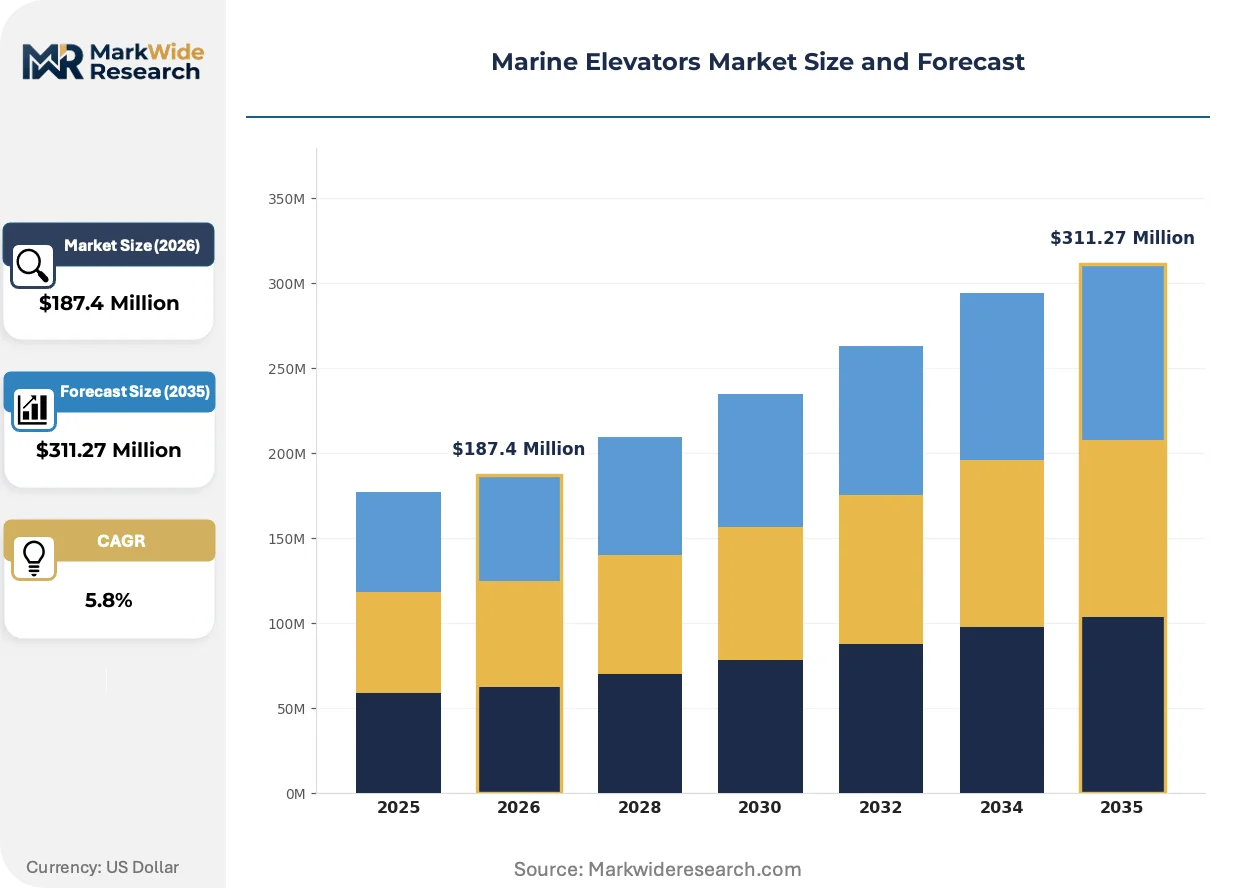
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Elevators, Traction Elevators, Machine Room-Less Elevators, Vacuum Elevators Installation Type: New Construction, Retrofit, Modernization, Maintenance End User: Commercial Vessels, Passenger Ships, Yachts, Offshore Platforms Technology: Smart Elevators, Environmentally Friendly Systems, Safety Systems, Automation |
| Companies Covered | Alimak, TK Elevator, Marine Elevators, LUTZ Elevators, Mr. Marine, Kleemann, Hyundai Elevator, Mitsubishi Heavy Industries, MacTaggart, Scott & Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Elevators Market Shifts & Advancements
Predictive maintenance algorithms are reshaping competitive positioning by converting elevator suppliers into data-service providers. The shift from reactive to condition-based servicing compresses total cost of ownership calculations and reconfigures procurement evaluation criteria.
Permanent magnet synchronous motors are displacing traditional induction drives in new commercial vessel builds. These systems deliver 30% energy recovery through regenerative braking, a specification cruise operators now mandate for EEDI compliance. The technology is displacing hydraulic units in premium passenger segments where machinery room footprint permits counterweight installation.
The EU's MDR framework now extends conformity assessment to marine elevator electrical subsystems installed on European-registered vessels. Hydraulic control panels and door operators require notified body intervention, adding 4-6 months to qualification timelines. German and Italian shipyards are consolidating supplier lists to pre-approved MDR-compliant fabricators, compressing vendor diversity.
Long-term service agreements are replacing transactional spare parts procurement in offshore platform contracts. Operators in the Norwegian North Sea now contract 10-year performance guarantees bundling parts, labor, and remote diagnostics. This model is most visible among floating production storage and offloading units where helicopter access costs dominate maintenance economics.
Marine Elevators Market Segmentation
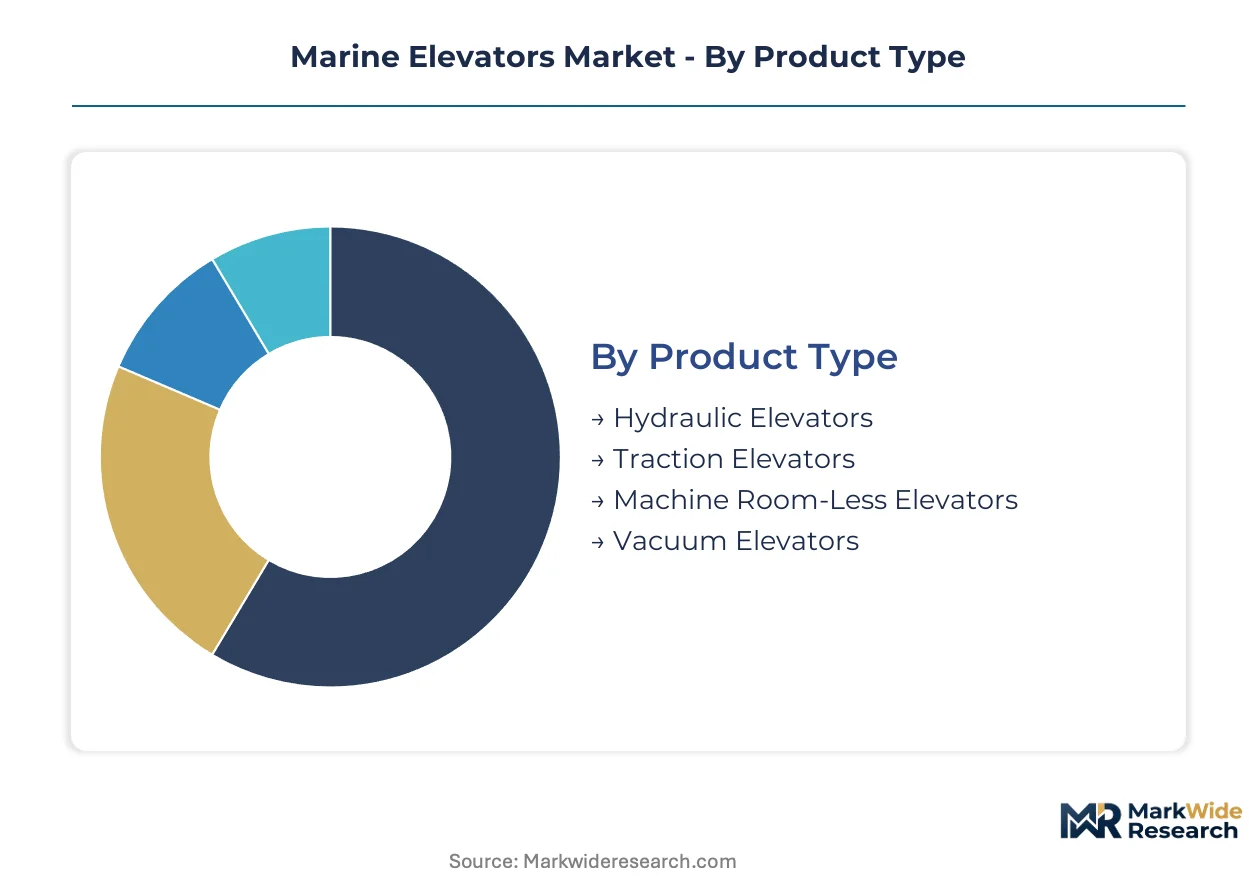
Marine elevator procurement decisions pivot on vessel architecture constraints, regulatory compliance tiers, and lifecycle cost models. Each segmentation dimension reveals distinct margin structures and competitive dynamics that reshape supplier positioning across newbuild and aftermarket channels.
Product Type:
Hydraulic units face intensifying substitution pressure from traction systems as cruise operators prioritize energy recovery specifications and machinery room flexibility.
- Hydraulic Elevators:Compact power units utilizing mineral oil or bio-based fluid systems deliver high load capacity within constrained shaft footprints. Demand concentrates in submarine and surface combatant applications where MacTaggart, Scott & Company Limited supplies purpose-built compact units, though Arctic route operators remain locked into mineral oil formulations due to cold-weather viscosity failures of bio-alternatives.
- Traction Elevators:Counterweight-configured systems with permanent magnet synchronous motors achieve 30% energy recovery through regenerative braking. Meyer Werft and Fincantieri specify these for 6,000+ passenger vessels requiring 40+ shafts per hull, with Mitsubishi Heavy Industries anchoring supply through in-house corrosion-resistant traction production.
- Machine Room-Less Elevators:Integrated drive systems eliminate dedicated machinery spaces, appealing to retrofit installations where deck penetration proves impractical.
- Vacuum Elevators:Pneumatic tube-based vertical transport serves yacht and luxury vessel segments seeking aesthetic differentiation and reduced mechanical complexity.
Traction elevators anchor the volume base while machine room-less configurations gain share at the steepest rate among retrofit-focused operators.
Installation Type:
Cost tier differentiation separates capital-intensive newbuild specifications from recurring-revenue aftermarket streams with divergent margin profiles.
- New Construction:Classification society type-approval mandates dominate procurement, with DNV GL, Lloyd's Register, and Bureau Veritas determining manufacturer eligibility before hull steel cutting. German shipyards in Hamburg and Bremen clusters concentrate 70% of European component sourcing for this channel.
- Retrofit:Legacy machinery room layouts from 1990s-era vessels force custom engineering on every counterweight installation, compressing fabricator margins through non-recurring engineering costs.
- Modernization:Control system upgrades and door operator replacements extend service life without full shaft reconstruction.
- Maintenance:Norwegian North Sea floating production operators now contract 10-year performance guarantees bundling parts, labor, and remote diagnostics, converting transactional spare parts procurement into annuity revenue streams.
Maintenance contracts deliver the most stable margin profile while retrofit installations expand most quickly as aging fleet replacement cycles accelerate.
End User:
Application-specific certification requirements fragment demand across naval, commercial, and offshore segments with incompatible technical specifications.
- Commercial Vessels:Cargo and general service ships prioritize durability and parts commonality over passenger comfort features.
- Passenger Ships:SOLAS Chapter II-2 fire safety amendments mandate redundant power systems and dual-circuit battery lowering assemblies for elevators in passenger zones, creating specification pull that favors pre-certified suppliers.
- Yachts:Custom aesthetics and space optimization drive specification, with vacuum elevator technology penetrating this segment for design differentiation.
- Offshore Platforms:Predictive maintenance algorithms reduce helicopter dispatch costs for technician visits in North Sea installations, with TK Elevator leveraging offshore service networks to sustain long-term contracts.
Passenger ships generate the highest unit volumes per vessel while offshore platforms deliver the strongest pricing power through performance-based contracting.
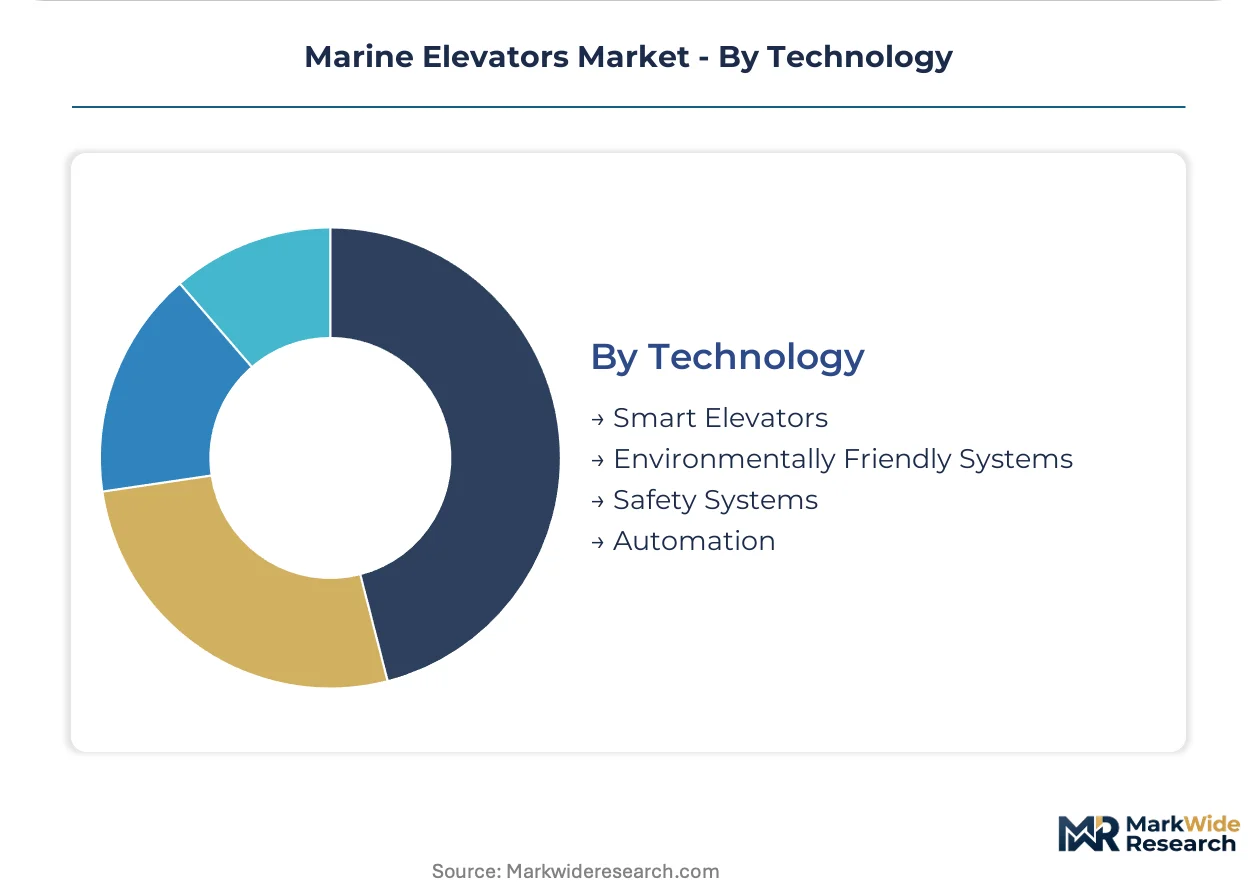
Technology:
Customer type stratification separates defense procurement agencies with multi-decade service horizons from commercial operators prioritizing total cost of ownership compression.
- Smart Elevators:Condition-based monitoring systems with predictive algorithms convert suppliers into data-service providers, reshaping competitive positioning through remote diagnostics capabilities.
- Environmentally Friendly Systems:Regenerative braking and permanent magnet motors address EEDI compliance mandates from the IMO.
- Safety Systems:Anti-heave compensation and emergency battery lowering ensure passenger safety during rough seas or power failure.
- Automation:Reduced crewing requirements through destination dispatch and integrated ship management system connectivity.
Safety systems constitute the non-negotiable baseline specification while smart elevator technology climbs the fastest as offshore operators quantify remote diagnostic savings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cruise operators and naval procurement agencies concentrate demand across five shipbuilding economies, with classification society proximity and steel alloy supply chains determining manufacturer access.
Germany
Meyer Werft's Papenburg yard and the Hamburg-Bremen corridor drive newbuild specifications for 6,000-passenger vessels requiring 40-plus elevator shafts per hull. The country's Federal Maritime and Hydrographic Agency enforces SOLAS Chapter II-2 amendments through DNV GL and Lloyd's Register certification protocols. Hamburg's stainless steel processing clusters supply 316L alloy components to fabricators serving North Sea offshore platforms.
Italy
Fincantieri's Monfalcone and Marghera shipyards anchor Mediterranean demand for premium passenger vessels with redundant power system mandates. The Italian Ministry of Infrastructure and Transport implements EU MDR conformity assessment for electrical subsystems through notified bodies in Milan and Genoa. Trieste's port engineering sector specializes in Arctic route vessel modifications for polar class certification.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries construct LNG carriers and container vessels with machinery room-less elevator specifications for deck-constrained retrofits. The Korean Register of Shipping enforces IMO energy efficiency design index compliance for regenerative braking systems. Busan's marine equipment district supplies permanent magnet synchronous motors to domestic shipyards.
Japan
Mitsubishi Heavy Industries' Nagasaki yard produces corrosion-resistant traction systems for naval surface combatants with multi-decade service horizons. Japan's Ministry of Land, Infrastructure, Transport and Tourism coordinates with ClassNK on elevator safety inspections for passenger vessels. Yokohama's industrial base supports predictive maintenance algorithm development for offshore platform contracts.
United States
Carnival Corporation's Miami headquarters influences fleet-wide elevator specifications across its nine cruise brands. The United States Coast Guard enforces SOLAS protocols through its Marine Safety Center certification reviews. Pascagoula's Ingalls Shipbuilding and Newport News Shipbuilding drive demand for compact hydraulic units in submarine and aircraft carrier applications.
Marine Elevators Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive marine divisions alongside specialized elevator fabricators. Tiered supply relationships separate classification society-approved incumbents from regional service providers. Two strategic archetypes dominate: integrated shipyard suppliers with in-house traction system production, and independent hydraulic specialists serving naval retrofit channels. Competitive moves center on long-term performance contracting and MDR pre-certification investments to secure European-flag registry eligibility.
Among diversified industrial groups, Mitsubishi Heavy Industries and Hyundai Elevator exemplify the integrated archetype with shipyard-aligned production capabilities. TK Elevator occupies a position bridging commercial marine and offshore platform segments through service network density. MacTaggart, Scott & Company Limited represents the compact hydraulic specialist tier serving constrained naval architectures. LUTZ Elevators and Kleemann sit within the European fabricator cluster concentrated around German and Italian classification society approvals.
| Leading Market Players |
|---|
| Alimak |
| TK Elevator |
| Marine Elevators |
| LUTZ Elevators |
| Mr. Marine |
| Kleemann |
| Hyundai Elevator |
| Mitsubishi Heavy Industries |
| MacTaggart, Scott & Company Limited |
| Others |
Supply & Pricing Matrix
Long-term performance guarantees bundling parts, labor, and remote diagnostics lock in supply access for North Sea offshore operators while anchoring price visibility across decade-long service horizons. This contract structure concentrates procurement power among DNV GL-certified fabricators in Hamburg and Bremen clusters, compressing vendor diversity while stabilizing input cost forecasting for 316L alloy components.
Pricing Analysis
Cost-plus contracts with nickel futures indexation dominate newbuild specifications for 6,000-passenger cruise vessels. Pricing stratifies across SOLAS-certified premium tier, MDR-compliant standard tier, and non-European economy tier based on classification society approval status and machinery room configuration complexity. Cost compression in the economy tier is intensifying because Meyer Werft and Fincantieri consolidate supplier lists to pre-approved fabricators. Retrofit operators exhibit highest price sensitivity due to non-recurring engineering burdens, while naval procurement agencies show lowest sensitivity given multi-decade service horizons.
Supply Chain Analysis
Strategic stockpiling of 316L marine-grade stainless steel prevails over just-in-time approaches given nickel price volatility and classification society audit compression timelines. Supply concentrates in Germany, Italy, and South Korea, with Hamburg's alloy processing clusters, Milan's notified bodies for MDR compliance, and Busan's permanent magnet motor production anchoring fabrication. The chain draws from nickel mining, rare earth magnet processing, and marine-grade steel rolling as critical inputs. Single-source vulnerability runs through German classification-approved component sourcing, which controls seventy percent of European eligibility. Distribution runs through shipyard-integrated procurement channels and offshore platform operator direct contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified marine elevator technician output from DNV GL and Lloyd's Register programs falls short of fleet maintenance requirements, creating a capability gap that constrains service network expansion and inflates field engineering premiums.
For Market Incumbents: Compound defensive positioning through captive production of corrosion-resistant traction systems and MDR pre-certification investments for European-flag registry eligibility. TK Elevator's offshore service network density offers a template for anchoring long-term maintenance contracts against emerging smart-enabled entrants. Backward integration into permanent magnet synchronous motor production secures supply continuity amid rare earth processing concentration. For New Entrants and Emerging Players: Lead with Arctic route vessel certification as Russia's Northern Sea Authority and Transport Canada develop ice-class elevator specifications for year-round polar operations. Naval fleet modernization programs for surface combatants present penetrable white-space given multi-decade service horizons and captive demand from defense procurement agencies. A go-to-market angle anchored in predictive maintenance algorithm development for offshore platforms bypasses incumbent certification advantages. For Investors and Strategic Acquirers: Capital is best deployed toward compact hydraulic specialists with submarine and surface vessel constraints expertise, such as fabricators serving Ingalls Shipbuilding and Newport News Shipbuilding applications. Long-term viability over a five-to-ten year window rests on defense procurement continuity and offshore platform retrofit cycle acceleration. The signal to watch is IMO SOLAS amendment timing for fire safety protocol expansion, which would trigger specification pull for dual-circuit battery lowering assemblies.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Pre-Certification Investment | Secures European-flag registry eligibility through notified body intervention in Milan and Genoa. |
| Predictive Maintenance Algorithm Development | Converts suppliers into data-service providers for Norwegian North Sea floating production operators. |
| Permanent Magnet Motor Integration | Delivers thirty percent energy recovery for Meyer Werft and Fincantieri EEDI compliance mandates. |
| Arctic Route Certification Pursuit | Captures emerging demand from Russia's Northern Sea Authority ice-class specifications. |
| Long-Term Performance Guarantee Structuring | Bundles parts, labor, and remote diagnostics into annuity revenue streams offshore. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with shipyard procurement directors, classification society surveyors, offshore platform maintenance managers, and naval fleet engineering officers. Secondary validation drew from IMO SOLAS convention documentation, DNV GL and Lloyd's Register certification protocols, EU MDR conformity assessment guidelines, and Meyer Werft and Fincantieri order book disclosures. Bottom-up vessel installation counts were triangulated against top-down shipbuilding output projections.
Across the analysis window, the forecasting framework modeled product type segmentation across hydraulic, traction, machine room-less, and vacuum configurations alongside installation type, end user category, and technology tier dimensions. CAGRs were derived from regression analysis against shipbuilding order pipelines and offshore platform fleet age profiles. Permanent magnet motor penetration rates and predictive maintenance algorithm adoption curves served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained cruise fleet expansion, stable nickel alloy pricing, and continued SOLAS enforcement through classification societies would require recalibration. Forecasts reflect documented assumptions regarding technician certification program output and shipyard consolidation trends. Revision becomes warranted when Arctic route vessel certification standards cross implementation thresholds or bio-based hydraulic fluid formulations achieve cold-weather viscosity specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Ship Rudders Market
Marine
Boat Console Market
Marine
Marine Fender Market
Marine
Trim Tabs Market
Marine
Sailboat Propellers Market
Marine
Commercial Hovercraft Market
Marine
Marine Big Data Market
Marine
Marine Glass Market
Marine
Marine and Marine Management Software Market
Marine
Military Marine Engine Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Engines Market
Marine
Boat Trolling Motor Market
Marine
Marine Base Steering Gear Market
Marine
Marine Turbocharger Market
Marine
Electric Boat and Ship Market