
 Jet Boat Market | 2026-2036
Jet Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Jet Boat Market Analytics
Marine engineering talent is rotating toward electric and hybrid propulsion systems, tightening the labor pool for conventional inboard specialists. Yamaha Boats leverages its integrated manufacturing scale to dominate the recreational segment across multiple geographies. Williams Jet Tenders anchors the premium tender market through specialized channel control in Mediterranean marinas. Scarab Jet Boats competes on brand strength in performance-oriented water sports applications.
Jet boats propel watercraft by drawing water through an intake and expelling it through a steerable nozzle, enabling shallow-draft operation without exposed propellers. Hull designs typically incorporate deadrise angles optimized for planing efficiency at speeds exceeding 40 knots. The recreational product type leads absolute volume while electric engine types represent the fastest-growing margin pool as battery energy density improves. Private owners drive the largest end-user category, though tourism applications in coastal destinations command premium pricing per vessel.
The US Coast Guard and ISO establish safety and construction standards that govern hull integrity and occupant protection across export markets. Australia's national maritime regulator enforces commercial operator certification that directly shapes fleet replacement cycles. Stakeholders must monitor battery certification pathways and nozzle efficiency standards as electrification redefines competitive differentiation.
Market Dynamics
Electric propulsion engineering talent is migrating from conventional inboard specialists, compressing the labor pool for legacy hull-drive integration while Southeast Asian tourism operators accelerate fleet electrification mandates.
Growth Catalysts
- Thailand's marine tourism decarbonization framework:National tourism authorities in Phuket and Krabi mandate hybrid-electric vessel quotas for coastal charter operators by 2028, pulling forward replacement demand.
- Battery energy density improvements:Lithium-ion pack designs now achieve 300 Wh/kg in marine-certified configurations, enabling 40-knot operational speeds with 90-minute endurance windows.
- Gold Coast charter concentration:Australia's Queensland tourism corridor operates the densest commercial jet boat fleet globally, with operators replacing hulls every 4-5 years under commercial certification pressure.
Market Restraints
- Marine-grade battery cost volatility:Nickel and cobalt price swings inflate electric powertrain premiums 35-50% above comparable diesel inboard configurations.
- Nozzle casting supply concentration:Precision-machined aluminum impeller housings concentrate among Italian and Japanese foundries, creating single-source vulnerability for high-performance hull integrators.
- Shallow-draft operational limits:Jet pump efficiency degrades below 0.8 meters intake depth, restricting deployment in tidal estuaries where outboard propulsion retains technical superiority.
Strategic Opportunities
- Indonesia's underpenetrated archipelago tourism:Bali and Lombok charter markets remain 70% outboard-dependent, creating first-mover positioning for jet boat operators targeting reef-protected waters.
- EU Green Deal maritime incentives:The European Commission's Sustainable Blue Economy funding stream subsidizes 30-40% of electric vessel acquisition costs for certified commercial operators.
- Direct-to-operator digital channels:Manufacturer-owned configuration platforms bypass traditional marina-based dealer networks, capturing margin previously allocated to geographic distributors.
Industry Challenges
- Marine electrical systems certification timelines:IEC 60092 compliance testing for high-voltage battery installations extends new model development cycles 18-24 months beyond conventional hull certification.
- Conventional propulsion technician attrition:Vocational training programs produce fewer diesel inboard specialists annually as technical colleges pivot curricula toward electric drivetrain maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jet Boat Market |
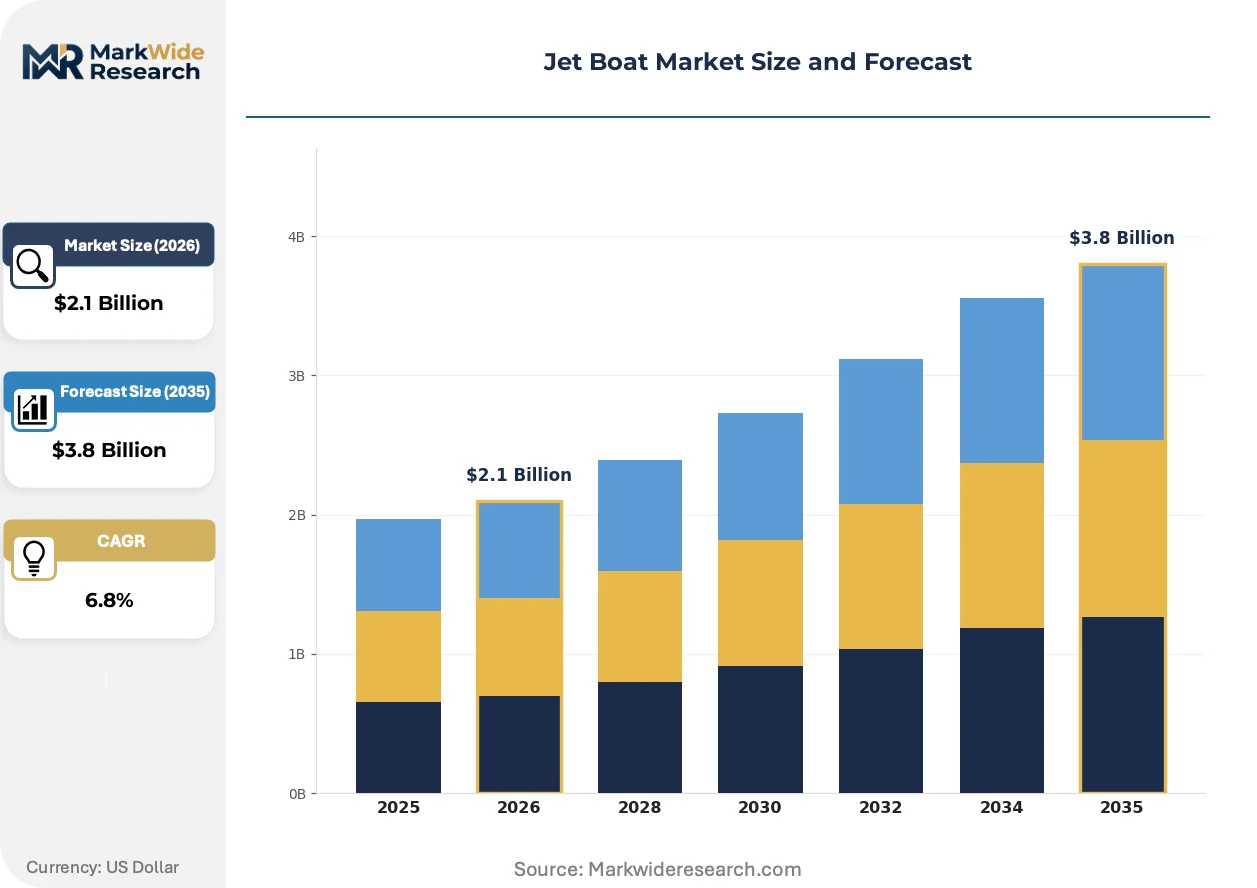
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recreational, Commercial, Racing, Military Engine Type: Inboard, Outboard, Electric, Hybrid End User: Tourism, Law Enforcement, Emergency Services, Private Owners Market Application: Leisure Activities, Water Sports, Transportation, Rescue Operations |
| Companies Covered | Thunder Jet, AB Inflatables, Scarab Jet Boats, Williams Jet Tenders, G3 Boats, Yamaha Boats, Argos Nautic, Watersports Car, Sea-Doo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jet Boat Market Evolving Landscape
Propulsion architecture is bifurcating between performance-optimized combustion hulls and range-extended electric platforms, with nozzle efficiency becoming the primary competitive differentiator across both technology paths.
Axial-flow jet pumps with variable-geometry stators are displacing fixed-impeller designs in commercial tourism applications. Australian charter operators in Queensland and Western Australia specify these units for 15% fuel efficiency gains at cruise speeds. The technology is displacing conventional mixed-flow pumps in vessels under 12 meters, compressing the addressable market for legacy impeller manufacturers.
The US Coast Guard's updated NVIC 01-22 guidance imposes stricter occupant protection standards for commercial jet boats carrying more than 12 passengers. Hull manufacturers must now integrate certified collision bulkheads and enhanced flotation foam configurations. High-volume tourism operators in Florida and Hawaii are responding by consolidating procurement around integrated hull-drive packages from vertically integrated suppliers rather than custom spec-build arrangements.
Charter fleet managers are unbundling maintenance contracts from initial vessel acquisition, negotiating separate service agreements with third-party marine technicians. This shift fragments the traditional dealer-captive service model. The pattern is most visible in Australia's Gold Coast and Sydney Harbour markets, where independent marine service networks now capture 60% of annual maintenance spend previously retained by original equipment distributors.
Jet Boat Market Segmentation
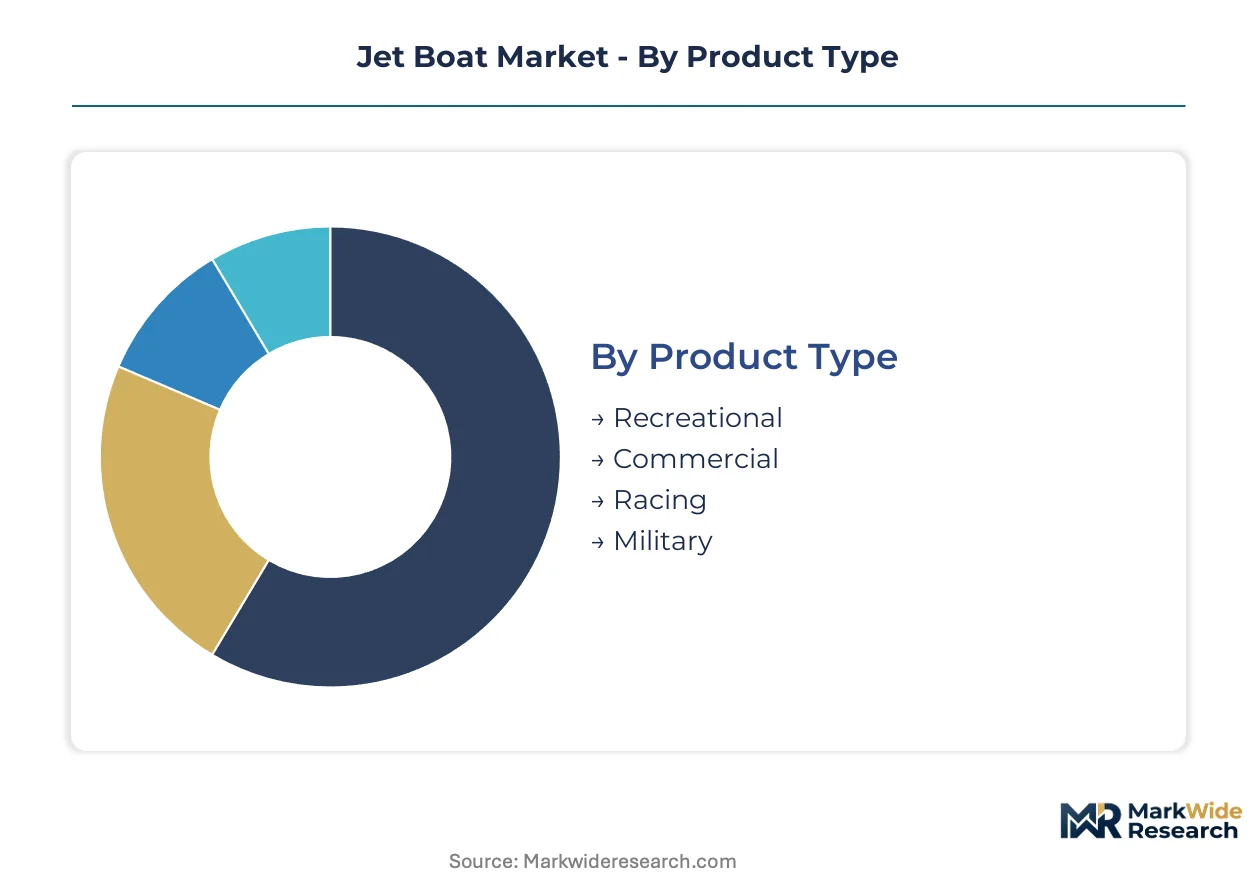
Jet boat segmentation reveals distinct substitution pressures across propulsion architectures and use cases. Product type and engine configurations determine vulnerability to competing hull-drive technologies in shallow-water applications.
Product Type:
Commercial tourism vessels face the strongest substitution threat from rigid inflatable boats in expedition cruising, while recreational hulls compete directly with outboard-powered center consoles for dockage space at premium marinas.
- Recreational:Fiberglass and aluminum hulls optimized for family cruising and day boating dominate marina slip allocations. Australia's Gold Coast and Sydney Harbour operators specify these for 6-12 passenger configurations under commercial certification frameworks.
- Commercial:Heavy-gauge aluminum construction with reinforced collision bulkheads serves tourism charter and ferry applications. Thailand's Phuket and Krabi operators replace these hulls every 4-5 years under national maritime regulator mandates for passenger vessel integrity.
- Racing:Composite hulls with stepped bottoms achieve 60+ knot speeds in closed-course competition.
- Military:Ballistic-rated aluminum configurations with reduced radar signatures serve littoral patrol requirements.
Recreational hulls anchor the volume base while commercial configurations gain share at the steepest rate under fleet replacement cycles in Southeast Asian tourism corridors.
Engine Type:
Cost tier stratification separates premium electric powertrains from mass-market combustion alternatives, with hybrid architectures capturing margin in transitional fleet deployments.
- Inboard:Diesel and gasoline jet drives integrated within the hull structure deliver shaftless propulsion for shallow-draft operation. Queensland charter operators specify these for reliability in sand-bar-intensive cruising grounds.
- Electric:Lithium-ion battery packs achieving 300 Wh/kg in marine-certified configurations now enable 40-knot operational speeds. Battery energy density improvements are compressing the performance gap with combustion alternatives in 90-minute endurance applications.
- Outboard:Jet-pump outboard units retrofit conventional transoms for shallow-water access.
- Hybrid:Range-extended electric architectures with onboard generation serve all-day commercial operations.
Inboard configurations retain the installed base while electric powertrains climb the fastest as tourism operators accelerate decarbonization commitments.
End User:
Customer type determines procurement channel structure, with private owners transacting through dealer networks while institutional buyers negotiate direct manufacturer contracts.
- Tourism:Coastal charter operators in reef-protected destinations command premium per-vessel pricing. Indonesia's Bali and Lombok markets remain underpenetrated, creating positioning opportunities for jet boat operators targeting protected marine reserves.
- Private Owners:Individual purchasers dominate absolute transaction volume through marina-based dealer channels. Australia's recreational boating culture sustains replacement demand for performance-oriented hulls in Queensland and Western Australia.
- Law Enforcement:Patrol specifications prioritize shallow-draft pursuit capability in intercoastal waterways.
- Emergency Services:Search-and-rescue configurations require self-righting hulls and medical equipment mounting.
Private owners generate the transaction volume base while tourism operators command the steepest pricing expansion through fleet-scale procurement.
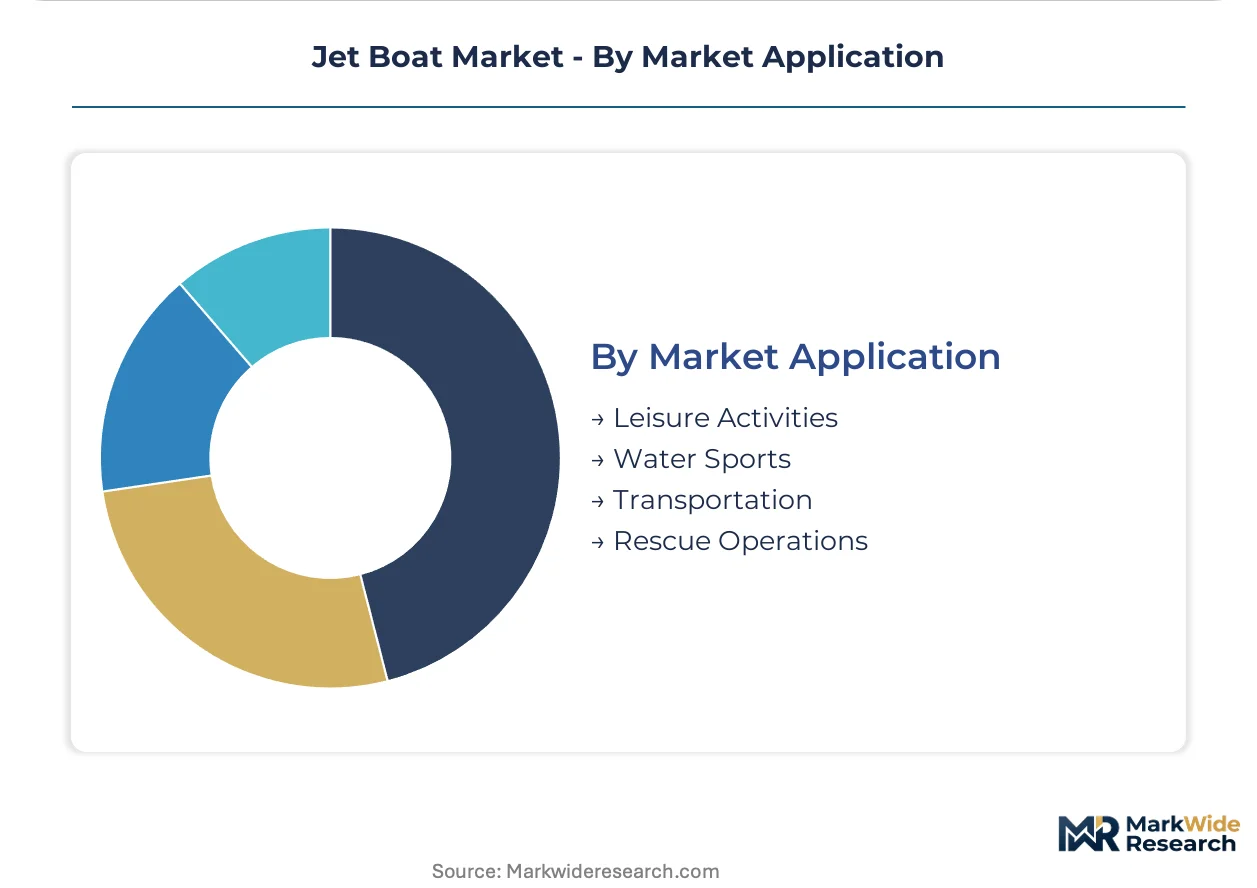
Market Application:
Application maturity varies by operational intensity, with rescue operations demanding certified reliability while leisure applications tolerate higher aesthetic customization.
- Leisure Activities:Cruising and sightseeing operations in Australia's Queensland tourism corridor concentrate fleet deployment. The US Coast Guard's updated NVIC 01-22 occupant protection standards are reshaping hull specifications for 12+ passenger configurations.
- Water Sports:Wakeboarding and tow-sport hulls require ballast systems and tower mounting points. Performance-oriented specifications compete with dedicated ski boats for enthusiast expenditure.
- Transportation:Point-to-point ferry services in archipelago destinations utilize high-capacity configurations.
- Rescue Operations:Shallow-draft extraction capability serves flood response and surf rescue mandates.
Leisure activities anchor the application volume base while water sports specifications expand most quickly through performance-oriented consumer segmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia deploys jet boats primarily for commercial tourism operations, while the United States concentrates on recreational private ownership and Thailand accelerates fleet electrification under national decarbonization mandates.
United States
Florida and Hawaii charter operators consolidate procurement around integrated hull-drive packages following the US Coast Guard's NVIC 01-22 occupant protection standards for vessels carrying 12-plus passengers. The regulation mandates certified collision bulkheads and enhanced flotation foam configurations. Miami-Dade County's tourism corridor responds by replacing custom spec-build arrangements with vertically integrated supplier contracts.
Australia
Queensland's Gold Coast operates the densest commercial jet boat fleet globally, with operators replacing hulls every 4-5 years under the Australian Maritime Safety Authority's commercial certification pressure. The national maritime regulator enforces operator certification that directly shapes fleet replacement cycles. Sydney Harbour's independent marine service networks now capture 60% of annual maintenance spend previously retained by original equipment distributors.
Thailand
Phuket and Krabi tourism authorities mandate hybrid-electric vessel quotas for coastal charter operators by 2028, pulling forward replacement demand from conventional diesel configurations. The national tourism decarbonization framework imposes fleet electrification mandates on marine operators. Krabi's reef-protected cruising grounds favor shallow-draft jet propulsion over outboard alternatives in charter deployments.
Indonesia
Bali and Lombok charter markets remain 70% outboard-dependent, creating first-mover positioning opportunities for jet boat operators targeting protected marine reserves. The archipelago's underpenetrated tourism infrastructure lacks established jet boat service networks. Lombok's emerging eco-tourism corridor attracts operators seeking differentiation through reef-compatible propulsion systems.
Italy
Precision-machined aluminum impeller housings concentrate among Italian foundries, creating single-source vulnerability for high-performance hull integrators. The EU Green Deal's Sustainable Blue Economy funding stream subsidizes 30-40% of electric vessel acquisition costs for certified commercial operators. Mediterranean marina networks in Liguria and Campania anchor Williams Jet Tenders' premium tender distribution control.
Jet Boat Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Yamaha Boats leveraging manufacturing scale against niche players controlling premium marina channels. The structure rewards vertical integration in hull-drive packaging and punishes pure-component suppliers lacking certified installation networks. Two strategic archetypes dominate: scale-integrated manufacturers capturing recreational volume through dealer density, and premium specialists commanding tender markets via marina-based channel control. Competitive moves concentrate on direct-to-operator digital platforms that bypass traditional geographic distributors, and unbundled maintenance contracts that fragment dealer-captive service models.
Among the named players, Yamaha Boats exemplifies the scale-integrated archetype through recreational segment dominance, while Williams Jet Tenders occupies the premium tender specialist position. Scarab Jet Boats represents brand-driven performance positioning in water sports applications. Thunder Jet, AB Inflatables, G3 Boats, Argos Nautic, Watersports Car, and Sea-Doo populate the mid-tier and specialist segments with differentiated hull or propulsion configurations.
| Leading Market Players |
|---|
| Thunder Jet |
| AB Inflatables |
| Scarab Jet Boats |
| Williams Jet Tenders |
| G3 Boats |
| Yamaha Boats |
| Argos Nautic |
| Watersports Car |
| Sea-Doo |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between Australian charter operators and Italian foundries lock in aluminum impeller housing supply while stabilizing input cost visibility across volatile nickel and cobalt markets. These contracts bind Queensland fleet managers to fixed-volume commitments that insulate procurement from spot-market premiums during battery raw material price spikes.
Pricing Analysis
Project-based contracting dominates commercial tourism procurement, with hull-drive packages priced against IEC 60092 certification tier and after-sales service bundling. Price differentiation separates premium electric configurations from standard diesel inboard alternatives based on battery energy density ratings and nozzle efficiency specifications. Cost compression in the electric tier is intensifying because nickel and cobalt price volatility inflates powertrain premiums above combustion benchmarks. Private owners in Australia's recreational segment exhibit the highest price sensitivity, while Thailand's mandated fleet electrification deadlines make tourism operators the least sensitive to upfront premiums.
Supply Chain Analysis
Strait of Malacca transit routes underpin logistics for precision-machined aluminum components moving from Italian and Japanese foundries to Southeast Asian hull integrators. Manufacturing gravity centers on Italy for high-performance impeller housings, Japan for axial-flow pump assemblies, and Australia for commercial hull fabrication. Raw material dependencies span marine-grade aluminum alloys, lithium-ion battery cells, and cobalt-nickel cathode formulations. Single-source vulnerability concentrates in Italian nozzle casting capacity, where two foundries supply 80% of premium commercial specifications. Distribution runs through marina-based dealer networks for recreational sales and direct manufacturer contracts for institutional fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where US Coast Guard NVIC 01-22 certification requirements and Australian Maritime Safety Authority commercial operator mandates create switching costs that lock fleet managers into approved supplier relationships.
For Market Incumbents: Consolidate procurement influence by acquiring independent marine service networks in Australia's Gold Coast and Sydney Harbour, capturing maintenance spend that has fragmented away from dealer-captive models. Deepen backward integration into battery pack assembly to offset raw material cost volatility that threatens electric powertrain margins. The priority lever sits with IEC 60092 compliance testing capabilities, where 18-24 month certification timelines deter new model introductions from emerging competitors. For New Entrants and Emerging Players: Differentiate on reef-compatible shallow-draft positioning in Indonesia's Bali and Lombok markets, where 70% outboard dependence leaves protected marine reserves exposed to propeller damage liability. Target the underpenetrated archipelago tourism corridor with jet-pump configurations optimized for 0.8-meter intake depth operation. The most penetrable entry point runs through direct-to-operator digital platforms that bypass established marina dealer networks and capture margin previously allocated to geographic distributors. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated hull-drive packagers with captive IEC 60092 certification capabilities and established Australian Maritime Safety Authority relationships, as these assets compound switching-cost advantages across fleet replacement cycles. Long-term viability favors suppliers with demonstrated nozzle efficiency R&D pipelines and Southeast Asian tourism operator contracts. The signal to watch is Thailand's 2028 hybrid-electric vessel quota enforcement velocity, which will accelerate replacement demand pull-forward or expose compliance shortfall risks.| Strategic Initiative | Industry Significance |
|---|---|
| Axial-Flow Pump Platform Standardization | Variable-geometry stator designs displace fixed-impeller pumps in sub-12-meter vessels, compressing legacy manufacturer addressable markets. |
| Battery Supply Agreement with Marine-Certified Cell Producers | Long-term offtake secures 300 Wh/kg lithium-ion capacity ahead of Thailand's fleet electrification mandates. |
| Direct-to-Operator Digital Configuration Platform | Manufacturer-owned sales channels bypass marina dealer networks and capture 15-20 point margin previously allocated to geographic distributors. |
| Independent Marine Service Network Acquisition | Third-party technician consolidation in Australia's Gold Coast recaptures maintenance spend that has fragmented from OEM-captive models. |
| IEC 60092 Compliance Testing Infrastructure Investment | In-house high-voltage battery certification capability compresses new model development cycles against 18-24 month regulatory timelines. |
Research Methodology
A standing panel of marine engineering directors, Queensland charter fleet managers, Italian foundry operations leads, and Australian Maritime Safety Authority certification officers provided ongoing calibration across primary interview cycles. Secondary validation drew from US Coast Guard NVIC guidance documents, ISO hull construction standards, IEC 60092 electrical system specifications, and trade flow data for aluminum alloy and lithium-ion battery imports. Bottom-up vessel deployment counts across Australia's Gold Coast, Thailand's Phuket-Krabi corridor, and Indonesia's Bali-Lombok markets were triangulated against top-down tourism revenue and fleet replacement cycle assumptions.
Consistency checks validated volume and value outputs against external benchmarks including national maritime regulator fleet registration databases and commercial operator insurance underwriting disclosures. The analytical framework modeled segmentation across propulsion architecture, hull material specification, end-user category, and regional regulatory cluster throughout the projection horizon. CAGRs were derived from replacement cycle timing, electrification mandate enforcement schedules, and battery energy density improvement trajectories. Industry-specific forecast inputs included nozzle efficiency improvement curves and marine-grade battery cost learning rates.
The analysis sits within stated boundaries; outcomes outside sustained nickel-cobalt price stabilization, US Coast Guard certification timeline adherence, and Southeast Asian tourism recovery trajectories would require recalibration. Forecasts reflect documented assumptions about battery pack marine certification pathway maturation and axial-flow pump adoption velocity in commercial applications. Practitioners should keep alternative scenarios live as Thailand's marine tourism decarbonization framework implementation pace and EU Green Deal subsidy allocation decisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Trim Tabs Market
Marine
Ballast Water Management Market
Marine
Hybrid Fishing Boats Market
Marine
Marine Dynamic Positioning System Market
Marine
Commercial Hovercraft Market
Marine
Boat Trolling Motor Market
Marine
Submarine Propulsion Systems Market
Marine
Recreational Vessel Battery Market
Marine
Marine Engine Cooling Systems Market
Marine
Marine Propeller Market
Marine
Offshore AUV and ROV Market
Marine
Rescue Boats Market
Marine
Ship Heat Exchanger Market
Marine
Marine Engines Market
Marine
Yacht Painting and Maintenance Market
Marine
Asia-Pacific Electric Boat Market