
 Automotive Wheel Coating Market | 2026-2036
Automotive Wheel Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Wheel Coating Market Intelligence
Capital-intensity divergence between integrated resin producers and regional applicators is collapsing as environmental compliance costs escalate. Axalta Coating Systems leverages its captive pigment synthesis network to sustain margin structures that smaller competitors cannot replicate. PPG Industries anchors its position through direct technical service contracts with major OEM assembly plants across North America and Europe. BASF SE differentiates by controlling the full additive chemistry stack, from polyurethane dispersions to crosslinker packages, for wheel-specific formulations.
Automotive wheel coating comprises protective and decorative film-forming systems applied to alloy or steel wheel substrates, typically ranging from 25 to 100 microns in cured thickness, to resist brake dust corrosion, UV degradation, and stone chip damage while maintaining gloss retention. Powder coating dominates OEM lines due to zero-VOC emissions and high transfer efficiency, though liquid coating retains share in aftermarket color-matching and repair applications where batch flexibility outweighs unit economics. Motorsports represents the fastest-growing application dimension as thermal barrier coatings and ceramic-reinforced topcoats penetrate professional racing procurement channels.
EPA regulations under the National Emission Standards for Hazardous Air Pollutants constrain solvent-borne coating operations at US wheel manufacturing facilities, while REACH authorization procedures in Europe restrict chromium trioxide use in decorative electroplating. The EU Green Deal's industrial emissions targets are forcing coating houses to retrofit lines or exit the supplier base. Stakeholders must monitor how China's MEE enforcement of GB standards on VOC content reshapes export qualification requirements for coating systems destined for assembly plants in that market.
Market Dynamics
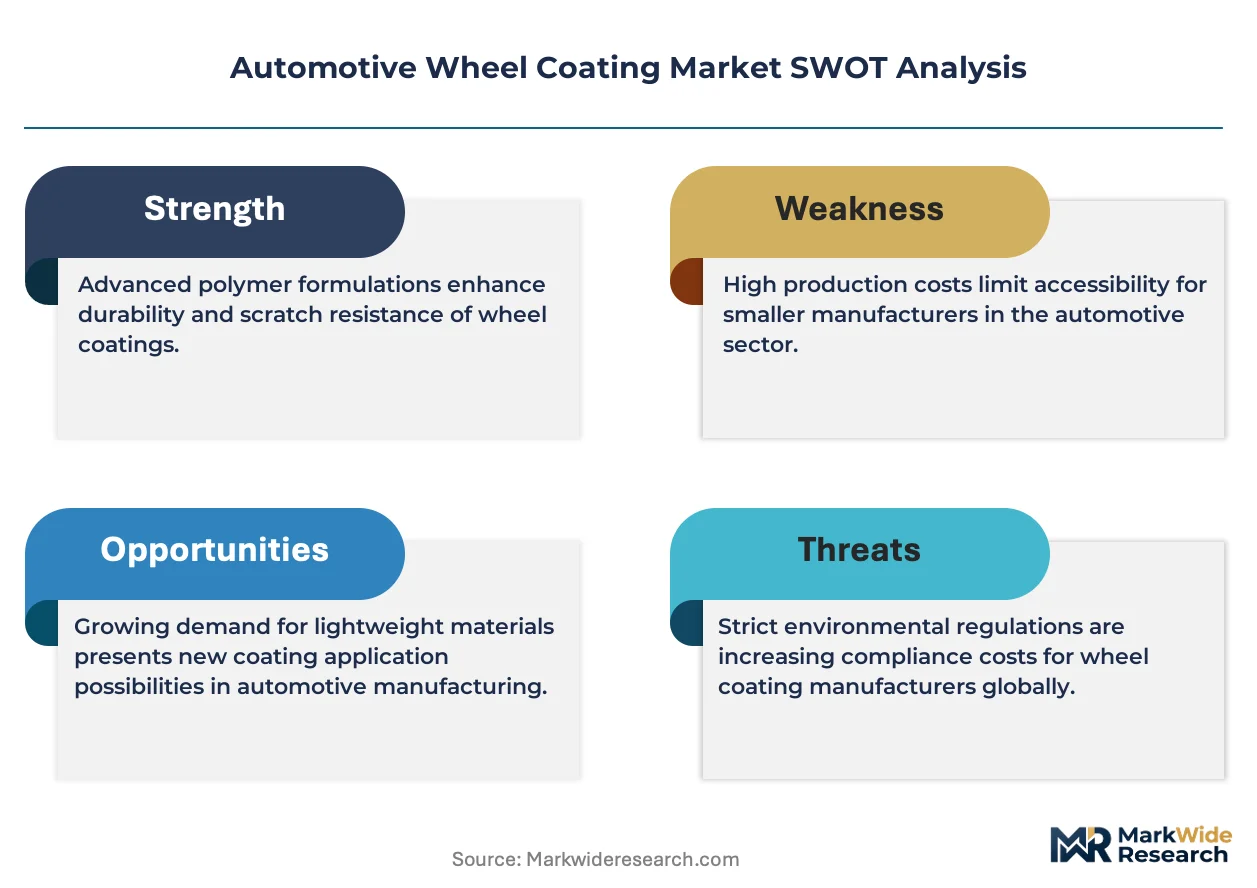
Waterborne polyurethane dispersion technology is compressing the cost gap between solvent-borne and eco-compliant coating systems, forcing incumbent suppliers to retrofit production assets or cede OEM contracts to reformulation-ready competitors.
Growth Catalysts
- EPA NESHAP compliance deadlines:Wheel manufacturers in the United States face escalating penalties for solvent-borne emissions, accelerating capital deployment into zero-VOC powder coating lines at major assembly plants.
- Aluminum wheel penetration in electric vehicles:Battery-electric platforms prioritize unsprung mass reduction, driving specification of larger-diameter alloy wheels requiring premium corrosion protection.
- China's localized coating supply chains:Domestic passenger vehicle production concentration in Jiangsu and Zhejiang provinces draws technical service investment from multinational formulation houses seeking direct OEM access.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings constrain margin predictability for regional applicators lacking long-term offtake agreements with chloride-process producers.
- Chromium trioxide authorization uncertainty:REACH sunset review procedures in Europe threaten decorative electroplating supply continuity for premium wheel finishers dependent on hexavalent chrome aesthetics.
- Ceramic thermal barrier substitution:Motorsports teams increasingly specify plasma-sprayed ceramic coatings for brake heat management, eroding addressable market for conventional organic topcoats in racing procurement.
Strategic Opportunities
- India's PLI scheme for auto components:Production-linked incentives for advanced automotive manufacturing attract coating system localization to serve emerging alloy wheel export hubs in Tamil Nadu and Gujarat.
- UV-curable liquid coating convergence:Combination of instant cure speed and batch flexibility enables penetration of fast-turnaround aftermarket repair channels previously dominated by thermoset powder.
- EU Green Deal industrial emissions targets:Retrofit financing mechanisms for coating line abatement technology create first-mover advantage for suppliers offering integrated VOC recovery and energy recovery systems.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in polyurethane dispersion stability and crosslinker kinetics concentrates at integrated resin producers, limiting talent mobility to independent coating houses.
- Dual-cure line integration complexity:Wheel manufacturers operating hybrid powder-liquid facilities face downtime risks and quality variance during substrate changeover sequences.
- GB standard certification timelines:China's MEE enforcement of updated VOC content limits for automotive coatings extends qualification periods for imported formulations, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Wheel Coating Market |
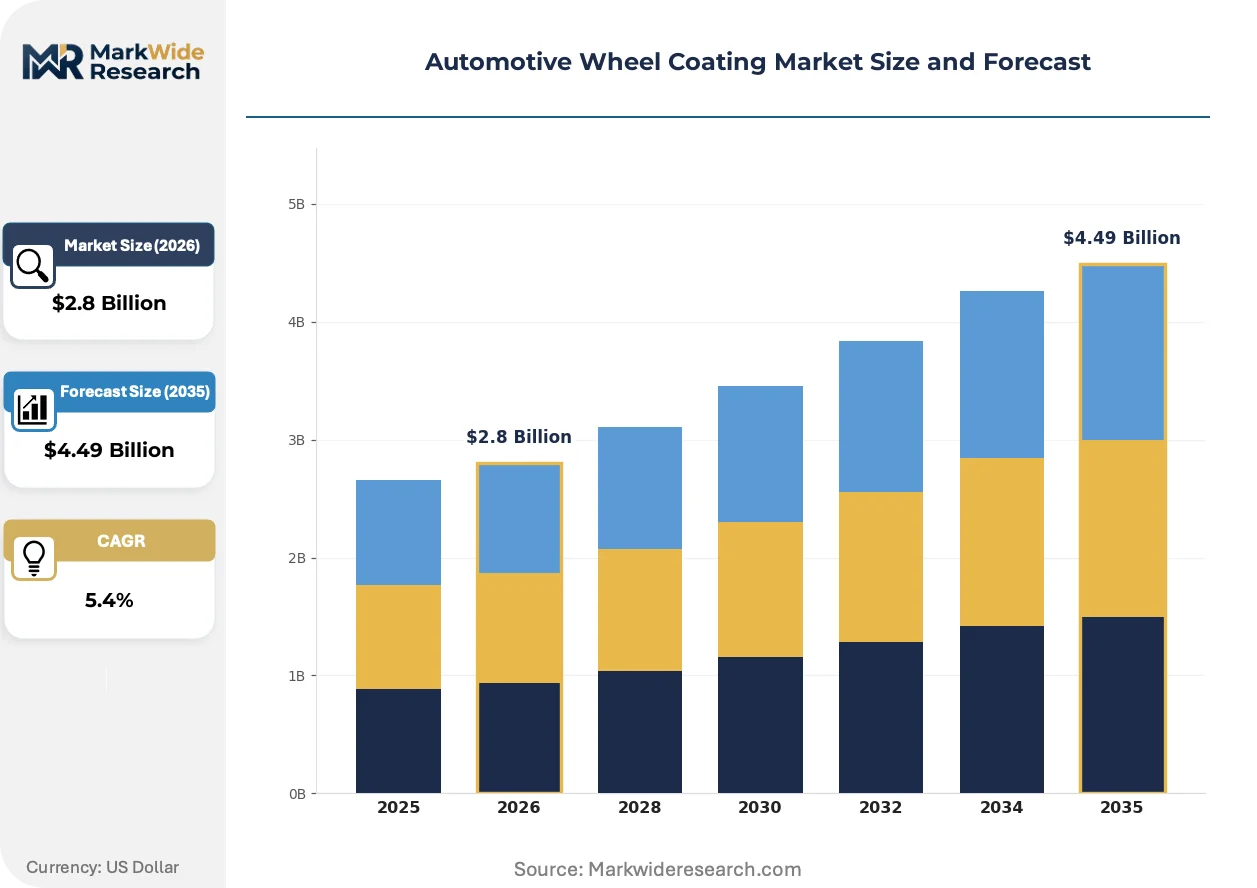
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Powder Coating, Liquid Coating, Electroplating, Anodizing End User: OEMs, Aftermarket Providers, Aftermarket Retailers, Vehicle Assemblers Material: Aluminum, Steel, Magnesium, Composite Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Motorsports |
| Companies Covered | Axalta Coating Systems, Nippon Paint, PPG Industries, Jotun A/S, Sherwin-Williams, BASF SE, Kansai Paint, KCC Corporation, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Wheel Coating Market Strategic Shifts & Innovations
Coating functionality is bifurcating between commodity corrosion protection and engineered surface performance, with thermal management and self-healing properties emerging as specification differentiators in premium wheel segments.
Self-healing clearcoat chemistry utilizing encapsulated polymer repair agents is supplanting conventional scratch-resistant topcoats in luxury OEM wheel programs. German and Japanese automakers specify these systems for factory-installed finishes on vehicles above premium price thresholds. The technology is compressing warranty claim exposure for cosmetic damage while commanding formulation premiums that solvent-borne alternatives cannot match.
REACH authorization restrictions on chromium trioxide are forcing decorative finishers toward trivalent chrome and physical vapor deposition alternatives. Wheel manufacturers serving European OEMs face supply base consolidation as smaller electroplating houses exit rather than absorb compliance retrofit costs. The shift is most pronounced in Italy and Poland, where historic decorative plating concentration now requires process reinvention to maintain export qualification.
Direct technical service contracting is consolidating procurement influence at major OEM assembly plants. Tier-one wheel suppliers increasingly specify approved coating system providers through multi-year framework agreements, displacing spot purchasing from regional distributors. This concentration is visible across North American truck and SUV production hubs, where captive wheel finishing operations favor single-source formulation partnerships with embedded laboratory support.
Automotive Wheel Coating Market Segmentation
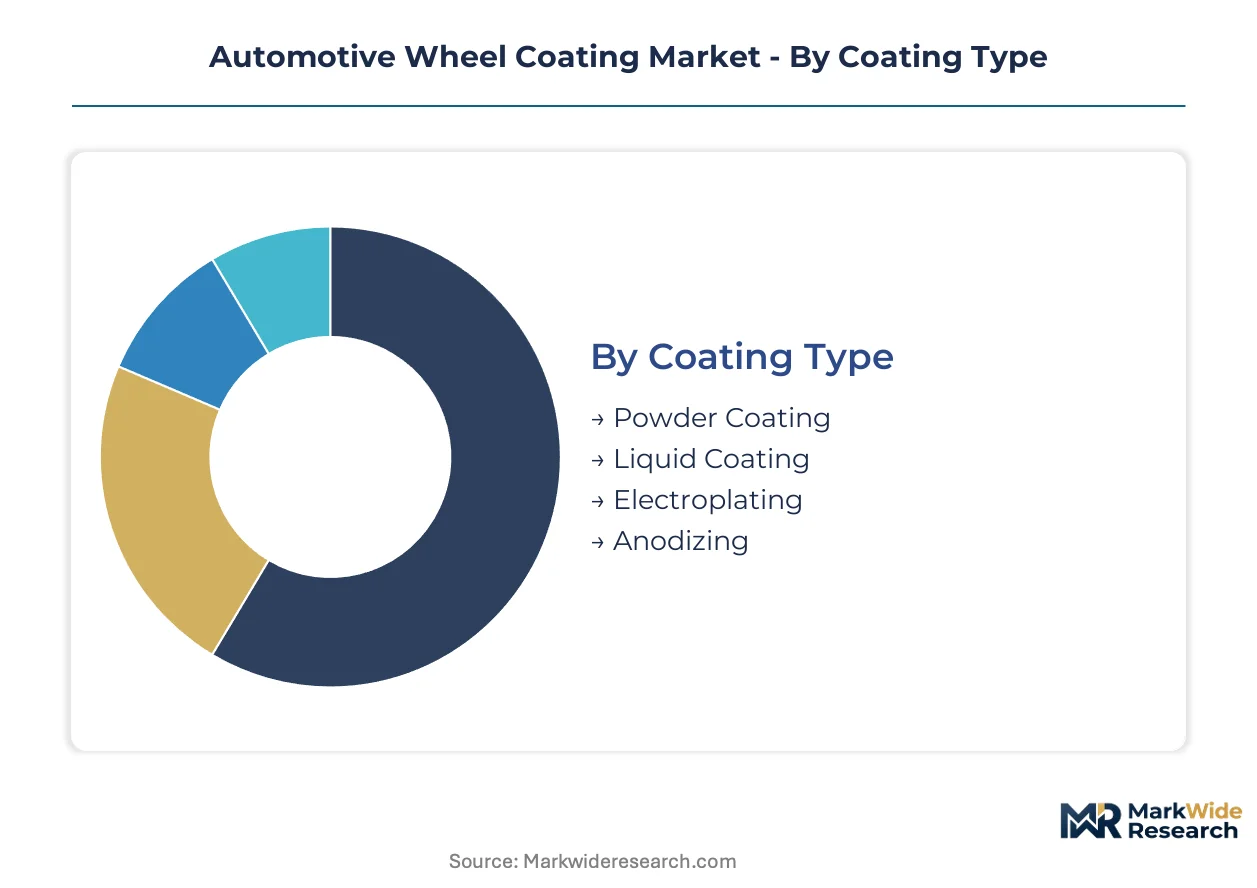
Coating selection in automotive wheels hinges on regulatory thresholds for volatile organic compounds and thermal performance requirements. Segmentation reveals how formulation houses allocate R&D resources across divergent compliance regimes and substrate specifications.
Coating Type:
EPA NESHAP enforcement and REACH authorization timelines create divergent qualification burdens across coating chemistries.
- Powder Coating:Thermoset polymer systems cure at 180-200°C to form dense crosslinked films with zero solvent emissions. OEM assembly plants in Michigan and South Carolina deploy captive powder lines to satisfy EPA hazardous air pollutant mandates while achieving 95%+ transfer efficiency.
- Liquid Coating:Solvent-borne and waterborne formulations deliver color-matching precision for aftermarket repair channels. Batch flexibility at regional applicators in Guangdong province sustains demand despite longer cure cycles and higher VOC compliance costs.
- Electroplating:Decorative chrome deposition via hexavalent or trivalent baths commands premium pricing for luxury wheel programs.
- Anodizing:Electrochemical oxide growth on aluminum substrates provides wear-resistant porous films sealable with organic dyes.
Established volume favors powder coating; emerging adoption favors liquid coating as waterborne polyurethane dispersions compress the eco-compliance cost gap.
End User:
Procurement concentration shifts with the scale of captive finishing operations versus distributed repair networks.
- OEMs:Automakers specify coating systems through direct technical service contracts with formulation houses, embedding laboratory support at assembly plant locations. Axalta and PPG anchor positions through multi-year framework agreements covering North American truck and SUV production hubs.
- Aftermarket Providers:Independent wheel refinishing shops purchase coating systems through regional distributors, prioritizing color-matching databases and rapid inventory replenishment.
- Aftermarket Retailers:Consumer-facing channels stock aerosol touch-up products and DIY refinishing kits with simplified application protocols.
- Vehicle Assemblers:Tier-one wheel suppliers operate captive finishing lines under OEM-directed coating specifications.
Direct contracting dominates OEM procurement; distributor networks retain aftermarket fragmentation.
Material:
Unsprung mass reduction priorities and corrosion susceptibility drive substrate-specific coating specifications.
- Aluminum:Cast and forged alloy wheels command the largest coating volume as battery-electric platforms prioritize mass reduction. Conversion coating pretreatments and powder topcoats dominate OEM specifications for 18-22 inch diameter wheels.
- Steel:Stamped and welded steel wheels persist in commercial vehicle and economy passenger segments. Cathodic electrodeposition primers and powder topcoats address salt spray corrosion requirements for fleet operators.
- Magnesium:Ultra-lightweight forged wheels penetrate motorsports and limited-production hypercar programs. Specialized conversion coatings manage galvanic corrosion risks with aluminum suspension components.
- Composite:Carbon fiber reinforced polymer wheels emerge in racing applications demanding extreme thermal insulation.
Aluminum substrates anchor mainstream volume; magnesium and composite materials gain share fastest in thermal-critical applications.
Application:
Operating environment severity determines coating performance tier and warranty exposure.
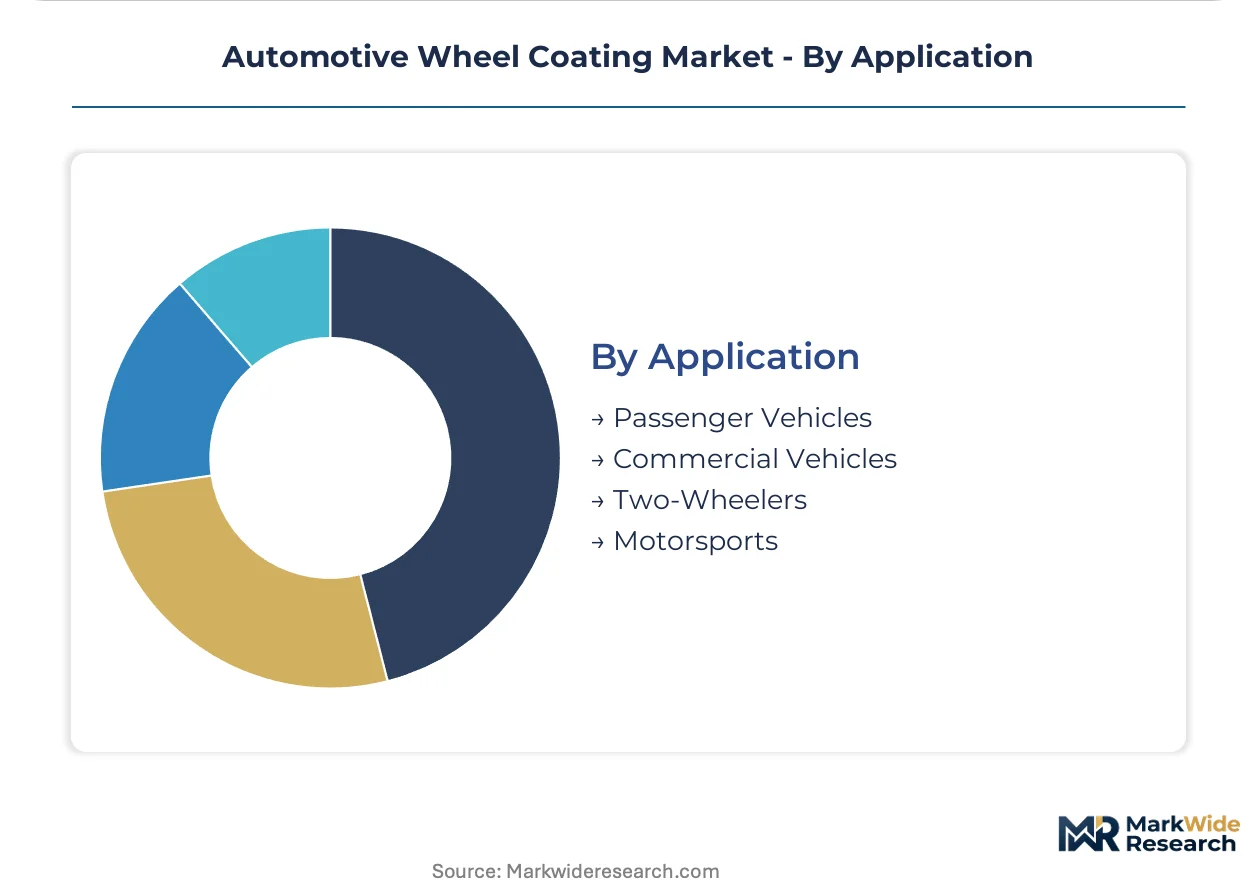
- Passenger Vehicles:Factory-installed wheel finishes must maintain gloss retention through automatic car wash cycles and brake dust exposure. Self-healing clearcoat chemistry penetrates luxury OEM programs above premium price thresholds.
- Commercial Vehicles:Fleet operators prioritize chip resistance and salt spray protection over aesthetic longevity. Heavy-duty truck wheel coating specifications emphasize extended maintenance intervals.
- Two-Wheelers:Motorcycle and scooter wheels require flexible coating films accommodating spoke flexure and rim impact.
- Motorsports:Professional racing procurement specifies thermal barrier coatings and ceramic-reinforced topcoats for brake heat management. Plasma-sprayed ceramic alternatives erode addressable market for conventional organic systems in this channel.
Passenger vehicle specifications set the volume baseline; motorsports commands the steepest expansion trajectory as thermal management functionality differentiates premium offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export qualification requirements now shape capacity location decisions more than raw material access. Wheel coating suppliers balance proximity to OEM assembly plants against compliance with destination-market environmental standards.
United States
Domestic truck and SUV production volumes sustain captive powder coating lines at Michigan and South Carolina assembly hubs. EPA NESHAP enforcement tightens solvent-borne emissions limits quarterly, forcing facility retrofits or contract migration to zero-VOC systems. Technical service teams from major formulation houses embed directly at OEM wheel finishing operations in Detroit and Spartanburg.
Germany
Luxury automaker specifications for self-healing clearcoats and trivalent chrome alternatives concentrate R&D investment in Baden-Württemberg. REACH authorization reviews for chromium trioxide threaten decorative plating supply continuity, accelerating physical vapor deposition adoption. Coating houses in Stuttgart and Karlsruhe retrofit lines to meet EU Green Deal industrial emissions targets ahead of 2030 deadlines.
China
Passenger vehicle production concentration in Jiangsu and Zhejiang provinces draws technical service investment from multinational suppliers seeking direct OEM access. MEE enforcement of updated GB standards on VOC content extends qualification timelines for imported formulations. Domestic coating supply chains now serve export-oriented assembly plants in Shanghai and Guangzhou with qualified waterborne systems.
Japan
Lightweight magnesium wheel programs for motorsports and limited-production vehicles drive specialized conversion coating demand. METI guidance on chemical substance management influences formulation specifications for domestic OEM supply. Coating development clusters in Aichi and Osaka prefectures focus on thermal barrier functionality for brake heat management applications.
India
Production-linked incentives for advanced automotive manufacturing attract coating system localization to serve emerging alloy wheel export hubs. BIS certification requirements for automotive coatings create entry barriers for unqualified imports. Tamil Nadu and Gujarat industrial corridors host new technical service facilities from multinational formulation houses targeting domestic OEM and export markets simultaneously.
Automotive Wheel Coating Market Key Industry Players
Concentration sits with integrated resin producers possessing captive pigment synthesis and additive chemistry control. Three structural archetypes define competitive positioning: multinational formulation houses with embedded OEM technical service, regional applicators serving aftermarket repair channels, and specialized electroplating finishers facing REACH-driven consolidation. Dominant competitive moves include direct contracting at assembly plant locations and retrofit financing partnerships for VOC abatement technology.
Among the integrated multinational tier, Axalta Coating Systems, PPG Industries, and BASF SE occupy positions defined by upstream control over critical raw materials. Axalta exemplifies the pigment-captive archetype through internal synthesis networks. PPG anchors the technical service-embedded model with laboratory co-location at major OEM facilities. BASF represents full-stack additive chemistry control from polyurethane dispersions through crosslinker packages. These three structures create qualification barriers that regional competitors cannot replicate without comparable backward integration.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| Nippon Paint |
| PPG Industries |
| Jotun A/S |
| Sherwin-Williams |
| BASF SE |
| Kansai Paint |
| KCC Corporation |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day pigment inventory cycles at regional applicators concentrate pricing power with chloride-process titanium dioxide producers in China and the US, while powder coating lines at OEM assembly plants command premium configured-to-order pricing through embedded technical service contracts.
Pricing Analysis
Configured-to-order pricing for OEM wheel programs commands 25-40% premiums over standard aftermarket formulations due to direct technical service embedding and laboratory co-location requirements. Price differentiation hinges on REACH compliance certification tier and volume-scale procurement frameworks, with multinational formulation houses anchoring premium tiers through captive pigment synthesis. Cost compression in waterborne polyurethane segments is intensifying as environmental compliance retrofits erode margin structures for regional applicators lacking long-term feedstock agreements. Aftermarket repair channels exhibit highest price sensitivity, while luxury OEM programs demonstrate lowest sensitivity due to warranty exposure and aesthetic performance requirements.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for titanium dioxide and specialty crosslinker packages sourced from Chinese and German chemical clusters. Raw material supply concentrates in China for pigment intermediates, Germany for polyurethane dispersion feedstocks, and the US for epoxy resin precursors, creating tariff exposure vulnerability for formulation houses dependent on transatlantic component flows. Distribution runs through direct technical service contracts at OEM assembly plants for powder coating systems, while liquid coating channels rely on regional distributor networks serving aftermarket refinishing operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in polyurethane dispersion stability and crosslinker kinetics concentrates at integrated resin producers, constraining talent mobility and creating durable competitive moats for backward-integrated formulation houses.
For Market Incumbents: Consolidate formulation chemist talent pools through captive R&D facility investments in Jiangsu and Baden-Württemberg to defend against waterborne technology disruption from reformulation-ready competitors. Deepen direct technical service contracts with major OEM assembly plants to lock out regional applicators seeking framework agreement entry, while retrofit financing partnerships for VOC abatement technology capture first-mover positioning under EU Green Deal timelines. For New Entrants and Emerging Players: Differentiate on UV-curable liquid coating convergence for fast-turnaround aftermarket repair channels in Guangdong and Tamil Nadu, where batch flexibility outweighs unit economics and incumbent powder coating dominance remains weakest. Target India's PLI scheme for auto components as the most penetrable geography, leveraging BIS certification gaps to establish technical service presence before multinational localization accelerates. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance-arbitrage play because REACH authorization timelines and EPA NESHAP enforcement windows create acquisition opportunities for distressed electroplating assets and regional applicators facing exit pressures. Monitor chromium trioxide sunset review proceedings as the critical signal for decorative finishing supply base consolidation velocity and trivalent chrome substitution ramp rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Synthesis | Captive titanium dioxide production insulates Axalta and PPG from chloride-process feedstock volatility. |
| Waterborne Formulation Retrofit Partnerships | Integrated VOC recovery and energy recovery systems create first-mover advantage under EU Green Deal targets. |
| Direct Technical Service Embedding | Laboratory co-location at Detroit and Spartanburg assembly plants locks in multi-year OEM framework agreements. |
| UV-Curable Liquid Coating Development | Instant cure speed enables penetration of fast-turnaround aftermarket channels previously dominated by thermoset powder. |
| India PLI Localization Investment | Tamil Nadu and Gujarat technical service facilities target domestic OEM and alloy wheel export hub qualification simultaneously. |
Research Approach
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and coating formulation R&D directors provided ongoing calibration across primary interview cycles, validated against customs trade data, SEC 10-K filings from integrated chemical producers, vehicle production databases, and MEE GB standard enforcement records. Bottom-up segment sizing triangulated with top-down market value reconstruction.
Consistency checks against external benchmarks validated volume and value outputs across coating type, end user archetype, substrate material, and regional production cluster segmentation dimensions. CAGRs derived from trend extrapolation of EPA NESHAP compliance deployment rates and aluminum wheel penetration curves in battery-electric platforms, cross-referenced with waterborne technology substitution elasticity estimates.
Material uncertainties — REACH authorization timeline revisions, titanium dioxide feedstock price dislocations, and MEE enforcement intensity variations — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory compliance cost trajectories and technology substitution rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Global Ultra High Performance Tire Market
Tires and Wheels
Run Flat Tire Inserts Market
Tires and Wheels
Tire Retreading Market
Tires and Wheels
Global Automotive Tire Inflator Market
Tires and Wheels
Automotive Smart Tire Market
Tires and Wheels
Ground Support Equipment Tires Market
Tires and Wheels
Rail Road Wheels Market
Tires and Wheels
Automotive Carbon Wheels Market
Tires and Wheels
Global Pneumatic Tires Market
Tires and Wheels
Automotive Tubeless Tire Market
Tires and Wheels
Forestry Equipment Tire Market
Tires and Wheels
Bicycle Rim Brake Market
Tires and Wheels
Green Tires Market
Tires and Wheels
Southeast Asian Tire Market
Tires and Wheels
Europe Green Tire Market