
 Mammalian Polyclonal Igg Antibody Market | 2026-2036
Mammalian Polyclonal Igg Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
Mammalian Polyclonal Igg Antibody Market Intelligence
Therapeutic-grade specificity standards is redrawing procurement criteria across the Mammalian Polyclonal Igg Antibody landscape. Thermo Fisher Scientific leverages its upstream serum supply chain to secure batch-to-batch consistency for high-sensitivity assays. Abcam plc differentiates through recombinant validation protocols that reduce cross-reactivity in diagnostic applications. Bio-Rad Laboratories anchors its position with ISO-compliant manufacturing infrastructure serving clinical laboratory customers.
Mammalian polyclonal IgG antibodies comprise heterogeneous immunoglobulin G populations derived from immunized host animals, typically exhibiting multi-epitope binding with molecular weights near 150 kDa and purification via protein A/G chromatography; these reagents enable signal amplification in protein detection workflows where monoclonal alternatives lack sufficient sensitivity. Research-grade antibodies occupy the largest volume share as academic institutions and early-stage discovery programs prioritize cost efficiency over lot-to-lot documentation. Diagnostic-grade segments command premium positioning due to FDA and EMA traceability mandates that elevate manufacturing overhead. Custom antibody services represent the fastest-expanding category as pharmaceutical manufacturers seek project-specific epitope coverage for preclinical target validation.
FDA quality system regulations and EMA IVD directive requirements shape product registration pathways, forcing manufacturers to maintain dual compliance documentation for transatlantic distribution. ISO 13485 certification serves as a baseline gate for clinical diagnostic supply contracts, while REACH and RoHS frameworks in Europe impose chemical-substance reporting obligations on conjugation chemistries. Stakeholders must monitor evolving regulatory convergence between FDA's proposed antibody characterization guidance and EMA's incoming in vitro diagnostic regulation implementation timelines to preempt supply chain disruption.
Market Dynamics
Therapeutic-grade specificity standards are compressing batch-to-batch tolerance windows, forcing manufacturers to abandon serum pooling practices that previously sufficed for research-grade supply. This structural tightening is redrawing procurement criteria across diagnostic and preclinical segments alike.
Growth Catalysts
- FDA Quality System Regulations:Traceability mandates for antibody characterization are elevating contract values for diagnostic-grade supply, compelling clinical laboratories to upgrade vendor qualification protocols.
- Affinity-Purification Automation:Protein A/G chromatography platforms are reducing lot-release cycle times, enabling manufacturers to serve just-in-time procurement schedules from biotechnology clusters in the United States and Germany.
- Preclinical Target Validation:Pharmaceutical manufacturers are expanding custom antibody service contracts to secure epitope coverage for novel biologic programs, accelerating project-specific production queues.
Market Restraints
- Serum Supply Concentration:Premium-grade fetal bovine serum sourcing concentrates in Australia and New Zealand, exposing manufacturers to export quota volatility and biosecurity-driven supply interruptions.
- Cross-Reactivity Validation Burden:Recombinant protein expression systems for antibody specificity testing require capital-intensive infrastructure that mid-tier suppliers struggle to amortize across limited product portfolios.
- EMA IVD Directive Compliance:Dual documentation requirements for transatlantic distribution inflate regulatory affairs headcount by thirty to fifty percent for manufacturers serving both FDA and European notified body pathways.
Strategic Opportunities
- China NMPA Pathway Harmonization:Convergence between Chinese pharmacopoeia standards and ISO 13485 frameworks is reducing registration friction for manufacturers establishing domestic production partnerships.
- Companion Diagnostic Co-Development:Antibody suppliers are embedding into pharmaceutical clinical trial design phases, capturing long-term supply agreements tied to biomarker-qualified therapeutic approvals.
- Single-Use Bioreactor Integration:Perfusion-based mammalian cell culture systems are enabling distributed production footprints that reduce cold-chain dependency for temperature-sensitive polyclonal lots.
Industry Challenges
- Serum Traceability Documentation:Veterinary health certificate aggregation across multi-source donor herds requires specialized quality assurance personnel that compete with broader biopharmaceutical talent pools.
- Host Animal Genetic Drift:Batch consistency protocols must account for immunoglobulin repertoire variation in outbred rabbit and goat populations, complicating reference standard establishment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mammalian Polyclonal Igg Antibody Market |
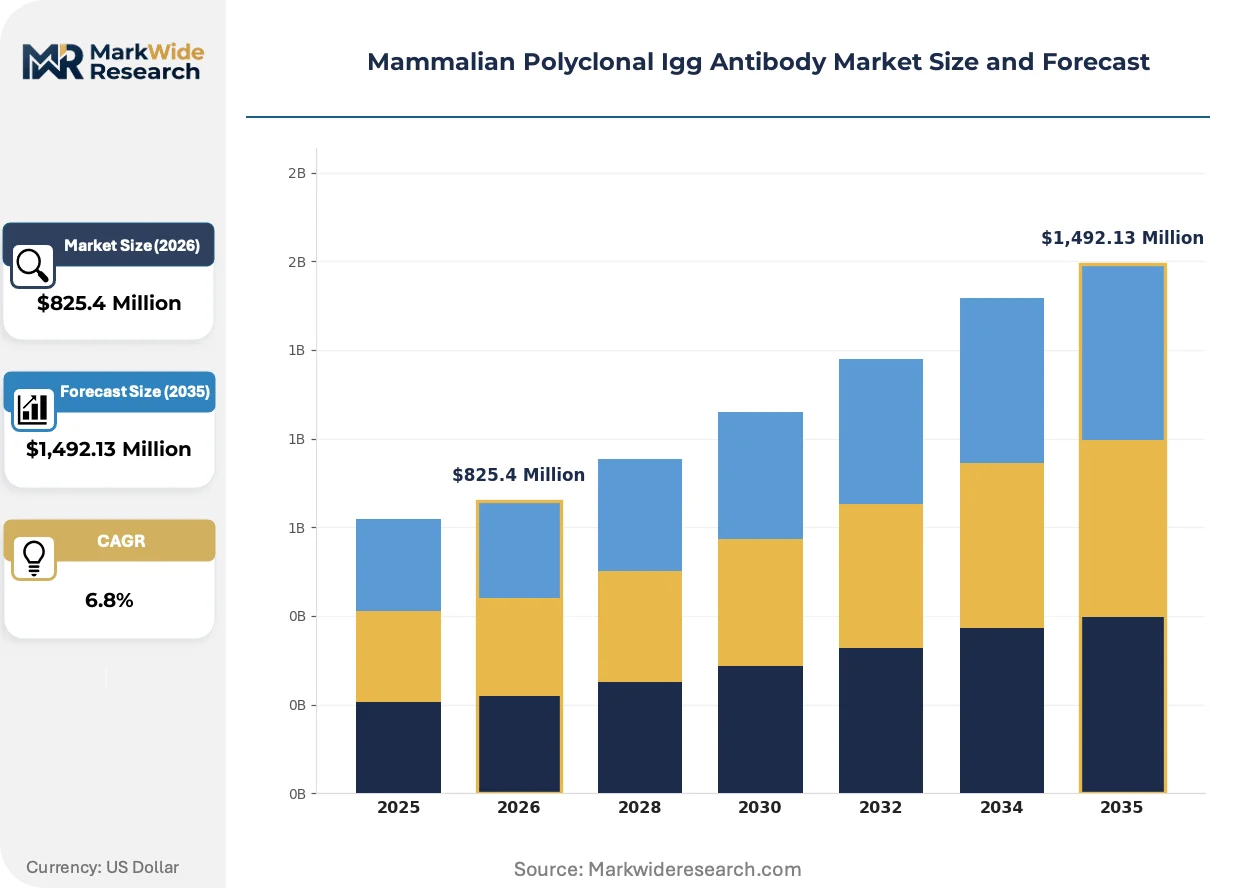
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,492.13 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Research Grade, Diagnostic Grade, Therapeutic Grade, Custom Antibodies Application: Western Blotting, Immunohistochemistry, ELISA, Flow Cytometry End User: Biotechnology Companies, Academic Institutions, Clinical Laboratories, Pharmaceutical Manufacturers Source: Goat, Rabbit, Horse, Sheep |
| Companies Covered | Thermo Fisher Scientific, Abcam plc, Bio-Rad Laboratories, Merck KGaA, Cell Signaling Technology, F. Hoffmann-La Roche Ltd, Santa Cruz Biotechnology, Novartis AG, Geno Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mammalian Polyclonal Igg Antibody Market Strategic Shifts & Innovations
Recombinant validation technologies are compressing the traditional polyclonal antibody development cycle, while regulatory convergence between FDA and EMA frameworks is standardizing quality documentation. These forces are simultaneously elevating technical barriers and consolidating procurement toward qualified suppliers.
Recombinant peptide antigen synthesis is supplanting native protein immunization for high-specificity antibody generation. Contract research organizations serving diagnostic manufacturers are adopting synthetic immunogen platforms at accelerated pace, reducing development timelines from sixteen weeks to eight. This compression is enabling rapid epitope mapping for emerging biomarker targets while eroding the competitive position of legacy serum-based immunization houses.
EMA's incoming In Vitro Diagnostic Regulation implementation is mandating performance study documentation for antibody components used in CE-marked assays. Manufacturers must now submit clinical evidence packages that demonstrate diagnostic accuracy across intended use populations, elevating regulatory affairs expenditure. European diagnostic kit assemblers are responding by consolidating supplier bases to partners with established notified body relationships and pre-submitted technical files.
Consolidated procurement frameworks are displacing spot purchasing for research-grade antibodies. Academic core facilities and institutional purchasing cooperatives are negotiating multi-year supply agreements that bundle volume commitments with dedicated lot reservation privileges. This behavioral shift is most pronounced in United States National Institutes of Health-funded institutions, where grant compliance requirements favor documented supply chain continuity over per-unit cost minimization.
Mammalian Polyclonal Igg Antibody Market Segmentation
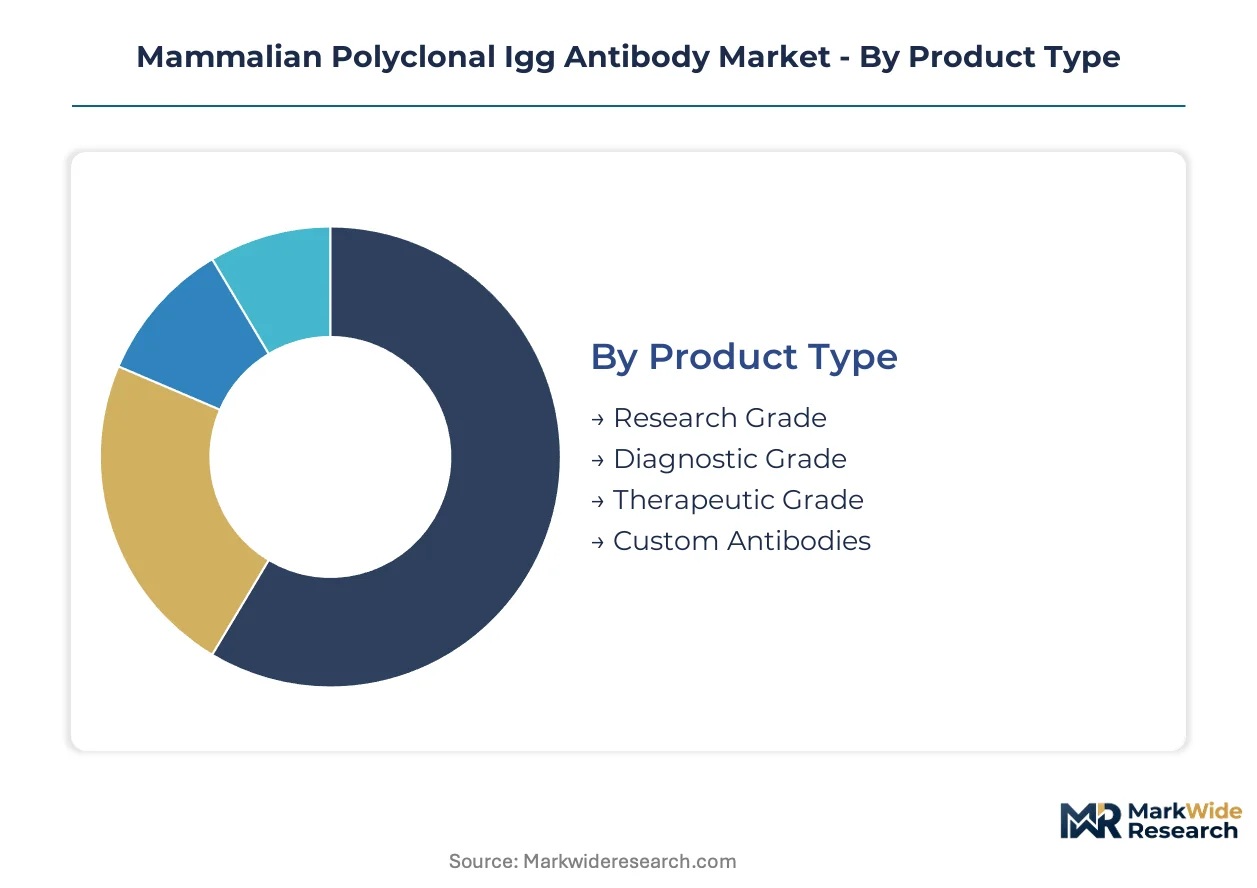
Antibody procurement patterns diverge sharply across certification tiers, with regulatory stringency dictating supplier qualification depth and pricing architecture. Each segment category reflects distinct technical specifications that align with specific workflow requirements in protein detection and diagnostic validation.
Product Type:
Research-grade polyclonals face mounting substitution pressure from recombinant monoclonal alternatives as validation standards tighten across grant-funded institutions.
- Research Grade:Heterogeneous immunoglobulin populations with standard protein A/G purification serve academic discovery programs and early-stage screening. Procurement concentrates in United States National Institutes of Health-funded institutions where grant compliance now favors documented supply chain continuity over per-unit cost minimization.
- Diagnostic Grade:Lot-to-lot consistency documentation and serum traceability protocols satisfy FDA quality system regulations and EMA IVD directive requirements. Clinical laboratories in Germany and the United States anchor demand as dual compliance documentation elevates vendor qualification thresholds.
- Therapeutic Grade:Stringent endotoxin and aggregate specifications support preclinical safety studies.
- Custom Antibodies:Project-specific epitope coverage for novel biologic programs climbs fastest as pharmaceutical manufacturers outsource immunogen design.
Research-grade retains volume leadership; custom antibodies hold the steepest expansion curve.
Application:
Workflow sensitivity requirements determine antibody selection, with signal amplification demands varying across detection platforms.
- Western Blotting:Enhanced chemiluminescence detection exploits polyclonal multi-epitope binding for low-abundance protein visualization. Academic core facilities in the United States sustain procurement volume despite gradual migration to recombinant alternatives.
- Immunohistochemistry:Tissue section staining requires batch-validated specificity against formalin-fixed epitopes. Diagnostic manufacturers in Germany prioritize ISO 13485-certified suppliers for companion diagnostic development.
- ELISA:Sandwich and competitive assay formats depend on paired antibody specificity.
- Flow Cytometry:Fluorophore-conjugated polyclonals enable multi-parameter cell surface marker analysis.
Western blotting retains installed base dominance; immunohistochemistry gains share fastest through companion diagnostic co-development.
End User:
Customer procurement sophistication spans from spot purchasing to multi-year framework agreements with dedicated lot reservation privileges.
- Biotechnology Companies:Preclinical target validation programs demand rapid turnaround custom services with epitope mapping support. Clusters in San Francisco and Boston anchor procurement volume for pre-IND biologic characterization.
- Academic Institutions:Core facility consolidation and cooperative purchasing agreements reshape supplier relationships. United States research universities increasingly negotiate multi-year bundles over transactional spot buying.
- Clinical Laboratories:Regulatory compliance documentation requirements elevate vendor consolidation.
- Pharmaceutical Manufacturers:Integrated antibody supply for biomarker-qualified therapeutic approvals drives strategic partnerships.
Academic institutions retain transaction volume leadership; pharmaceutical manufacturers demonstrate the steepest contract value expansion.
Source:
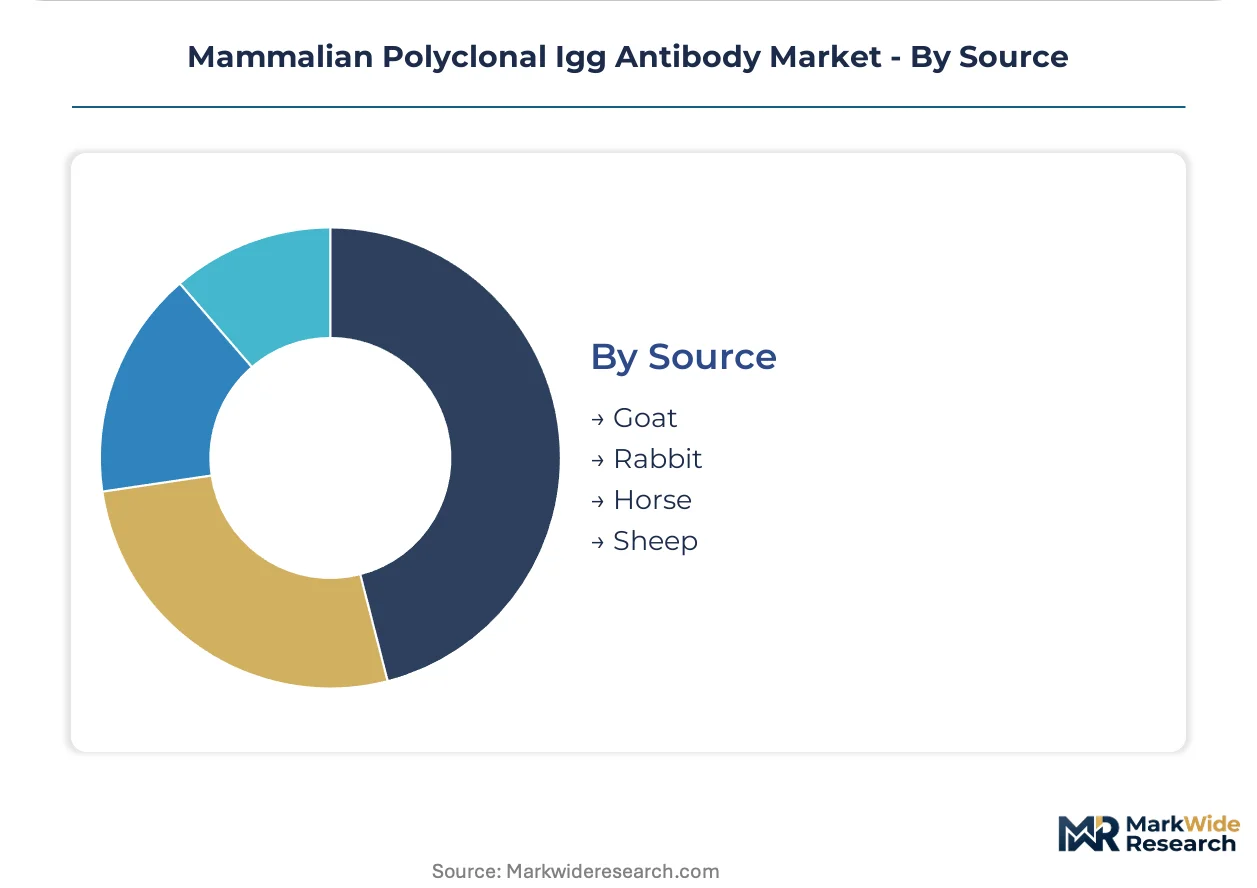
Host animal selection balances immunoglobulin repertoire breadth against serum supply concentration risks.
- Goat:Large-volume antiserum production supports industrial-scale diagnostic reagent manufacturing. Australian and New Zealand biosecurity regulations constrain premium-grade fetal bovine serum availability.
- Rabbit:Robust immune response to small-molecule haptens and phosphopeptide antigens dominates custom antibody generation. Outbred genetic variation complicates reference standard establishment across production lots.
- Horse:Alternative host for toxoid and venom immunization applications.
- Sheep:Cost-efficient large-animal production for bulk reagent supply.
Rabbit retains technical preference for high-specificity applications; goat maintains volume leadership through diagnostic-grade supply scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States demonstrate minimal price elasticity for diagnostic-grade supply, while academic procurement in India and China remains highly sensitive to per-unit cost differentials. This demand-elasticity contrast shapes regional supplier strategies and certification investment thresholds.
United States
NIH-funded institutions and biotechnology clusters in Boston and San Francisco drive premium-grade antibody consumption. FDA quality system regulations mandate traceability documentation that elevates vendor qualification costs. The Greater Boston biopharma corridor anchors custom antibody service demand for preclinical biologic programs.
Germany
Diagnostic manufacturers in Munich and Heidelberg prioritize ISO 13485-certified supply chains for companion diagnostic development. EMA's incoming In Vitro Diagnostic Regulation imposes performance study documentation requirements on antibody components. The Rhine-Main biotech cluster concentrates CE-marked assay development activity.
China
Domestic pharmaceutical manufacturers expand preclinical target validation programs, accelerating project-specific antibody procurement. NMPA pathway harmonization with ISO 13485 frameworks reduces registration friction for international suppliers. Yangtze River Delta biotechnology parks anchor both production partnerships and consumption growth.
Japan
Academic core facilities in Tokyo and Osaka sustain research-grade volume despite gradual migration toward recombinant alternatives. PMDA quality benchmarks for diagnostic-grade supply align with international ISO standards. The Kansai region maintains specialized immunohistochemistry reagent manufacturing infrastructure.
United Kingdom
London and Cambridge-based contract research organizations drive demand for rapid-turnaround custom antibody services. MHRA post-Brexit regulatory frameworks maintain convergence with EMA quality documentation requirements. The Cambridge life sciences cluster concentrates biomarker-qualified therapeutic development partnerships.
Mammalian Polyclonal Igg Antibody Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Consolidated procurement frameworks favor suppliers with established regulatory affairs infrastructure and pre-submitted technical files. Three archetypes dominate: diversified life science conglomerates with upstream serum supply chains, specialized antibody houses with recombinant validation platforms, and regional custom service providers with rapid-turnaround capabilities. Competitive moves concentrate on strategic partnerships for companion diagnostic co-development and geographic expansion through domestic production partnerships in China.
Among diversified life science conglomerates, Thermo Fisher Scientific and Merck KGaA occupy positions anchored by integrated upstream supply chain control. Abcam plc exemplifies the specialized validation-focused archetype, representing the recombinant protocol differentiation strategy. These three entities collectively illustrate how competitive positioning stratifies across certification depth, geographic reach, and technical specialization vectors.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Abcam plc |
| Bio-Rad Laboratories |
| Merck KGaA |
| Cell Signaling Technology |
| F. Hoffmann-La Roche Ltd |
| Santa Cruz Biotechnology |
| Novartis AG |
| Geno Technology |
| Others |
Cost & Logistics Intelligence
Sixteen-week lot-release cycles for custom antibody services compress procurement planning windows and amplify pricing power for manufacturers with captive serum inventories. This temporal constraint binds directly to geographic supply concentration, as diagnostic-grade buyers in Germany and the United States absorb premium markups to secure batch-to-batch consistency documentation.
Pricing Analysis
After-sales revenue from multi-year framework agreements with dedicated lot reservation privileges drives lifetime value for antibody suppliers. Three-tier pricing structure across diagnostic-grade, research-grade, and custom service levels reflects certification depth and serum traceability documentation. Cost compression in research-grade tiers intensifies because recombinant monoclonal alternatives erode spot-purchasing volumes. Academic institutions in India and China exhibit highest price sensitivity, while clinical laboratories in Germany demonstrate minimal elasticity for FDA-compliant supply.
Supply Chain Analysis
Australia and New Zealand anchor premium-grade fetal bovine serum production, constraining global availability through biosecurity-driven export quotas. Manufacturers draw from protein A/G chromatography resins, synthetic immunogen platforms, and outbred rabbit populations to assemble finished reagents. Single-source vulnerability concentrates in serum supply, exposing batch-release schedules to veterinary health certificate aggregation delays. Distribution runs through cold-chain logistics networks serving biotechnology clusters in the United States, Germany, and China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
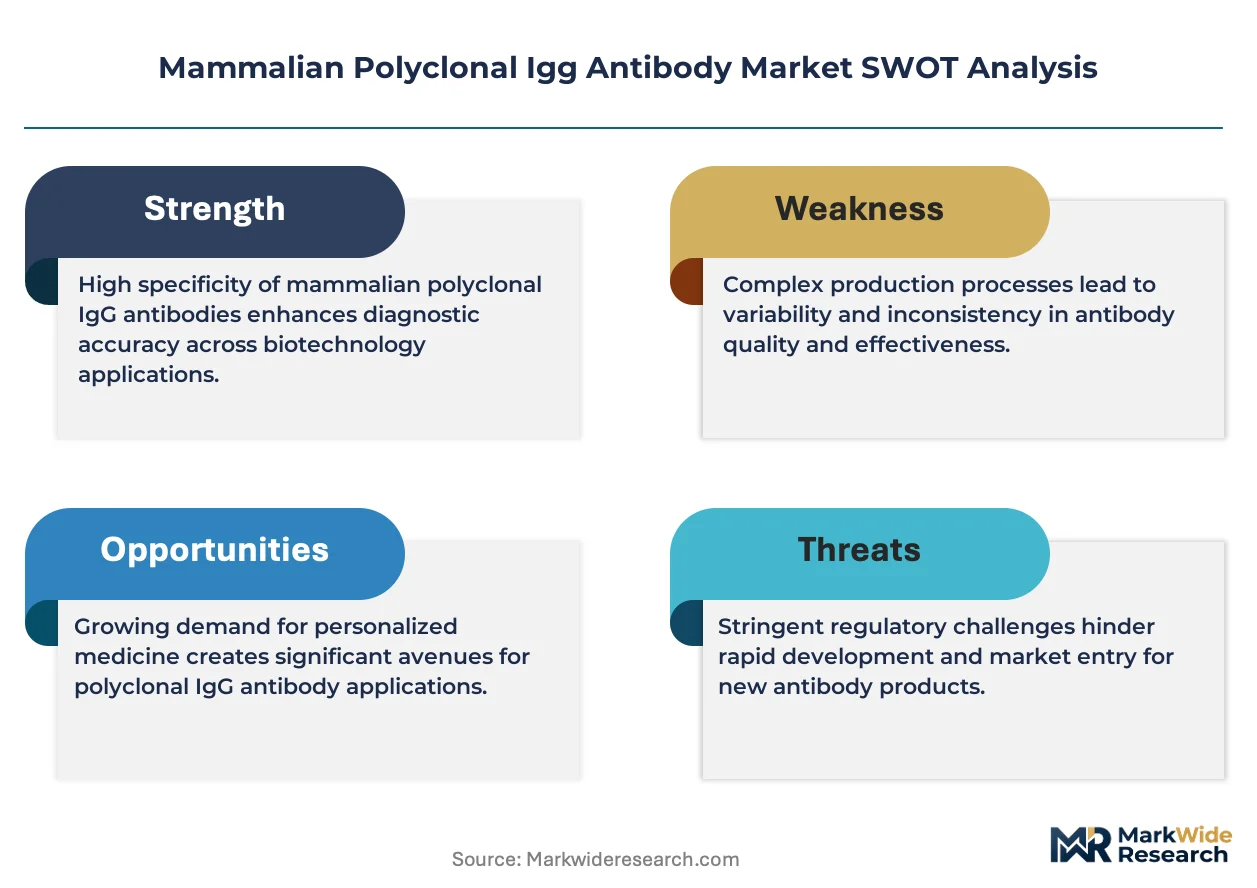
This market functions as a defensive-moat structure where regulatory entrenchment—specifically FDA quality system documentation and EMA IVD directive compliance—creates switching costs that lock clinical laboratories into qualified supplier relationships.
For Market Incumbents: Consolidate serum supply relationships through backward integration into donor herd management, insulating against Australian and New Zealand export quota volatility. Deepen ISO 13485 certification investments to capture EMA incoming IVD regulation compliance premiums before mid-tier competitors amortize validation infrastructure. Recombinant monoclonal substitution threatens research-grade polyclonal volumes; defend through bundled custom service offerings with rapid-turnaround guarantees. For New Entrants and Emerging Players: Lead with synthetic immunogen platform specialization targeting eight-week development timelines for preclinical target validation programs. White-space opportunity concentrates in China's Yangtze River Delta biotechnology parks, where NMPA pathway harmonization reduces registration friction for domestic production partnerships. Companion diagnostic co-development contracts offer the most penetrable entry vector, embedding suppliers into pharmaceutical clinical trial design phases before biomarker qualification locks incumbent relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across recombinant validation infrastructure as EMA performance study documentation mandates elevate regulatory affairs expenditure. Long-term viability favors specialized antibody houses with established notified body relationships over diversified life science conglomerates facing serum supply concentration risks. Acquisition target archetype: regional custom service providers with rapid-turnaround capabilities and pre-submitted technical files. Signal to watch: consolidation of academic core facility purchasing cooperatives toward multi-year framework agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | Antibody suppliers embedding into Roche and Thermo Fisher clinical trial partnerships capture long-term biomarker-qualified supply agreements. |
| Serum Supply Backward Integration | Captive donor herd operations in Australia reduce biosecurity-driven export quota exposure for diagnostic-grade manufacturers. |
| Synthetic Immunogen Platform Deployment | Eight-week development cycles compress traditional sixteen-week polyclonal timelines, eroding legacy serum-based immunization house positions. |
| EMA IVD Regulation Pre-Compliance | Pre-submitted technical files with notified body relationships accelerate CE-marked assay component approvals for European diagnostic kit assemblers. |
| China Domestic Production Partnership | NMPA pathway harmonization with ISO 13485 frameworks reduces registration friction for international suppliers establishing Yangtze River Delta facilities. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA quality system filings, EMA IVD directive guidance documents, and ISO 13485 certification databases. Interviews with regulatory affairs leads at diagnostic manufacturers, serum supply procurement directors, and academic core facility managers informed supply chain concentration assessments. Secondary validation drew from customs trade data for fetal bovine serum imports, ClinicalTrials.gov antibody-dependent assay registrations, and notified body technical file submissions. Bottom-up segment sizing triangulated against top-down biotechnology cluster expenditure estimates.
Segmentation dimensions modeled include product certification tier, application workflow, end-user procurement sophistication, and host animal source across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating grant funding trajectories at United States National Institutes of Health-funded institutions and pharmaceutical preclinical biologic program pipelines. Industry-specific forecast inputs captured protein A/G chromatography platform adoption rates and recombinant peptide antigen synthesis penetration in contract research organization service offerings.
The analysis sits within stated boundaries; outcomes outside sustained FDA-EMA regulatory convergence or prolonged Australian biosecurity restrictions would require recalibration. Forecasts reflect documented assumptions regarding serum supply availability and diagnostic laboratory vendor consolidation trajectories. Recalibration cycles align with material shifts in EMA IVD regulation implementation timelines and NMPA pathway harmonization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Daptomycin Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Purified Protein Derivative Market
Biopharmaceuticals
Latin America G-CSF/ PEG-G-CSF Market
Biopharmaceuticals
Antibiotics Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Ocular Tuberculosis Therapeutics Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Peptide Antibiotics Market