
 Global Custom Antibody Market | 2026-2036
Global Custom Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
Global Custom Antibody Market Foresight
Recombinant production service tiers is consolidating around platform-access contracts that bundle cell-line development with downstream purification. Thermo Fisher Scientific Inc. leverages its integrated instrument-reagent-service ecosystem to lock in multi-year pharmaceutical partnerships. GenScript anchors Asia-Pacific custom synthesis demand through automated peptide-to-antibody workflows. Abcam plc differentiates by curating recombinant rabbit monoclonal catalogs with batch-traceable quality documentation.
Custom antibodies are affinity proteins engineered to bind specific antigen epitopes with defined specificity, typically produced through hybridoma fusion, phage display library panning, or single B cell cloning at purity grades exceeding 95% for critical assay applications. Their primary purpose centers on enabling quantitative detection, therapeutic target validation, and diagnostic assay standardization across life sciences workflows. Monoclonal antibodies command the largest revenue share due to their renewable supply and batch-to-batch consistency requirements in regulated diagnostic settings. Recombinant antibodies are displacing traditional hybridoma-derived products in therapeutic discovery pipelines because recombinant platforms eliminate animal-dependency concerns and accelerate humanization timelines. Phage display technology leads production-method growth as it enables in vitro selection against toxic or non-immunogenic targets inaccessible to conventional immunization.
FDA biologics licensing requirements and EMA's MDR framework for companion diagnostics shape product validation standards that custom antibody suppliers must satisfy before commercial release. China's NMPA has tightened biosimilar analytical comparability guidelines, forcing foreign suppliers to establish local quality-testing partnerships or risk exclusion from domestic procurement. ISO 13485 certification and WHO prequalification pathways increasingly determine market access for antibodies destined for infectious disease diagnostics in low-resource settings. Stakeholders must monitor convergence between FDA's quality attribute assessment criteria and EMA's evolving expectations for analytical method robustness as dual-jurisdiction filings become standard for oncology companion diagnostic programs.
Market Dynamics
Recombinant antibody production platforms are compressing development timelines from months to weeks, forcing hybridoma-dependent suppliers to retool facilities or cede therapeutic discovery contracts to recombinant-native competitors.
Growth Catalysts
- EMA's MDR framework for companion diagnostics:Stringent batch-traceability requirements for IVD-certified antibodies pull monoclonal demand from clinical research into regulated diagnostic manufacturing.
- Phage display technology advances:In vitro selection against toxic or non-immunogenic antigens expands addressable target space beyond conventional immunization limits.
- Biopharmaceutical R&D concentration in Boston-Cambridge, Basel, and Shanghai:Geographic clustering of precision therapeutic programs creates localized demand density for high-throughput custom synthesis services.
Market Restraints
- Fetal bovine serum price volatility:Hybridoma culture media input costs fluctuate with agricultural commodity cycles, squeezing margin on traditional production methods.
- Chinese NMPA biosimilar comparability guidelines:Foreign suppliers without local quality-testing partnerships face procurement exclusion from domestic biopharma supply chains.
- Single B cell cloning throughput limitations:Low cell recovery rates from human donor samples constrain native human antibody discovery programs.
Strategic Opportunities
- India's CDSCO biologics pathway expansion:Streamlined investigational new drug approvals for imported reference standards create entry points for ISO 13485-certified antibody suppliers.
- AI-guided epitope prediction convergence with phage display:Machine learning-informed library design reduces panning rounds and accelerates lead identification timelines.
- WHO prequalification for infectious disease diagnostics:Certification tailwind opens procurement channels for HIV, malaria, and tuberculosis assay antibodies in Sub-Saharan African public health programs.
Industry Challenges
- Mammalian cell culture scale-up expertise scarcity:Shortage of process engineers capable of translating research-grade transient expression to GMP-compliant stable cell-line manufacturing.
- Dual-jurisdiction FDA-EMA filing complexity:Divergent quality attribute assessment criteria for oncology companion diagnostic antibodies extend validation timelines and duplicate analytical development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Custom Antibody Market |
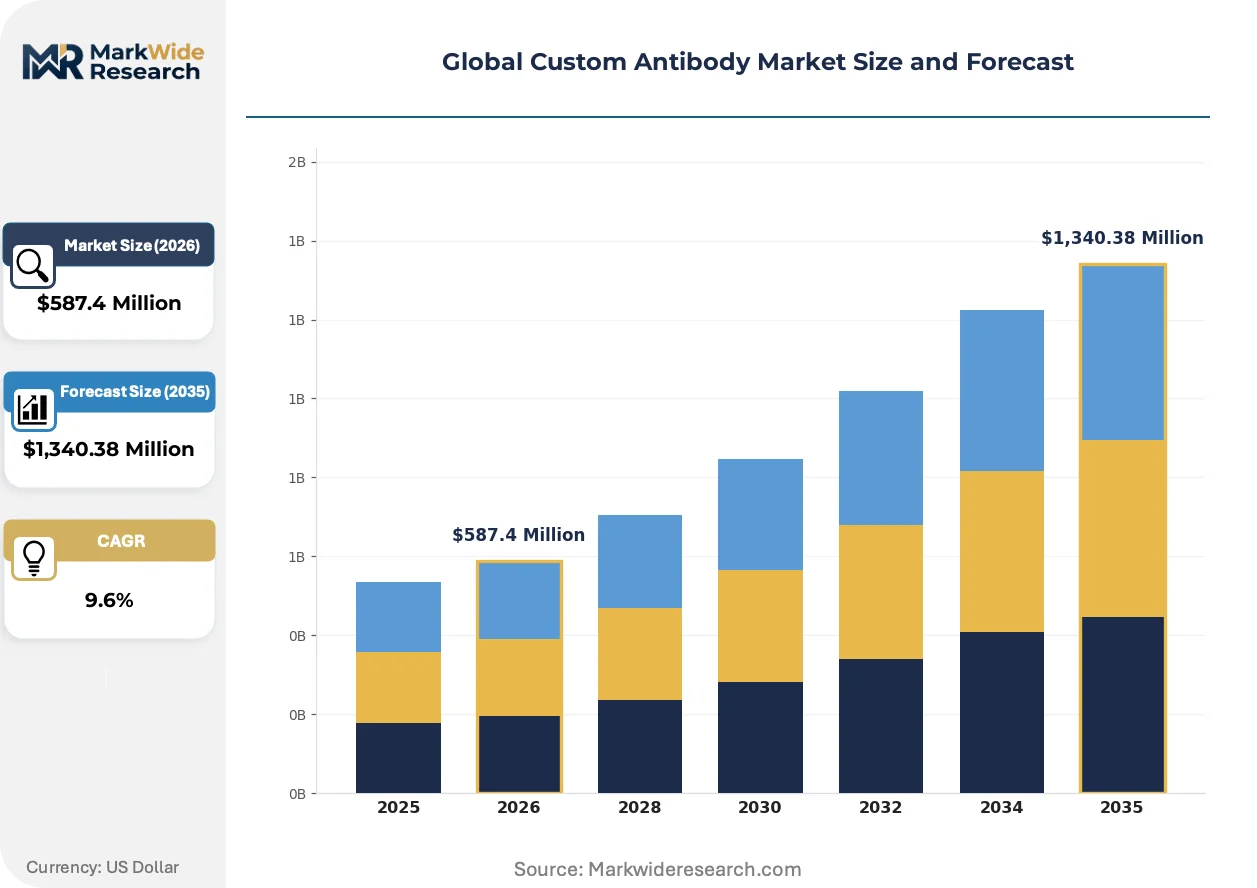
| Market Size in 2026 | $587.4 Million |
| Market Size in 2035 | $1,340.38 Million |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Polyclonal Antibodies, Recombinant Antibodies, Antibody Fragments, Bispecific Antibodies Application: Biomarker Discovery, Immunoassays, Therapeutics, Diagnostic Research, Vaccine Development End User: Pharmaceutical Companies, Biotechnology Firms, Academic Research Institutes, Contract Research Organizations, Diagnostic Laboratories Production Technology: Hybridoma Technology, Phage Display, Transgenic Animals, Yeast Display, Single B Cell Cloning |
| Companies Covered | Thermo Fisher Scientific Inc., GenScript, Bio-Rad Laboratories, Inc., Abcam plc, Merck KGaA, Agilent Technologies Inc., Creative Biolabs, Kaneka Eurogentec S.A., Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Custom Antibody Market Shifts & Advancements
Automation and platform standardization are reshaping competitive economics in custom antibody supply, compressing price points for routine reagents while creating premium tiers for complex, time-constrained therapeutic discovery programs.
Single-use bioreactor systems for transient expression are consolidating recombinant antibody production around modular, portable manufacturing footprints. Contract research organizations in Germany and the United States are adopting these systems to offer multi-week turnaround guarantees for preclinical candidate material. The technology is consolidating project economics by eliminating stainless-steel facility validation overhead and enabling distributed production closer to biopharma clusters.
REACH substance registration requirements for antibody-drug conjugate linker chemistries are tightening supply chain documentation obligations for European therapeutic developers. ECHA compliance costs now factor into early-stage supplier selection, favoring partners with established regulatory dossier capabilities. ADC programs targeting solid tumor indications face the steepest compliance burden as they combine biologic and small-molecule regulatory pathways.
Platform-access contracts bundling cell-line development with downstream purification are displacing transactional, per-project pricing in large pharmaceutical procurement. Biopharma buyers in the United States and Switzerland are consolidating vendor relationships to secure capacity allocation and batch-to-batch consistency guarantees. This shift concentrates revenue with integrated service providers capable of end-to-end workflow execution.
Global Custom Antibody Market Segmentation
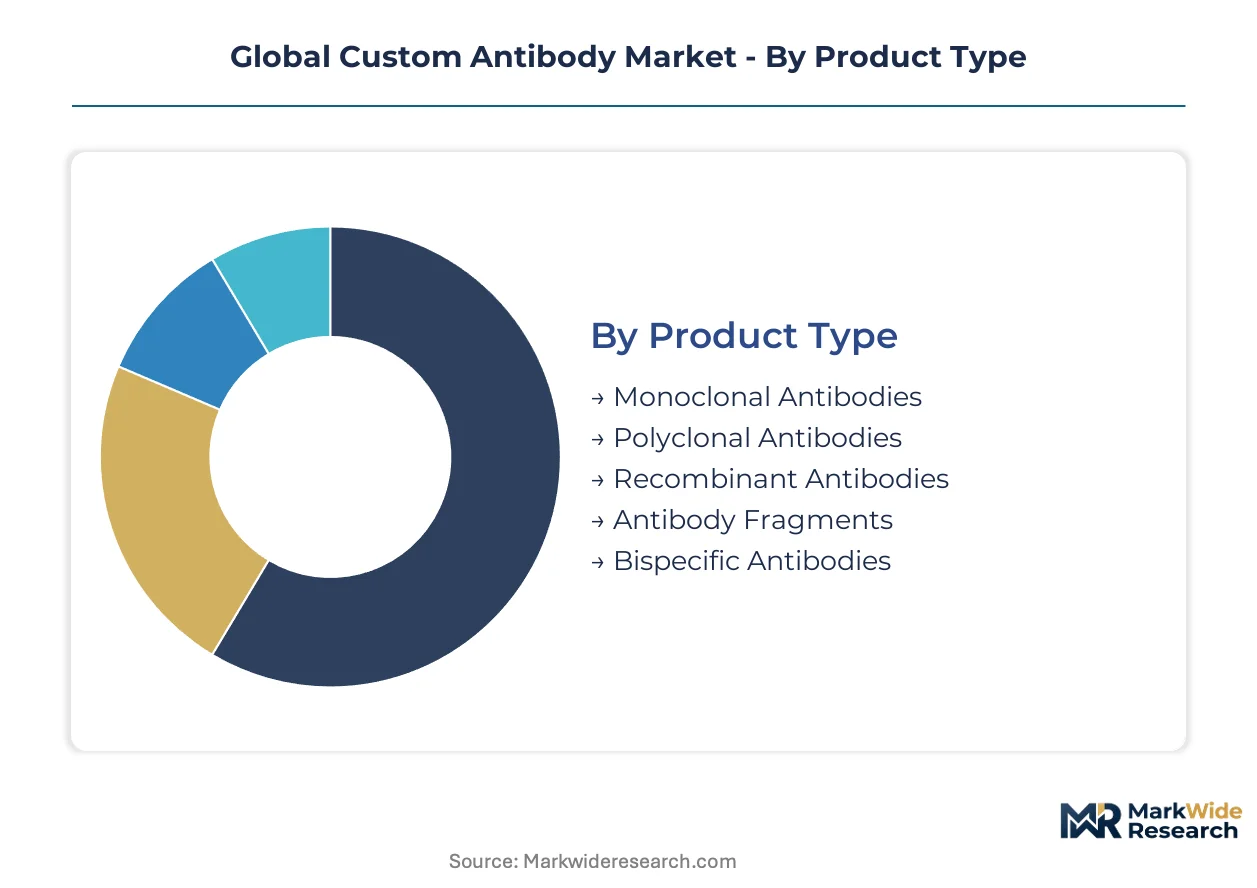
Segmentation in the Global Custom Antibody Market reveals how buyer priorities diverge across therapeutic discovery, diagnostic manufacturing, and academic research workflows. Product specifications, regulatory pathways, and production timelines vary sharply by end-use, forcing suppliers to maintain parallel capability portfolios.
Product Type:
Buyers select antibody formats based on batch consistency requirements, target specificity demands, and regulatory documentation burdens for their intended application.
- Monoclonal Antibodies:Derived from single B-cell clones with identical epitope specificity, these antibodies deliver renewable supply chains essential for FDA-validated diagnostic kits. Pharmaceutical procurement in the United States and Germany concentrates demand here due to stringent batch-traceability mandates for companion diagnostic programs.
- Recombinant Antibodies:Engineered through synthetic gene sequences and expressed in mammalian or microbial systems, these products eliminate animal-dependency concerns and compress humanization timelines for therapeutic pipelines. Biopharmaceutical companies in Basel and Boston-Cambridge clusters are displacing traditional hybridoma procurement with recombinant platform contracts.
- Polyclonal Antibodies:Heterogeneous antibody populations raised against multiple epitopes, valued for robust signal amplification in immunohistochemistry applications.
- Antibody Fragments:Engineered Fabs, scFvs, and VHH domains offering enhanced tissue penetration for imaging and therapeutic conjugation programs.
- Bispecific Antibodies:Dual-targeting constructs enabling simultaneous engagement of tumor antigens and immune effector cells in oncology drug development.
Volume sits with Monoclonal Antibodies; growth tilts toward Recombinant Antibodies.
Application:
Application selection determines purity grade requirements, with therapeutic and diagnostic manufacturing demanding GMP-compliant production while research applications tolerate research-grade specifications.
- Therapeutics:Full-length antibodies and engineered variants for precision medicine programs require extensive developability assessment, including aggregation propensity and immunogenicity risk profiling. Contract manufacturers in Switzerland and the United States are building dedicated capacity to serve biopharma clients with accelerated IND timelines.
- Immunoassays:Quantitative detection systems for clinical diagnostics and research screening depend on high-affinity capture-detection antibody pairs with validated cross-reactivity profiles. China's NMPA tightening of IVD registration standards is pulling demand toward monoclonal formats with documented batch consistency.
- Biomarker Discovery:Proteomics and genomics research programs seeking novel disease signatures drive demand for high-content screening antibody libraries.
- Diagnostic Research:Early-stage assay development for infectious disease and oncology panels requires flexible, small-volume antibody sourcing.
- Vaccine Development:Neutralizing antibody characterization and epitope mapping for immunogen design.
Therapeutics commands the largest revenue commitment; Immunoassays is expanding most quickly under EMA MDR and FDA diagnostic validation pressures.
End User:
Customer type shapes procurement structure, with large pharmaceutical buyers negotiating platform-access contracts while academic institutes transact on per-project terms.
- Pharmaceutical Companies:Integrated drug developers with internal biologics pipelines source custom antibodies through multi-year partnerships bundling cell-line development, transient expression, and GMP manufacturing. Thermo Fisher Scientific and GenScript have consolidated relationships with top-20 global pharma accounts through capacity reservation agreements.
- Contract Research Organizations:Service providers to biopharma clients require rapid-turnaround, research-grade antibody production with flexible specification adjustments. German and United States CROs are adopting single-use bioreactor systems to guarantee multi-week delivery timelines for preclinical programs.
- Biotechnology Firms:Venture-funded precision therapeutic developers with outsourced manufacturing models.
- Academic Research Institutes:University and government laboratories with grant-funded, small-batch requirements and price-sensitive procurement.
- Diagnostic Laboratories:Clinical reference labs and IVD manufacturers seeking validated antibody pairs for assay commercialization.
Procurement volume concentrates with Pharmaceutical Companies; Contract Research Organizations are gaining share fastest as biopharma outsourcing deepens.
Production Technology:
Technology selection balances timeline compression against target accessibility, with in vitro methods expanding addressable antigen space beyond immunization-tolerable targets.
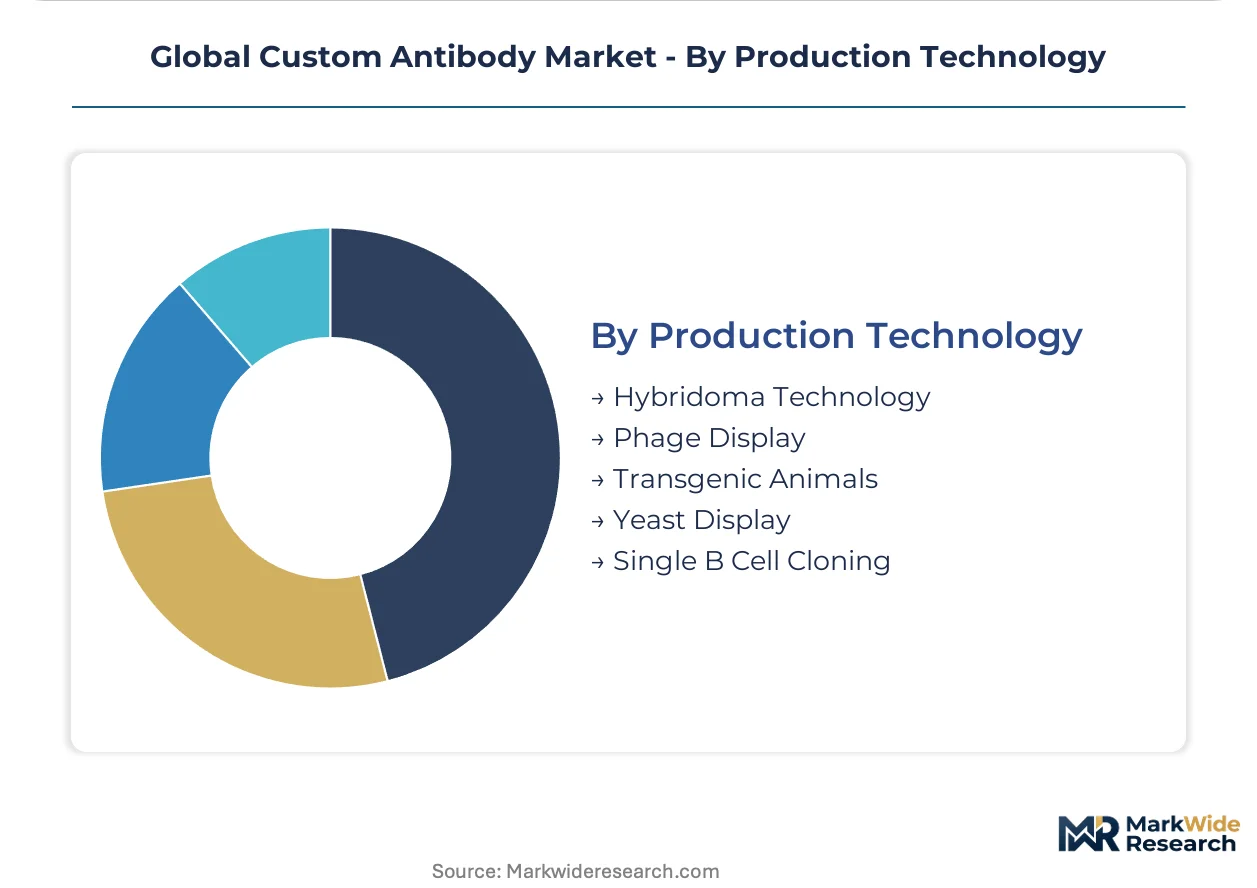
- Phage Display:In vitro selection from vast combinatorial libraries enables antibody generation against toxic, non-immunogenic, or conserved epitopes inaccessible to animal immunization. Platform advances in library design and next-generation sequencing are compressing lead identification from months to weeks in United States and United Kingdom discovery programs.
- Hybridoma Technology:Mouse B-cell fusion with myeloma partners remains the workhorse for high-affinity, well-characterized monoclonals with extensive regulatory precedent. Fetal bovine serum price volatility and animal welfare concerns are constraining expansion in European markets under REACH and ECHA pressure.
- Single B Cell Cloning:Direct recovery of antibody genes from sorted human B cells enables native human antibody discovery without subsequent humanization engineering.
- Transgenic Animals:Humanized mouse and rat platforms producing fully human antibodies through endogenous immune mechanisms.
- Yeast Display:Eukaryotic expression system offering glycosylation patterns and selection stringency intermediate between bacterial and mammalian platforms.
Established volume rests with Hybridoma Technology; Phage Display is climbing the fastest as toxic target programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany, Switzerland, and the United States while consumption concentrates in biopharma hubs across all three markets plus China. Hybridoma and recombinant manufacturing gravitate toward established life sciences infrastructure. Demand fragmentation follows regulatory approval pathways and therapeutic discovery funding density.
United States
FDA biologics licensing drives monoclonal antibody validation standards for companion diagnostic programs. The agency's quality attribute assessment criteria shape supplier documentation requirements. Boston-Cambridge and San Francisco Bay Area biotech clusters generate concentrated procurement for high-throughput custom synthesis services.
Germany
EMA's MDR framework mandates batch-traceability for IVD-certified antibodies entering regulated diagnostic manufacturing. REACH substance registration requirements tighten supply chain documentation for antibody-drug conjugate linker chemistries. Basel-adjacent facilities in Baden-Württemberg and North Rhine-Westphalia pharmaceutical corridors anchor European recombinant production capacity.
China
NMPA biosimilar comparability guidelines force foreign suppliers to establish local quality-testing partnerships or face domestic procurement exclusion. Shanghai and Suzhou biotech parks concentrate precision therapeutic R&D with outsourced antibody discovery demand. Government funding for domestic biologics capabilities accelerates local supplier technical maturation.
Switzerland
Swissmedic alignment with EMA standards enables seamless dual-jurisdiction filing for oncology companion diagnostic antibodies. Roche and Novartis therapeutic pipelines generate captive and outsourced monoclonal demand. Basel-Zurich corridor facilities specialize in GMP-compliant stable cell-line manufacturing for IND-stage programs.
United Kingdom
MHRA post-Brexit regulatory autonomy creates parallel validation requirements for EU-exporting antibody suppliers. London-Oxford-Cambridge golden triangle concentrates academic and venture-funded discovery programs. Phage display technology providers cluster around Oxford and Cambridge to serve toxic-target therapeutic discovery contracts.
Global Custom Antibody Market Competitive Landscape
Top-tier vendors anchor integrated platform-access contracts, while mid-tier specialists compete on turnaround speed and niche target expertise. The vendor base stratifies across three tiers: diversified life sciences conglomerates with instrument-reagent-service ecosystems, recombinant-native platform specialists, and hybridoma-dependent legacy suppliers retooling for mammalian cell culture. Dominant competitive moves include capacity reservation agreements locking in multi-year pharmaceutical partnerships and single-use bioreactor adoption for distributed production near biopharma clusters.
Among diversified conglomerates, Thermo Fisher Scientific Inc. exemplifies the integrated ecosystem archetype spanning instruments through GMP manufacturing services. GenScript anchors Asia-Pacific demand through automated synthesis workflows. Abcam plc represents the catalog-curation specialist model with batch-traceable quality documentation. These three occupy distinct positioning vectors rather than direct overlap, reducing price-only competition in premium therapeutic discovery segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| GenScript |
| Bio-Rad Laboratories, Inc. |
| Abcam plc |
| Merck KGaA |
| Agilent Technologies Inc. |
| Creative Biolabs |
| Kaneka Eurogentec S.A. |
| Danaher Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between GMP-compliant therapeutic antibodies and research-grade reagents creates parallel supply ecosystems with distinct margin profiles and procurement workflows. Premium-tier buyers in Basel and Boston-Cambridge clusters negotiate platform-access contracts bundling cell-line development with downstream purification, while academic institutes transact on per-project terms with minimal batch-traceability documentation. This bifurcation concentrates pricing power with integrated service providers capable of end-to-end execution, forcing hybridoma-dependent suppliers into commodity positioning.
Pricing Analysis
Margin tightening in research-grade segments reflects single-use bioreactor adoption compressing turnaround timelines from months to weeks. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated therapeutic candidates from research-grade catalog products and bulk polyclonal sera. Cost-down pressure on hybridoma-derived monoclonals accelerates because fetal bovine serum price volatility squeezes traditional production economics. Academic research institutes exhibit highest price sensitivity; pharmaceutical companies with IND-stage programs demonstrate lowest sensitivity due to batch-consistency requirements.
Supply Chain Analysis
ISO 13485 certification and WHO prequalification pathways gate market access for antibodies destined for infectious disease diagnostics in low-resource settings. Manufacturing concentrates in Germany, Switzerland, and the United States where GMP-compliant stable cell-line expertise clusters around Basel-Zurich and Boston-Cambridge corridors. Raw material dependencies include fetal bovine serum for hybridoma culture, recombinant protein expression media, and antibody-drug conjugate linker chemistries subject to REACH registration. Single-source vulnerability sits with Chinese NMPA-mandated local quality-testing partnerships for foreign suppliers. Distribution runs through direct pharmaceutical procurement contracts and CRO service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into mammalian cell culture scale-up expertise represents the decisive competitive lever as recombinant platforms displace hybridoma-dependent production. Players securing captive GMP manufacturing capacity and regulatory dossier capabilities will consolidate multi-year pharmaceutical partnerships.
For Market Incumbents: To counter recombinant-native competitors compressing development timelines, hybridoma-dependent suppliers must retool facilities for transient expression platforms or cede therapeutic discovery contracts entirely. Incumbents should prioritize capacity reservation agreements locking in top-20 global pharma accounts through integrated instrument-reagent-service ecosystems. FDA-EMA dual-jurisdiction filing expertise offers defensive moat against mid-tier specialists lacking regulatory infrastructure. For New Entrants and Emerging Players: Venture-funded biotechnology firms with outsourced manufacturing models represent the most penetrable buyer archetype for recombinant-native platform specialists. White-space opportunities concentrate in AI-guided epitope prediction convergence with phage display, reducing panning rounds for toxic-target programs. India's CDSCO biologics pathway expansion creates geographic entry point for ISO 13485-certified suppliers. Go-to-market positioning should emphasize multi-week turnaround guarantees for preclinical candidate material using single-use bioreactor systems. For Investors and Strategic Acquirers: Re-rating potential sits with recombinant-native platform specialists given EMA MDR and FDA diagnostic validation pressures pulling monoclonal demand into regulated manufacturing. Long-term viability over the next decade hinges on end-to-end workflow execution capabilities spanning cell-line development through GMP manufacturing. Acquisition targets should demonstrate established regulatory dossier capabilities for ADC linker chemistries under REACH. Signal to watch is convergence between FDA quality attribute assessment criteria and EMA analytical method robustness expectations.| Strategic Initiative | Industry Significance |
|---|---|
| Platform-Access Contract Expansion | Multi-year pharmaceutical partnerships bundle cell-line development with downstream purification capacity guarantees. |
| Single-Use Bioreactor Adoption | Modular manufacturing footprints enable distributed production near Boston-Cambridge and Basel biopharma clusters. |
| AI-Guided Epitope Prediction Integration | Machine learning-informed library design accelerates lead identification timelines for toxic-target therapeutic programs. |
| WHO Prequalification Pathway Pursuit | Certification opens procurement channels for HIV, malaria, and tuberculosis assay antibodies in Sub-Saharan Africa. |
| Dual-Jurisdiction Regulatory Infrastructure | FDA-EMA filing expertise reduces validation timeline duplication for oncology companion diagnostic antibodies. |
Research Methodology
Independent corroboration across primary interviews with drug development executives, regulatory affairs leads, and CRO procurement managers underwrites the qualitative findings. Secondary validation draws from FDA biologics licensing records, EMA MDR submissions, ClinicalTrials.gov antibody program listings, and ISO 13485 certification databases. Bottom-up triangulation across production technology adoption rates and top-down validation against therapeutic pipeline funding density ensures segmentation integrity.
Rate-of-change decomposition across the analysis window segments volume and value trajectories by antibody format, application workflow, end-user procurement structure, and production technology platform. CAGRs derive from modeled adoption curves for phage display versus hybridoma technology, regulatory filing pathway throughput assumptions, and geographic biopharma R&D concentration indices. Forecast inputs include single B cell cloning throughput improvements and NMPA biosimilar comparability guideline enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to mammalian cell culture scale-up expertise scarcity and REACH substance registration cost inflation for ADC programs. A model refresh is warranted upon material change in FDA-EMA quality attribute assessment criteria convergence or Chinese NMPA local partnership mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Antibodies Contract Manufacturing Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Biotech API Manufacturing Services Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Asia-Pacific Biotechnology Market