
 In Silico Protein Design Market | 2026-2036
In Silico Protein Design Market Size, Share, and Industry Trends Forecast 2026-2036
In Silico Protein Design Market Insights
Project finance and cloud-based subscription licensing is rewriting competitive entry dynamics in in silico protein design, lowering capital barriers for biotechnology startups and mid-tier research organizations. Schrödinger, Inc. leverages its physics-based simulation platform to anchor long-term partnerships with pharmaceutical clients across multiple therapeutic areas. Generate Biomedicines sustains generative AI capabilities that differentiate its approach to de novo protein generation. Arzeda specializes in industrial enzyme design, occupying a distinct niche between therapeutics and sustainable manufacturing applications.
In silico protein design encompasses computational methods that predict, model, and engineer amino acid sequences to achieve desired three-dimensional structures and biological functions, typically employing molecular dynamics simulations, Rosetta-based energy functions, or transformer neural networks trained on evolutionary sequence data. The discipline serves primarily to reduce experimental screening burdens in drug discovery and to create novel biocatalysts for industrial processes. Drug discovery applications lead current commercial deployment, while industrial enzymes represent the fastest-growing segment as chemical manufacturers pursue greener process chemistry. Cloud-based solutions capture expanding margin pools by converting perpetual licenses into recurring revenue streams with embedded computational infrastructure.
FDA oversight of computational drug design tools under evolving software-as-medical-device frameworks shapes validation requirements for platforms intended to guide regulatory submissions. The EPA and EMA both influence industrial enzyme deployment through emissions and biocontainment standards that determine market access for engineered catalysts. ISO quality management standards and OECD principles for computational toxicology further structure how platform developers document model reliability and prediction uncertainty. Stakeholders must monitor how regulatory bodies reconcile traditional experimental validation with acceptance of purely computational evidence packages.
Market Dynamics
Generative AI architectures trained on protein structure databases are compressing design timelines from months to weeks, forcing platform developers to recalibrate pricing models and partnership structures around computational throughput rather than per-project fees.
Growth Catalysts
- FDA software-as-medical-device frameworks:Evolving guidance for computational drug design tools creates regulatory clarity that accelerates pharmaceutical adoption of in silico platforms for IND-enabling studies.
- Industrial enzyme demand:Chemical manufacturers pursuing greener process chemistry expand contracts for engineered biocatalysts that reduce solvent use and energy consumption in pharmaceutical and agrochemical synthesis.
- Cloud infrastructure maturation:Elastic GPU clusters and specialized AI accelerators lower capital barriers for mid-tier biotechnology startups seeking molecular dynamics simulation capacity.
Market Restraints
- Validation cost structure:Experimental confirmation of computational predictions through X-ray crystallography and cryo-EM remains mandatory, adding substantial wet-lab expenditure to every design cycle.
- Talent concentration risk:Deep learning specialists with protein science domain expertise cluster near Boston and San Francisco, creating geographic hiring bottlenecks for platform developers elsewhere.
- EPA biocontainment standards:Engineered industrial enzymes face extended safety review timelines that delay commercial deployment and compress margin windows for catalyst developers.
Strategic Opportunities
- India contract research expansion:CDSCO-aligned bioinformatics service providers in Hyderabad and Bengaluru offer cost-advantaged computational screening capacity for Western pharmaceutical sponsors.
- EU Green Deal chemistry mandates:REACH-regulated manufacturers face binding emissions reduction targets that create procurement pull for enzymatic process alternatives to petrochemical routes.
- AlphaFold structure database convergence:Integration of open-access predicted structures with proprietary force fields enables hybrid physics-AI platforms that differentiate on accuracy benchmarks.
Industry Challenges
- Cross-functional talent gaps:Teams combining structural biology, machine learning engineering, and therapeutic domain expertise remain scarce, delaying platform scaling and client onboarding.
- ISO 9001 documentation burdens:Quality management certification for computational toxicology predictions requires extensive model validation protocols that extend sales cycles with risk-averse pharmaceutical procurement departments.
- Legacy ELN integration friction:In silico platforms must interface with established electronic laboratory notebook systems, creating API maintenance overhead and customization costs that erode SaaS margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Silico Protein Design Market |
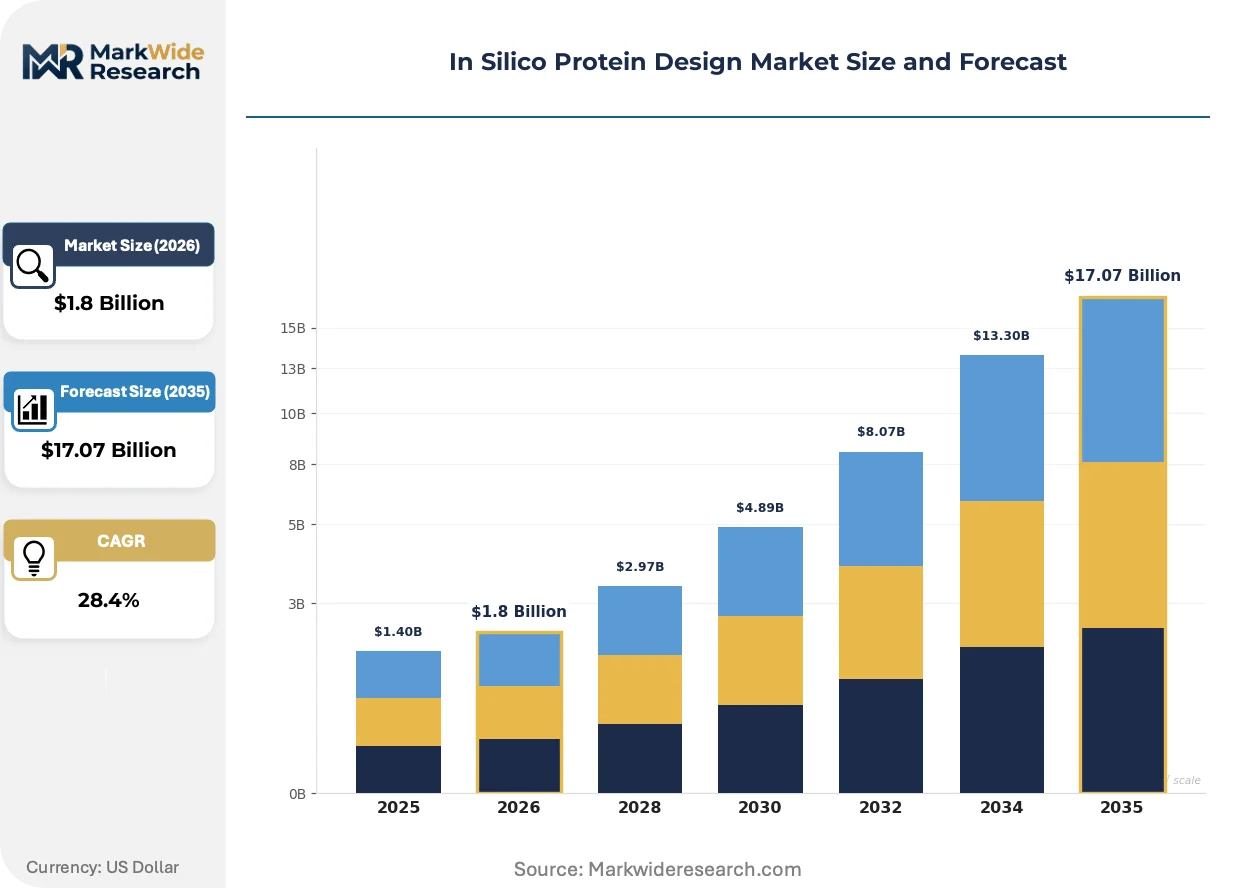
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Simulation Software, Design Tools, Computational Frameworks, Algorithm Platforms Application: Drug Discovery, Vaccine Development, Industrial Enzymes, Therapeutic Proteins End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Organizations Solution: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, Consulting Services |
| Companies Covered | Schrödinger, Inc., Biovia (Dassault Systèmes), Insilico Medicine, Generate Biomedicines, Arzeda, Chemical Computing Group ULC, Profluent, Cradle, Absci, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Silico Protein Design Market Trends and Innovations
Transformer neural networks trained on evolutionary sequence data are displacing traditional Rosetta-based energy functions as the dominant computational paradigm, reshaping how platform developers allocate R&D resources and structure scientific teams.
Physics-based molecular dynamics simulation is migrating from high-performance computing clusters to distributed cloud architectures with specialized AI accelerators. Mid-sized biotechnology companies now access nanosecond-scale trajectory calculations without capital investment in on-premise GPU farms. This migration from captive infrastructure to elastic compute is compressing the minimum viable scale for competitive protein engineering operations.
EMA qualification opinions for drug-device combination products incorporating computational design tools are establishing precedent for regulatory acceptance of purely in silico evidence packages. Pharmaceutical sponsors submitting under the EU MDR pathway increasingly reference platform validation studies in their technical documentation. Chemistry, manufacturing, and controls teams in Basel and Frankfurt now prioritize vendors with documented EMA interaction histories.
Biopharmaceutical procurement departments are unbundling computational platform subscriptions from bundled professional services, forcing vendors to demonstrate standalone software value. Large-cap pharmaceutical buyers in New Jersey and Basel now negotiate seat-based licenses with explicit throughput guarantees rather than full-time-equivalent scientist arrangements. This unbundling pressures mid-tier platform developers to automate customer success functions previously delivered through embedded field scientists.
In Silico Protein Design Market Segmentation
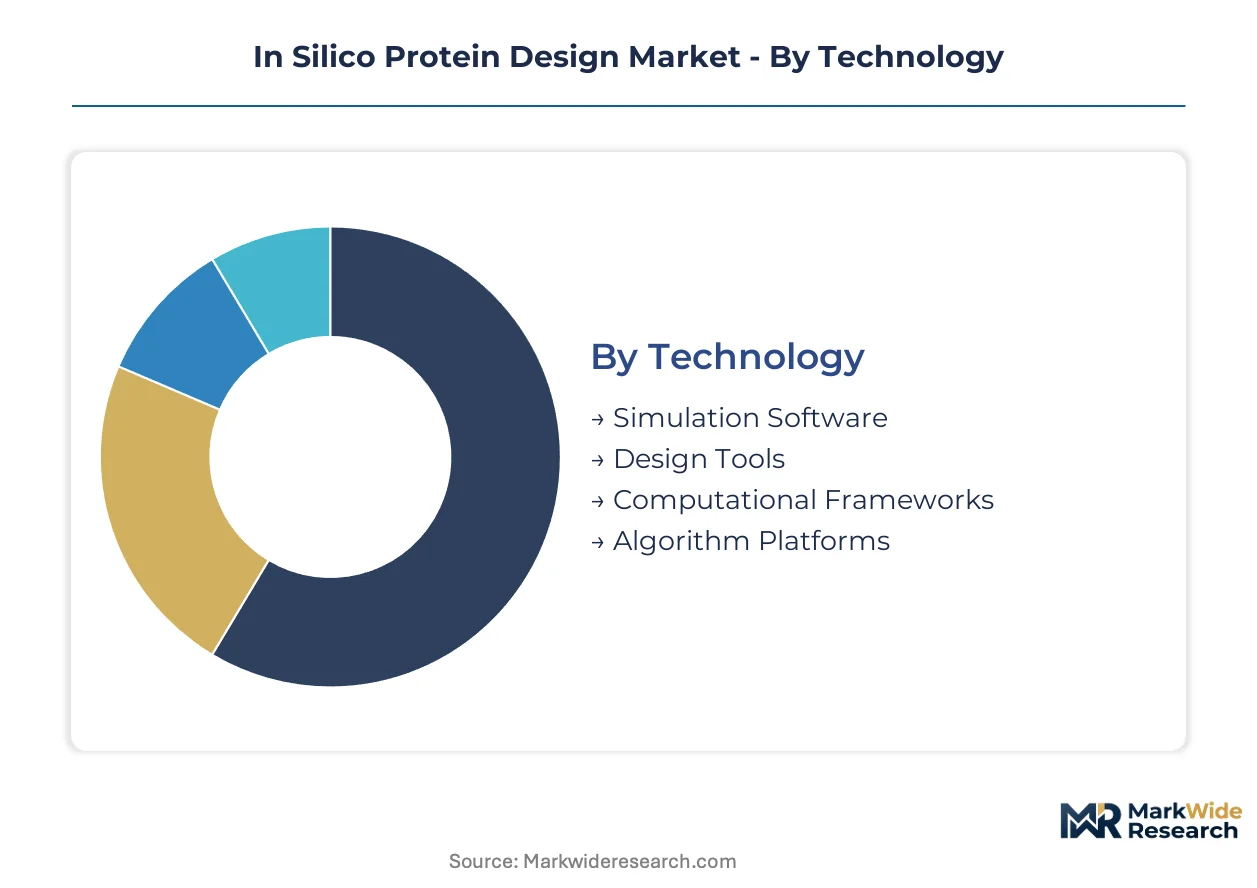
Segmentation in in silico protein design reveals how computational infrastructure investments and regulatory validation requirements stratify across customer archetypes. Platform developers calibrate deployment models and pricing architectures around distinct technology maturity levels and end-user risk tolerances.
Technology:
After-sales service intensity varies sharply across technology tiers, with physics-based simulation platforms demanding embedded field scientists for force-field calibration while algorithm platforms operate through automated API documentation.
- Simulation Software:Molecular dynamics engines execute force-field calculations for conformational sampling and binding affinity prediction. Demand concentrates among pharmaceutical sponsors in Basel and New Jersey seeking IND-enabling documentation packages for FDA submissions.
- Design Tools:Graphical interfaces and sequence editors enable structural biologists to manipulate alpha-carbon backbones and side-chain rotamers. Biotechnology startups in Cambridge and South San Francisco deploy these for rapid iteration cycles before committing to cryo-EM validation spend.
- Computational Frameworks:Integrated pipelines combining Rosetta protocols with custom scoring functions.
- Algorithm Platforms:Transformer neural networks and diffusion models for generative sequence design.
Simulation software holds the largest share; momentum sits with algorithm platforms.
Application:
Application segmentation tracks how therapeutic risk profiles and manufacturing scale requirements reshape customer procurement criteria and platform customization needs.
- Drug Discovery:Small-molecule binding site optimization and biologic lead identification dominate current commercial deployment. Large-cap pharmaceutical sponsors in New Jersey negotiate multi-year enterprise licenses with throughput guarantees for antibody engineering campaigns.
- Industrial Enzymes:Engineered biocatalysts for pharmaceutical and agrochemical process chemistry. Chemical manufacturers in Ludwigshafen and Basel pursue enzymatic alternatives under EU Green Deal emissions mandates, creating procurement pull for thermostable hydrolases and oxidoreductases.
- Vaccine Development:Immunogen design for stabilized prefusion conformations and T-cell epitope selection.
- Therapeutic Proteins:Cytokine engineering and multispecific antibody architectures.
Drug discovery commands current revenue concentration; industrial enzymes are climbing the fastest.
End User:
End-user segmentation exposes divergent purchasing authority structures, with procurement departments in large pharmaceutical companies unbundling software from services while academic labs prioritize grant-funded perpetual licenses.
- Pharmaceutical Companies:Integrated discovery organizations with dedicated computational chemistry groups. Sponsors in Basel and Frankfurt prioritize vendors with documented EMA qualification opinions for MDR pathway submissions.
- Biotechnology Firms:Venture-backed platform developers and therapeutic startups. Clusters near Boston and San Francisco drive seat-based subscription growth with elastic GPU cluster requirements.
- Academic Institutions:University structural biology departments and national laboratories.
- Research Organizations:Non-profit institutes and contract research providers.
Pharmaceutical companies anchor volume; biotechnology firms show steepest expansion trajectory.
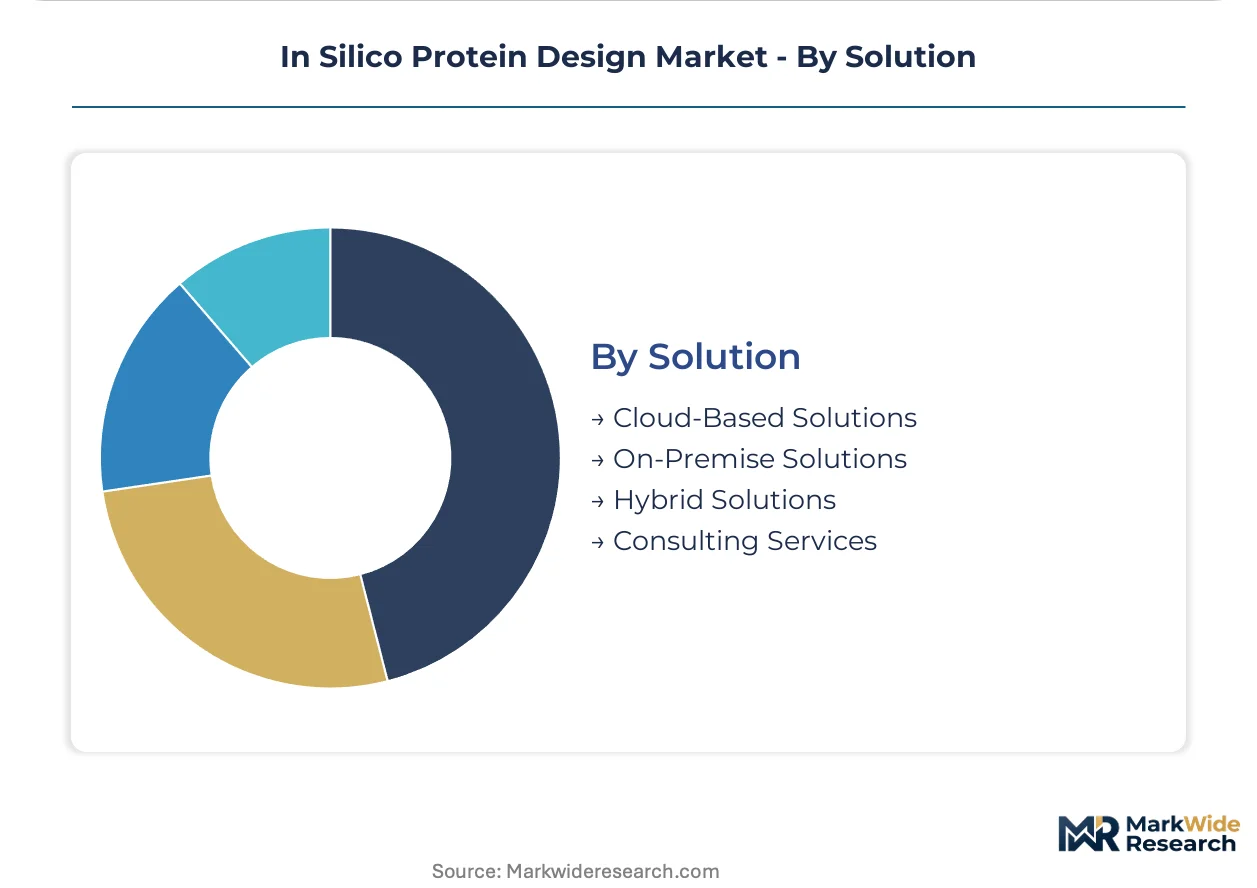
Solution:
Solution segmentation captures the infrastructure migration from captive data centers to elastic cloud architectures, with margin structures compressing for on-premise deployments as GPU-as-a-service matures.
- Cloud-Based Solutions:Subscription access to distributed GPU clusters with automated scaling for molecular dynamics trajectories. Mid-tier biotechnology companies in Research Triangle Park and Seattle access nanosecond-scale simulations without capital investment in on-premise hardware.
- Hybrid Solutions:Sensitive force-field development on local infrastructure combined with burst compute to cloud. Pharmaceutical sponsors in Switzerland and Germany deploy this architecture to reconcile data residency requirements with variable simulation demand.
- On-Premise Solutions:Perpetual licenses with dedicated hardware installations.
- Consulting Services:Embedded scientists and custom model development.
Cloud-based solutions dominate new bookings; hybrid solutions gain share fastest among risk-averse European sponsors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in in silico protein design services, exporting computational platforms to European and Asian pharmaceutical sponsors while importing specialized industrial enzyme design expertise from Western European developers.
United States
FDA software-as-medical-device guidance accelerates pharmaceutical adoption of computational platforms for IND-enabling studies. Venture capital concentration in Kendall Square and South San Francisco sustains platform developer density unmatched elsewhere. Boston-area startups leverage elastic GPU clusters to compress antibody engineering timelines for large-cap sponsors in New Jersey.
Germany
REACH-regulated chemical manufacturers procure engineered biocatalysts to meet binding EU Green Deal emissions reduction targets. EMA qualification opinions for computational design tools establish regulatory precedent for purely in silico evidence packages in MDR pathway submissions. Ludwigshafen and Frankfurt clusters anchor industrial enzyme demand for pharmaceutical process chemistry.
Switzerland
Basel-based pharmaceutical sponsors prioritize vendors with documented EMA interaction histories for chemistry, manufacturing, and controls documentation. Swissmedic oversight of computational toxicology predictions shapes quality management certification requirements for platform developers. The Basel-Zurich corridor concentrates procurement authority for multi-year enterprise simulation licenses.
India
CDSCO-aligned bioinformatics service providers in Hyderabad and Bengaluru offer cost-advantaged computational screening capacity for Western pharmaceutical sponsors. The country's national pharmaceutical regulator harmonizes data integrity standards with OECD computational toxicology principles. Bengaluru's IT corridor hosts expanding captive centers for molecular dynamics simulation outsourcing.
United Kingdom
London and Cambridge structural biology departments license perpetual software editions through grant-funded academic procurement channels. The Medicines and Healthcare products Regulatory Agency evaluates computational drug design tools under evolving software-as-medical-device frameworks. The Cambridge-London axis sustains deep learning research pipelines feeding into commercial platform development.
In Silico Protein Design Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in force-field development and algorithm licensing. The vendor base stratifies into three tiers: physics-based simulation incumbents with embedded field scientist models, generative AI challengers with automated API delivery, and niche industrial enzyme designers with sustainable manufacturing positioning. Strategic moves concentrate on cloud infrastructure partnerships and regulatory qualification documentation.
Within the physics-based tier, Schrödinger, Inc. and Chemical Computing Group ULC exemplify platform integrators anchoring long-term pharmaceutical relationships. Generate Biomedicines and Arzeda occupy positions at the generative AI and industrial enzyme specialization poles respectively.
| Leading Market Players |
|---|
| Schrödinger, Inc. |
| Biovia (Dassault Systèmes) |
| Insilico Medicine |
| Generate Biomedicines |
| Arzeda |
| Chemical Computing Group ULC |
| Profluent |
| Cradle |
| Absci |
| Others |
Pricing and Supply Chain Analysis
Boston and San Francisco GPU cluster capacity dynamics directly shape downstream pricing power for computational platform vendors serving pharmaceutical sponsors. Cloud infrastructure maturation in these corridors enables elastic pricing models that compress margins for on-premise perpetual license incumbents while expanding addressable markets for mid-tier biotechnology startups.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates FDA-validated simulation suites with embedded field scientists from automated API tiers and open-source framework adaptations. Cost compression in the standard tier intensifies because generative AI challengers automate customer success functions previously delivered through embedded scientists. Biotechnology startups in Cambridge and South San Francisco demonstrate highest price sensitivity, while Basel-based pharmaceutical sponsors prioritize throughput guarantees over per-seat economics.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for specialized AI accelerators and GPU hardware procurement. Hardware sourcing concentrates in Taiwan, South Korea, and the United States, with force-field calibration expertise drawing from Switzerland and Germany. Supply chain vulnerability rests on single-source dependencies for next-generation tensor processing units. Distribution runs through cloud service provider marketplaces and direct enterprise licensing agreements with pharmaceutical procurement departments in New Jersey and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI models trained on open-access protein structure databases pose acute substitution risk to physics-based simulation incumbents, forcing platform developers to defend proprietary data moats and regulatory qualification histories.
For Market Incumbents: Build regulatory qualification moats by securing EMA qualification opinions for MDR pathway submissions before generative AI challengers accumulate comparable documentation. Deepen backward integration into cloud GPU clusters to control computational throughput costs. Anchor multi-year enterprise licenses with explicit throughput guarantees that automated API competitors cannot match. For New Entrants and Emerging Players: Pursue white-space opportunities in industrial enzyme design for EU Green Deal-mandated process chemistry transitions, where thermostable hydrolase demand outpaces specialized vendor supply. Target CDSCO-aligned service partnerships in Hyderabad and Bengaluru as cost-advantaged computational screening channels for Western pharmaceutical sponsors. Lead with outcome-based pricing tied to experimental validation success rates rather than computational throughput. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform developers with documented FDA software-as-medical-device interaction histories and hybrid physics-AI architectures. Long-term viability hinges on regulatory acceptance trajectories for purely computational evidence packages. Watch EMA qualification opinion issuance velocity as the inflection signal distinguishing sustainable competitive position from commodity algorithm licensing.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Qualification Pathway | Establishes regulatory precedent for purely in silico evidence packages in MDR submissions. |
| Cloud GPU Partnership | Secures elastic computational capacity without capital investment in captive infrastructure. |
| Industrial Enzyme Expansion | Captures procurement pull from REACH-regulated manufacturers under EU Green Deal mandates. |
| Platform Integration | Reduces API maintenance overhead from legacy electronic laboratory notebook system interfaces. |
| Acquisition of Specialist Firm | Consolidates force-field development expertise concentrated in Swiss and German research clusters. |
Research Methodology
Operator-level perspectives from computational chemistry directors, regulatory affairs leads at platform developers, pharmaceutical procurement managers, and cloud infrastructure specialists anchored the qualitative base. Primary interview findings combined with secondary validation from FDA software-as-medical-device guidance documents, EMA qualification opinion databases, SEC filings of publicly traded platform developers, and OECD computational toxicology principle frameworks. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across technology tiers and application segments.
Scenario-bracketing around regulatory acceptance timelines and cloud infrastructure cost curves structured the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application, end-user archetype, and solution deployment model. CAGRs derived from fitted growth curves adjusted for experimental validation cost structures and talent concentration constraints. Industry-specific forecast inputs incorporated GPU cluster pricing trajectories and EMA interaction pipeline visibility.
Sensitivities concentrate around FDA software-as-medical-device framework evolution pace and experimental validation cost inflation. Forecasts reflect assumptions regarding regulatory acceptance of purely computational evidence packages and cloud infrastructure commoditization timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioinformatics
Global Chemoinformatics Market
Bioinformatics
Global Bioinformatics Services Market
Bioinformatics
Germany Computer-Aided Drug Discovery Market
Bioinformatics
US Computational Biology Market
Bioinformatics
Bioinformatics Software Market
Bioinformatics
Europe AI in Life Science Analytics Market
Bioinformatics
Germany Computational Biology Market
Bioinformatics
North America Computational Biology Market
Bioinformatics
Bioinformatics Market
Bioinformatics
China Computational Biology Market
Bioinformatics
Global Computational Biology Market
Bioinformatics
South Korea Computational Biology Market
Bioinformatics
Microrna (Mirna) Market
Bioinformatics
AI in Life Science Analytics Market
Bioinformatics
Bioinformatics in IVD Testing Market
Bioinformatics
LAMEA Computer-Aided Drug Discovery Market