
 North America Monoclonal Antibody Market | 2026-2036
North America Monoclonal Antibody Market Size, Share, and Industry Trends Forecast 2026-2036
North America Monoclonal Antibody Market Insights
Aftermarket service revenue from infusion center administration and patient monitoring programs is reconfiguring margin pools away from pure drug sales toward integrated care economics. F. Hoffmann-La Roche Ltd leverages its diagnostics-therapeutics pairing to control companion testing workflows. Amgen Inc anchors its position through biosimilar manufacturing scale in the U.S. West Coast corridor. Bristol Myers Squibb differentiates via checkpoint inhibitor specialization that sustains premium positioning.
North America monoclonal antibodies constitute recombinant immunoglobulin proteins engineered for target-specific binding, typically manufactured through mammalian cell culture in bioreactors exceeding ten thousand liters, then purified via protein A chromatography for therapeutic administration against defined cellular antigens. The IgG isotype dominates commercial pipelines due to established Fc-effector function and half-life extension, while phage display technology is displacing traditional hybridoma methods in early discovery for its speed in generating human antibody sequences. Oncology applications command the largest revenue share, though autoimmune disease indications are expanding fastest as IL-23 and IL-17 pathway inhibitors penetrate dermatology and gastroenterology practices.
FDA Center for Drug Evaluation and Research and Health Canada's Biologic and Radiopharmaceutical Drugs Directorate enforce batch consistency, viral clearance validation, and post-market pharmacovigilance requirements that shape manufacturing investment and approval timelines. The IRA Medicare price negotiation provisions and provincial formulary review processes in Canada are compressing reimbursement thresholds and forcing evidence-generation strategies earlier in development cycles. Stakeholders must monitor biosimilar interchangeability designations and state-level substitution laws to anticipate pricing erosion velocity and portfolio restructuring needs.
Market Dynamics
FDA biosimilar interchangeability designations and IRA Medicare price negotiation provisions are compressing reimbursement thresholds while redirecting hospital procurement toward integrated care economics across the United States and Canada.
Growth Catalysts
- Subcutaneous formulation advances:Self-administration capability expands patient access beyond infusion centers into home settings. Health systems in the U.S. Northeast corridor prioritize these formulations to reduce facility overhead.
- IL-23 and IL-17 pathway inhibitors:Dermatology and gastroenterology practices are expanding autoimmune disease indications faster than traditional oncology growth. Canadian provincial formularies accelerate access for plaque psoriasis and Crohn's disease therapies.
- Boston-New York biotech cluster concentration:Talent density and venture availability speed discovery-to-clinic timelines. Mammalian cell culture expertise pools in this corridor, lowering scale-up risk for novel IgG candidates.
Market Restraints
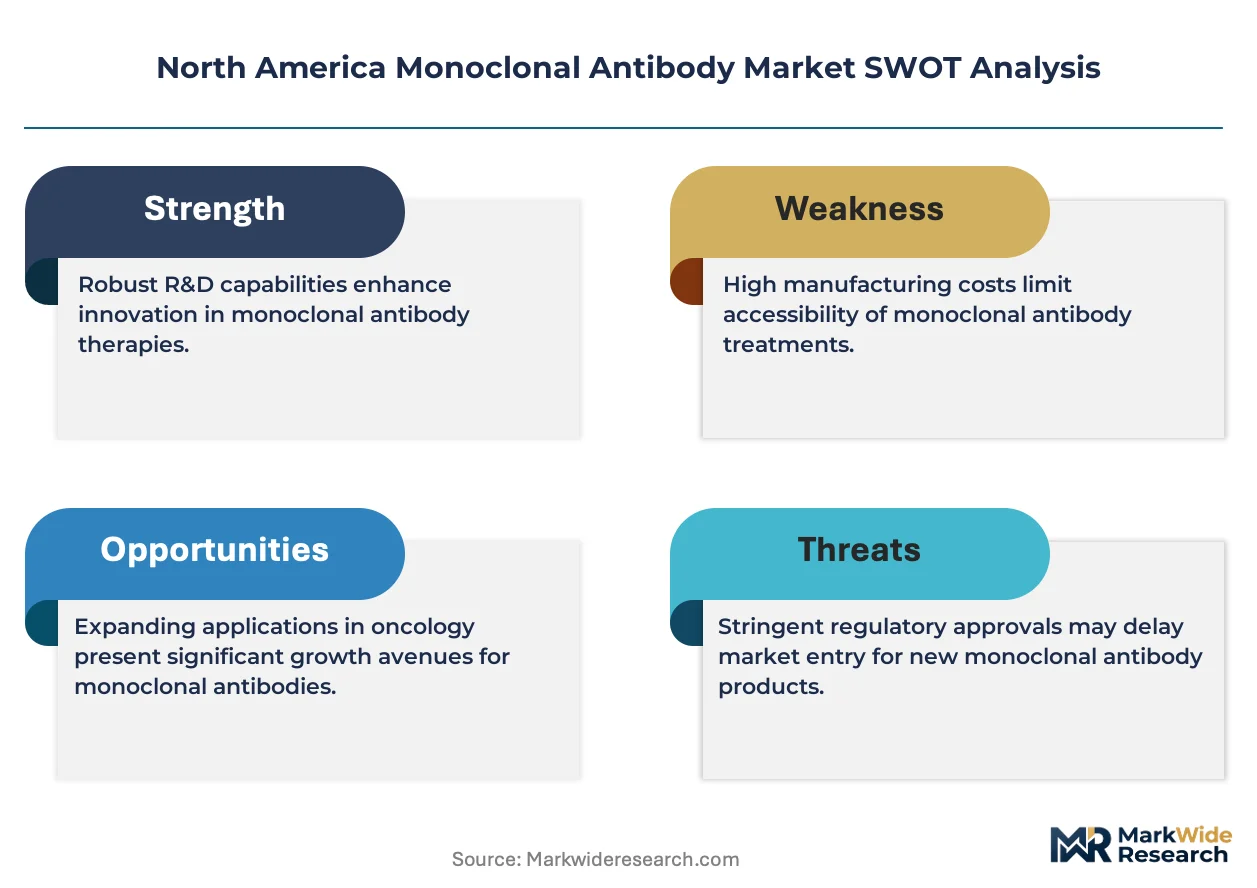
- Protein A chromatography resin supply concentration:Single-source dependency for purification media creates batch vulnerability. Suppliers in specific coastal U.S. regions dominate global resin production.
- Viral clearance validation complexity:FDA Center for Drug Evaluation and Research demands extensive documentation for adventitious agent removal. Each validation cycle extends approval timelines by quarters.
- Phage display patent thickets:Human antibody sequence generation tools face licensing friction. Early-stage discovery programs encounter royalty stacking that erodes therapeutic margins.
Strategic Opportunities
- Canadian provincial biosimilar substitution laws:Interchangeability designations open rapid uptake pathways for follow-on biologics. Quebec and Ontario formulary structures reward early biosimilar entrants with preferential listing.
- Companion diagnostic-therapeutic pairing:CDx integration captures testing workflow economics. F. Hoffmann-La Roche Ltd's precedent demonstrates margin protection through diagnostic control.
- Bioreactor scale virtualization:Continuous manufacturing and digital twin deployment reduce ten-thousand-liter facility capex requirements. Contract development organizations in the U.S. West Coast corridor pioneer modular production architectures.
Industry Challenges
- Cell line development talent scarcity:Mammalian host engineering expertise concentrates among senior scientists. Training pipelines fail to replace retiring hybridoma specialists.
- Fc-effector function optimization complexity:Glycoengineering for half-life extension requires specialized analytical capabilities. Biotech firms struggle to replicate Big Pharma's glycan profiling infrastructure.
- Post-market pharmacovigilance data integration:Real-world evidence collection across fragmented U.S. hospital systems strains safety surveillance. Health Canada's Biologic and Radiopharmaceutical Drugs Directorate demands comparable vigilance standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Monoclonal Antibody Market |
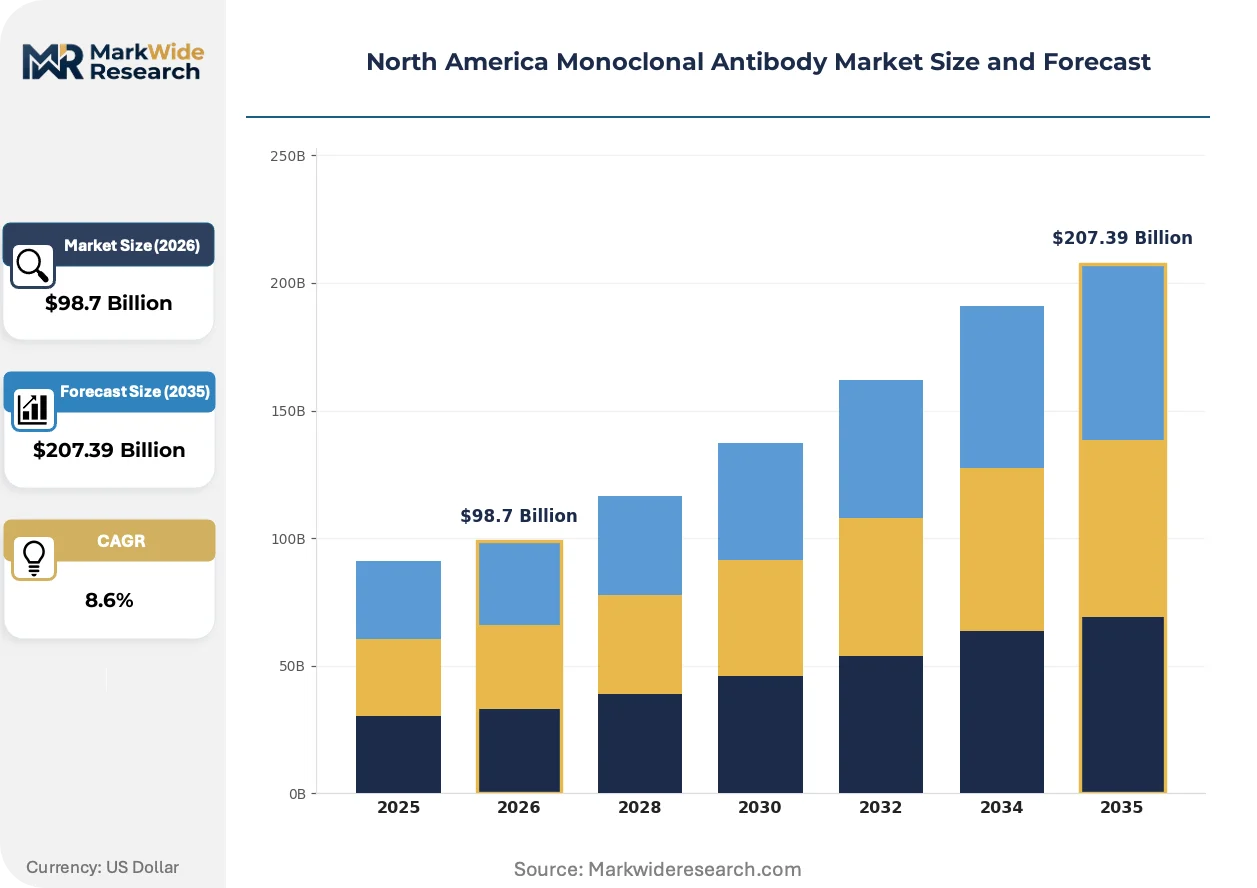
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $207.39 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IgG, IgM, IgA, IgE Application: Oncology, Autoimmune Diseases, Infectious Diseases, Neurology Technology: Hybridoma, Phage Display, Transgenic Technology, Recombinant DNA Technology End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Clinics |
| Companies Covered | F. Hoffmann-La Roche Ltd, Amgen Inc, Johnson & Johnson Services, Inc., Bristol Myers Squibb, AbbVie Inc, Merck & Co., Inc., Pfizer Inc., Novartis AG, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Monoclonal Antibody Market Trends and Innovations
Manufacturing modality shifts and reimbursement model compression are restructuring how monoclonal antibodies reach patients, with technology virtualization and policy-driven pricing pressure as dominant forces.
Continuous bioprocessing technology replaces traditional fed-batch mammalian cell culture in new facility designs. Contract manufacturers serving U.S. hospital networks adopt perfusion-based systems to improve volumetric productivity. This infrastructure is virtualizing capital allocation — firms deploy modular skid-mounted units rather than fixed stainless-steel trains, compressing facility commissioning timelines and enabling geographic flexibility for regional supply.
The IRA Medicare price negotiation provisions reshape evidence-generation requirements for therapeutic candidates. Manufacturers must demonstrate differentiated clinical value earlier in development cycles to justify premium positioning before price controls apply. Oncology mAbs face the steepest adjustment, with U.S. hospital procurement committees demanding head-to-head comparator data prior to formulary inclusion.
Hospital systems are unbundling drug acquisition from infusion administration services. Integrated delivery networks in the U.S. Northeast corridor now contract separately for mAb supply and site-of-care management. This bifurcation rewards vendors with captive infusion center assets or partnerships with ambulatory surgery centers, compressing traditional buy-and-bill margins for pure pharmaceutical distributors.
North America Monoclonal Antibody Market Segmentation
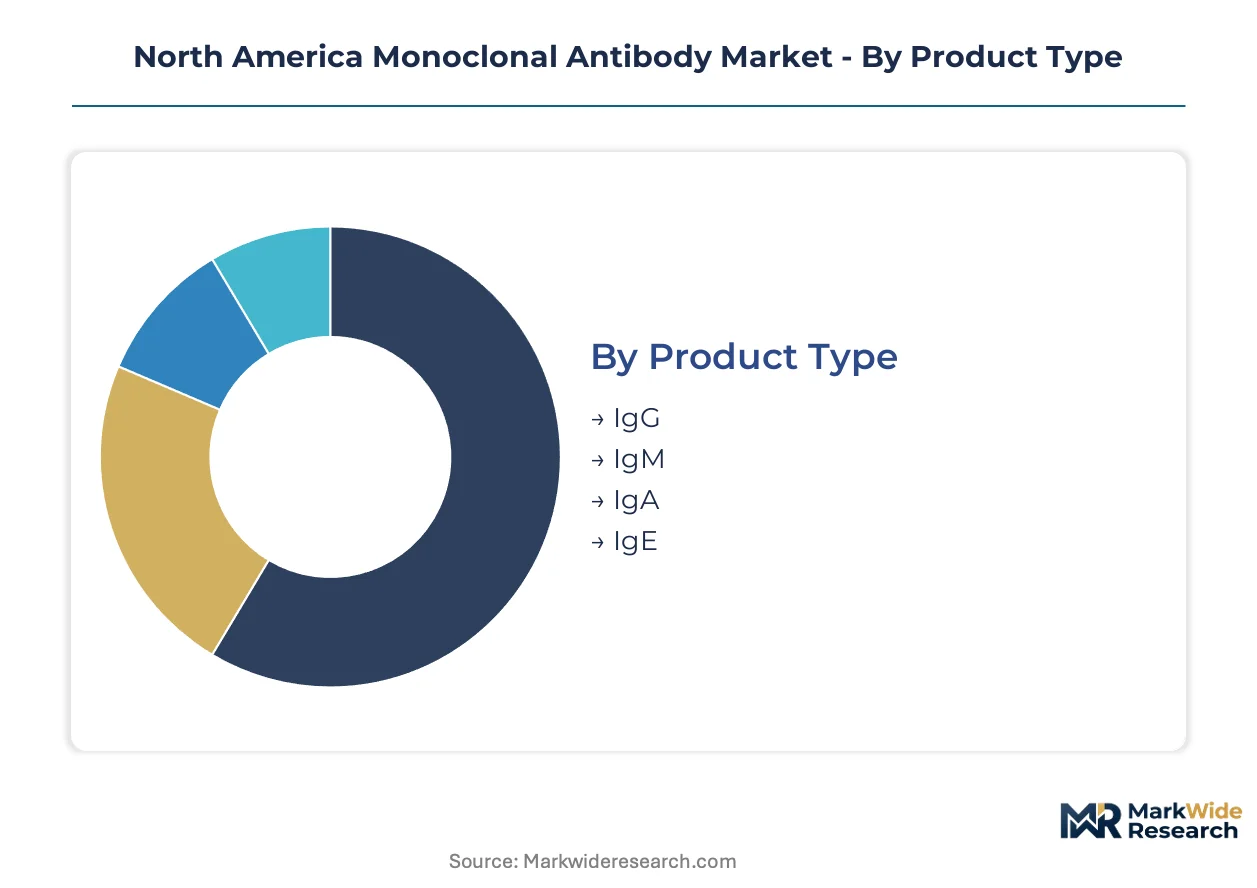
Monoclonal antibody segmentation in North America reflects therapeutic mechanism, production methodology, and care delivery setting. Each dimension shapes procurement patterns, reimbursement pathways, and manufacturing investment priorities across the United States and Canada.
Product Type:
The immunoglobulin class spectrum spans from established IgG dominance to specialized isotypes serving niche immunological functions.
- IgG:The predominant therapeutic isotype engineered for Fc-effector function and extended serum half-life through neonatal Fc receptor recycling. Hospital procurement committees across the U.S. Northeast corridor prioritize IgG candidates for oncology and autoimmune portfolios due to established manufacturing scalability and regulatory familiarity.
- IgM:Pentameric structure enables high-avidity binding to carbohydrate antigens and complement activation, positioning this isotype for infectious disease applications. Canadian provincial formularies show emerging interest in IgM-based therapeutics for antimicrobial-resistant pathogens where conventional IgG approaches demonstrate limited efficacy.
- IgA:Mucosal immunity applications drive development, with dimeric structure suited for respiratory and gastrointestinal targeting.
- IgE:Allergen-specific immunotherapy and parasite defense mechanisms represent narrow but growing therapeutic exploration.
Established volume favors IgG; emerging adoption favors IgM.
Application:
Therapeutic indication segmentation tracks disease biology complexity and reimbursement pressure intensity across North American healthcare systems.
- Oncology:Checkpoint inhibitors and antibody-drug conjugates command premium pricing through demonstrated survival benefits in solid tumors. FDA Medicare price negotiation provisions under the IRA compress margins fastest in this segment, forcing manufacturers toward combination therapy strategies and companion diagnostic integration.
- Autoimmune Diseases:IL-23 and IL-17 pathway inhibitors are expanding most quickly into dermatology and gastroenterology practices. Subcutaneous formulation advances in this segment enable home administration, reducing infusion center dependency and expanding patient access beyond traditional hospital settings.
- Infectious Diseases:Antibody cocktails for viral pathogens address emerging pandemic preparedness requirements.
- Neurology:Blood-brain barrier penetration challenges limit current penetration, though Fc-engineering innovations show early promise.
Oncology maintains revenue concentration; autoimmune disease applications are climbing the fastest.
Technology:
Discovery and production platform selection determines speed-to-clinic, intellectual property position, and manufacturing yield economics.
- Phage Display:In vitro selection of human antibody sequences accelerates discovery timelines and reduces immunogenicity risk versus murine-derived alternatives. Patent thickets surrounding human sequence generation create licensing friction, particularly for early-stage biotech firms in Boston and New York clusters seeking independent therapeutic development.
- Hybridoma:Traditional murine fusion technology retains relevance for established therapeutic antibodies and biosimilar replication. Retiring specialist scarcity threatens this segment as training pipelines fail to replace experienced mammalian cell culture engineers.
- Transgenic Technology:Human antibody production in genetically modified animals offers alternative glycosylation profiles.
- Recombinant DNA Technology:Foundational platform underlying all modern mAb production, with continuous bioprocessing advances reshaping facility design.
Hybridoma retains installed base; phage display is gaining share fastest.
End User:
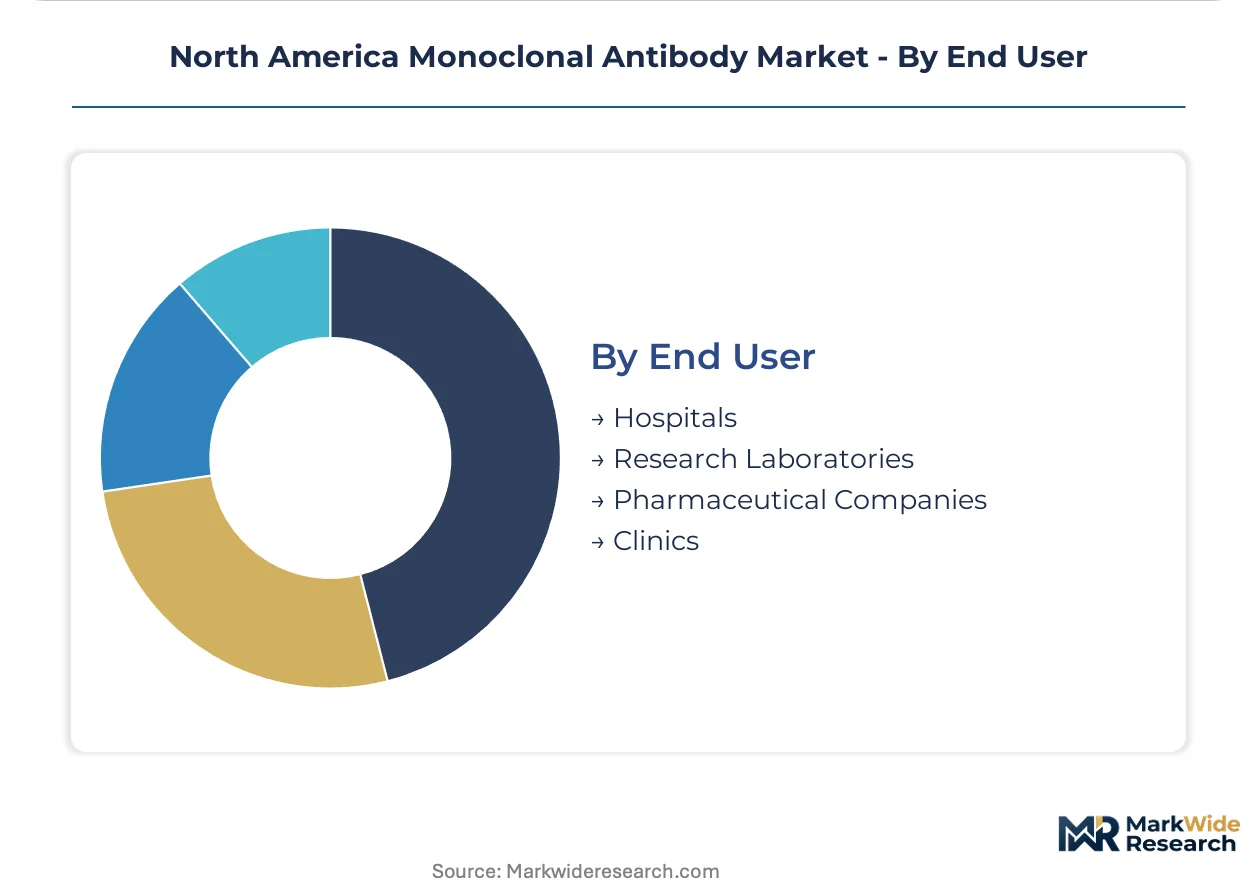
Site-of-care segmentation captures the unbundling of drug acquisition from administration services across North American health systems.
- Hospitals:Integrated delivery networks in the United States now contract separately for mAb supply and infusion management, compressing traditional buy-and-bill margins. Hospital procurement committees demand head-to-head comparator data prior to formulary inclusion, particularly for oncology candidates facing IRA price negotiation timelines.
- Research Laboratories:Discovery-stage antibody generation and preclinical validation services concentrate in Boston-New York and U.S. West Coast corridors. Academic medical centers leverage proximity to venture capital and talent pools to accelerate translational programs.
- Pharmaceutical Companies:Internal manufacturing and outsourced bioproduction decisions hinge on continuous processing technology adoption.
- Clinics:Ambulatory settings capture growing subcutaneous formulation administration as home infusion programs expand.
Hospitals dominate volume capture; clinics are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States demonstrate the highest price elasticity, while Canadian provincial formularies exhibit more rigid cost-effectiveness thresholds. Mexican healthcare systems operate at intermediate sensitivity, balancing biosimilar access with originator brand reliability.
United States
The FDA's biosimilar interchangeability pathway and IRA Medicare price negotiation provisions compress reimbursement margins fastest in oncology. Boston and New York biotech clusters concentrate mammalian cell culture expertise, accelerating discovery-to-clinic timelines for novel IgG candidates. Hospital procurement in the Northeast corridor now contracts separately for mAb supply and infusion administration services.
Canada
Health Canada's Biologic and Radiopharmaceutical Drugs Directorate enforces batch consistency and viral clearance validation that shapes manufacturing investment decisions. Provincial formulary review processes in Quebec and Ontario reward early biosimilar entrants with preferential listing status. Toronto and Montreal anchor contract manufacturing capacity serving both domestic demand and U.S. overflow.
Mexico
COFEPRIS regulatory alignment with FDA standards accelerates approval timelines for imported biologics. Public sector procurement through INSABI concentrates demand for oncology and autoimmune mAbs in Mexico City and Guadalajara metropolitan hospitals. Northern border states leverage maquiladora infrastructure for temperature-controlled distribution into U.S. Southwest markets.
North America Monoclonal Antibody Market Competitive Landscape
Capability concentration sits with integrated diagnostics-therapeutics pairings; scale advantage sits with biosimilar manufacturing specialists. The market structures around three tiers: originator innovators defending premium positioning, biosimilar manufacturers capturing volume through cost leadership, and contract development organizations enabling geographic flexibility. Strategic moves center on companion diagnostic integration and continuous bioprocessing technology licensing.
Among Swiss-origin pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd exemplifies the diagnostics-therapeutics pairing archetype. California-based Amgen Inc occupies a position representing biosimilar manufacturing scale. New York-headquartered Bristol Myers Squibb anchors the checkpoint inhibitor specialization tier. These three entities collectively illustrate the competitive vectors reshaping procurement relationships across U.S. hospital networks and Canadian provincial systems.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Amgen Inc |
| Johnson & Johnson Services, Inc. |
| Bristol Myers Squibb |
| AbbVie Inc |
| Merck & Co., Inc. |
| Pfizer Inc. |
| Novartis AG |
| Eli Lilly and Company |
| Others |
Pricing and Supply Chain Analysis
The I-95 pharmaceutical distribution corridor linking Boston to Philadelphia carries temperature-controlled mAb shipments whose freight costs compound with Protein A resin scarcity to widen price spreads between integrated biomanufacturers and contract-dependent developers. Hospital procurement committees exploit this bifurcation, extracting steeper discounts from supply-constrained entrants while locking in originator premiums through companion diagnostic bundling.
Pricing Analysis
Long-term offtake contracts dominate hospital procurement for oncology mAbs, with integrated delivery networks negotiating multi-year supply agreements that embed infusion service economics alongside drug acquisition. Price differentiation separates originator checkpoint inhibitors with companion diagnostic control from interchangeable biosimilars competing on provincial formulary listing. Cost compression in the biosimilar tier is intensifying because IRA Medicare price negotiation timelines compress pre-negotiation revenue windows, forcing earlier discounting. Community oncology practices exhibit highest price sensitivity, while academic medical centers anchored to research partnerships demonstrate lowest elasticity.
Supply Chain Analysis
Upstream Chinese hamster ovary cell culture media production concentrates in the United States, Switzerland, and Germany, with serum-free formulation advances reducing lot-to-lot variability for mammalian host systems. Raw material dependencies center on Protein A chromatography resins, single-use bioreactor bags, and viral clearance validation reagents. Single-source vulnerability for purification media creates batch vulnerability when coastal resin suppliers face weather disruptions. Distribution runs through specialized cold-chain logistics providers serving hospital infusion centers and ambulatory surgery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation across the United States, with ten hospital systems now controlling over forty percent of oncology mAb procurement volume.
For Market Incumbents: Build diagnostic-therapeutic pairing moats by capturing companion testing workflow economics before biosimilar interchangeability designations erode originator positioning. Secure mammalian cell culture talent through acquisition of Boston-New York corridor contract development organizations facing succession gaps. Anchor manufacturing scale in the U.S. West Coast corridor to amortize continuous bioprocessing infrastructure across multiple therapeutic programs. For New Entrants and Emerging Players: Establish a beachhead in Canadian provincial biosimilar substitution pathways where Quebec and Ontario formulary structures reward early interchangeable entrants with preferential listing. Target subcutaneous formulation development for IL-23 and IL-17 pathway inhibitors, as dermatology and gastroenterology practices seek home administration alternatives to infusion center dependency. Pursue partnership models with ambulatory surgery centers to capture unbundled site-of-care management contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from pharmaceutical conglomerates divesting legacy hybridoma-based manufacturing assets as phage display technology displaces traditional platforms. Long-term viability centers on continuous bioprocessing capability and companion diagnostic integration rather than single-asset therapeutic exposure. Monitor FDA biosimilar interchangeability designation velocity as inflection indicator for pricing erosion timelines across oncology portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | F. Hoffmann-La Roche Ltd's precedent demonstrates margin protection through testing workflow control. |
| Continuous Bioprocessing Adoption | Perfusion-based systems improve volumetric productivity for contract manufacturers serving U.S. hospital networks. |
| Biosimilar Interchangeability Pursuit | Canadian provincial substitution laws open rapid uptake pathways for follow-on biologics in Quebec and Ontario. |
| Subcutaneous Formulation Development | Self-administration capability expands patient access beyond infusion centers into home settings across the U.S. Northeast corridor. |
| Mammalian Cell Culture Talent Acquisition | Senior scientist scarcity in hybridoma engineering threatens manufacturing continuity for established therapeutic antibodies. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists provided ongoing calibration against secondary validation from FDA filings, Health Canada submissions, ClinicalTrials.gov records, and provincial formulary databases. Bottom-up therapeutic candidate tracking triangulated with top-down reimbursement flow analysis to anchor market sizing.
Scenario-bracketing around IRA Medicare price negotiation implementation timelines and biosimilar interchangeability designation velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include immunoglobulin isotype, therapeutic indication, discovery platform technology, and site-of-care administration setting. CAGRs derived from patent expiry clustering, pipeline progression rates, and historical biosimilar uptake curves in comparable therapeutic classes.
Stress conditions across FDA approval timeline variability, Protein A resin supply disruption severity, and provincial formulary listing rejection rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding continuous bioprocessing adoption curves and companion diagnostic penetration rates. Cross-checking against IQVIA prescription audit data and CMS Medicare Part B spending reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Antimycobacterial Drugs Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Biopharmaceuticals Manufacturing Consumables Testing Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Global Monoclonal Antibodies (Mabs) Market
Biopharmaceuticals
North America Plasma Fractionation Market