
 Peptide Antibiotics Market | 2026-2036
Peptide Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide Antibiotics Market Intelligence
Hospital procurement of peptide antibiotics is restructuring as health systems consolidate purchasing power across North America. Pfizer leverages its manufacturing scale to supply vancomycin and daptomycin to integrated delivery networks. Merck anchors its position through R&D intensity in novel lipopeptide candidates. Eli Lilly and Company differentiates via specialized fermentation capabilities for complex cyclic peptides.
Peptide antibiotics comprise ribosomally or non-ribosomally synthesized antimicrobial peptides, typically containing 12 to 50 amino acid residues with molecular weights below 10 kDa, engineered to disrupt bacterial cell membranes or inhibit cell wall synthesis. Glycopeptides occupy the largest revenue pool due to entrenched vancomycin use against methicillin-resistant Staphylococcus aureus. Bacteriocins represent the fastest-expanding category as food preservation applications in Europe and North America displace chemical preservatives. The injectable delivery method dominates hospital settings, while oral formulations remain limited by gastrointestinal degradation and poor bioavailability.
The FDA's Qualified Infectious Disease Product program shapes clinical trial incentives, while the EMA's antibacterial framework accelerates European market access for novel agents. The EPA regulates agricultural bacteriocin applications under pesticide tolerance statutes, constraining farm-scale deployment. Stakeholders must monitor FDA guidance on streamlined pathways for combination peptide therapies and EMA revisions to environmental risk assessments for veterinary glycopeptides.
Market Dynamics
Hospital procurement consolidation across the United States is compressing supplier margins while amplifying volume commitments for peptide antibiotic manufacturers serving integrated delivery networks.
Growth Catalysts
- FDA Qualified Infectious Disease Product incentives:Developers of novel peptide antibiotics receive priority review, fast-track designation, and extended market exclusivity, accelerating clinical trial enrollment and regulatory submission timelines.
- Academic medical center demand concentration:Major teaching hospitals in the United States drive adoption of advanced glycopeptide and lipopeptide agents for complex multidrug-resistant infections.
- Bacteriocin fermentation scale-up:European food manufacturers are displacing chemical preservatives with ribosomally synthesized antimicrobial peptides in clean-label product formulations.
Market Restraints
- Active pharmaceutical ingredient supply concentration:Fermentation-based production of cyclic peptides depends on a limited number of contract manufacturers in China and India, creating vulnerability to capacity constraints.
- Gastrointestinal degradation barriers:Oral bioavailability of peptide antibiotics remains below therapeutic thresholds due to enzymatic breakdown in the gut, restricting administration to injectable routes.
- EPA pesticide tolerance thresholds:Agricultural bacteriocin applications face prolonged environmental risk assessments that delay farm-scale deployment beyond commercial viability windows.
Strategic Opportunities
- EMA antibacterial framework acceleration:European developers gain streamlined market access for novel agents targeting resistant Gram-positive pathogens, reducing time-to-reimbursement.
- Combination peptide therapy pathways:FDA guidance on streamlined approval for synergistic antibiotic pairings creates regulatory runway for fixed-dose formulations.
- Specialized fermentation outsourcing:Biopharma contract manufacturers in South Korea and Singapore are building dedicated capacity for complex cyclic peptide production.
Industry Challenges
- Peptide chemist talent scarcity:Synthetic biology and solid-phase synthesis expertise concentrates in a handful of academic centers, constraining workforce expansion for commercial-scale operations.
- Current Good Manufacturing Practice compliance timelines:New fermentation facilities require 18-24 months for FDA pre-approval inspection clearance, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide Antibiotics Market |
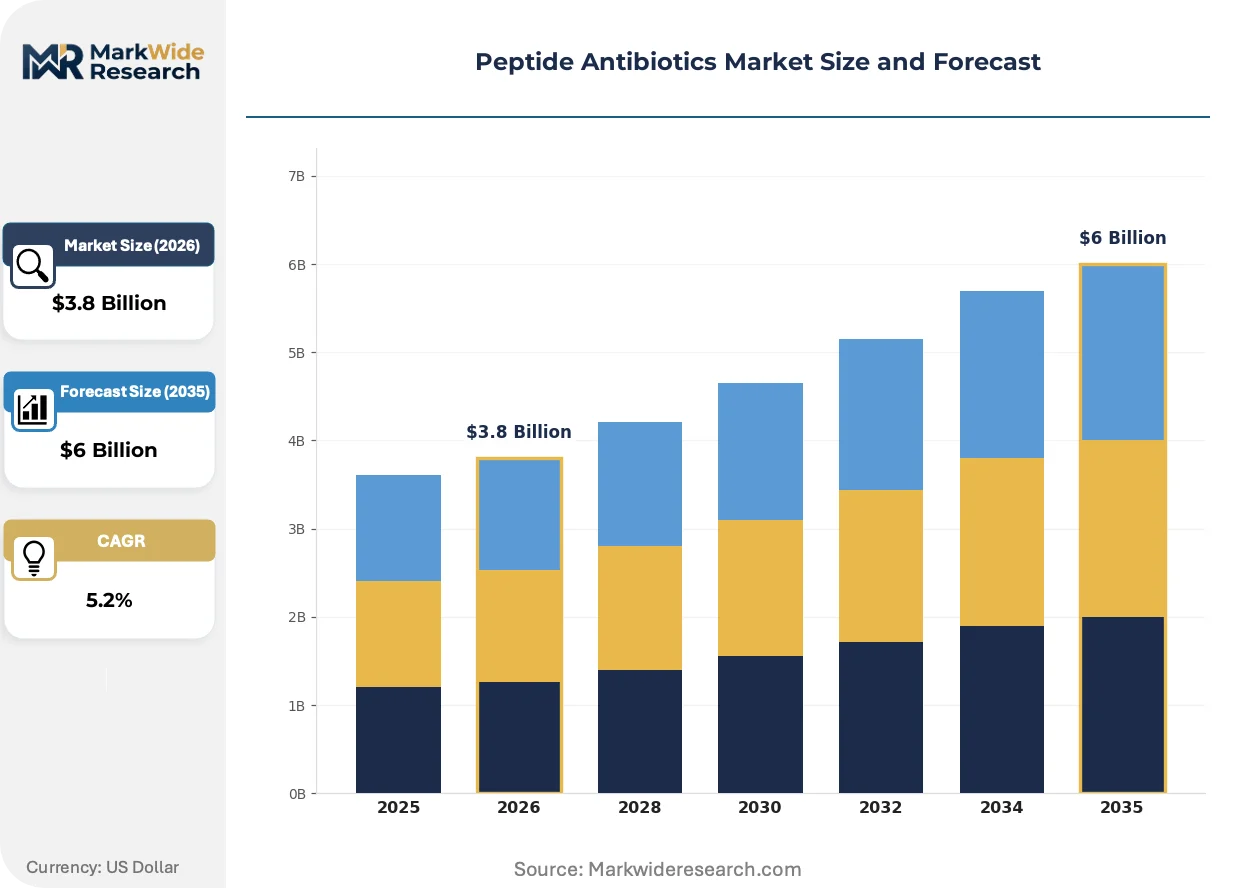
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteriocins, Lantibiotics, Glycopeptides, Cephalosporins Application: Infections, Agriculture, Veterinary Medicine, Food Preservation Delivery Method: Injectable, Oral, Topical, Intravenous End User: Hospitals, Pharmaceutical Companies, Research Laboratories, Clinics |
| Companies Covered | Pfizer, Merck, AbbVie, Eli Lilly and Company, Xellia Pharmaceuticals, Teva Pharmaceuticals Industries, Sanofi, GSK, The Menarini Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide Antibiotics Market Strategic Shifts & Innovations
Artificial intelligence is reshaping peptide discovery workflows while regulatory incentives compress development timelines for anti-infective agents targeting resistant pathogens.
Solid-phase peptide synthesis automation is integrating machine learning-driven retrosynthetic planning into manufacturing workflows. Contract manufacturers serving the pharmaceutical sector are adopting these platforms to reduce cycle times for complex cyclic peptides. The technology is integrating predictive analytics for impurity profiling, enabling real-time process adjustments that lower batch failure rates.
REACH authorization requirements for novel biocidal substances are tightening environmental discharge standards for antimicrobial peptide manufacturing in Europe. The European Chemicals Agency's cumulative assessment approach is forcing reformulation of process intermediates. Glycopeptide producers with legacy fermentation facilities in Germany and Belgium face capital-intensive wastewater treatment upgrades to maintain operating licenses.
Integrated delivery networks in the United States are consolidating antibiotic formularies under centralized pharmacy and therapeutics committees. Academic medical centers and community hospitals within the same health system now share restricted drug evaluation protocols, compressing vendor access to individual facility purchasing managers. This concentration is most pronounced in California and Texas, where mega-systems control over sixty percent of inpatient bed capacity.
Peptide Antibiotics Market Segmentation
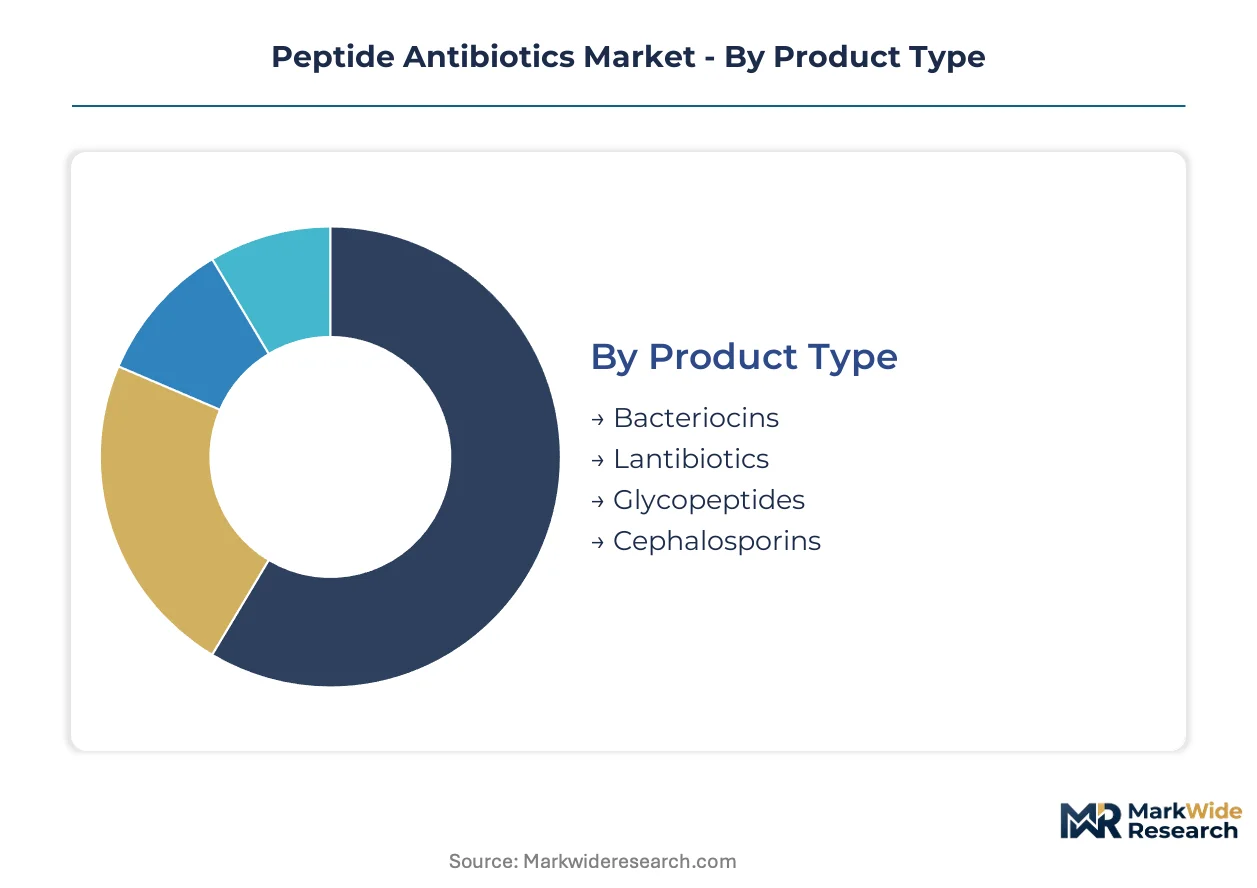
Peptide antibiotic manufacturers align R&D portfolios and production capacity against distinct demand profiles across therapeutic, agricultural, and food safety verticals. Each segment carries unique regulatory pathways, formulation constraints, and customer procurement behaviors that reshape competitive positioning.
Product Type:
Upgrade cycles in peptide antibiotic portfolios track resistance pattern shifts and manufacturing process innovations rather than patent expirations alone.
- Glycopeptides:These cyclic peptides incorporate amino sugars and aromatic rings that inhibit cell wall synthesis in Gram-positive pathogens. Demand concentrates in United States academic medical centers managing methicillin-resistant Staphylococcus aureus outbreaks, with FDA Qualified Infectious Disease Product incentives accelerating clinical adoption of next-generation derivatives.
- Bacteriocins:Ribosomally synthesized antimicrobial peptides disrupt target cell membranes through pore formation. European food manufacturers in Germany and France are displacing chemical preservatives with nisin and pediocin in clean-label dairy and meat applications, though EPA pesticide tolerance thresholds constrain agricultural deployment timelines.
- Lantibiotics:These post-translationally modified peptides contain lanthionine bridges conferring protease resistance. Nisin dominates commercial production through specialized fermentation processes.
- Cephalosporins:Beta-lactam antibiotics with peptide components in their core structure target bacterial cell wall synthesis. Generic competition has compressed margins on older generations.
Glycopeptides sit at the top of the volume ranking, with bacteriocins climbing the fastest as clean-label food preservation gains regulatory traction.
Application:
Cost tier differentiation separates premium hospital-grade formulations from commodity agricultural applications with divergent purity specifications and regulatory burdens.
- Infections:Systemic antibacterial therapy for drug-resistant pathogens commands premium pricing through intravenous administration in tertiary care settings. United States hospital procurement consolidation is compressing supplier margins while amplifying volume commitments for manufacturers serving integrated delivery networks in California and Texas.
- Food Preservation:Natural antimicrobial peptides extend shelf life in processed foods without synthetic chemical labels. European manufacturers face REACH authorization requirements for novel biocidal substances that tighten environmental discharge standards.
- Agriculture:Bacteriocin applications in livestock feed and crop protection remain constrained by prolonged environmental risk assessments.
- Veterinary Medicine:Glycopeptide and lipopeptide agents target resistant infections in companion animals and food-producing species. EMA revisions to environmental risk assessments for veterinary glycopeptides are reshaping product registration pathways.
Infections commands the largest revenue pool, with food preservation gaining share fastest as European clean-label mandates expand.
Delivery Method:
Volume concentration in hospital settings privileges parenteral routes despite patient preference for oral alternatives.
- Injectable:Intramuscular and subcutaneous administration bypasses gastrointestinal degradation for peptides with poor oral bioavailability. Hospital formularies in United States integrated delivery networks standardize on injectable glycopeptides and lipopeptides for severe infections.
- Intravenous:Direct vascular delivery achieves immediate therapeutic concentrations for sepsis and endocarditis. Academic medical centers drive adoption of extended-infusion vancomycin protocols.
- Oral:Enzymatic breakdown in the gut and poor membrane permeability restrict peptide bioavailability below therapeutic thresholds for most agents.
- Topical:Localized delivery for skin and soft tissue infections avoids systemic exposure. Limited commercial penetration outside compounded formulations.
Injectable dominates current volume, with intravenous holding the steepest expansion trajectory as extended-infusion protocols proliferate.
End User:
Customer type determines pricing power, with consolidated health systems extracting volume discounts unavailable to fragmented research buyers.
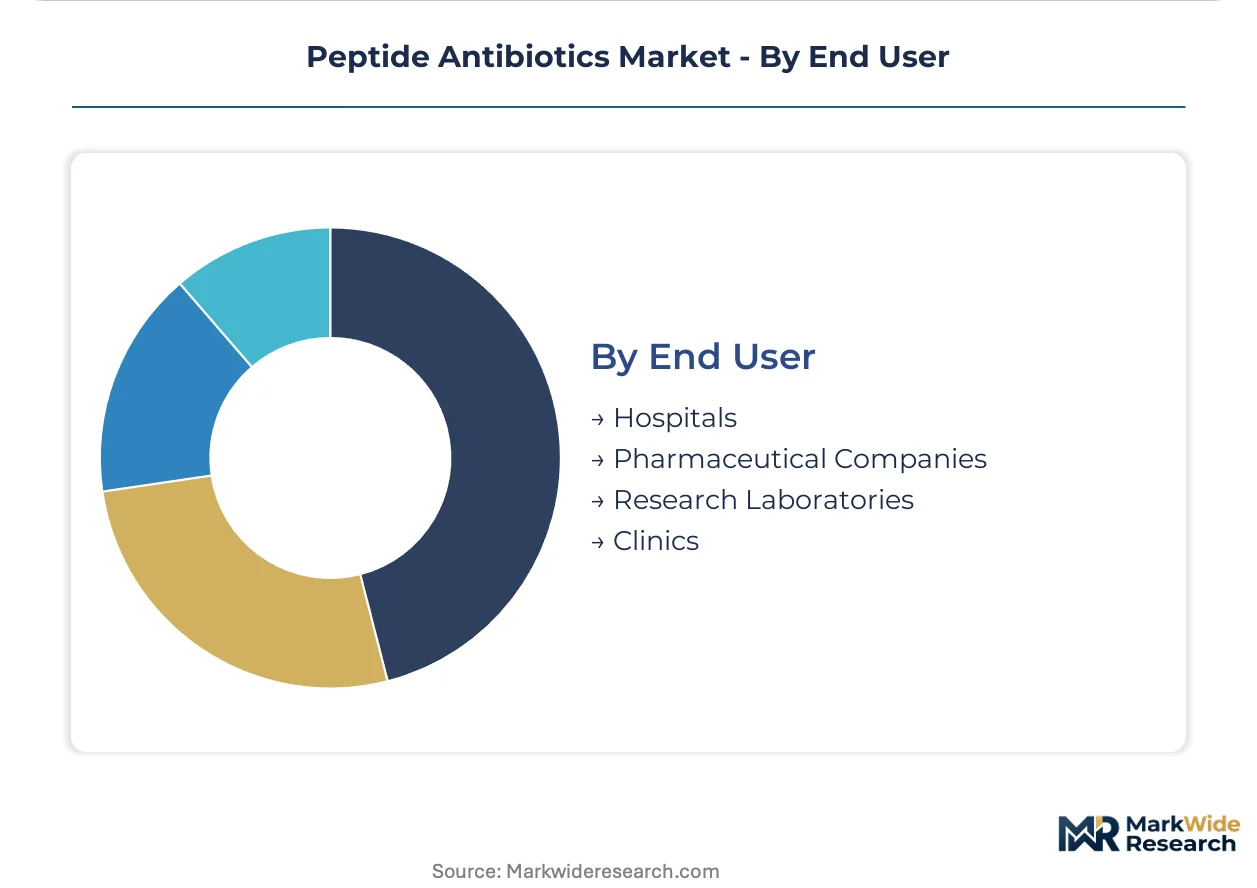
- Hospitals:Inpatient facilities administer peptide antibiotics through centralized pharmacy operations. Mega-systems controlling over sixty percent of United States inpatient bed capacity in California and Texas have consolidated antibiotic formularies under pharmacy and therapeutics committees.
- Pharmaceutical Companies:Developers source active pharmaceutical ingredients and conduct formulation development for novel candidates. Contract manufacturers in South Korea and Singapore are building dedicated capacity for complex cyclic peptide production.
- Research Laboratories:Academic centers conduct mechanistic studies and resistance surveillance. Peptide chemist talent scarcity in synthetic biology and solid-phase synthesis concentrates expertise at a handful of institutions.
- Clinics:Outpatient settings administer limited peptide antibiotic regimens, primarily oral alternatives where bioavailability permits.
Hospitals anchor procurement volume, with pharmaceutical companies expanding fastest as outsourced manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide chemist expertise clusters in United States academic centers and European fermentation hubs, anchoring global production capacity and clinical adoption patterns.
United States
Academic medical centers in Boston and Houston drive clinical demand for advanced glycopeptide and lipopeptide agents against multidrug-resistant infections. The FDA's Qualified Infectious Disease Product program accelerates development timelines through priority review and extended exclusivity. Pfizer leverages manufacturing scale to supply vancomycin and daptomycin to integrated delivery networks consolidating procurement across California and Texas.
Germany
REACH authorization requirements for novel biocidal substances tighten environmental discharge standards for antimicrobial peptide manufacturing. Glycopeptide producers with legacy fermentation facilities face capital-intensive wastewater treatment upgrades to maintain operating licenses. The Cologne-Düsseldorf corridor hosts specialized contract manufacturers building dedicated capacity for complex cyclic peptide production.
India
Active pharmaceutical ingredient supply concentration for fermentation-based cyclic peptides depends on contract manufacturers in Hyderabad and Ahmedabad. CDSCO regulatory pathways shape registration timelines for novel peptide antibiotics entering the domestic market. Workforce expansion for commercial-scale synthetic biology operations remains constrained by peptide chemist talent scarcity.
South Korea
Biopharma contract manufacturers in Seoul and Incheon are constructing dedicated fermentation facilities for complex cyclic peptide production. MFDS streamlined approval frameworks reduce time-to-market for novel anti-infective agents targeting resistant Gram-positive pathogens. Current Good Manufacturing Practice compliance timelines require 18-24 months for pre-approval inspection clearance.
Belgium
European Chemicals Agency cumulative assessment approaches force reformulation of process intermediates for glycopeptide producers. The Antwerp-Ghent industrial zone concentrates fermentation capacity serving food preservation bacteriocin applications. EMA antibacterial framework revisions accelerate market access for veterinary glycopeptide products.
Peptide Antibiotics Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across peptide antibiotic manufacturing tiers. The vendor base stratifies between scale-driven pharmaceutical majors and niche fermentation contractors. Three archetypes dominate: vertically integrated innovators controlling synthesis-to-distribution pipelines, technology licensors monetizing platform patents, and regional API suppliers serving formulation developers. Competitive moves center on M&A to secure fermentation capacity and strategic partnerships to access synthetic biology expertise.
Among diversified pharmaceutical majors, Pfizer, Merck, and Eli Lilly and Company occupy positions exemplifying scale-driven supply to consolidated health systems. Pfizer represents the manufacturing-scale archetype serving integrated delivery networks. Merck anchors R&D-intensive positioning in novel lipopeptide development. Eli Lilly and Company exemplifies specialized fermentation capabilities for complex cyclic peptides. These three entities collectively illustrate the competitive tension between breadth and depth in peptide antibiotic commercialization.
| Leading Market Players |
|---|
| Pfizer |
| Merck |
| AbbVie |
| Eli Lilly and Company |
| Xellia Pharmaceuticals |
| Teva Pharmaceuticals Industries |
| Sanofi |
| GSK |
| The Menarini Group |
| Others |
Cost & Logistics Intelligence
Solid-phase peptide synthesis automation is compressing manufacturing cycle times while simultaneously concentrating production capacity among contract manufacturers with capital-intensive equipment installations. This technological transition simultaneously lowers unit economics for complex cyclic peptides and amplifies pricing power for fermentation specialists serving integrated delivery networks.
Pricing Analysis
The bundled-versus-unbundled service split separates contract manufacturing organizations offering full-cycle development from commodity API suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks purity specifications and regulatory documentation depth. Cost compression in the standard tier is intensifying because hospital procurement consolidation extracts volume discounts from suppliers serving mega-systems. Research laboratories exhibit highest price sensitivity due to fragmented purchasing, while pharmaceutical companies demonstrate lowest sensitivity given downstream margin capture.
Supply Chain Analysis
Direct-to-pharmaceutical-company channels handle bulk active pharmaceutical ingredient demand from formulation developers. Fermentation-based production draws from specialized contract manufacturers in China, India, and South Korea. Raw material dependencies include amino acid feedstocks, specialized resins for solid-phase synthesis, and sterile filtration membranes. Single-source vulnerability concentrates in cyclic peptide fermentation capacity, where Current Good Manufacturing Practice compliance timelines extend facility qualification periods. Distribution runs through integrated delivery network centralized pharmacy operations in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in peptide antibiotics rests on fermentation scale-up efficiencies and premium-tier positioning for Qualified Infectious Disease Product-designated therapies. The shift toward clean-label food preservation in Europe creates parallel premiumization tracks outside hospital procurement.
For Market Incumbents: Hedge against API supply concentration by securing captive fermentation capacity in South Korea or Singapore. Anchor formulary position through extended-infusion protocol partnerships with academic medical centers in Boston and Houston. Defensive consolidation should prioritize synthetic biology talent acquisition as workforce scarcity constrains commercial-scale expansion. For New Entrants and Emerging Players: The price-point gap between premium glycopeptide formulations and economy-tier generic vancomycin creates entry space for specialized bacteriocin producers. Target food preservation applications in Germany and France where REACH authorization requirements deter established pharmaceutical players. A contract research organization partnership model reduces capital barriers to fermentation scale-up. For Investors and Strategic Acquirers: Valuations sit cheapest among regional API suppliers with legacy fermentation assets requiring wastewater treatment upgrades. Long-term viability over the next decade hinges on regulatory incentive capture through FDA Qualified Infectious Disease Product pathways or EMA antibacterial framework acceleration. Monitor FDA guidance publication timelines as the inflection signal for combination peptide therapy investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Specialized Fermentation Capacity Expansion | South Korean contract manufacturers are constructing dedicated facilities for complex cyclic peptide production under MFDS oversight. |
| Regulatory Incentive Capture | FDA Qualified Infectious Disease Product designation accelerates clinical timelines and extends market exclusivity for novel lipopeptide candidates. |
| Synthetic Biology Talent Acquisition | Peptide chemist expertise concentration at United States academic centers constrains workforce expansion for commercial operations. |
| Clean-Label Food Preservation Pivot | European manufacturers displace chemical preservatives with nisin and pediocin under tightening REACH authorization requirements. |
| Integrated Delivery Network Partnership | Hospital procurement consolidation in California and Texas mega-systems compresses supplier margins while amplifying volume commitments. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors grounded qualitative assessment. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation cross-checked segment estimates.
Output projections span product type, application, delivery method, and end user across the analysis window. CAGRs were derived from patent expiry schedules, resistance pattern trajectories, and regulatory incentive uptake curves. Forecast inputs incorporated fermentation capacity buildout timelines and hospital system consolidation patterns.
Caveats apply where FDA guidance revisions, EMA antibacterial framework modifications, or EPA pesticide tolerance threshold adjustments could materially shift the outlook. Forecasts reflect documented assumptions regarding clinical trial enrollment rates and manufacturing scale-up success. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Paediatric Oncology Therapeutics Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Global Upstream Bioprocessing Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market