
 Global Immune Repertoire Sequencing Market | 2026-2036
Global Immune Repertoire Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Immune Repertoire Sequencing Market Foresight
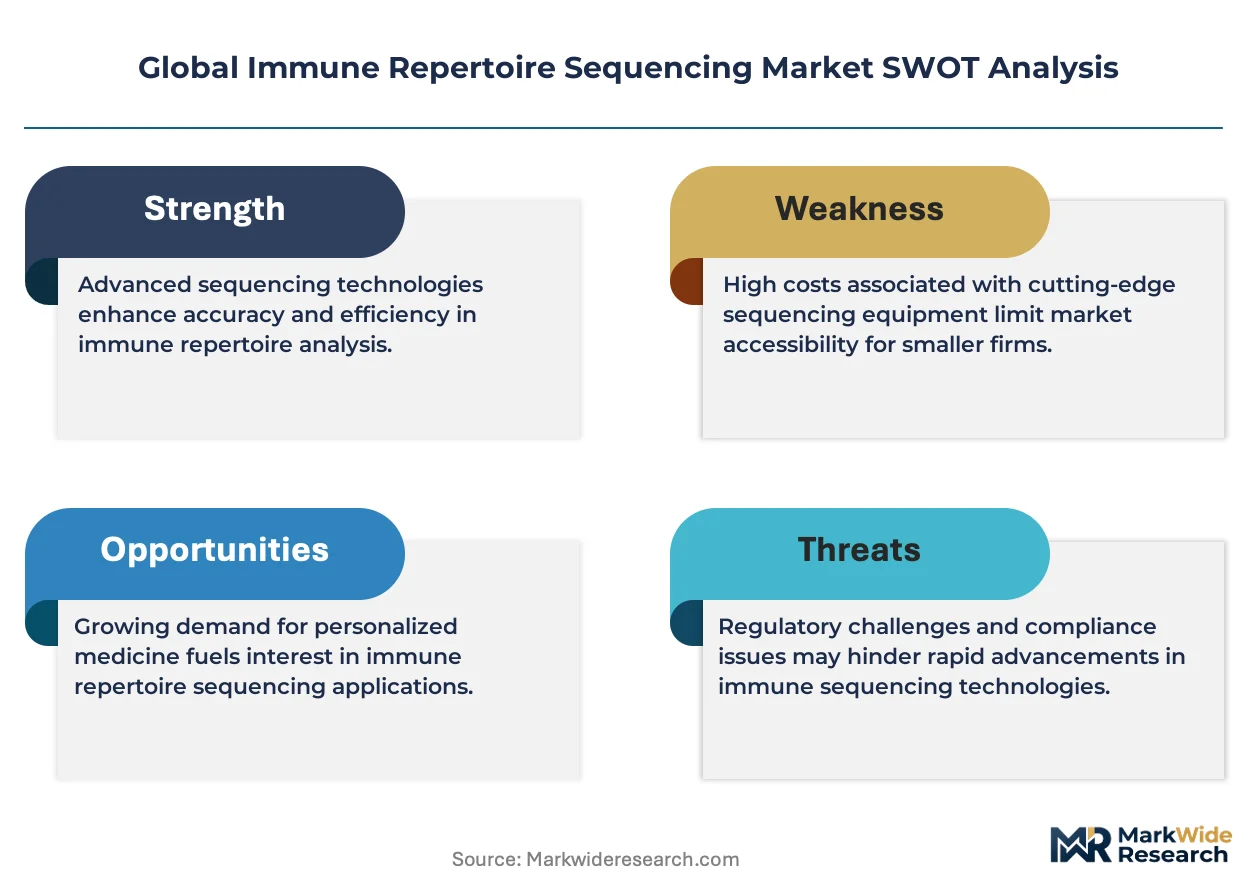
Bioinformatics talent scarcity is reorganizing competitive dynamics as platforms race to secure computational immunologists and pipeline engineers. Illumina sustains technology leadership through its dominant sequencing instrument installed base and integrated software ecosystems. Adaptive Biotechnologies specializes in clinical-grade immune repertoire diagnostics, anchoring its position through FDA-cleared assays for minimal residual disease detection. Thermo Fisher Scientific extends its reach across reagent supply chains and sample preparation workflows, competing on scale and channel density.
Immune repertoire sequencing captures the full diversity of B-cell and T-cell receptor sequences within a biological sample, typically resolving clonotypes at single-nucleotide resolution through multiplex PCR or 5' RACE amplification coupled with high-throughput readout. Its primary commercial purpose lies in mapping adaptive immune responses to identify therapeutic targets, monitor treatment efficacy, and stratify patient populations in immuno-oncology. Reagents and consumables generate recurring revenue streams that outpace instrument sales, as laboratories run high-frequency profiling panels for longitudinal studies. Cancer immunotherapy applications command premium positioning due to pharmaceutical sponsorship of companion diagnostic development, while single-cell sequencing technology captures the fastest expansion as researchers demand clonal resolution within heterogeneous tissue microenvironments.
The FDA regulates immune repertoire assays as in vitro diagnostics or research-use-only products depending on clinical claims, creating bifurcated commercialization pathways that shape go-to-market investment. The EMA's In Vitro Diagnostic Regulation and Japan's PMDA quality management requirements add compliance layers for multinational platform vendors seeking access to European and Japanese clinical markets. China's NMPA has streamlined innovation pathways for domestic genomic tools, accelerating local competitors. Stakeholders must monitor evolving reimbursement codes for immune profiling in oncology as payer decisions will determine whether clinical translation outpaces research demand.
Market Dynamics
Single-cell immune profiling is compressing turnaround times from weeks to days, forcing platform vendors to rearchitect workflows around droplet microfluidics and cloud-based clonotype assembly rather than bulk sequencing pipelines.
Growth Catalysts
- FDA Accelerated Approval Pathways:Biomarker-driven oncology therapies require immune repertoire data for regulatory submissions, expanding clinical-grade sequencing demand across pharmaceutical sponsors.
- 5' RACE Amplification Chemistry:Improved library preparation protocols reduce amplification bias in T-cell receptor sequencing, enabling more accurate clonotype frequency measurements in minimal residual disease monitoring.
- Boston Biotech Cluster Concentration:Dense proximity of academic medical centers and venture-backed immuno-oncology firms creates concentrated demand for standardized immune profiling protocols.
Market Restraints
- Illumina Reagent Supply Concentration:Dependence on a single dominant sequencing instrument vendor creates pricing power asymmetry and supply vulnerability for independent assay developers.
- Bioinformatics Talent Scarcity:Shortage of computational immunologists with expertise in V(D)J recombination analysis limits scaling of analytical services.
- Sample Preparation Complexity:Multiplex PCR workflows require specialized technical training, constraining adoption in hospital pathology laboratories without dedicated molecular teams.
Strategic Opportunities
- Japan PMDA Streamlined Review:Recent quality management pathway reforms reduce time-to-market for foreign immune repertoire diagnostics entering Japanese oncology centers.
- China NMPA Domestic Innovation Incentives:Accelerated approval tracks for locally developed genomic tools create opening for indigenous platform competitors to capture hospital laboratory procurement.
- Autoimmune Disease Applications:Expansion beyond oncology into rheumatoid arthritis and multiple sclerosis patient stratification opens new pharmaceutical sponsorship channels for repertoire-based companion diagnostics.
Industry Challenges
- Reimbursement Code Uncertainty:Absence of established CPT codes for immune profiling in solid tumor indications forces laboratories to absorb costs or pursue research billing.
- Cross-Platform Standardization Gaps:Lack of harmonized clonotype calling algorithms between sequencing platforms complicates multi-site clinical trial data integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Immune Repertoire Sequencing Market |
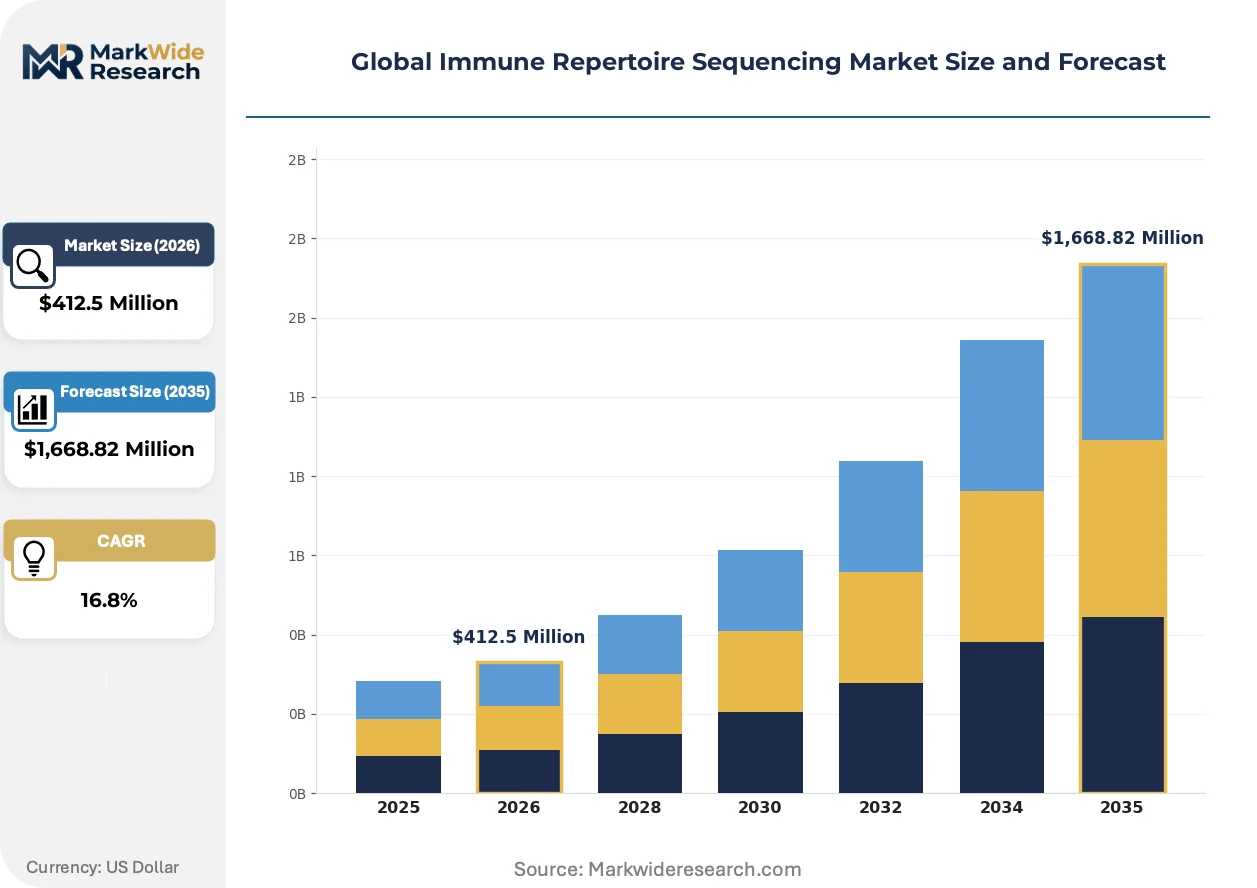
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,668.82 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instruments, Reagents, Consumables, Software Sequencing Technology: Next-Generation Sequencing, Single-Cell Sequencing, Microfluidics, Mass Cytometry, Digital PCR Application: Autoimmune Disorders, Infectious Diseases, Transplantation Monitoring, Cancer Immunotherapy, Vaccine Development End User: Research Institutes, Biotechnology Firms, Diagnostic Laboratories, Academic Centers |
| Companies Covered | Illumina, Thermo Fisher Scientific, Adaptive Biotechnologies, 10x Genomics, BGI Genomics, QIAGEN, F. Hoffmann-La Roche Ltd, Takara Bio, PacBio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Immune Repertoire Sequencing Market Shifts & Advancements
Workflow automation and regulatory data requirements are simultaneously pushing instrument footprints downward and analytical sophistication upward, creating bifurcated investment priorities across the vendor base.
Microfluidic droplet encapsulation systems for single-cell immune receptor sequencing are miniaturizing previously bulk-only workflows into benchtop formats. Academic core facilities and mid-sized biotechnology firms are adopting these platforms at replacement cycle intervals of 18-24 months. The technology is miniaturizing capital barriers to entry, enabling distributed sequencing capacity that challenges centralized service laboratory models.
The EMA's In Vitro Diagnostic Regulation imposes stricter performance documentation and post-market surveillance obligations on immune repertoire assays marketed in Europe. Manufacturers must maintain quality management systems exceeding previous CE-mark self-certification requirements. Multinational platform vendors are responding by consolidating European regulatory affairs functions and accelerating notified body engagement timelines.
Pharmaceutical sponsors now contract directly for longitudinal immune monitoring across trial cohorts rather than relying on investigator-initiated sequencing. This disintermediates traditional academic core facility relationships and concentrates purchasing authority within sponsor procurement functions. The shift is most visible in United States-based phase I/II immuno-oncology trials where real-time clonotype tracking informs dose-escalation decisions.
Global Immune Repertoire Sequencing Market Segmentation
Immune repertoire sequencing markets fragment across four distinct dimensions that shape procurement patterns and margin structures. Product type determines recurring revenue intensity. Sequencing technology governs analytical resolution limits. Application verticals channel pharmaceutical sponsorship. End-user categories concentrate purchasing authority differently across hospital systems, contract research organizations, and academic cores.
Product Type:
Reagents face acute substitution pressure from third-party manufacturers developing chemistry-compatible alternatives to dominant platform workflows.
- Reagents:Enzyme mixes, primers, and buffers constitute the highest-margin recurring revenue layer in immune profiling workflows. Pharmaceutical sponsors in Boston and San Francisco drive bulk procurement for longitudinal trial monitoring, creating volume concentration that rewards supply contract exclusivity.
- Consumables:Flow cells, cartridges, and single-use plastics scale linearly with sequencing throughput. Academic medical centers in Germany and Japan absorb premium pricing for clinical-grade consumables as EMA and PMDA quality requirements tighten vendor qualification standards.
- Instruments:Capital equipment anchors platform ecosystems through multi-year depreciation cycles and service contracts.
- Software:Clonotype assembly and V(D)J annotation tools face open-source competition from academic pipelines.
Reagents retain volume leadership; consumables hold the steepest expansion curve as throughput demands intensify.
Sequencing Technology:
Cost tiering separates clinical-grade certification from research-use flexibility, with reimbursement eligibility governing adoption ceilings.
- Single-Cell Sequencing:Droplet microfluidics and combinatorial indexing resolve clonal heterogeneity within tumor microenvironments. Biotechnology firms in Cambridge, Massachusetts and Basel, Switzerland prioritize these platforms for CAR-T target discovery, compressing turnaround times from weeks to days.
- Next-Generation Sequencing:Bulk immune repertoire profiling via Illumina and Thermo Fisher workflows dominates minimal residual disease monitoring. Diagnostic laboratories in the United States leverage FDA-cleared assays for leukemia surveillance, anchoring clinical validation requirements.
- Microfluidics:Benchtop encapsulation systems miniaturize previously core-facility-dependent workflows.
- Mass Cytometry:Metal-isotope tagging preserves tissue architecture for spatial immune mapping.
- Digital PCR:Absolute quantification of rare clonotypes supports minimal residual disease sensitivity thresholds.
Next-generation sequencing maintains installed base dominance; single-cell sequencing gains share fastest as resolution demands escalate.
Application:
Customer maturity varies sharply, with oncology commanding structured pharmaceutical budgets while autoimmune indications rely on exploratory research funding.
- Cancer Immunotherapy:Checkpoint inhibitor companion diagnostics and CAR-T target identification concentrate sponsorship from Roche, Bristol Myers Squibb, and Novartis. The FDA's accelerated approval pathways mandate immune repertoire data for biomarker-driven submissions, institutionalizing clinical-grade sequencing demand.
- Autoimmune Disorders:Rheumatoid arthritis and multiple sclerosis patient stratification remains pre-commercial, with academic consortia in the United Kingdom and Sweden advancing proof-of-concept studies. Pharmaceutical interest is deepening as T-cell receptor signatures predict treatment response.
- Infectious Diseases:Vaccine-induced clonotype tracking supports pandemic preparedness and pathogen-specific response characterization.
- Transplantation Monitoring:Graft-versus-host disease prediction requires longitudinal T-cell repertoire surveillance.
- Vaccine Development:Immunogen design relies on germline-targeting antibody lineage reconstruction.
Cancer immunotherapy commands revenue concentration; autoimmune disorders present the most rapid application expansion as pharmaceutical pipelines diversify.
End User:
Procurement centralization differs across institutional types, with biotechnology firms consolidating purchasing authority while academic centers fragment decision-making.
- Biotechnology Firms:Venture-backed immuno-oncology companies in South San Francisco and Kendall Square contract directly for immune monitoring, disintermediating traditional academic core relationships. Real-time clonotype tracking informs phase I/II dose-escalation decisions, concentrating platform vendor relationships within sponsor procurement functions.
- Research Institutes:Broad Institute, RIKEN, and Max Planck networks maintain diversified instrument portfolios to preserve experimental flexibility. Grant-funded procurement prioritizes publication-grade reproducibility over regulatory certification.
- Diagnostic Laboratories:Hospital-based molecular pathology groups require CLIA-compliant workflows and established CPT reimbursement codes.
- Academic Centers:University core facilities face pricing pressure from commercial service laboratories.
Biotechnology firms anchor premium segment demand; diagnostic laboratories represent the fastest-climbing volume tier as reimbursement pathways stabilize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways for biomarker-driven oncology therapies anchor United States demand, while EMA quality requirements and Japan's PMDA reforms reshape multinational vendor strategies across three additional major markets.
United States
The National Cancer Institute funds longitudinal immune profiling consortia, while Boston's Kendall Square and San Francisco's South San Francisco biotech clusters concentrate pharmaceutical sponsorship of companion diagnostic development. FDA clearance requirements for minimal residual disease assays institutionalize clinical-grade sequencing procurement patterns.
Germany
EMA In Vitro Diagnostic Regulation imposes stricter post-market surveillance on immune repertoire assays than prior CE-mark self-certification, consolidating vendor quality management investments in Baden-Württemberg and Bavaria. Heidelberg and Munich academic medical centers drive protocol standardization for multi-site European trials.
China
NMPA streamlined innovation pathways accelerate domestic genomic tool approvals, creating procurement openings for local platform competitors in Beijing-Tianjin-Hebei and Yangtze River Delta hospital laboratories. Shanghai and Shenzhen biotech parks concentrate immune profiling startup formation.
Japan
PMDA quality management pathway reforms reduce foreign diagnostic time-to-market, expanding access for immune repertoire platforms in Tokyo and Osaka oncology centers. RIKEN institutes maintain diversified instrument portfolios for publication-grade reproducibility.
Switzerland
Swissmedic certification requirements align with EMA standards while Basel's pharmaceutical headquarters sponsor CAR-T target discovery programs. Zurich and Geneva academic cores prioritize single-cell resolution platforms for heterogeneous tissue microenvironment research.
Global Immune Repertoire Sequencing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with sequencing instrument vendors commanding ecosystem control through reagent lock-in and software integration. Platform consolidation around FDA-cleared diagnostics creates tiered competitive positioning, while bioinformatics talent scarcity forces acquisition strategies over organic development. Specialists compete on analytical resolution, workflow automation, or disease-specific assay validation. Dominant moves include strategic partnerships with pharmaceutical sponsors for longitudinal trial monitoring and geographic expansion through notified body engagement in Europe and Asia-Pacific.
Within the integrated instrumentation tier, Illumina and Thermo Fisher Scientific exemplify ecosystem control through installed base dominance and channel density. Adaptive Biotechnologies occupies a distinct position anchoring clinical-grade immune repertoire diagnostics through regulatory-cleared assays. These three represent contrasting archetypes: sequencing infrastructure, reagent supply chain scale, and specialized diagnostic validation.
| Leading Market Players |
|---|
| Illumina |
| Thermo Fisher Scientific |
| Adaptive Biotechnologies |
| 10x Genomics |
| BGI Genomics |
| QIAGEN |
| F. Hoffmann-La Roche Ltd |
| Takara Bio |
| PacBio |
| Others |
Supply & Pricing Matrix
Ninety-day reagent inventory cycles at United States diagnostic laboratories signal pricing power asymmetry that favors dominant sequencing instrument vendors over independent assay developers. This lead-time compression concentrates procurement leverage within Illumina's channel ecosystem while forcing third-party chemistry suppliers into volume discounting to secure hospital laboratory contracts.
Pricing Analysis
United States clinical-grade consumables command 40-60% premiums over European research-use equivalents due to FDA clearance requirements and Boston biotech cluster demand concentration. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-certified diagnostics from exploratory research panels and academic core facility bulk purchasing. Cost compression in standard-tier reagents is intensifying because third-party manufacturers are developing chemistry-compatible alternatives to dominant platform workflows. Hospital pathology laboratories without dedicated molecular teams exhibit highest price sensitivity, while pharmaceutical sponsors in San Francisco demonstrate lowest sensitivity due to trial budget insulation.
Supply Chain Analysis
China and the United States anchor global reagent manufacturing, with Shanghai biotech parks concentrating domestic enzyme production and San Diego supply chains feeding North American pharmaceutical demand. Multiplex PCR primer sets, flow cell consumables, and V(D)J analysis software licenses constitute critical input dependencies. Single-source vulnerability around Illumina sequencing instruments creates supply disruption exposure for assay developers lacking alternative platform validation. Distribution runs through direct vendor relationships with biotechnology sponsors and contracted service laboratories, bypassing traditional academic core facility intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Immune repertoire sequencing sits in early-cycle expansion as FDA accelerated approval pathways institutionalize clinical-grade sequencing demand across pharmaceutical oncology pipelines. Single-cell resolution capabilities and autoimmune disease application expansion provide dual penetration vectors beyond established cancer immunotherapy dominance.
For Market Incumbents: Fortify ecosystem lock-in through integrated software pipelines that embed clonotype assembly workflows within sequencing instrument control systems. Deepen reagent supply contracts with Boston and San Francisco biotechnology clusters to preempt third-party chemistry substitution. Prioritize CLIA laboratory partnerships that secure longitudinal trial monitoring relationships before pharmaceutical sponsors consolidate procurement authority.
For New Entrants and Emerging Players: Lead with autoimmune disease stratification assays in European and Japanese markets where regulatory pathways are clarifying faster than oncology companion diagnostic saturation. Target mid-sized biotechnology firms in Basel and Cambridge lacking in-house immune profiling infrastructure. Pursue cloud-native clonotype analysis platforms that displace legacy bioinformatics talent dependencies.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because bioinformatics talent scarcity and regulatory certification barriers favor acquisition strategies over organic capability development. Focus on computational immunology teams with validated V(D)J algorithms and notified body relationships in Europe and Asia-Pacific. Monitor reimbursement code establishment for immune profiling in solid tumor indications as the critical inflection signal for clinical translation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA-cleared minimal residual disease assays anchor premium pricing tiers in United States oncology centers. |
| Strategic Partnership | Pharmaceutical sponsor contracts for longitudinal trial monitoring disintermediate academic core facility relationships. |
| Acquisition of Specialist Firm | Computational immunology teams with V(D)J expertise address acute bioinformatics talent scarcity constraints. |
| Platform Integration | Cloud-based clonotype assembly tools compress turnaround times from weeks to days for biotechnology sponsors. |
| Geographic Expansion | Notified body engagement in Germany and Japan unlocks EMA and PMDA quality management compliance pathways. |
Research Methodology
Operator-level perspectives from immuno-oncology drug development executives, CLIA laboratory directors, regulatory affairs specialists at sequencing platform vendors, and hospital procurement managers anchored the qualitative base. Primary interview findings triangulated against FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, ClinicalTrials.gov protocol specifications, and Japanese PMDA quality management system requirements. Secondary validation drew from biotechnology firm SEC disclosures, academic consortia publication records, and GPO contract databases. Bottom-up segment sizing and top-down market triangulation cross-verified volume and value estimates.
Sensitivity analysis tested forecast robustness across adoption rate scenarios for single-cell immune profiling platforms and autoimmune disease application expansion trajectories. The analytical framework modeled product type, sequencing technology, application vertical, and end-user category dimensions across the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating pharmaceutical sponsor budget allocation patterns, reimbursement pathway progression, and technology substitution elasticities. Instrument replacement cycle intervals and reagent consumption per sequencing run provided industry-specific forecast anchors.
The analysis sits within stated boundaries; outcomes outside FDA reimbursement code establishment, EMA notified body capacity constraints, or sustained pharmaceutical R&D budget allocation would require recalibration. Forecasts reflect documented assumptions regarding clinical translation velocity and regulatory pathway clarity. Recalibration cycles align with material shifts in payer coverage decisions, platform technology transitions, and multinational quality management requirement harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
United States Cancer Biomarkers Market
Genomics
Global Single-Cell Genome Sequencing Market
Genomics
Gene Sequencing Market
Genomics
Genetic Testing Service Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
Apolipoprotein Test Market
Genomics
Next Generation Molecular Assay Market
Genomics
Mitochondrial DNA Market
Genomics
Single-Cell Omics Market
Genomics
US Genetic Testing Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Mrna Sequencing Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market