
 Beta Interferon Market | 2026-2036
Beta Interferon Market Size, Share, and Industry Trends Forecast 2026-2036
Beta Interferon Market Analytics
Subscription-based patient support programs is recalibrating how beta interferon manufacturers monetize chronic therapy relationships. Biogen Inc. anchors its market presence through deep neurologist channel relationships and long-acting formulation development. Merck KGaA differentiates via European manufacturing scale and established hospital supply contracts. F. Hoffmann-La Roche Ltd leverages its diagnostic-neurology ecosystem to sustain brand loyalty in high-prescriver networks.
Beta interferon comprises a class of recombinant cytokines, specifically glycoproteins with 166 amino acids produced through mammalian cell culture, that modulate immune response by inhibiting viral replication and T-cell activation. These biologics serve primarily as disease-modifying therapies for relapsing-remitting multiple sclerosis and select autoimmune indications. Interferon Beta-1a dominates value generation due to its established efficacy profile and preference among neurologists for intramuscular administration with lower immunogenicity risk. The homecare settings segment is expanding fastest as self-injection devices and telehealth monitoring reduce clinic dependency. Pegylated interferon retains premium positioning in oncology adjuvant protocols where dosing interval extension commands measurable adherence advantages.
The FDA, EMA, and Japan's PMDA collectively enforce evolving biosimilar interchangeability standards that determine automatic substitution authority and thus competitive dynamics. The FDA's BPCIA guidance and EMA's biosimilar quality requirements shape development costs and market access timelines for follow-on entrants. Stakeholders must monitor regulatory divergence on interchangeability labeling and real-world evidence requirements as these decisions will determine whether originator brands retain pricing power or face accelerated erosion.
Market Dynamics
The FDA's biosimilar approval pathway under BPCIA is compressing originator pricing power while accelerating competitive entry into multiple sclerosis maintenance therapy. Neurology departments at hospital systems are expanding beta interferon prescribing as first-line disease-modifying therapy protocols harden.
Growth Catalysts
- Interchangeability Standards:The FDA's evolving biosimilar interchangeability guidance under BPCIA grants automatic substitution authority to qualifying follow-on products, expanding pharmacy-level access for patients.
- Homecare Infusion:Self-injection devices with telehealth monitoring capabilities are reducing clinic dependency and extending therapy adherence windows for relapsing-remitting multiple sclerosis patients.
- Neurology Channel Expansion:Hospital systems in the United States, Germany, and Japan are building dedicated multiple sclerosis centers with embedded infusion capabilities and specialized nursing support.
Market Restraints
- Mammalian Cell Culture Costs:Recombinant glycoprotein production through Chinese hamster ovary lines requires expensive serum-free media and extended batch timelines that constrain margin expansion.
- Immunogenicity Surveillance:Neutralizing antibody development in subcutaneous interferon beta-1b regimens necessitates costly monitoring protocols that burden payor reimbursement frameworks.
- Oral Small-Molecule Displacement:Sphingosine-1-phosphate receptor modulators and other oral disease-modifying therapies are capturing treatment-naive patient cohorts previously routed to injectable biologics.
Strategic Opportunities
- Pegylated Formulation Extension:PEG-conjugated interferon variants enable extended dosing intervals that command premium positioning in oncology adjuvant protocols where adherence correlates with outcomes.
- Diagnostic-Neurology Ecosystem Integration:MRI lesion monitoring platforms paired with therapy selection algorithms create sticky prescriber relationships and reduce switching behavior.
- Real-World Evidence Pathways:The FDA's acceptance of patient registry data for biosimilar interchangeability determinations lowers post-approval study costs for follow-on developers.
Industry Challenges
- Cold Chain Integrity:Temperature excursion risks during last-mile distribution of temperature-sensitive biologics require redundant monitoring infrastructure that elevates logistics costs.
- Patent Thicket Navigation:Process patent claims covering mammalian cell culture conditions and purification methods create licensing complexity for biosimilar entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beta Interferon Market |
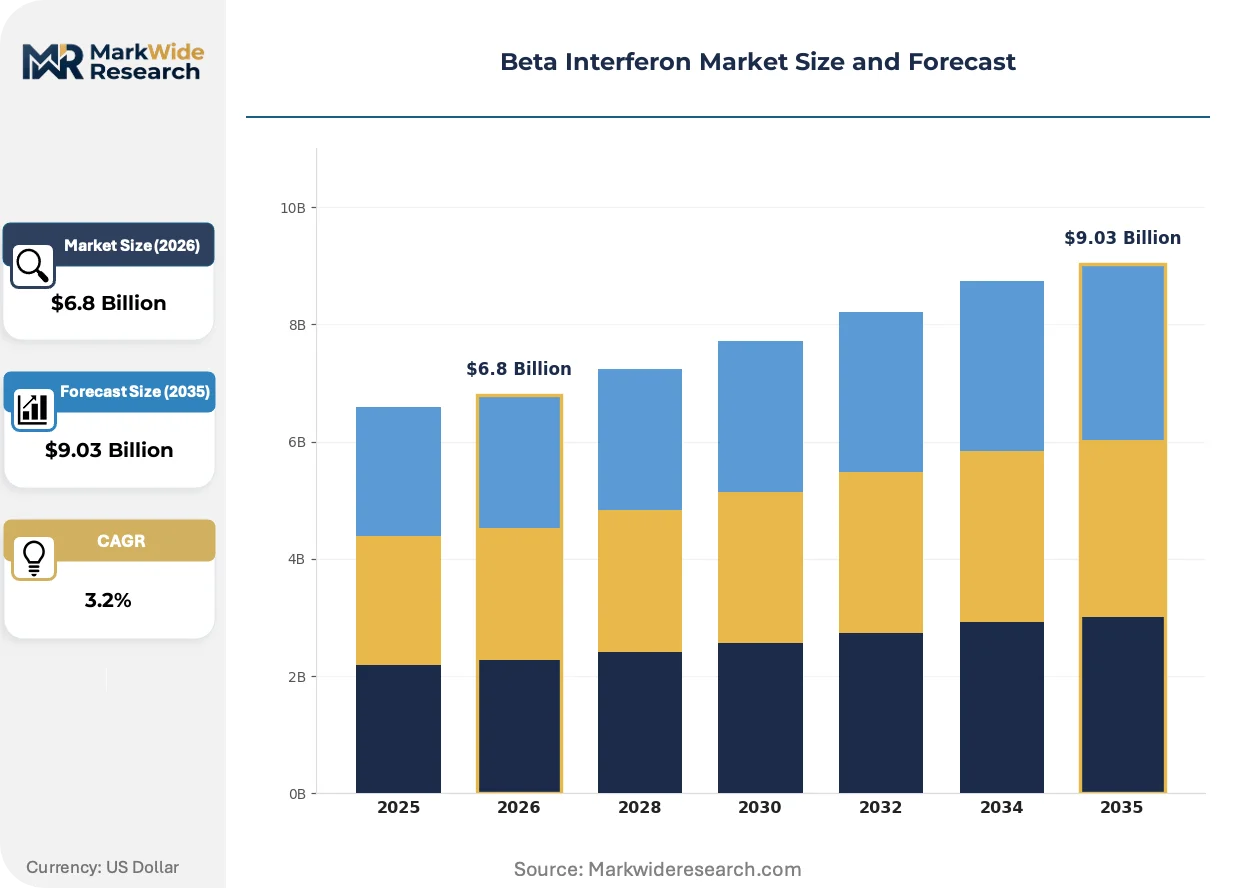
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.03 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Beta Interferon, Interferon Beta-1a, Interferon Beta-1b, Pegylated Interferon Therapy Area: Multiple Sclerosis, Hepatitis C, Oncology, Autoimmune Disorders End User: Hospitals, Research Institutes, Homecare Settings, Outpatient Clinics Administration Route: Subcutaneous, Intravenous, Intramuscular, Oral |
| Companies Covered | Biogen Inc., Merck KGaA, Bayer AG, Pfizer Inc., F. Hoffmann-La Roche Ltd, Novartis AG, Bristol-Myers Squibb, Zydus Cadila, Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beta Interferon Market Evolving Landscape
Long-acting formulation development and digital adherence monitoring are reshaping how beta interferon manufacturers capture and retain chronic therapy relationships. These shifts are compressing traditional competitive moats while opening new value-capture mechanisms.
PEGylation chemistry is consolidating competitive positioning in the beta interferon class by extending circulatory half-life and enabling less frequent dosing. Neurology practices with high multiple sclerosis patient volumes are adopting pegylated interferon beta-1a as their preferred maintenance protocol. This technology is consolidating market share among patients with high injection burden or needle anxiety who previously cycled through standard formulations.
The EMA's tightened biosimilar quality requirements and real-world evidence mandates are extending development timelines for European market entry. Follow-on manufacturers must now demonstrate comparable immunogenicity profiles through extended pharmacovigilance studies before gaining automatic substitution rights. German hospital pharmacy committees are responding by tightening tender specifications that favor originator brands with longer safety track records.
Subscription-based patient support programs are displacing traditional fee-for-service adherence coaching in the United States. Third-party hub services that coordinate injection training, refill reminders, and copay assistance are capturing patient relationship ownership from specialty pharmacies. This shift is most visible in California and New York health systems where integrated delivery networks negotiate bundled outcomes contracts with biologic manufacturers.
Beta Interferon Market Segmentation
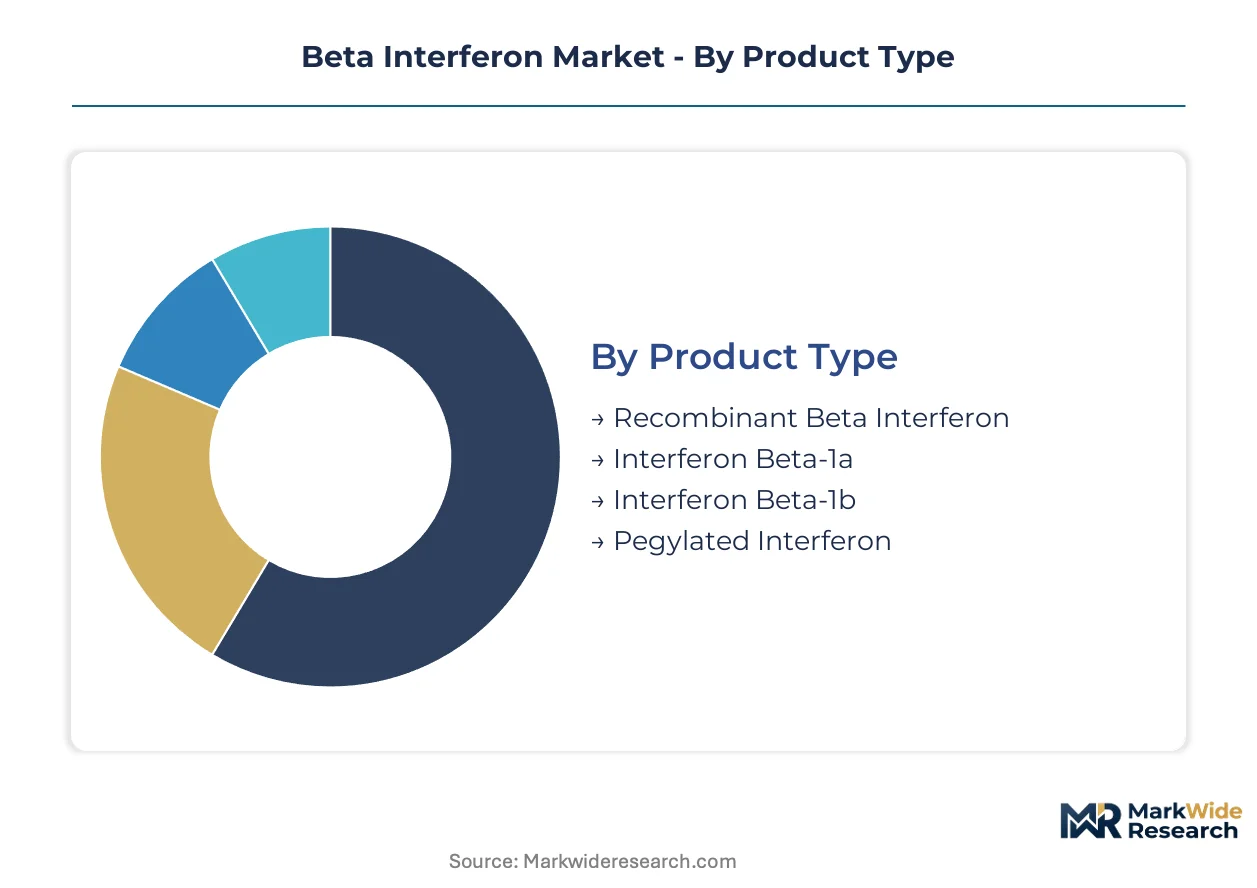
Segmentation in the beta interferon market reveals how manufacturing complexity, clinical protocol preferences, and reimbursement frameworks fragment commercial opportunity across distinct product and channel configurations. Understanding these divisions exposes where margin concentrates and where competitive entry faces lowest barriers.
Product Type:
Supply concentration in mammalian cell culture capacity favors established producers with validated CHO lines and serum-free media protocols, creating tiered access economics for different molecular formats.
- Interferon Beta-1a:Glycoprotein produced in mammalian cells with established glycosylation patterns that reduce immunogenicity risk versus bacterially expressed alternatives. Demand concentrates in the United States and Germany where neurologists prefer intramuscular administration for treatment-naive multiple sclerosis patients. The FDA's biosimilar interchangeability pathway under BPCIA is accelerating competitive entry and compressing originator pricing power in this segment.
- Pegylated Interferon:PEG-conjugated variants extending circulatory half-life through reduced renal clearance and proteolytic protection. Oncology adjuvant protocols in Japanese hospital systems command premium positioning where dosing interval extension correlates with measurable adherence advantages. EMA quality requirements for PEGylation chemistry and linker stability extend development timelines for European market entry.
- Recombinant Beta Interferon:Broad category encompassing non-glycosylated bacterial expression products with lower production costs but higher neutralizing antibody incidence.
- Interferon Beta-1b:Non-glycosylated variant produced in E. coli with subcutaneous administration protocols requiring more frequent immunogenicity surveillance.
Interferon Beta-1a absorbs the bulk of installed capacity; Pegylated Interferon is expanding most quickly.
Therapy Area:
Application-driven demand patterns split manufacturing capacity between chronic maintenance indications and acute oncology protocols with diverging margin profiles.
- Multiple Sclerosis:Dominant maintenance indication for relapsing-remitting disease where beta interferon established first-line disease-modifying therapy status. Hospital systems in the United States, Germany, and Japan are building dedicated multiple sclerosis centers with embedded infusion capabilities. Oral small-molecule displacement from sphingosine-1-phosphate receptor modulators is capturing treatment-naive cohorts previously routed to injectable biologics.
- Oncology:Adjuvant melanoma and select hematologic malignancy protocols where pegylated formulations command dosing interval premiums. Japanese and German reimbursement frameworks for injectable biologics sustain favorable access economics despite biosimilar pressure elsewhere.
- Hepatitis C:Declining indication as direct-acting antiviral regimens displace interferon-based protocols in most markets.
- Autoimmune Disorders:Niche applications in select vasculitis and uveitis subtypes with limited label expansion.
Multiple Sclerosis commands dominant manufacturing allocation; Oncology maintains the steepest expansion trajectory.
End User:
Channel configuration determines cold chain requirements, patient support infrastructure investment, and who captures the ongoing therapy relationship.
- Homecare Settings:Self-injection devices with telehealth monitoring capabilities are reducing clinic dependency and extending adherence windows. Subscription-based patient support programs in California and New York health systems are displacing traditional fee-for-service adherence coaching. Integrated delivery networks negotiate bundled outcomes contracts that shift relationship ownership toward third-party hub services.
- Hospitals:Neurology departments at United States hospital systems are expanding beta interferon prescribing as first-line protocols harden. German hospital pharmacy committees are tightening tender specifications that favor originator brands with longer safety track records.
- Outpatient Clinics:Specialized infusion centers with nursing support for patients requiring supervised administration.
- Research Institutes:Preclinical and clinical trial supply with distinct quality and documentation requirements.
Homecare Settings are climbing the fastest; Hospitals retain the largest volume share.
Administration Route:
Route selection shapes immunogenicity surveillance burden, patient training requirements, and competitive differentiation through device innovation.
- Intramuscular:Preferred administration for Interferon Beta-1a with lower injection site reaction incidence and reduced neutralizing antibody development versus subcutaneous alternatives. United States neurologists favor this route for treatment-naive patients with needle anxiety or high injection burden.
- Subcutaneous:Enables self-administration but requires more frequent immunogenicity monitoring protocols that burden payor reimbursement frameworks.
- Intravenous:Limited to select oncology protocols and acute settings with specialized nursing requirements.
- Oral:Not commercially available for beta interferon; included as placeholder for future formulation development.
Intramuscular administration captures the largest patient volume; Subcutaneous routes are gaining share fastest through homecare expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in mammalian cell culture facilities across Switzerland, Germany, and the United States, while consumption clusters in hospital systems with favorable biologic reimbursement. This geographic split shapes cross-border supply contracts and cold chain logistics investment.
United States
Neurology departments at Cleveland Clinic, Mayo Clinic, and Johns Hopkins anchor beta interferon prescribing volumes for relapsing-remitting multiple sclerosis maintenance. FDA's BPCIA biosimilar interchangeability pathway accelerates pharmacy-level substitution authority for qualifying follow-on products. The Northeast corridor from Boston to Philadelphia hosts the densest concentration of multiple sclerosis specialty centers with embedded infusion nursing.
Germany
Hospital pharmacy committees at Charité Berlin and University Hospital Heidelberg enforce tender specifications favoring originator brands with extended safety track records. EMA's tightened biosimilar quality requirements extend development timelines for European market entry. Bavaria and Baden-Württemberg concentrate manufacturing scale through established CHO line facilities serving EU hospital supply contracts.
Japan
PMDA's reimbursement frameworks for injectable biologics sustain premium positioning for pegylated interferon in oncology adjuvant protocols. Tokyo and Osaka metropolitan hospital systems command dosing interval premiums where adherence correlates with measurable outcomes. METI's pharmaceutical pricing reforms are compressing originator margins while preserving access for chronic maintenance indications.
Switzerland
Diagnostic-neurology ecosystem integration anchors prescriber loyalty through MRI lesion monitoring platforms paired with therapy selection algorithms. Basel and Zurich clusters concentrate biologics manufacturing with validated serum-free media protocols. Swissmedic's regulatory alignment with EMA standards facilitates parallel EU market access for domestic producers.
United Kingdom
NHS England's specialized commissioning frameworks route multiple sclerosis patients through designated neurology centers with embedded nursing support. MHRA's post-Brexit regulatory divergence from EMA creates dual-track approval complexity for biosimilar entrants. London and Manchester hospital systems are consolidating beta interferon prescribing within integrated care boards negotiating bundled outcomes contracts.
Beta Interferon Market Competitive Landscape
Capital-heavy producers with validated mammalian cell culture infrastructure compete with asset-light formulation specialists licensing manufacturing capacity. The vendor base stratifies across three tiers: integrated biopharmaceutical conglomerates with diagnostic ecosystems, mid-scale European manufacturers with hospital supply contracts, and emerging biosimilar developers exploiting FDA interchangeability pathways. Consolidation pressures intensify as oral small-molecule displacement shrinks addressable injectable volumes. Dominant competitive moves include long-acting formulation development and subscription-based patient support program deployment.
Within the integrated biopharmaceutical tier, Biogen Inc. and F. Hoffmann-La Roche Ltd exemplify archetypes leveraging diagnostic-neurology ecosystem integration to sustain prescriber loyalty. Merck KGaA occupies a position representing European manufacturing scale advantages through established CHO line facilities and hospital pharmacy committee relationships. These three anchors demonstrate how originator brands defend positioning through channel depth rather than molecule differentiation alone.
| Leading Market Players |
|---|
| Biogen Inc. |
| Merck KGaA |
| Bayer AG |
| Pfizer Inc. |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Bristol-Myers Squibb |
| Zydus Cadila |
| Dr. Reddy's Laboratories |
| Others |
Value Network & Pricing Analysis
Hospital pharmacy committee consolidation in Germany and tender specification tightening at Charité Berlin and University Hospital Heidelberg is forcing supply chain reconfiguration toward validated mammalian cell culture facilities with extended safety track records, compressing margin structures for biosimilar entrants lacking established CHO line pedigree.
Pricing Analysis
Margin tightening in the interferon beta-1a segment reflects FDA biosimilar interchangeability approvals under BPCIA accelerating pharmacy-level substitution authority. Three-tier pricing structure across originator premium, authorized generic standard, and biosimilar economy levels stratifies by glycosylation pattern certification and immunogenicity surveillance bundling. Cost-down pressure on subcutaneous formulations intensifies because oral small-molecule sphingosine-1-phosphate receptor modulators capture treatment-naive cohorts. German hospital systems exhibit highest price sensitivity; Japanese oncology adjuvant protocols retain lowest sensitivity due to adherence-outcome correlation.
Supply Chain Analysis
Returns of temperature-compromised biologics from last-mile distribution points in California and New York health systems necessitate redundant cold chain monitoring infrastructure and specialized reverse logistics partners. Manufacturing concentrates in Switzerland, Germany, and the United States through validated serum-free CHO line facilities. Production draws from Chinese hamster ovary cell banks, recombinant DNA master cell lines, and pegylation chemistry reagents. Single-source vulnerability in mammalian cell culture capacity creates bottleneck risk. Distribution runs through specialty pharmacy hubs with embedded nursing support for injection training.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA's evolving biosimilar interchangeability standards under BPCIA create barrier-to-entry moats for developers with pharmacovigilance infrastructure and extended immunogenicity tracking capabilities.
For Market Incumbents: Acquire diagnostic-neurology ecosystem assets including MRI lesion monitoring platforms and therapy selection algorithms to cement prescriber loyalty against biosimilar substitution. Defend against oral small-molecule displacement by accelerating long-acting pegylated formulation development with extended dosing intervals. Channel control through integrated delivery network bundled outcomes contracts in California and New York represents the critical defensive lever. For New Entrants and Emerging Players: FDA's BPCIA interchangeability pathway in the United States opens a window for asset-light biosimilar developers exploiting real-world evidence acceptance for post-approval study cost reduction. White-space concentrates in homecare settings with self-injection devices and telehealth monitoring capabilities where subscription-based patient support programs displace traditional fee-for-service coaching. Target integrated delivery networks negotiating bundled outcomes contracts as the most penetrable channel archetype. For Investors and Strategic Acquirers: Re-rating potential sits with mammalian cell culture facility owners possessing validated CHO lines and serum-free media protocols given EMA tightened quality requirements extending European development timelines. Long-term viability favors backward-integrated producers with captive supply of recombinant glycoprotein capacity. Monitor FDA interchangeability designation announcements as the primary inflection signal for originator pricing power erosion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Biosimilar Interchangeability Pursuit | FDA BPCIA designation grants automatic pharmacy substitution authority expanding access. |
| Long-Acting Formulation Development | Pegylated interferon beta-1a extends dosing intervals commanding premium oncology positioning. |
| Diagnostic-Neurology Ecosystem Integration | MRI lesion monitoring platforms paired with therapy algorithms reduce prescriber switching behavior. |
| Subscription-Based Patient Support Programs | Third-party hub services in California and New York capture relationship ownership from specialty pharmacies. |
| Mammalian Cell Culture Capacity Expansion | Validated CHO line facilities in Switzerland and Germany secure supply for EU hospital tenders. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided qualitative calibration. Secondary sources encompassed FDA BPCIA guidance documents, EMA biosimilar quality requirements, PMDA reimbursement frameworks, ClinicalTrials.gov entries, and hospital pharmacy committee tender specifications. Bottom-up patient volume modeling and top-down manufacturer capacity assessments were triangulated for convergence.
Granularity-level modeling operated at the intersection of product type, therapy area, administration route, end-user channel, and regional regulatory cluster dimensions across the analysis window. CAGRs were derived from segmented volume projections weighted by reimbursement framework favorability indices and biosimilar penetration assumptions. Forecast inputs incorporated neurologist prescribing pattern surveys, immunogenicity surveillance protocol adoption curves, and oral small-molecule displacement elasticity estimates.
Caveats apply where FDA interchangeability designation delays, EMA pharmacovigilance requirement tightening, or oral small-molecule efficacy breakthroughs could materially shift the outlook. Practitioners should monitor PMDA pricing reform announcements and German hospital pharmacy committee tender specification evolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Macrolide Antibiotics Market
Biopharmaceuticals
Rivaroxaban Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Bioactive Protein and Peptides Market
Biopharmaceuticals
Global Carboprost Tromethamine Market