
 Antibiotics Market | 2026-2036
Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Antibiotics Market Intelligence
Hospital formularies is reorganizing antibiotic procurement around resistance stewardship protocols, shifting volume toward narrow-spectrum and combination therapies. Pfizer Inc. leverages its injectable cephalosporin infrastructure to sustain institutional contracts across North American and European health systems. Hikma Pharmaceuticals PLC anchors generic injectable supply through vertically integrated manufacturing in the Middle East and North Africa. Sun Pharmaceutical Industries competes on cost-engineered oral solid doses for emerging market tenders.
Antibiotics constitute antimicrobial compounds derived from fungal or bacterial fermentation, semi-synthetic modification, or fully synthetic routes, typically characterized by minimum inhibitory concentration thresholds against specific pathogen classes and manufactured through large-scale bioreactor cultivation followed by extraction and purification. These agents serve as first-line therapeutics for bacterial infections across outpatient, inpatient, and critical care settings. Cephalosporins command the largest revenue pool among product types due to surgical prophylaxis dependency and broad gram-negative coverage, while macrolides face accelerating generic erosion in oral respiratory applications. Hospitals absorb the dominant share of end-user demand through centralized pharmacy and therapeutics committees, though ambulatory surgical centers represent the fastest-growing channel as same-day procedure volumes expand.
The FDA's Qualified Infectious Disease Product program and EMA's PRIME designation framework accelerate development timelines for novel mechanisms against resistant pathogens, reshaping R&D allocation across the industry. India's CDSCO enforces bioequivalence standards for export-oriented generic formulations, conditioning market access for international suppliers. China's NMPA aligns domestic production with national essential medicine list revisions, directing volume toward priority anti-infective categories. Stakeholders must monitor stewardship-driven formulary restrictions and regulator-backed incentive programs to align pipeline investments with reimbursable demand.
Market Dynamics
Resistance stewardship protocols are compressing demand for legacy broad-spectrum agents while concentrating purchasing power within hospital pharmacy and therapeutics committees, fundamentally restructuring how antibiotics are evaluated, contracted, and dispensed across health systems.
Growth Catalysts
- FDA's Qualified Infectious Disease Product program:Accelerated approval pathways for novel mechanisms against resistant pathogens are pulling R&D investment toward gram-negative coverage gaps. Developers prioritize carbapenem-resistant Enterobacteriaceae targets under this framework.
- Surgical prophylaxis protocols:Rising same-day procedure volumes in ambulatory surgical centers are expanding cephalosporin consumption outside traditional inpatient settings. These facilities now represent the fastest-growing channel for injectable antibiotic procurement.
- India's generic injectables corridor:Vertically integrated fermentation-to-finish manufacturing clusters in Hyderabad and Ahmedabad are lowering unit costs for export-oriented beta-lactam supply. CDSCO-enforced bioequivalence standards condition market access for international tenders.
Market Restraints
- Active pharmaceutical ingredient concentration:China's Zhejiang and Shandong provinces control critical intermediate supply for penicillin and cephalosporin fermentation, creating single-source vulnerability for non-integrated formulators. NMPA environmental enforcement periodically disrupts output.
- Resistance surveillance mandates:EMA's tightened manufacturing standards for environmental discharge of antibiotic residues are raising compliance capital requirements. Smaller fermentation facilities face consolidation pressure from wastewater treatment upgrades.
- Oral respiratory substitution:Macrolide demand faces compression from guideline-driven preference for doxycycline in community-acquired pneumonia. Generic erosion accelerates as tender specifications prioritize cost per treatment day over spectrum breadth.
Strategic Opportunities
- Sub-Saharan Africa tender expansion:National essential medicine list revisions across Nigeria, Kenya, and Ethiopia are prioritizing amoxicillin-clavulanate and ceftriaxone for pediatric and maternal health programs. WHO prequalification status determines supplier eligibility.
- Combination therapy development:Pairing legacy beta-lactams with novel beta-lactamase inhibitors addresses resistance without requiring new molecular entities. FDA breakthrough therapy designation applies to specific inhibitor pairings.
- Direct hospital contracting:Bypassing wholesale distribution through captive pharmacy networks allows manufacturers to capture formulary placement through stewardship-aligned value propositions. European health systems pilot outcome-linked procurement frameworks.
Industry Challenges
- Specialized fermentation expertise:Large-scale bioreactor operation requires hybrid skill sets spanning microbial genetics, downstream purification, and cGMP compliance. Talent pipelines from academic microbiology programs fail to match industrial demand.
- Legacy quality system integration:Data integrity requirements from FDA's 21 CFR Part 11 and EMA's Annex 11 are forcing paper-based manufacturing records into validated electronic systems. Retrofit timelines extend 18-24 months for established facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antibiotics Market |
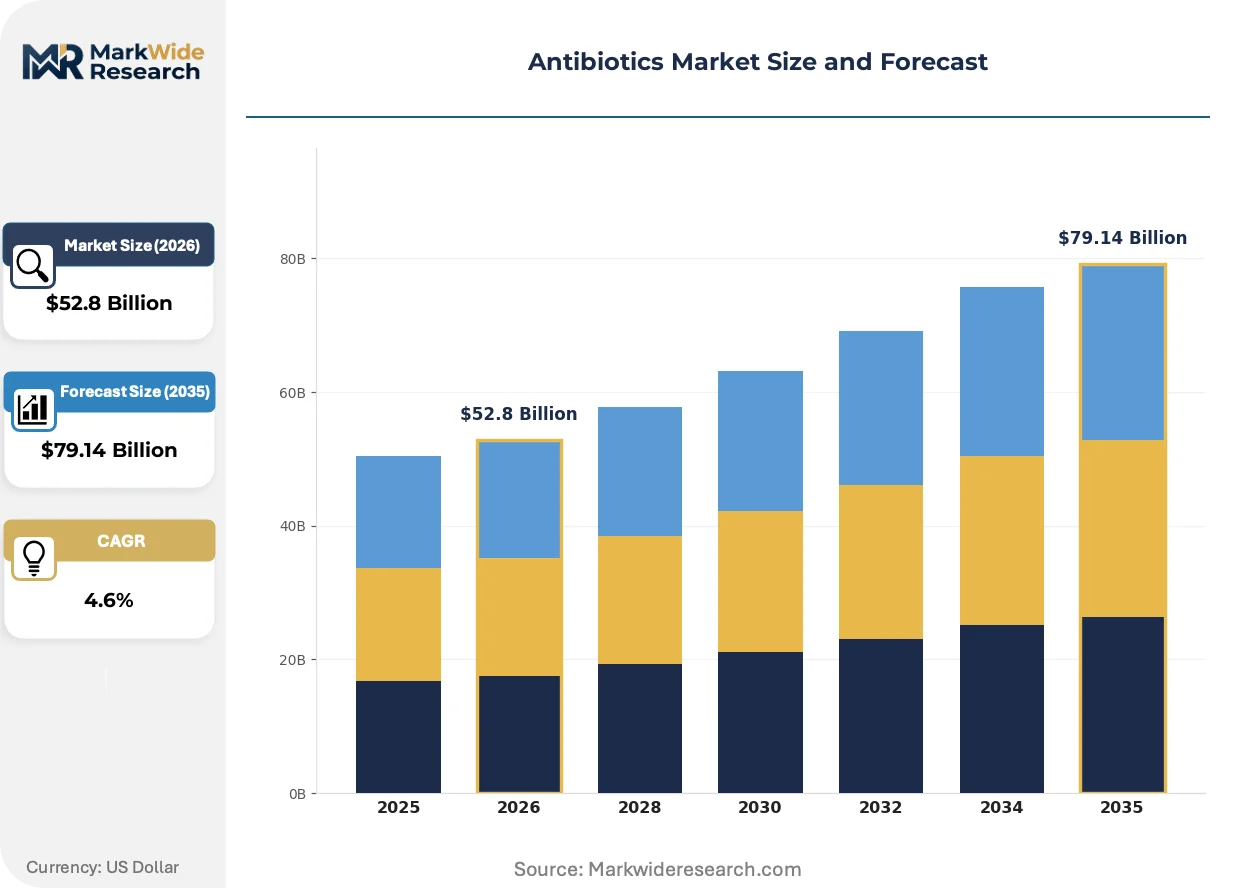
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $79.14 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Penicillins, Cephalosporins, Macrolides, Tetracyclines, Quinolones, Sulfonamides Application: Respiratory Infections, Skin Conditions, Urinary Tract Infections, Gastrointestinal Disorders, Sexually Transmitted Infections, Bacterial Meningitis End User: Hospitals, Clinics, Diagnostic Laboratories, Long-Term Care Facilities, Ambulatory Surgical Centers Formulation Type: Oral Tablets, Injectable Solutions, Topical Creams, Powders for Reconstitution, Extended-Release Capsules |
| Companies Covered | Novartis AG, Sanofi, Pfizer Inc., Hikma Pharmaceuticals PLC, Sun Pharmaceutical Industries, Merck & Co., AbbVie, Tetraphase Pharmaceuticals, GlaxoSmithKline (GSK), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antibiotics Market Strategic Shifts & Innovations
Continuous manufacturing technologies and AI-guided molecular design are shortening development cycles for next-generation agents, while regulatory incentives and procurement reform reshape competitive positioning around resistance stewardship rather than spectrum breadth alone.
Continuous processing technology is supplanting traditional batch fermentation for selected cephalosporin intermediates. Mid-tier manufacturers in India and China are piloting perfusion bioreactor systems that reduce cycle times from weeks to days. This shift compresses working capital requirements and enables smaller-footprint facilities closer to formulation sites.
EMA's PRIME designation framework is accelerating access negotiations for novel antibiotics targeting priority pathogens. Developers gain enhanced regulatory support and accelerated assessment timelines, conditioning pipeline prioritization toward carbapenem-resistant Acinetobacter baumannii and Pseudomonas aeruginosa coverage. European health technology assessment bodies are adapting reimbursement models to reward resistance impact over volume.
Hospital buyers are consolidating antibiotic procurement through centralized therapeutics committees with embedded infectious disease pharmacists. Traditional broad-spectrum empiric protocols face displacement by rapid diagnostic-directed therapy that narrows coverage within 48 hours. This behavioral shift concentrates purchasing influence in academic medical centers across the United States and Western Europe.
Antibiotics Market Segmentation
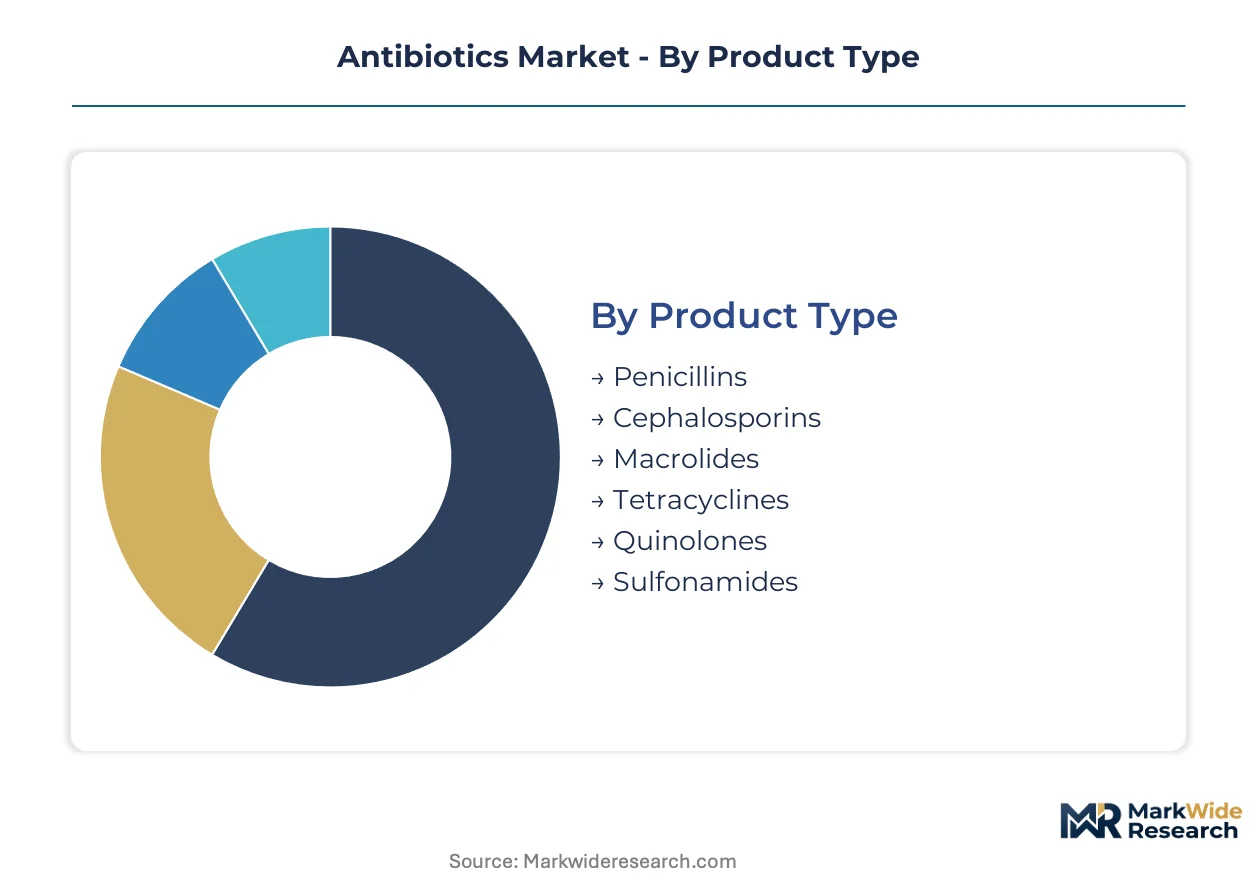
Antibiotic procurement patterns fragment sharply across formulation routes and care settings, with hospital formularies, retail pharmacy networks, and tender systems each demanding distinct product specifications. Understanding these segment boundaries clarifies where manufacturing investments align with volume concentration and where margin structures diverge.
Product Type:
Penicillins and cephalosporins anchor domestic production in India and China, while macrolides and quinolones flow through export-oriented formulations for European and North American tenders.
- Cephalosporins:Semi-synthetic beta-lactam agents with gram-negative coverage profiles dominate surgical prophylaxis protocols. Demand concentrates in hospital pharmacy and therapeutics committees across the United States, Germany, and Japan, driven by resistance stewardship mandates that favor narrow-spectrum empiric therapy.
- Penicillins:Fermentation-derived beta-lactam cores with aminopenicillin and antipseudomonal subclasses remain the most cost-engineered antibiotic category. India's Hyderabad corridor supplies amoxicillin-clavulanate to Sub-Saharan Africa and Southeast Asia through WHO-prequalified tender channels.
- Macrolides:Macrocyclic lactone ring structures with protein synthesis inhibition mechanisms face generic erosion in oral respiratory applications. EMA guidance on community-acquired pneumonia now favors doxycycline alternatives.
- Tetracyclines:Broad-spectrum bacteriostatic agents derived from chlortetracycline fermentation see renewed demand for atypical coverage in outpatient settings. China's Shandong province controls key intermediate supply.
- Quinolones:Synthetic DNA gyrase inhibitors with fluorinated modifications face regulatory restrictions in pediatric and agricultural applications. FDA black box warnings on tendon rupture limit hospital formulary placement.
- Sulfonamides:Structural analogs of para-aminobenzoic acid with dihydropteroate synthase inhibition occupy niche roles in urinary prophylaxis and toxoplasmosis combination therapy. Production concentrates in legacy Eastern European facilities.
Cephalosporins hold the largest share; momentum sits with penicillin combinations for emerging market tender expansion.
Application:
Respiratory and urinary tract applications generate the highest prescription volumes, while meningitis and sexually transmitted infection segments command premium pricing for narrow-spectrum agents.
- Respiratory Infections:Community-acquired pneumonia and acute bacterial sinusitis drive macrolide and respiratory fluoroquinolone consumption. Ambulatory care settings in the United States and United Kingdom account for the majority of oral antibiotic prescriptions in this category.
- Urinary Tract Infections:Uncomplicated cystitis and pyelonephritis represent the most frequent infectious disease indication in primary care. E. coli resistance patterns to trimethoprim-sulfamethoxazole vary significantly between European and North American surveillance networks.
- Skin Conditions:Methicillin-resistant Staphylococcus aureus coverage requirements push hospital demand toward lipopeptides and oxazolidinones for complicated skin and soft tissue infections. Outpatient cellulitis management relies on cephalosporin and penicillinase-resistant penicillin generics.
- Gastrointestinal Disorders:Traveler's diarrhea and intra-abdominal infection protocols favor fluoroquinolone and metronidazole combinations. Asia-Pacific travelers generate seasonal demand spikes in Western European retail pharmacies.
- Sexually Transmitted Infections:Neisseria gonorrhoeae resistance surveillance dictates dual-therapy guidelines with ceftriaxone and azithromycin. CDC and WHO treatment recommendations diverge on macrolide component inclusion.
- Bacterial Meningitis:CNS penetration requirements limit formulary options to third-generation cephalosporins and vancomycin combinations. Pediatric dosing protocols in neonatal intensive care units drive volume for specific powder-for-reconstitution presentations.
Respiratory applications command the greatest prescription volume; bacterial meningitis shows the steepest expansion trajectory for narrow-spectrum CNS-penetrant agents.
End User:
Hospital procurement operates through centralized pharmacy committees with embedded infectious disease pharmacists, while ambulatory surgical centers and long-term care facilities represent fragmented purchasing with distinct formulary constraints.
- Hospitals:Academic medical centers and community hospital systems with centralized therapeutics committees absorb the dominant share of parenteral antibiotic volume. Stewardship protocols in the United States and Germany restrict broad-spectrum empiric therapy duration.
- Ambulatory Surgical Centers:Same-day procedure facilities with limited pharmacy infrastructure rely on pre-packaged surgical prophylaxis kits. Cephalosporin single-dose vials dominate procurement in this fastest-expanding channel.
- Clinics:Primary care and urgent care settings with retail pharmacy affiliations drive oral antibiotic prescriptions for uncomplicated infections. India's Jan Aushadhi scheme and similar generic programs in Brazil compress margins.
- Diagnostic Laboratories:Reference labs with antimicrobial susceptibility testing capabilities influence downstream prescribing through rapid resistance reporting. European health systems pilot diagnostic-directed therapy reimbursement.
- Long-Term Care Facilities:Nursing homes and skilled nursing facilities with high multidrug-resistant organism prevalence face distinct regulatory reporting requirements. CMS antibiotic stewardship mandates in the United States condition survey compliance.
Hospitals retain the largest procurement volume; ambulatory surgical centers are climbing the fastest as same-day procedure volumes expand.
Formulation Type:
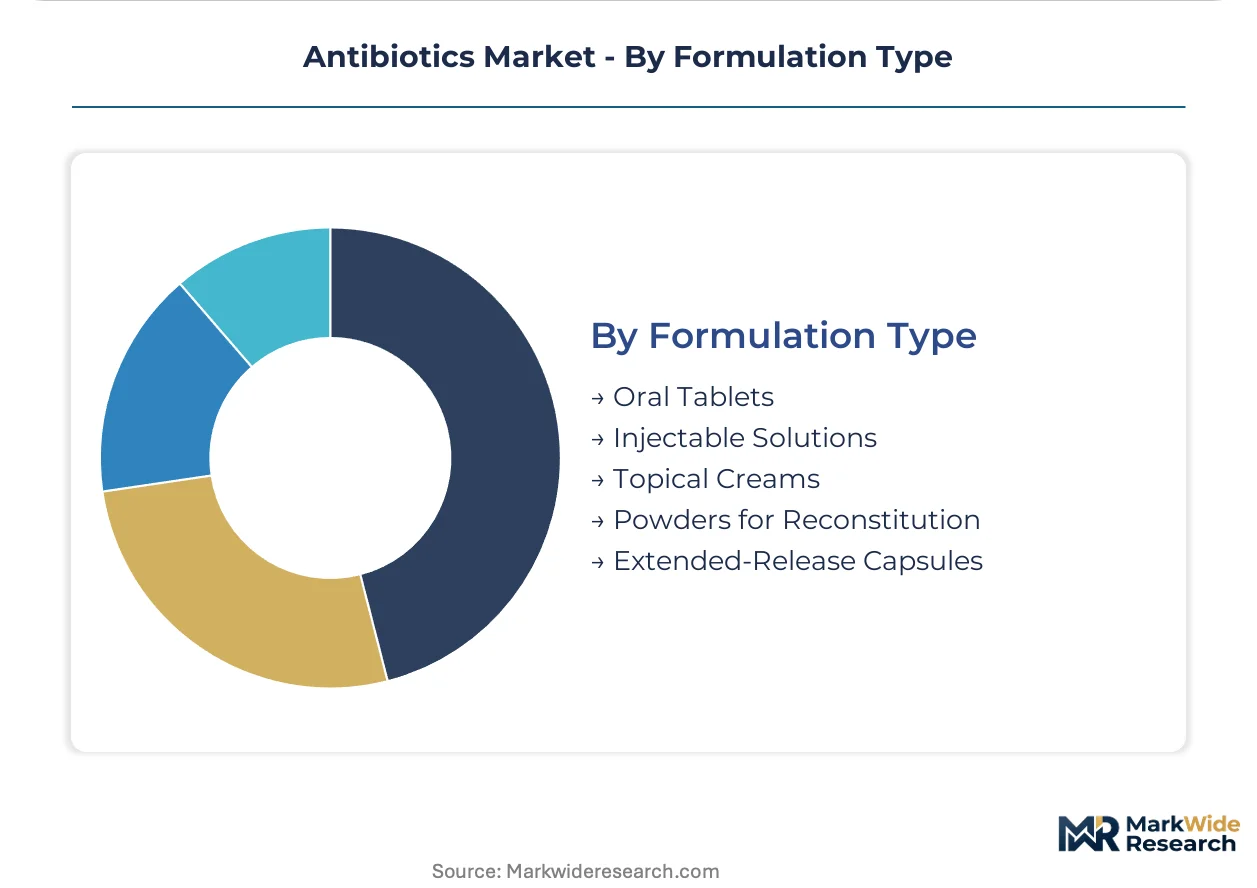
Injectable solutions command hospital premium pricing, while oral tablets and extended-release capsules compete on cost-per-treatment-day in retail and tender channels.
- Injectable Solutions:Sterile parenteral preparations in vial and pre-filled syringe formats dominate inpatient and surgical prophylaxis applications. Hyderabad and Ahmedabad manufacturing clusters supply export markets with USP and EP compliance.
- Oral Tablets:Immediate-release solid oral dosages with bioequivalence certification represent the most price-competitive antibiotic segment. India's CDSCO enforces dissolution profile matching for export-oriented generics.
- Powders for Reconstitution:Dry blend presentations requiring dilution prior to administration serve pediatric and neonatal dosing flexibility needs. WHO prequalification programs prioritize this format for resource-limited settings.
- Extended-Release Capsules:Modified-release formulations with pharmacokinetic advantages for compliance and tissue penetration occupy premium positioning. FDA's QIDP designation accelerates development timelines for novel extended-release agents.
- Topical Creams:Semisolid preparations for superficial skin and wound applications face competition from antiseptic alternatives. Silver sulfadiazine and mupirocin dominate burn unit and MRSA decolonization protocols.
Injectable solutions capture the highest value per unit; extended-release capsules are gaining share fastest through compliance-focused positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold chain infrastructure underwrites European distribution of temperature-sensitive injectable antibiotics, while India's Jawaharlal Nehru Port anchors export volumes to Sub-Saharan Africa and Southeast Asia.
United States
Academic medical centers in Boston and the Research Triangle drive demand for narrow-spectrum agents under FDA stewardship mandates. The FDA's Qualified Infectious Disease Product program accelerates development timelines for novel mechanisms. New Jersey's pharmaceutical corridor hosts formulation facilities serving hospital pharmacy and therapeutics committees nationwide.
Germany
EMA's PRIME designation framework pulls R&D investment toward carbapenem-resistant pathogen targets. Hospital procurement consolidation across Bavaria and North Rhine-Westphalia concentrates purchasing power within centralized therapeutics committees. Frankfurt's logistics hub distributes sterile parenteral preparations across the European Economic Area.
India
Hyderabad's fermentation-to-finish manufacturing clusters supply WHO-prequalified amoxicillin-clavulanate to African tender markets. CDSCO-enforced bioequivalence standards condition export access for generic injectables. Ahmedabad's vertically integrated facilities lower unit costs for beta-lactam active pharmaceutical ingredients.
China
Zhejiang and Shandong provinces control critical intermediate supply for penicillin and cephalosporin fermentation. NMPA environmental enforcement periodically disrupts output, creating volatility for non-integrated formulators. Shanghai's port infrastructure handles bulk fermentation exports to South Asian formulation sites.
Brazil
ANVISA's alignment with FDA bioequivalence standards opens tender access for Indian generic suppliers. São Paulo's hospital networks absorb the dominant share of parenteral antibiotic volume in Latin America. The Port of Santos handles temperature-controlled imports for critical care anti-infectives.
Antibiotics Market Key Industry Players
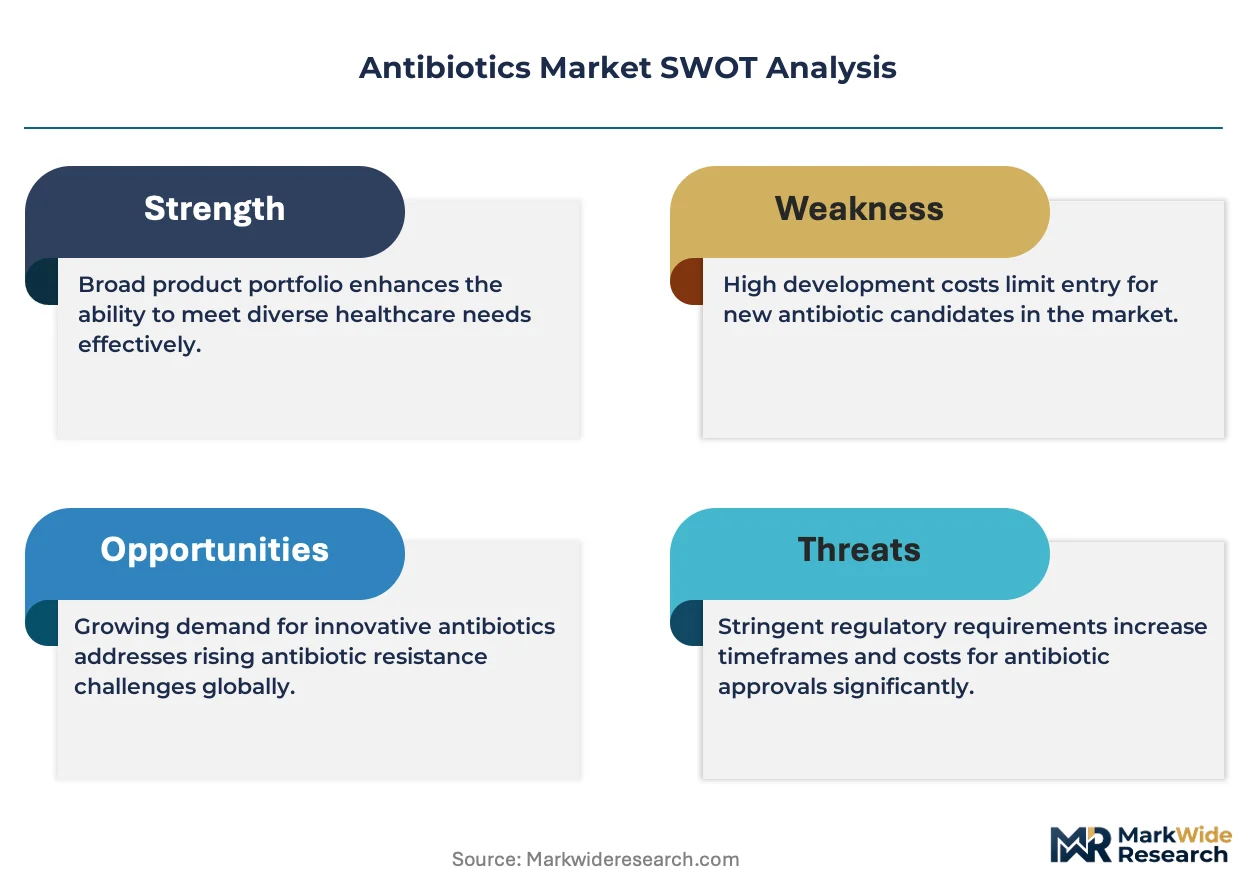
Listed leaders compete with private specialists across manufacturing scale and geographic coverage, creating a tiered structure where research-based multinationals anchor premium positioning and regional generic houses compete on cost-engineered volume. The market fragments across fermentation expertise, formulation technology, and tender access capabilities. Three archetypes dominate: vertically integrated fermentation-to-finish operators, pure-play generic formulators, and R&D-focused developers of novel mechanisms. Competitive moves center on backward integration into active pharmaceutical ingredient supply and direct hospital contracting to bypass wholesale distribution.
Among research-based developers, Pfizer Inc. and Novartis AG exemplify the premium-tier archetype with institutional contract infrastructure across North American and European health systems. Hikma Pharmaceuticals PLC represents the vertically integrated generic specialist with captive manufacturing in the Middle East and North Africa. Sun Pharmaceutical Industries occupies the cost-engineered oral solid dose segment for emerging market tenders.
| Leading Market Players |
|---|
| Novartis AG |
| Sanofi |
| Pfizer Inc. |
| Hikma Pharmaceuticals PLC |
| Sun Pharmaceutical Industries |
| Merck & Co. |
| AbbVie |
| Tetraphase Pharmaceuticals |
| GlaxoSmithKline (GSK) |
| Others |
Cost & Logistics Intelligence
Penicillin-to-cephalosporin intermediate substitution is rerouting active pharmaceutical ingredient flows from Zhejiang fermentation plants to Indian formulation sites, compressing procurement costs for export-oriented generics while elevating price volatility for non-integrated European formulators dependent on spot market access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates antibiotic procurement, with FDA QIDP-designated novel agents commanding premium positioning against WHO-prequalified tender generics and non-certified economy alternatives. Price differentiation rests on bioequivalence certification grade and volume scale, with Indian CDSCO-enforced standards separating export-eligible from domestic-only supply. Pricing pressure stems from guideline-driven macrolide substitution with doxycycline in respiratory applications. Hospital pharmacy committees exhibit lowest price sensitivity for narrow-spectrum CNS-penetrant agents, while emerging market tender systems prioritize cost-per-treatment-day above spectrum breadth.
Supply Chain Analysis
Zhejiang province's 6-APA intermediate production underwrites global penicillin and cephalosporin fermentation, creating single-source vulnerability for non-integrated formulators lacking backward integration into active pharmaceutical ingredient supply. Fermentation feedstocks draw from corn-derived dextrose and soy-based nitrogen sources concentrated in North American and South American agricultural belts. Supply chain risk centers on NMPA environmental enforcement disrupting Shandong and Zhejiang output without warning. Distribution runs through Rotterdam's pharmaceutical cold chain for European hospital networks and Jawaharlal Nehru Port for Sub-Saharan African tender fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital pharmacy and therapeutics committee consolidation across German and United States academic medical centers has shifted procurement leverage toward institutional buyers with embedded infectious disease pharmacists, fragmenting manufacturer pricing power across fragmented wholesale channels.
For Market Incumbents: Compound formulary stickiness through direct hospital contracting bypassing wholesale distribution, while deepening in-house production of beta-lactamase inhibitor combinations to offset generic erosion in legacy cephalosporin portfolios. Resistance stewardship mandates from FDA and EMA threaten broad-spectrum volume; captive fermentation infrastructure in Hyderabad or Ahmedabad secures cost position against spot-dependent competitors. For New Entrants and Emerging Players: Anchor in ambulatory surgical center surgical prophylaxis kits as the fastest-expanding channel with limited incumbent pharmacy infrastructure, targeting pre-packaged cephalosporin single-dose vials for same-day procedure facilities. Sub-Saharan Africa tender expansion for amoxicillin-clavulanate pediatric formulations offers penetrable white space contingent on WHO prequalification investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier Indian generic houses possessing CDSCO-certified export capacity but lacking European hospital direct contracting infrastructure. Long-term viability hinges on stewardship-aligned pipeline positioning rather than volume-driven respiratory macrolide exposure. Monitor EMA PRIME designation awards to novel gram-negative mechanisms as inflection signal for reimbursable demand concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Infrastructure | Captive 6-APA supply from Zhejiang or Hyderabad insulates against NMPA environmental disruption. |
| WHO Prequalification Investment | UNICEF and African tender eligibility unlocks volume in Nigeria, Kenya, and Ethiopia maternal health programs. |
| Direct Hospital Contracting Networks | Bypassing wholesale distribution captures formulary placement through stewardship-aligned value propositions in Germany. |
| Beta-Lactamase Inhibitor Combination Development | Pairing legacy agents with novel inhibitors addresses resistance without requiring new molecular entity investment. |
| Continuous Manufacturing Technology Adoption | Perfusion bioreactor systems in India and China compress cycle times from weeks to days. |
Research Approach
Cross-validation between primary interviews with hospital formulary directors, CDSCO regulatory affairs leads, generic manufacturing executives, and infectious disease pharmacists anchors the qualitative findings, supplemented by secondary validation through FDA QIDP designation databases, EMA PRIME submission records, WHO prequalification listings, and Indian pharmaceutical export customs data. Bottom-up volume estimates from fermentation capacity utilization rates and top-down value projections from tender award disclosures were reconciled through iterative triangulation.
Sensitivity analysis around resistance stewardship adoption rates, NMPA environmental enforcement frequency, and hospital procurement consolidation pace informs the analytical framework across the analysis window. Segmentation modeling incorporates product type, application, end user, formulation route, and regional regulatory cluster dimensions. CAGRs were derived from trend extrapolation of historical tender volumes and patent expiry impact assessment, with specific inputs including E. coli resistance surveillance patterns and same-day procedure volume trajectories.
Decision-makers should treat outputs as directional under sustained FDA and EMA stewardship mandate enforcement; material deviation in macrolide-to-doxycycline substitution velocity or NMPA production suspension frequency would warrant model refresh. Practitioners should keep alternative scenarios live as carbapenem-resistant pathogen prevalence and diagnostic-directed therapy reimbursement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Tyrosine Kinase Inhibitors Market
Biopharmaceuticals
Global CIS Insulin Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Oral Chemotherapy Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market