
 Northern Blotting Market | 2026-2036
Northern Blotting Market Size, Share, and Industry Trends Forecast 2026-2036
Northern Blotting Market Outlook
Equipment leasing and reagent rental programs are rewriting capital deployment patterns for mid-sized laboratories. Thermo Fisher Scientific leverages its instrument-reagent bundling to anchor recurring revenue streams. Qiagen competes through specialized nucleic acid isolation workflows that sustain pull-through for downstream blotting consumables. Bio-Rad Laboratories dominates gel electrophoresis infrastructure, extending its footprint into transfer and imaging stages.
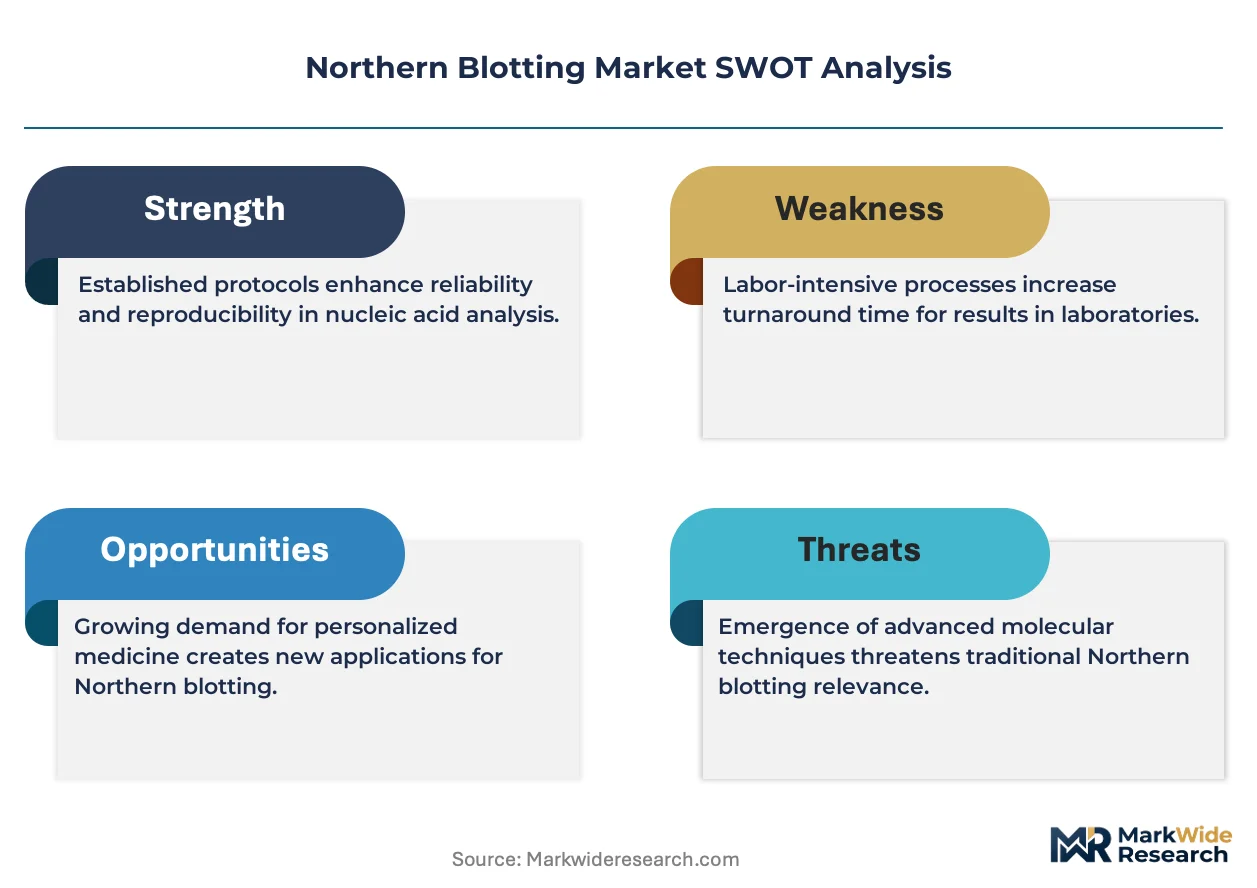
Northern blotting detects specific RNA sequences through size-separated electrophoretic transfer to membranes, followed by labeled probe hybridization and chemiluminescent or fluorescent detection. The technique requires formaldehyde or glyoxal denaturing gels, nylon or nitrocellulose membranes with 0.2 to 0.45 µm pore sizes, and stringency-controlled hybridization buffers to distinguish complementary RNA targets. Reagents and kits command the largest revenue share due to perpetual replenishment cycles, while imaging systems deliver the fastest expansion as laboratories replace film-based detection with digital chemiluminescence workstations. Academic research institutions represent the most entrenched end-user channel, though pharmaceutical companies are shifting toward automated northern blot platforms to accelerate preclinical RNA validation timelines.
The FDA oversees nucleic acid diagnostic assay validation through its Center for Devices and Radiological Health, while the EPA monitors laboratory chemical waste streams including formaldehyde and radioactive probe disposal. ISO 15189 accreditation requirements for clinical diagnostic laboratories are tightening analytical documentation standards for RNA-based testing workflows. Stakeholders must monitor how CRISPR-mediated RNA editing advances will either sustain northern blotting as a confirmatory gold standard or displace it with quantitative PCR and sequencing alternatives.
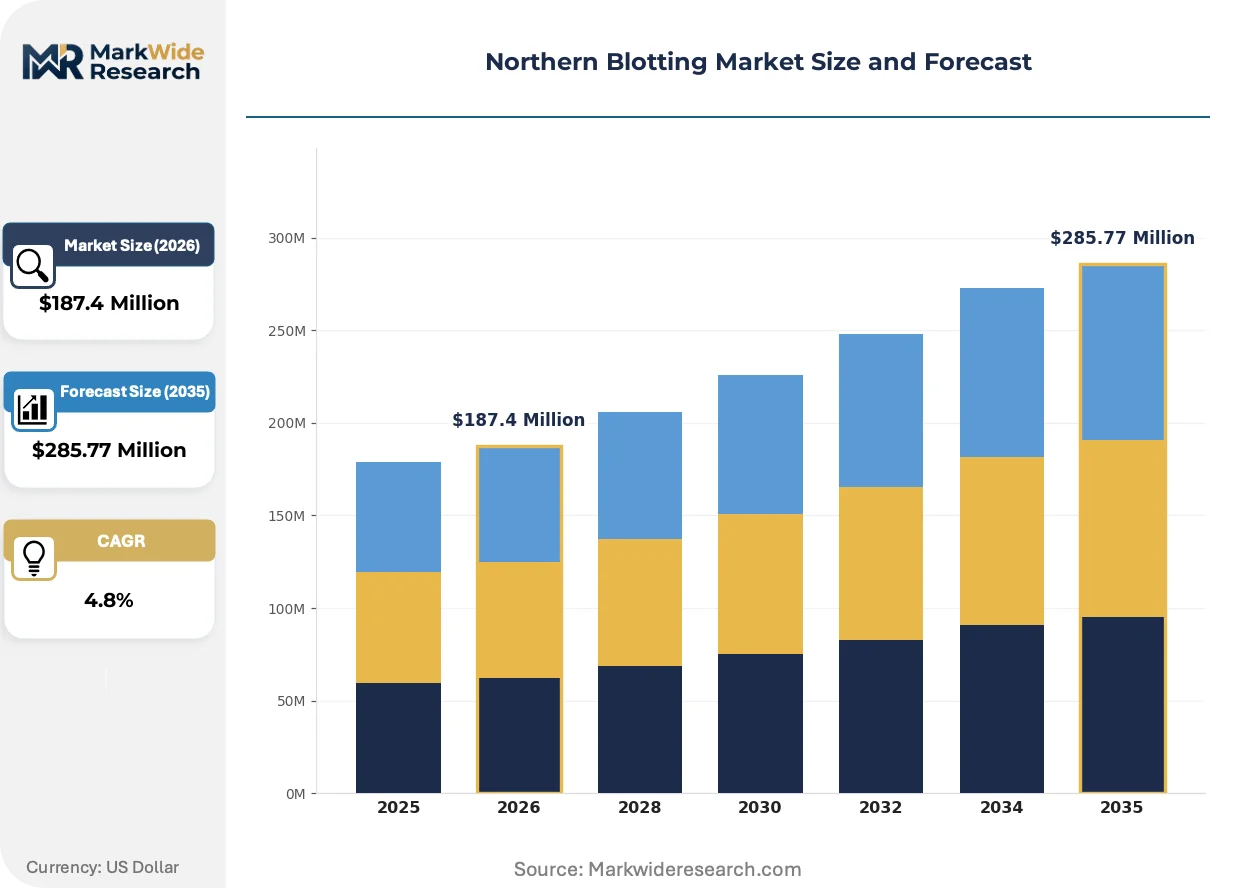
Market Dynamics
Digital chemiluminescence imaging systems are compressing detection timelines from hours to minutes, forcing laboratories to retire darkroom infrastructure and reallocate capital toward integrated workstation platforms.
Growth Catalysts
- RNA therapeutics pipelines:Pharmaceutical developers require northern blotting for mRNA integrity validation during preclinical stages, sustaining reagent demand across contract research organizations.
- FDA nucleic acid testing guidelines:Tightening validation requirements for molecular diagnostic protocols mandate confirmatory RNA characterization, embedding northern blotting into regulatory submission workflows.
- Germany's biotech clustering:Heidelberg and Munich research hubs concentrate procurement volume for automated northern blot platforms, creating localized demand density.
Market Restraints
- Formaldehyde input volatility:Laboratory chemical supply chains face price instability for denaturing gel reagents, squeezing operational budgets for high-throughput facilities.
- Quantitative PCR substitution:Real-time amplification technologies offer faster RNA quantification, diverting routine transcript analysis away from membrane-based detection.
- Radioactive probe disposal costs:EPA hazardous waste regulations impose escalating compliance burdens for isotope-labeled hybridization workflows.
Strategic Opportunities
- CRISPR RNA editing validation:Guide RNA characterization and off-target transcript detection create new confirmatory applications for high-specificity northern protocols.
- Equipment-as-a-service models:Reagent rental programs reduce capital barriers for mid-sized academic laboratories, expanding addressable instrument penetration.
- ISO 15189 accreditation tailwinds:Clinical diagnostic laboratories pursuing international quality standards require documented RNA testing workflows, standardizing northern blot adoption.
Industry Challenges
- Hybridization expertise scarcity:Stringency optimization and probe design require specialized molecular biology training that academic programs are de-emphasizing in favor of sequencing curricula.
- Legacy film darkroom integration:Facilities maintaining chemiluminescent film detection face workflow fragmentation when transitioning to digital imaging architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Northern Blotting Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Equipment, Membranes Application: Gene Expression Analysis, RNA Transcript Characterization, Disease Research, Quality Control End User: Academic Research Institutions, Biotechnology Firms, Pharmaceutical Companies, Diagnostic Labs Technology: Electrophoresis, Hybridization, Imaging Systems, Gel Transfer Techniques |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Qiagen, Sigma Aldrich, PerkinElmer, Agilent Technologies, Merck KGaA, Promega Corporation, Takara Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Northern Blotting Market Strategic Shifts
Automation and digital detection architectures are restructuring how laboratories execute RNA characterization, compressing manual intervention while expanding analytical throughput capabilities.
Automated northern blot workstations integrate electrophoretic separation, vacuum-assisted transfer, and programmable hybridization into single-platform workflows. Pharmaceutical quality control laboratories are adopting these systems to accelerate mRNA therapeutic batch release timelines. This consolidation is virtualizing discrete manual stages into continuous processing pipelines that reduce technician hands-on time.
The EPA's evolving hazardous waste rules for formaldehyde and radioactive probe materials are tightening disposal documentation requirements for research facilities. Clinical and academic laboratories must now maintain chain-of-custody records for chemical reagents from procurement through destruction. High-throughput RNA testing centers in the United States are responding by migrating to non-isotopic detection chemistries and glyoxal-based denaturing alternatives.
Academic research consortia are consolidating procurement through shared core facility models rather than maintaining distributed instrument fleets. Centralized imaging and blotting infrastructure replaces department-level equipment ownership, particularly at research universities with constrained capital renewal cycles. This restructuring is most pronounced in United States public university systems facing sustained state funding compression.
Northern Blotting Market Segmentation
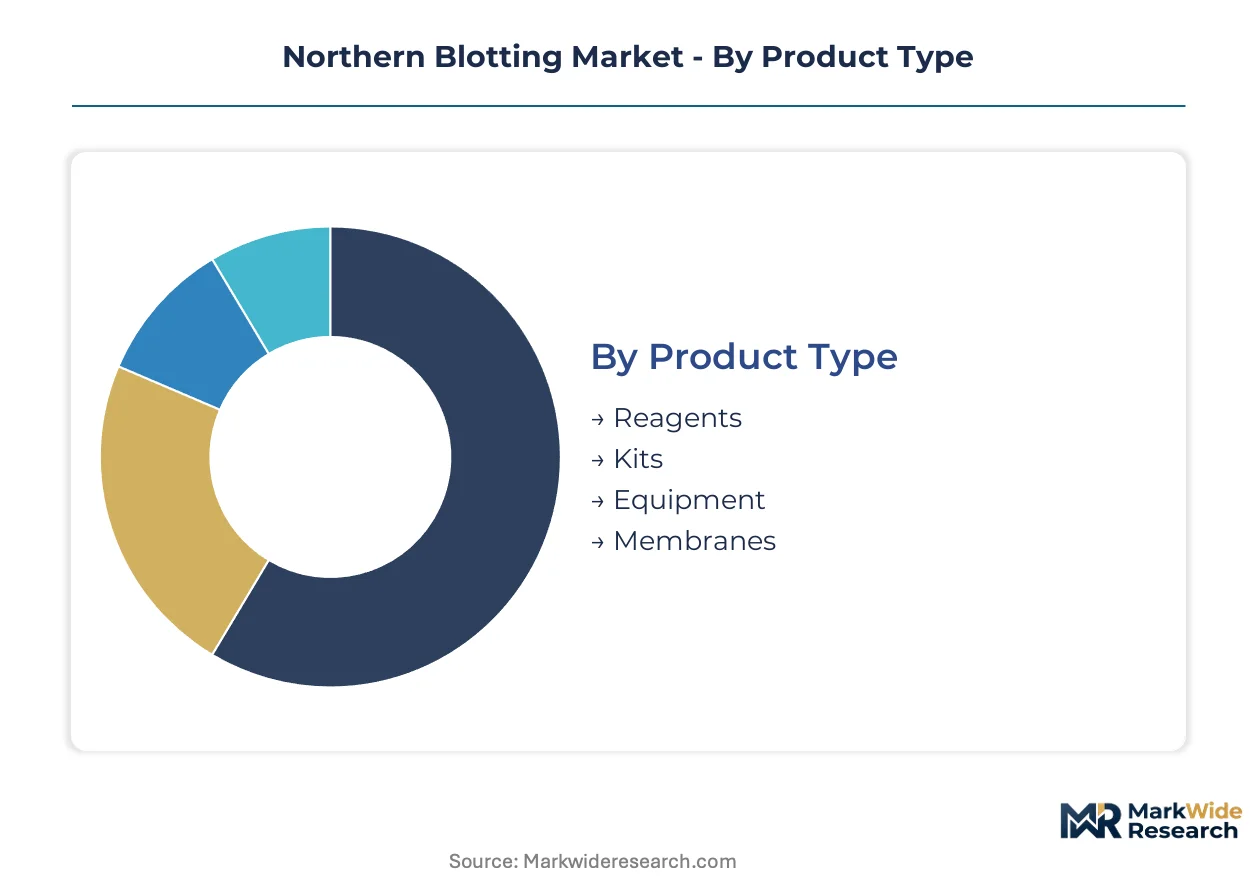
Northern blotting market segmentation reveals distinct procurement rhythms across product categories. Reagent replenishment cycles compress to weeks while imaging platforms extend across multi-year depreciation schedules. Understanding these temporal patterns enables vendors to calibrate inventory and service models against actual laboratory consumption behavior.
Product Type:
Cycle times vary dramatically across this category, with consumable reagents turning over in 30-60 day intervals while capital equipment locks laboratories into 5-7 year replacement horizons.
- Reagents:Denaturing agents, hybridization buffers, and chemiluminescent substrates require perpetual replenishment. Academic core facilities in the United States account for concentrated procurement volume as RNA transcript characterization workflows expand across research consortia. Perpetual replenishment cycles sustain vendor recurring revenue regardless of instrument installed base.
- Kits:Pre-formulated probe labeling and detection systems reduce protocol variability between technicians. Biotechnology firms in Germany's Heidelberg cluster favor bundled kit configurations that standardize cross-site methodology during mRNA therapeutic development. Kit standardization accelerates regulatory documentation for FDA submission packages.
- Equipment:Automated workstations and vacuum transfer systems represent capital-intensive procurement decisions. Pharmaceutical quality control laboratories deploy these platforms to compress mRNA batch release timelines.
- Membranes:Nylon and nitrocellulose sheets with 0.2-0.45 µm pore specifications enable RNA immobilization. High-throughput facilities favor roll formats over precut sheets to minimize per-blot material costs.
Reagents anchor the volume base while imaging systems gain share at the steepest rate as laboratories retire darkroom infrastructure.
Application:
Cost tier stratification separates routine screening applications from validation-intensive regulatory workflows, with the latter commanding 3-4x reagent expenditure per sample.
- Gene Expression Analysis:Quantitative assessment of transcript abundance across experimental conditions. Academic research institutions dominate this segment as CRISPR-mediated RNA editing studies proliferate and require confirmatory northern protocols.
- RNA Transcript Characterization:Size determination and integrity assessment of specific RNA species. Pharmaceutical companies concentrate procurement here during preclinical mRNA therapeutic validation, embedding northern blotting into regulatory submission workflows.
- Disease Research:Pathogenic RNA detection and viral transcript profiling. Diagnostic laboratories pursuing ISO 15189 accreditation standardize these workflows for clinical analytical documentation.
- Quality Control:Batch release testing for mRNA integrity and purity specifications. Contract research organizations automate these protocols to meet compressed client timelines.
Gene expression analysis anchors the volume base while RNA transcript characterization climbs the fastest as mRNA therapeutic pipelines mature.
End User:
Customer type determines procurement authority structure, with centralized core facilities consolidating purchasing power against distributed departmental ownership.
- Academic Research Institutions:Public university systems facing sustained state funding compression migrate toward shared core facility models. Centralized imaging infrastructure replaces distributed department-level equipment ownership.
- Biotechnology Firms:Venture-backed developers prioritize equipment-as-a-service models to preserve capital for therapeutic pipeline advancement. Reagent rental programs reduce barrier to automated platform adoption.
- Pharmaceutical Companies:Quality control laboratories demand integrated workstation platforms that virtualize manual stages into continuous processing pipelines. These facilities accelerate mRNA therapeutic batch release timelines through automation.
- Diagnostic Labs:Clinical facilities navigating FDA nucleic acid testing guidelines mandate confirmatory RNA characterization workflows. ISO 15189 accreditation requirements tighten analytical documentation standards.
Academic research institutions anchor the volume base while diagnostic labs expand most quickly as clinical RNA testing standardizes.
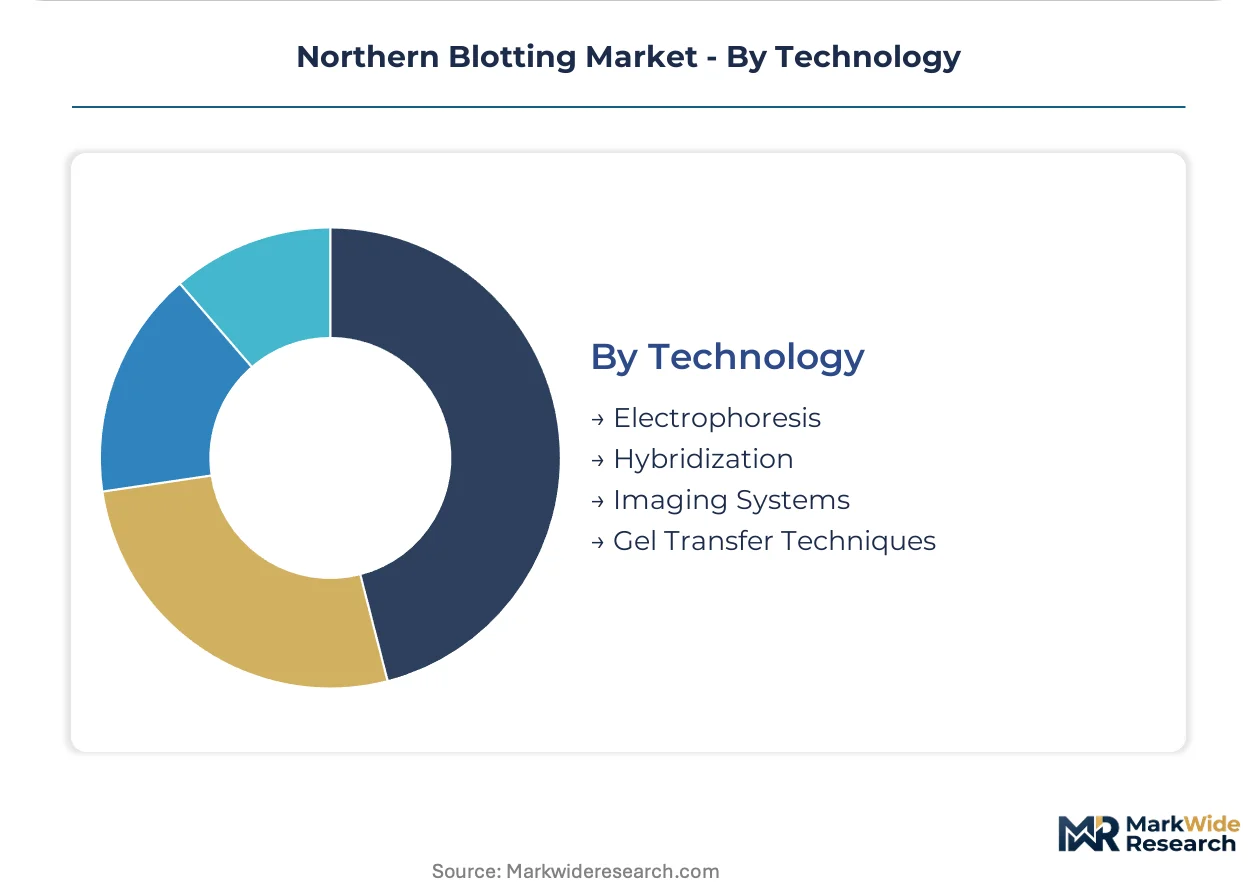
Technology:
Technology maturity spans legacy manual techniques through fully automated platforms, with hybridization expertise scarcity creating capability gaps between generations.
- Electrophoresis:Formaldehyde and glyoxal denaturing gel systems separate RNA by molecular weight. EPA hazardous waste regulations for formaldehyde disposal drive migration toward glyoxal-based alternatives.
- Hybridization:Stringency-controlled probe annealing distinguishes complementary RNA targets. Specialized molecular biology training requirements constrain technician availability as academic programs de-emphasize membrane-based methods.
- Imaging Systems:Digital chemiluminescence workstations compress detection timelines from hours to minutes. Laboratories retire film-based detection infrastructure and reallocate capital toward integrated platforms.
- Gel Transfer Techniques:Vacuum-assisted and capillary transfer methods immobilize RNA onto membranes. Automated workstations consolidate these stages into single-platform workflows.
Electrophoresis anchors the volume base while imaging systems show the steepest expansion trajectory as digital detection architectures displace darkroom infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA nucleic acid testing guidelines are tightening validation requirements for molecular diagnostic protocols across research jurisdictions. Academic research institutions in the United States are expanding RNA transcript characterization workflows. Germany's Heidelberg and Munich biotech clusters concentrate procurement volume for automated northern blot platforms.
United States
Academic research institutions are expanding RNA transcript characterization workflows across public university systems. The FDA's Center for Devices and Radiological Health oversees nucleic acid diagnostic assay validation requirements. Greater Boston and San Francisco Bay Area research hubs concentrate demand for automated northern blot workstations as core facilities consolidate procurement.
Germany
Heidelberg and Munich biotech clusters concentrate procurement volume for automated northern blot platforms. The EMA framework influences nucleic acid testing standards across European research jurisdictions. Baden-Württemberg pharmaceutical quality control laboratories deploy integrated workstation platforms to compress mRNA batch release timelines.
United Kingdom
Academic consortia are migrating toward shared core facility models to replace distributed instrument ownership. The Medicines and Healthcare products Regulatory Agency shapes nucleic acid diagnostic validation standards. London and Cambridge research hubs standardize northern blot workflows for CRISPR-mediated RNA editing confirmatory protocols.
Japan
Pharmaceutical companies are shifting toward automated northern blot platforms to accelerate preclinical RNA validation timelines. The PMDA influences molecular diagnostic protocol standards across domestic research institutions. Kansai region biotechnology firms favor bundled kit configurations that standardize cross-site methodology during therapeutic development.
China
Contract research organizations are automating quality control protocols to meet compressed client timelines for mRNA therapeutic batch release. The NMPA monitors nucleic acid diagnostic assay validation standards across clinical and research facilities. Yangtze River Delta biotech clusters are adopting equipment-as-a-service models to reduce capital barriers for mid-sized laboratories.
Northern Blotting Market Competitive Environment
Channel-controlling players compete with product-specialist players for positioning across reagent and instrumentation tiers. The market structure consolidates around integrated workstation platforms while fragmenting across consumable supply. Three archetypes dominate: full-spectrum life science conglomerates, nucleic acid workflow specialists, and electrophoresis infrastructure incumbents. M&A activity targets automated platform capabilities, while strategic partnerships anchor reagent rental programs.
Among full-spectrum conglomerates, Thermo Fisher Scientific anchors instrument-reagent bundling strategies that lock in recurring revenue streams. Bio-Rad Laboratories exemplifies electrophoresis infrastructure extension into transfer and imaging stages. Qiagen occupies a position as nucleic acid isolation workflow specialist, sustaining pull-through for downstream blotting consumables through integrated protocol design.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Qiagen |
| Sigma Aldrich |
| PerkinElmer |
| Agilent Technologies |
| Merck KGaA |
| Promega Corporation |
| Takara Bio |
| Others |
Value Chain & Pricing Dynamics
Transatlantic air freight corridors connecting Germany's Heidelberg biotech cluster to United States academic hubs concentrate high-value reagent shipments, with per-kilogram transport costs directly feeding into tiered pricing spreads between ISO 15189-certified diagnostic laboratories and standard research facilities. This logistics architecture amplifies price differentiation as downstream buyers absorb differential certification premiums alongside geographic delivery premiums.
Pricing Analysis
Certification level (ISO 15189/FDA-grade versus standard research-grade) creates the primary spread across consumable tiers, with diagnostic laboratories absorbing 40-60% premiums for documented chain-of-custody compliance. Three-tier pricing structure across premium, standard, and economy levels segments procurement: pharmaceutical quality control laboratories purchase premium bundled kits, academic core facilities standardize on mid-tier reagent configurations, and cost-constrained contract research organizations negotiate economy membrane roll formats. Pricing pressure stems from glyoxal-based denaturing reagent substitution as EPA formaldehyde disposal costs escalate. Diagnostic laboratories exhibit lowest price sensitivity due to regulatory documentation requirements, while public university systems facing state funding compression demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between United States and Chinese membrane manufacturing dominates supply chain risk calculus for North American reagent vendors. Nylon and nitrocellulose membrane production concentrates in China, Germany, and United States, with electrophoresis-grade formaldehyde sourcing anchored in domestic chemical manufacturing. Raw material dependencies include photographic-grade gel chemicals, chemiluminescent substrate enzymes, and precision-pore membrane substrates. Single-source vulnerability pervades specialized hybridization buffer formulations protected by proprietary formulations. Distribution runs through authorized distributor networks serving academic core facilities, with direct sales teams managing pharmaceutical quality control accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated northern blot workstation platforms are consolidating previously fragmented manual stages, creating platform-economics dynamics where instrument-reagent bundling determines competitive survival. Interoperability between electrophoresis, transfer, and imaging modules now dictates procurement authority.
For Market Incumbents: Entrench instrument-reagent bundling through equipment-as-a-service models that reduce capital barriers for mid-sized academic laboratories. Expand captive supply of glyoxal-based denaturing reagents to offset EPA formaldehyde disposal cost escalation. Defend against quantitative PCR substitution by embedding northern protocols into FDA nucleic acid testing guideline workflows as confirmatory gold standards.
For New Entrants and Emerging Players: China's Yangtze River Delta biotech clusters offer underpenetrated demand for automated quality control platforms serving contract research organizations. Target diagnostic laboratories pursuing ISO 15189 accreditation with documented RNA testing workflow packages. Penetrate through reagent rental programs that bypass capital procurement cycles.
For Investors and Strategic Acquirers: Nucleic acid isolation workflow specialists with integrated downstream blotting consumable pull-through represent prime acquisition targets. Long-term viability hinges on CRISPR RNA editing validation sustaining northern blotting against sequencing displacement. Watch for FDA guidance updates on nucleic acid diagnostic assay validation as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Workstation Platform Integration | Consolidates electrophoresis, transfer, and imaging into single-vendor control over laboratory capital budgets. |
| Reagent Rental Program Expansion | Reduces capital barriers for academic core facilities while locking recurring revenue streams. |
| Non-Isotopic Detection Chemistry Migration | Addresses EPA radioactive probe disposal cost escalation for high-throughput RNA testing centers. |
| Glyoxal-Based Denaturing Gel Transition | Mitigates formaldehyde hazardous waste documentation burdens under tightening EPA regulations. |
| ISO 15189 Accreditation Workflow Bundling | Captures diagnostic laboratory procurement authority through standardized analytical documentation packages. |
Study Parameters
A standing panel of pharmaceutical quality control directors, academic core facility managers, diagnostic laboratory accreditation leads, and reagent procurement specialists provided ongoing calibration against operating reality. Primary interviews combined with secondary validation from FDA Center for Devices and Radiological Health guidance documents, EPA hazardous waste regulation filings, ISO 15189 accreditation body reports, and EMA nucleic acid testing standards. Bottom-up instrument and reagent volume estimates triangulated against top-down market sizing from vendor revenue disclosures.
Scenario-bracketing framed projections across technology substitution pathways (quantitative PCR displacement versus CRISPR validation sustainment) and regulatory stringency variants. Segmentation modeling spanned product type, application workflow, end-user procurement authority structure, and technology maturity tier. CAGRs derived from instrument replacement cycles and reagent replenishment velocity analysis. Industry-specific inputs included mRNA therapeutic pipeline advancement rates and academic funding compression indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sequencing platform vendors into RNA validation workflows would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Fusion Biopsy Market
Biomedical Technology
Austria Flow Cytometry Market
Biomedical Technology
Global Nicotinamide Adenine Dinucleotide (NAD) Market
Biomedical Technology
Pyrosequencing Market
Biomedical Technology
Global Immunohistochemistry (IHC) Market
Biomedical Technology
Rare Biomarkers Specimen Collection and Stabilization Market
Biomedical Technology
Asia-Pacific Digital PCR Market
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Global Laser Capture Microdissection Market
Biomedical Technology
Ontogenetic Market
Biomedical Technology
Lipid Transfer Proteins Market
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Cell Disrupters Market
Biomedical Technology
In-Vitro Transcription Templates Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Polymerase Chain Reaction Technologies Market