
 Global Actinic Keratosis Drugs Market | 2026-2036
Global Actinic Keratosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Actinic Keratosis Drugs Market Foresight
Imiquimod-based immunomodulators is repositioning fluorouracil's historical dominance in first-line field therapy across mature markets. Galderma S.A. leverages its integrated dermatology portfolio to sustain formulary access across European outpatient networks. Sun Pharmaceutical Industries Ltd anchors its position through manufacturing scale in generic fluorouracil creams. Biofrontera AG differentiates via photodynamic therapy device-drug bundling that controls treatment protocols in German and US clinics.
Actinic keratosis drugs comprise pharmaceutical agents designed to eliminate or reduce premalignant epidermal lesions caused by cumulative ultraviolet exposure, with formulations ranging from topical antimetabolites like fluorouracil to photosensitizing agents such as aminolevulinic acid that require light activation at specific wavelengths. These therapeutics serve to prevent progression to invasive squamous cell carcinoma while offering lesion-directed or field-wide treatment modalities in outpatient dermatology settings. Immunomodulators lead the drug type category due to favorable patient adherence profiles and expanding label indications, while photodynamic therapy agents represent the fastest-growing segment driven by device-drug synergy and shorter treatment courses. Cream formulations dominate volume but gel formats command margin premiums through enhanced skin penetration and cosmetic acceptability.
The FDA and EMA jointly shape market access through divergent pathways for combination therapy approvals, with the FDA emphasizing lesion count endpoints while EMA prioritizes histological clearance metrics that extend trial timelines. The EU MDR and US HIPAA frameworks respectively govern device-drug combination classifications and patient data portability in teledermatology screening programs that drive early detection. Stakeholders must monitor reimbursement parity between lesion-directed and field therapy protocols as pharmacy benefit managers recalibrate coverage criteria.
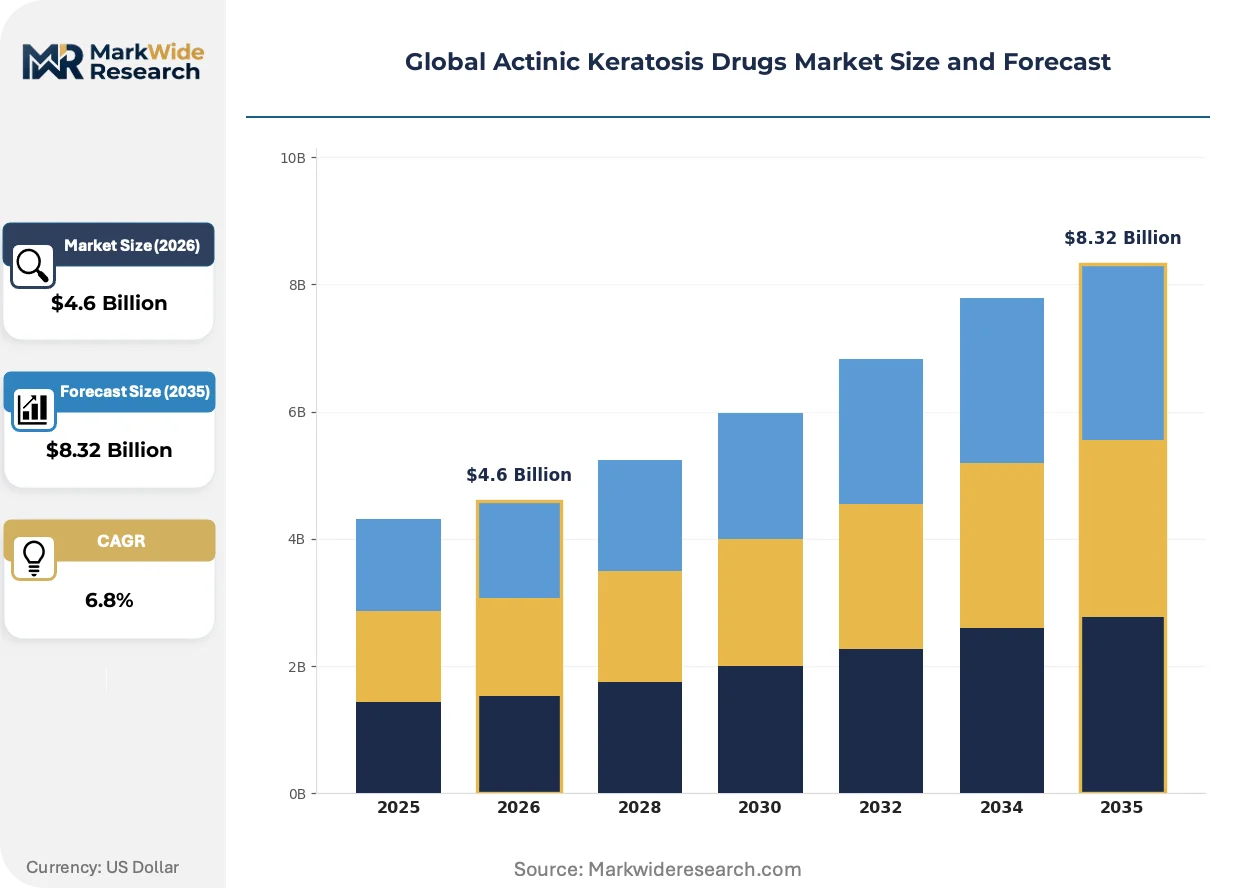
Market Dynamics
Photodynamic therapy reimbursement parity with topical agents is restructuring treatment selection protocols across outpatient dermatology networks, compressing the historical preference for lesion-directed pharmacotherapy.
Growth Catalysts
- EMA histological clearance mandates:These requirements extend trial timelines but elevate clinical evidence standards, creating durable competitive moats for compliant sponsors.
- Teledermatology screening programs:Remote lesion detection infrastructure in the United States accelerates early-stage diagnosis and expands addressable patient pools.
- Device-drug bundling protocols:Integrated photodynamic systems in German clinics lock in protocol adherence and reduce therapeutic substitution.
Market Restraints
- Photosensitizer supply concentration:Aminolevulinic acid active pharmaceutical ingredient production clusters in limited manufacturing sites, exposing formulation sponsors to single-source risk.
- FDA lesion count endpoint rigidity:Divergent evidentiary requirements from EMA standards force parallel trial designs that inflate development costs.
- Generic fluorouracil price erosion:Commoditized topical antimetabolites compress margin structures for field therapy portfolios.
Strategic Opportunities
- Japanese outpatient photodynamic expansion:METI reimbursement pilot programs for device-drug combinations create first-mover positioning for protocol sponsors.
- Home-use immunomodulator formulations:Patient-administered topical regimens bypass clinic capacity constraints and capture pharmacy benefit manager preference.
- EU MDR combination product harmonization:Streamlined device-drug classification pathways reduce regulatory duplication for photodynamic systems.
Industry Challenges
- Histopathology reader certification:EMA-mandated central assessment protocols require specialized dermatopathologist training that outpaces workforce supply.
- Legacy electronic health record integration:Teledermatology platforms face interoperability friction with hospital system infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Actinic Keratosis Drugs Market |
| Market Size in 2026 | $4.6 Billion |
| Market Size in 2035 | $8.32 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Topical Fluorouracil, Immunomodulators, Photodynamic Therapy Agents, Retinoids, Others Formulation: Cream, Gel, Solution, Patch, Ointment Application: Field Therapy, Lesion-directed Therapy, Combination Therapy, Preventive Treatment End User: Dermatology Clinics, Hospitals, Specialized Skin Institutes, Research Centers |
| Companies Covered | Sun Pharmaceutical Industries Ltd, Galderma S.A., Biofrontera AG, Almirall S.A., Bausch Health Companies Inc, LEO Pharma, 3M Company, Hill Dermaceuticals Inc, Cipher Pharmaceuticals Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Actinic Keratosis Drugs Market Shifts & Advancements
Convergence between light-activated modalities and immunomodulatory pharmacology is fragmenting the traditional dichotomy between lesion-directed and field-wide therapeutic paradigms.
Photosensitizer nanoemulsion formulations is electrifying tissue penetration depth and reducing activation light intensity requirements. Dermatology clinics in Germany and the United States are adopting these second-generation aminolevulinic acid derivatives for extended treatment fields. The technology is electrifying competitive positioning among photodynamic therapy sponsors by compressing the efficacy gap with surgical alternatives.
EU MDR Article 117 device-drug combination classifications are forcing sponsors to restructure quality management systems and clinical evaluation reports. The regulation imposes notified body involvement for photodynamic systems previously self-certified under medical device directives. German and French outpatient networks are prioritizing suppliers with established MDR technical documentation.
Pharmacy benefit managers are unbundling field therapy coverage from lesion-directed reimbursement codes, creating distinct prior authorization pathways. This fragmentation disrupts traditional dermatology clinic revenue models built on bundled procedural billing. The shift is most visible in United States commercial insurance networks where step-therapy protocols now mandate topical immunomodulator failure before photodynamic authorization.
Global Actinic Keratosis Drugs Market Segmentation
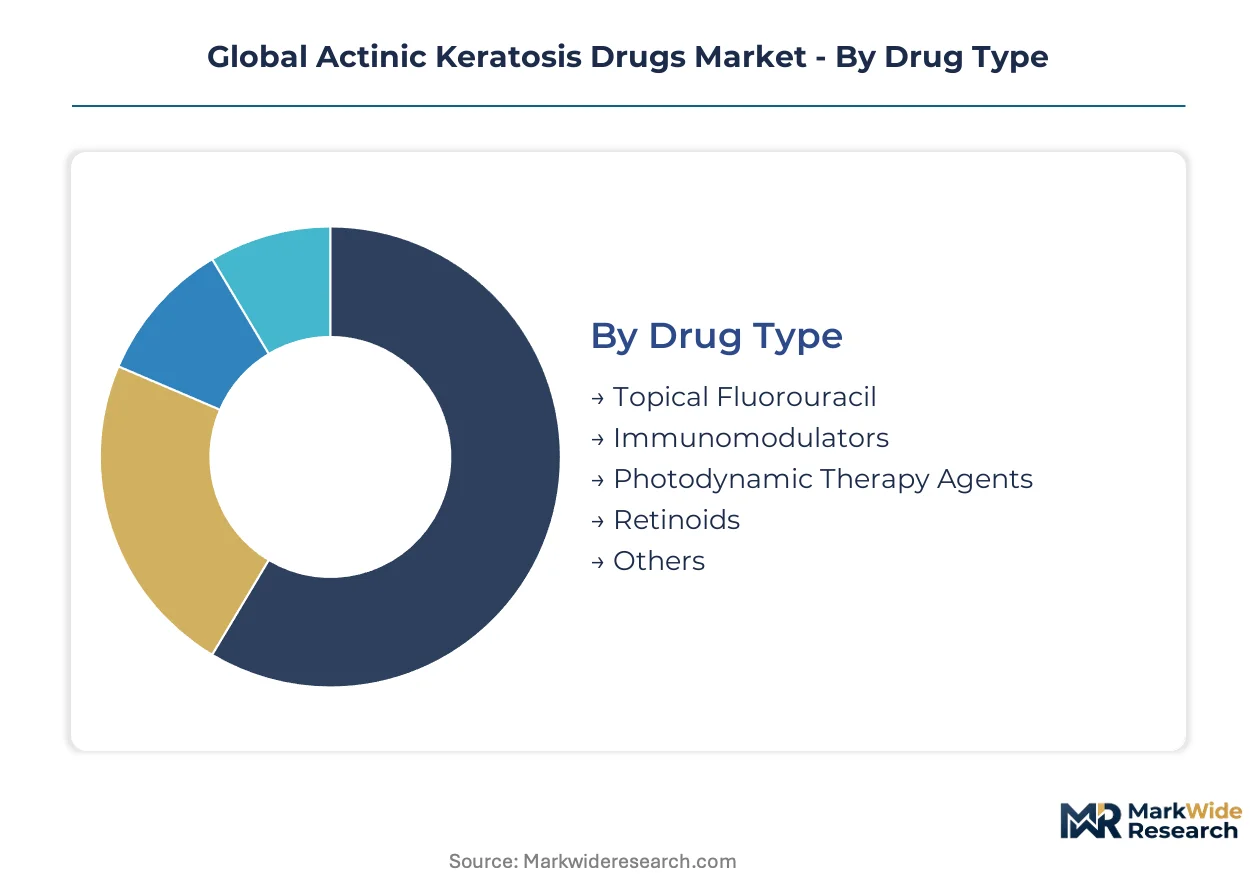
Actinic keratosis therapeutics fragment across multiple technical and commercial dimensions that determine reimbursement pathways, manufacturing scale requirements, and competitive moat durability. Understanding these segment boundaries clarifies where formulary access concentrates and which modalities face substitution pressure.
Drug Type:
Volume concentrates in legacy antimetabolites while premium capture shifts toward immunomodulatory mechanisms and device-dependent photosensitizers.
- Topical Fluorouracil:A pyrimidine antimetabolite that disrupts DNA synthesis in rapidly dividing keratinocytes through thymidylate synthase inhibition. Dermatology clinics in Germany and the United States deploy this agent for extensive field therapy where cost containment dominates protocol selection, though generic price erosion compresses sponsor margins.
- Immunomodulators:Toll-like receptor agonists—principally imiquimod and resiquimod—that stimulate local interferon production and cell-mediated immunity against dysplastic keratinocytes. Demand concentrates in US outpatient networks where pharmacy benefit managers favor patient-administered regimens that reduce clinic capacity utilization.
- Photodynamic Therapy Agents:Aminolevulinic acid and methyl aminolevulinate requiring 630nm red light activation to generate reactive oxygen species in neoplastic tissue. German reimbursement frameworks favor these agents for their shorter treatment courses.
- Retinoids:Vitamin A derivatives modulating epithelial differentiation and apoptosis. Prescribing concentrates in specialized skin institutes for chemoprevention protocols.
- Others:Diclofenac sodium and ingenol mebutate representing niche mechanistic alternatives with limited formulary penetration.
Today's leader: Topical Fluorouracil. Tomorrow's challenger: Immunomodulators.
Formulation:
Cream formats dominate prescription volume while gel and patch innovations command price premiums through enhanced cosmetic tolerability and dosing precision.
- Cream:Oil-in-water emulsion vehicles delivering 0.5% to 5% fluorouracil concentrations with established stability profiles. Manufacturing scale at Sun Pharmaceutical anchors cost structures.
- Gel:Hydroalcoholic matrices improving skin penetration for immunomodulator delivery. US dermatology clinics favor gels for facial applications where cosmetic acceptability drives adherence.
- Solution:Liquid vehicles enabling scalp and hair-bearing area application where cream residue creates patient dissatisfaction.
- Patch:Occlusive delivery systems controlling drug release kinetics and reducing application frequency. Biofrontera AG explores patch formats for photodynamic therapy agent stabilization.
- Ointment:Petrolatum-based vehicles for hyperkeratotic lesions requiring enhanced occlusion and moisture retention.
Volume leader: Cream. Premium trajectory: Gel.
Application:
Clinical protocols diverge between lesion-directed intervention for discrete pathology and field-wide treatment addressing subclinical photodamage across entire anatomic zones.
- Field Therapy:Treatment of entire sun-damaged areas to eliminate visible and subclinical actinic keratoses simultaneously. German outpatient networks favor this approach for its efficiency in high-volume settings.
- Lesion-directed Therapy:Targeted application to individual confirmed lesions with cryotherapy or pharmacologic agents. US Medicare reimbursement codes historically favored this lower-cost modality.
- Combination Therapy:Sequential or concurrent use of multiple mechanisms—typically immunomodulator followed by photodynamic therapy. EMA histological clearance mandates elevate evidence requirements for these protocols.
- Preventive Treatment:Long-term retinoid administration in immunosuppressed transplant recipients. Specialized skin institutes in France and Switzerland pioneer these protocols.
Reimbursement gravity: Field Therapy. Evidence frontier: Combination Therapy.
End User:
Site-of-care economics determine device investment feasibility and pharmacy dispensing models across institutional categories with divergent capital allocation authority.
- Dermatology Clinics:Private outpatient facilities performing the majority of actinic keratosis diagnoses and treatments. German clinic networks drive photodynamic therapy adoption through device-drug bundling contracts.
- Hospitals:Academic medical centers managing complex cases with extensive field involvement or immunosuppression. US hospital systems integrate teledermatology screening to expand capture.
- Specialized Skin Institutes:Dedicated facilities with advanced photodynamic therapy infrastructure and dermatopathology capabilities. Swiss and French institutes lead central assessment protocols for EMA submissions.
- Research Centers:Sites conducting phase II and III trials under FDA lesion count or EMA histological clearance endpoints. Trial concentration in the United States and Germany shapes regulatory precedent.
Volume concentration: Dermatology Clinics. Protocol innovation: Specialized Skin Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dermatology clinics anchor photodynamic therapy adoption through device-drug bundling contracts that lock in protocol adherence. The United States drives immunomodulator demand via pharmacy benefit manager preference for patient-administered regimens. Japanese METI reimbursement pilots and Swiss histopathology expertise reshape competitive positioning across mature markets.
United States
Teledermatology screening infrastructure accelerates early-stage diagnosis across commercial insurance networks. FDA lesion count endpoint requirements force parallel trial designs that inflate development costs for combination therapies. Dermatology clinics in Florida and Arizona concentrate field therapy volume due to elevated UV exposure demographics.
Germany
Outpatient networks favor photodynamic therapy for shorter treatment courses and efficient high-volume settings. EU MDR Article 117 device-drug combination classifications impose notified body involvement previously avoided under medical device directives. Berlin and Munich clinic clusters prioritize suppliers with established MDR technical documentation.
Japan
METI reimbursement pilot programs for device-drug combinations create first-mover positioning for protocol sponsors. PMDA regulatory pathways emphasize local clinical data requirements that extend market entry timelines. Osaka and Tokyo dermatology centers lead adoption of photosensitizer nanoemulsion formulations.
Switzerland
Specialized skin institutes pioneer central assessment protocols for EMA histological clearance mandates. Swissmedic governs device-drug combination approvals with stringent quality management system requirements. Basel and Geneva research centers concentrate dermatopathologist training programs that outpace workforce supply.
France
ANSM regulations shape outpatient reimbursement frameworks for lesion-directed versus field therapy protocols. Pharmacy benefit managers unbundle coverage codes that disrupt traditional clinic revenue models. Paris and Lyon dermatology networks drive preventive retinoid administration in immunosuppressed transplant recipients.
Global Actinic Keratosis Drugs Market Competitive Landscape
Global majors compete with regional champions across formulation manufacturing and device-drug integration capabilities. Market structure tilts toward consolidated immunomodulator portfolios alongside fragmented generic antimetabolite supply. Three archetypes dominate: integrated dermatology specialists, manufacturing-scale generic producers, and photodynamic therapy system bundlers. Capacity expansion in cream formulations and strategic partnerships for nanoemulsion delivery represent the dominant competitive moves.
Within the integrated dermatology tier, Galderma S.A. and LEO Pharma occupy positions sustained by formulary access across European outpatient networks. Sun Pharmaceutical Industries Ltd exemplifies the manufacturing-scale archetype through generic fluorouracil production. Biofrontera AG anchors the device-drug bundling segment via photodynamic therapy protocol control in German and US clinics.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| Galderma S.A. |
| Biofrontera AG |
| Almirall S.A. |
| Bausch Health Companies Inc |
| LEO Pharma |
| 3M Company |
| Hill Dermaceuticals Inc |
| Cipher Pharmaceuticals Inc |
| Others |
Supply & Pricing Matrix
Aminolevulinic acid active pharmaceutical ingredient costs cascade through photodynamic therapy pricing tiers, with concentrated photosensitizer manufacturing in Germany and the United States amplifying sponsor margin leverage at the premium end while generic fluorouracil commoditization compresses value at the economy tier.
Pricing Analysis
Input-cost pass-through from single-source photosensitizer suppliers elevates photodynamic therapy agent pricing relative to topical antimetabolites. Three-tier pricing structure across premium, standard, and economy levels separates device-drug bundled protocols from cream-based field therapy and generic fluorouracil commoditization. Pricing pressure stems from pharmacy benefit manager step-therapy protocols mandating immunomodulator failure before photodynamic authorization. Hospital systems exhibit lowest price sensitivity due to bundled procedural billing, while independent dermatology clinics face acute margin compression.
Supply Chain Analysis
EU MDR Article 117 certification requirements gate photodynamic system suppliers, forcing notified body involvement that filters subscale competitors from German and French outpatient procurement. Manufacturing concentrates in India for generic fluorouracil APIs, the United States for immunomodulator formulation, and Germany for photosensitizer nanoemulsion production. Raw material dependencies encompass aminolevulinic acid precursors, toll-like receptor agonist intermediates, and 630nm red light activation devices. Single-source vulnerability in photosensitizer API supply exposes formulation sponsors to disruption. Distribution runs through pharmacy benefit manager formularies in the United States and hospital procurement consortia in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Actinic Keratosis Drugs Market compounds steadily as aging demographics expand the addressable patient pool with cumulative UV exposure, sustaining durable demand for lesion-directed and field-wide therapeutic protocols.
For Market Incumbents: Deploy formulary lock-in contracts to secure pharmacy benefit manager preference before step-therapy protocols harden. Consolidate manufacturing scale in cream formulations to defend against Sun Pharmaceutical's generic fluorouracil cost position. Channel control through dermatology clinic device-drug bundling counters substitution pressure from immunomodulator patient-administered regimens. For New Entrants and Emerging Players: Pharmacy benefit manager partnership structures offer the most penetrable entry vector for home-use immunomodulator formulations bypassing clinic capacity constraints. White-space concentrates in Japanese outpatient photodynamic expansion under METI reimbursement pilots and EU MDR combination product harmonization pathways. A go-to-market angle anchored in teledermatology platform integration captures early-stage diagnosis workflow. For Investors and Strategic Acquirers: Consolidation pressure builds where device-drug bundling capabilities fragment across subscale photodynamic therapy sponsors lacking MDR technical documentation. Long-term viability favors integrated dermatology specialists with formulary access spanning European outpatient networks and US commercial insurance. The signal to monitor is pharmacy benefit manager unbundling of field therapy coverage codes, which would accelerate margin compression in commoditized topical antimetabolites.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Endpoint Harmonization | Parallel FDA lesion count and EMA histological clearance designs inflate development costs for combination therapies. |
| Device-Drug Bundling Contract Expansion | German clinic network lock-in protocols reduce therapeutic substitution and secure recurring photosensitizer revenue. |
| Home-Use Formulation Development | Patient-administered immunomodulator regimens capture pharmacy benefit manager preference for reduced clinic utilization. |
| Photosensitizer Nanoemulsion Scale-Up | Second-generation aminolevulinic acid derivatives compress efficacy gaps with surgical alternatives in US and German adoption. |
| EU MDR Technical Documentation Investment | Notified body involvement requirements filter competitors and prioritize established quality management systems in French procurement. |
Research Methodology
Direct dialogue with dermatology clinic procurement directors, formulary access specialists at pharmacy benefit managers, regulatory affairs leads at photodynamic therapy sponsors, and hospital system teledermatology platform engineers grounded qualitative insights. Secondary validation drew from FDA 510(k) filings, EMA centralized procedure assessments, ClinicalTrials.gov protocol registries, and German outpatient reimbursement framework documentation. Bottom-up patient volume modeling and top-down pharmaceutical expenditure analysis triangulated market sizing.
Bottom-up segmentation by drug type, formulation, application protocol, and end-user site-of-care anchored the analytical framework across the projection horizon. Treatment line positioning, regional regulatory cluster divergence, and patient adherence profile by administration route shaped segment-level growth trajectories. CAGRs derived from historical procedure volume elasticity to reimbursement rate changes and photosensitizer adoption curves in German pilot markets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance evolution on topical immunomodulator label claims and EMA histopathology reader certification workforce expansion. Model assumptions reflect current reimbursement parity frameworks and EU MDR implementation timelines. A model refresh is warranted upon material change in pharmacy benefit manager step-therapy protocol stringency or photodynamic therapy device-drug bundling contract renewal rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Global Hairy Cell Leukemia Drugs Market
Biopharmaceuticals
HIV Drugs Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Inactivated Vaccines Market
Biopharmaceuticals
Biopharmaceutical Oral Drug Delivery Market
Biopharmaceuticals
Immunocytokines Market
Biopharmaceuticals
Cephalosporin Market
Biopharmaceuticals
Global Endocrinology Drugs Market
Biopharmaceuticals
Recombinant Therapeutic Antibodies and Proteins Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market