
 Ocular Tuberculosis Therapeutics Market | 2026-2036
Ocular Tuberculosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Tuberculosis Therapeutics Market Analytics
Specialized ophthalmic pharmacology expertise is rotating toward ocular TB management as diagnostic capabilities improve and extrapulmonary case recognition expands. Bayer HealthCare AG leverages its anti-infective portfolio depth to sustain leadership in rifamycin-class compounds for ocular applications. Johnson & Johnson anchors hospital formulary access through its established TB therapeutic infrastructure. Novartis differentiates via integrated corticosteroid and immunomodulatory offerings that address the inflammatory complications of tubercular uveitis.
Ocular tuberculosis therapeutics comprise pharmaceutical agents targeting Mycobacterium tuberculosis infection of the eye and its immune-mediated complications, typically combining anti-tubercular drugs with adjunctive corticosteroids to prevent vision loss from choroidal granulomas and retinal vasculitis. Anti-TB drugs dominate prescription volumes as first-line protocols, while corticosteroids capture concentrated margin pools through branded intraocular and periocular formulations. Hospital pharmacies control the primary distribution channel for acute cases requiring supervised intravenous loading, though retail pharmacies extend reach for maintenance oral regimens in stable patients.
FDA oversight of sterile ophthalmic manufacturing and WHO prequalification standards for anti-TB medicines jointly determine market access for multi-ingredient ocular protocols. India's CDSCO regulates local production of fixed-dose combination therapies, while REACH compliance shapes import requirements for European hospital procurement. Stakeholders must monitor evolving pharmacovigilance databases for ocular TB drug interactions as biologics enter clinical pipelines against steroid-resistant uveitic presentations.
Market Dynamics
WHO treatment guidelines for extrapulmonary tuberculosis are compressing prescription timelines and forcing hospital ophthalmology departments toward standardized combination protocols that reduce physician discretion in drug selection.
Growth Catalysts
- Diagnostic capability expansion:PCR-based ocular fluid testing is shortening time-to-diagnosis from weeks to days, enabling earlier therapeutic intervention in tubercular uveitis cases across tertiary eye care centers.
- CDSCO fixed-dose mandates:India's regulatory push for standardized rifampicin-isoniazid combinations is streamlining procurement and reducing medication errors in high-volume public health programs.
- Hospital formulary centralization:Ophthalmology departments are consolidating vendor relationships around established anti-TB suppliers to secure volume pricing on intravenous loading doses.
Market Restraints
- API supply concentration:Rifampicin active pharmaceutical ingredient production clusters in Chinese and Indian chemical hubs, creating vulnerability to environmental compliance shutdowns and export restriction volatility.
- Sterile manufacturing capex barriers:FDA aseptic processing requirements for ophthalmic formulations demand capital-intensive isolator technology that excludes smaller compounders from commercial-scale production.
- Diagnostic substitution pressure:Interferon-gamma release assays are displacing tuberculin skin testing in some markets, creating protocol fragmentation that complicates therapeutic decision trees.
Strategic Opportunities
- Periocular depot formulations:Sustained-release corticosteroid implants address the compliance gap in maintenance therapy for steroid-responsive tubercular uveitis, reducing injection frequency burdens.
- REACH-compliant European hospital procurement:ECHA chemical safety documentation requirements are creating first-mover advantage for suppliers with pre-registered ocular excipient portfolios.
- Teleophthalmology integration:Remote monitoring platforms enable rural patient adherence tracking for maintenance oral regimens, extending retail pharmacy reach beyond urban hospital catchments.
Industry Challenges
- Ocular pharmacology specialization gaps:Training programs produce insufficient clinicians capable of managing drug-induced hepatotoxicity monitoring alongside intraocular pressure management in co-therapy protocols.
- Biologics pipeline integration complexity:Emerging anti-TNF agents for steroid-resistant presentations require pharmacovigilance infrastructure that most hospital ophthalmology departments lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Tuberculosis Therapeutics Market |
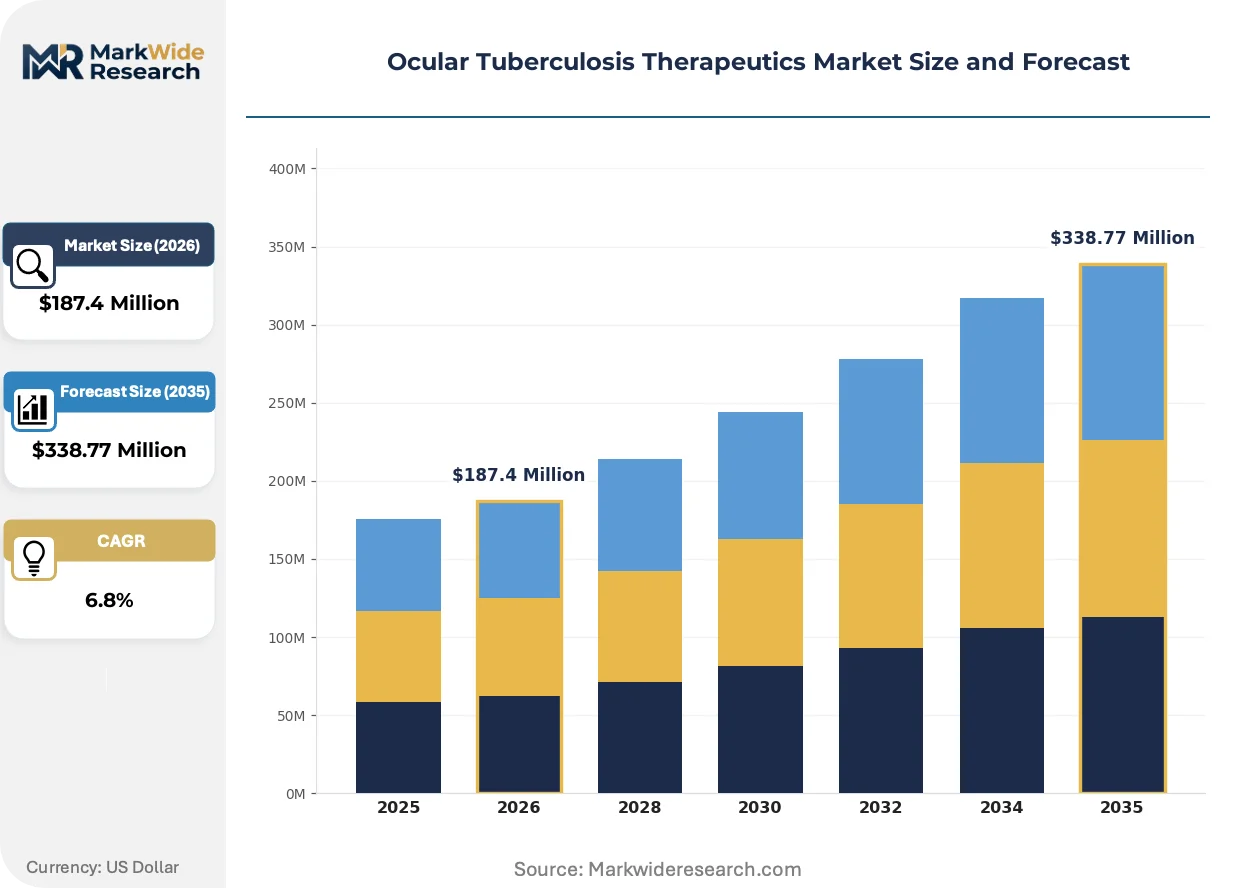
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-TB Drugs, Corticosteroids, Immunosuppressants, Biologics End User: Hospitals, Clinics, Research Laboratories, Homecare Settings Administration Route: Oral, Intravenous, Topical, Sublingual Distribution Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Specialty Stores |
| Companies Covered | AstraZeneca, Bayer HealthCare AG, Johnson & Johnson, Novartis, Pfizer, Sanofi, Lupin Pharmaceuticals Inc., Macleods Pharmaceuticals Ltd., Cadila Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Tuberculosis Therapeutics Market Evolving Landscape
Fragmentation across diagnostic modalities and treatment protocols is creating parallel therapeutic pathways that complicate standardization efforts while opening niche positioning opportunities for specialized compounders.
Polymer-based sustained-release intravitreal implants are fragmenting the corticosteroid delivery landscape by enabling month-long drug release profiles that reduce injection frequency. Tertiary eye hospitals in India and Brazil are adopting these implants for posterior uveitis cases where compliance with frequent periocular injections proves unreliable. The technology is fragmenting margin pools away from conventional solution formulations toward device-drug combination products with differentiated reimbursement profiles.
REACH substance restriction candidate listing for certain ophthalmic preservatives is forcing European formulators toward alternative sterilization methods and excipient substitutions. The regulation compresses formulation flexibility for multi-dose topical products while accelerating adoption of single-use vial formats in hospital settings. German and French hospital procurement consortia are now requiring full Article 33 supply chain disclosure for ocular TB combination therapies.
Centralized hospital pharmacy compounding is displacing ward-level medication preparation for intravitreal anti-TB protocols, concentrating therapeutic decision authority within infectious disease oversight committees. This consolidation reduces medication error incidence but extends treatment initiation timelines in acute presentations. The shift is most pronounced in Indian multi-specialty hospital chains where CDSCO cGMP inspections have raised compliance stakes for sterile preparation facilities.
Ocular Tuberculosis Therapeutics Market Segmentation
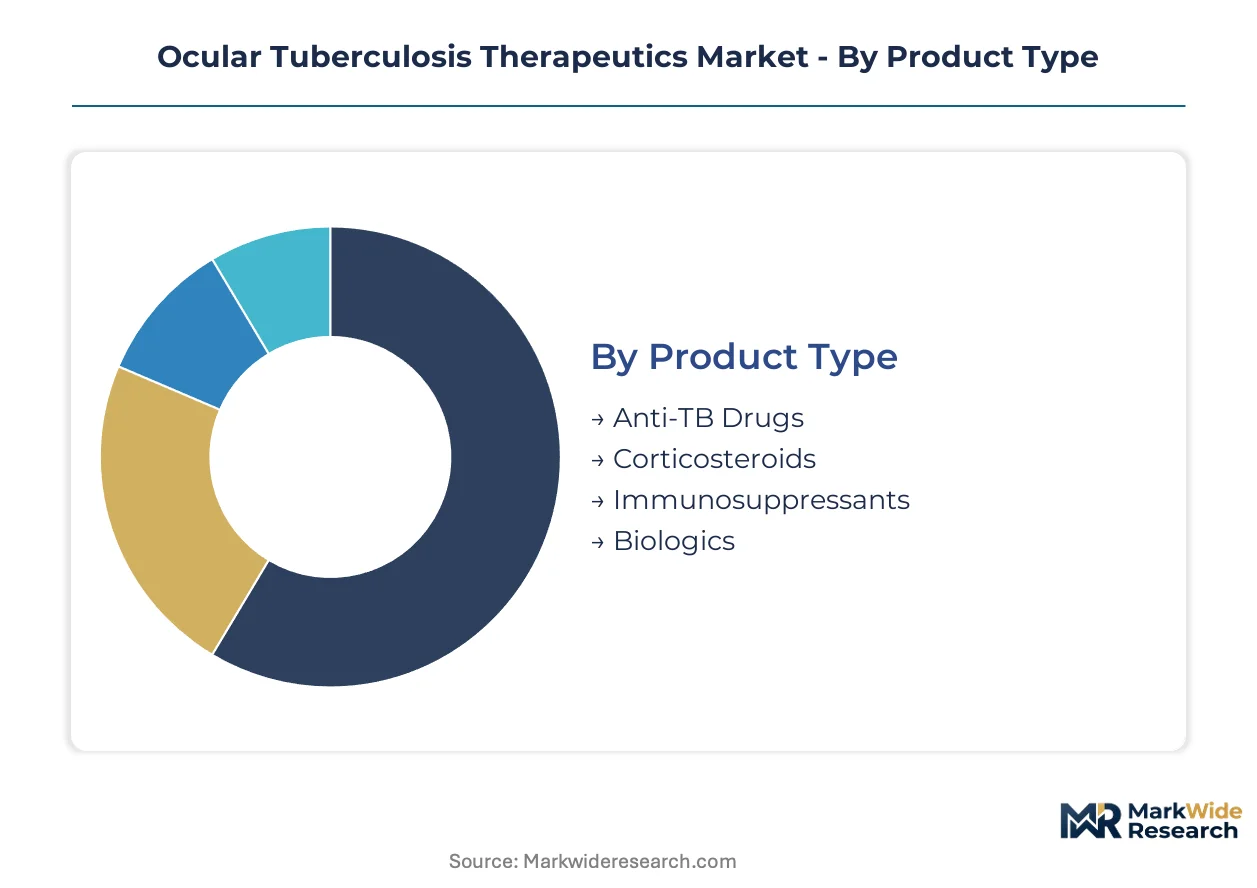
Segmentation in ocular TB therapeutics reveals divergent margin structures across administration routes and procurement channels. Product type and end-user configurations determine reimbursement pathways and regulatory scrutiny intensity.
Product Type:
Margin concentration tilts toward combination protocols where anti-TB backbone drugs anchor volume while corticosteroid adjuncts capture premium pricing.
- Anti-TB Drugs:Rifampicin-isoniazid-ethambutol combinations form the therapeutic backbone for tubercular uveitis protocols. Demand clusters in Indian public health programs where CDSCO fixed-dose mandates streamline procurement at scale. WHO prequalification requirements constrain supplier pools to established manufacturers with validated sterile production lines.
- Corticosteroids:Periocular and intraocular formulations address inflammatory complications of choroidal granulomas and retinal vasculitis. Tertiary eye hospitals in Brazil and India are adopting sustained-release implants to reduce injection frequency burdens in compliance-challenged patient populations. Branded depot formulations command pricing multiples over conventional solution presentations.
- Immunosuppressants:Cyclosporine and methotrexate serve as steroid-sparing alternatives in refractory cases.
- Biologics:Anti-TNF agents enter clinical pipelines for steroid-resistant presentations requiring specialized pharmacovigilance infrastructure.
Anti-TB drugs hold installed capacity. Biologics are rotating up the share rankings.
End User:
Procurement authority concentrates in hospital settings where infectious disease oversight committees govern therapeutic decision trees.
- Hospitals:Tertiary ophthalmology departments manage acute presentations requiring supervised intravenous loading and hepatotoxicity monitoring. Centralized pharmacy compounding is displacing ward-level preparation, extending treatment initiation timelines but reducing medication errors. Indian multi-specialty chains dominate volume procurement through consolidated vendor relationships.
- Clinics:Private ophthalmology practices handle stable maintenance cases with oral regimens and periocular injections. Teleophthalmology platforms are extending rural reach beyond urban hospital catchments through remote adherence tracking.
- Research Laboratories:Academic medical centers conduct PCR-based ocular fluid testing and biomarker development for diagnostic refinement.
- Homecare Settings:Self-administered oral maintenance regimens apply to stabilized patients with reliable compliance profiles.
Hospitals dominate current throughput. Clinics are gaining share fastest as diagnostic capability decentralizes.
Administration Route:
Route selection determines sterile manufacturing requirements and reimbursement complexity.
- Oral:Standard maintenance delivery for rifampicin-based protocols with established bioavailability profiles.
- Intravenous:Hospital-based loading doses for severe presentations require aseptic processing infrastructure.
- Topical:Periocular and intraocular corticosteroid delivery demands FDA-validated sterile ophthalmic manufacturing.
- Sublingual:Emerging alternative for patients with gastrointestinal absorption limitations or hepatotoxicity concerns.
Oral routes maintain volume leadership. Intravenous protocols are climbing the fastest as acute case recognition expands.
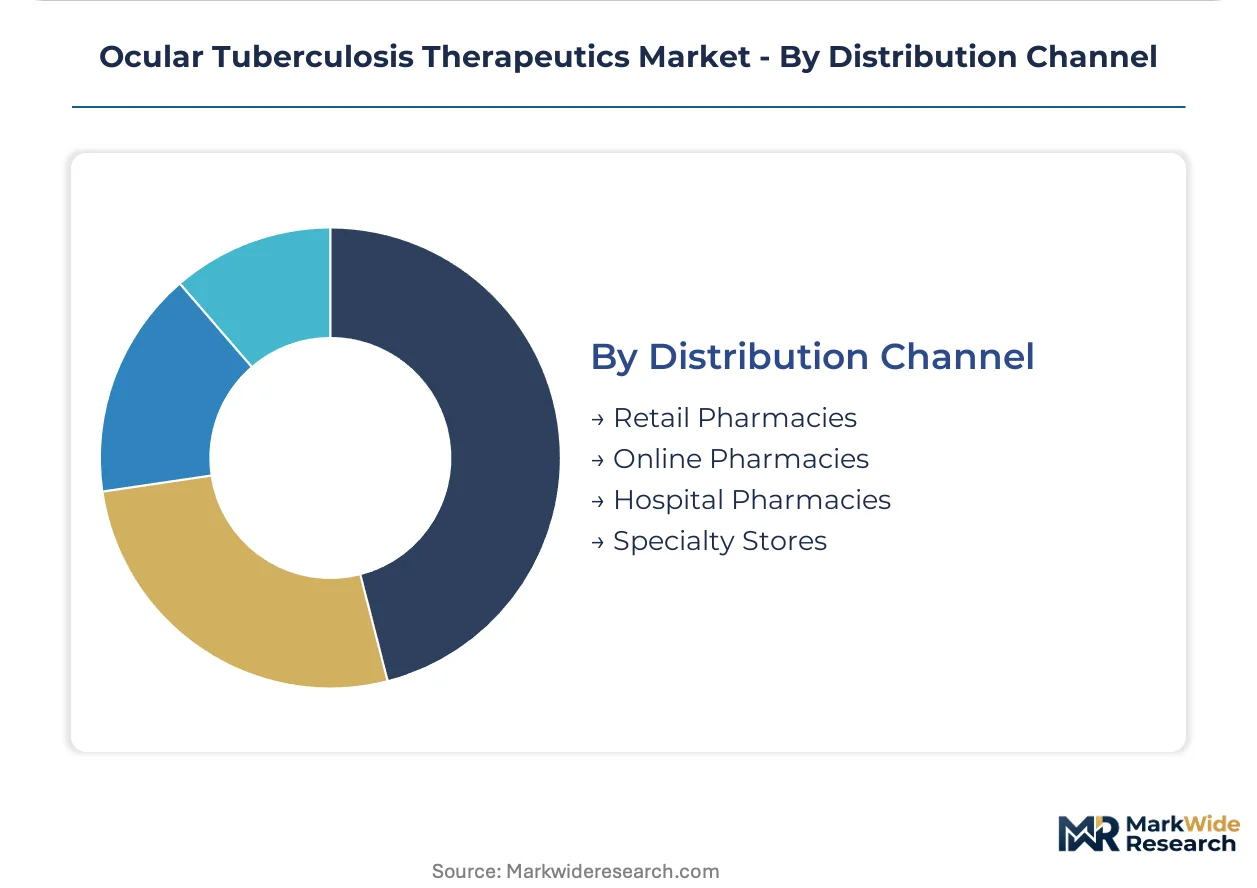
Distribution Channel:
Channel structure reflects the bifurcation between acute supervised care and chronic maintenance management.
- Retail Pharmacies:Maintenance oral regimens for stable patients with established prescriptions.
- Online Pharmacies:Direct-to-patient delivery expanding in urban markets with established cold-chain logistics.
- Hospital Pharmacies:Control acute case distribution through formulary centralization and infectious disease committee oversight. Volume pricing agreements with established anti-TB suppliers concentrate procurement authority.
- Specialty Stores:Ophthalmology-focused dispensaries with compounding capabilities for customized corticosteroid preparations.
Hospital pharmacies command acute case flow. Online channels are expanding most quickly in maintenance segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO fixed-dose mandates anchor procurement patterns in India, the dominant geography for ocular tuberculosis therapeutics volume. WHO prequalification standards and FDA sterile manufacturing requirements shape market access across secondary clusters.
India
Tertiary eye hospitals in Delhi and Mumbai drive demand for rifampicin-based combination protocols as BIS quality mandates standardize public procurement. CDSCO cGMP inspections are consolidating vendor relationships around established manufacturers with validated sterile production lines. The Chennai-Bengaluru corridor hosts specialized ophthalmic compounding facilities serving southern hospital chains.
United States
Academic medical centers in Boston and Baltimore advance PCR-based ocular fluid diagnostics, shortening time-to-treatment for tubercular uveitis presentations. FDA oversight of sterile ophthalmic manufacturing constrains supplier pools to facilities with isolator technology. The NIH-funded research corridor in Maryland anchors biomarker development for steroid-resistant case identification.
Brazil
São Paulo's tertiary ophthalmology institutes adopt sustained-release corticosteroid implants for posterior uveitis cases with compliance challenges. ANVISA registration requirements for fixed-dose anti-TB combinations align with WHO treatment guidelines for extrapulmonary protocols. The Rio de Janeiro hospital network centralizes pharmacy compounding to reduce medication errors in intravitreal preparations.
Germany
REACH substance restriction listings for ophthalmic preservatives are forcing formulators toward alternative sterilization methods and single-use vial formats. ECHA Article 33 supply chain disclosure requirements now govern hospital procurement consortia in Berlin and Munich. The Rhine-Ruhr industrial cluster supplies excipient portfolios pre-registered for European chemical safety compliance.
China
NMPA regulation of rifampicin API production concentrates active pharmaceutical ingredient supply in Jiangsu and Zhejiang chemical hubs. Environmental compliance shutdowns periodically disrupt export volumes to dependent formulation markets. The Shanghai-Pudong corridor hosts sterile ophthalmic manufacturing facilities serving domestic hospital demand and regional export markets.
Ocular Tuberculosis Therapeutics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the ocular tuberculosis therapeutics market. Multinational pharmaceutical conglomerates with anti-infective and ophthalmology divisions dominate hospital formulary access through established TB therapeutic infrastructure. Mid-cap generic manufacturers and regional compounders occupy the specialist tier, focusing on fixed-dose combinations and localized corticosteroid formulations. Competitive moves concentrate on portfolio diversification into sustained-release delivery systems and backward integration into API production to secure supply chain resilience.
Among integrated pharmaceutical leaders, Bayer HealthCare AG and Novartis exemplify the dual-capability archetype combining rifamycin-class anti-infectives with corticosteroid and immunomodulatory offerings. Johnson & Johnson occupies a position anchoring hospital formulary relationships through its established tuberculosis therapeutic infrastructure. These three companies represent distinct strategic postures: Bayer leverages anti-infective portfolio depth, Novartis differentiates via inflammatory complication management, and Johnson & Johnson reinforces access through existing healthcare system embeddedness.
| Leading Market Players |
|---|
| AstraZeneca |
| Bayer HealthCare AG |
| Johnson & Johnson |
| Novartis |
| Pfizer |
| Sanofi |
| Lupin Pharmaceuticals Inc. |
| Macleods Pharmaceuticals Ltd. |
| Cadila Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Sustained-release corticosteroid implants displacing conventional periocular injections are redrawing procurement economics across Indian and Brazilian hospital networks while compressing margin pools for solution-based formulations. This substitution dynamic simultaneously concentrates supply geography around device-drug combination manufacturers with sterile isolator capabilities and fragments pricing power away from commoditized anti-TB backbone drugs toward branded depot delivery systems.
Pricing Analysis
Price spreads between European REACH-compliant single-use vials and Indian multi-dose presentations reach multiples of three to five times for equivalent corticosteroid potency. Three-tier pricing structure across premium branded implants, standard hospital-formulary combinations, and economy generic oral regiments captures divergent buyer archetypes. Cost compression in the oral anti-TB tier intensifies because CDSCO fixed-dose mandates consolidate procurement volume around lowest-qualified bidders. Public hospital systems in India exhibit highest price sensitivity, while private tertiary ophthalmology departments in São Paulo and Munich demonstrate lowest sensitivity for sustained-release formulations that reduce injection compliance burdens.
Supply Chain Analysis
China and India anchor rifampicin active pharmaceutical ingredient production, with Jiangsu and Zhejiang chemical hubs feeding formulation networks across Asia-Pacific and Latin America. The supply chain draws from isoniazid precursors, ethambutol intermediates, and corticosteroid raw materials sourced from European and North American specialty chemical producers. Single-source vulnerability concentrates in Chinese environmental compliance shutdowns that periodically disrupt API export volumes to dependent markets. Distribution runs through hospital pharmacy centralization for acute intravenous loading, with retail and online channels extending reach for maintenance oral regimens.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital formulary centralization is shifting procurement leverage toward infectious disease oversight committees and consolidated vendor relationships, compressing supplier negotiation position. This buyer-power consolidation demands defensive repositioning across incumbent portfolios.
For Market Incumbents: Shield margin pools in the corticosteroid depot segment by accelerating FDA-validated sustained-release pipeline submissions before REACH substance restrictions fully displace preservative-dependent formulations. Backward integration into rifampicin API production mitigates Chinese supply concentration risk. Prioritize CDSCO cGMP certification maintenance to defend Indian public procurement eligibility against tightening inspection protocols.
For New Entrants and Emerging Players: Differentiate on periocular depot formulation innovation for steroid-responsive tubercular uveitis maintenance therapy, where compliance gaps create unmet need. Target Brazilian and Indian private ophthalmology clinic networks as the most penetrable channel archetype, bypassing entrenched hospital formulary barriers. Pursue teleophthalmology platform partnerships as the primary go-to-market angle for rural patient adherence tracking and remote monitoring revenue streams.
For Investors and Strategic Acquirers: The market sits at a diagnostic-capability-expansion phase that favors platform-integrated delivery system specialists over pure-play anti-TB generic manufacturers. Long-term viability over the next decade hinges on capturing biologics pipeline integration for steroid-resistant presentations. Watch for anti-TNF agent regulatory submissions as the critical inflection signal for pharmacovigilance infrastructure investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Periocular Depot Formulation Development | Sustained-release implants address compliance gaps in maintenance therapy for Indian and Brazilian patient populations. |
| REACH-Compliant Excipient Pre-Registration | ECHA Article 33 disclosure requirements create first-mover advantage for European hospital procurement consortia. |
| Teleophthalmology Platform Integration | Remote monitoring extends retail pharmacy reach beyond urban hospital catchments into rural maintenance segments. |
| Backward API Integration | In-house rifampicin production insulates against Chinese environmental compliance shutdown volatility. |
| Biologics Pharmacovigilance Infrastructure | Anti-TNF agent pipelines for steroid-resistant uveitis require specialized safety monitoring capabilities. |
Research Methodology
A standing panel of hospital formulary directors, ophthalmology department heads, CDSCO regulatory affairs leads, and infectious disease oversight committee members provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, WHO prequalification databases, ClinicalTrials.gov ocular TB protocols, and Indian public procurement records. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing triangulated across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, administration route, end-user configuration, and regional regulatory cluster segmentations. CAGR derivation incorporated treatment protocol adoption curves, diagnostic capability expansion rates, and fixed-dose combination regulatory mandate timelines. Modeled inputs included hospital pharmacy compounding centralization trends, sustained-release implant adoption patterns, and biologics pipeline progression markers.
Material uncertainties — API supply disruption from environmental compliance actions, REACH substance restriction expansion, and biologics regulatory pathway delays — sit outside the modeled envelope. Forecasts reflect assumptions about diagnostic substitution rates and hospital procurement consolidation trajectories. Recalibration cycles align with material shifts in WHO treatment guideline revisions and CDSCO cGMP inspection intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Brazil Generic Drug Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Erythropoietin Drugs Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Recombinant Human Interferon Protein Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
PCSK9 Inhibitors Market