
 US Generic Drug Market | 2026-2036
US Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
US Generic Drug Market Intelligence
ANDA certification is unwinding competitive access for domestic manufacturers. Teva Pharmaceutical Industries leverages its vertical integration across API and finished dosage forms to sustain cost leadership. Viatris anchors hospital channel relationships through injectable portfolios. Sun Pharmaceutical Industries specializes in complex generic formulations with higher technical barriers.
Generic drugs are chemically equivalent copies of brand-name pharmaceuticals, manufactured after patent expiry with identical active pharmaceutical ingredients, dosage forms, and bioequivalence profiles validated through pharmacokinetic studies. These products deliver equivalent therapeutic outcomes at substantially lower cost, serving as the primary mechanism for pharmaceutical expenditure reduction in national healthcare systems. Tablets dominate volume production due to manufacturing scalability and patient compliance advantages, while injectables command premium positioning within hospital procurement frameworks. The therapy area segmentation reveals cardiovascular and oncology generics as mature volume centers, with neurology emerging as a faster-growing margin pool driven by complex formulation requirements.
FDA oversight through ANDA review, current Good Manufacturing Practice enforcement, and the Drug Supply Chain Security Act collectively shape manufacturer compliance burdens and market access timelines. The IRA's Medicare price negotiation provisions redirect generic substitution incentives toward therapeutic categories facing federal pricing pressure. Stakeholders must monitor how FDA inspection backlogs and evolving bioequivalence standards for complex products reshape competitive viability.
Market Dynamics
The IRA's Medicare price negotiation provisions are compressing brand-name pricing floors, redirecting hospital procurement toward complex injectable generics as the primary mechanism for pharmaceutical expenditure containment. This regulatory pressure intersects with FDA ANDA backlogs to create selective access windows for manufacturers with pre-approved abbreviated applications.
Growth Catalysts
- IRA Medicare Price Negotiation:Federal pricing pressure on therapeutic categories accelerates generic substitution incentives, expanding hospital formulary access for injectable alternatives.
- Atlanta and Miami Distribution Hubs:Specialty pharmacy concentration in the southeastern United States reduces logistics costs for temperature-sensitive biologics and complex formulations.
- Continuous Manufacturing:Adoption of process analytical technology and real-time release testing compresses batch cycle times and quality control expenditures.
Market Restraints
- API Import Dependence:Active pharmaceutical ingredient sourcing concentrates in India and China, exposing manufacturers to geopolitical friction and customs delays.
- FDA Inspection Backlogs:Post-pandemic facility audit queues extend ANDA approval timelines, freezing competitive entry for domestic applicants without existing site clearances.
- Complex Product Bioequivalence:Long-acting injectables and ophthalmic suspensions lack validated pharmacokinetic surrogates, raising development costs and failure rates.
Strategic Opportunities
- Neurology Complex Formulations:Technical barriers around controlled-release antiepileptics and Parkinson's therapies create margin pools underserved by commodity tablet manufacturers.
- 340B Contract Pharmacy Expansion:Federal drug pricing program growth channels outpatient generic volume through hospital-affiliated dispensaries.
- Digital Therapeutic Adjacencies:Combination products integrating adherence monitoring with generic drug delivery open reimbursement pathways beyond commodity pricing.
Industry Challenges
- Process Analytical Technology Talent:Scarcity of chemometricians and PAT implementation specialists constrains continuous manufacturing scale-up.
- Drug Supply Chain Security Act Serialization:Unit-level traceability mandates require capital deployment for packaging line upgrades and data infrastructure.
- Reference Listed Drug Sourcing:Brand manufacturer restrictions on comparator product availability delay bioequivalence study initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Generic Drug Market |
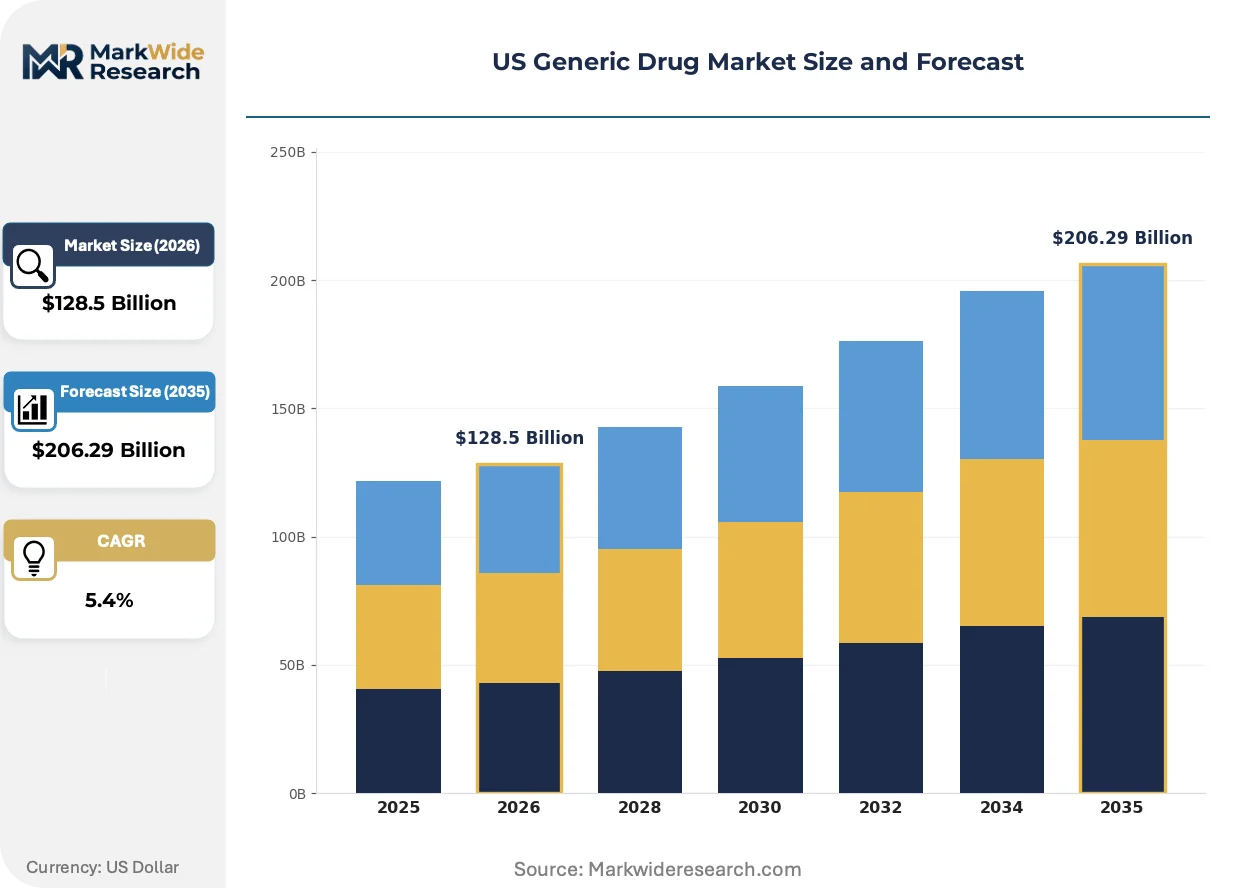
| Market Size in 2026 | $128.5 Billion |
| Market Size in 2035 | $206.29 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Injections, Topicals End User: Clinics, Hospitals, Pharmacies, Wholesalers Distribution Channel: Online Retail, Direct Sales, Drug Stores, Hospital Pharmacies Therapy Area: Cardiovascular, Neurology, Oncology, Endocrinology |
| Companies Covered | Teva Pharmaceutical Industries, Viatris, Sandoz, Sun Pharmaceutical Industries, Lupin, Amneal Pharmaceuticals, Aurobindo Pharma, Dr. Reddy's Laboratories, Apotex, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Generic Drug Market Strategic Shifts & Innovations
Generic drug manufacturing is splitting between high-volume commodity production and technically differentiated complex formulations, with regulatory science and process technology determining competitive positioning across each path.
Continuous direct compression and hot-melt extrusion equipment is bifurcating tablet manufacturing economics. Large-scale adopters in cardiovascular and analgesic categories achieve unit cost advantages of 30-40 percent against batch operations. Mid-tier manufacturers without capital access face margin compression in solid oral dosage forms, accelerating sector consolidation toward integrated API-to-tablet operations.
FDA's emerging guidance on complex generic bioequivalence for locally acting products tightens pharmacokinetic validation standards. Inhaled and nasal spray categories face extended development timelines as the agency demands clinical endpoint studies. Dermatology and respiratory generic sponsors are responding with increased investment in physiologically based pharmacokinetic modeling to preempt regulatory queries.
Hospital procurement consolidation through group purchasing organizations concentrates contract awards among manufacturers with broad injectable portfolios. Health system formulary committees now require single-source accountability for shortage-prone molecules, displacing fragmented multi-supplier arrangements. This behavioral shift is most visible in the southeastern United States, where integrated delivery networks around Atlanta and Miami negotiate multi-year supply agreements with penalty clauses for stockout events.
US Generic Drug Market Segmentation
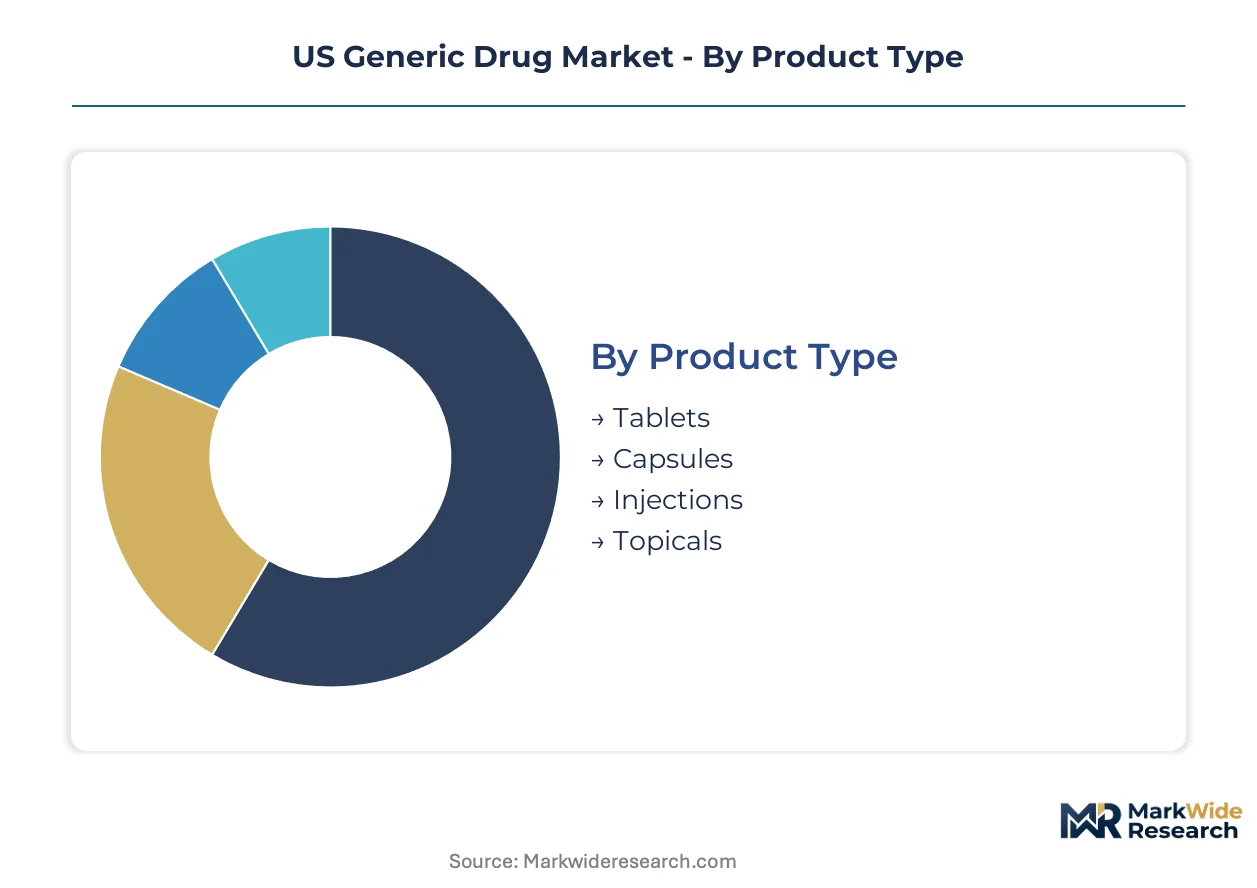
Segmentation in the US generic drug market reveals divergent margin structures across formulation complexity and procurement channels. Hospital buyers prioritize injectable reliability over tablet cost minimization, while therapy area specialization determines development investment thresholds.
Product Type:
Margin pools concentrate in parenteral formulations where manufacturing complexity erects competitive barriers, while oral solids compete on scale economies.
- Injections:Sterile liquid formulations requiring aseptic processing and endotoxin control command premium positioning within hospital procurement frameworks. Demand clusters around southeastern integrated delivery networks in Atlanta and Miami, where specialty pharmacy hubs minimize cold-chain logistics costs for temperature-sensitive biologics.
- Tablets:Compressed solid dosage forms dominate unit volume through manufacturing scalability and patient compliance advantages. Procurement concentrates in cardiovascular and analgesic categories where continuous direct compression technology compresses unit costs for large-scale adopters.
- Capsules:Gelatin or HPMC shells enclosing powder or pellet formulations serve modified-release applications.
- Topicals:Creams, ointments, and transdermal patches address dermatological and localized pain management.
Injections hold installed capacity. Tablets are rotating up the share rankings.
End User:
Procurement authority patterns split between institutional formulary committees and retail dispensing economics.
- Hospitals:Inpatient facilities with group purchasing organization contracts prioritize shortage-prone molecule security over per-unit cost minimization. The southeastern United States exhibits concentrated negotiating leverage through integrated delivery networks demanding multi-year supply agreements with stockout penalties.
- Clinics:Outpatient settings with 340B program participation channel federal drug pricing discounts through hospital-affiliated dispensaries.
- Pharmacies:Community and chain retail dispensaries drive substitution incentives for orally administered chronic therapies.
- Wholesalers:Distribution intermediaries consolidate procurement across fragmented pharmacy accounts.
Hospitals anchor volume concentration. Clinics are climbing the fastest.
Distribution Channel:
Channel selection determines reimbursement pathway access and patient adherence monitoring capabilities.
- Hospital Pharmacies:Captive dispensaries within integrated delivery networks manage formulary compliance for inpatient and 340B outpatient volume.
- Drug Stores:Chain and independent retail locations dominate Medicare Part D beneficiary access for maintenance medications.
- Direct Sales:Manufacturer-to-institution contracts bypass wholesale markups for high-volume injectable agreements.
- Online Retail:Mail-order and specialty pharmacy platforms serve chronic disease management with adherence packaging.
Hospital pharmacies control formulary gatekeeping. Online retail is gaining share fastest.
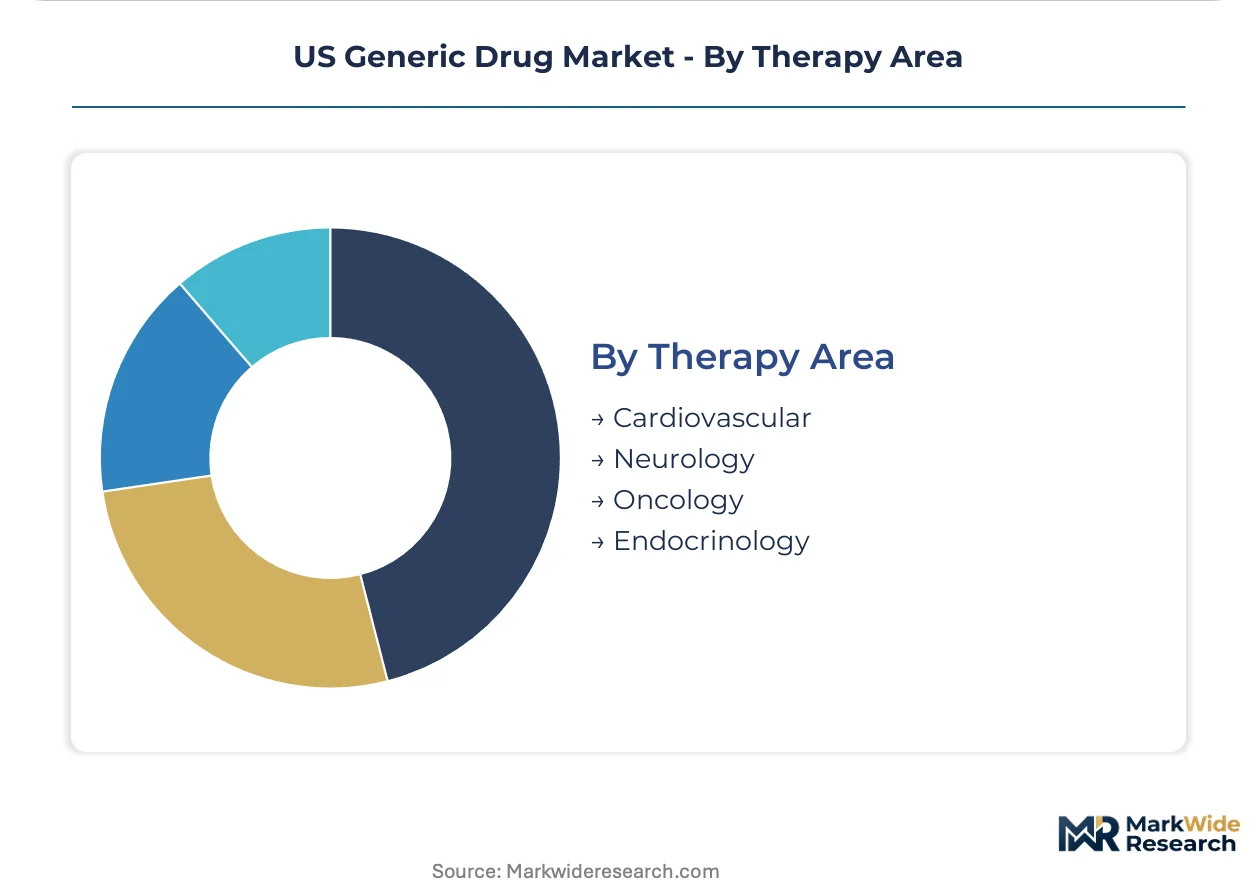
Therapy Area:
Technical barriers and patent cliff timing create uneven competitive intensity across therapeutic categories.
- Neurology:Controlled-release antiepileptics and Parkinson's therapies require complex formulation expertise that commodity manufacturers avoid. FDA bioequivalence standards for locally acting products extend development timelines, concentrating margin pools among sponsors with physiologically based pharmacokinetic modeling capabilities.
- Oncology:Cytotoxic injectables and supportive care molecules face hospital procurement consolidation toward single-source accountability for shortage-prone therapies.
- Cardiovascular:Statins and antihypertensives represent mature volume centers where continuous manufacturing achieves maximum scale economies.
- Endocrinology:Insulin and synthetic hormone generics compete with reference product reformulation strategies.
Cardiovascular holds installed capacity. Neurology represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The IRA's Medicare price negotiation provisions redirect hospital procurement toward southeastern distribution hubs. State-level Medicaid formulary policies and 340B program expansion create uneven access corridors across metropolitan clusters.
Southeast
Atlanta and Miami anchor specialty pharmacy concentration for temperature-sensitive biologics. Georgia's Medicaid preferred drug list reforms accelerate generic substitution for chronic therapies. Integrated delivery networks in Florida negotiate multi-year injectable supply agreements with stockout penalty clauses.
Northeast
Greater Boston and New York Metro house FDA review divisions and bioequivalence testing laboratories. Massachusetts health policy institutes pilot value-based generic procurement for hospital formularies. New York's 340B contract pharmacy density channels outpatient volume through hospital-affiliated dispensaries.
Midwest
Illinois and Michigan host group purchasing organization headquarters consolidating hospital procurement authority. Chicago-area health systems demand single-source accountability for shortage-prone oncology injectables. Ohio's pharmaceutical manufacturing corridor supplies API intermediates to regional finishers.
Southwest
Texas medical center complexes in Houston and Dallas drive demand for complex parenteral formulations. The state's independent pharmacy network density supports generic substitution incentives for Medicare Part D beneficiaries. San Antonio military health facilities procure through federal supply schedule contracts.
Pacific
California's biosimilar substitution legislation and Medi-Cal rebate negotiations compress reimbursement floors. Los Angeles and San Francisco Bay Area biotech clusters incubate continuous manufacturing technology vendors. Washington state's hospital association coordinates shortage monitoring for critical care injectables.
US Generic Drug Market Key Industry Players
Listed leaders compete with private specialists across manufacturing scale and therapy area depth. The vendor base splits between vertically integrated API-to-tablet operators and formulation-focused finishers. Three archetypes dominate: Israeli multinationals with captive API supply, Indian conglomerates with complex generic specialization, and North American hospital channel specialists. Competitive moves center on ANDA portfolio accumulation and continuous manufacturing technology licensing.
Within the integrated multinational tier, Teva Pharmaceutical Industries and Viatris exemplify backward integration strategies spanning active pharmaceutical ingredient synthesis through finished dosage distribution. Sun Pharmaceutical Industries occupies a position among complex formulation specialists targeting neurology and oncology categories with higher technical barriers. These three anchors demonstrate how geographic diversification of manufacturing assets interacts with FDA inspection clearance timelines to determine competitive access.
| Leading Market Players |
|---|
| Teva Pharmaceutical Industries |
| Viatris |
| Sandoz |
| Sun Pharmaceutical Industries |
| Lupin |
| Amneal Pharmaceuticals |
| Aurobindo Pharma |
| Dr. Reddy's Laboratories |
| Apotex |
| Others |
Cost & Logistics Intelligence
Continuous manufacturing scale advantages in cardiovascular tablets compress unit costs by 30-40 percent against batch operations, concentrating supply authority among large-scale adopters while forcing mid-tier manufacturers toward price floors in commodity oral solids. This scale bifurcation simultaneously elevates premium positioning for complex injectables where sterile processing barriers protect margins.
Pricing Analysis
Certification level creates the primary spread across FDA-grade, pre-ANDA, and commodity-tier supply. Three-tier pricing structure across premium, standard, and economy levels reflects ANDA approval status, bioequivalence validation investment, and hospital formulary security guarantees. Price erosion runs through tablet categories as continuous direct compression technology diffuses. Retail pharmacy chains exhibit highest price sensitivity; integrated delivery networks prioritize shortage protection over per-unit cost.
Supply Chain Analysis
API sourcing from India and China underwrites finished dosage production economics for US-based manufacturers. Active pharmaceutical ingredient supply draws from Indian chemical synthesis clusters and Chinese intermediate processing hubs, with tariff exposure on customs delays constraining just-in-time inventory models. Distribution runs through Atlanta and Miami specialty pharmacy concentration for temperature-sensitive biologics, while hospital pharmacies control formulary gatekeeping for injectable portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in adherence monitoring and 340B program administration expand faster than commodity drug manufacturing, rewarding manufacturers who bundle digital therapeutic adjacencies with generic delivery.
For Market Incumbents: Consolidate hospital channel relationships through multi-year injectable supply agreements with stockout penalty clauses. Expand captive API production to offset import dependence risks from Indian and Chinese suppliers. ANDA portfolio depth remains the critical lever against FDA inspection backlog delays.
For New Entrants and Emerging Players: Differentiate on neurology complex formulations where controlled-release antiepileptics and Parkinson's therapies face underserved margin pools. Target southeastern integrated delivery networks around Atlanta and Miami for specialty pharmacy hub access. Lead with physiologically based pharmacokinetic modeling capabilities to preempt FDA bioequivalence queries.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors continuous manufacturing technology licensors and PAT implementation specialists. Five-to-ten year viability hinges on regulatory science capabilities for complex generic categories. Watch FDA inspection clearance timelines as the inflection signal for competitive access windows.
| Strategic Initiative | Industry Significance |
|---|---|
| ANDA Portfolio Accumulation | FDA backlog creates selective entry windows for pre-approved abbreviated applications. |
| Continuous Manufacturing Licensing | PAT technology adopters achieve 30-40 percent unit cost compression in oral solids. |
| Hospital System Partnership | Integrated delivery networks demand single-source accountability for shortage-prone injectables. |
| Backward Integration into API | Captive synthesis reduces exposure to Indian and Chinese customs friction. |
| 340B Contract Pharmacy Expansion | Federal drug pricing program channels outpatient volume through hospital-affiliated dispensaries. |
Research Approach
Initial hypotheses were tested against primary input from formulary directors, hospital procurement managers, regulatory affairs leads, and ANDA submission specialists and refined through secondary validation across FDA ANDA filings, CMS Medicare reimbursement databases, hospital GPO contracts, and clinical endpoint study registries. Bottom-up volume modeling triangulated against top-down expenditure analysis.
Variance decomposition across the projection horizon isolates volume drivers from price effects within each segmentation dimension: product type, end user, distribution channel, and therapy area complexity tier. CAGRs derived from regression analysis of historical approval timelines, patent expiry schedules, and formulary adoption curves. Forecast inputs incorporate FDA inspection capacity assumptions and IRA Medicare negotiation category expansions.
The analysis sits within stated boundaries; outcomes outside stable FDA funding, continued IRA implementation, and intact US-India-China trade corridors would require recalibration. Model assumptions reflect ANDA approval velocity, API import reliability, and hospital procurement consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
HIV Drugs Market
Biopharmaceuticals
France Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Asia-Pacific Biologics Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
NF-KB Inhibitors Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Bacterial Conjunctivitis Drugs Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Insulin Market