
 Glucagon Injectable Market | 2026-2036
Glucagon Injectable Market Size, Share, and Industry Trends Forecast 2026-2036
Glucagon Injectable Market Foresight
Pre-filled syringe-grade formulation quality is unwinding traditional barriers to outpatient adoption. Amphastar Pharmaceuticals leverages vertical integration across active pharmaceutical ingredient synthesis to sustain cost competitiveness in emergency kits. Xeris Biopharma Holdings anchors its position through proprietary non-aqueous formulation technology that eliminates reconstitution steps. Novo Nordisk A/S dominates recombinant peptide manufacturing scale, extending supply security across hospital networks worldwide.
Glucagon injectable refers to parenteral formulations of the polypeptide hormone (29 amino acids, molecular weight approximately 3,485 Da) administered to counteract severe hypoglycemia by stimulating hepatic glycogenolysis and raising blood glucose within minutes. The primary commercial purpose centers on emergency reversal of insulin-induced hypoglycemic episodes in diabetic patients, with secondary applications in radiology for gastrointestinal motility inhibition. Ready-to-use injection formats command expanding share as home care settings prioritize elimination of reconstitution errors, while lyophilized powder formulations retain entrenched positions in hospital crash carts where cold-chain reliability varies. Emergency kits represent the mature revenue base, though nasal powder delivery is capturing fastest growth among patient populations with needle aversion or limited dexterity.
FDA biologics licensing requirements and EMA good manufacturing practice standards for peptide injectables shape product development timelines, forcing manufacturers to validate stability profiles under stress temperature conditions before market authorization. The US Pharmacopeia potency assay specifications and ISO 11608 needle-based injection system standards further constrain design freedom, particularly for multi-dose vial configurations. Stakeholders must weigh formulation innovation investments against the regulatory burden of demonstrating bioequivalence for novel delivery mechanisms.
Market Dynamics
FDA's streamlined biologics licensing for emergency-use injectables is compressing development timelines while simultaneously raising the bar for stability validation, forcing manufacturers to reallocate R&D spend toward ready-to-use formulations.
Growth Catalysts
- Home Care Self-Administration:Patients managing Type 1 diabetes outside clinical settings drive demand for needle-free and pre-filled delivery formats. Reimbursement pathways in the United States now cover emergency glucagon kits for home use.
- REACH Peptide Manufacturing Standards:European harmonization of good manufacturing practice for parenteral biologics reduces cross-border regulatory friction. Manufacturers gain faster market access across EU member states.
- Non-Aqueous Formulation Chemistry:Shelf-stable liquid glucagon eliminates cold-chain dependency. Rural hospitals and emergency medical services adopt these formulations where refrigeration infrastructure is unreliable.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Recombinant peptide synthesis capacity clusters among a handful of contract manufacturers. Supply disruption risk elevates procurement costs for finished dose producers.
- US Pharmacopeia Potency Assay Burden:Batch release testing requirements extend quality control timelines. Small manufacturers face disproportionate compliance overhead relative to production volume.
- Nasal Powder Substitution:Needle-free intranasal delivery formats capture patients with needle phobia or limited manual dexterity. Injectable volumes face demand compression in pediatric and geriatric segments.
Strategic Opportunities
- India Outpatient Expansion:Rising diabetes prevalence and government-funded universal health coverage create addressable demand for affordable emergency kits. Local manufacturing incentives under PLI scheme reduce import dependency.
- Radiology Motility Inhibition:Off-label procedural applications in gastrointestinal imaging represent untapped hospital pharmacy budgets. Contrast-enhanced procedures require glucagon inventory standardization.
- ISO 11608 Injection System Convergence:Standardized needle-based delivery platforms enable modular device development. Manufacturers leverage common engineering specifications across diabetes and emergency medicine portfolios.
Industry Challenges
- Peptide Formulation Scientist Scarcity:Specialized expertise in non-aqueous stability modeling commands premium compensation. Recruitment pipelines fail to match biologics sector expansion.
- Legacy Lyophilization Asset Stranding:Hospital crash cart procurement cycles lag behind ready-to-use adoption curves. Manufacturers maintain dual production lines for incompatible formulation formats.
- Biologics License Application Timelines:FDA stress-temperature validation requirements extend pre-market authorization phases. Working capital intensity constrains mid-tier development pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucagon Injectable Market |
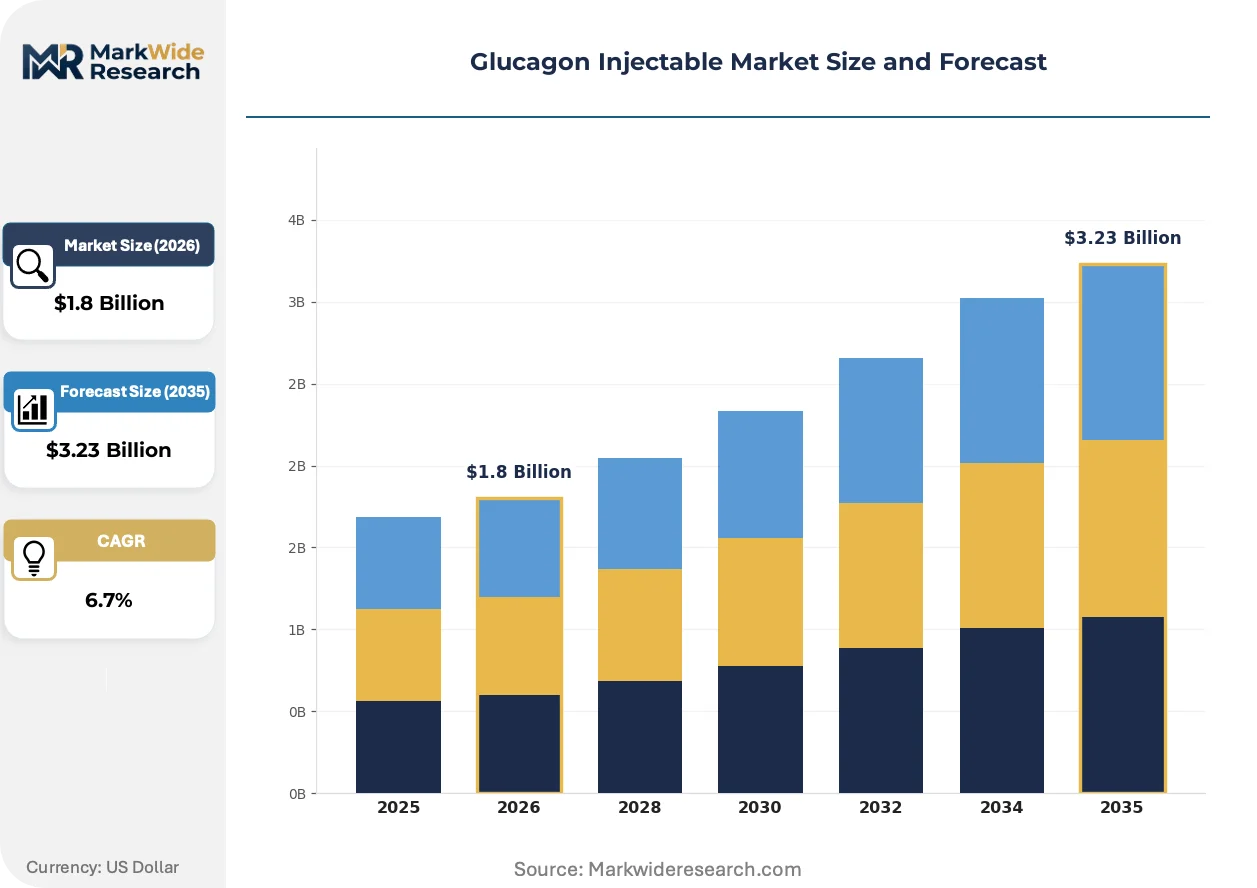
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emergency Kits, Nasal Powder, Ready-to-Use Injection, Reconstituted Injection Application: Hypoglycemia Treatment, Beta-Blocker Overdose, Radiology Procedures, Diagnostic Tests End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Home Care Settings Formulation: Lyophilized Powder, Liquid Solution, Pre-Filled Syringes, Multi-Dose Vials |
| Companies Covered | Amphastar Pharmaceuticals, Inc, Xeris Biopharma Holdings, Inc, Novo Nordisk A/S, Zealand Pharma A/S, Fresenius SE & Co. KGaA, Eli Lilly and Company, ILS Inc., United Biotech (P) Limited, Taj Pharmaceuticals Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucagon Injectable Market Shifts & Advancements
Formulation chemistry and delivery mechanism convergence are collapsing the traditional trade-off between shelf stability and injection convenience. Regulatory harmonization efforts are simultaneously compressing geographic expansion timelines.
Ready-to-use liquid glucagon is supplanting lyophilized powder formats in outpatient settings. Home care patients and emergency medical technicians adopt pre-filled syringes and auto-injectors to eliminate reconstitution errors. This shift is compressing the addressable market for traditional vial-and-diluent kits while expanding total patient access.
EMA good manufacturing practice harmonization for peptide parenterals reduces redundant facility inspections across EU member states. Manufacturers gain mutual recognition of batch release certifications. Hospital networks in Germany, France, and Italy accelerate supplier qualification for centralized procurement contracts.
Direct-to-patient distribution models bypass wholesale pharmacy intermediaries for emergency kit refills. Specialty pharmacies manage cold-chain logistics and patient education. This channel shift is most visible in United States Medicare Part D coverage, where mail-order fulfillment reduces retail pharmacy stockout risk for chronic hypoglycemia patients.
Glucagon Injectable Market Segmentation
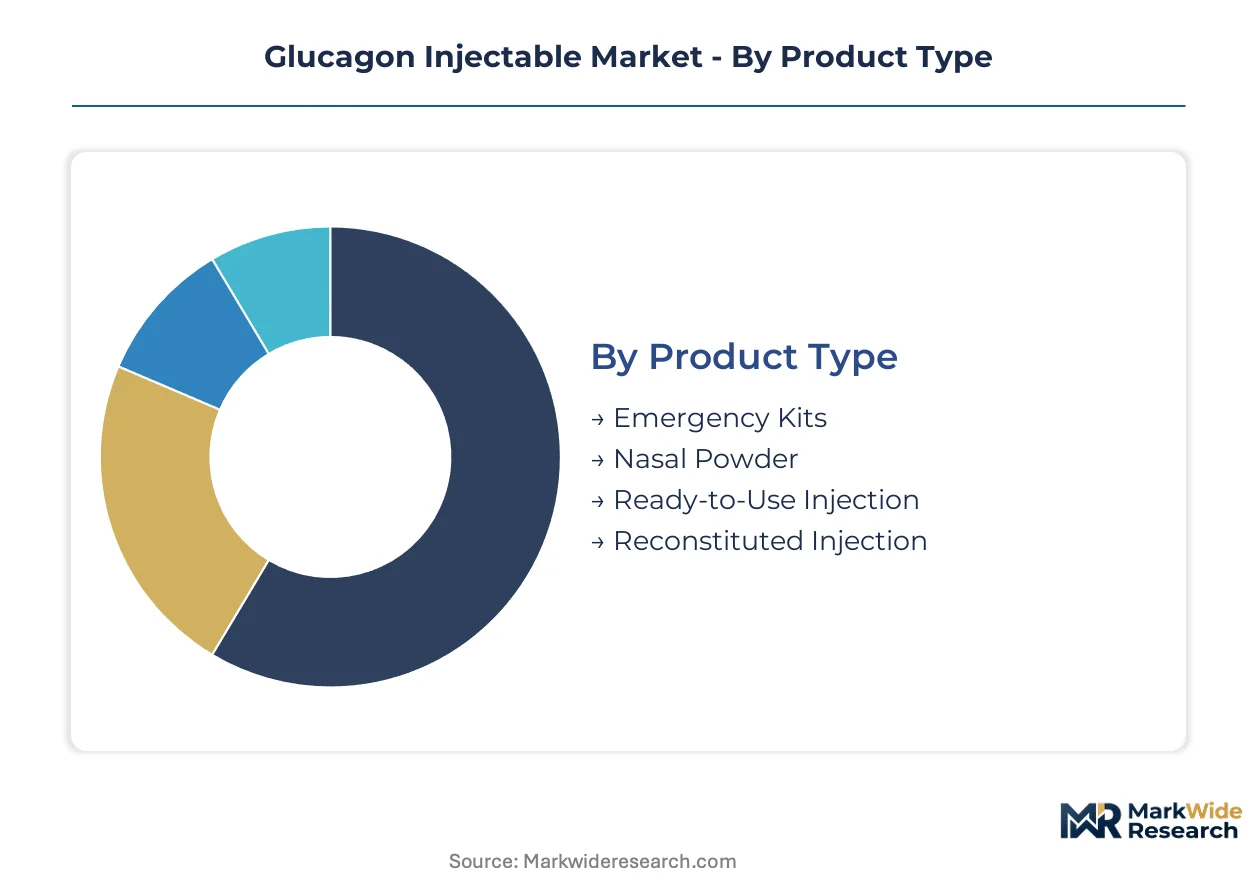
Glucagon injectable segmentation reveals divergent adoption patterns across clinical and non-clinical environments. Product format preferences split sharply between institutional procurement cycles and patient-directed purchasing decisions.
Product Type:
Domestic demand concentrates in ready-to-use formats, while export markets still absorb substantial lyophilized kit volumes.
- Ready-to-Use Injection:Liquid-stable formulations eliminate reconstitution steps. Home care patients in the United States and emergency medical technicians in rural Germany adopt these formats where error reduction outweighs unit cost premiums.
- Emergency Kits:Traditional vial-and-diluent combinations retain entrenched hospital positions. United States crash cart standardization and developing-market procurement budgets sustain manufacturing scale despite outpatient displacement.
- Nasal Powder:Needle-free delivery addresses pediatric and geriatric needle aversion. United Kingdom and Scandinavian reimbursement pathways now cover intranasal alternatives for Type 1 diabetes patients.
- Reconstituted Injection:Lyophilized powder requiring diluent persists in cost-sensitive institutional contracts. Indian and Brazilian hospital tenders favor these formats under government procurement ceilings.
Emergency Kits hold the largest share; momentum sits with Ready-to-Use Injection.
Application:
Clinical utility spans emergency medicine through procedural diagnostics, with reimbursement intensity varying by acuity level.
- Hypoglycemia Treatment:Emergency reversal of insulin-induced episodes constitutes the core commercial indication. United States Medicare Part D and commercial payers classify glucagon as essential benefit, driving refill frequency among insulin-dependent populations.
- Radiology Procedures:Gastrointestinal motility inhibition for contrast-enhanced imaging represents a secondary hospital pharmacy budget. German and French radiology departments maintain standing orders for procedural inventory.
- Beta-Blocker Overdose:Cardiac emergency applications command premium pricing in critical care settings. United States emergency department formularies stock glucagon for calcium channel antagonist reversal protocols.
- Diagnostic Tests:Stimulation protocols for growth hormone deficiency and other endocrine assessments utilize controlled glucagon doses. Specialty endocrinology clinics in Japan and South Korea drive demand for precise-dose vial configurations.
Hypoglycemia Treatment anchors revenue; Radiology Procedures are climbing fastest.
End User:
Procurement authority shifts from centralized pharmacy committees toward individual patient purchasing as self-administration expands.
- Home Care Settings:Patient-directed purchasing of emergency kits accelerates with diabetes self-management education. United States mail-order specialty pharmacies now handle cold-chain logistics and auto-injector training.
- Hospitals:Centralized pharmacy and crash cart standardization sustain bulk purchasing power. Joint Commission accreditation requirements in the United States mandate glucagon availability in emergency departments and intensive care units.
- Ambulatory Surgical Centers:Procedural sedation protocols require on-site hypoglycemia reversal capacity. Medicare-certified ASCs in the United States maintain emergency medication formularies including glucagon.
- Specialty Clinics:Endocrinology and diabetes centers prescribe emergency kits during patient education sessions. United Kingdom NHS specialist referral pathways incorporate glucagon dispensing.
Hospitals retain the largest share; Home Care Settings gain share fastest.
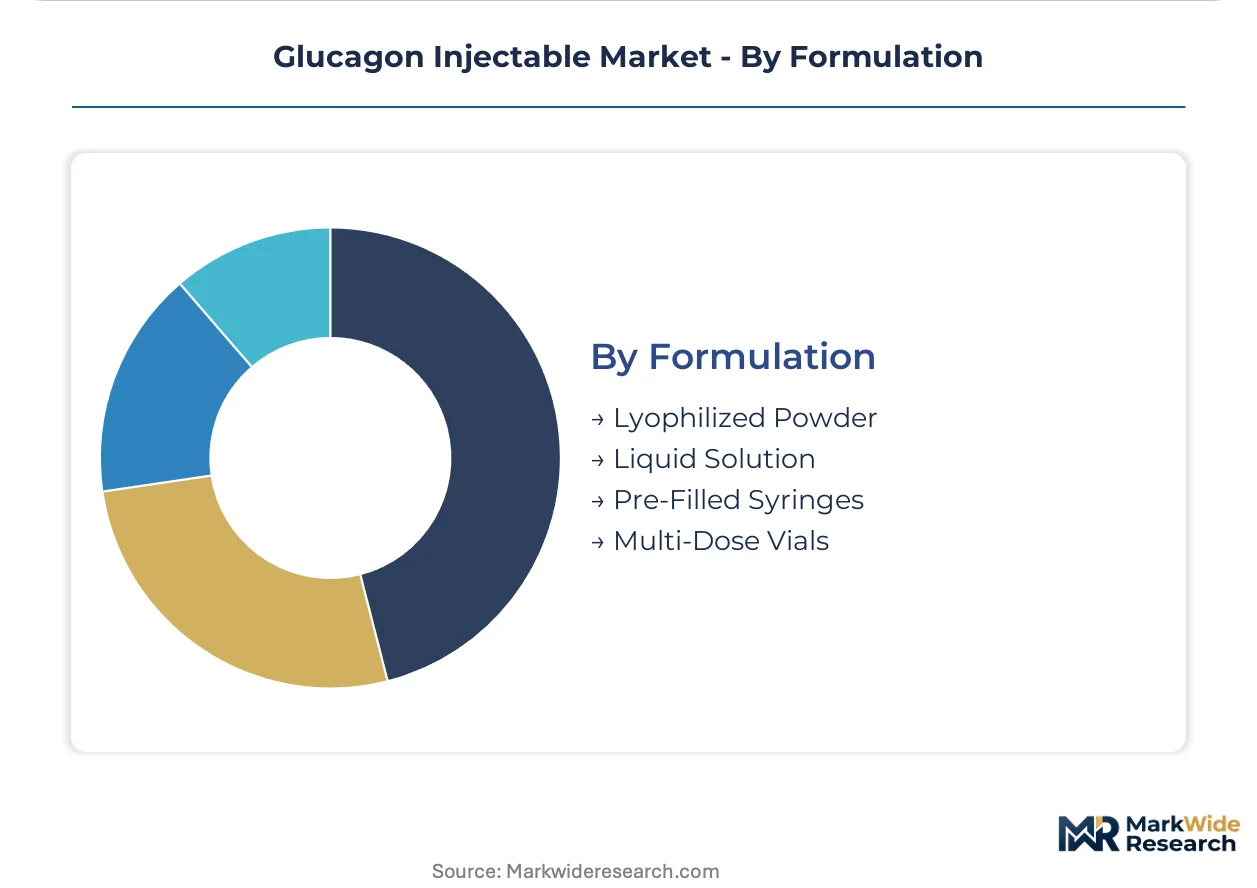
Formulation:
Stability chemistry and container closure systems determine distribution economics and storage infrastructure requirements.
- Liquid Solution:Non-aqueous chemistry enables ambient temperature stability without reconstitution. Xeris Biopharma Holdings and similar developers target emergency medical services and military medical kits where refrigeration fails.
- Lyophilized Powder:Freeze-dried peptide requires diluent reconstitution before injection. Hospital networks in Italy and Spain retain these formats for extended shelf life in variable storage conditions.
- Pre-Filled Syringes:Single-dose ready-to-inject units reduce dosing error risk. United States patient preference studies show strong adoption among caregivers managing pediatric Type 1 diabetes.
- Multi-Dose Vials:Bulk packaging serves high-throughput hospital pharmacies. Cost-per-dose economics favor these configurations in United States health system centralized distribution models.
Lyophilized Powder dominates current volume; Liquid Solution shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peptide synthesis capacity clusters among contract manufacturers in the United States, Germany, and India, while formulation finishing and packaging operations distribute across secondary markets. Regulatory divergence between FDA stress-temperature validation requirements and EMA good manufacturing practice harmonization creates asynchronous market entry timelines. Cold-chain infrastructure reliability varies sharply, driving adoption of non-aqueous liquid formulations in peripheral regions.
United States
Type 1 diabetes prevalence and Medicare Part D reimbursement for emergency kits sustain patient-directed purchasing volumes. FDA streamlined biologics licensing for emergency-use injectables compresses development timelines while raising stability validation requirements. Specialty pharmacies in California and Massachusetts manage direct-to-patient distribution and auto-injector training programs.
Germany
Hospital crash cart standardization and radiology department procedural protocols maintain institutional demand for multi-dose vial configurations. EMA good manufacturing practice harmonization enables mutual recognition of batch release certifications across EU member states. Pharmaceutical manufacturing clusters in North Rhine-Westphalia and Bavaria concentrate peptide synthesis and fill-finish operations.
India
Rising diabetes prevalence and government-funded universal health coverage expand addressable demand for affordable emergency kits. Production-Linked Incentive scheme reduces import dependency for active pharmaceutical ingredients. Contract manufacturing organizations in Maharashtra and Gujarat scale recombinant peptide synthesis capacity for export markets.
United Kingdom
NHS specialist referral pathways incorporate glucagon dispensing during patient education sessions for Type 1 diabetes management. Reimbursement coverage for intranasal alternatives addresses pediatric and geriatric needle aversion segments. London and Southeast England anchor distribution logistics for Northern European markets.
Japan
Specialty endocrinology clinics drive demand for precise-dose vial configurations in diagnostic stimulation protocols. PMDA stability requirements for peptide parenterals align with USP potency assay specifications, facilitating parallel regulatory submissions. Kanto region pharmaceutical manufacturing infrastructure supports regional supply security.
Glucagon Injectable Market Competitive Landscape
Concentration sits with vertically integrated peptide manufacturers and formulation technology specialists. The competitive structure tiers across recombinant manufacturing scale players, non-aqueous chemistry innovators, and regional contract manufacturers. Dominant moves include strategic partnerships for distribution reach and technology licensing for shelf-stable liquid formulations.
Among recombinant peptide manufacturers, Novo Nordisk A/S and Eli Lilly and Company occupy positions anchored by manufacturing scale and diabetes therapeutic portfolios. Xeris Biopharma Holdings exemplifies the formulation innovation archetype through proprietary non-aqueous chemistry. Amphastar Pharmaceuticals represents vertical integration from active pharmaceutical ingredient synthesis through finished dose production.
| Leading Market Players |
|---|
| Amphastar Pharmaceuticals, Inc |
| Xeris Biopharma Holdings, Inc |
| Novo Nordisk A/S |
| Zealand Pharma A/S |
| Fresenius SE & Co. KGaA |
| Eli Lilly and Company |
| ILS Inc. |
| United Biotech (P) Limited |
| Taj Pharmaceuticals Limited |
| Others |
Supply & Pricing Matrix
Recombinant peptide synthesis capacity utilization at contract manufacturers in the United States, Germany, and India directly determines price floors for finished glucagon injectables. Manufacturers with captive active pharmaceutical ingredient production command margin buffers that pure-play formulators cannot match. FDA stability validation requirements and cold-chain logistics costs further stratify pricing tiers across institutional and outpatient segments.
Pricing Analysis
US Pharmacopeia potency assay specifications dictate the pricing tier structure across glucagon injectable formats. Three-tier pricing structure across premium, standard, and economy levels separates ready-to-use liquid formulations from lyophilized emergency kits and reconstituted powder alternatives. Price differentiation rests on cold-chain dependency and reconstitution complexity. Cost compression in economy-tier lyophilized formats is intensifying because Indian and Brazilian government procurement ceilings cap reimbursement ceilings. Home care patients in the United States show lowest price sensitivity; developing-market hospital tenders exhibit highest.
Supply Chain Analysis
Strait of Hormuz transit vulnerability underwrites shipping route diversification for Middle East-bound glucagon shipments. Active pharmaceutical ingredient production concentrates in the United States, India, and China; formulation finishing distributes across Germany, Italy, and Japan. Recombinant peptide synthesis draws from microbial fermentation substrates, chromatography resins, and sterile packaging components. Single-source vulnerability sits with specialized non-aqueous formulation chemists. Distribution runs through hospital GPO contracts in the United States, wholesale pharmacy networks in Europe, and direct-to-patient specialty pharmacies for Medicare Part D enrollees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated United States hospital GPOs and Medicare Part D plan sponsors. Fragmentation among outpatient diabetes patients is giving way to centralized specialty pharmacy purchasing.
For Market Incumbents: Compound manufacturing scale advantages by securing multi-year peptide synthesis contracts before REACH compliance deadlines strain European capacity. Defend against nasal powder substitution by accelerating ready-to-use liquid approvals through FDA streamlined pathways. Prioritize backward integration into recombinant microbial strain development to reduce API procurement exposure. For New Entrants and Emerging Players: Anchor in Indian outpatient expansion where Production-Linked Incentive scheme subsidies offset capital intensity. Radiology motility inhibition applications represent the most penetrable hospital segment given entrenched incumbents' diabetes-centric focus. Pursue direct-to-patient distribution partnerships with mail-order specialty pharmacies to bypass wholesale intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulation chemistry specialists with proprietary non-aqueous stability platforms over commodity lyophilization asset operators. Long-term viability across the analysis window hinges on shelf-stable liquid portfolios displacing powder formats. Target acquisition archetype: mid-tier developers with FDA biologics license applications pending. Signal to watch: FDA approval velocity for ready-to-use emergency injectables as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Biologics License Application | Streamlined emergency-use pathway accelerates ready-to-use formulation market entry. |
| Non-Aqueous Formulation Licensing | Proprietary shelf-stable chemistry eliminates cold-chain dependency for rural deployment. |
| Hospital GPO Contracting | Joint Commission mandates sustain institutional purchasing volume for crash cart standardization. |
| Specialty Pharmacy Partnership | Medicare Part D mail-order fulfillment reduces retail stockout risk for chronic patients. |
| Peptide Manufacturing Scale-Up | REACH GMP harmonization enables faster EU batch release certification across member states. |
Research Methodology
Desk research of FDA biologics licensing files, EMA good manufacturing practice inspection reports, and ClinicalTrials.gov protocols preceded structured interviews with regulatory affairs leads, hospital formulary directors, GPO contracts managers, and peptide formulation scientists. Secondary validation drew from USP potency assay monographs, ISO 11608 injection system standards, and CMS Medicare Part D utilization data. Bottom-up patient population modeling and top-down pharmaceutical expenditure triangulation anchored volume estimates.
Variance decomposition across product type, application, end user, formulation chemistry, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macro healthcare expenditure trends. Forecast inputs included diabetes prevalence trajectories by country, reimbursement pathway expansion timelines, and peptide manufacturing capacity utilization rates.
Material uncertainties — FDA stress-temperature validation requirement changes, nasal powder substitution acceleration, and API synthesis capacity disruptions — sit outside the modeled envelope. Forecasts reflect assumptions documented in segmentation adoption curves and regulatory harmonization schedules. Practitioners should keep alternative scenarios live as EMA-FDA convergence timelines and Indian PLI scheme implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
EPO Biomarkers Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Theranostics Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Interleukin 1 Beta (IL-1β) ELISA Kit Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Macrolide Drugs Market