
 Latin America G-CSF/ PEG-G-CSF Market | 2026-2036
Latin America G-CSF/ PEG-G-CSF Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America G-CSF/ PEG-G-CSF Market Foresight
Oncology service lines across Latin American hospital networks are pivoting toward outpatient chemotherapy models that require robust neutropenia prophylaxis. Amgen leverages its pioneering filgrastim franchise to sustain brand loyalty among hematology-oncology specialists across Mexico and Brazil. Sandoz competes aggressively on biosimilar G-CSF pricing, while Fresenius Kabi anchors hospital pharmacy contracts through integrated oncology supportive care portfolios.
G-CSF and PEG-G-CSF constitute recombinant granulocyte colony-stimulating factors produced via E. coli or mammalian cell culture, with PEGylated variants achieving prolonged serum half-lives of 15-80 hours versus 3.5 hours for native filgrastim. These biologics stimulate neutrophil proliferation and maturation to prevent chemotherapy-induced febrile neutropenia. The biosimilars segment is expanding fastest as ANVISA and COFEPRIS accelerate abbreviated approval frameworks, while hospital pharmacies capture the dominant margin pool through centralized procurement of high-value oncology supportive care products.
ANVISA in Brazil, COFEPRIS in Mexico, and INVIMA in Colombia enforce biosimilar interchangeability standards and post-market pharmacovigilance that shape product substitution policies and physician confidence. REACH-aligned impurity profiling requirements for PEGylation reagents create technical barriers for manufacturers sourcing raw materials through European supply chains. Stakeholders must monitor how national health technology assessment bodies across the region calibrate cost-effectiveness thresholds for originator versus biosimilar PEG-G-CSF in public reimbursement formularies.
Market Dynamics
Brazil's ANVISA biosimilar interchangeability rulings are compressing originator pricing power while expanding hospital formulary access across São Paulo's integrated cancer networks.
Growth Catalysts
- Outpatient chemotherapy expansion:São Paulo and Rio de Janeiro metropolitan hospitals are shifting infusion services from inpatient wards to ambulatory centers, mandating prophylactic PEG-G-CSF protocols that reduce febrile neutropenia admissions.
- ANVISA abbreviated pathways:Brazil's streamlined biosimilar approval framework is slashing time-to-market for filgrastim alternatives, forcing originator price concessions that expand patient access in public reimbursement formularies.
- PEGylation chemistry advances:Improved site-specific conjugation methods are extending serum half-lives toward 80-hour thresholds, enabling single-dose per chemotherapy cycle administration that reduces nursing burden in high-volume oncology clinics.
Market Restraints
- European raw material concentration:REACH-aligned impurity specifications for PEGylation reagents lock Latin American manufacturers into German and Swiss chemical supplier networks, exposing production costs to euro-denominated volatility and customs delays.
- Originator patent thickets:Amgen's residual formulation patents in Mexico and Brazil create legal friction that delays biosimilar substitution even after COFEPRIS and ANVISA grant marketing authorization.
- Cold chain infrastructure gaps:Temperature-controlled distribution from Buenos Aires or Mexico City to secondary cities in Argentina's interior or Mexico's southern states requires capital investment that compresses distributor margins on lower-volume SKUs.
Strategic Opportunities
- Colombian reimbursement expansion:INVIMA's 2024 biosimilar interchangeability guidelines and the Ministry of Health's planned inclusion of PEG-G-CSF in the POS benefit package will open access for Bogotá and Medellín's growing oncology patient populations.
- Home administration protocols:Subcutaneous PEG-G-CSF delivery is enabling home-based neutropenia prophylaxis programs that reduce hospital occupancy costs and align with Chile's AUGE guaranteed access timelines for chemotherapy supportive care.
- COFEPRIS-ANVISA regulatory harmonization:Emerging mutual recognition agreements for biologics manufacturing inspections will allow Mexican producers to supply Brazilian hospital networks without redundant facility audits.
Industry Challenges
- Pharmacovigilance capacity constraints:Post-market adverse event reporting requirements for biologics under ANVISA's RDC 55/2010 demand specialized safety teams that mid-size distributors struggle to staff in Brazil's competitive labor market.
- Hospital formulary committee dynamics:Oncology pharmacy and therapeutics committees in Mexican ISSSTE and IMSS facilities apply inconsistent biosimilar substitution criteria, creating unpredictable demand swings that complicate inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America G-CSF/ PEG-G-CSF Market |
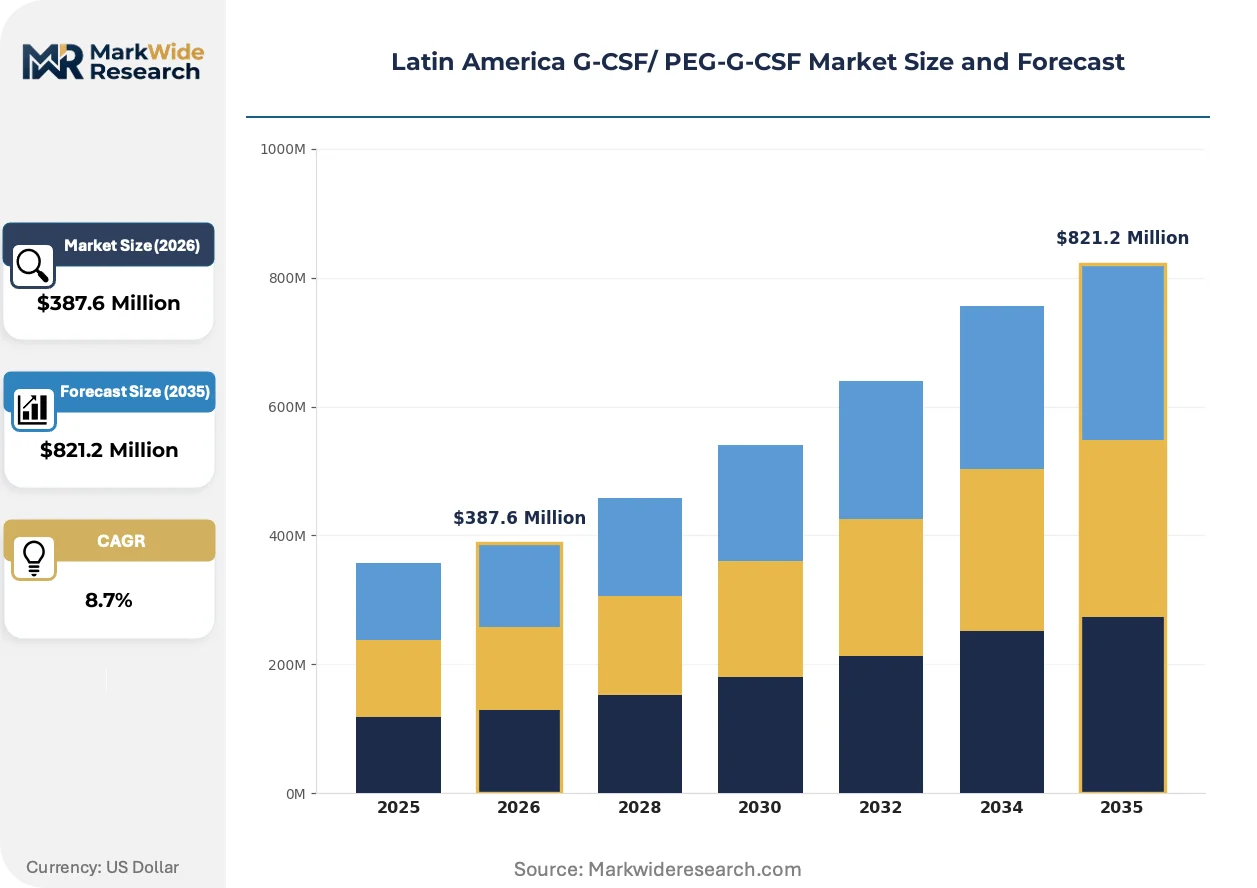
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $821.2 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: G-CSF, PEG-G-CSF, Biosimilars, Reference Products End User: Hospitals, Clinics, Homecare, Research Institutes Administration Route: Subcutaneous, Intravenous, Intramuscular, Oral Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Wholesalers |
| Companies Covered | Amgen, Fresenius Kabi, Sandoz, Pfizer, Biocon, Roche, Viatris, Teva Pharmaceutical Industries, CSPC, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America G-CSF/ PEG-G-CSF Market Shifts & Advancements
PEGylated long-acting formulations are restructuring competitive positioning across Latin American oncology supportive care, compressing the clinical and economic rationale for daily filgrastim administration.
Site-specific PEGylation chemistry is overtaking random lysine conjugation as the dominant manufacturing approach for new market entrants. Argentine and Brazilian contract manufacturers are adopting enzymatic conjugation platforms that yield more homogeneous drug-to-polymer ratios. This precision is overtaking legacy production methods in hospital pharmacy tender evaluations, where batch consistency metrics determine formulary placement.
ANVISA's RDC 205/2017 biosimilar interchangeability standards are forcing originator companies to demonstrate clinical equivalence through pharmacokinetic bridging studies. Brazilian public procurement bodies now require interchangeability certification for PEG-G-CSF inclusion in SUS hospital formularies. The policy shift is accelerating physician confidence in biosimilar switching protocols across Minas Gerais and Rio Grande do Sul state hospital networks.
Centralized hospital procurement consortia are consolidating purchasing power across multi-hospital systems in Mexico and Brazil. Group purchasing organizations in São Paulo's Albert Einstein and Sírio-Libanês networks now negotiate PEG-G-CSF contracts covering 40-plus affiliated facilities. This concentration is displacing fragmented single-hospital purchasing that previously allowed originator field forces to extract price premiums through relationship-based contracting.
Latin America G-CSF/ PEG-G-CSF Market Segmentation
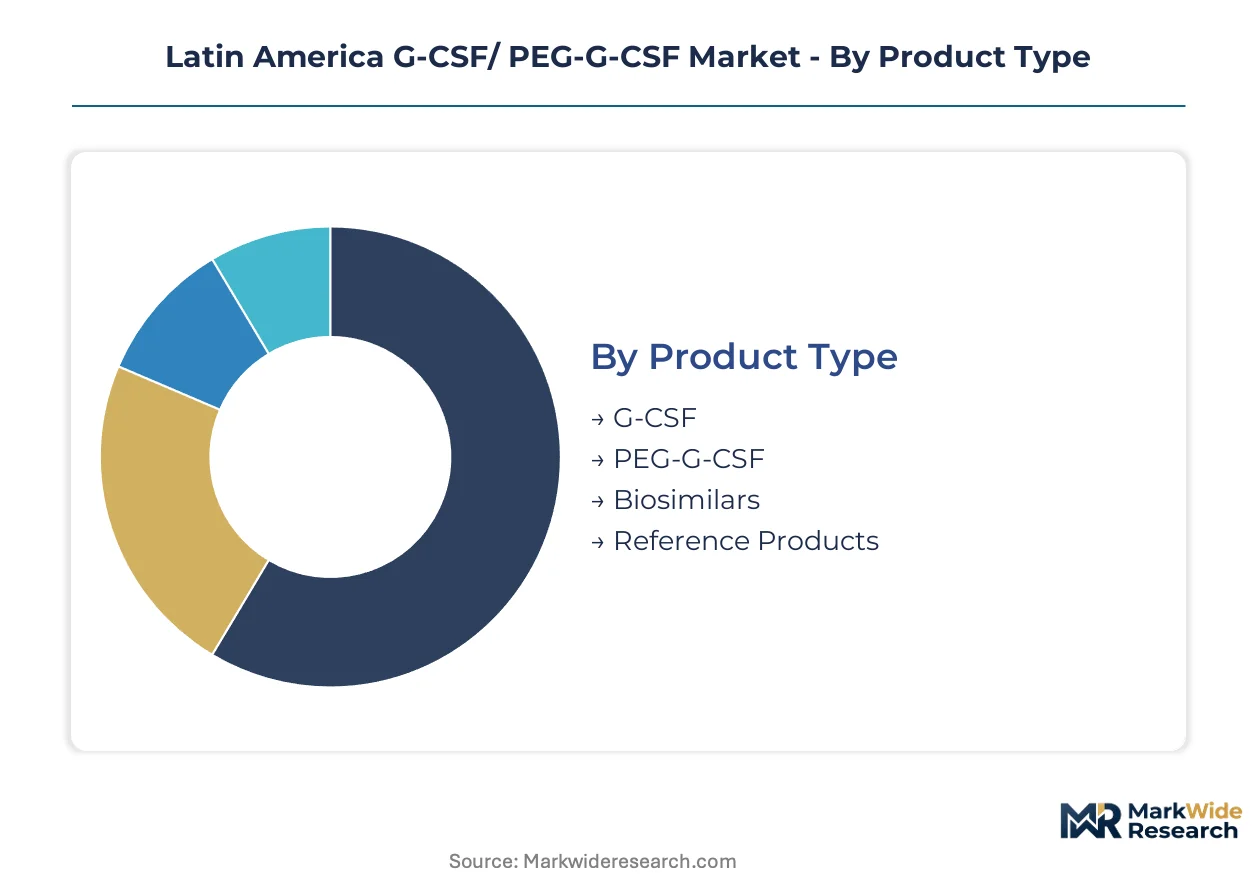
Product form, delivery setting, and procurement channel each impose distinct technical and commercial requirements on G-CSF suppliers across Latin American oncology networks. Understanding these segment boundaries clarifies where formulation investments yield margin protection versus where price competition dominates purchasing decisions.
Product Type:
Hospital pharmacy committees calibrate formularies around half-life duration, immunogenicity profiles, and interchangeability certification from national regulators.
- PEG-G-CSF:Site-specific PEGylation extends serum half-life to 15-80 hours, enabling single-dose prophylaxis per chemotherapy cycle. São Paulo's Albert Einstein and Sírio-Libanês networks mandate PEG-G-CSF for ambulatory infusion protocols to minimize febrile neutropenia readmissions.
- Biosimilars:ANVISA's abbreviated approval pathways and interchangeability rulings under RDC 205/2017 compress time-to-market for filgrastim alternatives. Brazilian SUS formularies increasingly require biosimilar certification, forcing originator price concessions in public procurement.
- G-CSF:Native filgrastim retains niche use in inpatient settings requiring dose titration flexibility.
- Reference Products:Originator formulations sustain loyalty among private-pay oncology specialists in Mexico City and Rio de Janeiro where reimbursement rates preserve premium pricing.
Volume sits with biosimilars in Brazilian public networks; growth tilts toward PEG-G-CSF as outpatient chemotherapy expands across metropolitan hospital systems.
End User:
Care setting determines cold chain requirements, nursing labor allocation, and reimbursement coding complexity for neutropenia prophylaxis.
- Hospitals:Integrated cancer centers in São Paulo, Rio de Janeiro, and Mexico City concentrate chemotherapy patient volumes and capture centralized procurement contracts for supportive care biologics. These facilities anchor demand for long-acting formulations that reduce bed occupancy.
- Clinics:Ambulatory oncology clinics across Brazil's Minas Gerais and Rio Grande do Sul states are shifting infusion services from inpatient wards, creating demand for subcutaneous PEG-G-CSF protocols that minimize nursing burden.
- Homecare:Subcutaneous self-administration programs are emerging in Chile's AUGE-covered populations and Colombian private insurance networks.
- Research Institutes:Academic medical centers in Buenos Aires and Mexico City conduct pharmacokinetic bridging studies for biosimilar interchangeability certification.
Procurement concentrates with hospitals; expansion tilts fastest toward homecare as reimbursement frameworks adapt to outpatient cost containment priorities.
Administration Route:
Delivery mechanism shapes patient compliance, nursing resource allocation, and formulary placement within hospital pharmacy and therapeutics committees.
- Subcutaneous:Preferred route for PEG-G-CSF enables home administration and reduces clinic visit frequency. Brazilian and Mexican hospital networks increasingly mandate subcutaneous protocols for ambulatory chemotherapy patients.
- Intravenous:Retains use in inpatient febrile neutropenia rescue protocols where rapid neutrophil count recovery is critical.
- Intramuscular:Limited application in specific institutional protocols requiring alternative delivery.
- Oral:Not commercially available for G-CSF/PEG-G-CSF; listed as theoretical route in regulatory filings.
Clinical practice concentrates with subcutaneous delivery; no meaningful expansion trajectory exists for alternative routes given biologic stability requirements.
Distribution Channel:
Channel selection reflects product value density, cold chain infrastructure, and hospital purchasing consolidation trends across Latin American markets.
- Hospital Pharmacies:Centralized procurement consortia across multi-hospital systems in São Paulo and Mexico City negotiate PEG-G-CSF contracts covering 40-plus affiliated facilities. This concentration displaces fragmented single-hospital purchasing.
- Wholesalers:Temperature-controlled distribution from Buenos Aires or Mexico City to secondary cities in Argentina's interior or Mexico's southern states requires capital investment that compresses margins on lower-volume SKUs.
- Retail Pharmacies:Limited role given prescription restrictions and cold chain requirements for biologics.
- Online Pharmacies:Emerging channel for patient support programs and refill coordination in urban Brazilian markets with established logistics networks.
Procurement volume sits with hospital pharmacies; channel expansion tilts toward consolidated wholesaler networks serving multi-state hospital systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone pharmaceutical manufacturing incentives concentrate biologics production infrastructure in Brazil's northern Amazonas state, drawing fill-finish operations for oncology supportive care products serving São Paulo and Rio de Janeiro hospital networks.
Brazil
São Paulo's Albert Einstein and Sírio-Libanês cancer networks anchor PEG-G-CSF procurement through centralized consortia covering 40-plus facilities. ANVISA's RDC 205/2017 interchangeability standards compress originator pricing in SUS public formularies while accelerating biosimilar substitution protocols across Minas Gerais state hospitals.
Mexico
Mexico City metropolitan oncology clinics drive demand for subcutaneous long-acting formulations as IMSS and ISSSTE facilities expand ambulatory chemotherapy services. COFEPRIS abbreviated biosimilar pathways under NOM-257-SSA1-2014 slash regulatory review timelines, enabling faster market entry for filgrastim alternatives in Jalisco and Nuevo León hospital systems.
Argentina
Buenos Aires academic medical centers conduct pharmacokinetic bridging studies for biosimilar interchangeability certification under ANMAT's biologics guidelines. Cold chain distribution from the capital to Córdoba and Rosario secondary markets exposes distributor margins to temperature-controlled logistics investments, compressing profitability on lower-volume SKUs.
Colombia
Bogotá and Medellín oncology patient populations expand access as INVIMA's 2024 biosimilar interchangeability guidelines align with Ministry of Health plans to include PEG-G-CSF in the POS benefit package. Antioquia department hospital networks pilot home administration protocols for subcutaneous delivery under emerging reimbursement frameworks.
Chile
Santiago metropolitan oncology services align PEG-G-CSF protocols with AUGE guaranteed access timelines for chemotherapy supportive care. Valparaíso and Biobío region clinics adopt single-dose per cycle administration to reduce nursing burden in high-volume ambulatory infusion centers.
Latin America G-CSF/ PEG-G-CSF Market Competitive Landscape
Top-tier vendors anchor originator biologics through specialist physician relationships, while mid-tier biosimilar specialists compete on price-access trade-offs in public procurement. Market structure tilts toward consolidation as hospital purchasing consortia concentrate contract negotiation power across multi-facility networks. Three archetypes dominate: multinational originators with legacy filgrastim franchises, biosimilar-focused generics divisions of major pharma, and emerging biotechs with enzymatic PEGylation platforms. Competitive moves center on regulatory interchangeability certification and backward integration into PEGylation reagent supply chains.
Among originator-tier anchors, Amgen occupies a position exemplifying sustained brand loyalty through pioneering filgrastim market presence. Sandoz and Fresenius Kabi represent the biosimilar-competition archetype, with the former emphasizing aggressive pricing postures and the latter anchoring hospital pharmacy contracts through integrated oncology supportive care portfolios. These three entities collectively illustrate the competitive tension between premium originator positioning and cost-driven substitution dynamics reshaping Latin American procurement patterns.
| Leading Market Players |
|---|
| Amgen |
| Fresenius Kabi |
| Sandoz |
| Pfizer |
| Biocon |
| Roche |
| Viatris |
| Teva Pharmaceutical Industries |
| CSPC |
| Others |
Supply & Pricing Matrix
Family-owned Brazilian pharmaceutical distributors with deep ties to São Paulo hospital networks anchor procurement discipline across Latin American oncology supportive care, compressing margins on originator biologics while extracting volume commitments that lock in biosimilar supply security.
Pricing Analysis
Premium pricing for 48-hour lead-time fulfillment separates São Paulo's Albert Einstein network contracts from spot-market inventory clearing in secondary Brazilian states. Three-tier pricing structure across originator, interchangeable biosimilar, and non-interchangeable filgrastim tiers reflects ANVISA certification grade and volume scale. Pricing pressure stems from COFEPRIS-ANVISA regulatory harmonization accelerating Mexican producer entry into Brazilian SUS tenders. Public hospital procurement committees exhibit highest price sensitivity; private-pay oncology specialists in Rio de Janeiro preserve lowest.
Supply Chain Analysis
Dual-sourcing mandates from São Paulo's centralized hospital consortia force qualification of both German and Swiss PEGylation reagent suppliers, insulating fill-finish operations against REACH-aligned customs delays. Manufacturing gravity centers on Brazil's Manaus Free Trade Zone and Mexican Jalisco biotech corridors, with fill-finish capacity drawing from Argentine Buenos Aires academic medical centers. Raw material dependencies rest on euro-denominated PEGylation chemistry, temperature-controlled cold chain infrastructure, and ANVISA-certified reference standards. Single-source vulnerability concentrates in European specialty chemical feedstocks. Distribution runs through hospital pharmacy consortia displacing fragmented wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic PEGylation platform capacity constraints among Brazilian contract manufacturers prop pricing power for originator-tier anchors, constraining biosimilar volume expansion despite regulatory tailwinds.
For Market Incumbents: Hedge against Sandoz-led price erosion by securing backward integration into site-specific PEGylation reagent production, eliminating euro-denominated input volatility. Anchor hospital pharmacy contracts through integrated oncology supportive care portfolios spanning antiemetics and myeloid growth factors, defending formulary position against Fresenius Kabi's bundled procurement tactics. For New Entrants and Emerging Players: Launch via Colombian INVIMA interchangeability certification pathway, exploiting Bogotá and Medellín reimbursement expansion ahead of saturated Brazilian SUS tender competition. Target home administration protocols in Chile's AUGE-covered populations, where subcutaneous delivery reimbursement frameworks remain underpenetrated by established hospital-centric vendors. For Investors and Strategic Acquirers: COFEPRIS-ANVISA mutual recognition agreement ratification is the leading indicator that Mexican production assets will command premium valuations for Brazilian market access. Five-to-ten year viability favors acquisition of enzymatic PEGylation platform specialists with existing hospital pharmacy consortia relationships, signaling defensible manufacturing moats against commodity filgrastim competition.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Interchangeability Certification | Unlocks SUS formulary inclusion and accelerates physician switching protocols across Minas Gerais networks. |
| Backward Integration into PEGylation Reagents | Insulates Brazilian manufacturers from REACH-aligned European supply volatility and euro currency exposure. |
| Home Administration Protocol Development | Aligns with Chile AUGE timelines and Colombian private insurance reimbursement expansion for subcutaneous delivery. |
| Hospital Pharmacy Consortium Contracting | Captures centralized procurement across São Paulo's 40-plus facility networks, displacing fragmented single-hospital purchasing. |
| COFEPRIS-ANVISA Regulatory Harmonization | Eliminates redundant facility audits, enabling Mexican producers to supply Brazilian hospital networks directly. |
Research Methodology
ANVISA regulatory filings, COFEPRIS biosimilar approval databases, and SUS hospital procurement records formed the secondary backbone, cross-referenced with primary interviews involving Brazilian formulary directors, Mexican oncology pharmacy committee chairs, Colombian INVIMA regulatory leads, and Argentine hospital procurement managers. Bottom-up and top-down triangulation validated patient volume estimates against centralized consortia contract disclosures and ambulatory chemotherapy expansion timelines across São Paulo, Rio de Janeiro, and Mexico City metropolitan networks.
Bottom-up modeling anchored volume projections to chemotherapy patient throughput at named hospital networks, while top-down analysis calibrated penetration rates against public reimbursement formularies and private insurance coverage expansion. Segmentation dimensions spanned product type, end-user setting, administration route, and distribution channel, with CAGRs derived from regression analysis of historical approval velocity and procurement contract cycle timing. Forecast inputs incorporated ANVISA interchangeability ruling implementation pace and PEG-G-CSF inclusion in Colombia's POS benefit package trajectory.
The model assumes a particular technology adoption path favoring site-specific enzymatic PEGylation; alternative pathways for random lysine conjugation would alter the outlook on manufacturing cost curves and batch consistency metrics. Deviation in ANVISA-COFEPRIS mutual recognition agreement ratification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Global Argatroban Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Progesterone Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Brexucabtagene Autoleucel Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Global Staphylococcal Infection Drugs Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Global Diagnostic Specialty Antibodies Market
Biopharmaceuticals
Global Protein Expression Market