
 Oligonucleotide API Market | 2026-2036
Oligonucleotide API Market Size, Share, and Industry Trends Forecast 2026-2036
Oligonucleotide API Market Outlook
Modular contract manufacturing arrangements for oligonucleotide APIs is expanding buyer flexibility across clinical and commercial stages. Thermo Fisher Scientific leverages integrated synthesis and purification infrastructure to serve multi-program clients. Lonza Group anchors European supply through dedicated oligonucleotide manufacturing campuses. Alnylam Pharmaceuticals differentiates via captive production of siRNA drug substance for its proprietary pipeline.
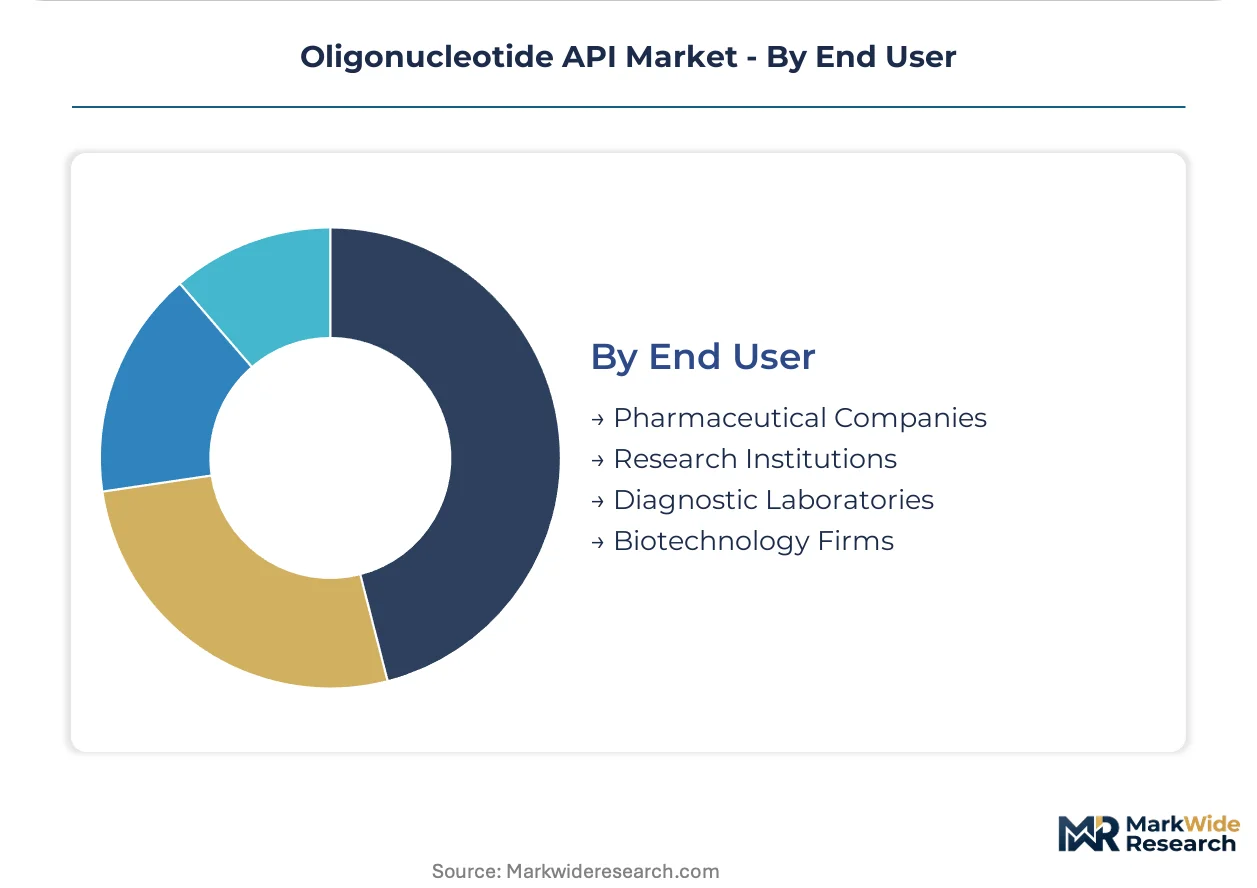
Oligonucleotide APIs are short-chain DNA or RNA molecules, typically 13–25 nucleotides in length, manufactured through solid-phase synthesis using phosphoramidite chemistry on controlled-pore glass supports. These molecules serve as the active pharmaceutical ingredient in antisense therapies, siRNA drugs, and molecular diagnostic probes. Synthetic oligonucleotides dominate current revenue owing to established synthesis protocols and broad therapeutic applicability, while siRNA represents the fastest-expanding category as RNA interference mechanisms advance through late-stage clinical validation. Among end users, pharmaceutical companies command the largest procurement volumes, though biotechnology firms are capturing disproportionate growth by outsourcing specialized chemistries.
FDA oversees oligonucleotide API quality through Current Good Manufacturing Practice regulations and chemistry, manufacturing, and controls guidance for gene therapy products. EMA applies its Advanced Therapy Medicinal Products framework and Good Manufacturing Practice standards to regulate European oligonucleotide supply chains. ISO 13485 and ICH Q7 guidelines further shape cross-border manufacturing protocols and documentation requirements. Stakeholders must monitor how evolving regulatory convergence between FDA and EMA on nucleic acid impurity thresholds will reshape qualification timelines and capital deployment decisions.
Market Dynamics
Regulatory convergence between FDA and EMA on nucleic acid impurity thresholds is compressing qualification timelines and forcing capital redeployment toward unified manufacturing standards across antisense and siRNA production networks.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy designation and EMA's PRIME scheme compress development timelines for gene therapy developers, expanding oligonucleotide procurement volumes across clinical stages.
- RNA Interference Mechanisms:siRNA therapeutic platforms advance through late-stage validation, creating pull-through demand for specialized phosphoramidite chemistries and purification infrastructure.
- United States Production Clusters:Massachusetts and North Carolina anchor commercial manufacturing networks, concentrating technical talent and regulatory expertise for multi-program clients.
Market Restraints
- Phosphoramidite Input Volatility:Specialty reagent supply concentrates among limited chemical manufacturers, exposing API producers to price swings and allocation constraints.
- European Supply Concentration:Switzerland and Germany host dominant contract manufacturing campuses, creating geographic vulnerability to single-point disruptions.
- Impurity Specification Stringency:ICH Q7 guidelines impose escalating analytical burden on synthetic oligonucleotide batches, extending release timelines and reject rates.
Strategic Opportunities
- India CDMO Expansion:Hyderabad and Bangalore clusters attract oligonucleotide investments through PLI scheme incentives and cost-advantaged synthesis labor pools.
- Molecular Diagnostic Convergence:CRISPR guide RNA and probe applications extend oligonucleotide demand beyond therapeutics into companion diagnostic supply chains.
- Modular Manufacturing Platforms:Disposable synthesis columns and single-use purification skids enable flexible capacity scaling across clinical-to-commercial transitions.
Industry Challenges
- Phosphoramidite Chemist Scarcity:Solid-phase synthesis expertise concentrates among aging specialist workforces, constraining capacity expansion at emerging manufacturing sites.
- GMP Facility Retrofit Costs:Containment requirements for potent nucleic acid APIs demand specialized HVAC and waste handling infrastructure, elevating capital intensity for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oligonucleotide API Market |
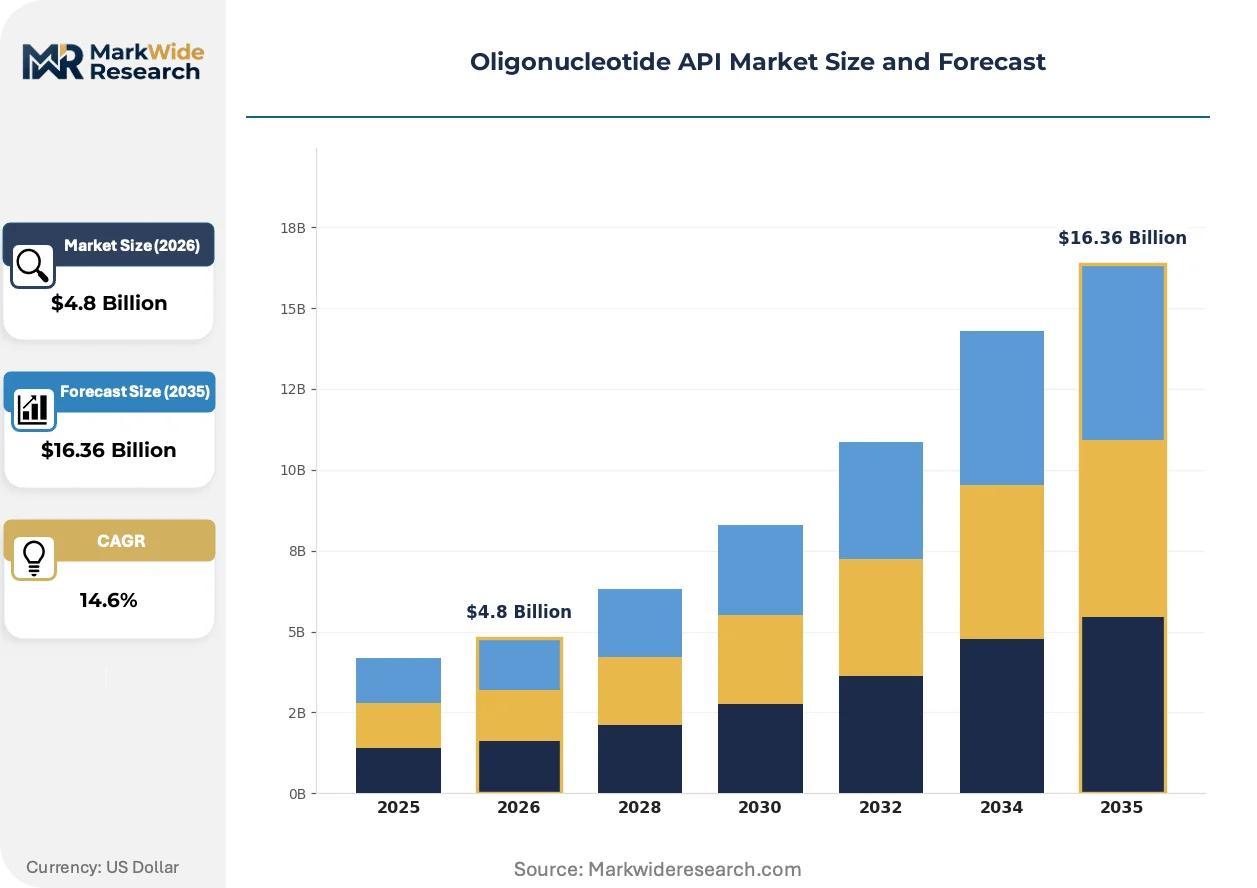
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oligonucleotides, PCR Oligonucleotides, LNA Oligonucleotides, siRNA Application: Gene Therapy, Diagnostics, Antisense Therapy, Research Technology: Solid-Phase Synthesis, Liquid-Phase Synthesis, Automated Synthesis, Enzymatic Synthesis End User: Pharmaceutical Companies, Research Institutions, Diagnostic Laboratories, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Merck KGaA, Lonza Group, Bachem, GenScript Biotech, Biogen, Alnylam Pharmaceuticals, Sarepta Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oligonucleotide API Market Strategic Shifts
Continuous manufacturing technologies and automated purification systems are compressing batch cycle times while regulatory harmonization efforts reshape quality management systems across transatlantic supply chains.
Flow-through solid-phase synthesis platforms are consolidating oligonucleotide production economics by enabling real-time process analytical technology integration. Mid-scale API producers adopt these systems to compress cycle times from days to hours. The technology is consolidating competitive position among manufacturers capable of simultaneous multi-kilogram output across diverse sequence portfolios.
EMA's Advanced Therapy Medicinal Products framework revision tightens nucleic acid traceability requirements from starting material to finished drug substance. European manufacturers must deploy blockchain-enabled chain-of-custody systems by implementation deadlines. siRNA drug substance operations face the steepest compliance burden given their higher complexity and patient exposure profiles.
Biotechnology firms now specify outcome-based supply agreements tying API release to functional potency rather than purity metrics alone. Contract manufacturers respond with integrated analytical development services that accelerate client regulatory filings. Massachusetts and California anchor this contracting evolution, where gene therapy developers concentrate technical sourcing decisions.
Oligonucleotide API Market Segmentation
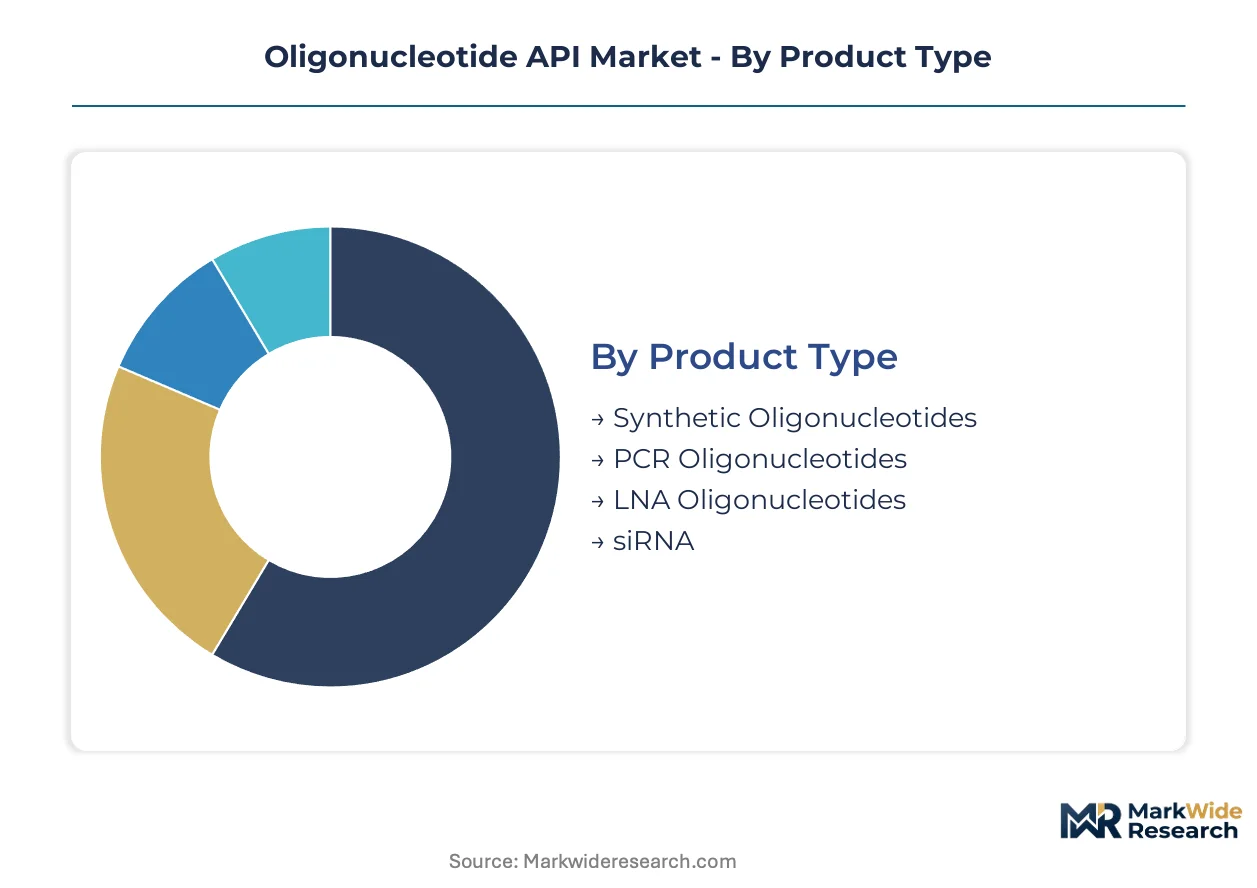
Oligonucleotide API procurement patterns diverge sharply between standalone therapeutic applications and embedded diagnostic systems. Understanding these integration-depth distinctions enables suppliers to align synthesis capacity with divergent purity specifications and regulatory pathways.
Product Type:
Standalone therapeutic oligonucleotides command premium purification infrastructure, while embedded diagnostic probes integrate into multiplex assay platforms with standardized purity thresholds.
- Synthetic Oligonucleotides:Manufactured through phosphoramidite chemistry on controlled-pore glass supports, these 13–25 nucleotide chains serve as the foundational building block for antisense therapeutics and molecular diagnostic probes. Massachusetts production clusters anchor commercial supply for gene therapy developers seeking multi-kilogram batch consistency under FDA Current Good Manufacturing Practice oversight.
- siRNA:RNA interference therapeutics utilize 21–23 nucleotide duplex structures with specialized chemical modifications for enhanced stability and target specificity. Alnylam Pharmaceuticals' captive manufacturing in the United States demonstrates how proprietary pipeline demands reshape investment in specialized phosphoramidite chemistries and double-stranded purification infrastructure.
- PCR Oligonucleotides:Primer and probe sequences for polymerase chain reaction amplification require high batch-to-batch consistency but lower regulatory stringency than therapeutic grades.
- LNA Oligonucleotides:Locked nucleic acid modifications introduce conformational rigidity for enhanced binding affinity in diagnostic and research applications.
Volume placements concentrate in synthetic oligonucleotides; the faster expansion belongs to siRNA.
Application:
Cost-tier stratification separates capital-intensive therapeutic manufacturing from research-grade procurement with abbreviated qualification timelines.
- Gene Therapy:Viral and non-viral vector systems incorporate oligonucleotide APIs as regulatory elements or therapeutic payloads, demanding the highest purity grades and extensive impurity profiling under EMA Advanced Therapy Medicinal Products frameworks. Swiss and German manufacturing campuses specialize in these complex supply relationships.
- Antisense Therapy:Single-stranded oligonucleotides modulate gene expression through mRNA degradation or translational blockade, with FDA breakthrough therapy designations compressing development timelines and expanding procurement across clinical stages. Ionis Pharmaceuticals anchors commercial demand for phosphorothioate-modified chemistries.
- Diagnostics:Companion diagnostic and molecular testing applications utilize oligonucleotide probes with functional potency specifications rather than purity metrics alone.
- Research:Preclinical and academic applications tolerate broader specification ranges in exchange for rapid turnaround and sequence diversity.
Revenue concentration favors gene therapy; antisense therapy is climbing the fastest as regulatory pathways mature.
Technology:
Volume-scale economics favor continuous processing platforms, while batch synthesis retains dominance in clinical-stage production requiring extensive documentation.
- Solid-Phase Synthesis:Phosphoramidite chemistry on controlled-pore glass supports remains the dominant manufacturing methodology for synthetic oligonucleotides, enabling stepwise nucleotide addition with high coupling efficiency. Thermo Fisher Scientific's integrated synthesis and purification infrastructure exemplifies how multi-program clients demand flexible capacity scaling across diverse sequence portfolios.
- Automated Synthesis:Robotic liquid handling and real-time process analytical technology integration compress cycle times from days to hours for mid-scale API producers seeking competitive positioning.
- Liquid-Phase Synthesis:Solution-phase methodologies offer alternative coupling chemistries for specialized modifications not compatible with solid-phase constraints.
- Enzymatic Synthesis:Polymerase-based production methods reduce phosphoramidite reagent dependence and enable longer sequence synthesis with reduced environmental waste handling burdens.
Capacity deployment concentrates in solid-phase synthesis; enzymatic synthesis is gaining share fastest as phosphoramidite input volatility intensifies.
End User:
Customer-type stratification distinguishes integrated pharmaceutical procurement from outsourced biotechnology relationships with outcome-based contracting terms.
- Pharmaceutical Companies:Large-scale therapeutic developers command the largest procurement volumes through dedicated manufacturing agreements and captive production networks, with Biogen's antisense manufacturing exemplifying vertical integration strategies that control supply security for commercial-stage products.
- Biotechnology Firms:Emerging gene therapy developers disproportionately drive growth by outsourcing specialized chemistries and specifying functional potency-based release criteria rather than traditional purity metrics, particularly in Massachusetts and California technical sourcing clusters.
- Research Institutions:Academic and government laboratories generate fragmented demand across diverse sequence requirements with limited batch sizes.
- Diagnostic Laboratories:Clinical testing and companion diagnostic developers integrate oligonucleotide procurement into automated assay manufacturing with standardized specification bands.
Procurement volume concentrates in pharmaceutical companies; biotechnology firms show the steepest expansion trajectory as RNA interference platforms advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in the United States and Switzerland while procurement demand spreads across therapeutic developers in Germany, Japan, and India. This geographic split shapes investment patterns across solid-phase synthesis infrastructure.
United States
FDA breakthrough therapy designations for antisense and siRNA candidates expand procurement volumes across clinical stages. The agency's chemistry, manufacturing, and controls guidance for gene therapy products governs quality standards. Massachusetts and North Carolina anchor commercial manufacturing networks where Biogen and Alnylam Pharmaceuticals concentrate technical talent for multi-kilogram production.
Switzerland
EMA Advanced Therapy Medicinal Products framework revisions tighten nucleic acid traceability requirements from starting material to finished drug substance. Swissmedic enforces Good Manufacturing Practice standards alongside European regulations. Basel and Visp host dedicated oligonucleotide manufacturing campuses where Lonza Group serves European gene therapy developers through integrated synthesis and purification infrastructure.
Germany
Ionis Pharmaceuticals and other antisense developers source specialized phosphorothioate-modified chemistries through German contract manufacturing relationships. EMA impurity threshold convergence with FDA compresses qualification timelines for cross-Atlantic supply. Bavaria and North Rhine-Westphalia concentrate analytical development services that accelerate client regulatory filings under unified manufacturing standards.
Japan
PMDA accelerated approval pathways for nucleic acid therapeutics mature, expanding oligonucleotide procurement from domestic biotechnology firms. METI industrial policy supports pharmaceutical manufacturing infrastructure investments. Kanto and Kansai regions develop specialized phosphoramidite chemistry capabilities as RNA interference platforms advance through late-stage clinical validation.
India
Hyderabad and Bangalore clusters attract oligonucleotide investments through PLI scheme incentives and cost-advantaged synthesis labor pools. CDSCO oversight of gene therapy products aligns with international quality standards. Domestic contract development and manufacturing organizations scale solid-phase synthesis capacity to serve European and North American biotechnology firms outsourcing specialized chemistries.
Oligonucleotide API Market Competitive Environment
The competitive structure tilts toward integrated life science conglomerates with captive synthesis infrastructure. Thermo Fisher Scientific and Merck KGaA anchor the consolidated tier through multi-program service platforms, while Lonza Group occupies specialized manufacturing positions. Three archetypes dominate: full-service CDMOs with regulatory filing support, biotechnology firms with backward integration into drug substance production, and reagent suppliers capturing phosphoramidite chemistry value. Capacity expansion and modular manufacturing platform deployment constitute the dominant competitive moves.
Among United States-based diversified suppliers, Thermo Fisher Scientific exemplifies the full-service CDMO archetype through integrated synthesis and purification infrastructure. Lonza Group represents European manufacturing specialization with dedicated oligonucleotide campuses serving EMA-regulated supply chains. Alnylam Pharmaceuticals occupies the biotechnology captive-production position, demonstrating how proprietary pipeline demands reshape investment in specialized chemistries.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Merck KGaA |
| Lonza Group |
| Bachem |
| GenScript Biotech |
| Biogen |
| Alnylam Pharmaceuticals |
| Sarepta Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Biotechnology firms specifying functional potency-based release criteria rather than traditional purity metrics are forcing contract manufacturers to restructure cost accounting around integrated analytical development services, compressing margins on standardized synthesis offerings while inflating premiums for outcome-validated supply agreements.
Pricing Analysis
Cost-down pressure on therapeutic-grade oligonucleotides accelerates because biotechnology procurement teams now bundle synthesis and regulatory filing support into single-source contracts. Three-tier pricing structure across GMP-certified, research-grade, and diagnostic-grade levels separates FDA-validated batches from preclinical materials. Price differentiation hinges on impurity specification stringency under ICH Q7 guidelines and after-batch analytical documentation depth. Emerging CDMOs in India exhibit highest price sensitivity; captive producers like Alnylam Pharmaceuticals show lowest.
Supply Chain Analysis
Phosphoramidite chemist scarcity in Massachusetts and North Carolina constrains capacity expansion despite surging siRNA demand. Solid-phase synthesis infrastructure concentrates in the United States, Switzerland, and Germany, with controlled-pore glass supports and specialty amidite reagents feeding from German chemical manufacturers. Single-source vulnerability around phosphoramidite inputs exposes API producers to allocation constraints. Distribution runs through dedicated cold-chain logistics serving GMP manufacturing campuses directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's Advanced Therapy Medicinal Products framework revisions erect a cost-of-compliance barrier that favors incumbent manufacturers with existing blockchain-enabled traceability systems and specialized containment infrastructure.
For Market Incumbents: Anchor market position through backward integration into phosphoramidite chemistry production and expansion of modular manufacturing platforms across Massachusetts and North Carolina clusters. Threat from enzymatic synthesis technologies demands preemptive investment in continuous processing capabilities to defend cycle-time advantages. Capacity addition in Switzerland reinforces EMA-regulated supply security for gene therapy developers. For New Entrants and Emerging Players: Enter via outcome-based supply agreements for biotechnology firms in California technical sourcing clusters, where functional potency specifications displace traditional purity metrics as procurement criteria. White-space opportunity concentrates in CRISPR guide RNA manufacturing for companion diagnostic supply chains. Go-to-market leverage rests on integrated analytical development services that accelerate client regulatory filings. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale CDMOs possessing phosphoramidite chemistry expertise and EMA/FDA dual-qualification status given regulatory convergence on nucleic acid impurity thresholds. Long-term viability over the projection horizon favors manufacturers with captive raw material sourcing and modular capacity deployment. Acquisition target archetype: European CDMOs with underutilized solid-phase synthesis infrastructure and established biotechnology client relationships. Signal to watch: FDA breakthrough therapy designation velocity for RNA interference platforms as demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designations compress development timelines and expand procurement volumes across clinical stages. |
| Manufacturing Scale-Up | Modular synthesis platforms enable flexible capacity scaling from clinical to commercial production for multi-program clients. |
| Backward Integration | Captive phosphoramidite chemistry production insulates API manufacturers from specialty reagent supply volatility and price swings. |
| Platform Integration | Blockchain-enabled chain-of-custody systems satisfy EMA traceability requirements for siRNA drug substance operations. |
| Geographic Expansion | Hyderabad and Bangalore clusters attract oligonucleotide investments through PLI scheme incentives and cost-advantaged synthesis labor pools. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving oligonucleotide synthesis directors, regulatory affairs leads at gene therapy developers, GMP facility managers, and biotechnology procurement specialists. FDA chemistry manufacturing controls guidance documents, EMA Advanced Therapy Medicinal Products framework revisions, and ISO 13485 certification databases supplied validation benchmarks. Bottom-up capacity assessments across Massachusetts, North Carolina, Switzerland, and Germany manufacturing clusters were reconciled with top-down demand projections from antisense and siRNA clinical pipeline tracking.
Data-stream reconciliation across production capacity surveys, procurement pattern analysis, and pricing intelligence from contract manufacturing agreements shaped the analytical framework. Segmentation modeling incorporated product type, application, synthesis technology, and end-user archetype dimensions across the projection horizon. CAGRs derived from weighted scenario analysis of regulatory approval velocity, phosphoramidite input cost trajectories, and biotechnology firm outsourcing propensity. Industry-specific inputs included FDA breakthrough therapy designation flow and EMA impurity threshold convergence timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phosphoramidite supply disruption or accelerated enzymatic synthesis adoption scenarios. Forecasts reflect documented assumptions regarding regulatory pathway maturation and biotechnology capital availability. Material deviation in FDA approval velocity or EMA traceability implementation deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Linaclotide API Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Rhu Albumin Market
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Plasma Protein System Market