
 Global Lenalidomide Market | 2026-2036
Global Lenalidomide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lenalidomide Market Foresight
Modular dosing configurations are recalibrating buyer choice across the lenalidomide supply chain, as manufacturers unbundle standard capsule strengths into patient-specific titration packs that align with cycle-based oncology protocols. Bristol Myers Squibb Company anchors the branded originator segment through its established REMS infrastructure and specialty pharmacy relationships. Cipla Ltd competes aggressively in emerging markets through cost-optimized capsule formulations that leverage its API-to-finished-dose vertical integration. Sun Pharmaceutical Industries Ltd. differentiates via its broad oncology portfolio cross-sell capability and hospital formulary positioning.
Lenalidomide is an immunomodulatory imide drug (IMiD) synthesized through a multi-step organic process involving glutarimide ring construction and phthalimide substitution, functioning primarily as a cereblon E3 ligase modulator that promotes degradation of transcription factors Ikaros and Aiolos in malignant plasma cells. The therapy area dimension shows multiple myeloma commanding the dominant volume share as maintenance therapy following autologous stem cell transplant, while mantle cell lymphoma represents a faster-growing but smaller addressable pool where off-label utilization is expanding. Capsule formulations retain the largest manufacturing scale and margin concentration, though extended-release development programs are gaining traction as patent cliffs approach for immediate-release variants.
FDA REMS requirements for thalidomide analogs mandate prescriber certification, patient counseling, and pregnancy prevention programs that directly constrain distribution channel structure and create compliance costs absorbed disproportionately by smaller entrants. EMA pharmacovigilance frameworks across European member states impose additional post-market surveillance obligations that lengthen approval timelines for generic lenalidomide submissions. Stakeholders must monitor evolving bioequivalence standards for immunomodulatory drugs and calibrate pipeline investments between formulation innovation and biosimilar readiness as originator exclusivity periods expire across major jurisdictions.
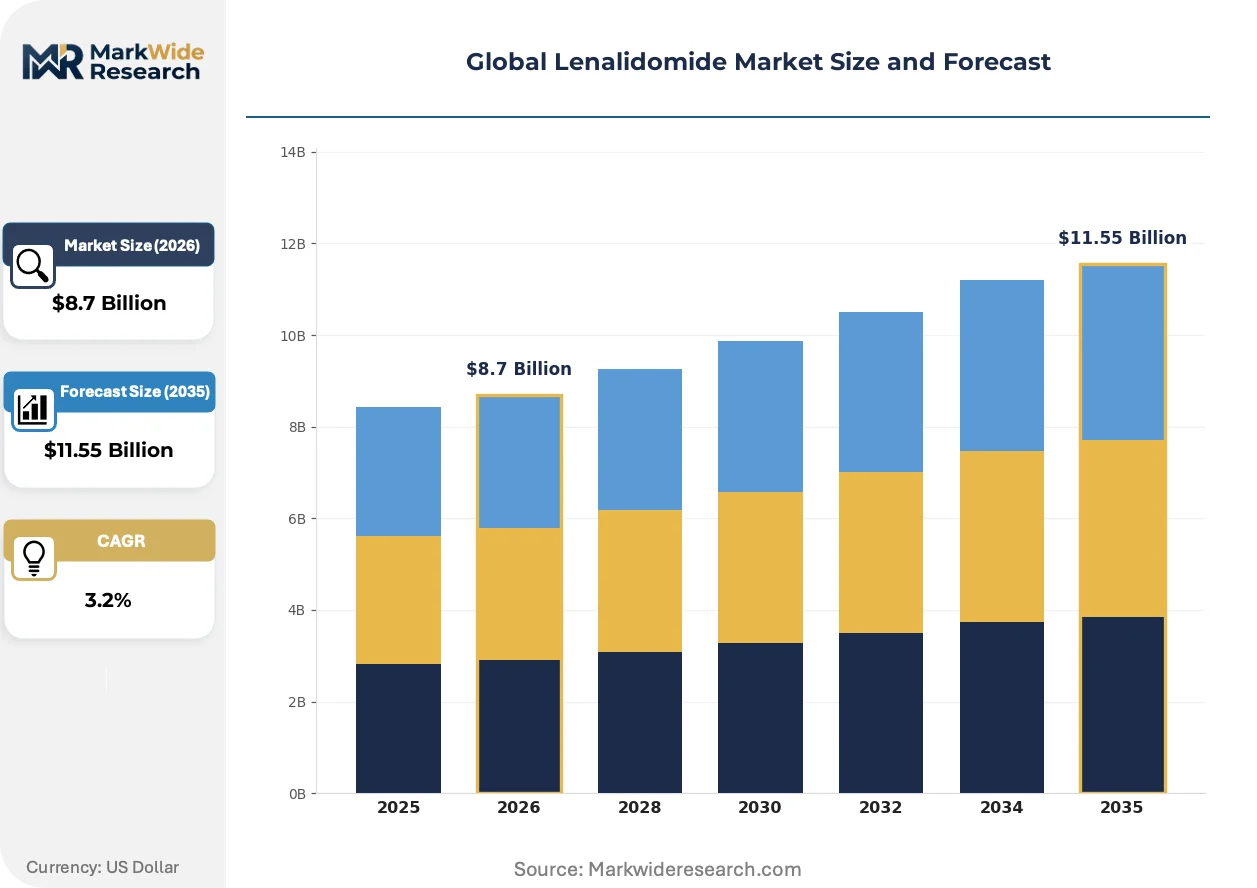
Market Dynamics
FDA REMS infrastructure for thalidomide analogs locks distribution into prescriber-certified specialty pharmacy networks, creating structural barriers that favor incumbents with compliance scale while constraining generic entry pathways.
Growth Catalysts
- Maintenance protocol expansion:Oncology centers in the United States are extending lenalidomide duration as first-line therapy following autologous stem cell transplant, embedding the drug into standard-of-care pathways.
- Medicare reimbursement frameworks:Part B and Part D coverage stability for oral oncology agents protects patient access and volume predictability across Medicare Advantage networks.
- API manufacturing concentration:Indian bulk drug parks and Chinese intermediate suppliers are expanding active pharmaceutical ingredient capacity to serve formulation demand in emerging markets.
Market Restraints
- REMS compliance costs:FDA-mandated prescriber certification, patient counseling, and pregnancy prevention programs impose fixed operational burdens that disproportionately burden smaller generic entrants.
- Bioequivalence complexity:Immunomodulatory mechanism variability and cereblon binding kinetics create regulatory uncertainty for abbreviated new drug applications targeting lenalidomide.
- Phthalimide intermediate volatility:Glutarimide ring synthesis feedstock prices fluctuate with agricultural chemical demand cycles, pressuring cost structures for API manufacturers.
Strategic Opportunities
- Extended-release formulation development:Patent cliff proximity for immediate-release variants creates white space for modified-release programs that could reset exclusivity timelines.
- Mantle cell lymphoma off-label expansion:Hematology protocols in Germany and France are testing lenalidomide combinations beyond approved indications, opening addressable pools outside multiple myeloma dominance.
- Biosimilar readiness positioning:EMA pharmacovigilance harmonization across European member states is streamlining post-market surveillance frameworks for generic submissions.
Industry Challenges
- REMS infrastructure replication:Building prescriber certification systems and patient registry platforms requires multi-year capital deployment that strains mid-cap entrants.
- Formulation scientist scarcity:Specialized expertise in immunomodulatory drug bioequivalence and cereblon pharmacodynamics concentrates within legacy oncology teams at established manufacturers.
- Supply chain reconfiguration friction:Reliance on Chinese phthalimide intermediates and Indian API finishing creates geopolitical exposure that demands dual-sourcing investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lenalidomide Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Oral Suspensions, Extended-Release, Injectable Therapy Area: Multiple Myeloma, Myelodysplastic Syndromes, Mantle Cell Lymphoma, Diffuse Large B-Cell Lymphoma, Amyloidosis End User: Hospitals, Specialty Clinics, Oncology Centers, Research Labs, Home Care Providers Distribution Channel: Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Direct Sales, Third-Party Distributors |
| Companies Covered | Cipla Ltd, Amneal Pharmaceuticals, Bristol Myers Squibb Company, Sun Pharmaceutical Industries Ltd., Natco Pharma, Dr. Reddy’s Laboratories, Sandoz, Zydus Lifesciences, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lenalidomide Market Shifts & Advancements
Formulation science and distribution infrastructure are diverging as patent cliffs approach, with manufacturers investing in delivery mechanism innovation while generic entrants navigate REMS complexity and bioequivalence standards.
Extended-release capsule technologies are expanding into lenalidomide development pipelines as originator manufacturers seek to extend market exclusivity beyond immediate-release patent expirations. These formulations employ matrix-based or osmotic pump mechanisms to modulate cereblon binding kinetics over 24-hour cycles. Hematology-oncology practices in the United States are evaluating these programs for maintenance therapy adherence improvement. The technology is expanding into pricing tier differentiation that separates premium branded extended-release from commoditized immediate-release generic substitutes.
EMA pharmacovigilance harmonization directives are compressing approval timelines for generic lenalidomide submissions across European member states. The framework mandates centralized post-market surveillance databases that reduce redundant national reporting obligations. Generic manufacturers in India and contract research organizations in Eastern Europe are recalibrating regulatory strategies to exploit this streamlining. Oncology hospital formularies in France, Germany, and Italy are preparing tender processes that assume accelerated generic availability.
Specialty pharmacy channel concentration is consolidating lenalidomide distribution into vertically integrated networks that control patient access and data flows. United States Medicare Part D plans and pharmacy benefit managers are narrowing preferred pharmacy networks to capture dispensing margins and adherence monitoring revenue. Community oncology practices are responding by affiliating with hospital outpatient departments or selling to platform operators. This channel restructuring is most visible in Florida, Texas, and California, where Medicare Advantage penetration and specialty pharmacy density intersect most intensely.
Global Lenalidomide Market Segmentation
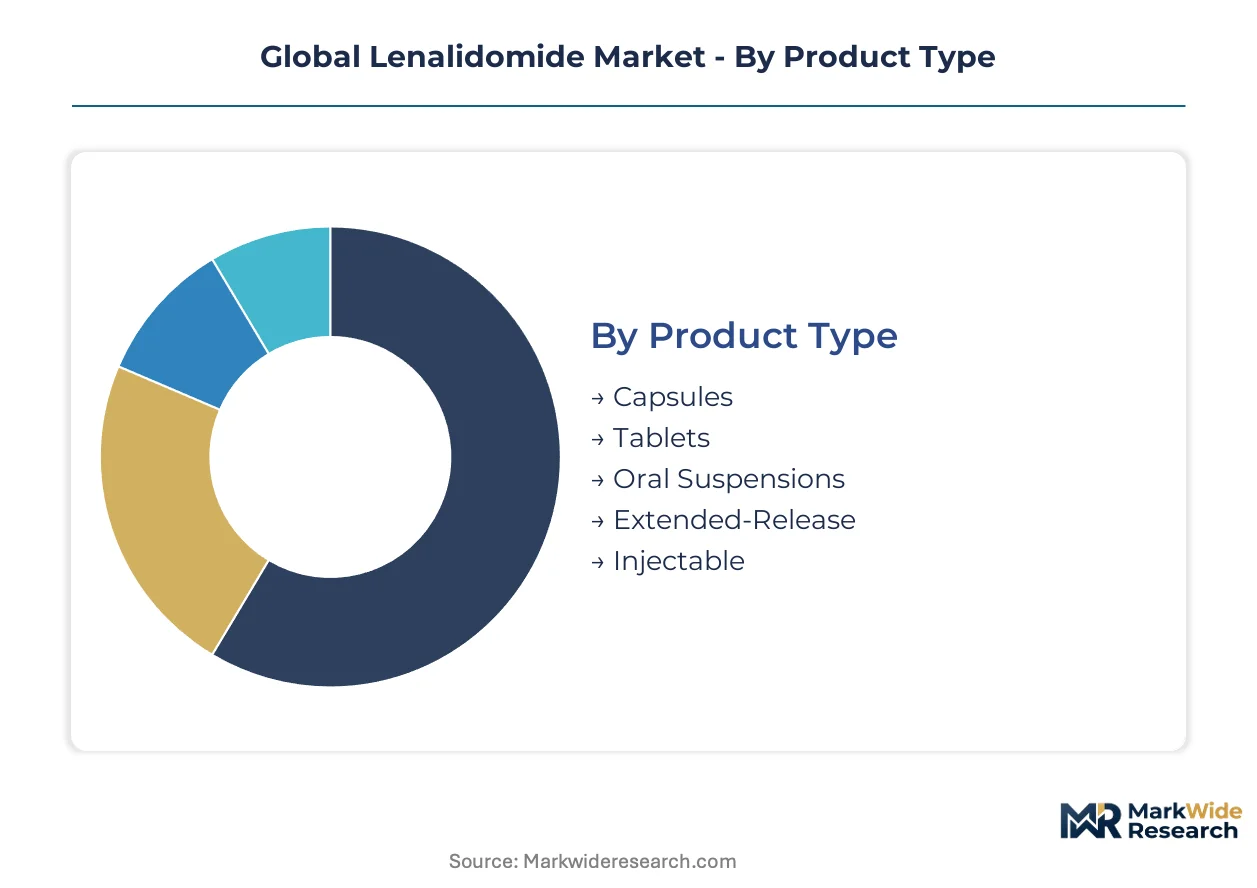
Lenalidomide's therapeutic versatility and REMS-governed distribution create distinct segment dynamics where formulation choice, therapy protocol, and channel access interlock. Understanding these dimensions reveals where pricing power concentrates and where generic substitution pressure mounts.
Product Type:
Standardization dominates immediate-release formats while extended-release variants represent the customization frontier where manufacturers seek patent reset opportunities.
- Capsules:Immediate-release gelatin shells containing lenalidomide powder blends dominate manufacturing scale and oncology protocol familiarity. Demand concentrates in United States Medicare networks where Bristol Myers Squibb's REMS infrastructure and specialty pharmacy relationships lock in formulary positioning.
- Extended-Release:Matrix-based or osmotic pump formulations modulate cereblon binding kinetics across 24-hour dosing cycles. Development pipelines in Germany and Massachusetts are targeting adherence improvement in maintenance therapy populations, creating premium pricing tiers separate from commoditized immediate-release substitutes.
- Tablets:Compressed dosage forms with modified disintegration profiles serve markets where capsule shell supply constraints or cultural preferences dictate alternative presentations.
- Oral Suspensions:Liquid formulations enable dose titration flexibility for patients with swallowing difficulties or pediatric protocols under investigator-initiated trials.
- Injectable:Parenteral delivery routes remain experimental, with Phase I programs exploring subcutaneous depot formulations for non-adherent maintenance populations.
Leading the category by volume: Capsules. Growing fastest: Extended-Release.
Therapy Area:
Application maturity varies sharply, with established maintenance protocols in hematologic malignancies contrasting against exploratory use in solid tumor combinations.
- Multiple Myeloma:Post-transplant maintenance therapy represents the anchor indication where lenalidomide embeds into standard-of-care pathways across NCCN guidelines. United States oncology centers extend treatment duration, embedding the drug into continuous therapy models that protect volume predictability.
- Mantle Cell Lymphoma:FDA-approved second-line indication with faster protocol expansion in French and German hematology practices testing combination regimens beyond labeled use. Off-label utilization is climbing fastest outside the myeloma core.
- Myelodysplastic Syndromes:Transfusion-dependent anemia with del(5q) cytogenetic abnormality constitutes a smaller but stable addressable pool with distinct reimbursement coding.
- Diffuse Large B-Cell Lymphoma:Investigational combinations with rituximab and checkpoint inhibitors are advancing through academic medical center trials in Italy and Spain.
- Amyloidosis:AL-type systemic disease represents an emerging application where immunomodulatory effects on plasma cell clones show preliminary efficacy signals.
Multiple Myeloma commands volume concentration. Mantle Cell Lymphoma shows steepest expansion trajectory.
End User:
Customer type segmentation reflects site-of-care migration trends, with hospital outpatient departments gaining share against community oncology practices.
- Oncology Centers:Dedicated hematology-oncology facilities in Texas, Florida, and California administer the majority of lenalidomide maintenance cycles, capturing Medicare Part B infusion revenue alongside oral drug dispensing.
- Hospitals:Academic medical centers with embedded specialty pharmacies control REMS compliance infrastructure and prescriber certification programs that generic entrants struggle to replicate.
- Specialty Clinics:Physician-owned infusion centers affiliate with hospital systems to access 340B pricing and narrow network contracts.
- Home Care Providers:Mail-order specialty pharmacies with REMS certification deliver direct-to-patient for stable maintenance populations.
- Research Labs:Investigator-initiated trials and biosimilar pharmacokinetic studies consume limited but high-margin clinical supply volumes.
Oncology Centers lead by patient volume. Home Care Providers are gaining share fastest as Medicare Advantage plans narrow network preferences.
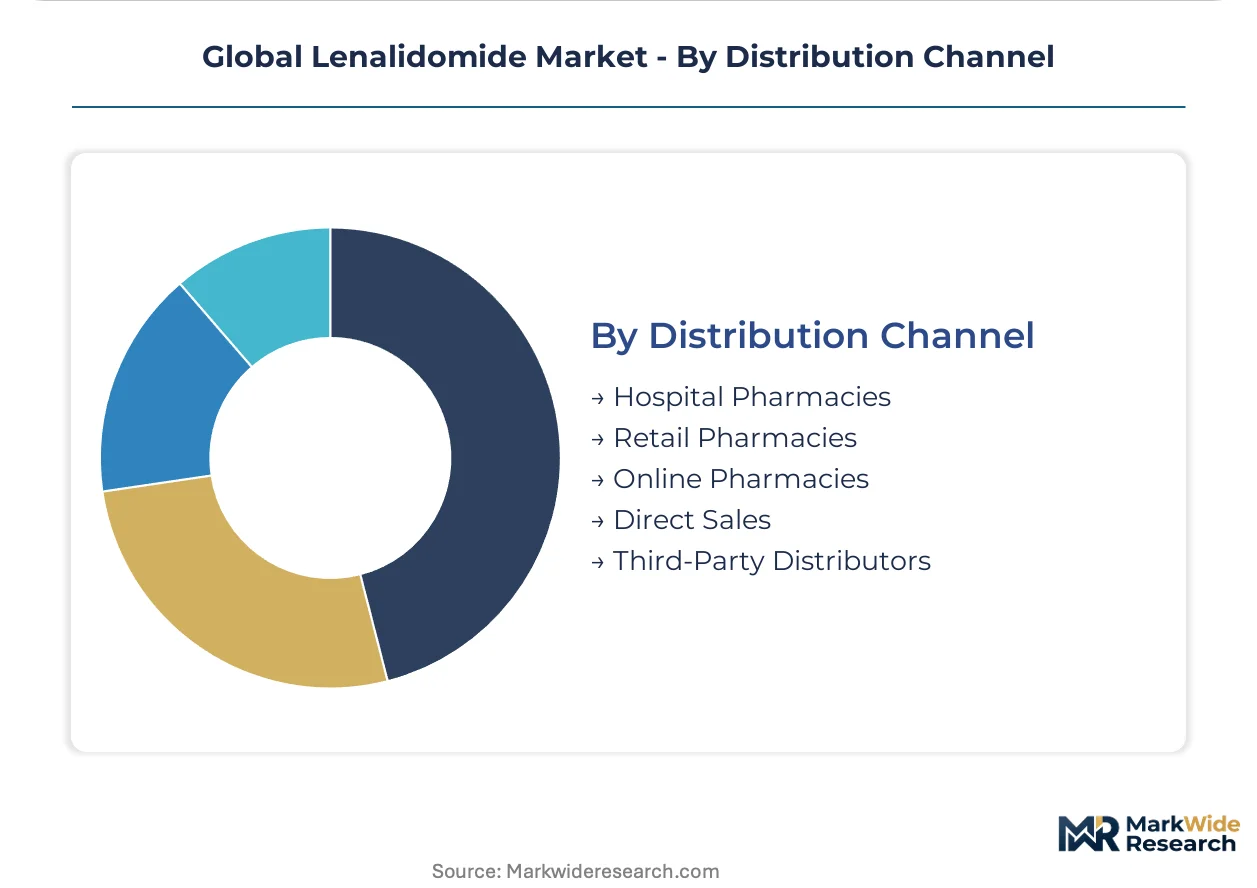
Distribution Channel:
Channel structure reflects REMS-mandated control requirements, with vertical integration rewarding scale operators over fragmented retail networks.
- Hospital Pharmacies:Integrated dispensing within oncology centers captures adherence data and REMS documentation requirements that satisfy FDA audit protocols. United States hospital systems in the Southeast and Midwest leverage 340B eligibility for margin expansion.
- Specialty Pharmacy Networks:Vertically integrated platforms like CVS Specialty and Accredo dominate Medicare Part D preferred networks, controlling patient access and data flows through prescriber certification systems.
- Retail Pharmacies:Generalist chains participate marginally due to REMS infrastructure gaps and limited oncology pharmacist staffing.
- Online Pharmacies:Verified internet pharmacy practice sites serve geographically dispersed patients with established REMS relationships.
- Direct Sales:Manufacturer-controlled distribution for clinical trial supplies and compassionate access programs.
- Third-Party Distributors:Wholesale intermediaries serve emerging markets where local specialty pharmacy infrastructure remains underdeveloped.
Hospital Pharmacies anchor volume distribution. Specialty Pharmacy Networks are consolidating fastest through PBM vertical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lenalidomide API manufacturing concentrates in Indian bulk drug parks and Chinese intermediate suppliers, while consumption gravity sits in United States Medicare networks and European hospital formularies. This production-consumption divide shapes trade flows, regulatory compliance investments, and generic entry strategies across major jurisdictions.
United States
Medicare Part B and Part D reimbursement stability anchors lenalidomide demand through oncology centers in Texas, Florida, and California. FDA REMS infrastructure for thalidomide analogs mandates prescriber certification and pregnancy prevention programs that lock distribution into specialty pharmacy networks. The Southeast hospital systems leverage 340B eligibility for margin expansion on oral oncology dispensing.
Germany
Hematology practices in Munich and Berlin test lenalidomide combinations for mantle cell lymphoma beyond approved indications, expanding off-label utilization fastest in Europe. EMA pharmacovigilance harmonization streamlines post-market surveillance obligations for generic submissions. The Baden-Württemberg pharmaceutical cluster hosts formulation development programs targeting extended-release variants.
India
Hyderabad and Ahmedabad bulk drug parks expand API finishing capacity to serve emerging market formulation demand. CDSCO accelerated approval pathways for oncology generics compress regulatory timelines for domestic manufacturers. The Telangana-Andhra Pradesh corridor concentrates cereblon-binding immunomodulator expertise through vertically integrated API-to-capsule operations.
China
Phthalimide intermediate suppliers in Jiangsu and Shandong provinces scale glutarimide ring synthesis feedstock for global API demand. NMPA bioequivalence standards for immunomodulatory drugs create regulatory uncertainty for abbreviated new drug applications. The Yangtze River Delta pharmaceutical manufacturing base attracts joint venture investments in oncology finished-dose capacity.
France
Academic medical centers in Paris and Lyon advance investigator-initiated trials for diffuse large B-cell lymphoma combinations. ANSM post-authorization safety study requirements align with EMA pharmacovigilance frameworks. The Île-de-France region concentrates hematology-oncology research infrastructure driving protocol innovation beyond multiple myeloma maintenance.
Global Lenalidomide Market Competitive Landscape
The competitive structure tilts toward originator-incumbent dominance reinforced by REMS compliance scale and specialty pharmacy channel control. Two to three strategic archetypes populate the landscape: branded originators with established risk management infrastructure, vertically integrated Indian generic manufacturers with API captive supply, and multinational specialty pharma platforms with hospital formulary positioning. Dominant competitive moves include extended-release formulation patent resets and EMA regulatory strategy recalibration for accelerated generic entry.
Among the branded originator tier, Bristol Myers Squibb Company anchors REMS infrastructure and United States specialty pharmacy relationships that constrain generic substitution pressure. Cipla Ltd and Sun Pharmaceutical Industries Ltd exemplify the Indian vertically integrated archetype, leveraging API-to-finished-dose control for cost-optimized capsule supply in emerging markets. Dr. Reddy's Laboratories and Zydus Lifesciences occupy positions within the multinational generic expansion vector, targeting EMA pharmacovigilance harmonization for European market access.
| Leading Market Players |
|---|
| Cipla Ltd |
| Amneal Pharmaceuticals |
| Bristol Myers Squibb Company |
| Sun Pharmaceutical Industries Ltd. |
| Natco Pharma |
| Dr. Reddy's Laboratories |
| Sandoz |
| Zydus Lifesciences |
| Teva Pharmaceutical Industries |
| Others |
Supply & Pricing Matrix
FDA Risk Evaluation and Mitigation Strategy compliance gates qualified supply access and premium-tier pricing power, as prescriber certification infrastructure and pregnancy prevention program costs create structural moats that only scaled operators can surmount. Manufacturers without REMS-compliant distribution networks face automatic disqualification from Medicare reimbursement pathways regardless of formulation quality.
Pricing Analysis
Margin tightening in immediate-release capsules reflects Indian API-to-finished-dose backward integration and Chinese intermediate scale economies compressing cost structures. Three-tier pricing structure across REMS-certified originator, vertically integrated generic, and emerging market commodity suppliers differentiates on regulatory compliance depth and prescriber relationship infrastructure. Pricing pressure stems from EMA pharmacovigilance harmonization accelerating European generic entry timelines. Community oncology practices show highest price sensitivity; academic medical centers with 340B eligibility demonstrate lowest.
Supply Chain Analysis
Freight cost volatility from Indian bulk drug parks to United States specialty pharmacy networks compounds phthalimide intermediate price swings tied to agricultural chemical demand cycles. API finishing concentrates in Hyderabad and Ahmedabad; glutarimide ring synthesis feedstock originates from Jiangsu and Shandong provinces. Single-source vulnerability pervades cereblon-binding immunomodulator expertise concentration in the Telangana-Andhra Pradesh corridor. Distribution runs through vertically integrated specialty pharmacy platforms controlling REMS documentation and patient registry compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA REMS infrastructure for thalidomide analogs functions as a cost-of-compliance barrier that rewards scaled incumbents while filtering out capital-constrained entrants unable to deploy multi-year certification systems.
For Market Incumbents: Cement REMS infrastructure moats by deepening prescriber certification platform investments and expanding specialty pharmacy data integration capabilities. Generic entrants with Indian API captive supply represent the primary substitution threat. Prioritize extended-release formulation patent resets as the defensive lever to reset exclusivity timelines beyond immediate-release cliffs. For New Entrants and Emerging Players: Underserved hematology practices in German and French academic medical centers offer white-space entry points for mantle cell lymphoma off-label combination protocols. EMA pharmacovigilance harmonization compresses approval timelines for compliant submissions. Pursue investigator-initiated trial sponsorship as the go-to-market angle to build cereblon pharmacodynamics credibility before formulary tender participation. For Investors and Strategic Acquirers: First generic lenalidomide approval in a major European jurisdiction is the leading indicator that originator pricing power erosion has reached an inflection point. Long-term viability favors vertically integrated manufacturers with API-to-finished-dose control and established REMS replication capability. Monitor CDSCO accelerated oncology approval decisions as the signal for emerging market generic supply acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Infrastructure Replication | Prescriber certification platforms satisfy FDA audit protocols and lock formulary positioning. |
| Extended-Release Formulation Development | Matrix-based delivery mechanisms reset patent exclusivity beyond immediate-release cliffs. |
| EMA Pharmacovigilance Harmonization | Centralized surveillance databases compress redundant national reporting for generic submissions. |
| API Backward Integration | Captive glutarimide ring synthesis insulates against phthalimide intermediate price volatility. |
| Mantle Cell Lymphoma Protocol Expansion | Off-label utilization in German hematology practices diversifies revenue beyond myeloma maintenance. |
Research Methodology
FDA filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced against primary interviews with regulatory affairs leads, formulary directors at United States oncology centers, and payer access specialists at Medicare Advantage plans. Bottom-up and top-down triangulation validated volume estimates across prescriber-certified specialty pharmacy networks and hospital outpatient dispensing data.
Bottom-up modeling anchored patient-flow analysis through treatment line progression and maintenance therapy duration assumptions, while top-down approaches cross-checked against API production capacity and phthalimide intermediate trade flows. Segmentation dimensions included dosage form, therapy area, end-user site-of-care type, and regional regulatory cluster. CAGRs derived from protocol expansion rates and reimbursement framework stability assessments across the projection horizon, with cereblon binding kinetics variability and bioequivalence standard evolution as key forecast inputs.
Revisions become necessary when FDA REMS requirement modifications, EMA pharmacovigilance directive changes, or phthalimide intermediate supply disruptions materialize beyond baseline assumptions. Forecasts reflect documented assumptions about prescriber certification penetration and specialty pharmacy network consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Global Anti-Tuberculosis Therapeutics Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
Antibacterial Drugs Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
Drug Discovery Outsourcing Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Global Bruton Tyrosine Kinase (BTK) Inhibitors Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Peptide Drug Conjugates Market
Biopharmaceuticals
Global Flu Vaccine Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market