
 Atipamezole Market | 2026-2036
Atipamezole Market Size, Share, and Industry Trends Forecast 2026-2036
Atipamezole Market Analysis
Veterinary clinic direct purchasing is reshaping how atipamezole reaches end users, bypassing traditional wholesale layers. Zoetis Inc. leverages its companion animal franchise to sustain dominant shelf presence across North American veterinary hospitals. Orion Corporation anchors its position through specialized anesthesia reversal formulations tailored for European regulatory standards. Vetoquinol S.A. competes by extending its distribution footprint into emerging veterinary service networks.
Atipamezole is an alpha-2 adrenergic antagonist administered parenterally to reverse sedative and analgesic effects of dexmedetomidine or medetomidine in veterinary patients, typically achieving full recovery within fifteen to thirty minutes post-injection. The compound functions by competitively binding alpha-2 receptors in the central nervous system, restoring normal cardiovascular and respiratory parameters in canines and felines. Injectable solutions lead product type demand due to immediate bioavailability requirements in emergency sedation reversal scenarios. Research institutions represent the fastest-growing end user segment as translational studies expand alpha-2 antagonist applications beyond standard veterinary protocols.
FDA Center for Veterinary Medicine oversees approval pathways for atipamezole formulations, while EMA veterinary product standards govern European market access through centralized authorization procedures. USDA and national agricultural regulators in key markets enforce manufacturing quality and import compliance for veterinary pharmaceuticals. Stakeholders must monitor evolving pharmacovigilance reporting requirements and anticipate regulatory divergence between major jurisdictions when planning product registration strategies.
Market Dynamics
Veterinary emergency care protocols are tightening sedation reversal timelines, compressing the window between alpha-2 agonist administration and atipamezole intervention from hours to minutes in companion animal hospitals.
Growth Catalysts
- Emergency veterinary infrastructure:United States, Germany, and Japan are upgrading 24-hour critical care facilities, embedding rapid-reversal anesthesia protocols as standard operating procedure.
- EMA centralized authorization:Streamlined veterinary product pathways accelerate atipamezole formulation approvals across European Union member states, reducing time-to-market barriers.
- Translational research expansion:Universities and contract research organizations are repurposing alpha-2 antagonist mechanisms for neuropharmacology studies beyond standard veterinary applications.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis of high-purity atipamezole hydrochloride concentrates among three specialized European contract manufacturers, creating single-source vulnerability.
- FDA pharmacovigilance expansion:Post-market adverse event reporting requirements for veterinary anesthetics have lengthened compliance timelines and inflated documentation costs.
- Dexmedetomidine-sparing protocols:Alternative sedation strategies using benzodiazepine-ketamine combinations reduce dependency on alpha-2 agonists in select feline procedures.
Strategic Opportunities
- Japanese exotic animal segment:METI-supported veterinary modernization programs in Osaka and Tokyo are extending anesthesia reversal protocols to avian and reptile collections in zoological and private practice settings.
- Prefilled syringe delivery:Ready-to-use parenteral formats eliminate compounding steps in emergency scenarios, aligning with USDA biosecurity standards for field veterinary operations.
- ISO 10993 biocompatibility alignment:Medical-grade polymer packaging innovations position atipamezole formulations for crossover into research anesthesia device compatibility testing.
Industry Challenges
- Veterinary anesthesiologist certification:ACVAA diplomate scarcity limits institutional capacity to implement advanced reversal protocols in mid-tier companion animal hospitals.
- Cold chain integrity:Temperature-sensitive parenteral formulations require validated logistics infrastructure that many rural veterinary distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atipamezole Market |
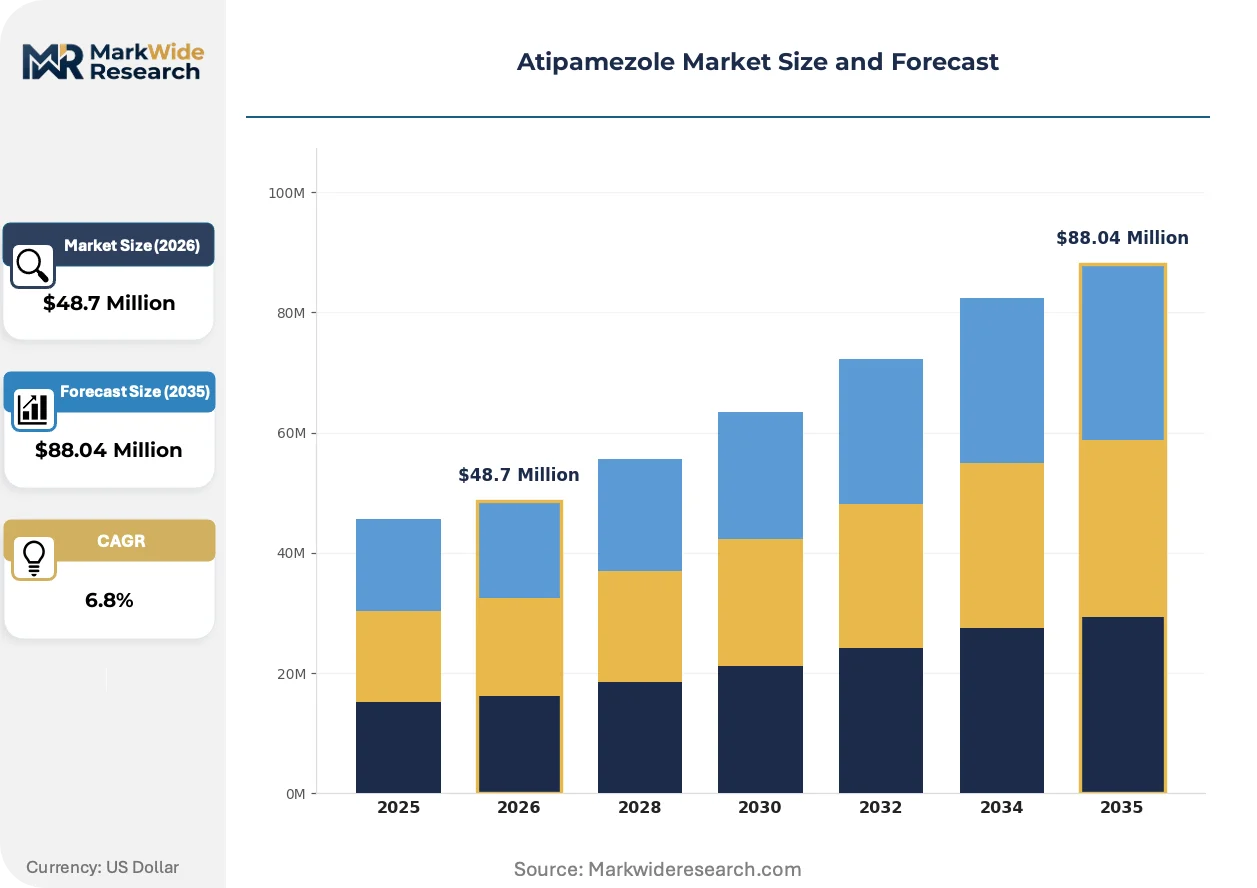
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Solution, Oral Solution, Tablet, Intranasal Spray End User: Veterinarians, Animal Clinics, Research Institutions, Zoos Application: Reversal Agent, Sedation Recovery, Emergency Care, Diagnostic Procedures Distribution Channel: Online Pharmacies, Retail Pharmacies, Direct Sales, Veterinary Clinics |
| Companies Covered | Zoetis Inc., Orion Corporation, Pfizer Inc., Merck & Co., Inc., Elanco Animal Health Incorporated, Vetoquinol S.A., Virbac S.A., Modern Veterinary Therapeutics, Alvetra u. Werfft GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atipamezole Market Emerging Trajectories
Formulation science and delivery mechanisms are converging to compress administration errors and accelerate onset consistency in emergency veterinary settings.
Lyophilized atipamezole powder-for-injection formats are collapsing reconstitution variability that previously delayed sedation reversal in high-stress clinical environments. Emergency veterinary technicians in tertiary referral hospitals are adopting these formats within eighteen months of availability. The technology is collapsing the gap between pharmacy preparation and bedside administration, reducing human-factor errors in time-critical scenarios.
FDA Center for Veterinary Medicine's 2023 revised guidance on generic animal drug bioequivalence has tightened pharmacokinetic study requirements for atipamezole competitors. The regulation now mandates parallel clinical endpoint trials in both canine and feline models, elevating development costs for abbreviated new animal drug applications. European sponsors are responding by front-loading EMA scientific advice consultations to preempt regulatory divergence.
Consolidated purchasing alliances among corporate veterinary groups are unbundling traditional distributor relationships in North American markets. Multi-site practice networks negotiate direct manufacturer contracts, displacing wholesale markup layers that historically captured thirty to forty percent of product margin. This concentration is most visible in California and Texas, where Banfield and VCA facility density enables volume-based tendering.
Atipamezole Market Segmentation
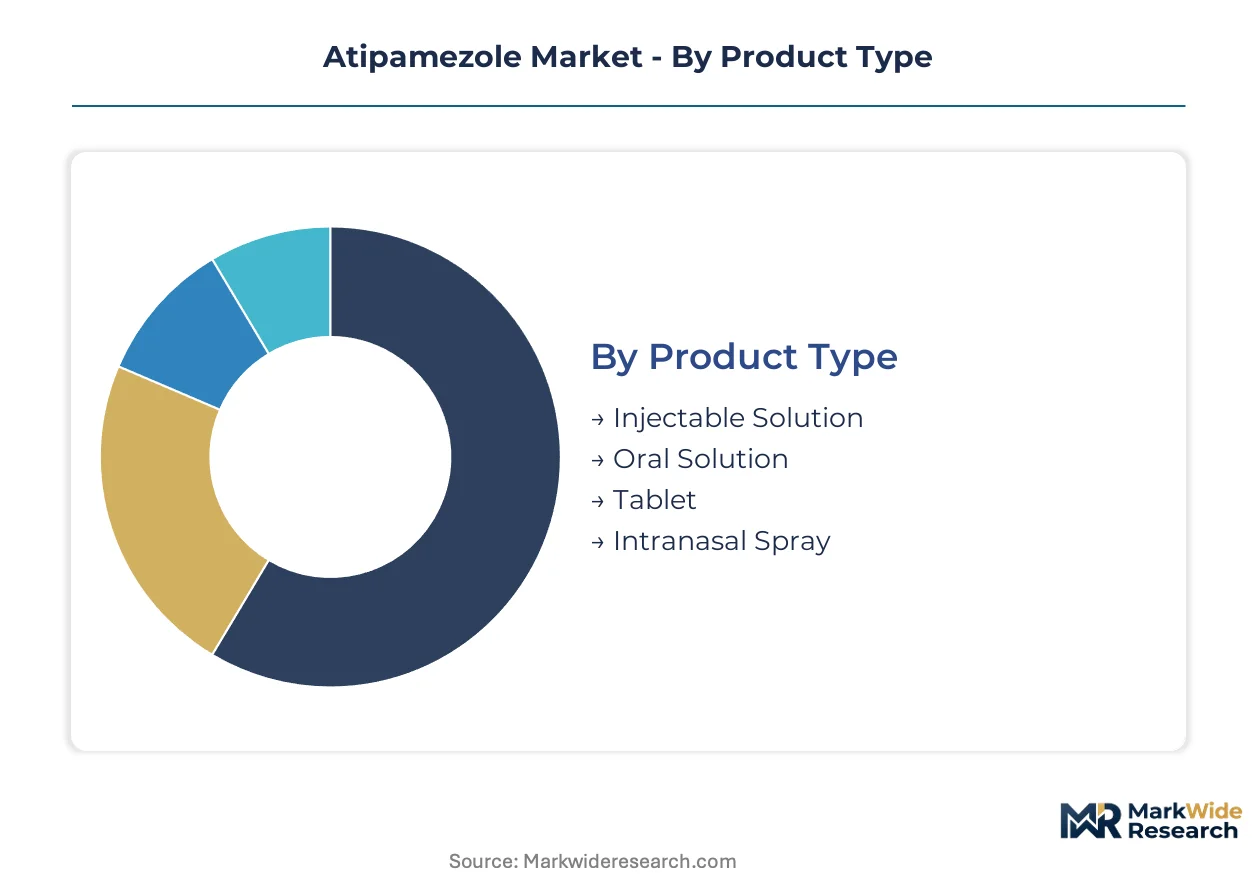
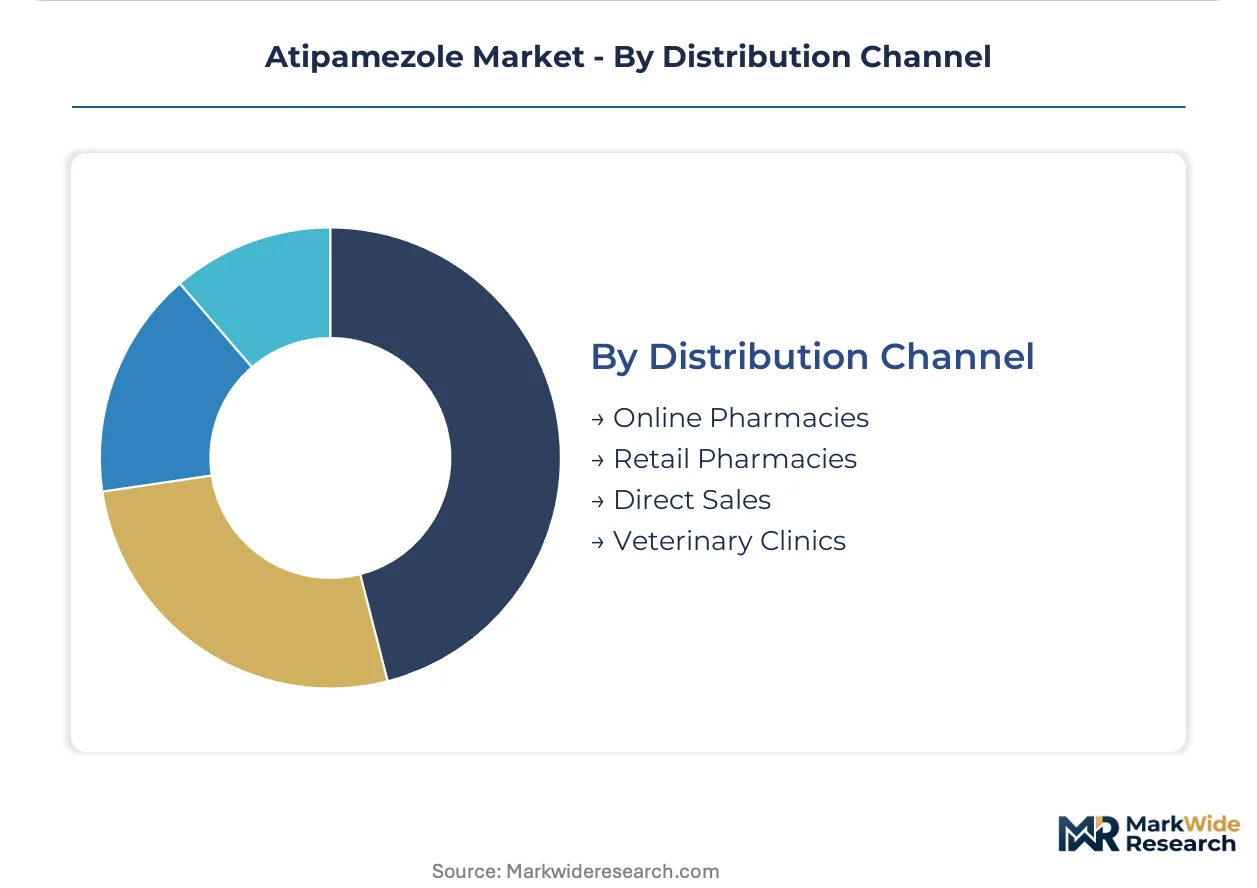
Atipamezole market segmentation reveals distinct service intensity profiles across product formats and delivery channels. Injectable solutions demand immediate technical support and cold chain logistics, while research applications require specialized pharmacovigilance documentation.
Product Type:
After-sales service intensity varies dramatically across formulation formats, with parenteral products requiring field technical support and stability monitoring that oral formats rarely need.
- Injectable Solution:Sterile aqueous formulations containing atipamezole hydrochloride achieve immediate bioavailability through intramuscular or intravenous routes. Demand concentrates in United States emergency veterinary hospitals where fifteen-minute reversal timelines are mandatory for critical care protocols.
- Oral Solution:Palatable liquid suspensions enable outpatient sedation reversal in mobile veterinary practices lacking injection capabilities. Growth is accelerating in German rural companion animal networks where home-visit services are expanding.
- Tablet:Solid oral dosage forms offer extended stability and simplified logistics for field operations. Japanese zoological facilities favor these for avian and reptile collections where parenteral administration risks tissue trauma.
- Intranasal Spray:Mucosal absorption formulations bypass first-pass metabolism for rapid onset without injection stress. Emerging applications in feline practices are gaining traction in United Kingdom specialist clinics.
By volume, Injectable Solution leads. By growth pace, Intranasal Spray is ahead.
End User:
Cost tier stratification separates institutional buyers with consolidated purchasing power from fragmented independent operators.
- Veterinarians:Individual practitioners and small partnerships represent the price-sensitive base of the market, often delaying purchases until generic alternatives become available.
- Animal Clinics:Multi-doctor facilities with in-house pharmacy capabilities capture economies of scale through direct manufacturer contracts. United States corporate veterinary groups in California and Texas are displacing wholesale intermediaries.
- Research Institutions:Universities and contract research organizations drive off-label protocol innovation. Translational neuropharmacology studies at German Max Planck institutes are expanding alpha-2 antagonist applications beyond veterinary boundaries.
- Zoos:Specialized exotic animal collections require customized dosing regimens and extended veterinary support. Osaka and Tokyo zoological gardens are extending anesthesia reversal protocols to reptile and avian species under METI modernization grants.
By procurement scale, Animal Clinics dominate. By application expansion, Research Institutions are climbing the fastest.
Application:
Customer type differentiation separates emergency responders needing immediate availability from scheduled procedure planners.
- Reversal Agent:Primary indication for counteracting dexmedetomidine or medetomidine sedation in routine surgical recovery. Standard protocol compliance drives volume in Japanese companion animal hospitals.
- Sedation Recovery:Post-operative monitoring applications emphasize cardiovascular parameter normalization. German veterinary anesthesiology specialists prioritize this segment for ACVAA certification compliance.
- Emergency Care:Time-critical interventions for sedation overdose or adverse cardiovascular events. United States 24-hour referral hospitals embed atipamezole in crash cart inventories.
- Diagnostic Procedures:Controlled reversal for imaging and endoscopic examinations requiring patient cooperation. Outpatient diagnostic centers in United Kingdom urban markets are adopting rapid-recovery protocols.
By protocol standardization, Reversal Agent leads. By urgency premium capture, Emergency Care is gaining share fastest.
Distribution Channel:
Supply concentration determines margin allocation between manufacturer, intermediary, and end user.
- Online Pharmacies:Digital platforms serving remote and rural veterinarians with 48-hour delivery guarantees. Regulatory compliance with state veterinary pharmacy boards constrains expansion.
- Retail Pharmacies:Traditional brick-and-mortar channels with compounding capabilities for customized formulations. European independent pharmacy networks maintain regional presence.
- Direct Sales:Manufacturer-to-clinic relationships eliminating distributor markups. Corporate veterinary groups in United States negotiate volume-based tenders capturing thirty to forty point margin improvements.
- Veterinary Clinics:In-house dispensing for immediate patient administration. Tertiary referral hospitals with 24-hour emergency services maintain highest inventory turnover.
By transaction volume, Veterinary Clinics lead. By margin compression, Direct Sales is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese procurement channels, while United States distributors absorb compressed margins from consolidated veterinary group purchasing. Regulatory divergence between FDA pharmacovigilance mandates and EMA centralized pathways is fragmenting compliance costs across jurisdictions.
United States
Corporate veterinary networks in California and Texas negotiate direct manufacturer contracts, displacing wholesale intermediaries that previously captured substantial margin. FDA Center for Veterinary Medicine tightened 2023 bioequivalence guidance for generic atipamezole, elevating development costs for abbreviated new animal drug applications. Emergency veterinary infrastructure in metropolitan Dallas and Los Angeles embeds rapid-reversal protocols as standard crash cart inventory.
Germany
Max Planck institutes and contract research organizations drive off-label alpha-2 antagonist applications in translational neuropharmacology studies. EMA centralized authorization procedures streamline veterinary product approvals across EU member states, reducing time-to-market barriers. Bavarian veterinary anesthesiology specialists prioritize ACVAA certification compliance, anchoring demand for advanced sedation recovery protocols in Munich and Nuremberg referral hospitals.
Japan
METI-supported veterinary modernization programs extend anesthesia reversal protocols to avian and reptile collections in zoological settings. PMDA oversight governs pharmaceutical manufacturing quality and import compliance for veterinary therapeutics. Osaka and Tokyo zoological gardens under METI grants are adopting customized atipamezole dosing regimens for exotic species collections.
United Kingdom
Specialist feline clinics in London and Birmingham pioneer intranasal spray formulations for rapid sedation reversal without injection stress. The Veterinary Medicines Directorate enforces pharmacovigilance reporting aligned with EMA standards. Urban outpatient diagnostic centers across Greater Manchester adopt rapid-recovery protocols for imaging and endoscopic examinations requiring patient cooperation.
Atipamezole Market Vendor Landscape
Integrated animal health conglomerates and specialized anesthesia reversal formulators split the market into distinct capability tiers. Consolidation pressure from corporate veterinary purchasing alliances favors scale players with direct distribution infrastructure. Three archetypes dominate: diversified pharmaceutical majors leveraging companion animal franchises, European specialists tailoring formulations to regional regulatory standards, and emerging platform companies extending into exotic animal segments. Competitive dynamics center on backward integration into API supply and geographic expansion through METI-supported Japanese modernization programs.
Within the diversified pharmaceutical tier, Zoetis Inc. and Merck & Co., Inc. occupy positions shaped by companion animal hospital penetration and direct sales infrastructure. Orion Corporation exemplifies the European specialist archetype, with formulation science capabilities aligned to EMA veterinary product standards. Vetoquinol S.A. represents the distribution-focused model, extending reach into emerging veterinary service networks through regional pharmacy relationships.
| Leading Market Players |
|---|
| Zoetis Inc. |
| Orion Corporation |
| Pfizer Inc. |
| Merck & Co., Inc. |
| Elanco Animal Health Incorporated |
| Vetoquinol S.A. |
| Virbac S.A. |
| Modern Veterinary Therapeutics |
| Alvetra u. Werfft GmbH |
| Others |
Supply Flow & Price Mechanics
Specialized European API manufacturing capacity running at tight utilization is forcing veterinary pharmaceutical sponsors into longer-term offtake commitments and advance payment structures to secure atipamezole hydrochloride supply. This capacity constraint simultaneously elevates input costs for formulation developers and compresses margin flexibility for finished dose manufacturers negotiating with consolidated corporate veterinary purchasers.
Pricing Analysis
Configured-to-order pricing for customized exotic animal dosing regimens commands substantial premiums over standard companion animal formulations in Japanese zoological and German research applications. Pricing stratifies across premium, standard, and economy tiers based on formulation complexity and after-sales veterinary support bundling. Cost compression in standard injectable solutions is intensifying because corporate veterinary groups in California and Texas negotiate direct manufacturer contracts eliminating wholesale markups. Individual practitioners and small partnerships represent the most price-sensitive segment, often delaying purchases until generic alternatives become available.
Supply Chain Analysis
Export-control scrutiny over advanced pharmaceutical manufacturing equipment limits capacity expansion for European contract manufacturers producing high-purity atipamezole hydrochloride. Synthesis of active pharmaceutical ingredient concentrates among specialized European contract manufacturers, with formulation and packaging operations distributed across United States, Germany, and Japan. Raw material dependencies include specialized chemical precursors, sterile packaging components, and cold chain logistics infrastructure. Single-source vulnerability in API supply creates structural risk for formulation developers. Distribution runs through direct manufacturer-to-clinic relationships for corporate veterinary networks, with traditional wholesale channels serving independent practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as emergency veterinary infrastructure upgrades create service-level niches between tertiary referral hospitals and mid-tier companion animal clinics. Demand-side shift toward 24-hour critical care protocols in metropolitan markets is spawning underserved segments requiring differentiated product formats.
For Market Incumbents: Build regulatory moat through early EMA scientific advice consultations and FDA pharmacovigilance compliance infrastructure ahead of generic competitor entry. Secure backward integration into API supply through long-term offtake agreements with European contract manufacturers. Expand direct sales infrastructure to capture margin from consolidated corporate veterinary group purchasing in United States metropolitan markets. For New Entrants and Emerging Players: Pursue white-space opportunities in Japanese exotic animal anesthesia reversal protocols supported by METI modernization grants. Target German translational research institutions expanding alpha-2 antagonist applications beyond standard veterinary boundaries. Leverage prefilled syringe delivery formats as go-to-market angle for field veterinary operations requiring USDA biosecurity compliance. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across lyophilized powder-for-injection manufacturing capacity as FDA bioequivalence guidance elevates development costs. Long-term viability favors platform companies with cross-species formulation capabilities spanning companion animals through exotic collections. Acquisition target archetype: European specialists with EMA-aligned formulation science and established API supplier relationships. Signal to watch: METI grant disbursement velocity for veterinary modernization programs as inflection indicator for Japanese market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Scientific Advice Consultation | Front-loads regulatory alignment to preempt divergence between FDA and European authorization pathways. |
| Backward Integration into API Supply | Captures margin from specialized European contract manufacturers facing capacity constraints. |
| Prefilled Syringe Format Development | Eliminates compounding steps in emergency scenarios while aligning with USDA biosecurity standards. |
| Direct Manufacturer-to-Clinic Contracts | Displaces wholesale intermediaries capturing thirty to forty point margin improvements in corporate veterinary networks. |
| Lyophilized Powder-for-Injection Manufacturing Scale-Up | Collapses reconstitution variability that previously delayed sedation reversal in high-stress clinical environments. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with veterinary pharmaceutical executives, regulatory affairs specialists, emergency veterinary hospital directors, and corporate veterinary group procurement managers; and secondary validation through FDA Center for Veterinary Medicine filings, EMA centralized authorization procedure documentation, and METI veterinary modernization program disclosures. Bottom-up and top-down triangulation cross-referenced manufacturer shipment data with institutional purchasing records across United States, German, and Japanese markets.
Forecast inputs considered formulation type segmentation, end-user institutional scale, application urgency tiers, and distribution channel concentration across the projection horizon. CAGRs were derived from modeled adoption curves for rapid-reversal anesthesia protocols in emergency veterinary infrastructure upgrades. Industry-specific inputs included ACVAA diplomate certification expansion rates and METI grant allocation trajectories for exotic animal anesthesia programs.
Sensitivities concentrate around regulatory divergence between FDA pharmacovigilance mandates and EMA centralized pathways, API supply disruptions from European contract manufacturer concentration, and substitution risk from dexmedetomidine-sparing protocols using benzodiazepine-ketamine combinations. Forecasts reflect assumptions regarding sustained corporate veterinary consolidation and continued METI program support. Material shifts in FDA bioequivalence guidance stringency or EMA authorization timeline compression would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
Isocitrate Dehydrogenase (IDH) Inhibitors Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Biopharmaceutical Excipients Market
Biopharmaceuticals
Spain Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
Chronic Phase Markers Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Pruritus Therapeutics Market
Biopharmaceuticals
Global Seasonal Influenza Vaccine Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
In Situ Gel Drug Delivery Market
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Insulin Syringes Market
Biopharmaceuticals
Benzbromarone API Market