
 Purified Protein Derivative Market | 2026-2036
Purified Protein Derivative Market Size, Share, and Industry Trends Forecast 2026-2036
Purified Protein Derivative Market Analysis
The gap between premium-grade tuberculin validated for national screening programs and commodity research reagents is restructuring procurement dynamics across the PPD value chain. Sanofi Pasteur leverages its historical position in BCG-derived biologics to sustain supply relationships with national immunization programs. Zoetis competes in veterinary tuberculosis diagnostics, where regulatory differentiation for bovine PPD creates specialized margin pools distinct from human health applications.
Purified Protein Derivative is a sterile precipitate of proteins extracted from Mycobacterium tuberculosis culture filtrates, standardized to contain defined tuberculin units per dose for intradermal diagnostic testing. Its primary commercial purpose centers on detecting latent tuberculosis infection through delayed-type hypersensitivity reactions, with potency calibrated against WHO international reference standards. Diagnostic tests command the largest revenue share within product type segmentation, while clinical research applications are expanding fastest as pharmaceutical sponsors integrate PPD into vaccine trial immunogenicity protocols. Hospitals anchor end-user demand through high-volume screening mandates, though academic institutions are gaining procurement share where investigator-initiated tuberculosis studies require certified reagent batches.
FDA potency standards and WHO prequalification pathways govern market access for human diagnostic tuberculin, with batch release testing requirements shaping manufacturer compliance costs and regional distribution eligibility. EMA's centralized marketing authorization framework for tuberculin PPD adds a parallel regulatory gate for European commercial entry, particularly affecting suppliers without established notified body relationships. Stakeholders must monitor evolving national tuberculosis program tender specifications, as shifting from monobacterial to comparative skin test protocols would recalibrate demand across PPD product grades and supplier qualification thresholds.
Market Dynamics
WHO prequalification requirements are compressing supplier eligibility for human diagnostic tuberculin, forcing manufacturers to absorb batch-release testing costs that commodity-grade producers cannot sustain. This regulatory tightening is bifurcating procurement channels between certified national program suppliers and research-grade vendors.
Growth Catalysts
- India's Revised National Tuberculosis Control Program:Government-funded screening mandates across district hospitals are expanding standardized PPD procurement volumes through centralized tender mechanisms.
- IFN-gamma release assay validation protocols:Comparative skin testing requirements in vaccine trials are pulling certified tuberculin batches into pharmaceutical sponsor supply chains.
- Bovine tuberculosis eradication frameworks:Veterinary diagnostic programs in dairy-intensive regions are creating parallel demand streams for species-specific PPD formulations.
Market Restraints
- Mycobacterial culture filtrate supply concentration:BCG strain banks and seed lot maintenance capabilities cluster within a limited set of national reference laboratories.
- FDA potency standard compliance costs:Batch release testing against international reference standards imposes fixed cost burdens that scale poorly for low-volume manufacturers.
- Interferon-gamma blood test substitution:IGRA platforms are capturing latent TB detection volume in private healthcare settings where skin test administration logistics deter adoption.
Strategic Opportunities
- Sub-Saharan Africa national program integration:WHO prequalification pathways offer first-mover positioning for suppliers meeting decentralized cold chain distribution requirements.
- Multiplex skin test convergence:Combined tuberculin and non-tuberculous mycobacterial antigen formulations are enabling differentiated product positioning in comparative diagnostic protocols.
- Direct-to-laboratory distribution channels:E-procurement platforms for academic research institutions are bypassing traditional distributor markups on certified reagent batches.
Industry Challenges
- Reference standard calibration expertise scarcity:WHO international standard maintenance and potency assay validation require specialized biochemistry capabilities concentrated in legacy national control laboratories.
- Multi-year tender lock-in cycles:National tuberculosis program procurement contracts extend 3-5 years, freezing supplier switching and compressing pricing negotiation windows.
- Legacy cold chain infrastructure gaps:Last-mile distribution to district-level health facilities in tropical climates strains temperature-controlled logistics networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Purified Protein Derivative Market |
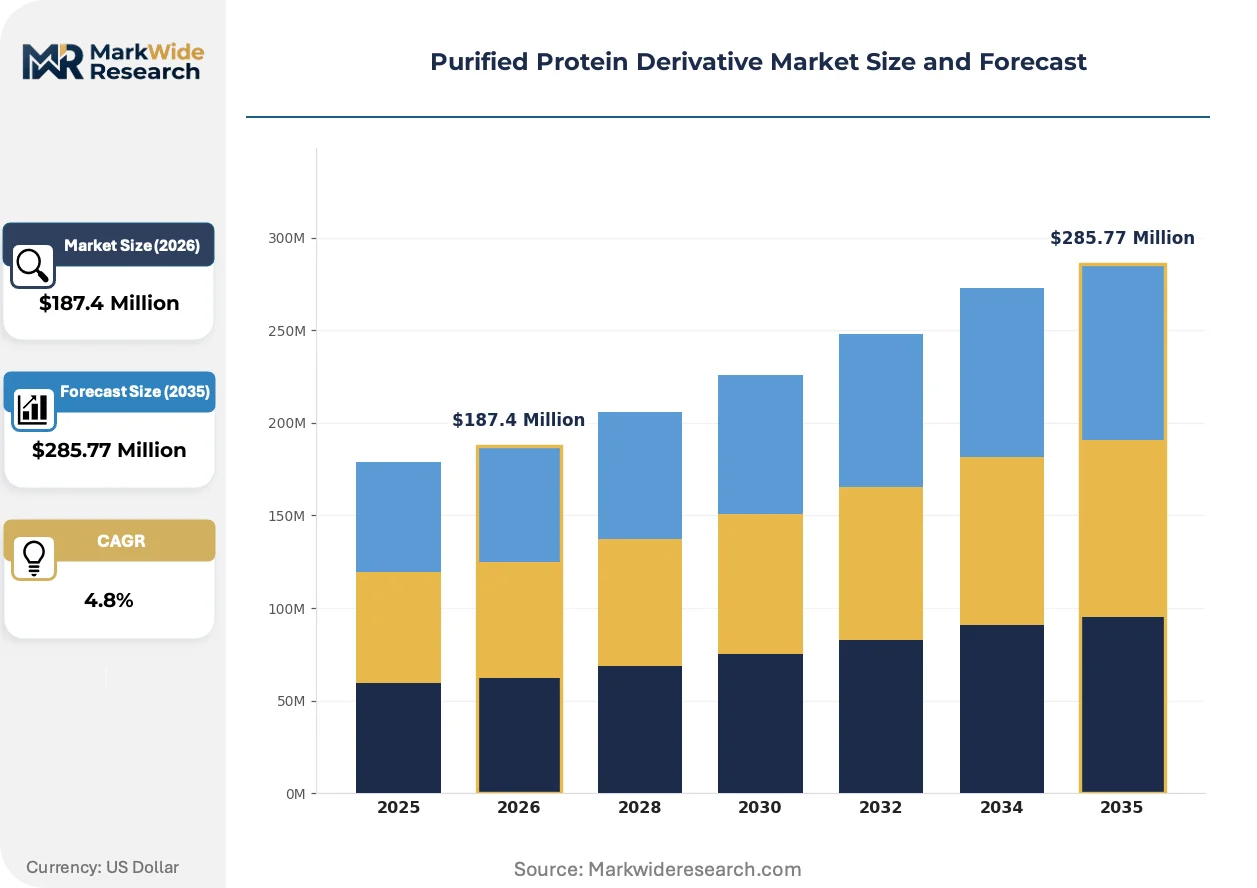
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tuberculin, Diagnostic Tests, Research Reagents, Therapeutic Agents Application: Diagnostic Imaging, Allergy Testing, Vaccine Development, Clinical Research End User: Hospitals, Laboratories, Academic Institutions, Pharmaceutical Companies Distribution Channel: Direct Sales, Online Retailers, Medical Supply Distributors, Wholesalers |
| Companies Covered | Sanofi Pasteur, Zoetis, Statens Serum Institut, Par Sterile, Japan BCG Laboratory, Thermo Fisher, Sanroad Biological, CNBG, CZ Veterinaria, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Purified Protein Derivative Market Emerging Trajectories
Diagnostic protocol standardization is absorbing digital traceability requirements and antigen manufacturing advances into tuberculin production workflows. These shifts are compressing the gap between research-grade and clinical-grade supply chains.
Lyophilized PPD formulations are absorbing moisture-stability advantages that extend shelf life beyond liquid alternatives. National reference laboratories in Brazil and South Africa are adopting these formats for decentralized distribution networks. The technology is absorbing cost premiums from cold chain reduction into procurement budgets previously allocated to logistics.
EMA's centralized marketing authorization framework for tuberculin PPD is tightening documentation requirements for master seed lot traceability. Manufacturers without established notified body relationships face extended timeline risks for European commercial entry. Hospital networks in Germany and France are consolidating procurement around suppliers holding MDR-compliant technical files.
Academic medical centers are unbundling reagent procurement from contract research organization service packages. Principal investigators running investigator-initiated tuberculosis studies are sourcing certified PPD batches directly through institutional purchasing offices. This pattern is most visible in US academic health systems where NIH-funded trials require documented chain-of-custody for immunogenicity endpoints.
Purified Protein Derivative Market Segmentation
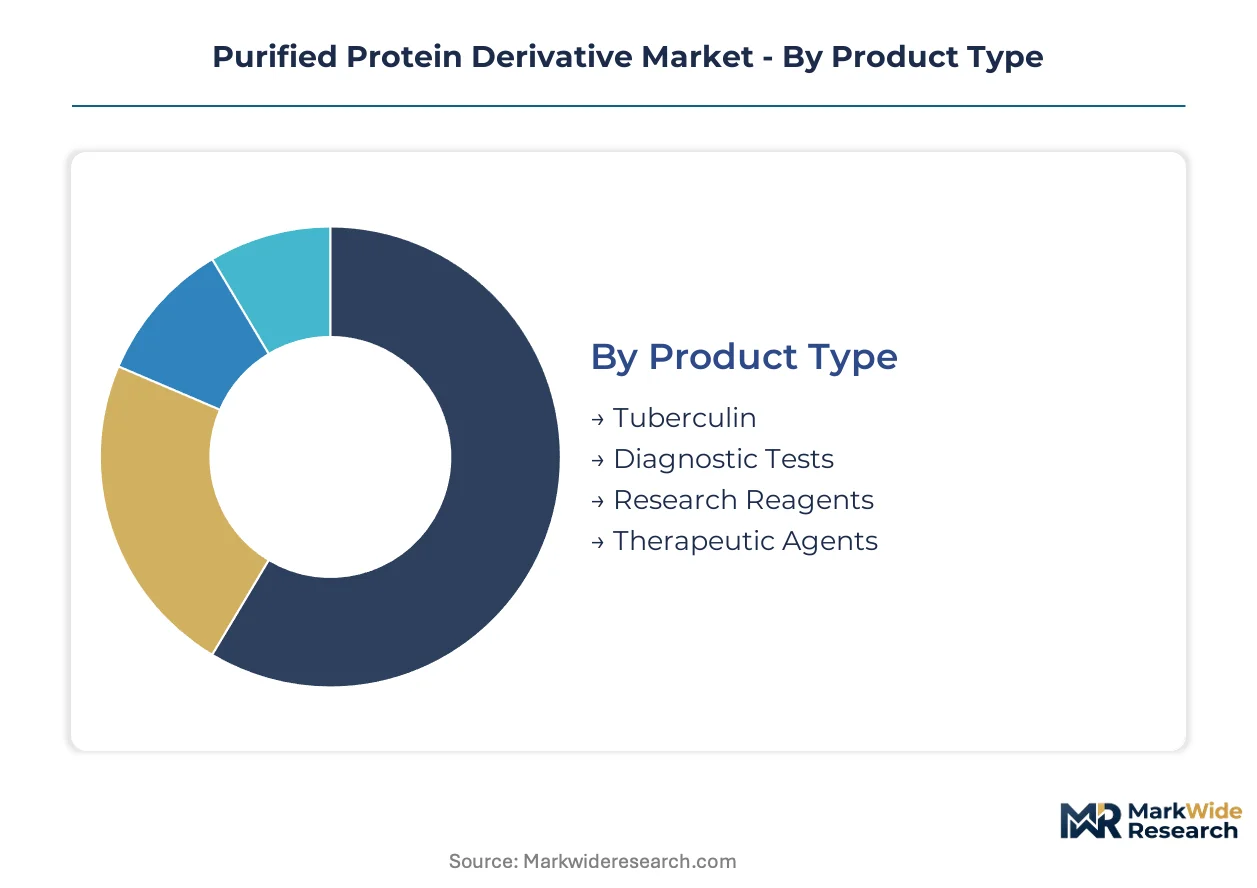
PPD procurement patterns fragment sharply across product grades, with WHO-prequalified clinical batches commanding premium positioning against commodity research alternatives. Segmentation discipline separates certified diagnostic workflows from exploratory research applications, each carrying distinct regulatory baggage and margin profiles.
Product Type:
Upgrade cycles differentiate certified clinical stock from research-grade alternatives, with potency validation requirements forcing periodic supplier recertification.
- Tuberculin:Standardized precipitate of Mycobacterium tuberculosis culture filtrates calibrated to WHO international reference standards. Hospital networks in India anchor procurement volumes through centralized national program tenders, though batch release testing costs compress supplier margins.
- Diagnostic Tests:Pre-formulated intradermal test kits incorporating stabilized PPD with administration devices. Demand concentrates in district-level health facilities across India's Revised National Tuberculosis Control Program, where standardized screening mandates override price sensitivity.
- Research Reagents:Bulk PPD formulations for investigator-initiated studies and pharmaceutical immunogenicity protocols. Academic medical centers in the United States source directly through institutional purchasing offices to satisfy NIH chain-of-custody requirements.
- Therapeutic Agents:Specialized formulations for immunotherapy applications and desensitization protocols. Niche positioning limits volume scale to select tertiary care centers with established mycobacterial therapy programs.
Volume placements concentrate in Tuberculin; the faster expansion belongs to Diagnostic Tests.
Application:
Application segmentation tracks the divergence between regulated clinical workflows and exploratory pharmaceutical development, with each pathway imposing distinct documentation burdens.
- Diagnostic Imaging:PPD-based hypersensitivity assessment integrated with radiographic confirmation protocols for active tuberculosis exclusion. India's district hospital networks drive procurement scale through mandatory latent TB infection screening before biologic therapy initiation.
- Allergy Testing:Comparative skin test applications for non-tuberculous mycobacterial sensitivity profiling. Veterinary diagnostic programs in dairy-intensive regions deploy species-specific formulations for bovine tuberculosis eradication frameworks.
- Vaccine Development:Immunogenicity endpoint validation in tuberculosis vaccine clinical trials. Pharmaceutical sponsors absorb certified tuberculin batches into comparator arm protocols, with FDA potency standards governing batch qualification.
- Clinical Research:Mechanistic studies of cellular immune response and delayed-type hypersensitivity kinetics. Academic institutions bypass traditional distributor markups through direct-to-laboratory e-procurement platforms.
Diagnostic Imaging captures the dominant procurement share; Vaccine Development is climbing the fastest as trial pipelines expand.
End User:
Customer type segmentation exposes the procurement authority split between centralized government tenders and decentralized institutional purchasing.
- Hospitals:High-volume screening mandates across inpatient and outpatient settings. India's public health infrastructure scales PPD consumption through state-level medical college hospital networks with cold chain distribution requirements.
- Laboratories:Reference testing facilities and quality control laboratories maintaining national standard calibration. Brazil and South Africa's national reference laboratories adopt lyophilized formulations for decentralized network stability.
- Academic Institutions:University-affiliated medical centers running investigator-initiated tuberculosis studies. Principal investigators require documented batch certification for NIH-funded trial immunogenicity endpoints.
- Pharmaceutical Companies:Vaccine sponsors integrating PPD into Phase II/III trial comparator arms. EMA's centralized marketing authorization framework shapes European supplier selection around MDR-compliant technical files.
Hospitals dominate absolute volume; Academic Institutions are gaining share fastest through unbundled reagent procurement.
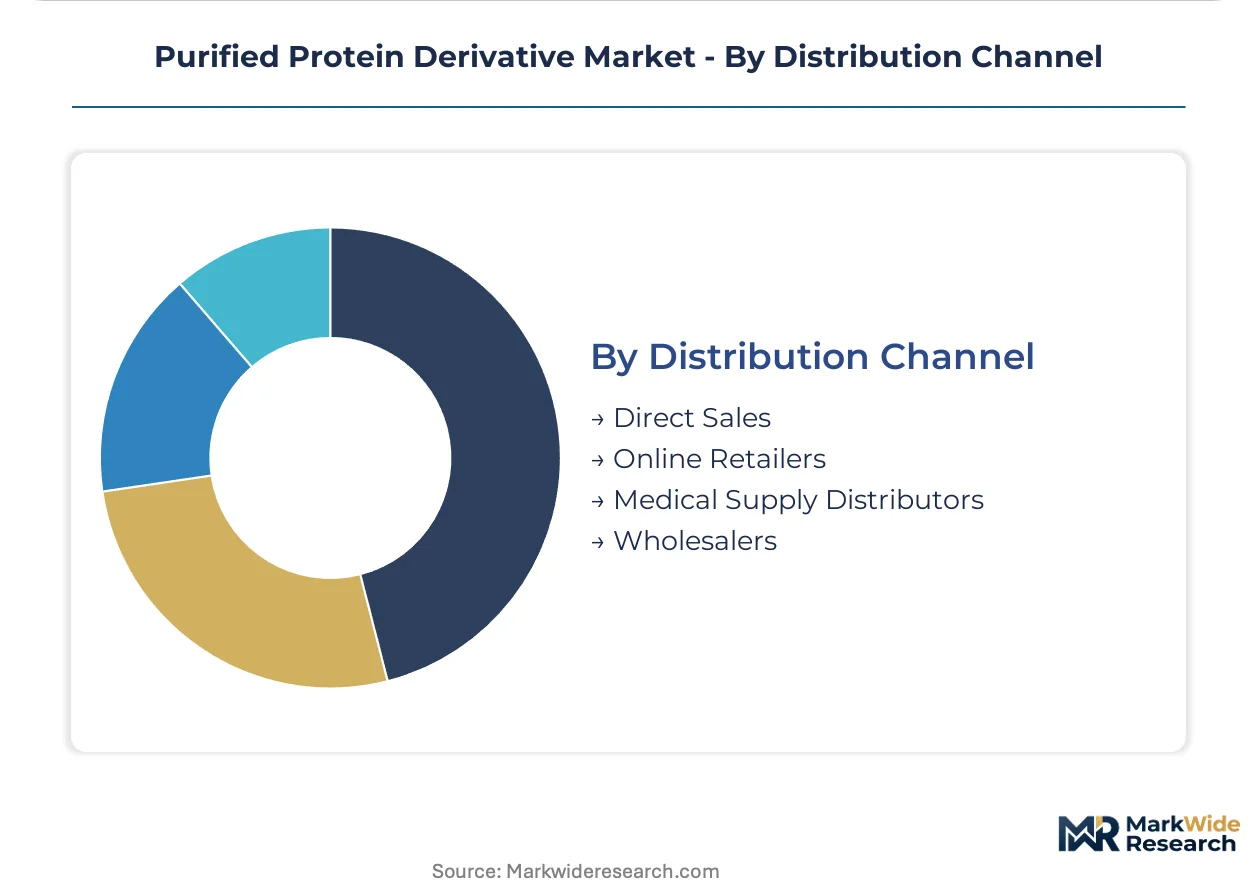
Distribution Channel:
Channel structure reflects the tension between national program tender consolidation and research market fragmentation.
- Direct Sales:Manufacturer relationships with national tuberculosis programs and reference laboratories. Multi-year tender lock-in cycles freeze supplier switching and compress pricing negotiation windows for human diagnostic tuberculin.
- Online Retailers:E-procurement platforms serving academic research institutions with certified reagent batches. Direct-to-laboratory channels bypass traditional distributor markups in United States academic health systems.
- Medical Supply Distributors:Regional wholesalers handling cold chain logistics for district-level health facilities. Last-mile distribution to tropical climates strains temperature-controlled networks.
- Wholesalers:Bulk procurement aggregators for veterinary PPD formulations in dairy-intensive markets. Species-specific regulatory differentiation creates specialized margin pools distinct from human health applications.
Direct Sales commands the largest placement volume; Online Retailers show the steepest expansion trajectory as academic procurement digitizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors procurement volume for PPD diagnostics through India's centralized vaccine and biologics distribution networks. The city's national reference laboratory infrastructure calibrates potency standards for subcontinental screening programs.
India
District hospital networks under the Revised National Tuberculosis Control Program absorb standardized tuberculin batches through state-level medical college procurement. CDSCO batch release protocols govern import and domestic manufacturing quality benchmarks. Cold chain distribution from Hyderabad radiates to tropical climates where lyophilized formulations reduce logistics strain.
United States
Academic medical centers in Boston and the Research Triangle unbundle reagent procurement from contract research organization service packages. FDA potency standards mandate documented chain-of-custody for NIH-funded trial immunogenicity endpoints. Principal investigators at Johns Hopkins and Stanford source certified batches through institutional purchasing offices.
Brazil
ANVISA governs marketing authorization for diagnostic tuberculin while national reference laboratories in São Paulo adopt lyophilized formats for decentralized network stability. Dairy-intensive regions in Minas Gerais deploy species-specific veterinary PPD formulations under bovine tuberculosis eradication frameworks. Public health infrastructure scales screening through SUS procurement channels.
Germany
EMA's centralized marketing authorization framework shapes European commercial entry around MDR-compliant technical files. Hospital networks in Bavaria and North Rhine-Westphalia consolidate procurement around suppliers holding notified body relationships. Berlin-based reference laboratories maintain WHO international standard calibration for regional potency assays.
South Africa
National reference laboratories in Johannesburg and Cape Town adopt moisture-stable lyophilized formulations for last-mile distribution to district health facilities. The country's tuberculosis program integrates PPD screening with HIV co-infection protocols across public health infrastructure. Cold chain gaps in tropical climates drive formulation preferences toward extended shelf-life alternatives.
Purified Protein Derivative Market Vendor Landscape
Premium-margin players sit above commodity-margin players across WHO prequalification status and batch certification tiers. The supplier base concentrates around legacy national reference laboratories and pharmaceutical biologics manufacturers with BCG strain bank access. Three archetypes dominate: prequalified national program suppliers, veterinary diagnostic specialists, and research-grade commodity vendors. Competitive positioning hardens through multi-year tender lock-in cycles and M&A targeting regional distribution capabilities.
Within the prequalified human diagnostic tier, Sanofi Pasteur and Statens Serum Institut occupy positions anchored to historical BCG-derived biologics supply relationships. Zoetis exemplifies the veterinary specialization archetype, where species-specific regulatory differentiation creates margin pools distinct from human health applications. Japan BCG Laboratory represents the national reference laboratory model with integrated seed lot maintenance and potency calibration capabilities.
| Leading Market Players |
|---|
| Sanofi Pasteur |
| Zoetis |
| Statens Serum Institut |
| Par Sterile |
| Japan BCG Laboratory |
| Thermo Fisher |
| Sanroad Biological |
| CNBG |
| CZ Veterinaria |
| Others |
Supply Flow & Price Mechanics
India's Revised National Tuberculosis Control Program tender specifications for WHO-prequalified tuberculin batches are forcing manufacturers to absorb batch-release testing costs that commodity-grade suppliers cannot sustain, compressing viable supply to certified national program vendors and widening price spreads between clinical and research grades.
Pricing Analysis
Value-based pricing anchored to WHO prequalification status separates certified diagnostic batches from research-grade alternatives. Three-tier pricing structure across premium clinical, standard institutional, and economy research tiers reflects certification burden and potency validation rigor. Cost compression in the economy tier intensifies as academic buyers unbundle procurement through direct e-platforms. National tuberculosis programs exhibit lowest price sensitivity due to mandatory screening mandates, while principal investigators running NIH-funded trials absorb premium markups for documented chain-of-custody.
Supply Chain Analysis
Regional distribution centers in Hyderabad, São Paulo, and Johannesburg anchor hub-and-spoke patterns radiating to district health facilities. Manufacturing concentrates in India, Denmark, and Japan where BCG strain banks and seed lot maintenance capabilities cluster. Raw material dependencies include mycobacterial culture filtrates, master seed lots, and international reference standards. Single-source vulnerability around WHO international standard calibration expertise strains supplier qualification timelines. Distribution runs through temperature-controlled medical supply networks with last-mile cold chain gaps in tropical climates driving lyophilized formulation preferences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
WHO prequalification requirements function as a cost-of-compliance moat, with FDA potency standards and CDSCO batch release protocols creating barrier-to-entry dynamics that favor incumbent national reference laboratories over speculative entrants.
For Market Incumbents: Extend potency calibration service offerings into adjacent national reference laboratories lacking WHO international standard maintenance capabilities. Deepen backward integration into BCG seed lot banking to defend against emerging biologics manufacturers seeking strain access. Lock in multi-year tender positions across India's state-level medical college hospital networks before contract renewal windows compress. For New Entrants and Emerging Players: The price-point gap between premium WHO-prequalified clinical batches and uncertified research reagents opens white-space positioning for mid-tier institutional suppliers. Target academic medical centers in the United States running investigator-initiated tuberculosis studies with direct-to-laboratory e-procurement channels. Pursue veterinary tuberculosis diagnostic programs in dairy-intensive regions where species-specific regulatory differentiation creates specialized margin pools distinct from human health applications. For Investors and Strategic Acquirers: The window for entry favors vertically integrated biologics manufacturers with captive BCG strain banks and established notified body relationships. Long-term viability hinges on regulatory certification durability rather than volume scale alone. Watch for shifting national tuberculosis program tender specifications from monobacterial to comparative skin test protocols as the signal for demand recalibration across PPD product grades.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilized Formulation Scale-Up | Moisture-stable formats reduce cold chain strain for Brazil and South Africa's decentralized networks. |
| Direct-to-Laboratory E-Procurement Launch | Bypasses distributor markups for Johns Hopkins and Stanford principal investigators sourcing certified batches. |
| WHO Prequalification Pathway Investment | Unlocks first-mover positioning in Sub-Saharan Africa national program integration opportunities. |
| Multiplex Skin Test Development | Combined tuberculin and non-tuberculous mycobacterial antigens enable differentiated comparative diagnostic protocols. |
| Regional Distribution Center Expansion | Hyderabad and São Paulo hubs anchor last-mile reach to tropical district health facilities. |
Methodological Framework
Document review covered WHO prequalification databases, CDSCO batch release records, and national tuberculosis program tender specifications, complemented by interviews with diagnostic reagent procurement managers at Indian state medical colleges, reference laboratory directors in Brazil and South Africa, pharmaceutical sponsor clinical operations leads, and academic principal investigators at US academic health centers. Secondary validation drew from FDA potency standard documentation, EMA centralized marketing authorization frameworks, and NIH grant award databases for tuberculosis immunogenicity studies. Bottom-up procurement volume estimates triangulated against top-down national program budget allocations.
Cross-referencing historical tender award patterns with expert panel input on shifting diagnostic protocol preferences shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product grade tier, application workflow type, end-user procurement authority, and regional regulatory cluster. CAGRs derived from regression against national tuberculosis program expansion trajectories and pharmaceutical trial pipeline density. Industry-specific inputs incorporated lyophilized formulation adoption curves and IGRA substitution rates in private healthcare settings.
Inputs from WHO prequalification status registries and national reference laboratory certification records were available through the study window; gaps in multi-year tender contract pricing introduce uncertainty bands around supplier margin estimates. Forecasts reflect assumptions on regulatory pathway stability and cold chain infrastructure investment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Tamiflu (Oseltamivir Phosphate) Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Europe Plasma Fractionation Market
Biopharmaceuticals
Beta Interferon Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
Antibody Pair Kits Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Glycoprotein Market
Biopharmaceuticals
Global Biologics Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Cancer Drug Market
Biopharmaceuticals
Rivaroxaban Market