
 Magnesium Carbonate Market | 2026-2036
Magnesium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Carbonate Market Intelligence
Asset-light leasing arrangements for calcination and grinding equipment is narrowing the capital barrier for mid-tier producers seeking furnace capacity without owning fixed assets. Grecian Magnesite leverages its integrated mining-to-refining footprint across Greek deposits to sustain cost advantages in heavy magnesium carbonate grades. Hebei Meishen Technology anchors its position through captive access to magnesite reserves in Hebei province, while Kyowa Chemical Industry differentiates via pharmaceutical-grade specialization that commands premium positioning in Japanese and Southeast Asian supply chains.
Magnesium carbonate is a white, odorless inorganic salt with the formula MgCO₃, typically synthesized through carbonation of magnesium hydroxide or mined as magnesite ore and processed to purities ranging from technical to food-grade and pharmaceutical specifications; it functions primarily as an alkalizing agent, filler, and processing aid across industrial and consumer formulations. Light magnesium carbonate dominates volume in pharmaceutical and food additive applications due to its superior surface area and reactivity, while heavy magnesium carbonate occupies mature demand channels in construction and fire retardant compounding where bulk density and cost efficiency outweigh performance refinement. The buffering agents application within pharmaceutical and nutritional formulations represents the most concentrated margin pool, as certification requirements for USP and EP grades create supply scarcity that rewards qualified producers.
FDA oversight of pharmaceutical excipients through ICH Q3D elemental impurity guidelines and USP monograph compliance shapes purity thresholds for magnesium carbonate entering drug formulations, while REACH registration and the EU Green Deal carbon border adjustments constrain import pathways for non-European producers seeking European market access. China's NMPA and GB standards for food-grade and pharmaceutical-grade magnesium salts impose parallel testing regimes that filter out uncertified suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and Chinese Pharmacopoeia standards, as divergence in heavy metal limits and microbial specifications threatens to fragment qualified supplier pools and redirect procurement toward multi-certified producers.
Market Dynamics
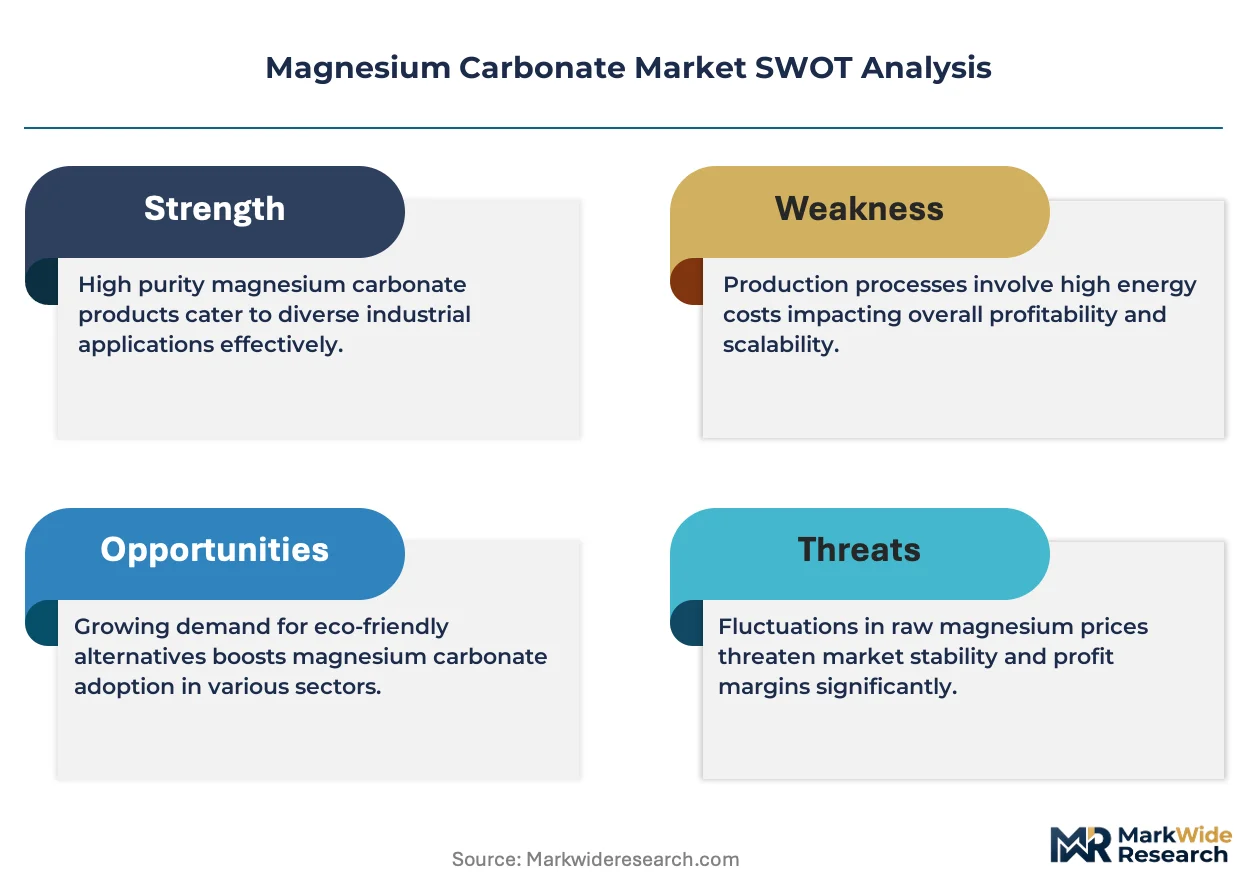
Pharmaceutical-grade certification requirements under USP and EP monographs are concentrating qualified supplier pools while calcination equipment leasing models lower capital barriers for mid-tier producers seeking furnace capacity without fixed asset ownership.
Growth Catalysts
- REACH and EU Green Deal carbon border adjustments:Tightening purity benchmarks for chemical imports into Europe are filtering uncertified suppliers and redirecting procurement toward multi-certified producers with compliant excipient portfolios.
- Tablet manufacturing expansion:Drug formulators seeking compliant alkalizing agents and fillers are absorbing rising volumes of light magnesium carbonate for its superior surface area and reactivity in direct compression processes.
- Construction fire retardant compounding:Heavy magnesium carbonate grades maintain mature demand channels where bulk density and cost efficiency outweigh performance refinement in building material formulations.
Market Restraints
- Magnesite ore supply concentration:Captive access to high-purity deposits in Hebei province and Greek mining districts creates geographic dependency for integrated producers.
- Calcination energy intensity:Thermal processing requirements for converting raw magnesite to reactive grades expose margins to natural gas and electricity price volatility.
- Calcium carbonate substitution:Lower-cost alkalizing agents compete in non-pharmaceutical applications where certification thresholds do not mandate magnesium-based excipients.
Strategic Opportunities
- Asset-light leasing arrangements:Equipment financing models for calcination and grinding capacity enable mid-tier producers to scale output without balance sheet expansion.
- Pharmacopeial harmonization gaps:Divergence in heavy metal limits between USP, EP, and Chinese Pharmacopoeia standards creates arbitrage potential for producers achieving multi-certification.
- Nutraceutical buffering applications:Sports nutrition and antacid formulations represent adjacent demand channels with lower regulatory barriers than prescription drug excipients.
Industry Challenges
- Elemental impurity testing capacity:ICH Q3D guideline compliance requires inductively coupled plasma mass spectrometry capabilities that strain analytical chemistry staffing at smaller producers.
- Microbial specification validation:USP and EP divergences in bioburden limits force dual validation protocols that extend batch release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Carbonate Market |
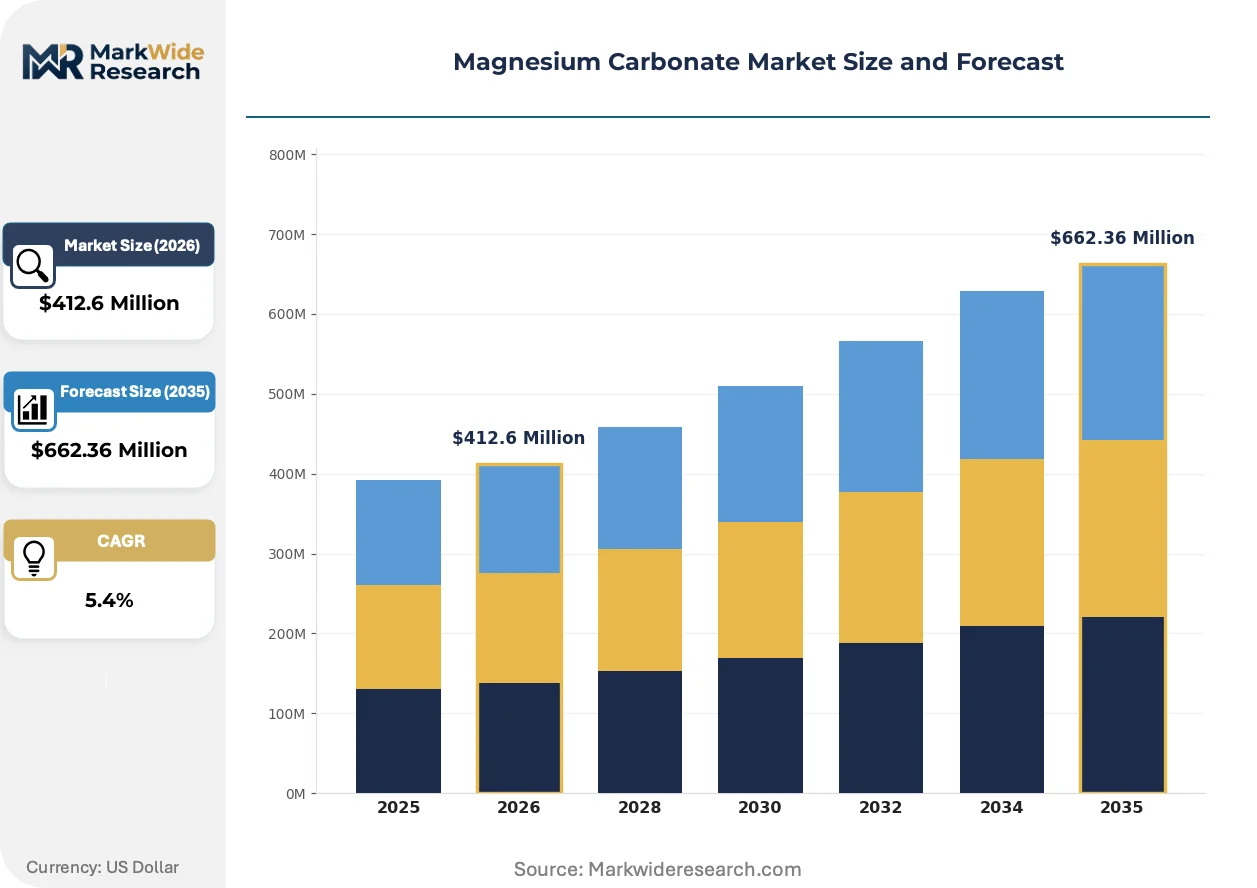
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $662.36 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Magnesium Carbonate, Heavy Magnesium Carbonate, Monohydrate, Anhydrous End Use Industry: Pharmaceuticals, Food Additives, Fire Retardants, Construction Materials Form: Powder, Granules, Tablets, Liquid Application: Buffering Agents, Anti-Caking Agents, Absorbents, Fertilizers |
| Companies Covered | Grecian Magnesite, Hebei Meishen Technology, FMC Corporation, Kyowa Chemical Industry, Lehmann & Voss, ICL Group, Konoshima Chemical, Magnesia International, Omya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Carbonate Market Strategic Shifts & Innovations
Process control technologies and regulatory data systems are compressing certification timelines while reshaping how producers demonstrate compliance across pharmacopeial jurisdictions.
Continuous carbonation reactor monitoring with inline particle size analyzers is digitizing quality assurance workflows for light magnesium carbonate synthesis. Pharmaceutical contract manufacturers in Japan and South Korea are adopting these systems fastest, replacing offline laboratory sampling with real-time release testing that compresses batch cycle times by eliminating quarantine periods.
EU Green Deal carbon border adjustment mechanisms are restructuring import economics for non-European magnesium carbonate suppliers. The phased implementation of embedded carbon reporting requirements is forcing Turkish and Chinese exporters to document Scope 1 and 2 emissions or face tariff penalties, with pharmaceutical-grade shipments facing the strictest documentation thresholds due to their higher value-to-weight ratios.
Direct procurement relationships between drug formulators and certified chemical producers are displacing traditional distributor intermediaries in excipient sourcing. Large pharmaceutical manufacturers in Germany and Switzerland are consolidating supplier lists to single-source magnesium carbonate for specific tablet lines, replacing multi-distributor procurement with audited direct contracts that embed quality agreements and audit rights.
Magnesium Carbonate Market Segmentation
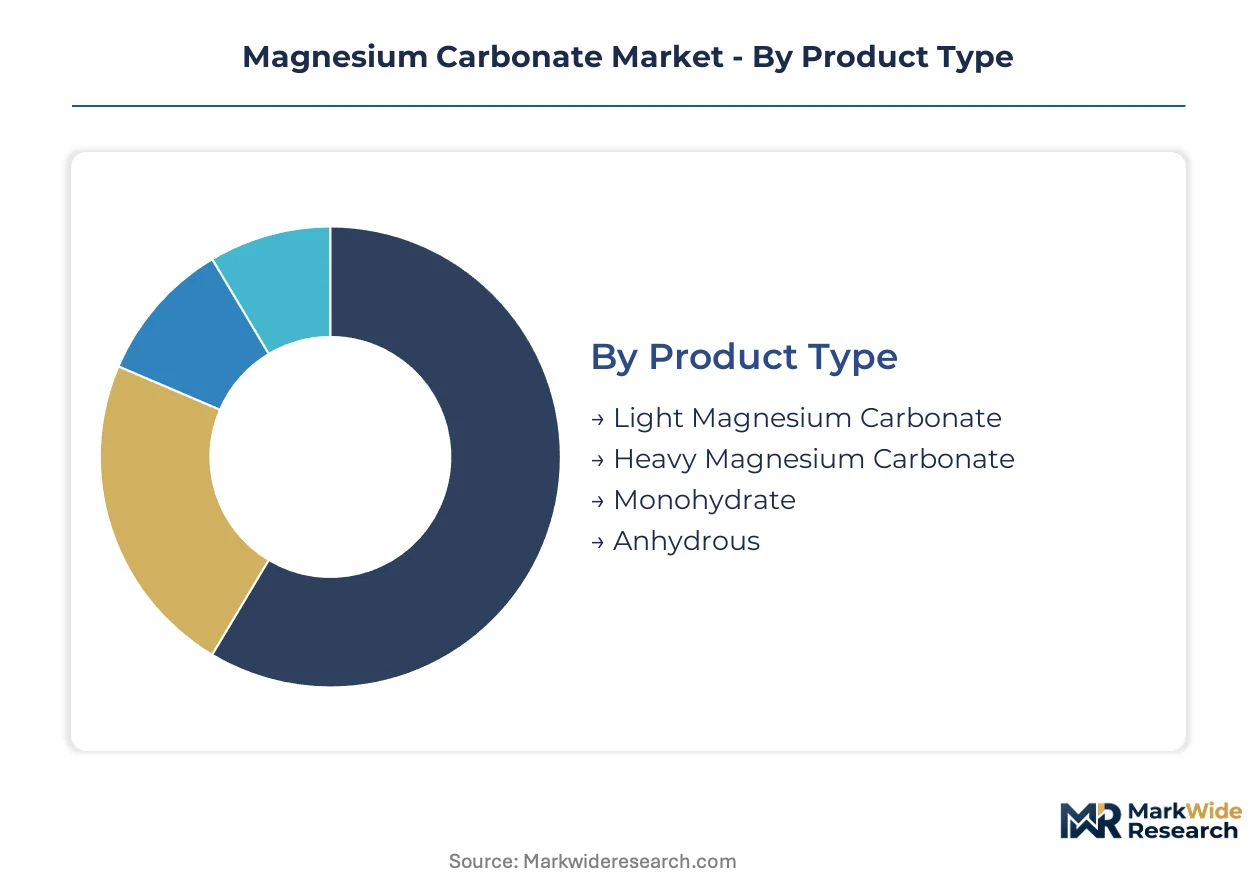
Magnesium carbonate segmentation reflects divergent purity requirements and processing economics across pharmaceutical, food, and industrial channels. Product density and hydration state determine reactivity profiles that align with specific formulation constraints. End-use certification tiers create non-substitutable demand pockets that resist cross-grade competition.
Product Type:
Density and hydration chemistry separate magnesium carbonate grades into distinct cost-performance tiers with limited interchangeability.
- Light Magnesium Carbonate:A low-density, high-surface-area form synthesized through carbonation of magnesium hydroxide slurry. Pharmaceutical tablet manufacturers in Japan and South Korea absorb the bulk of qualified supply for its superior compressibility and rapid dissolution in antacid formulations.
- Heavy Magnesium Carbonate:Denser crystalline material derived from direct magnesite calcination. Construction compounding and fire retardant masterbatch producers in China's Hebei province maintain mature procurement relationships based on bulk density specifications and freight efficiency.
- Monohydrate:Single-water molecule coordination compound offering intermediate stability between anhydrous and fully hydrated forms. Specialty ceramic glaze manufacturers specify this grade for controlled decomposition behavior during kiln firing.
- Anhydrous:Water-free magnesium carbonate requiring sealed storage and inert atmosphere handling. Desiccant and rubber accelerator applications in Germany's chemical processing corridor absorb limited volumes at premium pricing.
Heavy magnesium carbonate commands the established base. The steepest expansion runs through light magnesium carbonate.
End Use Industry:
Regulatory certification intensity varies sharply across end-use channels, concentrating margin capture in pharmaceutical and food-grade segments.
- Pharmaceuticals:USP and EP monograph compliance mandates ICH Q3D elemental impurity testing and validated microbial specifications. Direct compression tablet lines at Swiss and German drug formulators now specify single-source magnesium carbonate with embedded audit rights.
- Food Additives:E504(i) and E504(ii) designations under EU 231/2012 purity criteria govern acidity regulation in confectionery and flour treatment. Chinese GB 25587-2010 parallel standards create dual-certification requirements for exporters.
- Fire Retardants:Heavy-grade magnesium carbonate releases carbon dioxide and water vapor at elevated temperatures. Building material compounders in Turkey prioritize bulk density and thermal decomposition onset over purity refinement.
- Construction Materials:Magnesium oxychloride cement formulations and lightweight aggregate production consume technical-grade material. Greek mining districts supply integrated producers with captive magnesite conversion to finished construction chemicals.
Construction materials anchor volume throughput. Pharmaceuticals generate the steepest margin expansion trajectory.
Form:
Physical presentation determines handling economics and dissolution kinetics in downstream processing equipment.
- Powder:Fine particulate with particle size distributions typically spanning 1-45 microns. Fluid bed coating operations at Indian nutraceutical contract manufacturers prefer this form for uniform dispersion in antacid suspensions.
- Granules:Agglomerated particles with improved flow characteristics for high-speed tablet presses. Japanese pharmaceutical equipment OEMs specify granule specifications that minimize hopper bridging during continuous manufacturing.
- Tablets:Pre-compressed magnesium carbonate for direct use as effervescent bases or laboratory reagents. Analytical chemistry suppliers in Switzerland package certified reference materials in this format.
- Liquid:Aqueous suspensions or slurries for specialized coating and impregnation processes. Textile flame retardant finishers in South Korea apply liquid formulations via padding mangles with controlled wet pickup.
Powder formulations command the established base. Granules are gaining share fastest in pharmaceutical automation.
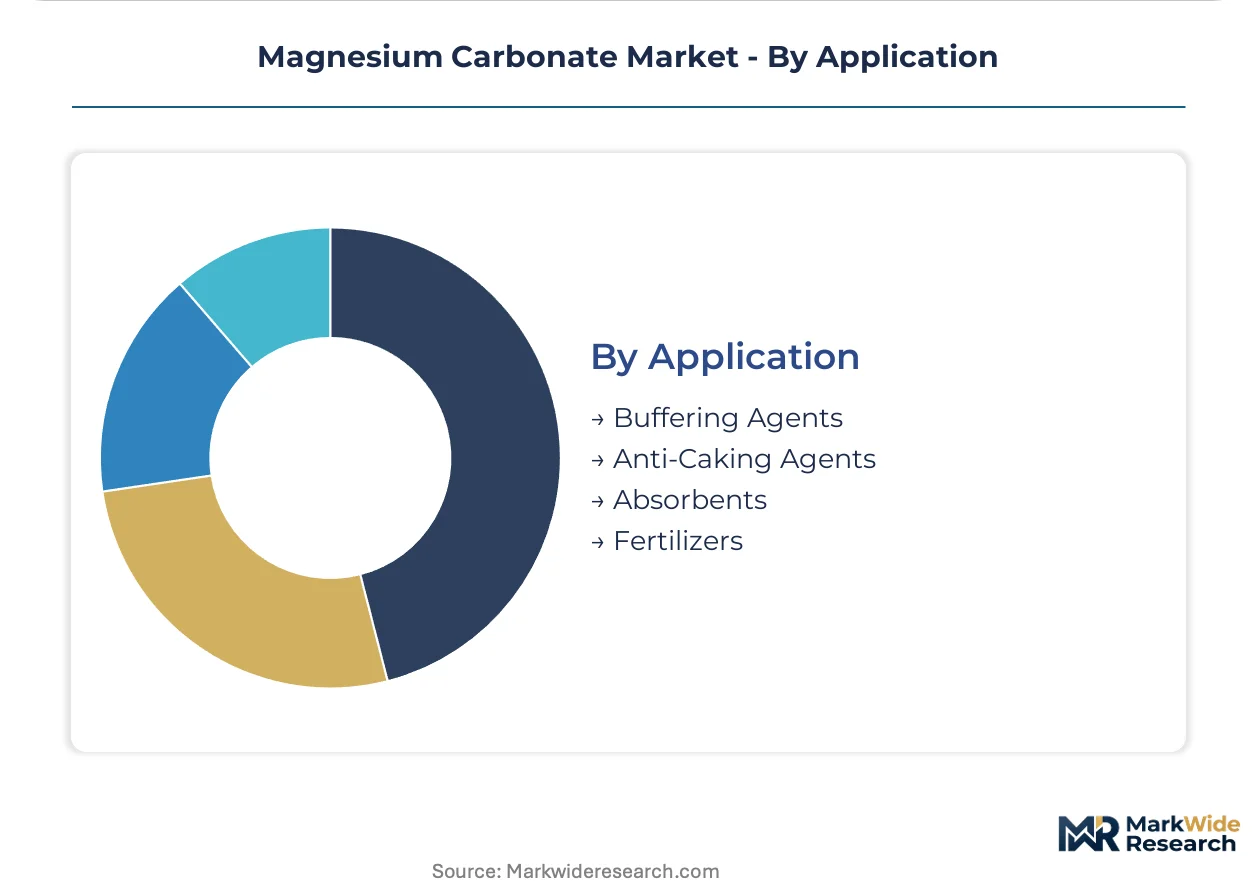
Application:
Functional role in formulation chemistry determines specification stringency and substitution vulnerability.
- Buffering Agents:pH stabilization in pharmaceutical and nutritional formulations requiring tight alkalinity control. Sports nutrition pre-workout powders specify light magnesium carbonate for gastric acid neutralization without laxative effect.
- Anti-Caking Agents:Free-flow maintenance in hygroscopic food powders and agricultural chemicals. Salt and seasoning blenders in India's FSSAI-regulated sector specify food-grade heavy magnesium carbonate at sub-2% inclusion rates.
- Absorbents:Oil and moisture capture in cosmetic talcs and industrial spill response materials. Personal care formulators in France's ANSM-regulated market prefer light-grade absorbency for face powder applications.
- Fertilizers:Magnesium source for foliar feeds and soil amendments where water solubility requirements are moderate. Brazilian agricultural distributors blend technical-grade material with NPK compounds for coffee and soybean cultivation.
Buffering agents anchor the premium tier. Anti-caking applications are expanding most quickly in emerging market food processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese producers capture pricing power through captive magnesite reserves, while European manufacturers absorb carbon border adjustment premiums that Turkish exporters struggle to pass through. This asymmetry reshapes procurement patterns across pharmaceutical and industrial channels.
China
Hebei province's magnesite belt feeds domestic pharmaceutical tablet manufacturing and construction chemical compounding. NMPA pharmaceutical-grade certification requirements under GB standards filter uncertified suppliers from hospital procurement channels. Tianjin's port infrastructure handles bulk export volumes to Southeast Asian nutraceutical contract manufacturers.
Germany
Direct compression tablet lines at Swiss and German drug formulators specify single-source magnesium carbonate with embedded audit rights. EU Green Deal carbon border adjustments impose documentation burdens on Turkish and Chinese exporters. The Rhine-Ruhr chemical corridor hosts analytical chemistry laboratories validating ICH Q3D elemental impurity compliance.
United States
FDA oversight through USP monograph compliance shapes purity thresholds for magnesium carbonate entering domestic drug formulations. Sports nutrition pre-workout powder manufacturers in Utah and Colorado specify light magnesium carbonate for gastric acid neutralization. Gulf Coast chemical processors import technical grades for fire retardant masterbatch production.
Japan
Pharmaceutical contract manufacturers in Osaka and Tokyo adopt continuous carbonation reactor monitoring with inline particle size analyzers. PMDA oversight aligns with USP and EP standards for excipient certification. Kyushu's chemical processing cluster supplies Southeast Asian tablet manufacturers through established distributor relationships.
India
FSSAI-regulated salt and seasoning blenders specify food-grade heavy magnesium carbonate at sub-2% inclusion rates. CDSCO pharmaceutical certification requirements parallel USP standards for domestic generic drug production. Gujarat's specialty chemical corridor hosts contract manufacturers supplying European nutraceutical brands.
Magnesium Carbonate Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper process knowledge. The vendor base stratifies across integrated mining-to-refining operators, pharmaceutical-grade specialists, and regional construction chemical suppliers. Three archetypes dominate: captive reserve holders with backward integration into magnesite conversion, multi-certified excipient producers serving regulated pharmaceutical channels, and asset-light processors leasing calcination capacity. Competitive moves concentrate on pharmacopeial harmonization achievements and direct procurement relationships displacing distributor intermediaries.
Among integrated reserve holders, Grecian Magnesite and Hebei Meishen Technology exemplify the captive supply archetype through geographic concentration of magnesite deposits. Kyowa Chemical Industry occupies a position within the pharmaceutical-grade specialization tier, representing premium positioning in Japanese and Southeast Asian supply chains where USP and EP multi-certification commands supplier preference.
| Leading Market Players |
|---|
| Grecian Magnesite |
| Hebei Meishen Technology |
| FMC Corporation |
| Kyowa Chemical Industry |
| Lehmann & Voss |
| ICL Group |
| Konoshima Chemical |
| Magnesia International |
| Omya |
| Others |
Cost & Logistics Intelligence
Carbon border adjustment exposure under the EU Green Deal determines both the premium spread between pharmaceutical and industrial grades and the geographic reconfiguration of supplier relationships. Buyers now face tiered cost structures where documentation-compliant cargoes from Turkish and Chinese exporters absorb tariff-equivalent penalties, forcing procurement toward multi-certified European producers or integrated reserve holders with captive carbon accounting.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical-grade USP and EP certification commands the top tier due to ICH Q3D elemental impurity testing costs, while technical-grade heavy carbonate for construction compounding sits at the economy tier driven by bulk density specifications and freight efficiency. Cost compression in the standard tier is intensifying because calcium carbonate substitutes compete in non-pharmaceutical alkalizing applications. Construction material compounders exhibit the highest price sensitivity, whereas Swiss and German drug formulators prioritize audit rights and single-source security over unit cost.
Supply Chain Analysis
Contract manufacturing concentration among Japanese pharmaceutical excipient processors and Indian nutraceutical contract manufacturers shapes downstream availability. Raw magnesite supply draws from Hebei province deposits, Greek mining districts, and Turkish export corridors, with calcination capacity clustering near these extraction points. Single-source vulnerability concentrates in high-purity pharmaceutical grades where qualified supplier pools remain narrow under divergent USP, EP, and Chinese Pharmacopoeia standards. Distribution runs through direct procurement relationships that displace traditional distributor intermediaries, particularly for tablet manufacturing lines in Germany and Switzerland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmacopeial harmonization gaps fragment qualified supplier pools and create niche entry points for producers achieving multi-certification. Direct procurement consolidation by large drug formulators further atomizes the vendor landscape, rewarding specialists with embedded quality agreements.
For Market Incumbents: Build certification moats through simultaneous USP, EP, and NMPA compliance to capture procurement consolidation toward single-source suppliers. Secure backward integration into captive magnesite reserves or locked-in offtake agreements from Hebei province and Greek mining districts to defend against raw material cost volatility. Embed audit rights and quality agreements into direct contracts with Swiss and German pharmaceutical manufacturers to displace distributor intermediaries. For New Entrants and Emerging Players: Build out asset-light calcination capacity through equipment leasing arrangements that bypass fixed asset ownership barriers. Target nutraceutical buffering applications in sports nutrition and antacid formulations where regulatory thresholds sit below prescription drug excipient requirements. Pursue white-label supply relationships with Southeast Asian tablet contract manufacturers seeking qualified light magnesium carbonate for direct compression processes. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustment implementation reshapes the acquisition landscape toward producers with documented Scope 1 and 2 emissions accounting. Prioritize integrated mining-to-refining operators with Greek or Hebei reserve positions and existing pharmaceutical-grade certification infrastructure. Monitor Turkish exporter documentation compliance rates as an inflection indicator for European market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Reserves | Hebei province and Greek deposit control secures raw material cost stability against magnesite ore concentration. |
| Multi-Certification Investment | Simultaneous USP, EP, and NMPA compliance unlocks direct procurement relationships with German and Swiss drug formulators. |
| Asset-Light Capacity Expansion | Calcination equipment leasing enables mid-tier producers to scale output without balance sheet strain. |
| Continuous Process Monitoring Adoption | Inline particle size analyzers at Japanese pharmaceutical contract manufacturers compress batch release timelines. |
| Carbon Border Documentation Systems | Scope 1 and 2 emissions reporting capabilities preserve European market access for Turkish and Chinese exporters. |
Research Approach
Desk research of customs and trade flow databases, pharmacopeial monograph archives, and SEC regulatory filings preceded structured interviews with pharmaceutical procurement directors, chemical plant managers, excipient distribution channel partners, and technical R&D directors. Primary fieldwork combined with secondary validation across ECHA REACH registration data, NMPA certification records, and EU Green Deal implementation documents. Bottom-up volume modeling and top-down value triangulation reconciled segment-level outputs.
Fixed assumptions around carbon border adjustment implementation timelines and pharmacopeial harmonization progress shaped the analytical framework across the projection horizon. Segmentation dimensions included density grade, end-use certification tier, physical form factor, and regional regulatory cluster. CAGRs derived from regression analysis against historical pharmaceutical tablet production indices and construction chemical compounding volumes. Forecast inputs incorporated natural gas price volatility for calcination energy costs and ICH Q3D testing capacity expansion rates.
Sensitivities concentrate around carbon border tariff equivalent rates, pharmacopeial standard divergence persistence, and magnesite ore supply disruptions from Hebei province environmental inspections. Forecasts reflect these documented assumptions with acknowledged revision potential from regulatory implementation delays or accelerated harmonization. Quarterly review of EU Green Deal documentation thresholds, NMPA certification queue lengths, and Turkish exporter compliance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
Global Sodium Percarbonate Market
Bulk Chemicals
Pyrophyllite Powder Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Mangiferin Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Global Plastics Market
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
Sodium Gluconate Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Valeric Acid Market
Bulk Chemicals
US Trona Market
Bulk Chemicals
Bulk Chemical Packaging Market
Bulk Chemicals
Sorbic Acid Market