
 US Trona Market | 2026-2036
US Trona Market Size, Share, and Industry Trends Forecast 2026-2036
US Trona Market Insights
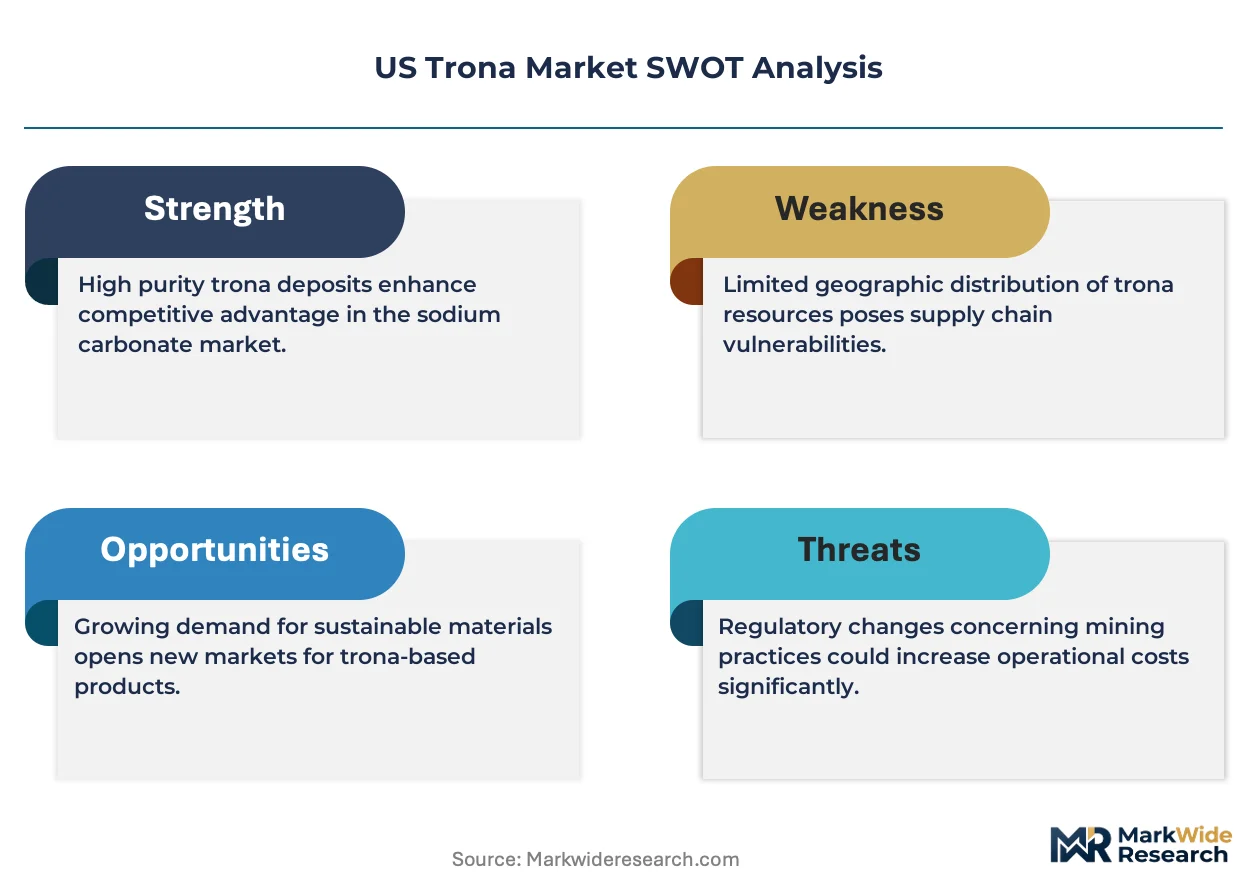
Long-term supply contracting is rebalancing procurement patterns across the US trona value chain, shifting buyers from spot purchases toward multi-year volume commitments with embedded price adjustment mechanisms. Ciner Resources anchors North American supply through its integrated mining and refining operations in Wyoming. Tata Chemicals competes on specialty-grade sodium bicarbonate for pharmaceutical and food-grade applications. Solvay differentiates through its European-linked distribution network serving import-dependent coastal buyers.
Trona is a naturally occurring sodium sesquicarbonate mineral (Na₂CO₃·NaHCO₃·2H₂O) containing approximately 46% sodium carbonate equivalent, mined through room-and-pillar underground methods and processed via the monohydrate or sesquicarbonate refining routes to produce soda ash, the primary output accounting for roughly half of US domestic supply. Soda Ash dominates product-type revenue flows given its irreplaceable role in flat glass and container manufacturing, while Sodium Bicarbonate captures expanding margin pools in pharmaceutical and environmental remediation applications. Glass Manufacturing anchors application-level demand through architectural and automotive sector offtake, though Water Treatment represents the fastest-growing application segment as municipal utilities expand flue gas desulfurization and pH adjustment programs.
The EPA enforces National Ambient Air Quality Standards that constrain mining and calcining emissions, while OSHA governs workplace silica and dust exposure limits across underground extraction sites, and Wyoming's Department of Environmental Quality administers state-level aquifer protection rules specific to the Green River Basin mining district. These layered frameworks elevate compliance capital requirements and favor operators with established permitting relationships over prospective entrants. Stakeholders must monitor pending federal critical minerals designations that could reshape royalty structures and access to Department of Energy financing instruments.
Market Dynamics
The US trona market is restructuring around long-term supply contracting as buyers abandon spot markets for multi-year volume commitments with embedded price adjustment mechanisms tied to energy indices. This shift favors established Wyoming operators with integrated mining and refining assets while elevating barriers for speculative entrants.
Growth Catalysts
- EPA Emissions Standards:Tightening National Ambient Air Quality Standards for industrial minerals processing are accelerating capital deployment into cleaner calcining technologies across the Green River Basin.
- Container Glass Demand:Automotive and construction sector expansion is lifting soda ash offtake for flat glass and container manufacturing applications.
- Green River Basin Concentration:The world's largest accessible trona deposits anchor North American supply security, insulating domestic buyers from import volatility.
Market Restraints
- Natural Gas Price Volatility:Energy costs dominate soda ash production economics, with calcining operations exposed to Henry Hub price swings that compress operating margins unpredictably.
- Wyoming Supply Concentration:Over 90 percent of US trona reserves sit in a single geological formation, creating systemic geographic risk from localized weather, labor, or infrastructure disruptions.
- Synthetic Soda Ash Substitution:Solvay process production in Europe and Asia competes on price during energy cost differentials, pressuring domestic market share in coastal export zones.
Strategic Opportunities
- Flue Gas Desulfurization Expansion:Municipal utilities across the Ohio River Valley are expanding sodium bicarbonate injection systems for SO₂ scrubbing, opening new environmental remediation demand channels.
- Pharmaceutical-Grade Bicarbonate:FDA-registered food and drug applications command 40-60 percent price premiums over technical grades, rewarding purification technology investments.
- Department of Energy Financing:Pending critical minerals designation would unlock loan guarantee programs and royalty restructuring for Green River Basin expansion projects.
Industry Challenges
- Underground Mining Talent Pipeline:Room-and-pillar extraction requires specialized equipment operators and ground control engineers that Wyoming's sparse population base struggles to replenish.
- OSHA Silica Compliance:Workplace dust exposure limits necessitate continuous monitoring infrastructure and respiratory protection programs that elevate fixed costs per ton.
- Aquifer Protection Permitting:Wyoming Department of Environmental Quality review timelines for new wellfield development routinely extend 18-24 months, constraining greenfield project velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Trona Market |
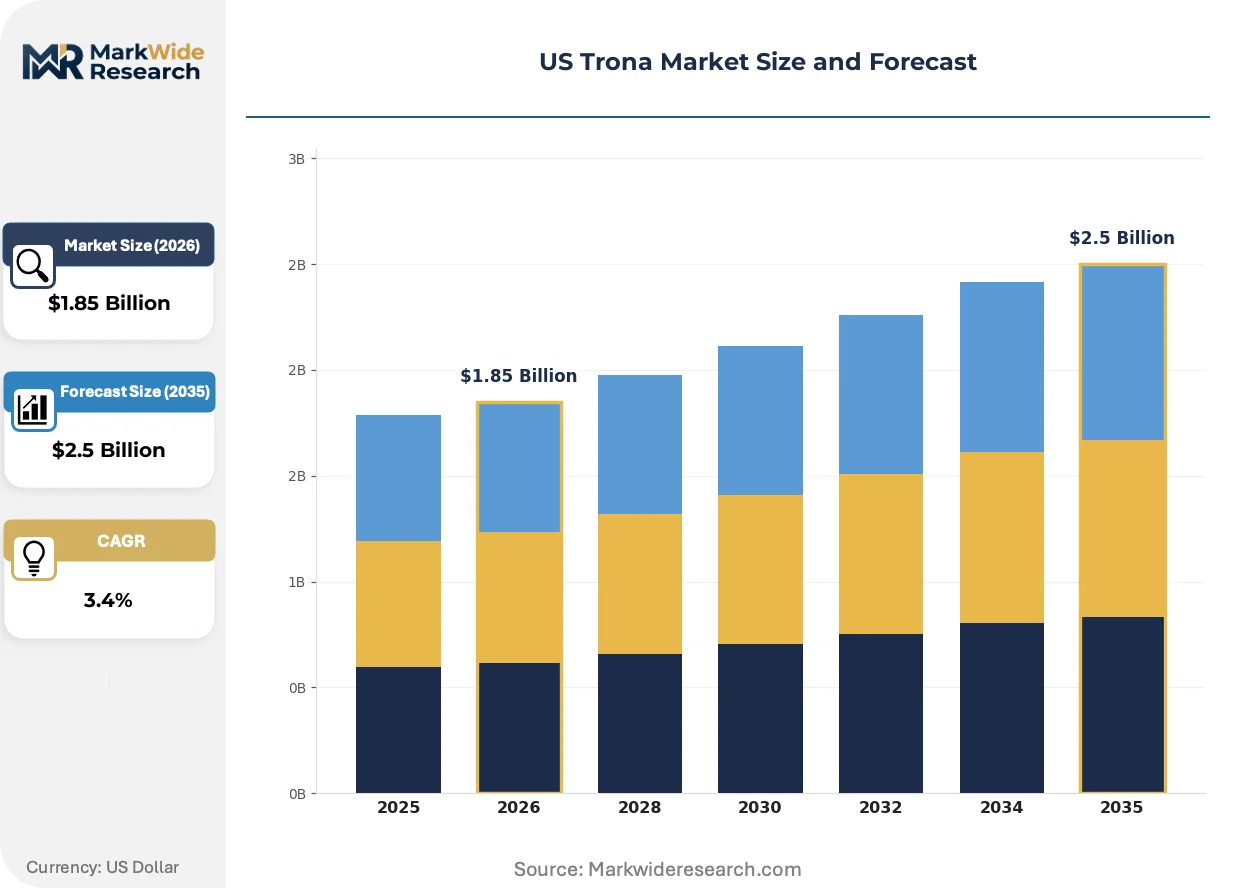
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soda Ash, Sodium Bicarbonate, Calcium Carbonate, Others Application: Glass Manufacturing, Detergents, Chemical Production, Water Treatment End User: Construction, Consumer Goods, Industrial, Agriculture Sales Channel: Direct Sales, Distributors, Online Retail, Wholesale |
| Companies Covered | Ciner Resources, Searles Valley Minerals, WE Soda, Kew Soda, TRInternational, Solvay, Tata Chemicals, Orion Resource Partners, FMC Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Trona Market Trends and Innovations
Digital process control systems and modular refining units are compressing capital deployment timelines while enabling smaller-scale production economics previously excluded from the trona value chain. These shifts are redistributing competitive advantage toward technology-integrated operators.
Sesquicarbonate refining technology is decentralizing production location decisions by reducing energy intensity versus traditional monohydrate routes. Mid-sized chemical processors in the Mountain West are piloting these units to bypass rail freight costs from Wyoming. The technology is decentralizing supply chain geography and enabling distributed soda ash production closer to end-use markets.
OSHA's updated respirable crystalline silica standard is mandating real-time dust monitoring and engineering controls across underground extraction sites. Mining operators are retrofitting continuous miner fleets with enclosed cabs and automated water suppression systems. Wyoming's largest producers are absorbing six-figure compliance capital per active face to maintain operating permits.
Glass manufacturers are consolidating purchase volumes through direct long-term contracts with integrated trona miners, bypassing traditional merchant distributor networks. Container and flat glass producers in the Midwest and Southeast are negotiating five to seven year offtake agreements with price collars. This pattern is most pronounced among automotive tier-one suppliers seeking supply security for just-in-time manufacturing schedules.
US Trona Market Segmentation
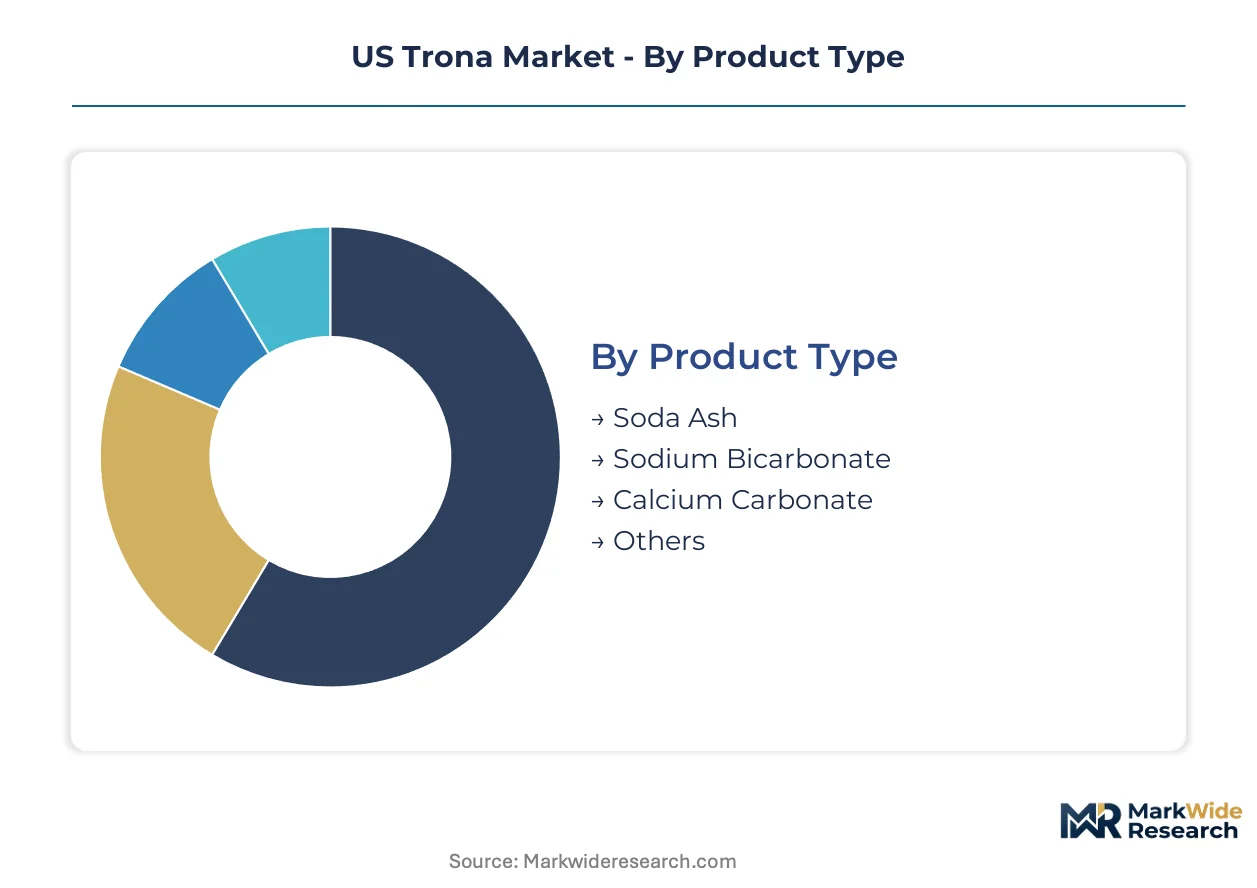
Trona market segmentation reveals distinct procurement patterns across product grades and buyer categories. Wyoming operators calibrate output specifications to match end-use purity requirements while navigating channel-specific logistics constraints.
Product Type:
Buyers select grades based on sodium carbonate equivalent content and impurity tolerances specific to their manufacturing processes.
- Soda Ash:Dense and light variants contain approximately 99% sodium carbonate, produced through monohydrate or sesquicarbonate calcining routes. Glass manufacturers in Ohio and Pennsylvania consume the majority of dense soda ash output for flat glass and container applications.
- Sodium Bicarbonate:Refined to USP and food-grade specifications through solution crystallization and carbonation. Pharmaceutical compounders and municipal flue gas desulfurization systems in the Ohio River Valley drive demand for high-purity bicarbonate grades.
- Calcium Carbonate:Byproduct of trona refining processes, sold as filler material for paper coating and plastics compounding applications.
- Others:Includes sodium sesquicarbonate and specialty sodium salts for niche chemical synthesis and de-icing formulations.
Volume sits with Soda Ash; growth tilts toward Sodium Bicarbonate.
Application:
End-use specifications determine the required processing intensity and corresponding margin capture for Wyoming refiners.
- Glass Manufacturing:Flat glass and container production consumes approximately half of US soda ash output. Automotive tier-one suppliers and architectural glass fabricators in the Midwest negotiate long-term offtake agreements with Green River Basin producers.
- Water Treatment:Municipal utilities deploy sodium bicarbonate for pH adjustment and flue gas desulfurization. EPA Clean Air Act compliance deadlines are accelerating sodium-based scrubbing system installations across coal-dependent power grids.
- Detergents:Powder and liquid laundry formulations use soda ash as a builder and pH buffer. Consumer goods manufacturers favor dense grades for compaction technologies.
- Chemical Production:Intermediate feedstock for sodium silicates, phosphates, and specialty organic synthesis.
Glass Manufacturing commands the largest share; Water Treatment is climbing the fastest.
End User:
Customer scale and technical sophistication shape contracting structures and service requirements.
- Industrial:Chemical processors and manufacturers with dedicated procurement teams negotiate multi-year supply agreements with embedded price adjustment mechanisms tied to natural gas indices.
- Construction:Glass fabricators and building materials suppliers purchase through merchant distributors or direct mill relationships depending on volume thresholds.
- Consumer Goods:Detergent and household product manufacturers require consistent lot-to-lot quality for automated packaging lines.
- Agriculture:Limited direct consumption; primarily indirect through animal feed bicarbonate applications.
Industrial buyers anchor contract volumes; Construction shows the steepest expansion trajectory.
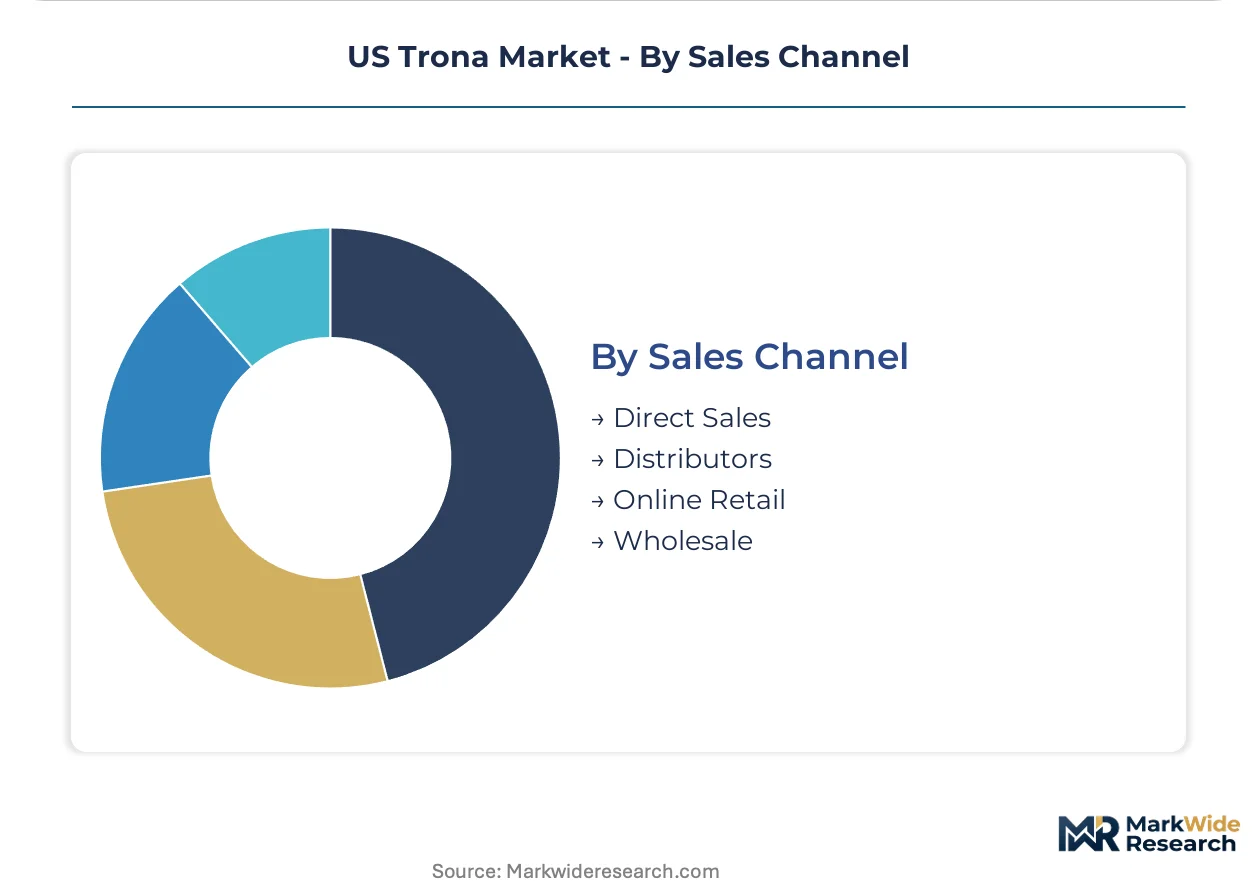
Sales Channel:
Channel selection reflects buyer scale, geographic proximity to Wyoming, and inventory carrying preferences.
- Direct Sales:Large-volume glass and chemical manufacturers contract directly with Ciner Resources and integrated Wyoming operators. Rail-served facilities in the Midwest and Southeast receive unit train shipments on 30-60 day cycles.
- Distributors:Regional chemical distributors stock soda ash and bicarbonate for mid-sized processors lacking rail siding infrastructure. Warehouse networks in Chicago, Atlanta, and Dallas-Fort Worth buffer supply for spot purchases.
- Wholesale:Bulk resellers aggregate smaller orders for water treatment utilities and specialty chemical blenders.
- Online Retail:Limited to laboratory-grade sodium bicarbonate and small-package technical grades for research and artisanal applications.
Direct Sales dominate tonnage; Distributors are gaining share fastest among mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
US trona production concentrates almost entirely within Wyoming's Green River Basin while consumption spreads across industrial corridors nationwide. This geographic mismatch shapes logistics costs and regional pricing dynamics.
Wyoming
The Green River Basin hosts the world's largest accessible trona deposits, with underground mining operations supplying raw material for domestic soda ash and sodium bicarbonate production. The Wyoming Department of Environmental Quality administers aquifer protection rules that extend wellfield permitting timelines to 18-24 months. Sweetwater County anchors extraction activity, with room-and-pillar operations feeding integrated refining complexes.
Ohio River Valley
Coal-dependent power utilities across Ohio, Kentucky, and West Virginia are expanding sodium bicarbonate injection systems for flue gas desulfurization compliance with EPA Clean Air Act deadlines. State public utility commissions are approving rate-base recovery for scrubbing infrastructure investments. The Cincinnati-Louisville corridor is emerging as a demand cluster for high-purity bicarbonate grades.
Southeast
Automotive glass fabricators in Tennessee and South Carolina are negotiating direct long-term offtake agreements with Wyoming producers to secure supply for just-in-time manufacturing schedules. State economic development authorities are offering infrastructure incentives for rail-served chemical processing facilities. The Greenville-Spartanburg metro is attracting container glass investment tied to regional beverage manufacturing growth.
Texas Gulf Coast
Petrochemical processors and water treatment utilities along the Houston Ship Channel consume dense soda ash for sodium silicate production and pH adjustment applications. Texas Commission on Environmental Quality regulations govern industrial discharge standards affecting chemical procurement specifications. The Corpus Christi refining corridor is expanding specialty chemical capacity requiring consistent soda ash feedstock.
Midwest
Flat glass manufacturers in Michigan and Illinois purchase dense soda ash through unit train shipments on 30-60 day cycles for architectural and automotive applications. State transportation departments are prioritizing rail infrastructure maintenance serving industrial corridors. The Toledo-Detroit glass manufacturing belt maintains direct mill relationships with integrated Wyoming operators.
US Trona Market Competitive Landscape
The competitive structure tilts toward integrated resource holders with captive mining and refining assets. Wyoming-based operators with established permitting relationships command structural advantages over prospective entrants. Two archetypes dominate: basin-anchored integrated producers with unit train logistics capabilities, and specialty-grade processors competing on purification technology. Capacity expansion and strategic partnerships represent the primary competitive moves, with operators securing long-term offtake agreements to lock in demand visibility.
Among integrated Wyoming operators, Ciner Resources anchors North American supply through its Green River Basin mining and refining complex. Searles Valley Minerals occupies a position within the specialty-grade tier, with historical operations in California's Searles Lake. Tata Chemicals exemplifies the diversified chemical conglomerate archetype, competing on pharmaceutical and food-grade sodium bicarbonate applications.
| Leading Market Players |
|---|
| Ciner Resources |
| Searles Valley Minerals |
| WE Soda |
| Kew Soda |
| TRInternational |
| Solvay |
| Tata Chemicals |
| Orion Resource Partners |
| FMC Corporation |
| Others |
Pricing and Supply Chain Analysis
Automotive tier-one suppliers consolidating purchase volumes through direct mill relationships are compressing distributor margins and forcing Wyoming operators to embed natural gas price collars into long-term offtake agreements. This procurement shift concentrates pricing power with integrated miners while exposing merchant distributors to volume attrition.
Pricing Analysis
Margin tightening in dense soda ash reflects Henry Hub volatility passing through to calcining operations. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade sodium bicarbonate separates USP-certified product commanding 40-60 percent premiums from commodity dense ash. Cost compression accelerates in standard grades as synthetic Solvay process imports pressure coastal markets during European energy cost differentials. Industrial chemical processors exhibit highest price sensitivity; pharmaceutical compounders demonstrate lowest.
Supply Chain Analysis
Natural gas supply rests on Permian Basin production corridors and interstate pipeline capacity into Wyoming's Green River Basin. Room-and-pillar mining equipment, continuous miner fleets, and calcining kiln refractories anchor capital equipment dependencies. Single-source vulnerability concentrates in rail logistics serving the Midwest and Southeast through BNSF and Union Pacific corridors. Distribution runs through unit train direct sales to large glass manufacturers, with regional chemical distributors buffering mid-market spot demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sesquicarbonate refining technology is displacing legacy monohydrate routes, enabling distributed production economics that bypass Wyoming rail freight premiums and reshape competitive positioning.
For Market Incumbents: To counter synthetic soda ash substitution pressure from European Solvay producers, deepen backward integration into wellfield development to secure 18-24 month permitting timelines, and accelerate sesquicarbonate technology deployment to reduce energy intensity per ton. For New Entrants and Emerging Players: Municipal utility procurement teams in the Ohio River Valley represent the most penetrable channel for high-purity sodium bicarbonate, given EPA Clean Air Act compliance deadlines accelerating flue gas desulfurization system installations without incumbent long-term contract coverage. For Investors and Strategic Acquirers: The window for entry favors specialty-grade processors with FDA-registered purification capabilities, as pharmaceutical and food-grade applications command durable margin premiums. Watch for Department of Energy critical minerals designation as the inflection signal unlocking federal loan guarantee programs.| Strategic Initiative | Industry Significance |
|---|---|
| Sesquicarbonate Technology Deployment | Reduces energy intensity versus monohydrate routes, enabling distributed production closer to end-use markets. |
| Long-term Supply Agreement | Locks in volume visibility with automotive glass fabricators seeking just-in-time manufacturing security. |
| Backward Integration into Wellfields | Captures Wyoming aquifer protection permitting relationships that constrain greenfield competitor velocity. |
| Pharmaceutical-Grade Certification | Unlocks USP and food-grade premiums through FDA-registered purification technology investments. |
| Joint Venture with Regional Distributors | Extends reach to mid-market water treatment utilities lacking rail siding infrastructure. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at Wyoming refining complexes, procurement leads at Midwest glass manufacturers, distribution channel partners in Chicago and Atlanta, and technical R&D directors at sodium bicarbonate processors. Bottom-up volume modeling triangulated against top-down industry association aggregates from the American Chemistry Council and Wyoming Mining Association.
Reconciliation of production volume data, rail shipment manifests, and end-use consumption surveys informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use industry application, and regional demand cluster. CAGRs derived from curve-fitting historical production trends against announced capacity expansions and regulatory compliance timelines, with natural gas price scenarios and EPA emissions standard implementation schedules as key forecast inputs.
Caveats apply where Department of Energy critical minerals designation timing, OSHA silica compliance cost pass-through, and synthetic soda ash import price volatility could materially shift the outlook. A small set of triggers—federal financing program activation, Wyoming permitting timeline shifts, and European energy cost differentials—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Trimellitic Anhydride Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
US Carbon Black Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Ammonium Sulfate Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Ammonium Bicarbonate Market
Bulk Chemicals
Magnesium Citrate Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market