
 Asia-Pacific Formaldehyde Market | 2026-2036
Asia-Pacific Formaldehyde Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Formaldehyde Market Outlook
Long-term offtake contracts with embedded maintenance and technical service provisions are recalibrating how formaldehyde suppliers monetize relationships beyond molecule sales. BASF SE leverages its integrated methanol-to-derivatives network to sustain cost-advantaged positions across multiple Asian production hubs. Jiangsu Sanmu Group Co. Ltd anchors regional supply through specialized urea-formaldehyde concentrate capacity serving domestic panelboard mills. Mitsubishi Gas Chemical Company, Inc. differentiates via high-purity formaldehyde technology leadership for electronics-grade applications.
Formaldehyde is a reactive aldehyde (CH₂O) produced primarily via silver-catalyzed or metal oxide-catalyzed oxidation of methanol, with concentrations typically ranging from 37% to 55% in aqueous solution known as formalin. The compound serves as a foundational building block for thermosetting resins, disinfectants, and chemical intermediates across industrial manufacturing. Wood Products applications dominate volume offtake as the structural backbone of particleboard and plywood adhesives, while Chemicals processing represents the fastest-growing margin pool through derivative expansion into polyols and specialty intermediates. Liquid form commands the majority of logistical flows due to handling infrastructure compatibility, though Powder formulations are gaining traction in controlled-release agricultural and healthcare sterilization segments.
China's MEE enforces progressively stricter volatile organic compound emission caps on formaldehyde resin production facilities, while India's BIS mandates product quality certification for imported formaldehyde derivatives under revised chemical safety protocols. Japan's METI coordinates industrial chemical stewardship guidelines that influence cross-border supply qualifications for Korean and Taiwanese downstream manufacturers. Stakeholders must monitor evolving substance restriction harmonization between China's GB standards and ASEAN regulatory cooperation frameworks to anticipate compliance-driven sourcing shifts.
Market Dynamics
China's MEE emission directives are compressing formaldehyde resin capacity across eastern manufacturing clusters, forcing producers toward methanol oxidation technology upgrades and captive methanol supply integration.
Growth Catalysts
- Wood adhesive demand:Southeast Asia's construction sector is expanding particleboard and plywood manufacturing, driving bulk chemical offtake from regional formaldehyde suppliers.
- GB standard harmonization:China's tightening GB standards on indoor air quality are mandating low-emission resin formulations, creating certified-product premiums for compliant manufacturers.
- Electronics-grade purity:High-purity formaldehyde for semiconductor and display manufacturing is commanding specialized supply contracts from Korean and Taiwanese electronics clusters.
Market Restraints
- Methanol cost volatility:Feedstock price swings tied to coal-to-methanol economics in China create margin compression for non-integrated producers.
- Supply concentration risk:Eastern China's Shandong and Jiangsu provinces host disproportionate resin capacity, exposing buyers to localized environmental shutdowns.
- Formaldehyde substitution:Bio-based adhesive technologies and MDI alternatives are displacing urea-formaldehyde in select furniture and automotive interior applications.
Strategic Opportunities
- Vietnam manufacturing expansion:Panelboard producers are relocating capacity to northern Vietnam to access ASEAN trade preferences and evade China's emission caps.
- Dual carbon policy tailwind:China's dual carbon goals are incentivizing methanol-to-formaldehyde producers with carbon capture integration to secure preferential licensing.
- Agrochemical controlled release:Powder formaldehyde formulations for fertilizer coating and soil sterilization represent underpenetrated demand in India's agricultural belt.
Industry Challenges
- Environmental compliance capex:MEE-mandated volatile organic compound abatement systems require substantial capital deployment for existing aqueous solution plants.
- Cross-border certification friction:India's BIS quality certification for imported derivatives creates timeline delays for Chinese exporters seeking market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Formaldehyde Market |
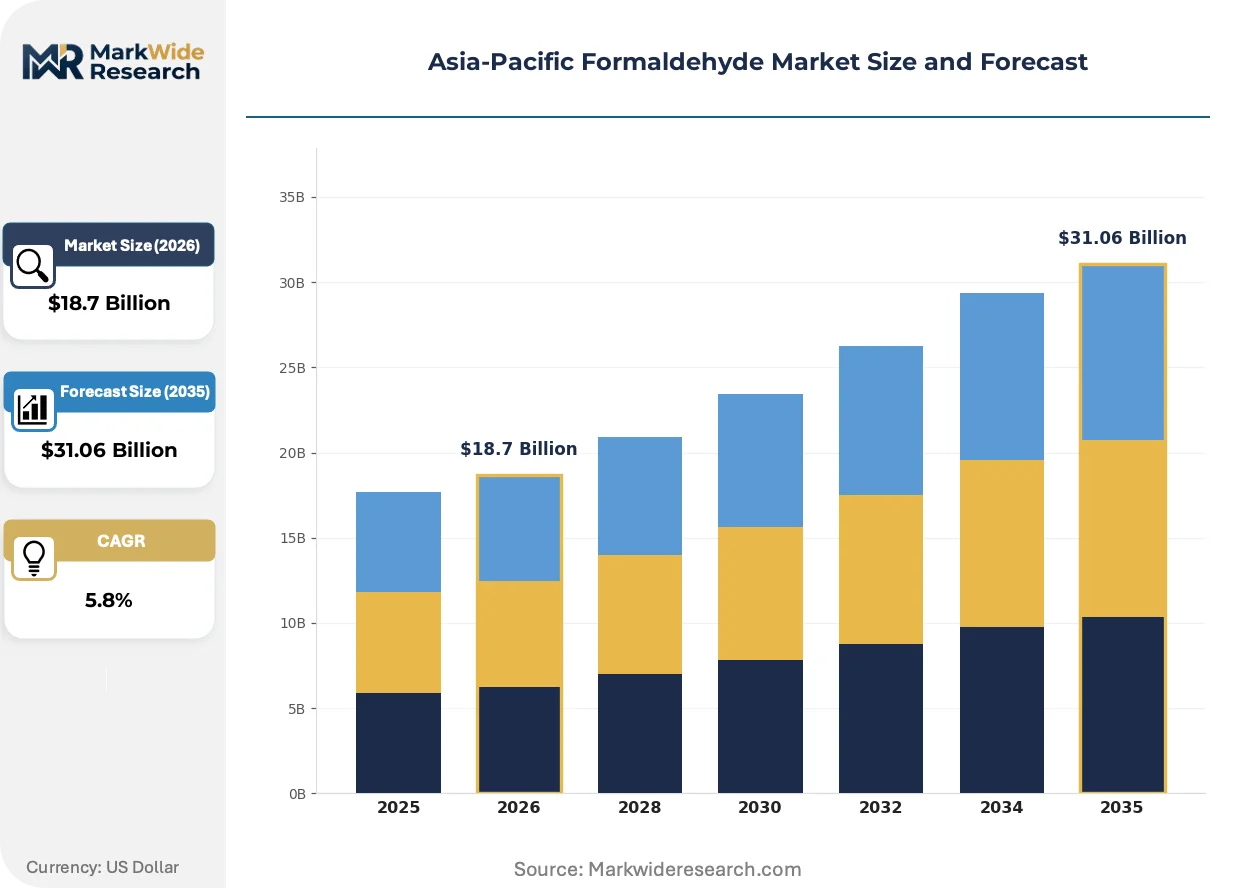
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Wood Products, Chemicals, Textiles, Agriculture Form: Liquid, Gas, Powder, Tablet End User: Construction, Automotive, Healthcare, Consumer Goods Distribution Channel: Direct Sales, Retail, E-commerce, Distributors |
| Companies Covered | Perstorp, Balaji Formalin Private Limited, BASF SE, ARCL Organics Ltd, Jiangsu Sanmu Group Co. Ltd, Hexion, Kanoria Chemicals & Industries Ltd, Hexza Corporation Berhad, Mitsubishi Gas Chemical Company, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Formaldehyde Market Strategic Shifts
Silver-catalyzed oxidation technology is displacing metal oxide processes across Asia-Pacific production bases, reshaping capital deployment patterns and methanol conversion economics for formaldehyde manufacturers.
Membrane-based formaldehyde concentration technology is integrating into new plant designs across Korean and Japanese chemical complexes. Electronics-grade resin producers in Taiwan are adopting these systems to reduce energy intensity in high-purity output streams. This integration is compressing the cost gap between commodity and specialty formaldehyde grades.
China's MEE is enforcing progressive volatile organic compound emission caps on formaldehyde resin production facilities through its 14th Five-Year Plan environmental enforcement framework. Industrial consequence includes accelerated consolidation among small-scale aqueous solution producers unable to fund abatement retrofits. Panelboard adhesive manufacturers in Hebei and Shandong provinces are responding by qualifying low-emission concentrate suppliers with verified carbon footprint documentation.
Long-term offtake contracts with embedded technical service provisions are displacing spot market procurement across Southeast Asian panelboard mills. Korean and Taiwanese buyers are unbundling maintenance and formulation support from molecule pricing. This pattern is most visible in Vietnam's northern industrial zones, where Japanese and Chinese resin suppliers compete through integrated service packages rather than pure commodity bids.
Asia-Pacific Formaldehyde Market Segmentation
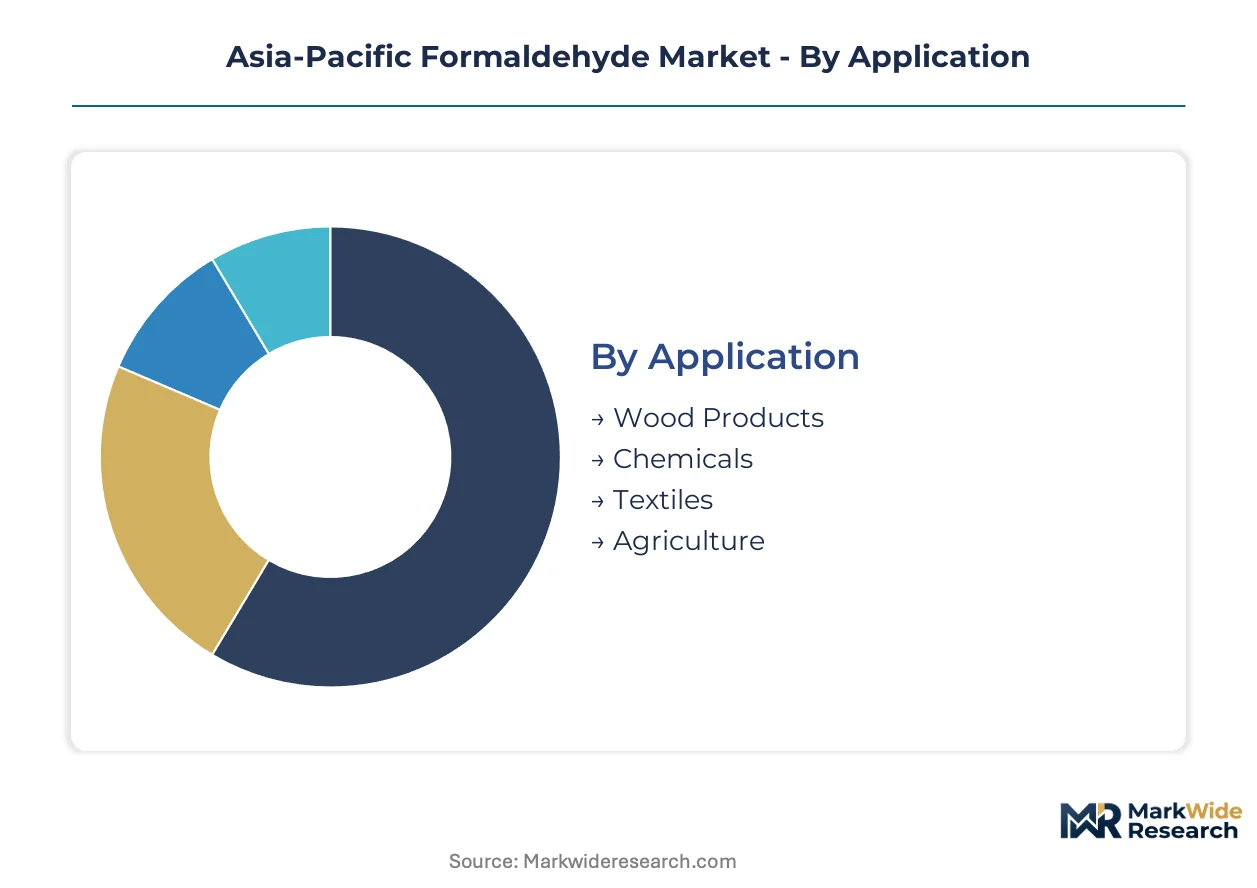
Formaldehyde demand patterns diverge sharply across application chemistry, physical state, and procurement channel. Segment-level analysis reveals where margin pools concentrate versus where volume throughput dominates.
Application:
Silver-catalyzed oxidation output finds its highest-value conversion pathways through resin chemistry specifications.
- Wood Products:Urea-formaldehyde and phenol-formaldehyde resins constitute the dominant adhesive chemistry for particleboard and plywood manufacturing. Eastern China's panelboard clusters in Shandong and Jiangsu provinces drive bulk offtake, though MEE emission caps are forcing reformulation toward low-emission concentrates.
- Chemicals:Polyol intermediates and specialty derivative synthesis command premium pricing through electronics-grade purity requirements. Korean semiconductor fabs and Taiwanese display manufacturers are expanding specialized supply contracts for ultra-high-purity formaldehyde streams.
- Textiles:Permanent-press fabric finishing and wrinkle-resistant treatments utilize formaldehyde-based crosslinking agents. India's textile belt around Surat and Tiruppur generates consistent industrial demand.
- Agriculture:Controlled-release fertilizer coatings and soil sterilization applications employ powder formulations. India's agricultural regions represent underpenetrated demand for formaldehyde-based agrochemical inputs.
Wood Products leads on scale; Chemicals leads on momentum.
Form:
Logistical infrastructure and handling safety protocols determine form selection across downstream manufacturing.
- Liquid:Aqueous formalin solutions at 37-55% concentration dominate regional supply chains due to established tank storage and bulk transport compatibility. Vietnam's northern industrial zones are expanding liquid receiving terminal capacity to support relocated panelboard manufacturing.
- Gas:Anhydrous formaldehyde vapor serves specialized polymerization chemistry and sterilization applications. Japanese electronics chemical complexes maintain dedicated gas handling infrastructure for high-purity processes.
- Powder:Paraformaldehyde and trioxane solid forms enable controlled-release agricultural applications and healthcare sterilization. Powder logistics bypass aqueous solution emission constraints in China's tightening regulatory environment.
- Tablet:Compressed solid formulations support discrete-dose applications in medical sterilization and laboratory settings. Healthcare procurement in Australia's hospital networks specifies tablet form for handling safety compliance.
Liquid commands volume throughput; Powder captures regulatory-driven substitution.
End User:
Construction sector procurement patterns are decoupling from pure commodity pricing toward integrated service contracts.
- Construction:Panelboard adhesive demand concentrates in Southeast Asia's residential and commercial building expansion. Vietnamese and Indonesian construction growth is attracting Chinese resin suppliers through technical service-embedded offtake agreements.
- Automotive:Interior component bonding and insulation applications utilize formaldehyde-based resins. Bio-based adhesive substitution is displacing urea-formaldehyde in select European-export-oriented seating applications.
- Healthcare:Sterilization equipment and medical device manufacturing employ high-purity formaldehyde derivatives. Japan's METI-coordinated chemical stewardship guidelines influence qualification requirements for Korean medical suppliers.
- Consumer Goods:Durable household products and furniture manufacturing consume resin formulations. China's GB standard harmonization on indoor air quality is mandating certified low-emission resins for domestic furniture production.
Construction anchors volume; Healthcare expands fastest on purity premiums.
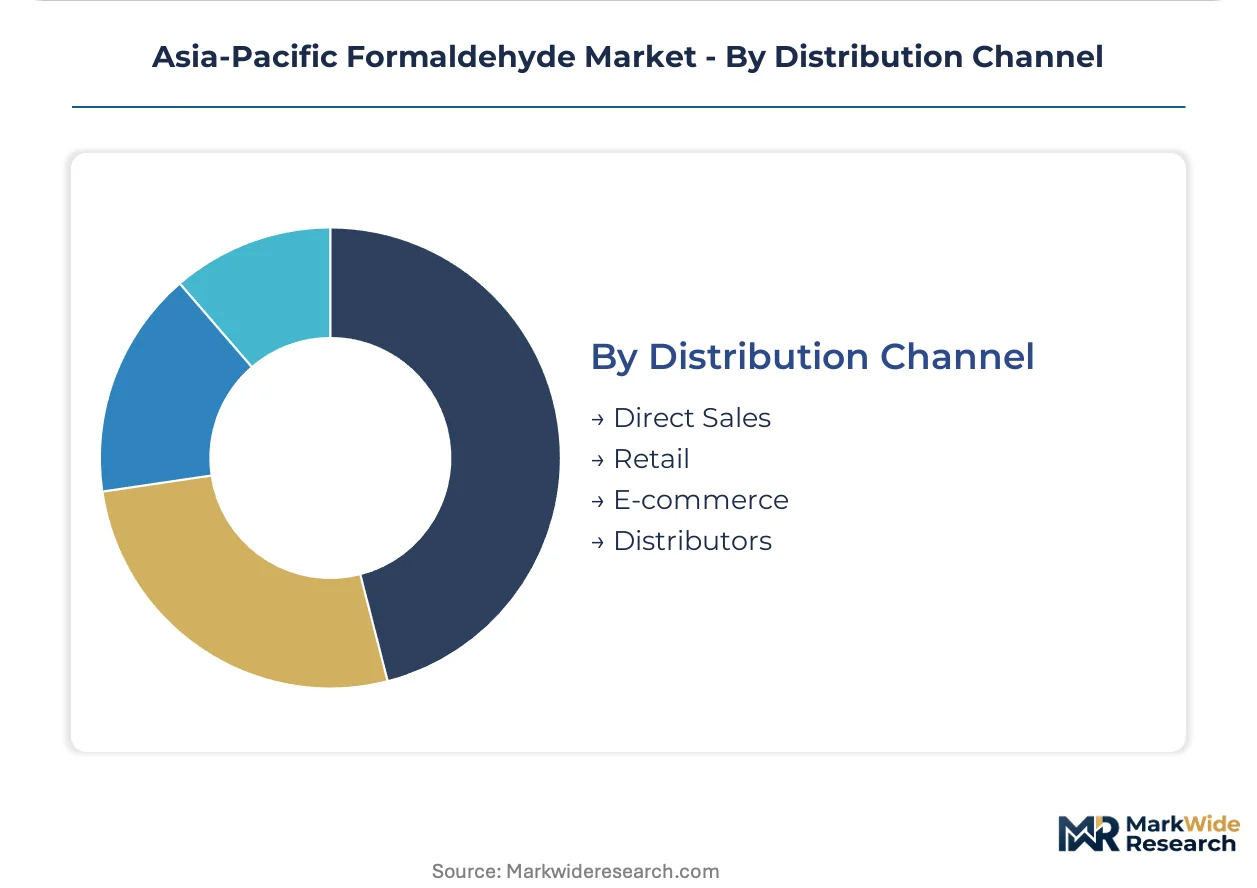
Distribution Channel:
Procurement channel selection reflects customer scale and technical support requirements.
- Direct Sales:Bulk formaldehyde supply to integrated panelboard mills and chemical complexes runs through long-term contracts with embedded maintenance provisions. Korean and Taiwanese buyers are unbundling technical service from molecule pricing.
- Retail:Small-volume formalin sales for laboratory, educational, and artisan woodworking applications flow through chemical supply distributors. India's BIS certification requirements create friction for imported retail-packaged derivatives.
- E-commerce:Specialty chemical marketplaces are emerging for controlled-volume formaldehyde derivative procurement. Australian and New Zealand buyers utilize digital channels for certified low-emission resin sourcing.
- Distributors:Regional chemical distributors aggregate supply for mid-scale adhesive manufacturers and textile processors. Southeast Asian distributor networks are consolidating to serve Vietnam's manufacturing relocation trend.
Direct Sales dominates value capture; E-commerce gains share on procurement efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's formaldehyde consumption dwarfs India's by an order of magnitude, yet Vietnam's manufacturing relocation is accelerating faster than either market's historical trajectory. This divergence is reshaping supply chain configurations across the region.
China
Shandong and Jiangsu provinces host concentrated panelboard manufacturing clusters driving bulk formaldehyde offtake. MEE emission caps under the 14th Five-Year Plan are forcing aqueous solution producers toward methanol oxidation technology upgrades. Hebei province's furniture manufacturers are qualifying low-emission concentrate suppliers with verified carbon footprint documentation.
India
Surat and Tiruppur textile belts generate consistent industrial demand for formaldehyde-based crosslinking agents. BIS mandates product quality certification for imported derivatives under revised chemical safety protocols. Maharashtra's chemical complexes are expanding domestic resin capacity to reduce import dependency.
Vietnam
Construction sector expansion in northern industrial zones is attracting relocated panelboard capacity from China. Japanese and Chinese resin suppliers compete through technical service-embedded offtake agreements rather than pure commodity bids. Hai Phong and Bac Ninh provinces are expanding liquid formaldehyde receiving terminal infrastructure.
South Korea
Semiconductor fabs and display manufacturers are expanding specialized supply contracts for ultra-high-purity formaldehyde streams. METI-coordinated chemical stewardship guidelines from Japan influence cross-border supply qualifications. Yeosu and Ulsan chemical complexes maintain dedicated gas handling infrastructure for electronics-grade processes.
Japan
Electronics-grade resin producers in Nagoya and Tokyo regions are adopting membrane-based concentration systems to reduce energy intensity. METI industrial chemical stewardship guidelines shape regional qualification requirements. Osaka-based chemical complexes differentiate through high-purity technology leadership for healthcare sterilization applications.
Asia-Pacific Formaldehyde Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated methanol-to-derivatives networks commanding cost-advantaged positions in bulk applications while purity-focused specialists capture electronics-grade premiums. The vendor base organizes around three archetypes: diversified chemical conglomerates with captive feedstock integration, regional resin specialists serving domestic panelboard mills, and technology leaders in high-purity segments. Competitive dynamics center on long-term offtake contract structures with embedded technical services, and geographic relocation of production capacity to evade emission constraints.
Among Asia-Pacific-based suppliers, Jiangsu Sanmu Group Co. Ltd and Mitsubishi Gas Chemical Company, Inc. occupy distinct positioning archetypes, while BASF SE represents the integrated multinational model. Jiangsu Sanmu exemplifies the regional specialist category through concentrated capacity serving domestic manufacturing clusters. Mitsubishi Gas Chemical sits within the technology-differentiated tier where purity specifications command specialized supply relationships. BASF anchors the diversified conglomerate archetype with network economics across multiple production hubs. European-headquartered Perstorp and Hexion represent alternative international positioning models in the regional competitive set.
| Leading Market Players |
|---|
| Perstorp |
| Balaji Formalin Private Limited |
| BASF SE |
| ARCL Organics Ltd |
| Jiangsu Sanmu Group Co. Ltd |
| Hexion |
| Kanoria Chemicals & Industries Ltd |
| Hexza Corporation Berhad |
| Mitsubishi Gas Chemical Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
Process engineer concentrations in eastern China's Shandong and Jiangsu provinces anchor labor-cost differentials that widen spreads between premium electronics-grade and standard industrial formaldehyde tiers. MEE-mandated emission abatement investments compress margins at smaller aqueous solution plants while integrated methanol-to-derivatives networks sustain cost advantages across pricing bands.
Pricing Analysis
Capacity additions in Vietnam's northern industrial zones are reshaping price floors for standard-grade formaldehyde resin. Long-term contract-based offtake agreements with embedded technical service provisions dominate procurement, separating premium certified-low-emission grades from commodity spot volumes. Pricing pressure intensifies in the standard tier as relocated Chinese panelboard mills negotiate volume-scale discounts. Small-scale Vietnamese adhesive manufacturers exhibit highest price sensitivity, while Korean semiconductor fabs prioritize purity certification over unit cost.
Supply Chain Analysis
Methanol feedstock supply rests on Chinese coal-to-chemicals complexes, South Korean petrochemical hubs, and Middle Eastern gas-based producers. Formaldehyde manufacturing clusters concentrate in China's Shandong and Jiangsu provinces, Vietnam's Hai Phong-Bac Ninh corridor, and Japan's Nagoya-Tokyo industrial belt. Single-source vulnerability runs through eastern China's emission-capped resin capacity, where MEE environmental directives trigger unplanned shutdowns. Distribution runs through direct sales contracts to integrated panelboard mills and chemical complexes, with regional distributors serving mid-scale textile and agricultural processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: Vietnam's manufacturing relocation captures ASEAN trade preferences while evading China's MEE emission caps and associated compliance capex burdens.
For Market Incumbents: Acquire captive methanol production assets to insulate margin structures from feedstock volatility. Integrate carbon capture systems to secure preferential licensing under China's dual carbon policy framework. Defend against bio-based adhesive substitution by qualifying low-emission concentrate formulations with verified carbon footprint documentation for European-export-oriented furniture manufacturers. For New Entrants and Emerging Players: Launch via technical service-embedded distribution partnerships serving Vietnam's relocated panelboard capacity. Target India's underpenetrated agricultural belt for powder formaldehyde formulations in controlled-release fertilizer coatings. Penetrate through e-commerce channels for certified low-emission resin sourcing by Australian and New Zealand healthcare procurement networks. For Investors and Strategic Acquirers: Regional resin specialists with concentrated domestic capacity are the most active acquirer targets in this space. Evaluate long-term viability through 5-10 year windows anchored to MEE enforcement trajectory and ASEAN regulatory harmonization pace. Watch for BIS certification timeline delays as the inflection signal for Chinese exporter market access friction into India.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol | Captive feedstock supply shields margin compression from coal-to-chemicals price swings in China. |
| Carbon Capture Integration | MEE dual carbon policy incentives reward abatement-equipped producers with preferential licensing. |
| Membrane-Based Concentration Technology | Korean and Japanese electronics chemical complexes reduce energy intensity in high-purity output streams. |
| Long-Term Offtake Agreements | Vietnamese panelboard mills unbundle technical service from molecule pricing in procurement contracts. |
| Geographic Manufacturing Relocation | Capacity shifts to northern Vietnam access ASEAN trade preferences and evade China's emission caps. |
Study Parameters
Multiple input streams — formaldehyde plant manager interviews, downstream OEM procurement lead discussions, distribution channel partner assessments, and technical R&D director consultations — were reconciled against customs and trade data, ACC regional chemical reports, and SEC 10-K filings from integrated chemical conglomerates. Bottom-up capacity and utilization estimates across Shandong, Jiangsu, and Vietnamese production clusters were cross-validated through top-down consumption modeling.
Historical capacity expansion patterns were cross-referenced against panel input from industry stakeholders to construct analytical frameworks across the projection horizon. Segmentation dimensions modeled include grade tier (electronics versus industrial purity), end-use industry (wood products, chemicals, textiles, agriculture), physical form (liquid, gas, powder, tablet), and regional production hub. CAGRs were derived through regression analysis of methanol feedstock cost trajectories and resin demand elasticity across construction sector cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt MEE enforcement escalations or sudden BIS certification requirement changes. Forecasts reflect assumptions regarding methanol supply continuity and ASEAN regulatory cooperation framework evolution. A small set of named triggers — environmental directive implementation pace, bio-based adhesive cost-parity achievement, and cross-border certification harmonization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Asia-Pacific Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
US Carbon Black Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
GCC Calcium Chloride Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Linear Alkylbenzene (LAB) Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Nickel Carbonate Market
Bulk Chemicals
Carbamide Market
Bulk Chemicals
Global Boric Acid Market