
 Sulfur Palletized Plant and Granulator Market | 2026-2036
Sulfur Palletized Plant and Granulator Market Size, Share, and Industry Trends Forecast 2026-2036
Sulfur Palletized Plant and Granulator Market Outlook
Modular skid-mounted configurations is expanding as the preferred delivery format for sulfur forming systems, letting processors scale capacity without greenfield construction. Thyssenkrupp leverages its engineering heritage to dominate large turnkey installations. Enersul Limited Partnership specializes in portable, redeployable units for remote oilfield operations. FEECO International anchors North American aftermarket service networks with extensive spare parts inventories.
Sulfur palletized plants and granulators are industrial systems that transform molten sulfur into solid, transportable forms—typically pellets, granules, or prills—using rotary drums, pastillators, or belt-based cooling processes operating at controlled temperatures and throughput rates. These systems serve primarily to enable safe storage, rail shipment, and downstream application of elemental sulfur recovered from oil refining and natural gas processing. Pelletizers command the largest installed base among product type segments due to their operational simplicity and compatibility with diverse sulfur grades. Mechanical technology leads current deployments, though hybrid systems combining thermal and mechanical forming are gaining traction where energy recovery matters. Soil enhancement applications within the agriculture end user segment represent the fastest-growing demand pool as sulfur-deficient soils drive micronutrient supplementation programs.
EPA regulations on sulfur recovery unit emissions shape equipment specifications for US installations, while REACH compliance in Europe constrains material selections for components contacting elemental sulfur. China's MEE enforces stricter fugitive emission controls at sulfur handling facilities, elevating demand for enclosed forming systems. India's CEA mandates stack monitoring at fertilizer complexes, indirectly driving upgrades to closed-loop palletizing operations. Stakeholders should monitor evolving carbon border adjustment mechanisms that could restructure competitive sourcing between regional equipment suppliers.
Market Dynamics
Modular skid-mounted sulfur forming systems are compressing deployment timelines from eighteen months to under six months, enabling processors to match capacity additions to volatile sulfur recovery volumes without stranded asset risk.
Growth Catalysts
- Soil amendment mandates:Sulfur-deficient agricultural regions are expanding micronutrient supplementation programs, driving procurement of palletized sulfur for controlled-release fertilizer blends.
- EPA emission standards:Stricter sulfur recovery unit requirements are forcing refinery upgrades that increase elemental sulfur output needing immediate solidification capacity.
- Remote oilfield sulfur:Portable forming units are capturing stranded sulfur at isolated gas processing sites where rail access eliminates long-haul trucking economics.
Market Restraints
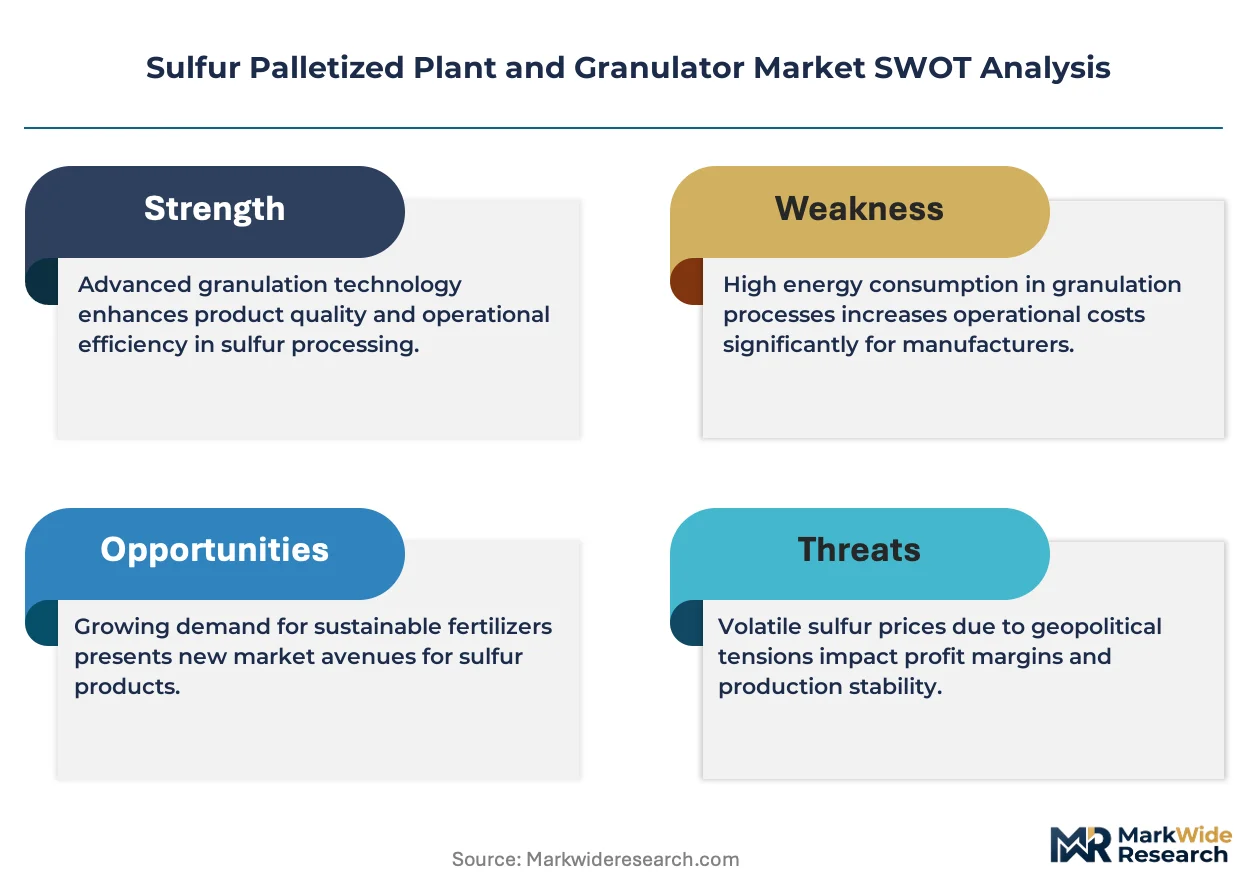
- Energy cost volatility:Thermal forming processes consume substantial natural gas, exposing operators to price swings at US Gulf Coast and Middle Eastern installations.
- Equipment supply concentration:Large turnkey system engineering concentrates among European and North American vendors, limiting sourcing options for Asian fertilizer producers.
- Mechanical forming limits:Belt-based cooling struggles with high-impurity sulfur streams containing hydrocarbon residuals, restricting feedstock flexibility.
Strategic Opportunities
- India fertilizer corridor:CEA-mandated stack monitoring at fertilizer complexes is creating demand for enclosed, low-emission palletizing systems in the country's eastern and western production belts.
- Hybrid thermal-mechanical systems:Converging energy recovery technology with mechanical forming is opening retrofit opportunities at existing sulfur recovery facilities.
- Digital predictive maintenance:Sensor-integrated forming equipment enables remote monitoring contracts, shifting revenue from hardware sales to recurring service streams.
Industry Challenges
- Specialized welding certification:ASME pressure vessel standards for molten sulfur handling require scarce qualified fabricators, extending fabrication queues for critical components.
- Legacy DCS integration:Brownfield installations face protocol mismatches between modern forming controls and decades-old refinery distributed control systems.
- Corrosion metallurgy expertise:Sulfur-resistant alloy selection for high-temperature zones depends on diminishing pools of materials engineers with specific sulfur service experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sulfur Palletized Plant and Granulator Market |
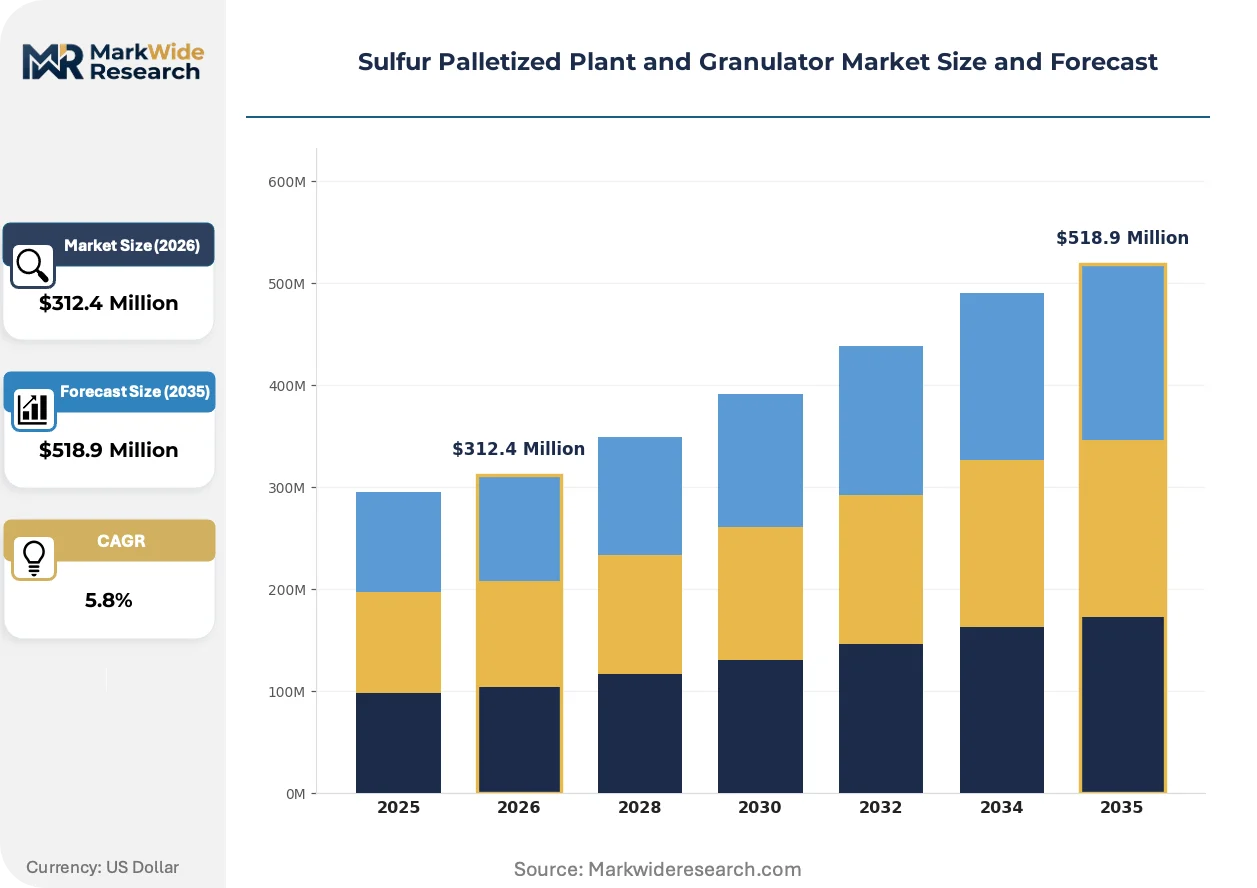
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granulators, Pelletizers, Extruders, Mixers End User: Agriculture, Fertilizers, Oil & Gas, Chemical Manufacturing Technology: Mechanical, Electrical, Hybrid, Thermochemical Application: Soil Enhancement, Sulfur Recovery, Fuel Production, Industrial Uses |
| Companies Covered | Thyssenkrupp, Enersul Limited Partnership, FEECO International, GEA Group, FLSmidth & Co. A/S, Metso Outotec Corporation, Chemetics Inc., John Zink Hamworthy Combustion, Bechtel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sulfur Palletized Plant and Granulator Market Strategic Shifts
Forming technology evolution is fragmenting the historical dominance of centralized, large-scale installations while regulatory pressure and procurement model shifts are rewriting competitive advantage definitions.
Containerized pastillation units are decentralizing sulfur solidification capacity placement decisions. Mid-size refiners in Texas and Louisiana are deploying these systems to avoid rail loading bottlenecks at shared terminal facilities. This technology is decentralizing the economics of sulfur logistics by enabling point-of-production solidification rather than molten transfer to distant forming plants.
China's GB standards on sulfur handling and storage are tightening equipment specifications for fugitive emission containment. The country's MEE enforcement is elevating demand for fully enclosed forming systems with negative-pressure hooding and vapor recovery. Domestic fertilizer producers are responding by specifying stainless steel construction and automated bagging lines that eliminate manual exposure points.
Service unbundling is separating equipment supply from long-term operating contracts. Fertilizer cooperatives in the US Midwest are procuring forming capacity through performance-based arrangements where vendors retain ownership and charge per-ton processing fees. This shift is most visible in regions with seasonal demand spikes that punish capital-intensive ownership models.
Sulfur Palletized Plant and Granulator Market Segmentation
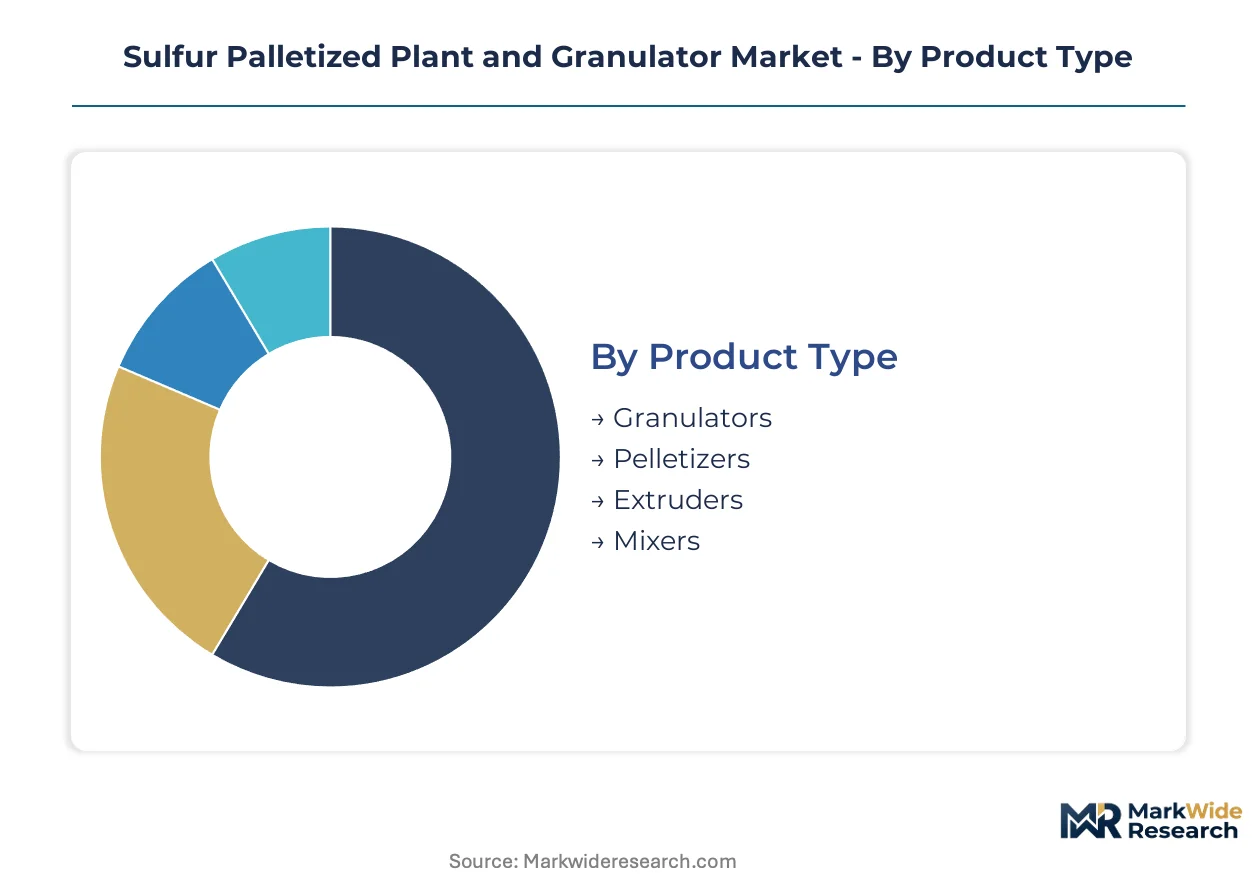
Sulfur forming equipment procurement varies sharply by operational scale, feedstock quality, and emission constraints. Buyers prioritize throughput reliability, energy efficiency, and regulatory compliance when selecting across product configurations. Understanding segment boundaries clarifies where technology investments concentrate versus where commoditization pressures dominate.
Product Type:
Capital intensity and maintenance accessibility drive equipment selection more than raw throughput capacity.
- Pelletizers:Rotary drum systems dominate current installations due to operational simplicity and tolerance for variable sulfur grades. US Gulf Coast refineries specify these for high-volume continuous runs where downtime costs exceed equipment price premiums.
- Granulators:Fluidized bed and prilling configurations excel where spherical particle uniformity matters for pneumatic conveying and precise blending. Chinese fertilizer producers under MEE emission mandates increasingly specify enclosed granulator lines with integrated vapor recovery.
- Extruders:Screw-press designs suit niche applications requiring dense, high-strength pellets for ocean freight stability.
- Mixers:Pre-conditioning units blend molten sulfur with additives for specialized agricultural formulations.
Pelletizers lead on scale; granulators lead on momentum.
End User:
Application chemistry and logistics infrastructure shape procurement specifications across buyer categories.
- Fertilizers:Controlled-release nutrient delivery demands palletized sulfur with consistent dissolution rates. Indian CEA-mandated stack monitoring at eastern and western production belts is accelerating enclosed-system upgrades.
- Agriculture:Direct soil amendment programs in sulfur-deficient regions require micronutrient-grade product with low contaminant thresholds.
- Oil & Gas:Remote gas processing sites deploy portable forming units where rail access eliminates uneconomical molten sulfur trucking.
- Chemical Manufacturing:Sulfuric acid feedstock producers prioritize thermal efficiency and SO₂ recovery integration.
Fertilizers lead on scale; agriculture leads on momentum.
Technology:
Energy recovery potential and emission footprint now outweigh pure mechanical reliability in technology selection.
- Mechanical:Belt-based cooling and rotary forming remain the installed base majority due to lower capital outlay and established maintenance protocols.
- Hybrid:Combined thermal-mechanical systems capture waste heat from forming operations, cutting natural gas consumption at US Gulf Coast installations facing volatile energy pricing.
- Electrical:Resistance-heated precision forming suits laboratory-scale and specialty chemical applications requiring exact temperature control.
- Thermochemical:Reaction-based solidification processes remain experimental for high-purity sulfur recovery.
Mechanical leads on scale; hybrid leads on momentum.
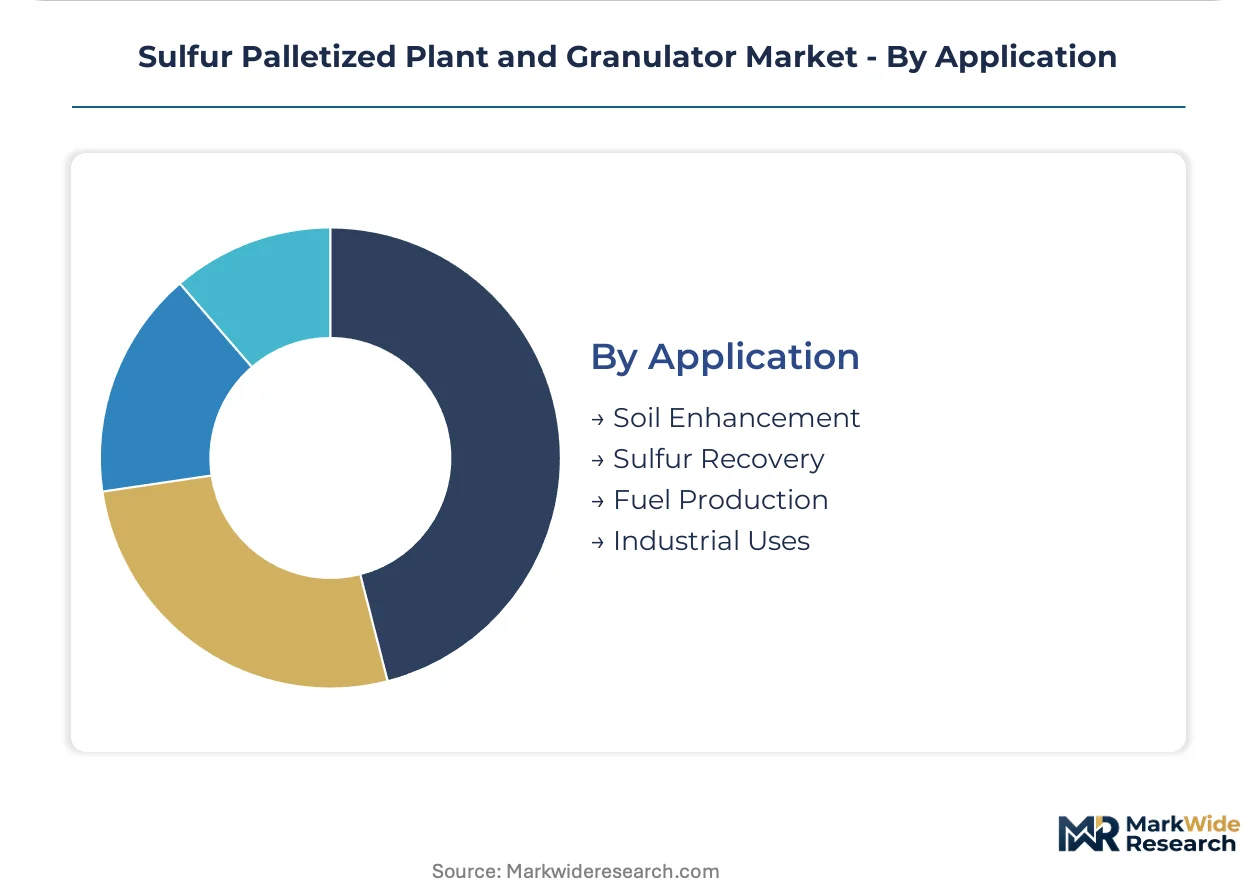
Application:
Downstream value capture and regulatory exposure determine where processors invest in forming capacity versus outsourcing.
- Sulfur Recovery:Refinery and gas plant SRU output requires immediate solidification to prevent molten storage bottlenecks. EPA emission standards are forcing capacity expansions that outpace terminal availability.
- Soil Enhancement:Micronutrient supplementation programs in sulfur-deficient agricultural regions are climbing fastest as precision agriculture spreads.
- Fuel Production:Hydrotreating operations generate sulfur streams needing compliant forming for hazardous materials transport.
- Industrial Uses:Rubber vulcanization and chemical synthesis pull smaller volumes of specialized sulfur grades.
Sulfur recovery leads on scale; soil enhancement leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sulfur forming equipment manufacturing originated in German engineering centers during the post-war chemicals expansion, then migrated to US Gulf Coast petrochemical corridors as refining capacity scaled. Today's procurement patterns reflect this dual heritage while incorporating new regulatory pressures across major sulfur-producing jurisdictions.
United States
EPA emission standards for sulfur recovery units are forcing refinery upgrades along the Texas and Louisiana coastlines. The agency's stricter SO₂ thresholds are accelerating enclosed palletizing system deployments at Port Arthur and Lake Charles complexes. Modular skid-mounted units are compressing installation timelines to under six months at stranded gas processing sites in the Permian Basin.
Germany
REACH compliance constraints on materials contacting elemental sulfur are elevating stainless steel specifications for component fabrication. The country's chemicals sector maintains demanding purity requirements for sulfuric acid feedstock production. Engineering heritage from the Ruhr industrial region continues to influence large turnkey system design standards exported worldwide.
China
MEE enforcement of GB standards on sulfur handling is tightening fugitive emission controls at fertilizer complexes in Shandong and Hebei provinces. Domestic producers are specifying fully enclosed forming systems with negative-pressure hooding. The Yangtze River Delta corridor is seeing concentrated upgrades to automated bagging lines that eliminate manual exposure points.
India
CEA-mandated stack monitoring at fertilizer complexes is driving enclosed-system procurement in Gujarat and Maharashtra production belts. The eastern and western coastal corridors are expanding micronutrient supplementation programs for sulfur-deficient agricultural soils. Domestic blenders are prioritizing palletized sulfur with consistent dissolution rates for controlled-release formulations.
Saudi Arabia
Remote gas processing sites in the Eastern Province are deploying portable forming units where rail access eliminates uneconomical molten sulfur trucking. The kingdom's Master Gas System expansion is generating stranded sulfur volumes requiring immediate solidification capacity. Aramco's downstream integration is concentrating procurement decisions at Jubail Industrial City complexes.
Sulfur Palletized Plant and Granulator Market Competitive Environment
Premium-margin players sit above commodity-margin players across engineering depth and aftermarket service intensity. The vendor base separates into turnkey specialists commanding large installation contracts and portable unit fabricators serving remote oilfield logistics. Three archetypes dominate: heritage engineering conglomerates with integrated metallurgy capabilities, regional specialists in redeployable modular systems, and service-anchored aftermarket operators with extensive spare parts networks. Consolidation pressure is minimal; competitive intensity centers on technology licensing partnerships and geographic expansion through local fabrication joint ventures.
Within the heritage engineering tier, Thyssenkrupp exemplifies the large-scale turnkey installation archetype with deep metallurgical process knowledge. Enersul Limited Partnership occupies a distinctive position among portable system specialists, while FEECO International anchors the North American aftermarket service vector. These three entities collectively span the principal procurement decision criteria: capital intensity, deployment flexibility, and long-term operating cost predictability.
| Leading Market Players |
|---|
| Thyssenkrupp |
| Enersul Limited Partnership |
| FEECO International |
| GEA Group |
| FLSmidth & Co. A/S |
| Metso Outotec Corporation |
| Chemetics Inc. |
| John Zink Hamworthy Combustion |
| Bechtel Corporation |
| Others |
Value Chain & Pricing Dynamics
Modular skid-mounted configurations are compressing capital deployment timelines while simultaneously redistributing pricing power from large turnkey vendors toward regional fabricators with flexible production footprints. This technology shift tightens margins on centralized installations while opening premium capture opportunities for portable unit specialists serving remote oilfield logistics.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates heritage engineering conglomerates from regional modular specialists and commodity fabricators. Price differentiation hinges on ASME certification grade and after-sales service bundling. Cost compression in economy-tier belt-based systems is intensifying because Chinese domestic producers are scaling stainless steel fabrication capacity. Fertilizer cooperatives in the US Midwest exhibit highest price sensitivity due to seasonal demand volatility, while Gulf Coast refineries prioritize reliability over capital outlay.
Supply Chain Analysis
Refurbishment flows for rotary drum components and pastillation belts create secondary supply channels that extend equipment lifecycles and dampen new-build demand cyclicality. Manufacturing concentrates in Germany, the United States, and China, with specialized welding certification requirements constraining qualified fabricator pools. Raw material dependencies include sulfur-resistant alloys, stainless steel grades for MEE-compliant enclosures, and precision bearings for high-temperature zones. Single-source vulnerability runs through ASME-certified pressure vessel shops. Distribution runs through EPC contractors for large installations and direct procurement for modular redeployable units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where MEE enforcement in China and CEA mandates in India create equipment upgrade cycles that lag EPA-driven replacement waves in the United States by several years, enabling technology transfer and pricing premiums for early movers.
For Market Incumbents: Deploy digital predictive maintenance platforms to capture recurring service revenue streams and offset hardware margin compression. Fortify position by deepening metallurgical expertise pools through apprenticeship partnerships with Ruhr-region technical institutes, countering the scarcity of sulfur-service materials engineers. Expand captive spare parts inventories at Gulf Coast logistics hubs to lock in aftermarket relationships against emerging regional competitors. For New Entrants and Emerging Players: CEA-mandated stack monitoring in India opens a window for enclosed-system specialists to penetrate fertilizer corridor upgrades in Gujarat and Maharashtra. Target portable forming unit deployment at stranded gas processing sites in Saudi Arabia's Eastern Province where rail access eliminates molten trucking economics. Lead with performance-based contracting models where vendors retain ownership and charge per-ton processing fees, matching cooperative procurement preferences in seasonal-demand regions. For Investors and Strategic Acquirers: Roll-up economics work for regional aftermarket service networks because fragmented spare parts distribution creates margin capture opportunities through inventory consolidation and technician cross-training. Target acquisition archetypes include North American service-anchored operators with established plant engineer relationships and documented maintenance protocols. Monitor MEE enforcement intensity in Shandong and Hebei provinces as inflection indicator for Chinese domestic equipment replacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Fabrication | Captive supply of sulfur-resistant materials insulates against ASME-certified welder shortages and extends margin capture. |
| Joint Venture with Indian EPC Contractors | Local fabrication partnerships navigate CEA compliance requirements while compressing delivery timelines for eastern fertilizer belts. |
| Technology Licensing to Chinese Domestic Producers | Knowledge transfer agreements monetize engineering heritage while accommodating MEE-driven demand for enclosed forming systems. |
| Long-term Service Contract with Gulf Coast Refiners | Performance-based arrangements shift revenue toward recurring streams and align vendor incentives with uptime guarantees. |
| Capacity Expansion in Modular Skid-Mounted Units | Scalable production lines match volatile sulfur recovery volumes without stranding capital at single-site installations. |
Study Parameters
Coverage spans the United States Gulf Coast, Germany's Ruhr industrial region, China's Yangtze River Delta and northern fertilizer belts, India's western and eastern production corridors, and Saudi Arabia's Eastern Province, with primary inputs from each. The analysis combines structured interviews with refinery SRU engineers, fertilizer procurement leads, EPC contractor project managers, and aftermarket service directors with secondary validation through EPA emission filings, MEE enforcement bulletins, CEA stack monitoring mandates, customs equipment trade data, and SEC disclosures from listed engineering conglomerates. Bottom-up equipment shipment tallies triangulate against top-down sulfur production forecasts.
Granularity extends to product type, technology configuration, end-use application, and regional regulatory cluster across the analysis window. CAGRs derive from modeled unit deployment trajectories weighted by capital intensity and replacement cycle timing. Forecast inputs incorporate natural gas price volatility assumptions for thermal forming economics and MEE enforcement probability scenarios for Chinese equipment specification shifts.
Revisions become necessary when carbon border adjustment mechanisms materialize, restructuring competitive sourcing between regional equipment suppliers, or when ASME welding certification bottlenecks extend fabrication queues beyond typical procurement timelines. Practitioners should monitor EPA SO₂ threshold adjustments, MEE fugitive emission enforcement intensity, and CEA stack monitoring expansion for early signals of regulatory-driven replacement demand.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Manganese Sulfate Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
Methyl Mercaptan Market
Bulk Chemicals
Asia-Pacific Ammonium Nitrate Market
Bulk Chemicals
South America Carbon Black Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Saudi Arabia Formic Acid Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market