
 Global 2-Ethylhexanoic Acid Market | 2026-2036
Global 2-Ethylhexanoic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global 2-Ethylhexanoic Acid Market Foresight
European petrochemical capacity is hardening around oxo-alcohol feedstock availability. BASF SE leverages integrated C4 chemistry complexes in Ludwigshafen to sustain captive 2-ethylhexanoic acid output. Eastman Chemical Company anchors North American supply through Kingsport operations, while Perstorp Holding AB competes from Swedish specialty chemical positions.
2-Ethylhexanoic acid is a branched C8 carboxylic acid produced via oxidation of 2-ethylhexanal, with a molecular weight of 144.21 g/mol and a boiling point of 228°C, serving primarily as a chemical intermediate for metal salts, esters, and polymeric stabilizers. Industrial grade material dominates volume flows into plasticizers manufacture, where margin pools remain deepest amid vinyl compound formulation demand. Reagent grade supply is concentrating among electronic material suppliers serving semiconductor fabrication, as trace metal specifications tighten for precursor applications.
REACH registration requirements in the European Union and China's GB 38508 standards on volatile organic compound content in coatings are elevating analytical certification burdens across exporters. The EPA's Toxic Substances Control Act oversight in the United States shapes import documentation for lubricant additive applications. Stakeholders must monitor feedstock propylene volatility and regional carbon-accounting rules to calibrate capacity commitments and grade-mix decisions.
Market Dynamics
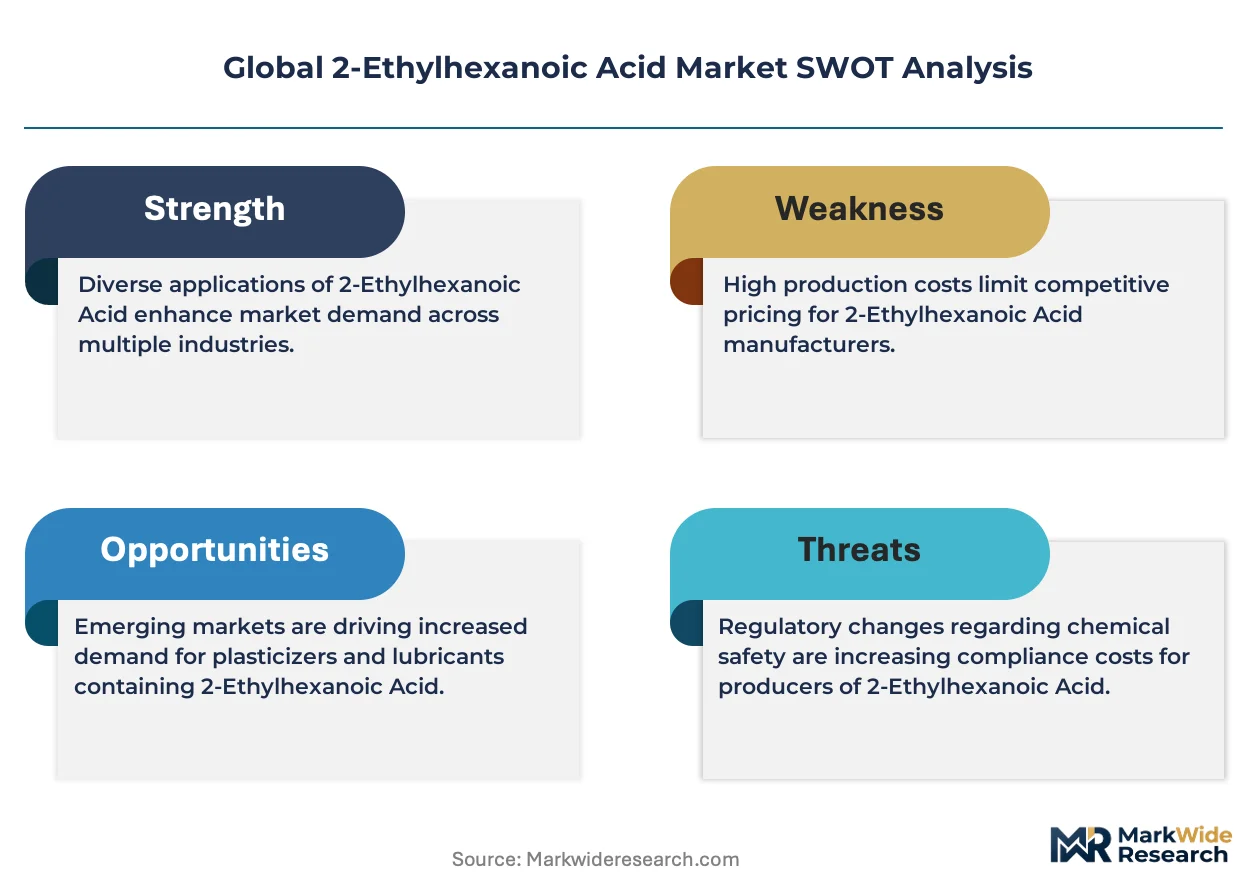
Oxo-alcohol feedstock volatility and REACH registration tier upgrades are compressing margin pools for non-integrated producers while rewarding C4 chemistry complexes with captive oxidation capacity.
Growth Catalysts
- GB 38508 VOC limits:China's coatings standards are forcing reformulation toward low-emission alkyd resins, pulling technical-grade 2-ethylhexanoic acid into high-specification paint applications.
- Semiconductor precursor demand:Reagent-grade material with sub-ppb metal specifications is electrifying procurement volumes from electronic chemical suppliers serving wafer fabrication.
- East China manufacturing corridor:Concentrated specialty chemical capacity around Shanghai and Ningbo is shortening logistics loops for Asia-Pacific metal salt and ester derivative producers.
Market Restraints
- Propylene feedstock volatility:Crude-linked C4 stream pricing transmits directly to 2-ethylhexanoic acid cash costs, eroding margin stability for non-backward-integrated manufacturers.
- REACH analytical certification burden:ECHA tiered registration requirements are elevating testing expenditures for exporters serving EU lubricant additive and paint segments.
- Isooctanoic acid substitution:Branched C8 acid alternatives with comparable metal chelation performance are capturing share in select PVC stabilizer applications.
Strategic Opportunities
- India specialty chemical expansion:PLI scheme incentives for chemical manufacturing are drawing capacity investment toward domestic 2-ethylhexanoic acid production for metal salt derivatives.
- Bio-based feedstock pathways:Oxidation of 2-ethylhexanol from renewable C4 streams is opening carbon-accounting premiums for EU and North American sustainability-mandated buyers.
- Direct-to-formulator digital channels:Specialty chemical platforms are compressing distributor layers for mid-volume metal soap and drier manufacturers.
Industry Challenges
- Analytical chemist scarcity:ICP-MS and GC-MS proficiency for sub-ppb contaminant verification is concentrated among aging specialist workforces in European and Japanese laboratories.
- Multi-grade inventory complexity:Parallel stocking of industrial, technical, and reagent grades with divergent certification timelines strains working capital for regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 2-Ethylhexanoic Acid Market |
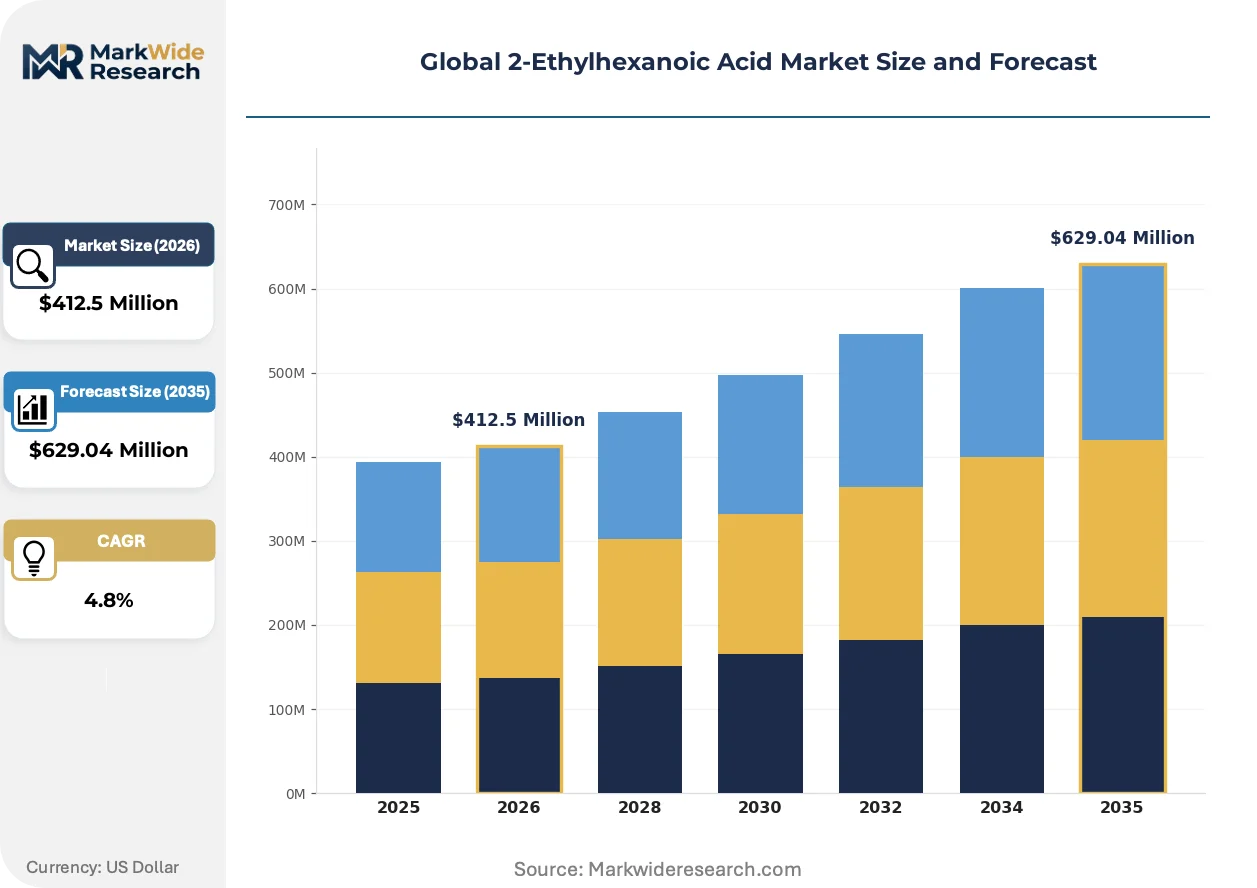
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Reagent Grade, Technical Grade, Electronic Grade Application: Plasticizers Manufacture, Paints & Coatings, Lubricant Additives, Catalyst Production, Synthetic Detergents End User: Chemical Manufacturers, Paint Producers, Lubricant Formulators, Detergent Makers, Electronic Material Suppliers Packaging Type: Drums, Bulk Containers, Intermediate Bulk Containers, Ton Bags |
| Companies Covered | BASF SE, Eastman Chemical Company, The Dow Chemical Company, Perstorp Holding AB, Oxea Corporation, Elekeiroz S.A., KH Neochem Co., Ltd., Huntsman Corporation, LG Chem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 2-Ethylhexanoic Acid Market Shifts & Advancements
Process intensification in oxidation reactors and tightening trace-metal specifications are bifurcating equipment investment strategies between commodity-scale and electronic-grade producers.
Continuous flow oxidation technology is electrifying selective conversion efficiency in 2-ethylhexanal-to-acid synthesis. German and Japanese engineering firms are deploying modular reactor trains for mid-scale specialty chemical producers. This hardware shift is compressing batch-to-batch variability and enabling just-in-time certification for semiconductor precursor supply.
REACH SVHC candidate list expansion is forcing reformulation audits across EU coatings and lubricant additive supply chains. Downstream formulators are demanding extended substance data sheets and third-party analytical verification. Metal salt derivative manufacturers serving automotive and construction verticals are absorbing the steepest compliance cost escalations.
Specification-driven procurement consolidation is compressing supplier counts among large-scale PVC stabilizer and alkyd resin producers. Direct technical service relationships are displacing arm's-length distributor transactions for volume accounts. This behavioral shift is most visible in German and Chinese paint manufacturing clusters where formulation co-development agreements now precede multi-year supply commitments.
Global 2-Ethylhexanoic Acid Market Segmentation
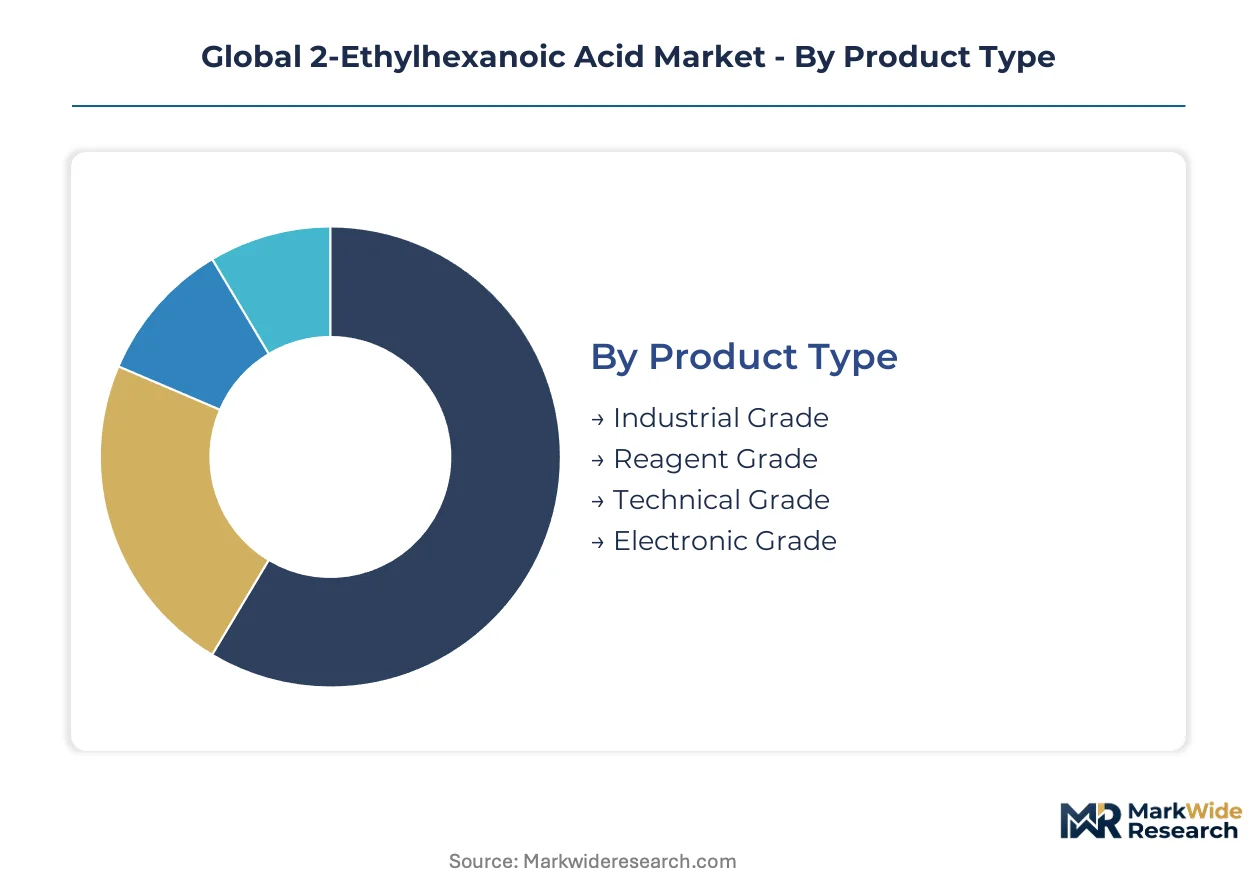
Segmentation in 2-ethylhexanoic acid markets tracks the divergence between commodity-scale industrial flows and precision-grade electronic material supply. Grade purity thresholds determine equipment investment, certification burden, and margin architecture across value chains.
Product Type:
Customization intensity ranges from standardized industrial bulk to hyper-specified electronic precursor material with sub-ppb metal controls.
- Industrial Grade:Standard purity material (typically 99.0-99.5%) serves high-volume plasticizer and metal salt derivative production. BASF's Ludwigshafen complex and Eastman's Kingsport operations anchor supply for PVC stabilizer manufacturers in Germany and the United States. Margin pools remain deepest here amid continuous vinyl compound formulation demand.
- Reagent Grade:Elevated purity specifications (99.5-99.9%) with comprehensive analytical certification support laboratory and pharmaceutical intermediate applications. Procurement concentrates among Japanese and European electronic chemical suppliers serving semiconductor fabrication clusters in Hsinchu and Dresden. Trace metal specifications tighten continuously for precursor deposition processes.
- Technical Grade:Mid-tier purity positioning bridges industrial commodity and precision applications. Paint producers in Germany and China are expanding procurement for high-performance alkyd resin formulations under tightening VOC regulations.
- Electronic Grade:Ultra-high purity material with ICP-MS verified sub-ppb contaminant profiles commands premium positioning. Supply concentrates among specialized Japanese and German producers serving wafer fabrication equipment manufacturers.
Most installed capacity flows through Industrial Grade. Expansion is steepest in Electronic Grade.
Application:
Volume scale inversely correlates with specification stringency across derivative chemistry endpoints.
- Plasticizers Manufacture:Dominant volume sink consuming industrial-grade material for PVC plasticizer and stabilizer synthesis. Formulators in China's East China corridor around Shanghai and Ningbo drive procurement for vinyl compound production serving construction and automotive verticals.
- Paints & Coatings:Technical-grade material enables high-performance alkyd resin synthesis for industrial and decorative coatings. Germany's coatings cluster and China's Yangtze River Delta manufacturing belt concentrate demand under REACH and GB 38508 compliance pressures.
- Lubricant Additives:Metal salt derivatives serve corrosion inhibitor and detergent functions in engine oil formulations. North American and European blenders absorb steady volumes amid EPA TSCA and REACH registration documentation requirements.
- Catalyst Production:Drier metal soaps accelerate oxidation in coatings and printing inks. Italian and Spanish coatings manufacturers maintain concentrated procurement relationships with C4-integrated suppliers.
- Synthetic Detergents:Minor volume application for surfactant intermediate synthesis. Southeast Asian detergent manufacturers source through regional distributors with limited backward integration.
Plasticizers Manufacture retains the largest installed demand base. Paints & Coatings is climbing the fastest on regulatory reformulation momentum.
End User:
Procurement sophistication stratifies between integrated chemical manufacturers and formulation-dependent downstream processors.
- Chemical Manufacturers:Integrated producers with captive oxidation capacity or direct oxo-alcohol feedstock access dominate volume procurement. Perstorp's Swedish specialty chemical operations and Chinese state-owned petrochemical complexes exemplify this structural advantage.
- Paint Producers:Formulation-driven procurement concentrates among German and Chinese manufacturers expanding technical-grade uptake for alkyd resin reformulation. Direct technical service relationships increasingly displace distributor intermediation.
- Lubricant Formulators:Additive compounders in the United States and Europe source metal salt derivatives under EPA and REACH compliance documentation burdens. Procurement consolidation favors suppliers with integrated analytical certification capabilities.
- Detergent Makers:Regional formulators in Southeast Asia and Latin America absorb commodity-grade flows through arm's-length distributor channels with limited specification differentiation.
- Electronic Material Suppliers:Precision procurement from Japanese and German specialists serving semiconductor fabrication. Sub-ppb certification requirements concentrate supply among aging specialist analytical workforces.
Most installed capacity flows through Chemical Manufacturers. Expansion is steepest in Electronic Material Suppliers.
Packaging Type:
Logistics configuration tracks shipment scale, hazard classification, and customer handling infrastructure.
- Drums:Standard 200-liter steel or HDPE containers serve mid-volume chemical manufacturers and paint producers lacking bulk handling infrastructure. German and Italian coatings clusters maintain substantial drum-based procurement.
- Bulk Containers:Tank truck and railcar shipments dominate integrated chemical manufacturer supply chains. Ludwigshafen and Antwerp petrochemical complexes optimize through pipeline-connected bulk transfer.
- Intermediate Bulk Containers:1000-liter IBC totes bridge drum and bulk economics for regional distributors serving fragmented lubricant and paint formulators. East China chemical logistics hubs concentrate IBC repackaging operations.
- Ton Bags:Flexible intermediate bulk containers serve solid derivative shipments including metal salt powders. Indian specialty chemical expansion under PLI scheme incentives is drawing ton bag logistics investment.
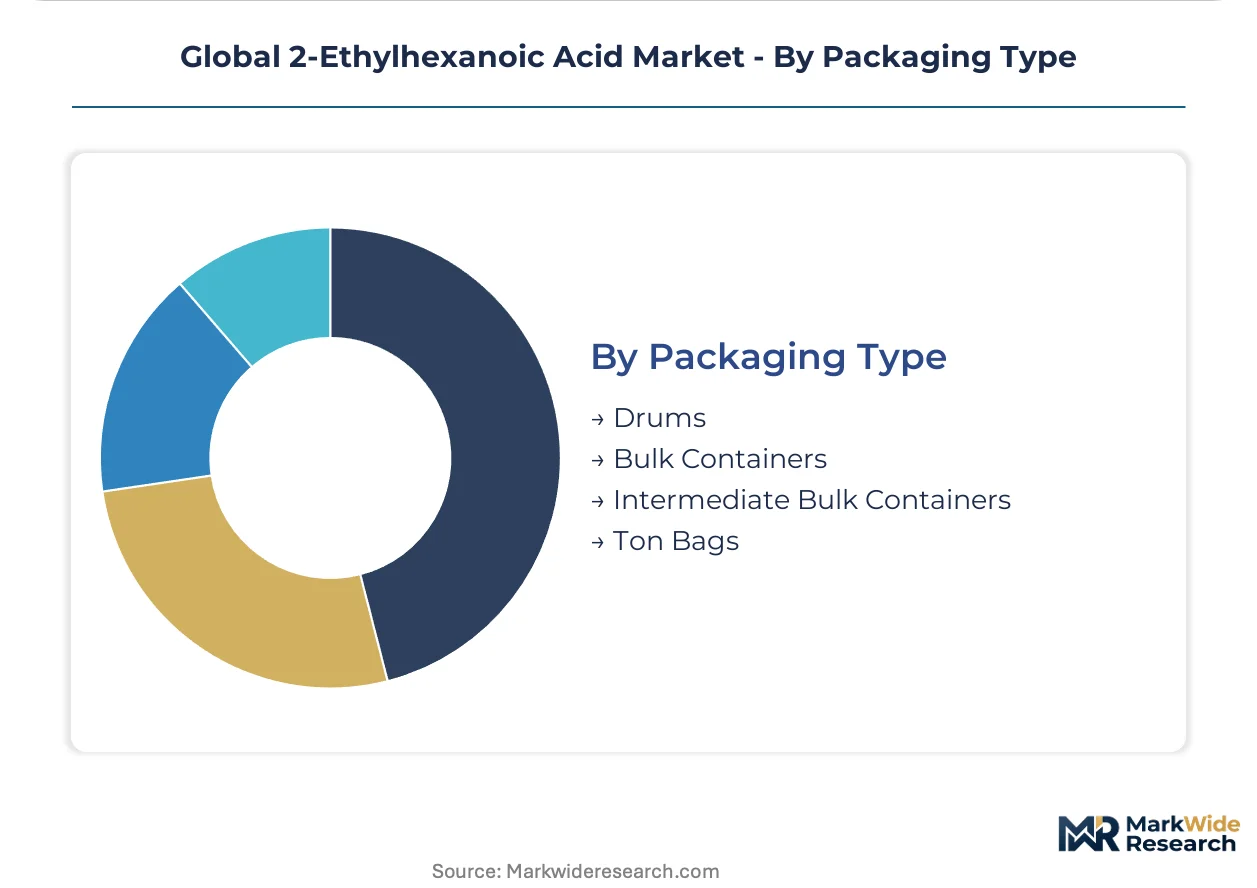
Most installed capacity flows through Bulk Containers. Expansion is steepest in Intermediate Bulk Containers on distributor consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are shifting production capacity toward jurisdictions with streamlined chemical registration frameworks. Manufacturers are relocating oxidation assets to exploit gaps between REACH compliance costs in the European Union and less burdensome certification regimes elsewhere.
China
GB 38508 VOC limits are forcing alkyd resin reformulation across the Yangtze River Delta manufacturing belt. MEE enforcement of dual carbon goals is tightening emissions scrutiny at Ningbo petrochemical complexes. Shanghai specialty chemical producers are expanding technical-grade 2-ethylhexanoic acid output for domestic paint manufacturers.
Germany
ECHA REACH tier upgrades are elevating analytical certification expenditures for lubricant additive exporters. The country's coatings cluster around Ludwigshafen sustains captive C4 chemistry integration for industrial-grade supply. BASF's integrated oxidation capacity anchors regional production for PVC stabilizer manufacturers.
United States
EPA TSCA documentation requirements are shaping import protocols for metal salt derivative applications. The Gulf Coast petrochemical corridor maintains oxo-alcohol feedstock access for regional 2-ethylhexanoic acid synthesis. Eastman's Kingsport operations supply North American plasticizer compounders under consolidated procurement relationships.
India
PLI scheme incentives for chemical manufacturing are attracting capacity investment toward domestic metal salt derivative production. BIS purity specifications are tightening for imported technical-grade material serving paint formulators. Gujarat specialty chemical zones are emerging as repackaging hubs for regional distributor networks.
Japan
METI semiconductor material initiatives are accelerating reagent-grade certification for wafer fabrication precursors. JIS standards on trace metal content are concentrating supply among specialized analytical laboratories. Osaka-based electronic chemical suppliers are tightening sub-ppb verification protocols for deposition process applications.
Global 2-Ethylhexanoic Acid Market Competitive Landscape
German producers anchor one tier through integrated C4 chemistry complexes; Japanese and Korean specialists hold precision-grade positioning for electronic material applications. The vendor base stratifies between commodity-scale oxidation operators and certification-intensive reagent-grade suppliers. Three archetypes dominate: backward-integrated petrochemical majors, mid-scale specialty chemical platforms, and analytical-service-anchored electronic material specialists. Capacity expansion and direct-to-formulator channel compression represent the dominant competitive moves.
Within the integrated petrochemical tier, BASF SE and Eastman Chemical Company exemplify captive feedstock advantages. Perstorp Holding AB occupies a position among specialty chemical platforms with Nordic operational positioning. These three entities represent the structural spectrum from commodity-scale oxidation through precision-grade certification capabilities.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| The Dow Chemical Company |
| Perstorp Holding AB |
| Oxea Corporation |
| Elekeiroz S.A. |
| KH Neochem Co., Ltd. |
| Huntsman Corporation |
| LG Chem Ltd. |
| Others |
Supply & Pricing Matrix
Oxo-alcohol feedstock costs transmit directly through C4 chemistry complexes into downstream pricing tiers, with propylene volatility compressing margin pools for non-integrated manufacturers while captive oxidation operators capture grade-based premiums.
Pricing Analysis
Distributor margin compression is accelerating direct-to-formulator channel migration, particularly for mid-volume metal soap and drier manufacturers. Pricing stratifies across electronic, reagent, technical, and industrial certification grades, with sub-ppb ICP-MS verification commanding substantial analytical service premiums. Cost compression in technical-grade supply is intensifying because GB 38508 compliance investments are elevating certification burdens. Paint producers in Germany exhibit highest price sensitivity amid reformulation budget constraints, while semiconductor material suppliers demonstrate lowest sensitivity given deposition process criticality.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for metal salt derivative manufacturers seeking tariff-advantaged regional supply. Production gravity centers on Germany, China, and the United States, with Ludwigshafen, Ningbo, and Kingsport complexes anchoring respective regional flows. Feedstock dependencies rest on propylene C4 streams, oxo-alcohol intermediates, and oxidation catalyst systems. Single-source vulnerability concentrates around Japanese analytical laboratories for sub-ppb certification. Distribution runs through integrated chemical manufacturers for bulk volumes, with regional distributors handling IBC and drum repackaging for fragmented formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 2-ethylhexanoic acid market functions as a stable compounder where regulatory reformulation mandates in coatings and semiconductor material specifications generate persistent grade-differentiated demand.
For Market Incumbents: Deploy captive C4 oxidation capacity as the primary defensive lever against propylene feedstock volatility and isooctanoic acid substitution threats. BASF's Ludwigshafen integration model demonstrates how backward control over oxo-alcohol feedstock insulates margin stability. Expand electronic-grade certification capabilities to capture semiconductor precursor procurement consolidation. For New Entrants and Emerging Players: The premium-to-economy price-point gap in technical-grade supply creates entry opportunity for mid-scale oxidation operators serving India's PLI-incentivized specialty chemical expansion. Target Gujarat chemical zones for metal salt derivative production serving domestic paint formulators. Pursue direct technical service relationships displacing legacy distributor intermediation. For Investors and Strategic Acquirers: Consolidation pressure builds where analytical certification capabilities concentrate among aging specialist workforces in European and Japanese laboratories. Long-term viability favors integrated platforms with grade-flexible oxidation assets and established REACH or GB standards compliance infrastructure. Watch semiconductor capital expenditure cycles as inflection indicator for reagent-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oxo-Alcohol Feedstock | Captive C4 supply secures margin stability against propylene volatility for integrated producers. |
| Electronic-Grade Certification Investment | ICP-MS analytical capabilities capture semiconductor precursor procurement from wafer fabrication clusters. |
| Direct-to-Formulator Channel Expansion | Technical service relationships displace distributor layers for alkyd resin and metal soap manufacturers. |
| India Capacity Buildout under PLI Incentives | Domestic production serves regional metal salt derivative demand with tariff-advantaged positioning. |
| Continuous Flow Oxidation Technology Deployment | Modular reactor trains from German engineering firms compress batch variability for just-in-time certification. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at C4-integrated complexes, procurement leads at PVC stabilizer and alkyd resin manufacturers, distribution channel partners in East China logistics hubs, and technical R&D directors at electronic chemical suppliers. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and REACH registration databases. Bottom-up grade-tier demand modeling and top-down petrochemical capacity assessment provided cross-verification.
Historical reference periods anchored the projection horizon across industrial, technical, reagent, and electronic grade tiers, with end-use segmentation spanning plasticizers, paints and coatings, lubricant additives, catalyst production, and semiconductor precursors. CAGRs were derived from installed capacity utilization trends and regulatory-driven reformulation timelines. Forecast inputs incorporated propylene feedstock price elasticity and REACH tier upgrade compliance cost trajectories.
Caveats apply where feedstock volatility, regulatory registration delays, or analytical chemist workforce constraints could materially shift the outlook. Forecasts reflect documented assumptions regarding oxo-alcohol supply continuity and semiconductor capital expenditure cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Zinc Chloride Market
Bulk Chemicals
Global Sodium Phosphate Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Castor Wax Market
Bulk Chemicals
Global Quinine Sulphate Market
Bulk Chemicals
Global Ground and Precipitated Calcium Carbonate Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
Global Concentrated Nitric Acid Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Ethyl Mercaptan Market
Bulk Chemicals
China Lime Market
Bulk Chemicals
Brazil Magnesium Phosphate Market
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market