
 Prescription Hair Loss and Hair Removal Drugs Market | 2026-2036
Prescription Hair Loss and Hair Removal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Prescription Hair Loss and Hair Removal Drugs Market Analytics
Prescription-grade minoxidil formulations are redrawing competitive boundaries in hair restoration pharmacotherapy. Merck & Co., Inc. anchors its position through decades of clinical data supporting its oral 5-alpha-reductase inhibitor portfolio. Pfizer Inc. leverages global manufacturing scale to sustain supply reliability across regulated markets. Johnson & Johnson competes through dermatologist-channel depth and topical formulation expertise.
Prescription hair loss and hair removal drugs comprise FDA-approved small-molecule therapeutics—typically minoxidil, finasteride, eflornithine, and spironolactone—formulated for topical, oral, or injectable administration to modulate androgen-mediated follicular activity. These agents function primarily through vasodilation, enzyme inhibition, or anti-androgenic mechanisms to arrest progression of androgenetic alopecia or suppress hirsutism in clinical and home-care settings. Oral finasteride and topical minoxidil command the largest revenue pools within the product type dimension, reflecting entrenched physician familiarity and broad insurance coverage. The injectable delivery mode represents the fastest-expanding segment, driven by compounding pharmacy innovation and patient preference for reduced application frequency. Home care channels are capturing incremental volume as telehealth prescribing normalizes post-pandemic, though dermatology clinics retain the highest-margin patient relationships.
The FDA, EMA, and national equivalents such as India's CDSCO govern approval pathways, manufacturing standards, and post-market surveillance for these prescription dermatological agents. Stringent bioequivalence requirements for generic finasteride and minoxidil products limit rapid market entry by non-specialist manufacturers, preserving margin structures for established filers. Stakeholders must monitor evolving FDA guidance on compounded topical formulations, as regulatory clarity on outsourcing facility compliance will determine competitive access for emerging delivery technologies.
Market Dynamics
Telehealth prescribing platforms are collapsing the traditional gatekeeper function of dermatology clinics, funneling patients directly toward prescription-grade therapies while reshaping how oral anti-androgen and topical vasodilator therapies reach end-users.
Growth Catalysts
- FDA Labeling Updates:Revised safety communication requirements for finasteride products are prompting prescriber re-education and formulary reviews across United States health systems.
- Injectable Formulation Innovation:Compounding pharmacies are developing extended-release injectable minoxidil preparations that reduce patient application burden and improve adherence curves.
- Androgenetic Alopecia Prevalence:Aging demographics in developed economies are expanding the addressable patient pool for 5-alpha-reductase inhibitor therapies.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:China and India dominate minoxidil and finasteride API manufacturing, creating single-source vulnerability for Western formulators.
- Bioequivalence Barriers:FDA's stringent pharmacokinetic requirements for generic topical minoxidil delay market entry and preserve incumbent pricing power.
- Psychological Side-Effect Documentation:Post-marketing surveillance data on finasteride's neuropsychiatric profile has triggered prescriber caution and patient hesitancy.
Strategic Opportunities
- Latin American Market Development:Brazil's ANVISA and Mexico's COFEPRIS are streamlining registration pathways for reference-listed drugs, opening underpenetrated markets.
- Combination Therapy Protocols:Dermatology practices are piloting oral minoxidil plus low-dose oral finasteride regimens that improve efficacy endpoints.
- Direct-to-Patient Subscription Models:Telehealth platforms are building recurring revenue streams through automated refill systems and remote monitoring.
Industry Challenges
- Compounding Pharmacy Compliance:FDA's evolving guidance on 503B outsourcing facility standards creates uncertainty for injectable formulation innovators.
- Patient Acquisition Economics:Digital health platforms face escalating customer acquisition costs as competition intensifies for the same telehealth-eligible demographic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prescription Hair Loss and Hair Removal Drugs Market |
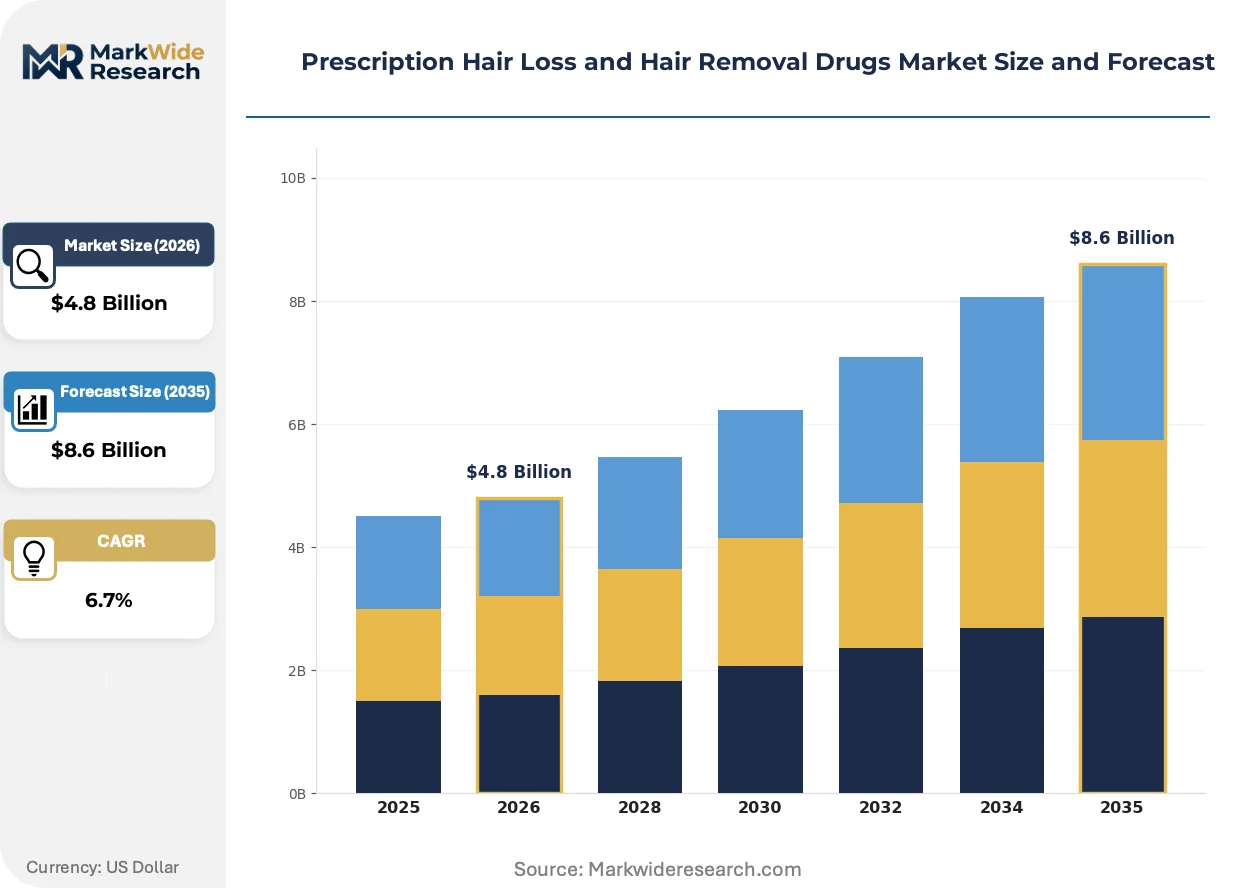
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minoxidil, Finasteride, Eflornithine, Spironolactone Therapy Area: Androgenetic Alopecia, Hirsutism, Unwanted Hair Growth, Alopecia Areata Delivery Mode: Topical, Oral, Injectable, Transdermal End User: Dermatology Clinics, Hospitals, Home Care, Pharmacies |
| Companies Covered | Merck & Co., Inc., Pfizer Inc., Johnson & Johnson, Dr. Reddy's Laboratories Ltd., Cipla Limited, Sandoz, Bayer AG, Eli Lilly and Co., Viatris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prescription Hair Loss and Hair Removal Drugs Market Evolving Landscape
Oral minoxidil repurposing is disrupting the topical-dominated hair restoration paradigm, while regulatory clarity on compounded formulations and shifting patient acquisition channels are rewriting competitive rules.
Low-dose oral minoxidil tablets originally developed for hypertension are displacing topical solutions as first-line therapy in progressive dermatology practices. Patients frustrated with topical application frequency and scalp irritation are migrating toward oral regimens. This shift is compressing margins for topical formulation specialists while creating new compounding and manufacturing demand for oral dosage forms.
EMA's updated pharmacovigilance requirements for centrally authorized dermatological products are forcing expanded post-authorization safety studies across European markets. Manufacturers must now submit periodic safety update reports with greater frequency for products containing finasteride. The regulatory burden falls heaviest on mid-sized generic filers lacking dedicated pharmacovigilance infrastructure.
Subscription-based prescribing is replacing episodic clinic visits as the dominant patient relationship model in United States hair restoration care. Telehealth platforms are capturing lifetime value through automated adherence programs rather than one-time consultations. This behavioral shift concentrates volume with vertically integrated digital health providers and marginalizes traditional dermatology referral networks.
Prescription Hair Loss and Hair Removal Drugs Market Segmentation
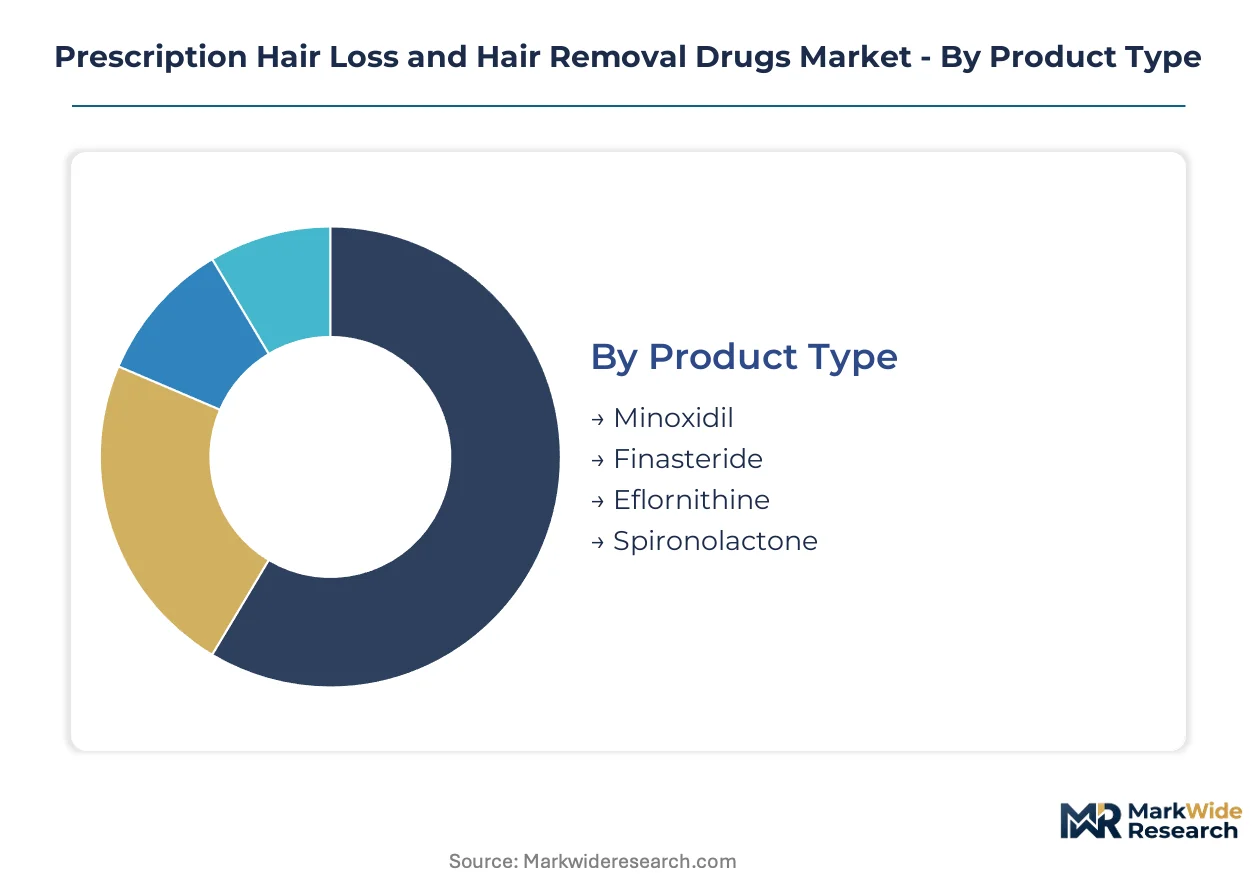
Prescription hair loss and hair removal pharmacotherapy fragments across four distinct category dimensions. Each dimension carries unique margin structures, regulatory burdens, and patient access pathways that determine competitive positioning.
Product Type:
Margin pools concentrate in oral 5-alpha-reductase inhibitors and topical vasodilators where patent cliffs have stabilized and generic entry barriers remain elevated.
- Minoxidil:A potassium channel opener originally developed for hypertension, now formulated in topical solutions and oral tablets for follicular stimulation. Dermatology practices in the United States are pivoting toward oral minoxidil as first-line therapy, driven by patient preference for reduced application burden and improved adherence curves compared to twice-daily topical regimens.
- Finasteride:A selective type II 5-alpha-reductase inhibitor that blocks dihydrotestosterone conversion, available in oral tablets and topical compounded preparations. Prescriber caution has intensified following FDA safety communications regarding neuropsychiatric adverse events, compressing volume growth in North American markets while sustaining pricing power for established filers.
- Eflornithine:An irreversible ornithine decarboxylase inhibitor formulated as a facial cream for hirsutism management. Demand concentrates in specialty dermatology channels treating polycystic ovary syndrome patients.
- Spironolactone:An aldosterone antagonist with anti-androgenic properties, prescribed off-label for female pattern hair loss. Compounding pharmacies are capturing incremental volume through customized dosing protocols.
The dominant share belongs to Minoxidil, while Finasteride is closing the gap fastest through oral formulation innovation.
Therapy Area:
Volume distribution tracks androgen-mediated conditions where pharmacological intervention offers measurable efficacy endpoints against progression.
- Androgenetic Alopecia:Pattern hair loss driven by dihydrotestosterone sensitivity in genetically predisposed follicles. Oral finasteride and minoxidil command the largest prescription volumes, with telehealth platforms channeling patients directly toward maintenance therapy regimens.
- Hirsutism:Excessive terminal hair growth in androgen-dependent areas, predominantly affecting women with endocrine disorders. Eflornithine creams and spironolactone tablets capture specialty pharmacy dispensing volume.
- Unwanted Hair Growth:Cosmetically significant hair proliferation beyond diagnostic thresholds for hirsutism. Laser adjunct therapy and prescription topical combinations are expanding the addressable patient pool.
- Alopecia Areata:Autoimmune-mediated non-scarring hair loss with emerging JAK inhibitor competition threatening traditional prescription categories. Dermatology clinics are reserving oral anti-androgen therapy for refractory cases.
Androgenetic Alopecia retains the deepest revenue pool, though Alopecia Areata is expanding most quickly through autoimmune-targeted innovation.
Delivery Mode:
Patient adherence economics and compounding pharmacy capabilities are reshaping route-of-administration preferences across prescriber channels.
- Topical:Solutions, foams, and creams applied directly to affected skin or scalp surfaces. Twice-daily application frequency drives discontinuation rates exceeding oral alternatives.
- Oral:Systemic absorption through tablet or capsule formulations. Compounding demand is climbing fastest as dermatologists prescribe low-dose minoxidil and finasteride combinations.
- Injectable:Extended-release preparations developed by 503B outsourcing facilities. Regulatory uncertainty around FDA facility standards is constraining supply scalability.
- Transdermal:Patch-based delivery systems in limited commercial availability. Manufacturing complexity has restricted market entry to specialty formulators.
Oral formulations hold the largest installed base, while Injectable delivery is gaining share fastest through reduced dosing frequency.
End User:
Channel economics diverge sharply between high-touch clinical settings and automated direct-to-patient fulfillment models.
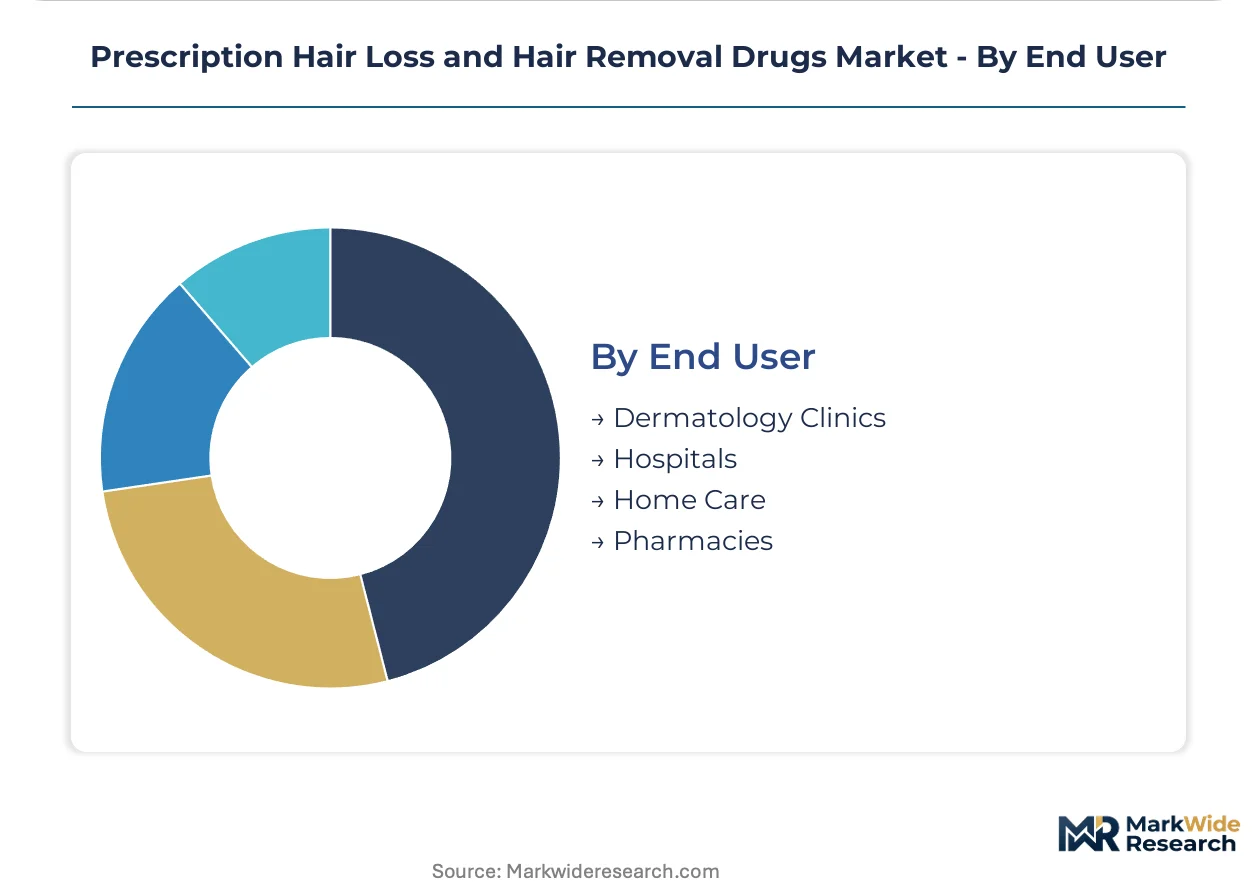
- Dermatology Clinics:Specialized practices with diagnostic capability and procedure integration. These settings retain premium pricing through combination therapy protocols and in-office dispensing.
- Hospitals:Institutional settings managing complex cases with comorbid endocrine or autoimmune conditions. Formulary committees govern anti-androgen selection.
- Home Care:Patient-managed administration following telehealth consultation. Subscription-based refill systems are displacing episodic pharmacy visits.
- Pharmacies:Retail and specialty dispensing channels handling prescription fulfillment. Insurance prior authorization requirements create friction for oral finasteride access.
Home Care is expanding most quickly, while Dermatology Clinics maintain the highest per-patient revenue capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports active pharmaceutical ingredients for minoxidil and finasteride to formulators in the United States and Europe, sustaining supply chains for Western telehealth platforms and dermatology networks.
United States
Telehealth prescribing platforms and direct-to-consumer subscription models are capturing patient volume from traditional dermatology channels. FDA labeling updates for finasteride products are prompting prescriber re-education across health systems. Boston and New York City host dense clusters of digital health startups integrating remote diagnostics with automated refill systems.
Germany
EMA pharmacovigilance requirements are expanding post-authorization safety study obligations for finasteride-containing products. Germany's statutory health insurance system maintains broad coverage for oral 5-alpha-reductase inhibitors. The Rhine-Main region concentrates dermatology research institutions piloting combination therapy protocols.
India
Domestic manufacturers supply generic finasteride and minoxidil APIs to regulated markets worldwide while building branded formulation capabilities for local consumption. CDSCO streamlined registration pathways are accelerating market entry for reference-listed drugs. Hyderabad and Ahmedabad anchor concentrated pharmaceutical manufacturing corridors serving export demand.
Brazil
ANVISA registration pathway simplification is opening access for multinational reference drugs previously delayed by complex dossier requirements. Private health insurance expansion in São Paulo and Rio de Janeiro is extending reimbursement coverage for prescription hair restoration therapies. Southeast dermatology clinic chains are adopting oral minoxidil protocols pioneered in North American practices.
Japan
PMDA maintains stringent bioequivalence standards for generic topical minoxidil that limit rapid market entry and sustain premium pricing for established filers. Aging demographics are expanding the addressable patient pool for androgenetic alopecia pharmacotherapy. Tokyo and Osaka metropolitan areas concentrate specialized dermatology practices with procedure integration capabilities.
Prescription Hair Loss and Hair Removal Drugs Market Competitive Landscape
Listed leaders compete with private specialists across formulation innovation and channel access dimensions. The market structures around three tiers: multinational originators with decades of clinical data, generic filers with regulatory scale, and emerging telehealth-integrated platforms. Strategic archetypes include API-integrated formulators, dermatology channel specialists, and direct-to-patient digital health operators. Competitive moves concentrate on portfolio diversification into oral minoxidil and vertical control over compounding pharmacy networks.
Among originator-tier pharmaceutical companies, Merck & Co., Inc. and Pfizer Inc. occupy positions anchored by historical clinical development investments. Johnson & Johnson sits within the dermatology channel specialist archetype through topical formulation heritage. Indian generic filers Dr. Reddy's Laboratories Ltd. and Cipla Limited exemplify API-to-formulation vertical integration strategies serving regulated export markets. These five entities represent distinct competitive positioning vectors rather than uniform strategic approaches.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Pfizer Inc. |
| Johnson & Johnson |
| Dr. Reddy's Laboratories Ltd. |
| Cipla Limited |
| Sandoz |
| Bayer AG |
| Eli Lilly and Co. |
| Viatris |
| Others |
Value Network & Pricing Analysis
Capacity reservation agreements with Indian API manufacturers lock in multi-year supply access for Western formulators while anchoring price visibility against raw material volatility. These contracts insulate dermatology networks and telehealth platforms from spot-market swings in minoxidil and finasteride precursor costs.
Pricing Analysis
Formulation-generation pricing gaps separate topical legacy solutions from oral repurposed tablets and emerging injectable preparations. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery complexity and prescriber channel depth. Cost compression in economy-tier topical generics intensifies as Indian filers expand capacity, while premium oral regimens retain pricing power through compounding pharmacy relationships. Telehealth subscription buyers exhibit lowest price sensitivity; retail pharmacy cash-pay patients face highest out-of-pocket friction.
Supply Chain Analysis
Inventory lead times for oral minoxidil API stretch to 16-20 weeks due to batch certification requirements at Hyderabad manufacturing clusters. Active pharmaceutical ingredient production concentrates in India and China, with secondary formulation capacity in the United States and Germany. Finished dosage form distribution runs through specialty pharmacy networks and direct-to-patient fulfillment centers. Single-source vulnerability in 5-alpha-reductase inhibitor precursors creates exposure to export licensing shifts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prescription hair loss pharmacotherapy functions as a service-attach market where subscription-based adherence programs and remote monitoring layers expand faster than standalone drug margins.
For Market Incumbents: Secure captive API supply through backward integration into Indian manufacturing corridors or long-term offtake contracts with Hyderabad-based producers. Defend formulary position by accelerating oral minoxidil portfolio expansion before compounder networks consolidate market share. For New Entrants and Emerging Players: Anchor in Latin American regulatory simplification corridors where ANVISA and COFEPRIS pathways shorten time-to-revenue for reference-listed drugs. Target Brazil's private insurance expansion as the most penetrable reimbursement environment, deploying direct-to-patient digital platforms with local pharmacy fulfillment partnerships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telehealth-integrated platforms with automated refill systems and remote dermatology monitoring capabilities. Long-term viability over the next decade hinges on regulatory navigation expertise rather than manufacturing scale alone. Monitor FDA guidance clarity on 503B outsourcing facility standards as the critical inflection signal for injectable formulation scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Oral Formulation Portfolio Expansion | Captures patient migration from topical solutions toward low-dose tablet regimens in dermatology practices. |
| Compounding Pharmacy Network Integration | Secures distribution access for customized dosing protocols beyond standard commercial formulations. |
| Direct-to-Patient Subscription Infrastructure | Builds recurring revenue streams through automated adherence programs and remote monitoring capabilities. |
| Latin American Regulatory Registration | Opens underpenetrated markets via streamlined ANVISA and COFEPRIS approval pathways for reference drugs. |
| API Manufacturing Backward Integration | Reduces single-source vulnerability to Indian and Chinese export licensing fluctuations for critical precursors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Interviews with drug development executives, regulatory affairs leads, formulary directors, and telehealth platform operators informed demand-side assumptions. Bottom-up prescription volume modeling triangulates against top-down market sizing across product type, therapy area, delivery mode, and end-user channels.
Segmentation dimensions modeled include treatment line positioning, dosage form complexity, administration route preference, patient population demographics, and regional regulatory cluster characteristics. CAGRs derive from trend extrapolation of prescription fulfillment data and telehealth platform growth trajectories across the projection horizon. Forecast inputs incorporate oral minoxidil repurposing adoption curves and compounding pharmacy capacity expansion rates.
Decision-makers should treat outputs as directional under assumptions of stable FDA guidance on compounded formulations and continued telehealth prescribing normalization; material deviation would warrant model refresh. Specific risk factors include API export restrictions, neuropsychiatric safety labeling revisions, and reimbursement policy shifts. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
US Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Global Sugar-Based Excipients Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market