
 Carbonate Market | 2026-2036
Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Carbonate Market Analysis
Direct supply contracts between carbonate producers and glass manufacturers is narrowing the role of traditional chemical distributors in bulk sodium carbonate. Albemarle Corporation leverages its Nevada-based lithium-carbonate co-production to secure long-term industrial contracts. BASF SE anchors European supply through its Ludwigshafen integrated chemical complex. Solvay SA dominates synthetic soda ash capacity in Italy and maintains tight control over pharmaceutical-grade specifications.
Carbonates are ionic salts derived from carbonic acid, with sodium carbonate (Na₂CO₃, 99.2% purity in dense grade) produced via the Solvay process or mined as trona ore, serving primarily as flux in glass melting and pH regulator in chemical synthesis. Calcium carbonate leads volume across construction fillers and paper coatings, though pharmaceutical-grade sodium bicarbonate commands the strongest margin pool due to stringent USP-NF purity requirements. Industrial-grade sodium carbonate sustains the largest revenue base through glass manufacturing offtake, while food-grade potassium carbonate grows fastest in specialty beverage processing.
The EPA enforces air emissions limits on synthetic soda ash plants under the Clean Air Act, while OSHA mandates dust exposure controls in carbonate handling facilities. REACH registration requirements in Europe restrict import of unregistered carbonate derivatives, reshaping supplier qualification protocols. Stakeholders must monitor evolving carbon border adjustments and decide between synthetic and natural trona sourcing before regulatory thresholds tighten.
Market Dynamics
Glass manufacturers are consolidating carbonate procurement through direct supply agreements, bypassing traditional chemical distributors and compressing margin pools across the value chain.
Growth Catalysts
- Flat glass expansion:Solar panel and automotive glass producers in China absorb dense-grade soda ash volumes at industrial scale.
- EU Green Deal carbon pricing:Natural trona-derived sodium carbonate gains cost advantage over synthetic production as emissions costs internalize.
- Pharmaceutical-grade bicarbonate demand:USP-NF certified potassium carbonate volumes rise in specialty beverage and dialysis applications.
Market Restraints
- Energy input volatility:Synthetic soda ash production depends on natural gas and ammonia costs, which fluctuate with European supply disruptions.
- Supply concentration risk:Wyoming trona deposits and Chinese synthetic capacity control over 70% of merchant-grade sodium carbonate availability.
- Substitution by caustic soda:Pulp and paper processors increasingly switch to sodium hydroxide for pH adjustment in certain bleaching sequences.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO registration pathways for pharmaceutical-grade carbonates remain underpenetrated relative to formulation output growth.
- Battery-grade lithium carbonate:Cathode precursor specifications create premium purity tiers above industrial-grade lithium sources.
- Carbon capture integration:Solvay-process plants retrofit carbon dioxide recovery systems to generate compliance credits under EU ETS frameworks.
Industry Challenges
- Process safety certification:OSHA and EPA joint inspections of dust-handling facilities extend compliance timelines for facility upgrades.
- Legacy logistics infrastructure:Bulk rail and river barge networks serving traditional glass corridors require capital-intensive modernization for just-in-time delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbonate Market |
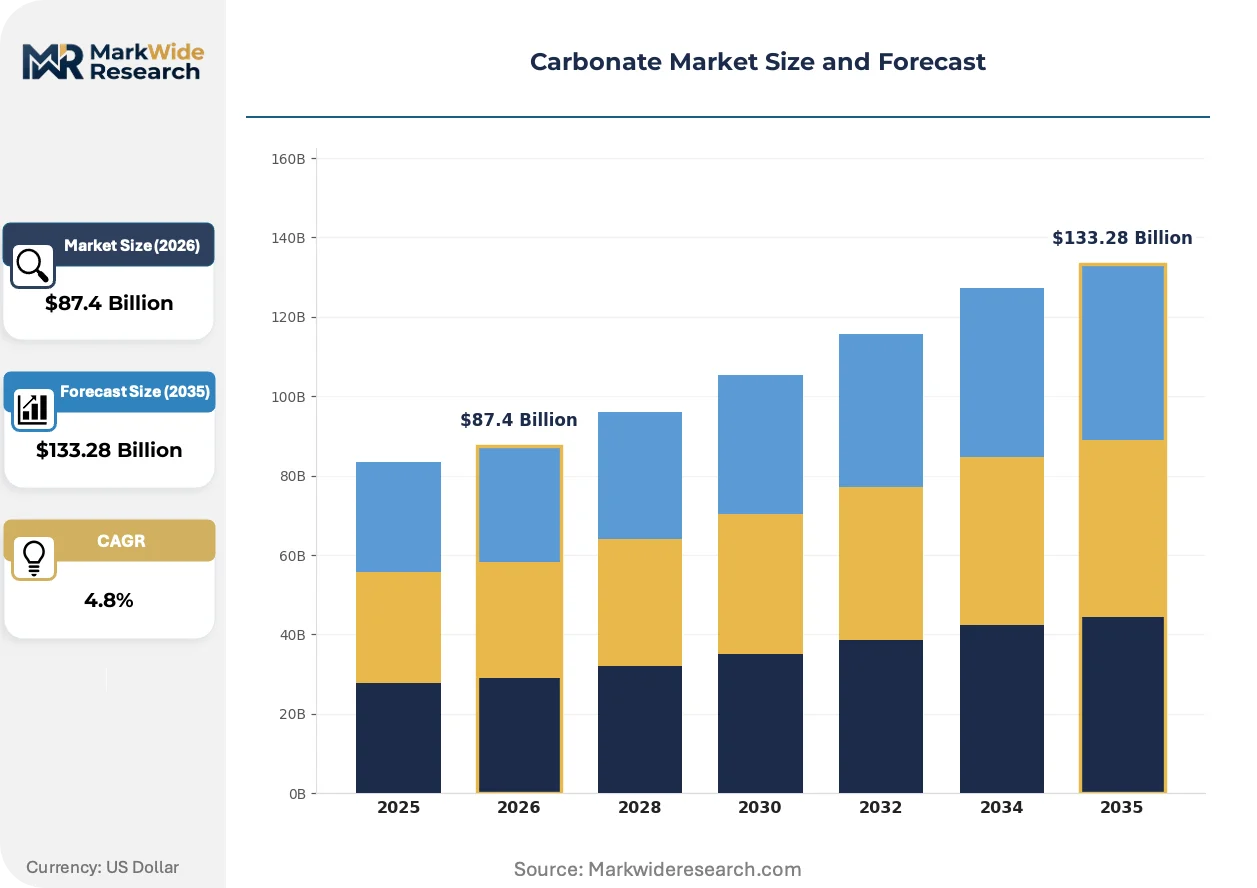
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $133.28 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Carbonate, Potassium Carbonate, Calcium Carbonate, Bicarbonate End Use Industry: Glass Manufacturing, Chemical Processing, Agriculture, Pharmaceuticals Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Agricultural Grade Form: Powder, Granules, Solution, Crystals |
| Companies Covered | Albemarle Corporation, BASF SE, FMC Corporation, Solvay SA, Evonik Industries AG, Huntsman International LLC, LyondellBasell Industries Holdings B.V., Anmol Chemicals Group, Clariant AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbonate Market Emerging Trajectories
Digital process control and emissions monitoring systems are reconfiguring how carbonate producers manage quality assurance and regulatory reporting across dispersed production assets.
Digital twin modeling is virtualizing process optimization across Solvay-process plants, enabling real-time simulation of temperature and pressure variables without physical experimentation. Glass manufacturers in Germany and Belgium deploy these systems to reduce soda ash consumption per ton of melted glass. The technology is virtualizing traditional empirical process control, compressing the competitive advantage of legacy operational expertise.
REACH registration deadlines for carbonate derivatives are tightening supplier qualification protocols for European chemical distributors. Importers must demonstrate full substance dossier compliance before warehouse stocking, delaying market entry for unregistered Asian producers. Pharmaceutical-grade sodium bicarbonate supply chains are responding by consolidating around pre-registered European warehouse operators.
Long-term offtake contracting is displacing spot market purchasing among container glass producers facing energy cost volatility. Buyers in Italy and Spain now fix twelve to twenty-four month soda ash volumes with price-adjustment clauses tied to natural gas indices. This pattern is most visible in Southern European markets where energy-intensive manufacturing faces margin compression.
Carbonate Market Segmentation
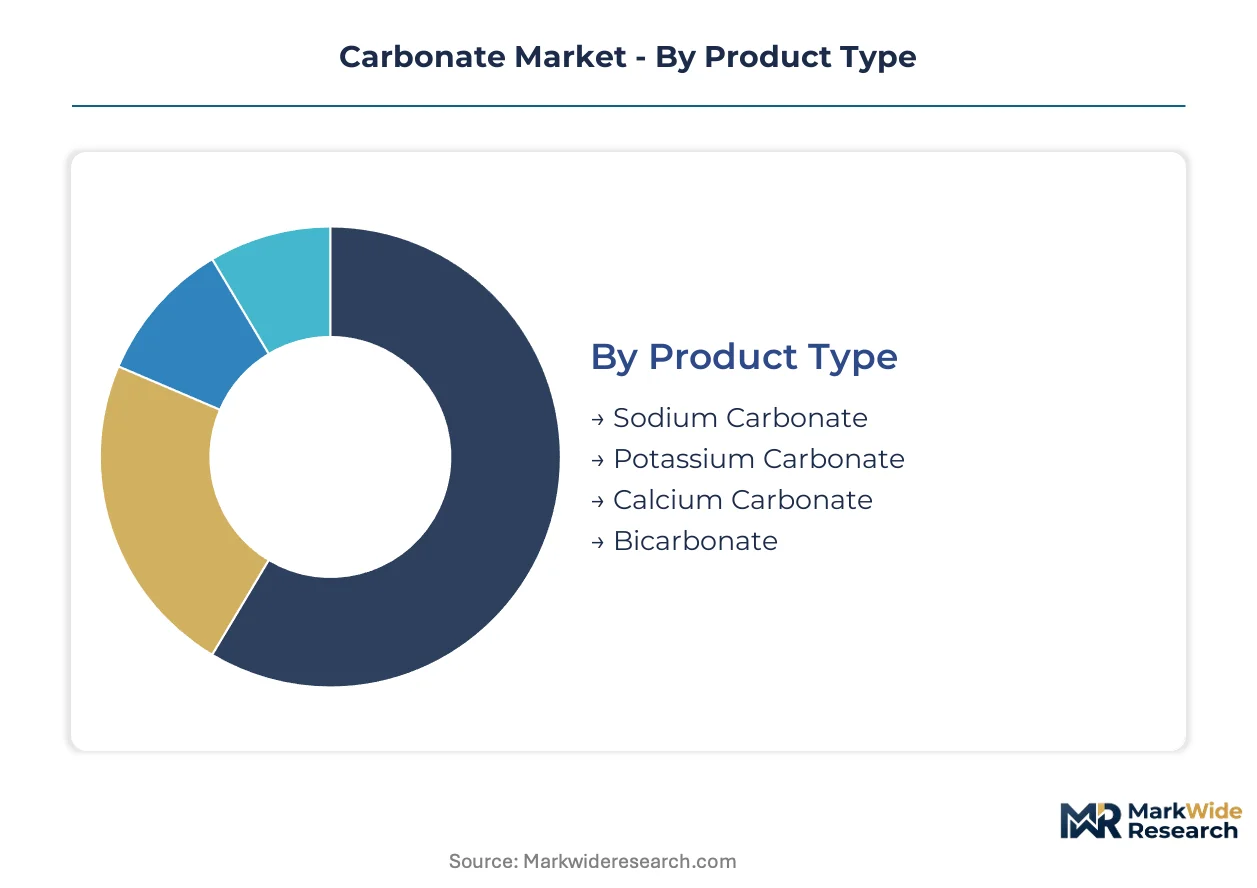
Carbonate producers structure their service and technical support models around the purity requirements and application criticality of each segment. Pharmaceutical-grade contracts demand batch certification and regulatory documentation that industrial-grade bulk sales rarely require.
Product Type:
After-sales service intensity varies sharply across carbonate chemistries, with lithium-carbonate co-production requiring specialized technical support for battery cathode manufacturers.
- Sodium Carbonate:Dense-grade material at 99.2% purity serves as the primary flux in flat glass and container manufacturing, with Solvay-process and natural trona-derived variants competing on emissions credentials. Chinese glass producers absorb the largest industrial volumes, while European buyers increasingly specify low-carbon trona sources to manage EU ETS exposure.
- Potassium Carbonate:Higher solubility and hygroscopic properties position this chemistry in specialty glass and liquid fertilizer formulations. Demand concentrates in South Korean display glass manufacturing and Brazilian agricultural blending operations where potassium nutrient delivery takes priority over sodium alternatives.
- Calcium Carbonate:Ground and precipitated grades dominate construction filler and paper coating applications with minimal post-sale technical engagement.
- Bicarbonate:Sodium and potassium variants span food leavening, pharmaceutical antacids, and dialysis solutions where USP-NF certification drives service intensity.
By volume, sodium carbonate leads. By growth pace, bicarbonate applications in dialysis and specialty beverages are climbing the fastest.
End Use Industry:
Cost tier differentiation separates commodity carbonate buyers from premium-grade purchasers willing to absorb certification and documentation premiums.
- Glass Manufacturing:Flat glass for solar panels and automotive applications consumes dense-grade soda ash at industrial scale, with Chinese producers operating the largest melting capacities globally. Container glass manufacturers in Italy and Spain increasingly favor long-term supply contracts with price-adjustment clauses tied to natural gas indices.
- Chemical Processing:pH regulation and synthesis feedstock applications absorb technical-grade carbonates where process consistency outweighs absolute purity. German and Belgian chemical complexes source through integrated pipeline networks that bypass merchant distribution.
- Agriculture:Soil amendment and fertilizer blending applications favor cost-optimized agricultural-grade specifications with minimal regulatory documentation.
- Pharmaceuticals:USP-NF certified sodium bicarbonate and potassium carbonate command the strongest margin pool due to FDA and EMA batch release requirements.
Glass manufacturing anchors volume demand. Pharmaceutical applications deliver the steepest expansion trajectory for certified grades.
Grade:
Application maturity determines how grade specifications propagate through supply chains, with food and pharmaceutical tiers requiring the most intensive supplier qualification.
- Industrial Grade:Unspecified purity tolerances serve bulk chemical synthesis and construction applications where functional performance exceeds certification needs. Wyoming trona-derived material competes with Chinese synthetic capacity on delivered cost to North American glass corridors.
- Pharmaceutical Grade:USP-NF monograph compliance, heavy metals testing, and microbial limits define this tier for dialysis solutions and intravenous preparations. CDSCO registration pathways in India remain underpenetrated relative to formulation output growth.
- Food Grade:FSSAI and FDA food additive specifications govern leavening and pH adjustment in processed foods and beverages.
- Agricultural Grade:Minimum purity thresholds for fertilizer blending allow broader source qualification and compressed documentation requirements.
Industrial grade dominates tonnage. Pharmaceutical grade is gaining share fastest as dialysis and biologic manufacturing expand.
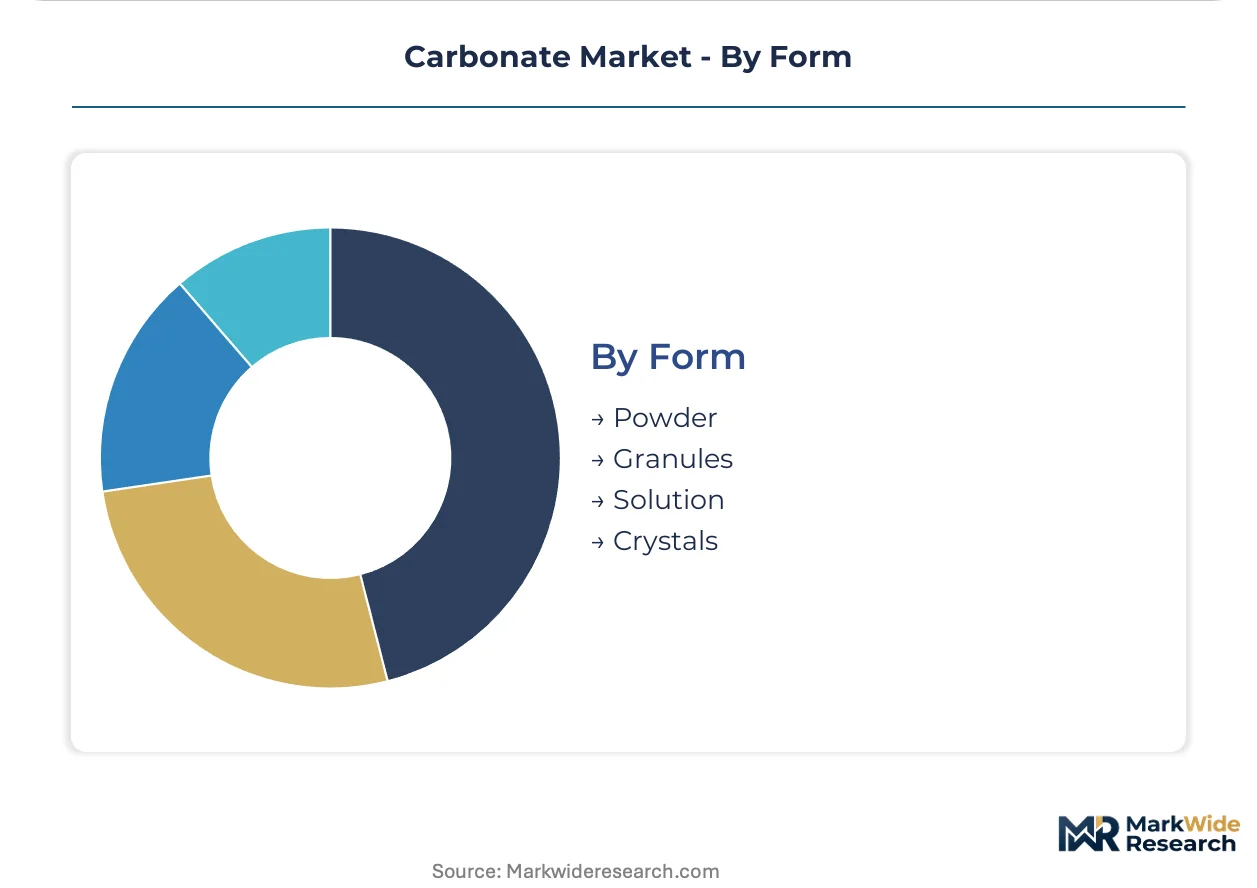
Form:
Customer type and handling infrastructure dictate form selection, with powder and granule buyers operating fundamentally different logistics systems than solution purchasers.
- Powder:Fine particle size enables rapid dissolution in chemical synthesis and uniform distribution in dry fertilizer blends. Dust exposure controls mandated by OSHA extend compliance timelines for handling facility upgrades in US manufacturing plants.
- Granules:Controlled particle size reduces dust generation during pneumatic conveying, favored by glass manufacturers operating bulk handling systems. German flat glass producers deploy digital twin modeling to optimize soda ash consumption per ton of melted granule feedstock.
- Solution:Pre-dissolved carbonate eliminates solid handling infrastructure for small-volume chemical processors and food manufacturers.
- Crystals:Defined morphology supports pharmaceutical tableting and specialized chemical synthesis where dissolution kinetics matter.
Powder form leads by volume. Solution form is expanding most quickly among food and pharmaceutical processors seeking to eliminate solid handling capital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese synthetic carbonate producers command pricing leverage over European trona miners as energy cost differentials widen, while North American natural soda ash maintains cost advantage under Clean Air Act compliance burdens.
China
Flat glass and solar panel manufacturing absorb dense-grade soda ash volumes at industrial scale. MEE emissions standards tighten synthetic production permits in Shandong and Hebei provinces. The Yangtze River Delta glass corridor concentrates melting capacity for automotive and photovoltaic applications.
United States
Wyoming trona deposits supply low-carbon sodium carbonate to container and flat glass producers nationwide. EPA Clean Air Act enforcement drives synthetic plant retrofits in the Ohio River Valley. The Green River Basin mining complex anchors North American merchant-grade availability.
Germany
EU ETS carbon pricing reshapes procurement toward natural trona imports for Ludwigshafen chemical complexes. REACH registration requirements filter unregistered carbonate derivatives from warehouse stocking. The Rhine-Main industrial belt integrates pipeline supply networks bypassing merchant distribution.
India
Pharmaceutical formulation growth outpaces CDSCO-registered carbonate supply capacity. FSSAI food additive specifications govern leavening applications in processed food manufacturing. Maharashtra and Gujarat chemical corridors concentrate technical-grade consumption for dye and detergent synthesis.
Italy
Container glass manufacturers in Lombardy and Veneto lock twelve-month soda ash contracts with natural gas price-adjustment clauses. EU Green Deal carbon border adjustments favor low-emission trona sourcing over synthetic alternatives. The Po Valley glass district sustains Southern European melting capacity.
Carbonate Market Vendor Landscape
Integrated chemical conglomerates and specialty carbonate producers split the market along purity-grade boundaries. The vendor base concentrates around three strategic archetypes: Solvay-process operators with captive ammonia supply, trona miners controlling natural deposit access, and pharmaceutical-grade specialists commanding certification premiums. Capacity expansion and long-term offtake contracting dominate competitive moves as energy volatility reshapes procurement patterns.
Among European integrated chemical producers, Solvay SA and BASF SE exemplify the conglomerate archetype with Ludwigshafen and Italian site networks. Albemarle Corporation anchors the natural resource-driven tier through Nevada-based lithium-carbonate co-production. These three occupy positions spanning industrial bulk supply through battery-grade purity tiers.
| Leading Market Players |
|---|
| Albemarle Corporation |
| BASF SE |
| FMC Corporation |
| Solvay SA |
| Evonik Industries AG |
| Huntsman International LLC |
| LyondellBasell Industries Holdings B.V. |
| Anmol Chemicals Group |
| Clariant AG |
| Others |
Supply Flow & Price Mechanics
Wyoming trona deposit control and Chinese synthetic capacity concentration anchor pricing power at the upstream mining and chemical synthesis tiers, compressing margin capture for merchant distributors while glass manufacturers extract volume discounts through direct contracting.
Pricing Analysis
The customization-premium spread between pharmaceutical-grade USP-NF certified carbonates and industrial-grade bulk material reaches three-to-one multiples. Contract-based long-term offtake dominates, with twelve to twenty-four month agreements tying soda ash prices to natural gas indices. Price differentiation hinges on certification level — FDA and EMA batch release requirements for dialysis-grade bicarbonate — and volume scale, with flat glass producers commanding lowest unit costs. Pricing pressure stems from energy input volatility as European gas supply disruptions ripple through Solvay-process economics. Container glass manufacturers in Southern Europe show highest price sensitivity; pharmaceutical formulators absorb premium tiers with minimal negotiation.
Supply Chain Analysis
Extended payment terms from trona miners to merchant distributors stretch sixty to ninety days, reflecting upstream working capital strength. Supply concentrates in the United States, China, and Turkey, with Wyoming's Green River Basin and Shandong synthetic corridors controlling over seventy percent of merchant-grade sodium carbonate. Raw material dependencies center on natural gas, ammonia, and trona ore feedstock. Single-source vulnerability runs through Wyoming trona rail corridors serving North American glass manufacturers. Distribution runs through direct pipeline networks at integrated chemical complexes, bypassing traditional merchant distribution for Ludwigshafen and Belgian buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal carbon border adjustments and REACH registration tightening are disrupting competitive positioning, rewarding early movers on low-emission trona sourcing and pre-registered supply chains.
For Market Incumbents: Build certification moats around pharmaceutical-grade bicarbonate capacity with CDSCO and EMA pre-registration. Secure backward integration into Wyoming trona mining or captive ammonia supply to deflect energy cost volatility. Anchor long-term offtake with Italian and Spanish container glass producers before carbon border adjustments tighten. For New Entrants and Emerging Players: India's underpenetrated CDSCO-registered carbonate supply relative to pharmaceutical formulation output offers white-space entry. Target battery-grade lithium carbonate purity tiers above industrial specifications, where cathode precursor demand outstrips qualified supply. Enter through toll manufacturing partnerships with established European warehouse operators holding REACH dossiers. For Investors and Strategic Acquirers: Capital is best deployed toward trona-mining specialists with low-carbon positioning and Solvay-process operators retrofitting carbon capture for EU ETS credit generation. Five-to-ten year viability favors assets with pipeline-integrated supply to German chemical corridors. Watch for MEE permit restrictions in Shandong and Hebei as inflection signals on Chinese synthetic capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trona Mining | Green River Basin access secures low-carbon feedstock advantage under EU ETS frameworks. |
| Carbon Capture Retrofit | Solvay-process plants generate compliance credits while reducing Scope 1 emissions intensity. |
| Long-term Supply Agreement | Italian container glass producers lock twelve-month volumes with natural gas price-adjustment clauses. |
| Pharmaceutical-Grade Certification Investment | USP-NF and CDSCO registration opens dialysis and biologic manufacturing premium tiers. |
| Joint Venture with Battery Cathode Producer | Lithium-carbonate co-production secures offtake for EV battery precursor specifications. |
Methodological Framework
Operator-level perspectives from plant managers at trona mining complexes, procurement leads at flat glass manufacturers, distribution channel partners, and technical R&D directors anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, Cefic chemical industry reports, customs and trade data, and EPA enforcement records. Bottom-up capacity modeling and top-down demand triangulation cross-checked volume estimates across the analysis window.
Scenario-bracketing framed optimistic, baseline, and constrained cases across the projection horizon. Segmentation dimensions modeled include grade tier, end-use industry, regional production hub, and purity specification. CAGRs derived from production capacity expansion schedules, glass manufacturing output trajectories, and pharmaceutical formulation growth rates. Battery-grade lithium carbonate purity thresholds and REACH registration timelines served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese synthetic producers or accelerated carbon border adjustment implementation would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Carbon Black Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Cellulose Powder Market
Bulk Chemicals
South America Carbon Black Market
Bulk Chemicals
North America Sodium Chlorate Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
Global Tetrahydrofuran Market
Bulk Chemicals
Commodity Plastics Market
Bulk Chemicals
Calcium Nitrate Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Global Hexane Market