
 United States Soda Ash Market | 2026-2036
United States Soda Ash Market Size, Share, and Industry Trends Forecast 2026-2036
United States Soda Ash Market Intelligence
The price-performance boundary between premium specialty soda ash and commodity dense grades is hardening as buyers in container glass and chemical production impose stricter purity thresholds. Genesis Alkali dominates Wyoming trona-based production with integrated mining and refining operations that sustain cost advantages across the Green River Basin. Tata Chemicals leverages its dual-source supply architecture to navigate freight differentials between domestic and import channels. Ciner Resources anchors its position through captive control over surface-mined reserves in the western United States.
Soda ash, or anhydrous sodium carbonate, is an alkaline white powder produced primarily through the Solvay process or from natural trona ore refining, with dense grades typically exhibiting bulk densities above 0.9 g/cm³ for glass furnace compatibility. Its primary commercial purpose centers on fluxing silica in glass melting, neutralizing acids in chemical synthesis, and softening water through ion exchange precipitation. Dense soda ash occupies the largest volume share in glass manufacturing applications where furnace throughput economics reward consistent particle size distribution, while specialty grades command margin premiums in pharmaceutical and food-grade sodium bicarbonate production. The water treatment application segment is expanding fastest as municipal utilities upgrade lime-softening systems to sodium-based alternatives across the Ohio River Valley and Southwest.
The EPA enforces National Emission Standards for Hazardous Air Pollutants at trona calcining facilities, while OSHA mandates permissible exposure limits for sodium carbonate dust in mining and processing environments. State regulators in Wyoming and California impose additional groundwater monitoring requirements on tailings impoundments that shape siting decisions for capacity expansions. Stakeholders must monitor whether proposed revisions to federal coal combustion residuals rules will tighten access to synthetic soda ash byproducts from flue gas desulfurization.
Market Dynamics
EPA's tightening National Emission Standards for Hazardous Air Pollutants are forcing Wyoming trona calciners to retrofit calcining kilns with advanced scrubbing systems, compressing operating margins while accelerating capital deployment toward cleaner production architectures.
Growth Catalysts
- Container glass furnace expansion:Texas and Louisiana flat glass facilities are expanding dense soda ash procurement volumes to feed automotive and solar panel manufacturing lines.
- IRA clean water infrastructure allocations:Municipal utilities across the Ohio River Valley are replacing lime-softening systems with sodium-based precipitation technologies.
- REACH-aligned purity thresholds:European import specifications for pharmaceutical-grade sodium derivatives are pulling higher-purity specialty grades from domestic refiners.
Market Restraints
- Natural gas price volatility:Wyoming trona calcining operations face margin compression when Henry Hub benchmarks spike above seasonal norms.
- Green River Basin supply concentration:Three integrated operators control roughly eighty percent of domestic natural soda ash capacity, creating single-source vulnerability.
- Synthetic soda ash substitution:Chinese Solvay-process imports undercut western trona-based pricing in coastal chemical derivative markets.
Strategic Opportunities
- Southwest water treatment retrofit wave:Arizona and Nevada municipal districts are accelerating sodium-based softening system deployments amid drought-driven conservation mandates.
- Carbon capture integration:Wyoming producers can monetize calciner CO₂ streams for enhanced oil recovery and food-grade applications.
- Pharmaceutical bicarbonate vertical:FDA-registered specialty grades command three-to-five-fold premiums over commodity dense material in antacid and dialysis buffer markets.
Industry Challenges
- Process engineer scarcity:Wyoming and California facilities compete for talent against Permian Basin oilfield operators offering comparable compensation.
- EPA permitting timelines:New tailings impoundment approvals now stretch eighteen to twenty-four months, delaying Green River Basin capacity additions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Soda Ash Market |
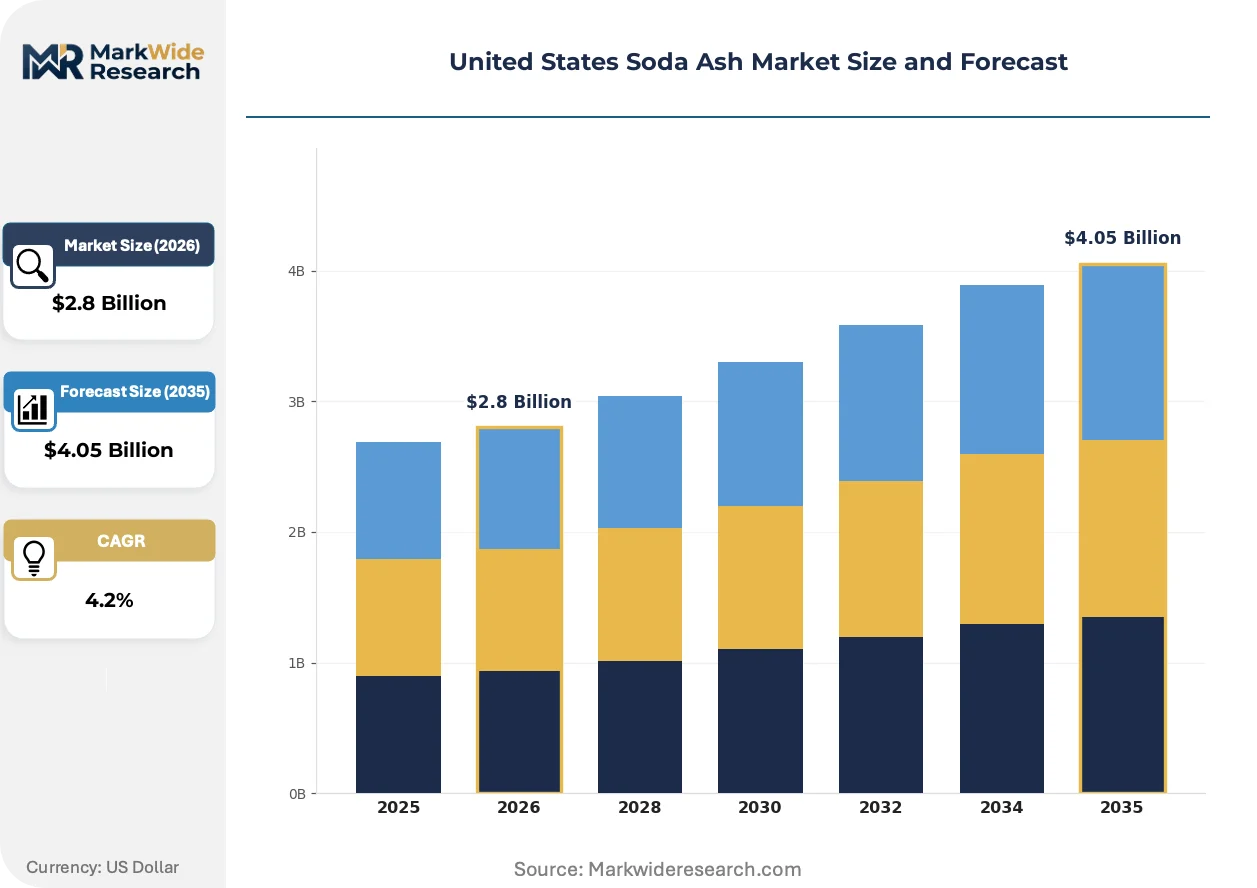
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dense Soda Ash, Light Soda Ash, Specialty Soda Ash, Granular Soda Ash End Use Industry: Glass Manufacturing, Chemical Production, Detergents, Water Treatment Distribution Channel: Direct Sales, Distributors, Retailers, Online Sales Application: Container Glass, Flat Glass, Fiberglass, Sodium Bicarbonate Production |
| Companies Covered | Tata Chemicals, Genesis Alkali, WE Soda, Searles Valley Minerals, SevEN Energy LP, Solvay, Şişecam, Olin Corporation, Ciner Resources, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Soda Ash Market Strategic Shifts & Innovations
Digital instrumentation and closed-loop process control are penetrating trona refining operations, replacing manual sampling with real-time purity verification that compresses batch-to-batch variation.
Automated laser diffraction particle sizing is automating dense grade classification at Wyoming calcining facilities. Container glass manufacturers in the Texas-Louisiana corridor are adopting this specification data for furnace feed optimization. The technology is automating quality assurance labor while enabling just-in-time procurement contracts that minimize working capital.
EPA's proposed revisions to coal combustion residuals rules are tightening eligibility criteria for synthetic soda ash derived from flue gas desulfurization. Chemical manufacturers in the Gulf Coast corridor are diversifying supply sources toward verified natural trona origin. Specialty chemical blenders are reformulating sodium silicate and detergent builder recipes to exclude synthetic material facing downstream liability exposure.
Buyer consolidation among North American container glass producers is compressing supplier negotiation cycles from annual to quarterly frameworks. Owens-Illinois and Ardagh Group procurement teams are demanding volume-flexibility clauses tied to automotive production schedules. This concentration is most visible in the Michigan-Ohio glass corridor where furnace economics reward dense soda ash suppliers offering demand-responsive logistics.
United States Soda Ash Market Segmentation
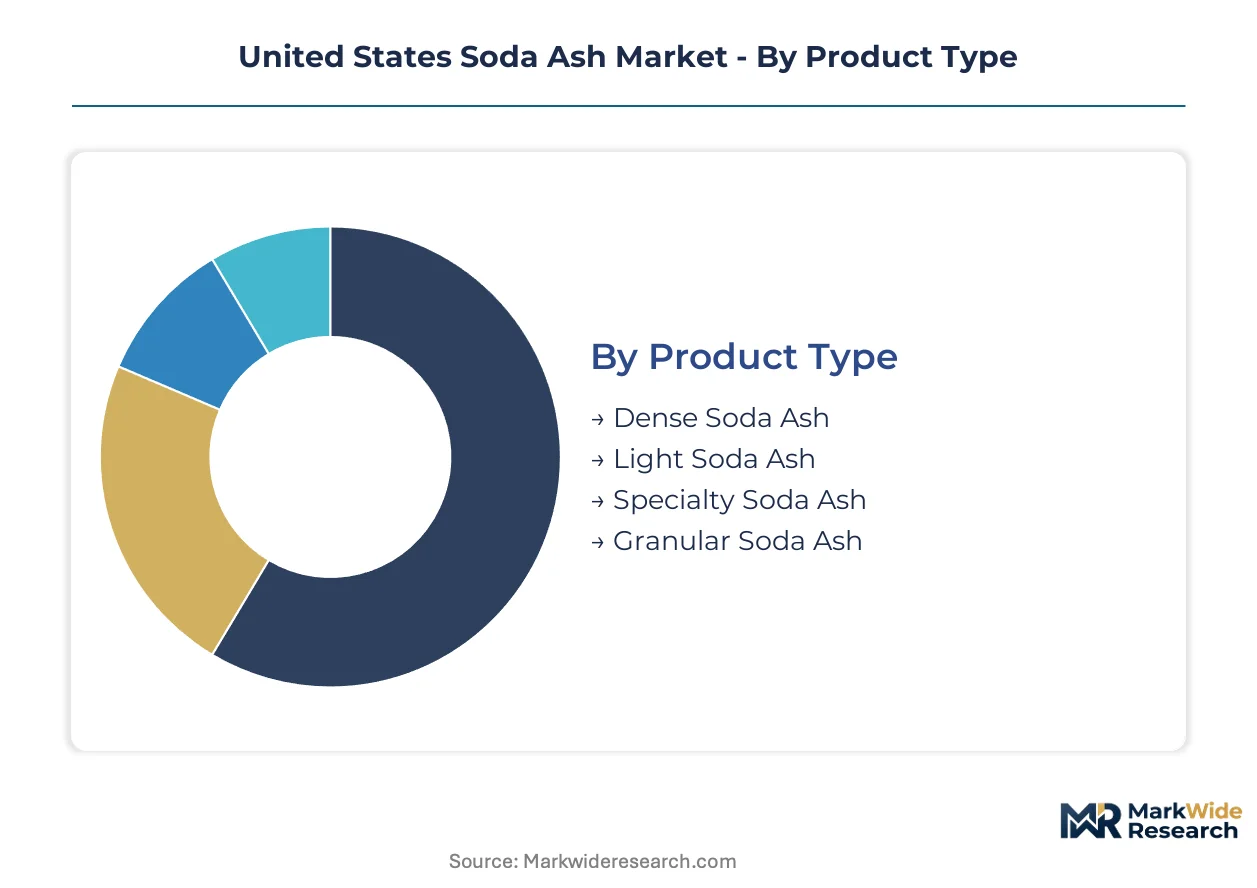
Soda ash segmentation in the United States reflects divergent certification burdens and furnace compatibility requirements across glass grades, chemical derivatives, and municipal water systems. Buyers in pharmaceutical and food-grade channels impose stricter purity thresholds than commodity dense material purchasers, fragmenting procurement specifications and margin structures.
Product Type:
FDA registration requirements concentrate in specialty grades, while EPA emissions frameworks shape production economics for dense and light variants across Wyoming and California facilities.
- Dense Soda Ash:Bulk densities exceeding 0.9 g/cm³ optimize furnace throughput in container and flat glass operations. Texas-Louisiana automotive and solar panel manufacturing lines are expanding procurement volumes to feed expanded float glass capacity.
- Specialty Soda Ash:Pharmaceutical-grade material carries FDA-registered status for antacid and dialysis buffer applications. REACH-aligned European import specifications are pulling higher-purity volumes from domestic refiners, commanding three-to-five-fold premiums over commodity dense grades.
- Light Soda Ash:Lower bulk density suits chemical synthesis and detergent builder applications where rapid dissolution accelerates processing.
- Granular Soda Ash:Controlled particle size reduces dust exposure in mining and handling environments, aligning with OSHA permissible exposure limits.
Dense soda ash sits at the top of the volume ranking, with specialty grades climbing the fastest.
End Use Industry:
Cost tier stratification separates furnace-feed glass buyers seeking scale economies from chemical producers optimizing for reagent purity.
- Glass Manufacturing:Container and flat glass segments consume the largest domestic volumes, with Owens-Illinois and Ardagh Group procurement teams demanding quarterly negotiation cycles and volume-flexibility clauses tied to automotive schedules.
- Chemical Production:Sodium silicate and detergent builder manufacturers in the Texas-Louisiana corridor are reformulating recipes to exclude synthetic material facing EPA coal combustion residuals liability exposure.
- Water Treatment:Municipal utilities across the Ohio River Valley and Southwest are replacing lime-softening systems with sodium-based precipitation technologies, accelerating fastest among end-use segments.
- Detergents:Builder applications favor light soda ash grades for rapid dissolution in formulation processes.
Glass manufacturing anchors volume demand, while water treatment expands most quickly.
Distribution Channel:
Customer type determines channel selection, with integrated glass producers favoring direct procurement and fragmented municipal buyers relying on distributor networks.
- Direct Sales:Large container glass and chemical producers negotiate long-term offtake agreements with Wyoming trona operators, capturing freight efficiencies through rail-served facilities.
- Distributors:Regional chemical blenders and smaller water treatment operators access inventory pooling and technical support through specialty chemical distribution networks.
- Retailers:Limited to consumer-facing sodium bicarbonate and small-volume water treatment applications.
- Online Sales:Emerging channel for specialty grades in research and pharmaceutical laboratory procurement.
Direct sales dominate volume flows, with distributor channels gaining share in municipal water treatment segments.
Application:
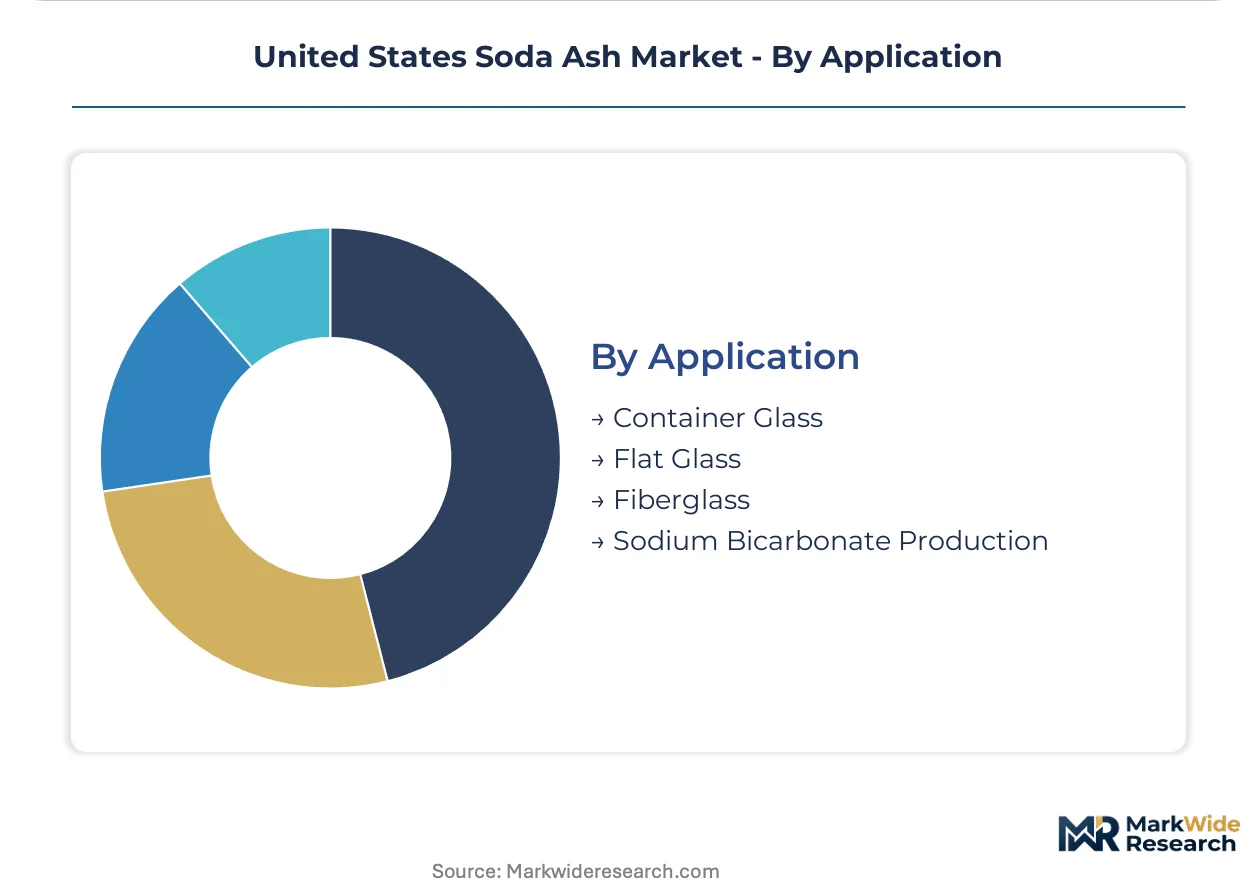
Application maturity varies across glass sub-segments, with container glass representing established demand and fiberglass oriented toward renewable energy infrastructure.
- Container Glass:Michigan-Ohio glass corridor furnaces reward dense soda ash suppliers offering demand-responsive logistics and consistent particle size distribution.
- Flat Glass:Texas and Louisiana facilities are expanding procurement to feed automotive and solar panel manufacturing lines, tying volumes to renewable energy deployment schedules.
- Fiberglass:Insulation and composite applications demand specialized grade specifications for melt viscosity control.
- Sodium Bicarbonate Production:Pharmaceutical and food-grade channels require FDA-registered specialty soda ash feedstock, filtering upstream into antacid and dialysis buffer markets.
Container glass holds the largest application share, with flat glass scaling fastest on solar and automotive demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Process engineers and mining technicians concentrate in Wyoming's Green River Basin, anchoring domestic natural soda ash production capacity. Their specialized expertise in trona calcining operations sustains the country's lowest-cost production base. This workforce distribution shapes regional supply patterns across downstream manufacturing corridors.
Wyoming
Trona mining and calcining operations dominate the Green River Basin, supplying dense grades to glass manufacturers nationwide. EPA National Emission Standards for Hazardous Air Pollutants mandate advanced scrubbing retrofits at calcining kilns, compressing operating margins. Surface-mined reserves near Green River feed integrated refining complexes serving the Texas-Louisiana chemical corridor.
Texas-Louisiana Corridor
Flat glass facilities in this region are expanding dense soda ash procurement to feed automotive and solar panel manufacturing lines. State environmental agencies enforce groundwater monitoring requirements on chemical processing facilities. Houston-area sodium silicate and detergent builder manufacturers are reformulating recipes to exclude synthetic material facing EPA coal combustion residuals liability.
California
Searles Valley brine-based production supplies specialty grades for pharmaceutical and food-grade sodium bicarbonate channels. State regulators impose additional tailings impoundment monitoring requirements that shape siting decisions for capacity expansions. The Owens Lake basin processing complex serves West Coast container glass and water treatment markets.
Ohio River Valley
Municipal utilities across Kentucky, Ohio, and Indiana are replacing lime-softening systems with sodium-based precipitation technologies. IRA clean water infrastructure allocations accelerate procurement from regional distributors. The Cincinnati-Louisville industrial corridor concentrates water treatment chemical blending operations serving municipal upgrade programs.
Southwest
Arizona and Nevada municipal districts are accelerating sodium-based softening system deployments amid drought-driven conservation mandates. State-level carbon policies tighten process standards for industrial chemical users. The Phoenix-Tucson corridor anchors regional distributor networks supplying Southwest water infrastructure retrofits.
United States Soda Ash Market Key Industry Players
Top-tier vendors anchor Wyoming trona-based production, while mid-scale operators and import-dependent distributors occupy downstream tiers. Three integrated operators control roughly eighty percent of domestic natural soda ash capacity, creating a concentrated upstream structure. Strategic archetypes include captive reserve holders, dual-source supply architects, and specialty grade refiners. Dominant competitive moves center on calciner emissions retrofits and carbon capture integration for CO₂ monetization.
Within the captive reserve tier, Genesis Alkali exemplifies integrated mining and refining operations across the Green River Basin. Tata Chemicals occupies a position as a dual-source supply architect, navigating freight differentials between domestic and import channels. Ciner Resources anchors the western production base through surface-mined reserve control. These three entities represent distinct approaches to securing feedstock advantage in a geography-constrained industry.
| Leading Market Players |
|---|
| Tata Chemicals |
| Genesis Alkali |
| WE Soda |
| Searles Valley Minerals |
| SevEN Energy LP |
| Solvay |
| Şişecam |
| Olin Corporation |
| Ciner Resources |
| Others |
Cost & Logistics Intelligence
Quarterly procurement cycles demanded by Owens-Illinois and Ardagh Group procurement teams are compressing supplier negotiation windows and forcing Wyoming trona operators toward demand-responsive logistics investments that reshape margin structures across dense grade supply tiers.
Pricing Analysis
Contract-based long-term offtake agreements dominate dense grade flows to integrated glass manufacturers, while spot-market flexibility serves smaller chemical blenders. Price differentiation rests on FDA registration status and volume scale, with specialty grades commanding substantial premiums over commodity dense material. Cost compression in commodity dense tiers is intensifying because Chinese Solvay-process imports undercut western trona-based pricing in coastal markets. Municipal water treatment operators exhibit highest price sensitivity due to constrained public budgets, while pharmaceutical-grade buyers prioritize certification assurance over cost.
Supply Chain Analysis
Single-source vulnerability sits with Wyoming's Green River Basin, where three integrated operators control roughly eighty percent of domestic natural soda ash capacity. Production draws from surface-mined trona reserves, natural gas feedstock for calcining kilns, and specialized rail infrastructure serving the Texas-Louisiana corridor. Tariff exposure on Chinese synthetic imports creates downstream liability for chemical manufacturers reformulating sodium silicate recipes. Distribution runs through rail-served direct sales to large glass producers, with regional distributors pooling inventory for fragmented municipal buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Soda Ash Market functions as a regulatory compounder, with IRA clean water infrastructure allocations accelerating sodium-based softening system deployments across municipal utilities and embedding demand growth in federal spending mandates.
For Market Incumbents: Acquire carbon capture integration assets at Wyoming calcining facilities to monetize CO₂ streams for enhanced oil recovery and food-grade applications. Secure captive tailings impoundment permits ahead of eighteen-to-twenty-four-month EPA approval timelines to defend Green River Basin capacity expansion options against permitting delays. Backward integration into surface-mined reserve control reinforces feedstock security against Chinese synthetic import price pressure. For New Entrants and Emerging Players: Capture Southwest water treatment retrofit opportunities in Arizona and Nevada municipal districts where drought-driven conservation mandates accelerate sodium-based softening deployments. Target specialty pharmaceutical-grade bicarbonate verticals where FDA-registered status commands substantial margin premiums over commodity material. Partner with regional distributors serving fragmented municipal buyers to bypass direct sales barriers dominated by incumbent rail-served operators. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty grade refiners possessing FDA-registered production lines and REACH-aligned European export certification. Long-term viability over a five-to-ten-year window favors operators integrating carbon capture monetization with calciner emissions compliance investments. Watch EPA coal combustion residuals rule revisions as the signal indicating synthetic soda ash liability exposure expansion and natural trona origin verification premium crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| Calciner Emissions Retrofit | EPA National Emission Standards compliance secures operating permits for Wyoming trona facilities. |
| Carbon Capture Integration | CO₂ monetization for enhanced oil recovery creates revenue streams from compliance investments. |
| Specialty Grade Certification | FDA registration unlocks pharmaceutical bicarbonate markets commanding substantial margin premiums. |
| Long-term Supply Agreement | Quarterly volume-flexibility contracts with container glass producers lock in furnace feed demand. |
| Joint Venture | Regional distributor partnerships penetrate fragmented municipal water treatment procurement channels. |
Research Approach
Coverage spans the Green River Basin, Texas-Louisiana chemical corridor, California Searles Valley, and Ohio River Valley municipal districts, with primary inputs from each. Plant managers at Wyoming trona calcining facilities, procurement leads at Owens-Illinois and Ardagh Group, distribution channel partners serving Southwest water treatment districts, and technical R&D directors at sodium silicate manufacturers provided structured interviews. Secondary validation drew from EPA enforcement records, SEC 10-K filings of listed chemical producers, customs trade data on Chinese synthetic imports, and American Chemistry Council industry reports. Bottom-up volume modeling triangulated against top-down value estimates across dense, specialty, light, and granular grade categories.
Granularity-level modeling distinguished product type, end-use industry, distribution channel, and application segments with distinct certification burdens and furnace compatibility requirements. CAGRs were derived through trend extrapolation of glass manufacturing expansion schedules, water treatment infrastructure retrofit timelines, and pharmaceutical-grade demand pull from REACH-aligned European specifications. Forecast inputs incorporated Henry Hub natural gas price volatility scenarios, EPA permitting timeline distributions, and IRA clean water allocation disbursement patterns across the analysis window.
Henry Hub price spikes above seasonal norms, EPA coal combustion residuals rule revision timing, and Chinese Solvay-process import tariff adjustments are the dominant revision risks warranting forecast reassessment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Japan Caustic Potash Market
Bulk Chemicals
North America Polyvinyl Chloride (PVC) Market
Bulk Chemicals
Global 2-Ethylhexanoic Acid Market
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
Sodium Hydrosulfide Market
Bulk Chemicals
Para Nitrophenol Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Mangiferin Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Europe Lime Market
Bulk Chemicals
Tertiary Butylhydroquinone Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
4-Diisopropylbenzene Market