
 Calcium Hypophosphite Market | 2026-2036
Calcium Hypophosphite Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Hypophosphite Market Analysis
Modular packaging configurations for calcium hypophosphite is shifting procurement patterns across buyer tiers. Hubei Xingfa Chemicals Group leverages integrated phosphate supply chains to control input costs. Solvay SA anchors European distribution through REACH-certified material streams. American Elements specializes in high-purity grades for North American laboratory and electronics buyers.
Calcium hypophosphite is a calcium salt of hypophosphorous acid with the formula Ca(H2PO2)2, typically manufactured through neutralization of hypophosphorous acid with calcium carbonate or calcium hydroxide, and serves primarily as a reducing agent in electroless nickel plating and as a nutrient source in specialized fertilizers. Industrial grade material dominates volume flows due to sustained electroplating demand, while pharmaceutical grade commands premium positioning through USP and EP certification requirements. Food grade applications in preservation face slower expansion as clean-label trends reshape additive acceptance across European and North American retail channels.
REACH registration obligations in Europe, EPA chemical data reporting in the United States, and China's GB standards under SAMR oversight collectively constrain market entry for uncertified producers and elevate compliance spending across the supply base. FDA food additive regulations and FSSAI standards in India further segment grade-specific market access by application. Stakeholders must monitor evolving nickel plating substitution technologies and phosphorus discharge limits that could redirect demand toward alternative reducing chemistries.
Market Dynamics
Electroless nickel plating substitution by direct laser metal deposition is compressing industrial-grade calcium hypophosphite offtake while REACH-certified pharmaceutical-grade streams command widening premiums. Supply concentration in Hubei province creates procurement bottlenecks for European compounders seeking dual-certified material.
Growth Catalysts
- Pharmaceutical-grade purity mandates:REACH registration deadlines in Europe compel compounders to source USP-certified material, tightening specification requirements across the supply base.
- China:SAMR oversight of GB standards for food-grade applications creates compliance-driven demand for certified domestic production.
- Electroless nickel in aerospace component finishing:Surface treatment requirements for turbine blades sustain reducing agent consumption despite substitution pressures in general manufacturing.
Market Restraints
- Phosphorus discharge limits:EPA effluent guidelines in the United States raise wastewater treatment costs for plating operations using hypophosphite-based chemistries.
- Supply concentration risk:Hubei province dominates merchant-grade production, exposing buyers to single-origin disruption from environmental inspections or energy rationing.
- Direct laser metal deposition:Additive manufacturing technologies eliminate reducing agent requirements in certain aerospace and medical device applications.
Strategic Opportunities
- India:FSSAI food additive regulations create certified-grade demand as domestic pharmaceutical formulation expands.
- Battery-grade phosphorus compounds:Lithium iron phosphate cathode manufacturing offers adjacent demand for high-purity hypophosphite derivatives.
- EU Green Deal:Circular economy mandates for metal recovery incentivize closed-loop electroless plating systems using recyclable reducing chemistries.
Industry Challenges
- Analytical chemist shortage:ICP-MS proficiency for phosphorus speciation testing bottlenecks quality control hiring at certification laboratories.
- Dual REACH-FDA registration timelines:Concurrent European and United States pharmaceutical-grade approvals extend time-to-market by 18-24 months for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Hypophosphite Market |
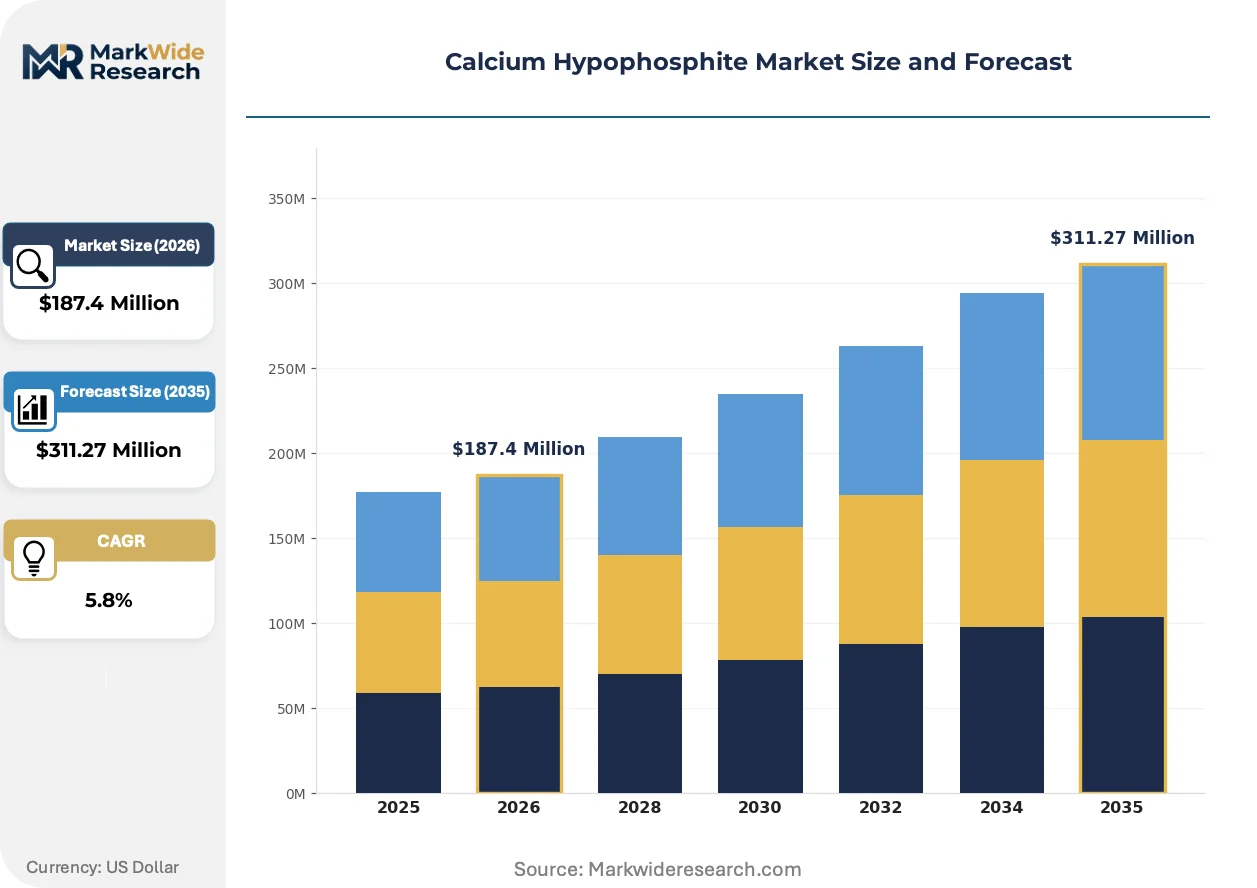
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Laboratory Grade Application: Fertilizers, Food Preservation, Pharmaceutical Manufacturing, Chemical Synthesis End User: Agriculture, Food Production, Healthcare, Chemical Industry Packaging Type: Drums, Bags, Bulk Containers, Bottles |
| Companies Covered | Hubei Xingfa Chemicals Group Co., Ltd., Solvay SA, Nippon Chemical Industrial Co., Ltd., Sigma-Aldrich, American Elements, Triveni Chemicals, LANXESS AG, Jiangxi Fuerxin Pharmaceutical & Chemical Co., Ltd., IRO Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Hypophosphite Market Emerging Trajectories
Clean-label food preservation rejection and additive manufacturing substitution are bifurcating calcium hypophosphite demand into premium-certified and commodity-industrial streams with diverging growth trajectories.
Closed-loop electroless nickel plating systems with zero liquid discharge are overtaking conventional open-tank operations in European and North American automotive component manufacturing. BMW Group and tier-one suppliers in Stuttgart and Detroit metro areas mandate phosphorus recovery rates exceeding 95 percent. This technology is compressing per-unit hypophosphite consumption while elevating specification requirements for high-activity grades.
REACH Annex XIV authorization requirements for nickel compounds are tightening occupational exposure limits across electroplating facilities in Germany, France, and Belgium. Compounders must document full substance flow analysis from hypophosphite reducing agent through nickel-phosphorus deposition. Small and mid-sized plating shops in Turin and Barcelona are consolidating or exiting as compliance costs escalate.
Modular packaging configurations are fragmenting procurement patterns as compounders shift from bulk tanker deliveries to intermediate bulk container and drum formats. North American laboratory chemical distributors now stock pharmaceutical-grade material in kilogram-scale packaging for just-in-time synthesis workflows. This shift is most visible in Boston and San Diego biotech corridors where contract research organizations prioritize inventory velocity over volume discounts.
Calcium Hypophosphite Market Segmentation
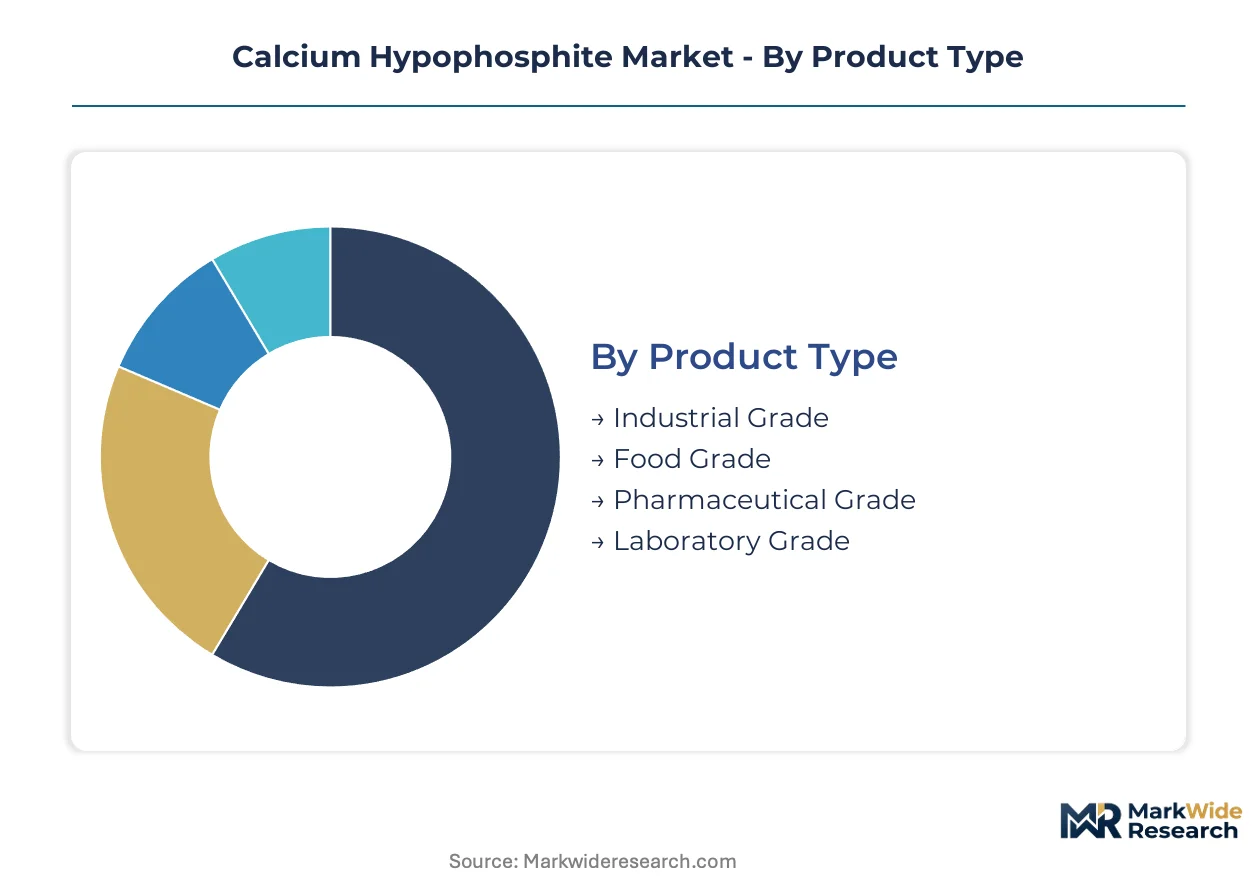
Calcium hypophosphite procurement splits sharply across certification tiers, with REACH, FDA, and FSSAI compliance requirements dictating supplier qualification timelines and pricing spreads. Buyers in electroplating, pharmaceuticals, and food preservation operate under incompatible specification regimes that prevent grade substitution.
Product Type:
REACH registration obligations in Europe and FDA food additive regulations in the United States impose distinct certification burdens across each grade tier, with pharmaceutical and food grades requiring 18-24 month approval timelines.
- Industrial Grade:Standard purity material serves electroless nickel plating operations with minimal analytical certification. Demand concentrates in Hubei province manufacturing clusters supplying automotive component finishing in Stuttgart and Detroit metro areas, though EPA phosphorus discharge limits compress per-unit consumption as closed-loop plating systems spread.
- Pharmaceutical Grade:USP and EP-certified material commands specification premiums through documented ICP-MS phosphorus speciation testing. European compounders facing REACH Annex XIV nickel compound authorization requirements source this grade exclusively, with dual REACH-FDA registration timelines constraining new supplier entry.
- Food Grade:FSSAI standards in India and FDA regulations in the United States govern preservative applications. Clean-label rejection across European and North American retail channels slows expansion despite technical efficacy in shelf-life extension.
- Laboratory Grade:High-purity material for analytical standards and research synthesis. Boston and San Diego biotech corridors drive kilogram-scale procurement through just-in-time distributor networks.
Leading the category by volume: Industrial Grade. Growing fastest: Pharmaceutical Grade.
Application:
Cost tier stratification separates commodity fertilizer deployment from premium pharmaceutical formulation, with electroplating occupying the mid-tier on volume-margin efficiency.
- Fertilizers:Calcium hypophosphite delivers bioavailable phosphorus in specialty crop nutrition. China and India concentrate procurement for industrial-grade material, with SAMR GB standards compliance required for domestic food-grade fertilizer registration.
- Pharmaceutical Manufacturing:Reducing agent applications in active pharmaceutical ingredient synthesis demand documented substance flow analysis under REACH. European compounders in Germany, France, and Belgium pay widening premiums as small plating shops exit and consolidate supply.
- Food Preservation:Antioxidant and antimicrobial functions face clean-label headwinds. Retail channel rejection in Europe and North America limits expansion despite regulatory approval status.
- Chemical Synthesis:Precursor applications in organophosphorus chemistry and metal complex formation. Laboratory and pilot-scale demand favors modular packaging configurations over bulk tanker delivery.
Highest margin capture: Pharmaceutical Manufacturing. Steepest volume trajectory: Fertilizers.
End User:
Customer type determines packaging format and certification depth, with healthcare and chemical industry buyers driving specification divergence.
- Chemical Industry:Merchant-grade procurement for electroless plating and synthesis intermediates dominates tonnage flows. Hubei province concentration exposes buyers to single-origin disruption from environmental inspections.
- Healthcare:Pharmaceutical formulation and medical device finishing require full certification documentation. REACH occupational exposure limits for nickel compounds tighten specification requirements across German, French, and Belgian facilities.
- Agriculture:Specialty fertilizer blending uses industrial-grade material with regional GB standards compliance. China and India absorb volume through domestic production.
- Food Production:Additive applications face regulatory fragmentation across FDA, FSSAI, and EFSA jurisdictions. Clean-label trends reshape acceptance faster than formulation substitution permits.
Maximum specification burden: Healthcare. Fastest procurement format shift: Chemical Industry.
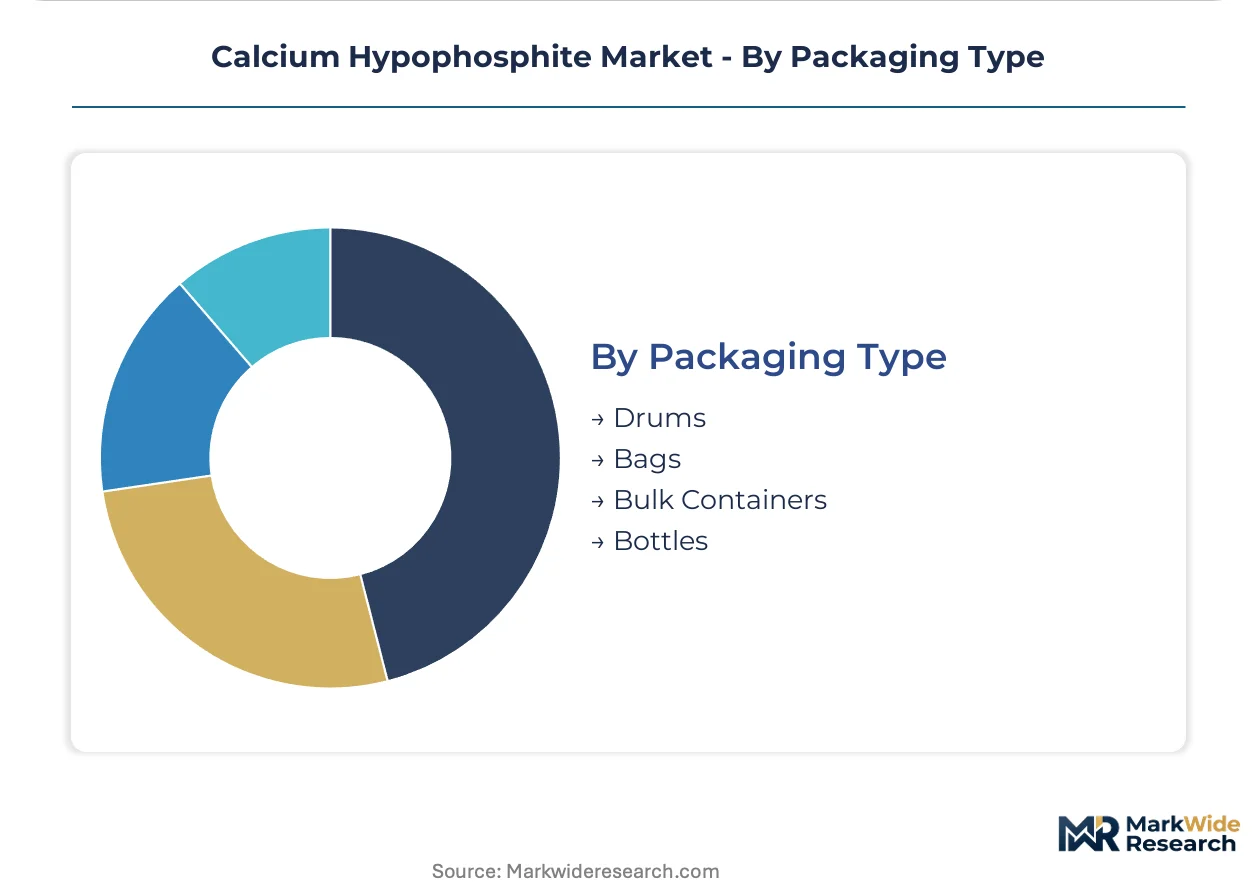
Packaging Type:
Supply chain configuration dictates format selection, with bulk concentration in electroplating and modular fragmentation in laboratory distribution.
- Bulk Containers:Tanker and tote deliveries serve high-volume electroless nickel plating operations. BMW Group and tier-one automotive suppliers mandate closed-loop systems with 95 percent phosphorus recovery rates.
- Drums:Intermediate-scale packaging bridges industrial and pharmaceutical procurement. European compounders seeking dual-certified material favor drum formats for inventory flexibility.
- Bags:Fertilizer blending and agricultural distribution use multi-layer industrial packaging. China and India domestic supply chains optimize for bagged material handling.
- Bottles:Kilogram-scale laboratory packaging serves Boston and San Diego biotech corridors. Contract research organizations prioritize inventory velocity over volume discounts.
Dominant format by tonnage: Bulk Containers. Fastest format growth: Bottles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of merchant-grade calcium hypophosphite while Germany and the United States absorb premium-certified volumes for pharmaceutical and aerospace applications. This production-consumption divide creates logistics complexity and regulatory friction across trade corridors.
China
Hubei province hosts concentrated phosphate chemical manufacturing that feeds electroless nickel plating demand in automotive supply chains. SAMR oversight of GB standards for food-grade and industrial applications elevates compliance costs for domestic producers. Environmental inspections and energy rationing in the Yangtze River Delta periodically disrupt export flows to European compounders.
Germany
REACH Annex XIV authorization requirements for nickel compounds tighten occupational exposure limits across electroplating facilities in Stuttgart and industrial zones. ECHA registration deadlines compel pharmaceutical compounders to source USP-certified material with full substance flow documentation. Small plating shops in Baden-Württemberg consolidate as compliance costs escalate beyond operational margins.
United States
EPA effluent guidelines raise wastewater treatment costs for plating operations using hypophosphite-based chemistries in Detroit metro automotive clusters. FDA pharmaceutical-grade and food additive regulations segment market access by certification tier. Boston and San Diego biotech corridors drive kilogram-scale procurement through just-in-time distributor networks.
India
FSSAI food additive regulations create certified-grade demand as domestic pharmaceutical formulation expands in Maharashtra and Gujarat manufacturing belts. CDSCO oversight of active pharmaceutical ingredient production tightens impurity profiling requirements. Industrial-grade material from domestic phosphate processors serves regional fertilizer blending operations.
Japan
METI industrial standards govern electroless nickel plating specifications for precision electronics and automotive component finishing in Nagoya and Osaka manufacturing regions. PMDA pharmaceutical-grade requirements align with USP and EP certification benchmarks for reducing agent applications. Domestic chemical producers maintain captive supply relationships with plating equipment manufacturers.
Calcium Hypophosphite Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers, creating a bifurcated structure where scale advantages clash with specification depth. The vendor base clusters around phosphate mining integration on one vector and pharmaceutical-grade analytical capability on another. Three archetypes dominate: upstream-integrated Chinese producers, European REACH-certified compounders, and North American high-purity specialists. Competitive moves center on backward integration into phosphate rock supply and dual-certification capacity expansion for pharmaceutical-grade streams.
Among China-based producers, Hubei Xingfa Chemicals Group Co., Ltd. and Jiangxi Fuerxin Pharmaceutical & Chemical Co., Ltd. exemplify the upstream-integrated archetype with phosphate supply chain control. Solvay SA represents the European REACH-certified tier, anchoring distribution through regulatory-compliant material streams. American Elements occupies the North American high-purity specialist position, serving laboratory and electronics buyers with specification-focused offerings.
| Leading Market Players |
|---|
| Hubei Xingfa Chemicals Group Co., Ltd. |
| Solvay SA |
| Nippon Chemical Industrial Co., Ltd. |
| Sigma-Aldrich |
| American Elements |
| Triveni Chemicals |
| LANXESS AG |
| Jiangxi Fuerxin Pharmaceutical & Chemical Co., Ltd. |
| IRO Group Inc. |
| Others |
Supply Flow & Price Mechanics
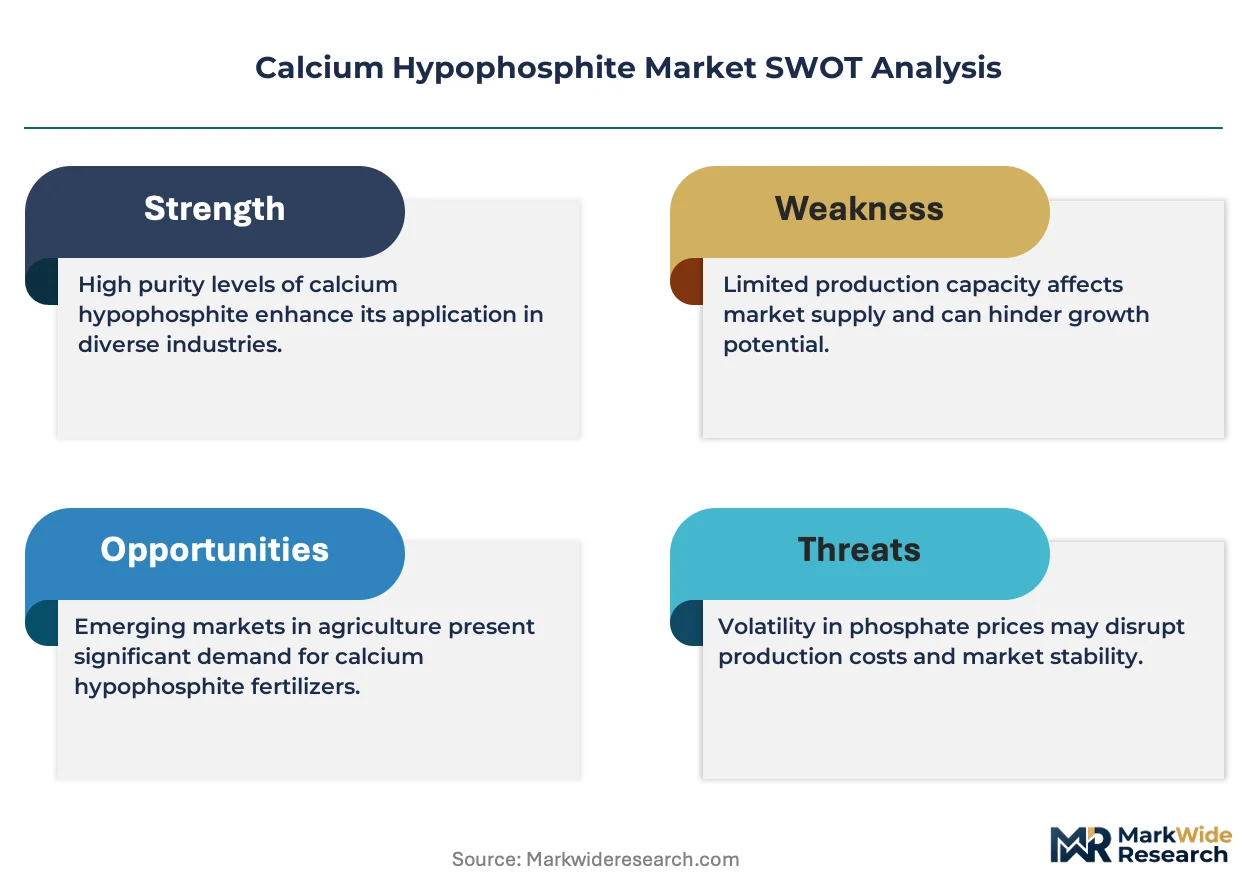
Phosphate rock index movements cascade through calcium hypophosphite supply chains, compressing margins for industrial-grade producers while pharmaceutical-grade premiums widen under REACH certification scarcity. Hubei province's concentration of merchant-grade manufacturing creates asymmetric pricing power that European compounders must absorb or circumvent through dual-certified sourcing.
Pricing Analysis
Margin tightening in industrial-grade material reflects EPA phosphorus discharge compliance costs and closed-loop plating system adoption. Three-tier pricing structure across pharmaceutical, industrial, and food-grade levels separates USP-certified streams commanding specification premiums from commodity electroplating supply. Cost-down pressure on industrial tiers accelerates because direct laser metal deposition eliminates reducing agent requirements in select aerospace applications. Automotive plating operations in Detroit and Stuttgart exhibit highest price sensitivity, while Boston and San Diego biotech corridors absorb kilogram-scale premiums for inventory velocity.
Supply Chain Analysis
REACH-FDA dual qualification gates extend supplier onboarding timelines, fragmenting procurement across certified and uncertified channels. Manufacturing concentrates in China, Germany, and the United States, with Hubei province dominating merchant-grade output. Production draws from phosphate rock, hypophosphorous acid, and calcium carbonate feedstocks. Single-source vulnerability in Hubei exposes buyers to environmental inspection disruptions and energy rationing. Distribution runs through REACH-certified compounders in Europe, direct mill relationships in China, and specialty chemical distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Calcium hypophosphite demand is bifurcating as direct laser metal deposition displaces legacy electroless nickel plating in aerospace component finishing, forcing stakeholders to recalibrate around premium-certified pharmaceutical streams.
For Market Incumbents: Deepen backward integration into phosphate supply chains to offset input cost volatility and defend margin position against Hubei province concentration. Expand dual REACH-FDA certification capacity to capture pharmaceutical-grade premiums as European compounders consolidate supply sources. Prioritize closed-loop plating system partnerships with BMW Group and tier-one automotive suppliers to secure volume offtake despite per-unit consumption compression. For New Entrants and Emerging Players: Laboratory distributor digital channels offer low-friction entry into Boston and San Diego biotech corridors where just-in-time procurement favors modular packaging over bulk supply. Target FSSAI-certified food-grade production in India as domestic pharmaceutical formulation expands and CDSCO oversight tightens impurity requirements. Pursue white-label synthesis partnerships with contract research organizations seeking kilogram-scale reducing agents. For Investors and Strategic Acquirers: Distressed-cycle entries favor REACH-certified European compounders in Germany and Belgium as small plating shops exit under nickel compound authorization costs. Long-term viability hinges on pharmaceutical-grade purity capability rather than industrial-grade volume exposure. Watch substitution rates in aerospace additive manufacturing as the inflection signal for industrial-grade demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Capacity Expansion | Simultaneous REACH-FDA registration cuts 18-24 month approval timelines for pharmaceutical-grade supply. |
| Backward Integration into Phosphate Rock | Hubei Xingfa-style supply chain control insulates margins from phosphate index volatility. |
| Closed-Loop Plating System Partnerships | BMW Group mandates 95 percent phosphorus recovery, elevating high-activity grade specifications. |
| Laboratory Distribution Channel Entry | Kilogram-scale packaging in Boston and San Diego biotech corridors captures inventory velocity premiums. |
| India FSSAI-Certified Production Buildout | Domestic pharmaceutical formulation growth in Maharashtra and Gujarat creates certified-grade demand. |
Methodological Framework
Document review covered customs trade data, ECHA registration filings, and SEC chemical industry disclosures, complemented by interviews with electroplating plant managers, pharmaceutical procurement leads, and specialty chemical distribution partners. Primary fieldwork engaged REACH compliance officers at European compounders and SAMR regulatory specialists in China. Secondary validation drew from ACC industry reports, IEA energy transition databases, and hospital procurement records. Bottom-up grade-segmentation modeling and top-down phosphate chemical demand triangulation anchored volume estimates.
Cross-referencing historical trade flows against expert panel inputs on substitution technology penetration shaped the analytical framework across the projection horizon. Segmentation dimensions included grade tier certification, end-use application, packaging format, and regional production hub clustering. CAGRs derived from phosphorus discharge regulation trajectory and pharmaceutical formulation expansion patterns. Industry-specific forecast inputs incorporated EPA effluent guideline enforcement intensity and EU Green Deal circular economy mandate adoption rates.
The model holds under steady REACH enforcement and gradual laser deposition adoption; deviation in aerospace substitution velocity or Hubei environmental inspection intensity would shift pharmaceutical-industrial grade demand splits. Forecasts reflect assumptions on certification timeline stickiness and clean-label food preservation rejection persistence. A model refresh is warranted upon material change in nickel compound occupational exposure limit tightening or lithium iron phosphate cathode manufacturing scale-up.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Guanidine Nitrate Market
Bulk Chemicals
North America Dimethyl Phosphate Market
Bulk Chemicals
Borates Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Isoprene Monomer Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Ammonium Bromide Market
Bulk Chemicals
Iodine Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
North America Sodium Chloride Market
Bulk Chemicals
Benzotrifluoride Market
Bulk Chemicals
North America Calcium Carbonate Market
Bulk Chemicals
Isatoic Acid Anhydride Market