
 Mangiferin Market | 2026-2036
Mangiferin Market Size, Share, and Industry Trends Forecast 2026-2036
Mangiferin Market Analytics
Modular dosing formats is expanding across the mangiferin value chain as brands unbundle bulk extracts into single-serve sachets and unit-dose capsules to serve direct-to-consumer channels. Chemcopia Ingredients Pvt Ltd leverages its botanical extraction infrastructure to supply standardized mangiferin isolates for pharmaceutical compounding. Merck KGaA anchors its position through analytical-grade reference materials that validate purity claims across quality tiers. Thermo Fisher Scientific Inc. competes by extending its reagent-grade portfolio into high-throughput screening applications for xanthonoid bioactivity research.
Mangiferin is a C-glucosylated xanthone (C19H18O11) extracted primarily from mango leaves and bark, functioning as a polyphenolic antioxidant with demonstrated anti-inflammatory and antidiabetic properties in preclinical models. Powder formulations currently dominate commercial volumes due to stability in bulk handling and flexibility for downstream formulation into tablets, capsules, and functional food matrices. The dietary supplements application segment leads revenue contribution as consumers seek evidence-backed botanical ingredients for metabolic health, while pharmaceutical-grade extracts command premium pricing through stringent heavy-metal and residual solvent specifications. Source type segmentation centers on Mangifera indica cultivars, where established agricultural supply chains in India and Southeast Asia support consistent raw material flows for industrial extraction.
The FDA's New Dietary Ingredient notification framework governs market entry for novel mangiferin preparations in the United States, while the EFSA Novel Food regulation shapes compliance requirements across European Union member states. India's FSSAI and CDSCO maintain parallel oversight for domestic nutraceutical and pharmaceutical applications respectively, creating a multi-jurisdictional compliance burden for exporters. Stakeholders must monitor evolving pharmacopeial monograph developments and adapt sourcing strategies to emerging sustainability certification requirements for wild-harvested versus cultivated botanical raw materials.
Market Dynamics
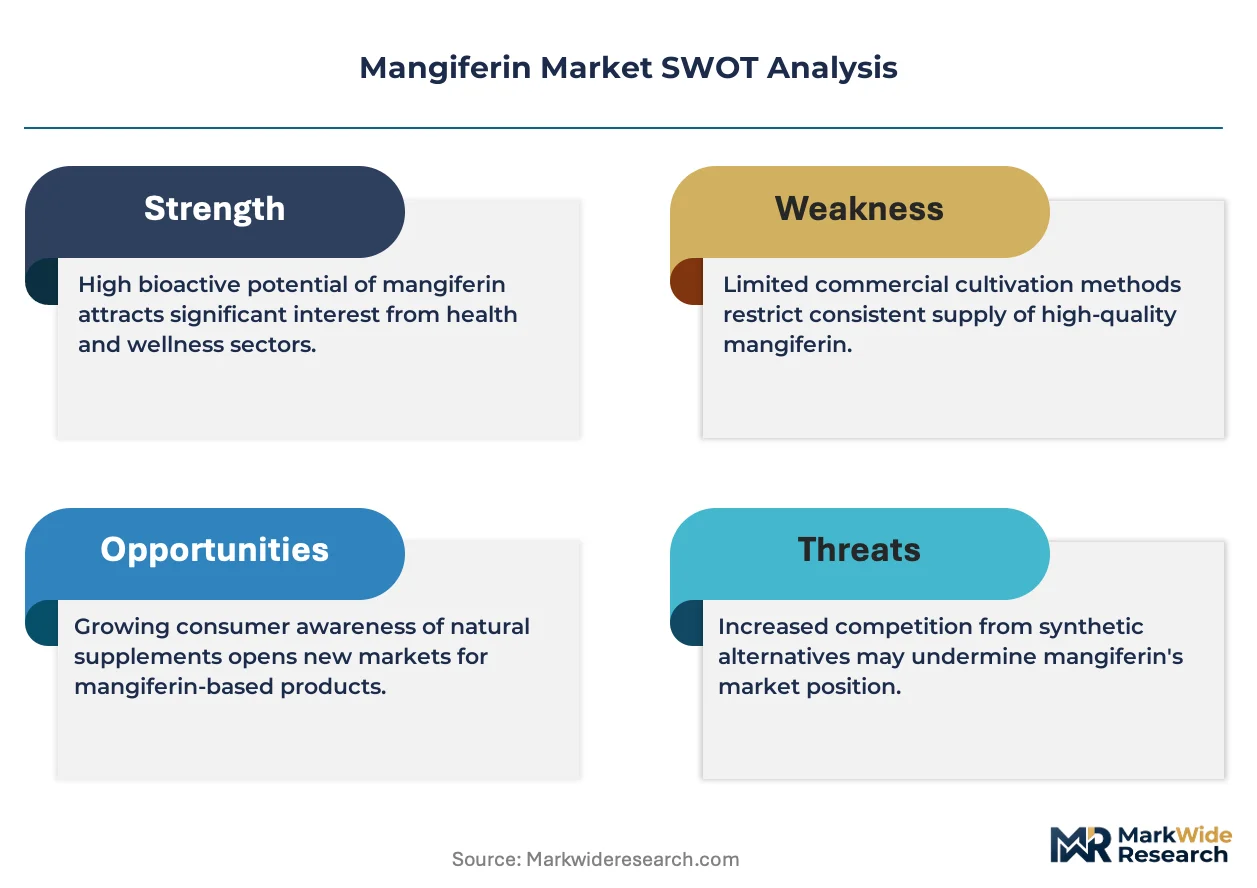
The Mangiferin Market is being fundamentally restructured by regulatory fragmentation across nutraceutical and pharmaceutical approval pathways, forcing suppliers to maintain parallel compliance systems for dietary supplement and drug-grade extract streams.
Growth Catalysts
- Metabolic health positioning:Preclinical validation of antidiabetic and anti-inflammatory mechanisms drives formulator interest in evidence-backed botanical ingredients for functional food and supplement matrices.
- India's PLI scheme:Production-linked incentives for active pharmaceutical ingredient manufacturing attract investment in botanical extraction infrastructure, lowering unit costs for standardized xanthonoid isolates.
- Modular dosing formats:Single-serve sachets and unit-dose capsules expand addressable channels through direct-to-consumer platforms, unbundling bulk extract volumes into higher-margin finished goods.
Market Restraints
- Raw material concentration:Mangifera indica leaf supply chains cluster in India and Southeast Asia, exposing processors to monsoon-driven crop volatility and regional logistics disruptions.
- FDA NDI notification costs:New Dietary Ingredient pre-market submissions impose six-figure compliance burdens that disproportionately constrain smaller extract suppliers seeking US market entry.
- Synthetic antioxidant substitution:Butylated hydroxytoluene and tert-butylhydroquinone maintain cost advantages in mass-market food preservation, limiting mangiferin penetration in price-sensitive applications.
Strategic Opportunities
- Pharmaceutical compounding channels:Standardized isolates meeting USP heavy-metal and residual solvent specifications command premium positioning in integrative medicine and personalized pharmacy formulations.
- EFSA Novel Food authorization:Successful regulatory navigation opens fortified food and beverage applications across European Union member states, expanding beyond supplement capsules into mainstream consumption occasions.
- Sustainability certification integration:Wild-harvested versus cultivated sourcing distinctions create tiered product positioning aligned with regenerative agriculture and carbon accounting mandates in corporate procurement policies.
Industry Challenges
- Analytical method standardization:Absence of harmonized pharmacopeial monographs for mangiferin content assay creates inter-laboratory variance, complicating quality agreements between extractors and finished goods manufacturers.
- Multi-jurisdictional compliance staffing:Simultaneous navigation of FDA, EFSA, FSSAI, and CDSCO requirements demands specialized regulatory affairs capabilities scarce in mid-scale botanical processing operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mangiferin Market |
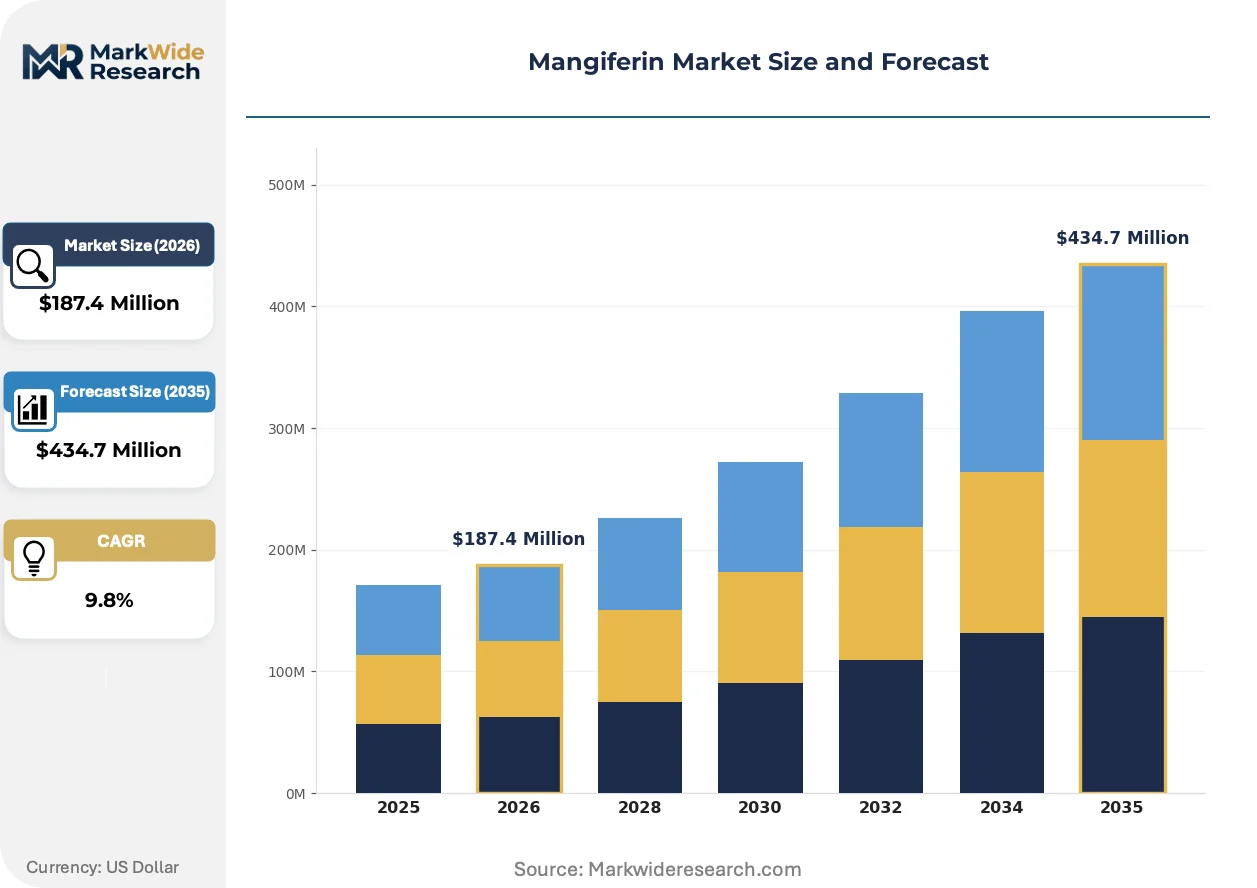
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Liquid, Extract, Capsule Source Type: Mangifera indica, Mangifera zeylanica, Mangifera caesia, Others Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Health Food Stores |
| Companies Covered | Chemcopia Ingredients Pvt Ltd, Biosynth, Merck KGaA, Cayman Chemical, Enzo Life Sciences, Inc., ChromaDex Inc., Carbosynth Limited, Thermo Fisher Scientific Inc., Selleck Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mangiferin Market Evolving Landscape
Green extraction technologies and analytical-grade reference standardization are compressing quality verification timelines while enabling new application categories. Formulation science advances unlock bioavailability improvements that expand effective dose ranges.
Supercritical carbon dioxide extraction is converging with microwave-assisted processing to reduce solvent residues and thermal degradation in xanthonoid recovery. European nutraceutical manufacturers are adopting these hybrid systems to meet EFSA purity specifications. The technology convergence is enabling pharmaceutical-grade certification for extracts previously limited to supplement applications.
REACH registration requirements for novel botanical substances are tightening substance characterization obligations for EU market entrants. Industrial consequence includes mandatory toxicological dossier preparation that extends lead times by 18-24 months. Pharmaceutical-grade extract suppliers are responding by pre-registering master files with EMA to streamline downstream customer compliance.
Direct sourcing contracts between finished goods brands and Indian cultivation cooperatives are displacing spot-market leaf purchasing. This procurement evolution concentrates volume commitments with traceable farmgate origins, bypassing traditional auction-based raw material markets. The shift is most visible among US dietary supplement brands marketing regenerative agriculture claims to metabolically health-conscious consumer segments.
Mangiferin Market Segmentation
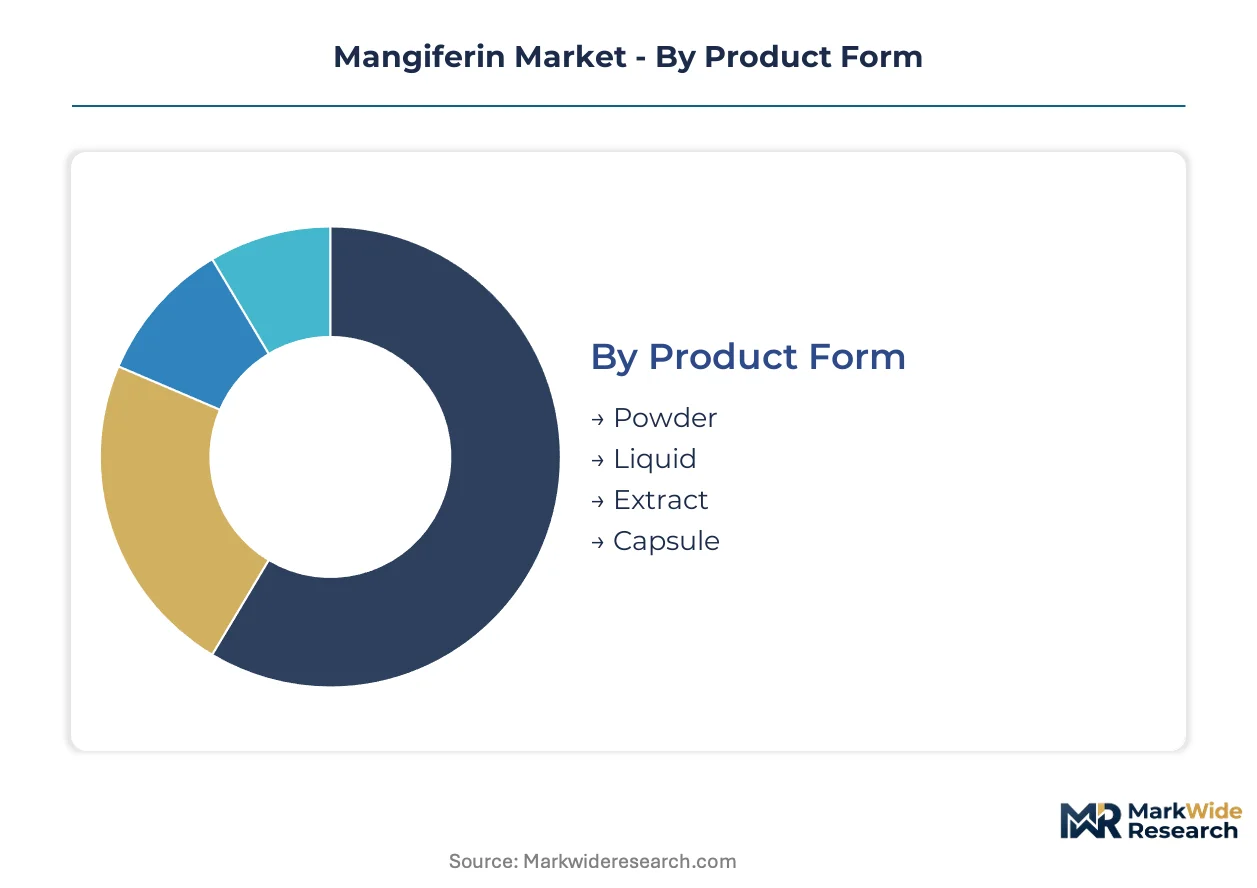
Segmentation in the mangiferin market reveals how extraction technology, regulatory pathways, and end-use specifications create distinct commercial tiers. Product form and source type decisions cascade through compliance costs, bioavailability engineering, and channel access strategies.
Product Form:
Customization versus standardization tensions peak in this category, with bulk powder formats serving commodity buyers while encapsulated and liquid delivery systems command formulation premiums through dosing precision.
- Powder:Free-flowing crystalline or spray-dried preparations dominate industrial procurement due to stability in ambient storage and compatibility with tablet compression, capsule filling, and functional food integration. Demand concentrates among US dietary supplement contract manufacturers seeking antioxidant active ingredients for metabolic health positioning, though hygroscopicity challenges necessitate nitrogen-flushed packaging for ocean freight.
- Liquid:Aqueous or hydro-alcoholic solutions enable rapid absorption formulations and beverage fortification applications where solid-state dissolution kinetics prove limiting. Expansion concentrates in European functional drink development pipelines navigating EFSA Novel Food authorization timelines, with sublingual delivery formats gaining traction in integrative medicine channels.
- Extract:Semi-standardized preparations with defined xanthonoid concentration ranges serve intermediate processors lacking in-house extraction infrastructure.
- Capsule:Pre-formulated unit-dose products bypass downstream manufacturing complexity for direct-to-consumer brands prioritizing speed-to-market over margin capture.
Most installed capacity flows through Powder. Expansion is steepest in Liquid.
Source Type:
Cost tier stratification separates established agricultural supply chains from emerging cultivar development programs, with wild-harvested alternatives commanding sustainability premiums in corporate procurement policies.
- Mangifera indica:The dominant commercial source leverages century-old orchard networks across India, Southeast Asia, and Brazil for consistent leaf and bark raw material flows. Demand concentrates among pharmaceutical-grade extractors requiring documented cultivation provenance for USP monograph compliance, with Indian PLI scheme beneficiaries investing in solvent recovery infrastructure to meet residual specification tightening.
- Mangifera zeylanica:Sri Lankan endemic varieties yield distinct xanthonoid profiles with differential bioactivity signatures in preclinical inflammation models. Niche positioning targets European botanical supplement brands marketing biodiversity narratives, though limited domestic extraction capacity constrains volume scaling.
- Mangifera caesia:Borneo-origin genetic resources remain pre-commercial due to restricted wild harvest quotas and absence of cultivation protocols.
- Others:Experimental cultivars and tissue culture propagation alternatives occupy R&D-stage supply relationships with university-affiliated compound libraries.
Raw material procurement concentrates through Mangifera indica. Mangifera zeylanica is gaining share fastest among sustainability-certified product lines.
Application:
Application segmentation tracks divergent regulatory density, with pharmaceutical pathways imposing multi-year toxicological dossier requirements while dietary supplement channels operate under substantially abbreviated notification frameworks.
- Dietary Supplements:Capsule, tablet, and powder delivery formats targeting antioxidant and metabolic health positioning constitute the primary revenue contribution, driven by US consumer demand for evidence-backed botanical actives. FDA NDI notification costs disproportionately constrain novel formulation entrants, favoring incumbent suppliers with grandfathered ingredient status or GRAS self-affirmation capabilities.
- Functional Foods:Beverage fortification and baked good integration require heat-stable extract forms and masking technologies for bitter xanthonoid taste profiles. European development pipelines dominate this segment pending EFSA Novel Food authorization clarity, with encapsulation advances enabling expanded effective dose ranges in mainstream consumption occasions.
- Pharmaceuticals:USP-grade isolates meeting heavy-metal and residual solvent specifications serve compounding pharmacies and integrative medicine formulations.
- Cosmetics:Topical antioxidant claims in dermocosmetic applications leverage mangiferin's polyphenolic stability for UV-protection positioning.
Formulation volumes concentrate in Dietary Supplements. Steepest expansion trajectory belongs to Functional Foods.
Distribution Channel:
Channel segmentation reflects the unbundling of bulk extract volumes into higher-margin finished goods, with direct-to-consumer platforms displacing traditional wholesale relationships for brand-building entrants.
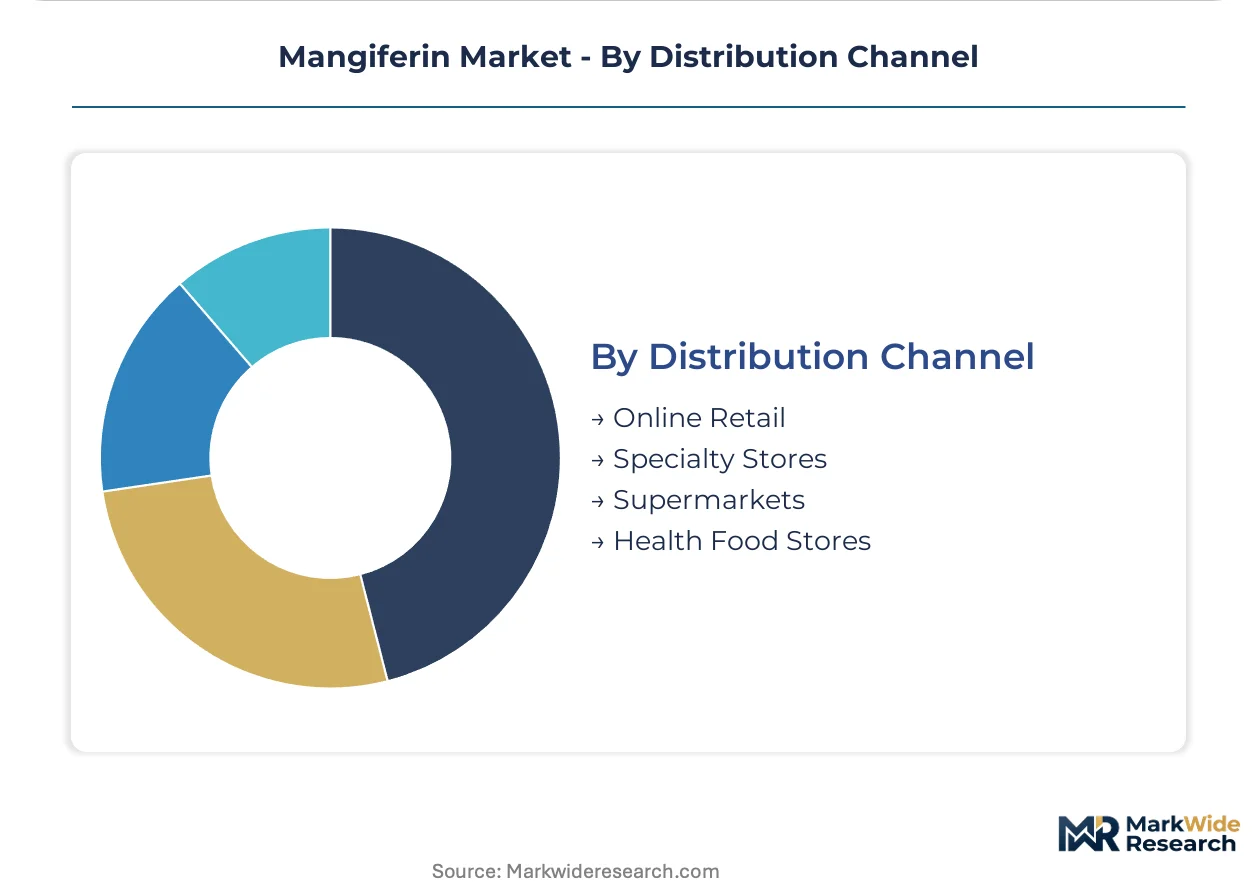
- Online Retail:Amazon, direct-to-consumer storefronts, and subscription platforms enable bypass of retail margin stacking for emerging brands with clinical narrative differentiation. Demand concentrates among metabolically health-conscious consumer segments in the United States and Western Europe, where third-party certification logos substitute for pharmacist consultation in purchase decisions.
- Specialty Stores:Independent health food retailers and practitioner-exclusive channels maintain higher service intensity for complex dosing regimens and poly-botanical stacking protocols.
- Supermarkets:Mass-market grocery placement remains limited to fortified functional beverages with established consumer recognition.
- Health Food Stores:Regional chains and cooperatives prioritize regenerative agriculture sourcing claims and transparent supply chain documentation.
Transaction volumes concentrate through Online Retail. Health Food Stores are expanding most quickly among sustainability-positioned product lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mangiferin extraction first achieved industrial scale in India during the 1990s, leveraging established mango orchard networks in Maharashtra and Gujarat for consistent leaf raw material supply. The industry has since dispersed across pharmaceutical-grade extraction hubs in Germany, dietary supplement formulation centers in the United States, and expanding botanical processing infrastructure in China.
India
Domestic extractors supply both pharmaceutical and nutraceutical buyers with standardized xanthonoid preparations. The PLI scheme for active pharmaceutical ingredient manufacturing attracts investment in solvent recovery infrastructure. Maharashtra's Nashik-Solapur corridor hosts concentrated extraction capacity serving export markets.
United States
Dietary supplement formulators expand procurement of mangiferin powders for antioxidant formulations targeting metabolic health positioning. FDA's New Dietary Ingredient notification requirements shape compliance pathways for novel botanical extracts. California's Los Angeles-Orange County cluster houses contract manufacturers integrating mango-derived actives into finished capsule products.
Germany
Pharmaceutical-grade reference material suppliers anchor quality verification standards across European value chains. EFSA Novel Food regulation creates 18-24 month authorization timelines for fortified food applications. Bavaria's Munich-Stuttgart axis concentrates analytical-grade production serving compounding pharmacy channels.
China
Domestic extractors scale supercritical carbon dioxide capacity to meet residual solvent specifications for export markets. NMPA pharmaceutical registration requirements parallel FDA pathways for drug-grade botanical submissions. Shandong Province's Qingdao-Yantai corridor emerges as a green extraction technology hub.
Switzerland
Specialized botanical traders bridge Indian raw material flows with European pharmaceutical certification requirements. Swissmedic's monograph development influences pharmacopeial standards for xanthonoid content assay. Basel-Zurich corridor firms pre-register master files with EMA to streamline customer compliance.
Mangiferin Market Competitive Landscape
The competitive structure tilts toward analytical-grade reference material specialists commanding quality verification premiums across fragmented botanical extraction tiers. Mid-scale Indian processors compete on standardized isolate volumes for pharmaceutical compounding, while European traders arbitrage regulatory compliance complexity. Three archetypes dominate: reference standard suppliers, integrated extractors with cultivation contracts, and formulation-focused distributors. Capacity expansion in green extraction technology and backward integration into farmgate sourcing represent the dominant competitive moves.
Among analytical-grade specialists, Merck KGaA exemplifies the reference material archetype through purity validation capabilities. Thermo Fisher Scientific Inc. occupies a position serving high-throughput screening applications for xanthonoid bioactivity research. Chemcopia Ingredients Pvt Ltd represents the integrated extractor model, leveraging botanical extraction infrastructure to supply standardized isolates.
| Leading Market Players |
|---|
| Chemcopia Ingredients Pvt Ltd |
| Biosynth |
| Merck KGaA |
| Cayman Chemical |
| Enzo Life Sciences, Inc. |
| ChromaDex Inc. |
| Carbosynth Limited |
| Thermo Fisher Scientific Inc. |
| Selleck Chemicals |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap extractors across Maharashtra and Gujarat anchor raw material procurement through multi-generational orchard relationships, translating cultivation proximity into pricing discipline that resists spot-market volatility. Their retained earnings finance solvent recovery infrastructure without external equity dilution, compressing unit economics for USP-grade isolates while maintaining premium positioning against trader-dependent competitors.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and commodity bulk levels segments buyer access by certification stringency. Price differentiation hinges on USP heavy-metal compliance and EFSA Novel Food authorization status, with pharmaceutical tiers commanding multiples over supplement-grade volumes. Cost compression in commodity powder segments is intensifying because Indian PLI scheme beneficiaries expand solvent recovery capacity. Contract manufacturers in the United States exhibit highest price sensitivity due to FDA NDI notification cost burdens, while European compounding pharmacies show lowest sensitivity given reimbursement pass-through structures.
Supply Chain Analysis
Direct sourcing contracts between finished goods brands and Indian cultivation cooperatives now displace traditional auction-based leaf markets. Raw material flows concentrate through India, with secondary extraction capacity scaling in China and Switzerland. Mangifera indica leaf supply draws from Maharashtra orchard networks, supercritical CO2 equipment imports from Germany, and analytical reference materials from Bavaria. Single-source vulnerability in monsoon-dependent Maharashtra leaf harvests threatens volume continuity. Distribution runs through Swiss trading houses for European pharmaceutical certification and direct US importer relationships for supplement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mangiferin Market compounds steadily as metabolic health positioning hardens into sustained consumer preference for evidence-backed botanical actives. Regulatory fragmentation creates durable competitive moats for compliance-capable incumbents.
For Market Incumbents: Deploy pharmacopeial monograph development as a lever to lock in quality verification premiums before harmonized standards emerge. Anchor capacity expansion in Nashik-Solapur corridor extraction clusters to capture PLI scheme benefits. Defensive consolidation should target Swiss trading houses with EMA master file pre-registration capabilities, neutralizing emerging entrants lacking multi-jurisdictional regulatory affairs staffing. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms targeting metabolically health-conscious segments in Western Europe, bypassing retail margin stacking that favors incumbents. White-space concentration exists in Mangifera zeylanica biodiversity narratives for sustainability-certified product lines, and in sublingual liquid formats pending EFSA Novel Food authorization clarity. Go-to-market angle should emphasize regenerative agriculture sourcing claims with blockchain-traceable farmgate documentation. For Investors and Strategic Acquirers: Pharmaceutical-grade botanical extractors with CDSCO and FDA dual compliance capabilities are the most active acquirer targets in this space. Long-term viability rests on backward integration into cultivation contracts rather than spot-market sourcing dependence. Acquisition target archetype: mid-scale Indian processors with installed supercritical CO2 capacity and unexploited USP certification potential. Signal to watch is EFSA Novel Food authorization timeline compression, which would unlock fortified food applications and re-rate functional food segment valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation Contracts | Direct farmgate sourcing bypasses auction volatility and secures traceability documentation for EFSA submissions. |
| Supercritical CO2 Capacity Expansion | Hybrid extraction systems enable pharmaceutical-grade certification previously limited to supplement applications. |
| Pharmacopeial Monograph Development | Pre-standardization positioning captures quality verification premiums across inter-laboratory variance disputes. |
| EFSA Novel Food Pre-Registration | Master file submission compresses customer compliance timelines by 18-24 months for EU market entry. |
| Direct-to-Consumer Channel Launch | Subscription platforms unbundle bulk extract volumes into higher-margin finished goods with clinical narrative differentiation. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with extraction plant managers, regulatory affairs leads at botanical suppliers, dietary supplement formulators, and Swiss trading house procurement officers with secondary validation. Secondary sources included FDA NDI notification databases, EFSA Novel Food submission registers, CDSCO manufacturing license records, Indian customs export data, and USP monograph development proceedings. Bottom-up volume modeling from installed extraction capacity triangulated against top-down demand estimates from end-use segment consumption patterns.
Historical reference periods anchored the projection horizon through verified extraction capacity utilization rates and documented regulatory authorization timelines across the analysis window. Segmentation dimensions modeled included product form tier, source type cultivar, application regulatory pathway, and distribution channel structure. CAGRs derived from slope-consistency checks against comparable botanical extract markets and verified capacity expansion announcements. Industry-specific forecast inputs incorporated PLI scheme beneficiary identification and supercritical CO2 equipment installation tracking.
Forecast precision tightens around the base case; tail outcomes carry wider variance under monsoon-driven crop failures or accelerated EFSA Novel Food authorization timelines. Outputs reflect documented assumptions regarding regulatory pathway durations and cultivation yield stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sulfur Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Global Naphthenic Base Oil Market
Bulk Chemicals
North America Hydrochloric Acid Market
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Copper (II) Carbonate Basic Market
Bulk Chemicals
Ethylene Glycol Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Bromine Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Foundry Coke Market
Bulk Chemicals
Bulk Molding Compounds Market