
 Sodium Gluconate Market | 2026-2036
Sodium Gluconate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Gluconate Market Analytics
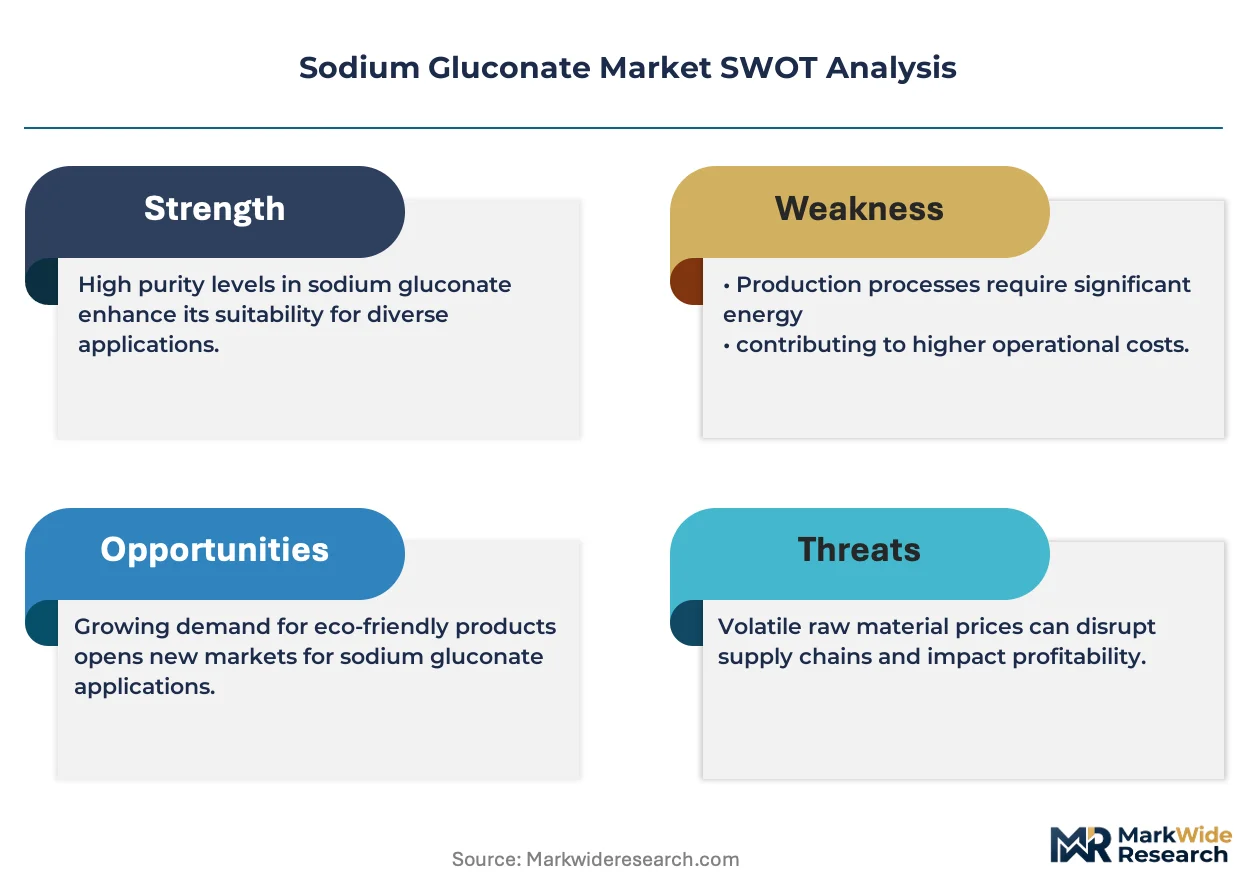
Biotechnological fermentation optimization is rewriting sodium gluconate production economics, enabling higher yields from glucose feedstocks at lower energy intensity. BASF SE leverages its integrated biotechnology platform to sustain cost leadership across European supply chains. Jungbunzlauer Suisse AG anchors premium-grade output through Swiss manufacturing protocols. Shandong Fuyang Bio-Tech CO.LTD dominates volume production by controlling corn-derived glucose sourcing in China's northern plains.
Sodium gluconate is the sodium salt of gluconic acid, produced industrially through aerobic fermentation of glucose with Aspergillus niger or Gluconobacter species, typically yielding white crystalline powder with 99% minimum purity. It functions primarily as a chelating agent, concrete retarder, and cleaning formulation additive across industrial and consumer applications. Industrial-grade sodium gluconate leads volume demand through its entrenched role in construction chemicals, while pharmaceutical-grade variants command superior margins due to stringent CDSCO and FDA purity requirements. The food and beverage segment competes for fermentation-derived supply as clean-label sequestrant demand intensifies in processed food formulations.
REACH registration requirements in Europe, FDA food additive regulations under 21 CFR, and China's GB 7654-1987 food-grade standards collectively shape product specifications and market access pathways for sodium gluconate manufacturers. The EPA's industrial chemical reporting framework in the United States further conditions import volumes and domestic production thresholds. Stakeholders must monitor regulatory convergence between EU Green Deal chemical sustainability criteria and China's dual carbon goals, as these frameworks will increasingly determine which production assets qualify for preferential supply contracts.
Market Dynamics
Fermentation yield optimization and China's tightening GB purity standards are restructuring sodium gluconate supply economics, compressing margins for non-integrated producers while rewarding biotechnology platforms with captive glucose sourcing.
Growth Catalysts
- Construction Chemicals Procurement:Infrastructure buildouts in Indonesia, Vietnam, and India are accelerating industrial-grade sodium gluconate offtake for concrete retarder applications.
- REACH Registration Compliance:ECHA's updated chemical safety dossier requirements are filtering out non-compliant suppliers, consolidating volume with registered European producers.
- Fermentation Process Intensification:Continuous aerobic bioreactor designs are lifting Aspergillus niger productivity metrics and reducing batch cycle times.
Market Restraints
- Corn-Derived Glucose Volatility:Feedstock price swings in North American grain markets transmit directly to fermentation cost structures.
- Shandong Supply Concentration:Over 60% of global fermentation capacity clusters in China's northern plains, creating single-geography disruption exposure.
- Phosphonate Substitution:Organophosphonate chelating agents compete in industrial cleaning formulations with comparable sequestration performance.
Strategic Opportunities
- Indian Pharmaceutical-Grade Gap:CDSCO-registered domestic production remains underdeveloped, creating import substitution potential for GMP-certified fermentation assets.
- EU Green Deal Chemical Criteria:Renewable carbon certification for bio-based sodium gluconate unlocks preferential procurement terms under EU public tender rules.
- Digital Twin Fermentation:AI-driven process control hybridizing with traditional metabolic engineering compresses scale-up timelines for new production lines.
Industry Challenges
- Metabolic Engineering Talent Scarcity:Strain optimization expertise sits concentrated with legacy biotechnology institutes in Basel and Shanghai.
- Multi-Jurisdiction Certification Overlap:Simultaneous FDA food additive, REACH full registration, and NMPA pharmaceutical-grade approvals demand redundant toxicology dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Gluconate Market |
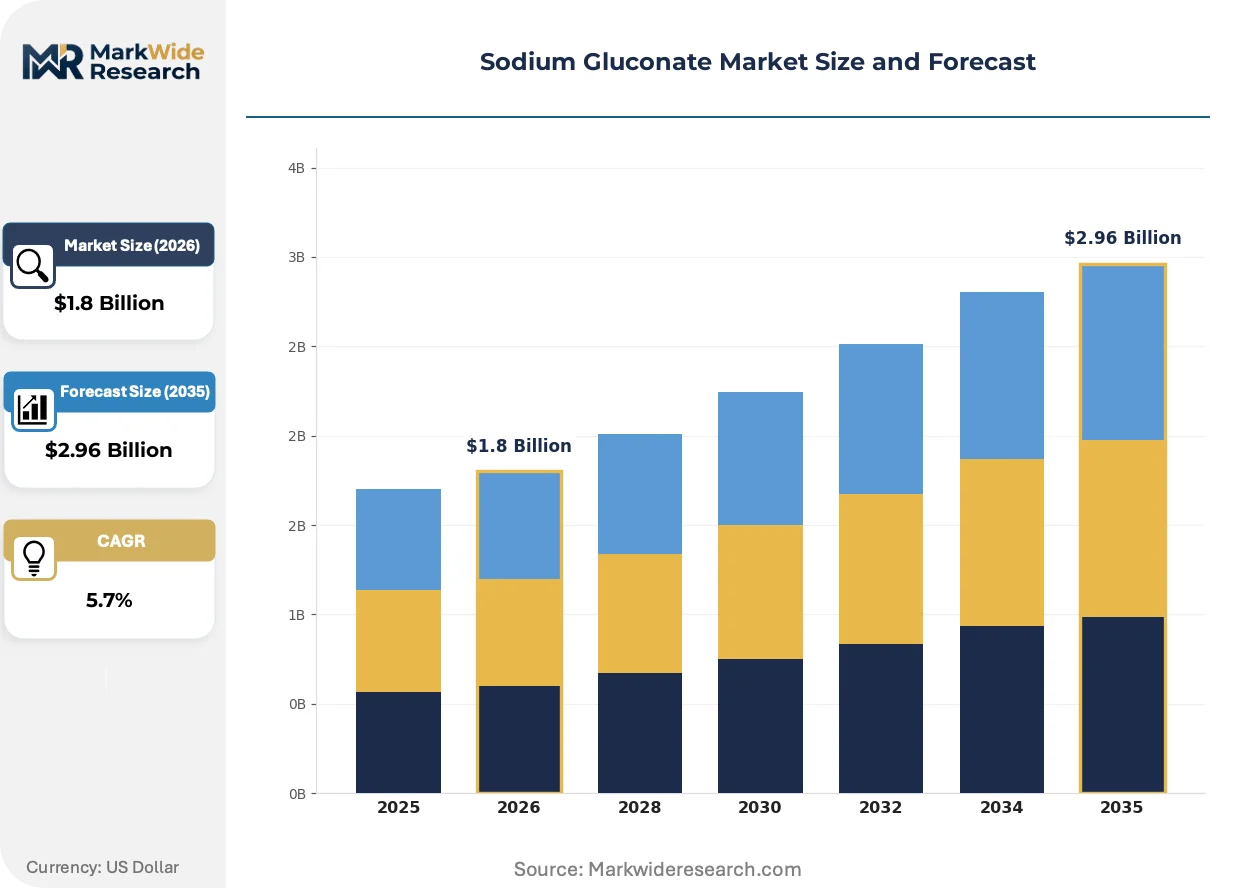
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Pharmaceutical Grade, Industrial Grade, Feed Grade End Use Industry: Construction, Food and Beverage, Pharmaceuticals, Agriculture Form: Powder, Granules, Liquid, Crystals Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | BASF SE, Jungbunzlauer Suisse AG, Fermentation Products, Inc., Shandong Fuyang Bio-Tech CO.LTD, Roquette Frères, Bailin Group Co.,Ltd, Shandong Xiwang Sugar Industry Co., Ltd., Hefei TNJ Chemical Industry Co., Ltd., Henan Kingsun Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Gluconate Market Evolving Landscape
Biotechnology convergence with digital manufacturing tools is compressing the traditional fermentation scale-up timeline, while regulatory fragmentation across major economies forces producers into parallel compliance investments.
Continuous fermentation technology is hybridizing with cell retention systems to eliminate downtime between batches. Construction chemical formulators in Germany and Japan are piloting these systems for just-in-time sodium gluconate delivery. The technology is hybridizing capital requirements, favoring integrated producers with existing biotechnology infrastructure over merchant chemical players.
China's evolving GB standards on food-grade chemical purity are tightening heavy metal and microbial specification thresholds. Domestic producers in Shandong Province are retrofitting downstream purification trains to meet anticipated 2026 revisions. Pharmaceutical-grade sodium gluconate destined for NMPA-registered applications faces the most stringent compliance burden, with some exporters pivoting toward industrial-grade markets.
Direct procurement contracts between fermentation producers and ready-mix concrete multinationals are displacing traditional distributor channels. Cemex and Holcim subsidiaries in Southeast Asia are negotiating volume commitments with Shandong-based suppliers, bypassing regional chemical traders. This pattern concentrates most visibly in Indonesia's infrastructure corridor, where project-scale demand justifies dedicated supply agreements.
Sodium Gluconate Market Segmentation
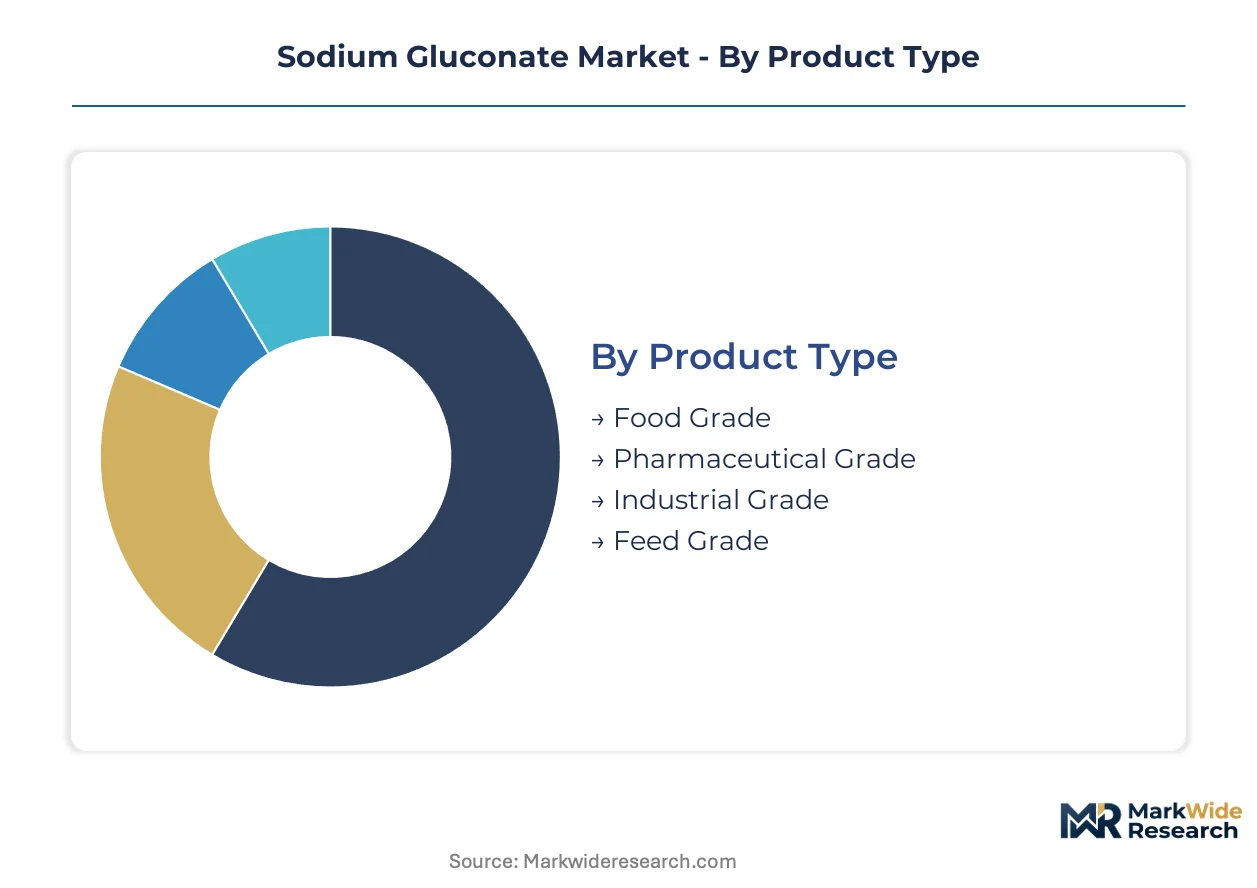
Sodium gluconate's functional versatility across chelation, retardation, and sequestration creates distinct specification tiers that command radically different pricing and compliance burdens. Each grade demands dedicated fermentation trains and purification protocols, fragmenting manufacturing economics across customer requirements.
Product Type:
Use-case spectrum spans concrete admixture chemistry to parenteral drug formulations, with purity thresholds separating commodity fermentation output from premium-margin specialties.
- Industrial Grade:Minimum 98% purity white crystalline powder serves concrete retarder applications and industrial cleaning formulations. Demand concentrates in Indonesia's infrastructure corridor and Vietnam's ready-mix concrete sector, driven by megaproject-scale procurement from Cemex and Holcim subsidiaries seeking dedicated supply agreements.
- Pharmaceutical Grade:Ultra-purified to meet NMPA, FDA, and CDSCO injectable standards with endotoxin and heavy metal specifications below 10 ppm. Compounding pharmacies and parenteral drug manufacturers in India and China absorb output, constrained by redundant toxicology dossier requirements across jurisdictions.
- Food Grade:Fermentation-derived sequestrant complying with GB 7654-1987 and 21 CFR food additive regulations for processed cheese, beverages, and canned goods. Clean-label demand from European and North American food manufacturers competes for supply with industrial applications.
- Feed Grade:Lower-purity additive for animal nutrition formulations, primarily mineral chelation in poultry and swine feed. Chinese and Brazilian feed compounders drive procurement, with specifications falling between food and industrial tiers.
Established volume favors Industrial Grade; emerging adoption favors Pharmaceutical Grade.
End Use Industry:
Cost tier stratification places construction chemicals at volume base and pharmaceutical applications at margin apex.
- Construction:Concrete retarder formulations consume fermentation output through direct procurement contracts with ready-mix multinationals. Shandong-based suppliers bypass regional distributors to serve Southeast Asian infrastructure buildouts.
- Pharmaceuticals:Parenteral drug buffering and mineral supplementation demand CDSCO-registered, GMP-certified supply chains that remain underdeveloped domestically in India.
- Food and Beverage:Clean-label sequestrant applications in processed formulations compete for fermentation capacity against industrial buyers, with EU Green Deal renewable carbon certification unlocking preferential procurement terms.
- Agriculture:Chelated micronutrient fertilizers and foliar sprays utilize technical-grade material, with Brazilian and Chinese agrochemical formulators representing concentrated demand pockets.
Margin concentration sits with Pharmaceuticals; volume expansion concentrates in Construction.
Form:
Customer type preferences for handling efficiency and dissolution kinetics determine physical specification requirements.
- Powder:Free-flowing crystalline powder dominates bulk industrial procurement for concrete admixture blending and dry cleaning compound formulation.
- Liquid:Aqueous solutions suit just-in-time delivery systems and automated dosing in continuous fermentation facilities serving German and Japanese construction chemical formulators.
- Granules:Agglomerated particles reduce dust exposure in feed milling operations and agricultural blending equipment.
- Crystals:High-purity crystalline solid meets pharmaceutical visual inspection standards and extended shelf-life requirements for parenteral applications.
Operational convenience favors Powder; precision dosing favors Liquid.
Distribution Channel:
Supply concentration in Shandong Province is restructuring traditional channel economics toward direct engagement.
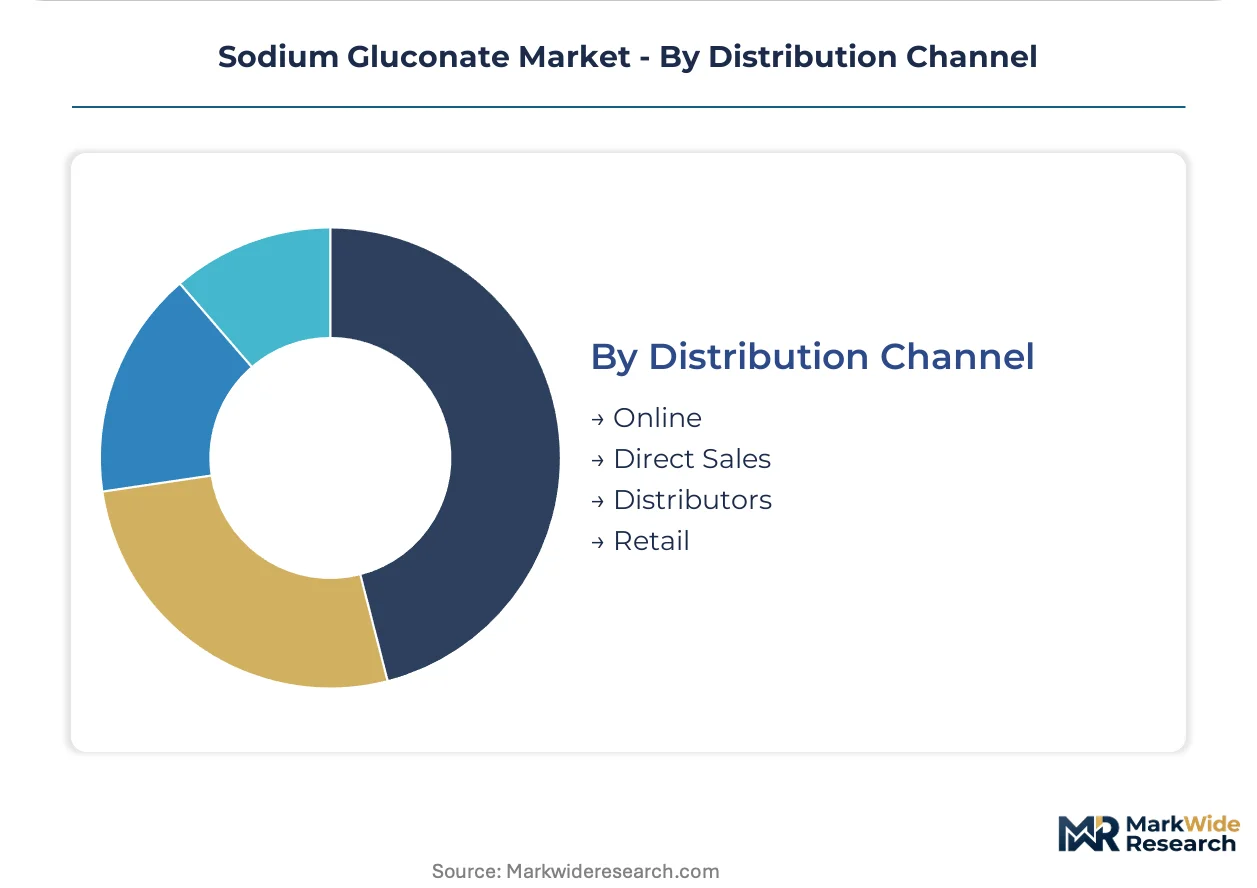
- Direct Sales:Volume commitments between Shandong fermentation assets and Southeast Asian concrete multinationals displace regional chemical traders, concentrating in Indonesia's project-scale demand environment.
- Distributors:Remain relevant for fragmented food and beverage and agricultural customers requiring technical support and smaller lot sizes.
- Online:E-procurement platforms serve research institutions, small compounders, and specialty chemical buyers seeking rapid specification comparison.
- Retail:Limited to consumer-facing cleaning formulations and niche nutritional supplements through pharmacy and specialty store channels.
Scale efficiency favors Direct Sales; service intensity favors Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong Province exports fermentation-derived sodium gluconate to Indonesia, Vietnam, and India through direct procurement contracts with ready-mix concrete multinationals. This trade corridor concentrates supply-side leverage in China's northern plains while Southeast Asian infrastructure buildouts absorb industrial-grade volumes.
China
Shandong Province's fermentation corridor houses over sixty percent of global capacity, with corn-derived glucose feedstock secured from northern plains agricultural networks. NMPA pharmaceutical-grade standards and evolving GB food purity regulations are tightening heavy metal and microbial thresholds for 2026 implementation. Qingdao and Jinan-based producers retrofit purification trains to meet anticipated compliance revisions.
Indonesia
Megaproject-scale concrete demand from Cemex and Holcim subsidiaries drives industrial-grade procurement through dedicated supply agreements bypassing regional distributors. The country's national food and drug regulator enforces import specifications for pharmaceutical-grade material that remain less stringent than NMPA requirements. Jakarta-Bandung infrastructure corridor concentrates ready-mix offtake.
Germany
Construction chemical formulators pilot continuous fermentation delivery systems for just-in-time sodium gluconate dosing in concrete admixture applications. REACH registration requirements filter non-compliant suppliers toward ECHA-registered European producers. BASF SE leverages Ludwigshafen biotechnology infrastructure to sustain cost leadership across EU supply chains.
India
CDSCO-registered domestic pharmaceutical-grade production remains underdeveloped, creating import dependency for parenteral drug buffering applications. The country's national pharmaceutical regulator maintains redundant toxicology dossier requirements that parallel FDA and NMPA frameworks. Maharashtra and Gujarat pharmaceutical clusters absorb premium-grade imports for compounding pharmacies.
United States
EPA industrial chemical reporting frameworks condition import volumes and domestic production thresholds for fermentation-derived material. FDA food additive regulations under 21 CFR govern clean-label sequestrant applications in processed cheese and beverage formulations. Corn-belt glucose price volatility transmits directly to fermentation cost structures.
Sodium Gluconate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered certification grades. The vendor base clusters around biotechnology platforms with captive glucose sourcing, integrated European chemical conglomerates, and Shandong-based volume producers. Three archetypes dominate: fermentation-integrated biotech specialists, diversified chemical multinationals with biotechnology divisions, and regionally concentrated volume exporters. Capacity expansion and backward integration into corn-derived glucose supply represent the dominant competitive moves.
Among European biotechnology-anchored conglomerates, BASF SE and Jungbunzlauer Suisse AG exemplify divergent strategic positioning. BASF SE occupies the integrated multinational archetype with Ludwigshafen-based fermentation infrastructure. Jungbunzlauer Suisse AG represents the Swiss premium-grade specialist tier. Shandong Fuyang Bio-Tech CO.LTD anchors the volume-export archetype from China's northern plains fermentation corridor.
| Leading Market Players |
|---|
| BASF SE |
| Jungbunzlauer Suisse AG |
| Fermentation Products, Inc. |
| Shandong Fuyang Bio-Tech CO.LTD |
| Roquette Frères |
| Bailin Group Co.,Ltd |
| Shandong Xiwang Sugar Industry Co., Ltd. |
| Hefei TNJ Chemical Industry Co., Ltd. |
| Henan Kingsun Chemical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Overcapacity signals in Shandong Province's fermentation corridor are compressing spot-market pricing for industrial-grade material while simultaneously elevating bargaining leverage for construction chemical multinationals procuring through direct contracts. This utilization imbalance feeds supplier migration toward pharmaceutical-grade tiers where NMPA and FDA certification requirements sustain margin buffers.
Pricing Analysis
Batch-process versus continuous fermentation technology is widening the pricing gap between legacy producers and digitally upgraded facilities. Three-tier pricing structure across pharmaceutical, food, and industrial grades anchors the market, with certification level and volume scale serving as primary differentiation drivers. Cost compression in industrial-grade tiers is intensifying because Shandong exporters compete for Southeast Asian megaproject offtake. Ready-mix concrete multinationals exhibit highest price sensitivity; parenteral drug manufacturers show lowest sensitivity due to GMP compliance requirements.
Supply Chain Analysis
Corn-derived glucose feedstock from China's northern plains, North American grain belts, and Brazilian agricultural networks anchors global fermentation economics. Production draws from Aspergillus niger strain banks, aerobic bioreactor equipment, and downstream crystallization trains. Single-geography concentration in Shandong Province creates disruption exposure from NMPA regulatory revisions or logistics interruptions. Distribution runs through direct procurement contracts with construction multinationals, displacing traditional chemical traders in Indonesia and Vietnam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct procurement consolidation among ready-mix concrete multinationals, fragmenting traditional distributor intermediaries and compressing margin capture for non-integrated fermentation assets.
For Market Incumbents: Insulate pharmaceutical-grade margin tiers by accelerating NMPA and CDSCO registration investments before 2026 GB standard revisions tighten compliance thresholds. Defend against phosphonate substitution in industrial cleaning by embedding sodium gluconate into formulated admixture bundles with technical service support. Prioritize backward integration into captive corn-derived glucose supply to neutralize North American feedstock volatility. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO-registered pharmaceutical-grade gap before domestic GMP-certified capacity matures. Target Maharashtra and Gujarat compounding pharmacy clusters with import substitution positioning. Leverage EU Green Deal renewable carbon certification as differentiation wedge for European public tender access. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous fermentation technology deployments, favoring scaled biotechnology platforms over merchant chemical entrants. Over a multi-year viability window, prioritize acquisition targets with integrated glucose sourcing and existing REACH registration dossiers. Monitor Shandong Province environmental enforcement intensity as inflection signal for supply relocation economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Supply | Corn-belt sourcing control neutralizes feedstock volatility for Shandong fermentation assets. |
| Continuous Fermentation Technology Deployment | AI-driven bioreactor designs compress batch cycle times for German construction chemical formulators. |
| Multi-Jurisdiction Certification Investment | Simultaneous NMPA, FDA, and CDSCO registrations unlock pharmaceutical-grade margin tiers. |
| Direct Procurement Contract Structuring | Volume commitments with Cemex and Holcim subsidiaries displace regional distributor channels in Indonesia. |
| Renewable Carbon Certification Program | EU Green Deal bio-based credentials secure preferential public tender terms for European supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across fermentation plant managers, construction chemical procurement leads at ready-mix multinationals, pharmaceutical compounding pharmacy directors, and food industry technical R&D heads. Secondary validation drew from NMPA registration filings, ECHA REACH dossiers, CDSCO import records, Shandong Province customs export data, and GB standards revision notices. Bottom-up capacity assessments and top-down demand modeling were triangulated to cross-validate volume estimates.
Calibration against historical price trajectories and capacity utilization signals informed the analytical framework across the analysis window. Segmentation dimensions modeled include grade tier, end-use industry, and regional production hub. CAGRs were derived from slope analysis of normalized growth curves. Forecast inputs incorporated Aspergillus niger productivity metrics and corn-derived glucose price elasticity coefficients.
Macroeconomic conditions sit as an overlay; deviation in infrastructure investment cycles, grain commodity indices, or regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding GB standard implementation timing and continuous fermentation adoption rates. Cross-checking against ECHA registration renewal patterns and CDSCO import volume trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
North America Carbon Black Market
Bulk Chemicals
Calcium Sulfite Market
Bulk Chemicals
Magnesium Acetate Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Ammonium Molybdate Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
Asia-Pacific Formaldehyde Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Calcium Carbonate Market