
 Triammonium Citrate Market | 2026-2036
Triammonium Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Triammonium Citrate Market Analytics
Buyer consolidation among pharmaceutical contract manufacturers is repositioning procurement leverage toward volume-committed suppliers. Anhui Jinao Chemical Co., Ltd. leverages integrated citric acid feedstock access to control input costs. Nanjing MSN Chemical Pvt., Ltd. sustains technical-grade specialization for industrial buffer applications. Shanghai Sychem Pharma Co., Ltd. anchors pharmaceutical-grade certification pipelines for injectable drug formulations.
Triammonium citrate is a tribasic ammonium salt of citric acid with the molecular formula (NH₄)₃C₆H₅O₇, typically manufactured through neutralization of citric acid with ammonia solution followed by crystallization or spray drying to achieve specified purity grades. The compound functions primarily as a buffering agent, emulsifier, and pH stabilizer across pharmaceutical, food, and agricultural formulations. Powder form dominates current volume due to handling efficiency in bulk pharmaceutical manufacturing, while pharmaceutical grade commands premium positioning driven by USP and EP monograph compliance requirements. Food grade applications in beverage acidification and dairy stabilization represent mature demand with steady replacement cycles.
Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade REACH registration requirements in Europe mandate full toxicological dossiers for citrate salt imports above one-tonne annual thresholds. China's SAMR enforces GB standards for food additive ammonium citrate specifications covering heavy metal limits and microbial contamination. India's FSSAI aligns food-grade citrate purity rules with Codex Alimentarius benchmarks for imported buffer salts. Stakeholders must monitor evolving pharmaceutical-grade monograph revisions and regional purity standard harmonization to secure formulation-ready supply positions.
Market Dynamics
Pharmaceutical buffer standardization is compressing supplier qualification timelines, forcing citrate salt manufacturers to pre-certify against evolving USP and EP monograph drafts before formal adoption.
Growth Catalysts
- Biologic drug pipeline expansion:mRNA and monoclonal antibody formulations require pH-stable buffer systems. Triammonium citrate's tribasic profile enables precise titration in cell culture media.
- REACH registration completion:Full toxicological dossier acceptance for citrate salt imports above one-tonne thresholds has unlocked formulation-grade supply continuity for European pharmaceutical contract manufacturers.
- Jiangsu-Shandong manufacturing clusters:Concentrated specialty chemical infrastructure in these Chinese provinces yields feedstock proximity advantages that lower crystallization-stage production costs.
Market Restraints
- Citric acid feedstock volatility:Molasses and corn-derived glucose prices fluctuate with agricultural commodity cycles, compressing margin predictability for neutralization-process manufacturers.
- Single-source ammonia supply risk:Regional ammonia plant outages in key producing belts disrupt neutralization throughput, forcing crystallization batch delays.
- Acetate and phosphate buffer substitution:Sodium acetate and dibasic sodium phosphate compete in pH 4.5-6.5 stabilization applications with lower raw material cost structures.
Strategic Opportunities
- Vietnam pharmaceutical manufacturing buildout:Greenfield injectable drug facilities in Ho Chi Minh City industrial zones lack qualified local buffer salt suppliers, creating first-mover certification advantages.
- SAMR food additive purity alignment:China's GB standard revisions for heavy metal limits and microbial contamination create compliance-service revenue streams for pre-certified exporters.
- Spray-dried granule format development:Instant-dissolve agglomerated citrate salts address powder caking in high-humidity climates, opening tropical-market pharmaceutical distribution channels.
Industry Challenges
- Analytical method validation backlog:USP monograph revision cycles outpace in-house HPLC and titration protocol updates, delaying batch release for pharmaceutical-grade shipments.
- Cross-contamination prevention capex:Dedicated crystallization lines for technical versus pharmaceutical grades require stainless steel reactor duplication, straining mid-cap manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Triammonium Citrate Market |
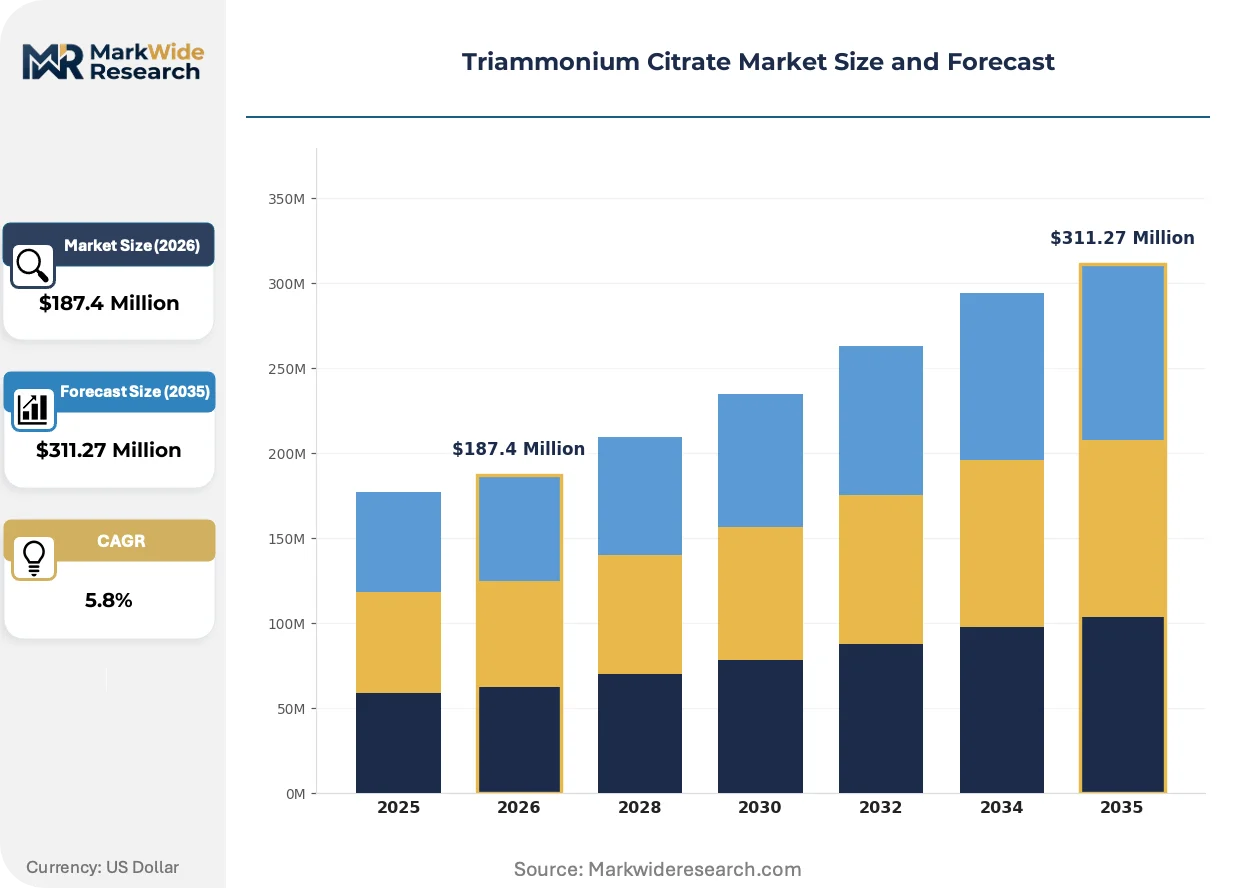
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Solution, Tablets End Use Industry: Pharmaceuticals, Food & Beverage, Agriculture, Nutraceuticals Packaging Type: Bags, Bottles, Drums, Sachets Purity Grade: Food Grade, Industrial Grade, Pharmaceutical Grade, Technical Grade |
| Companies Covered | Eagle Chemical Works, Anhui Jinao Chemical Co., Ltd., Nanjing MSN Chemical Pvt., Ltd., Xiamen Vast Land Chemical Co., Ltd., A & Z Food Additives Co., Ltd., Shanghai Sychem Pharma Co., Ltd., Triveni Interchem Pvt. Ltd., Ningxiang Xinyang Chemical Co., Ltd., Jinan Boss Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Triammonium Citrate Market Evolving Landscape
Continuous crystallization technology and real-time process analytical technology are displacing batch-wise manufacturing, while regulatory pre-certification protocols compress supplier onboarding timelines for pharmaceutical formulators.
Continuous flow crystallization systems with inline PAT probes are converging with quality-by-design frameworks in pharmaceutical-grade citrate salt production. European CMOs now specify real-time particle size distribution monitoring as a contractual requirement. This convergence is compressing batch-to-batch variability acceptance thresholds from historical ±5% to ±2% coefficient of variation ranges.
REACH Annex XV dossier updates for citrate salt hazard classification are tightening toxicological data requirements for imports above ten-tonne annual thresholds. ECHA's 2024 guidance on respiratory sensitization endpoints now demands additional in vitro testing. Pharmaceutical-grade importers are responding by pre-submitting extended safety data sets before formal regulatory deadlines.
Long-term offtake agreements with volume-commitment clauses are displacing spot-market buffer salt procurement among top-twenty pharmaceutical contract manufacturers. Tier-one CMOs now insist on eighteen-month minimum supply guarantees with price-lock provisions. This pattern is most visible in Germany's Rhineland pharmaceutical corridor, where Bayer and Boehringer Ingelheim affiliate facilities have consolidated supplier panels to three qualified citrate salt sources.
Triammonium Citrate Market Segmentation
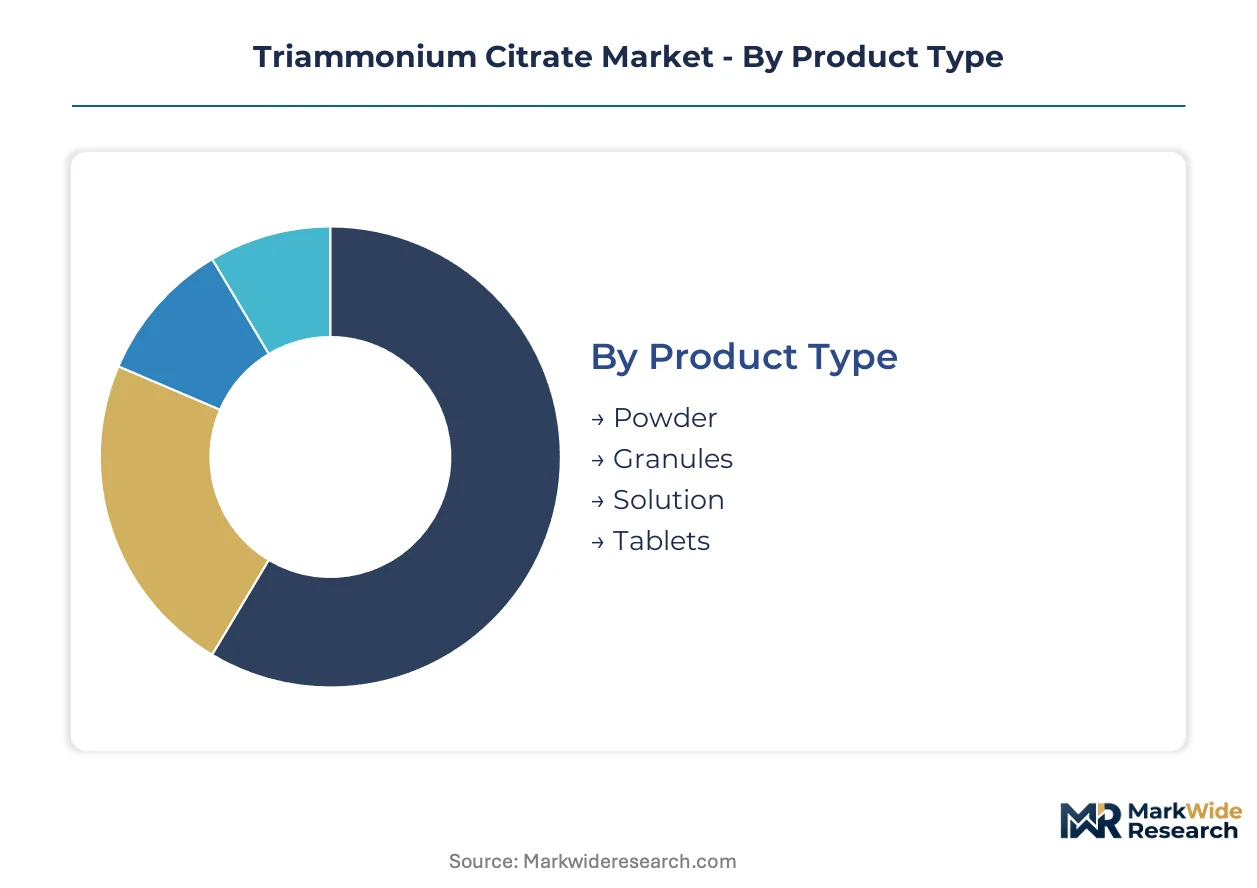
Triammonium citrate demand fragments across formulation requirements, handling constraints, and regulatory thresholds. Procurement teams select formats and grades based on dissolution kinetics, contamination risk, and downstream certification burdens.
Product Type:
Replacement cycles favor formats that reduce caking liability and accelerate dissolution in high-throughput manufacturing.
- Powder:Fine crystalline particles with high surface area enable rapid pH equilibration in bioreactor buffer preparation. Pharmaceutical contract manufacturers in Germany's Rhineland corridor specify powder for monoclonal antibody cell culture media, though humidity exposure during monsoon distribution to India triggers caking claims.
- Granules:Agglomerated particles with controlled porosity resist moisture uptake in tropical climates. Spray-dried granule adoption is climbing fastest among Southeast Asian pharmaceutical greenfield facilities lacking climate-controlled warehousing.
- Solution:Ready-to-use aqueous concentration eliminates weighing variability in GMP environments.
- Tablets:Pre-measured solid dosage units suit small-batch compounding pharmacies and veterinary formulation.
Volume placements concentrate in Powder; the faster expansion belongs to Granules.
End Use Industry:
Cost tiers separate commodity buffer applications from certification-intensive pharmaceutical supply.
- Pharmaceuticals:Injectable drug and biologic formulations demand USP and EP monograph compliance with validated endotoxin and heavy metal specifications. mRNA vaccine buffer standardization by Pfizer and Moderna affiliate manufacturers has tightened particle size distribution requirements for citrate salt inputs.
- Food & Beverage:Acidification and emulsification in dairy and beverage processing operates under Codex Alimentarius and national food additive registers. China's SAMR enforces GB 1886.306-2021 for ammonium citrate microbial limits in imported buffer salts.
- Agriculture:Chelating agent applications in micronutrient fertilizers prioritize technical-grade cost efficiency over purity certification.
- Nutraceuticals:Dietary supplement buffer systems occupy a mid-tier regulatory position between food and pharmaceutical standards.
Revenue concentration sits with Pharmaceuticals; Nutraceuticals is gaining share fastest as supplement GMP rules tighten.
Packaging Type:
Supply chain configuration reflects handling automation levels and contamination sensitivity across customer tiers.
- Bags:Multi-wall paper or woven polypropylene suits bulk powder shipments to industrial compounders. Jiangsu province manufacturers favor 25kg bags for domestic pharmaceutical distributor palletization.
- Bottles:HDPE containers with desiccant closures protect hygroscopic powder during laboratory-scale procurement. Bottled format adoption is climbing fastest among European R&D service providers requiring gram-scale repeatability.
- Drums:Steel or fiber drums with liner systems enable pharmaceutical-grade lot segregation and chain-of-custody documentation.
- Sachets:Single-use foil pouches reduce cross-contamination risk in multi-product contract manufacturing facilities.
Shipment volumes cluster in Bags; the steepest expansion trajectory belongs to Bottles.
Purity Grade:
Margin stratification follows certification burden and analytical release protocol complexity.
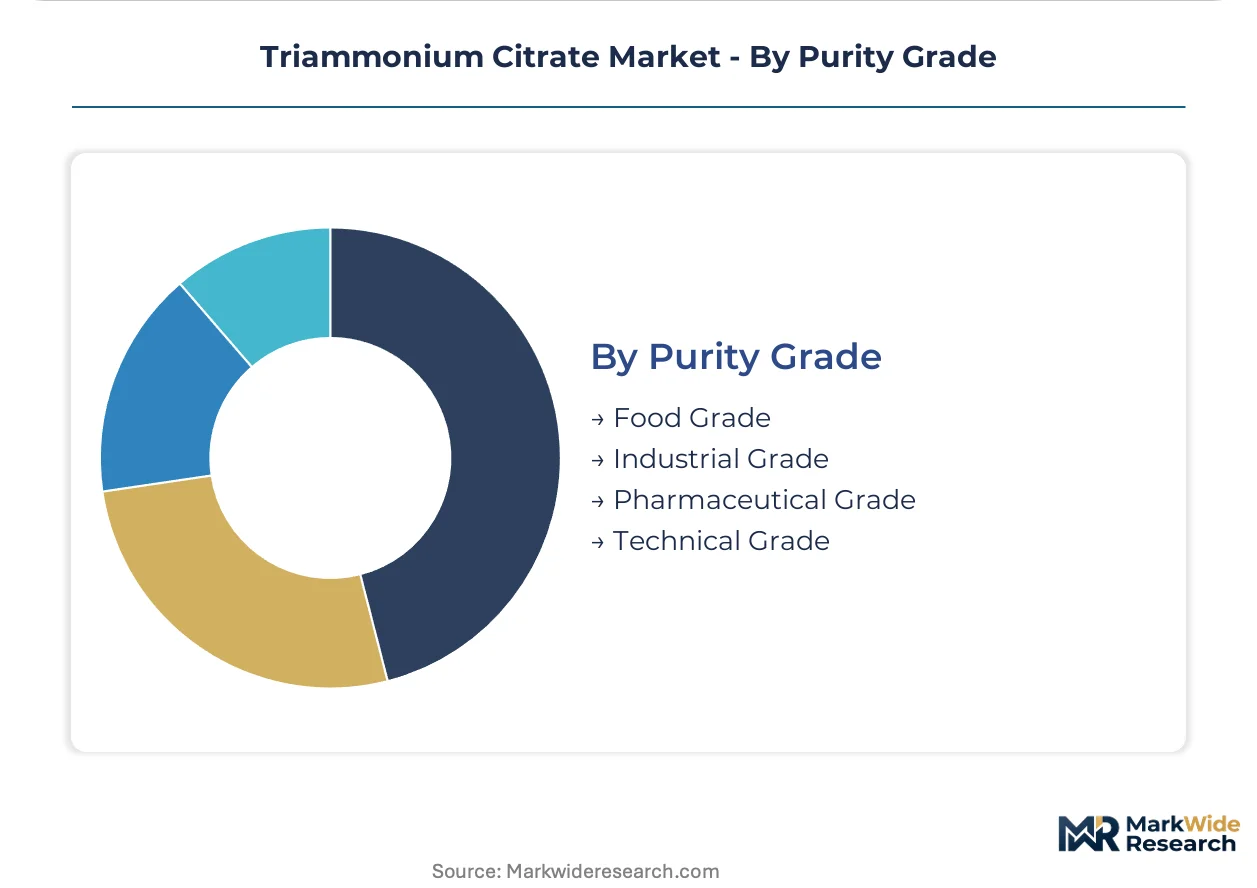
- Pharmaceutical Grade:USP-NF and EP monograph compliance with validated HPLC impurity profiling and endotoxin testing. Batch release documentation for sterile injectable applications requires six to eight weeks, compressing supplier qualification timelines for European CMOs.
- Food Grade:Heavy metal limits and microbial specifications under Codex and national food additive standards. China's GB standard revisions for ammonium citrate arsenic and lead thresholds are forcing pre-certification investments by exporters.
- Industrial Grade:Technical specifications for metal chelation and cleaning compound applications without pharmaceutical or food contact certification.
- Technical Grade:Baseline purity for agricultural and non-critical industrial buffer applications with minimal analytical documentation.
Revenue margins peak at Pharmaceutical Grade; Food Grade commands the broadest volume base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Molasses and corn-derived glucose feedstock availability anchors manufacturing economics across major producing belts. Jiangsu and Shandong provinces in China concentrate crystallization capacity near citric acid precursor plants. Regulatory divergence between FDA monograph standards and ECHA REACH dossier requirements fragments supplier qualification protocols.
China
Biologic drug buffer demand from domestic CMOs and export pharmaceutical contracts drives specialty-grade consumption. SAMR enforces GB 1886.306-2021 for ammonium citrate microbial limits and heavy metal thresholds. Jiangsu province manufacturers cluster around Taixing and Zhangjiagang chemical parks where integrated citric acid-to-citrate salt production lowers neutralization-stage costs.
Germany
Rhineland pharmaceutical corridor facilities demand pre-certified EP monograph compliance for injectable drug formulations. ECHA's 2024 respiratory sensitization guidance now mandates additional in vitro testing for REACH Annex XV dossiers. Leverkusen and Ludwigshafen industrial zones host Bayer and Boehringer Ingelheim affiliate plants that have consolidated supplier panels to three qualified citrate salt sources.
United States
mRNA vaccine manufacturers require validated endotoxin specifications and particle size distribution controls for cell culture media buffers. FDA enforces USP-NF monograph compliance with extended impurity profiling for sterile injectable applications. New Jersey and Massachusetts biotech clusters source predominantly through long-term offtake agreements with eighteen-month supply guarantees.
India
Contract manufacturing buildout for generic injectables and growing nutraceutical formulation activity expands technical-grade demand. FSSAI aligns food-grade citrate purity rules with Codex Alimentarius benchmarks for imported buffer salts. Gujarat and Maharashtra pharmaceutical zones in Ahmedabad and Mumbai-Pune corridor lack qualified local suppliers, creating import dependency for pharmaceutical-grade certification.
Vietnam
Greenfield injectable drug facilities in Ho Chi Minh City industrial zones require buffer salt inputs for nascent biologics manufacturing. The country's national pharmaceutical regulator is developing GMP inspection protocols for excipient qualification. First-mover certification advantages exist for exporters able to pre-validate against evolving ASEAN harmonization standards.
Triammonium Citrate Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification pipelines and tropical-market format differentiation. The supplier base stratifies across integrated feedstock operators, technical-grade specialists, and pharmaceutical-grade certification anchors. Three archetypes dominate: citric acid backward-integrated manufacturers, regional technical-grade compounders, and monograph-compliant pharmaceutical excipient suppliers. Competitive moves concentrate on REACH dossier pre-submission and spray-dried granule format development for humidity-resistant distribution.
Among China-based chemical manufacturers, Anhui Jinao Chemical Co., Ltd. exemplifies feedstock-integrated positioning through citric acid precursor access. Nanjing MSN Chemical Pvt., Ltd. occupies a technical-grade specialization niche for industrial buffer applications. Shanghai Sychem Pharma Co., Ltd. anchors the pharmaceutical-grade certification tier with injectable drug formulation pipelines. These three represent distinct competitive vectors without implying specific market share or strategic actions.
| Leading Market Players |
|---|
| Eagle Chemical Works |
| Anhui Jinao Chemical Co., Ltd. |
| Nanjing MSN Chemical Pvt., Ltd. |
| Xiamen Vast Land Chemical Co., Ltd. |
| A & Z Food Additives Co., Ltd. |
| Shanghai Sychem Pharma Co., Ltd. |
| Triveni Interchem Pvt. Ltd. |
| Ningxiang Xinyang Chemical Co., Ltd. |
| Jinan Boss Chemical Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Pharmaceutical contract manufacturers in Germany's Rhineland corridor command three-year price-lock provisions through consolidated supplier panels, anchoring contract-based long-term offtake as the dominant pricing model. This buyer concentration shifts pricing power toward volume-committed incumbents while compressing margin flexibility for spot-market suppliers.
Pricing Analysis
Volume placements concentrate in technical-grade and food-grade tiers where commodity spot dynamics prevail, while pharmaceutical-grade certification sustains premium positioning. Price differentiation hinges on USP-NF monograph compliance and validated endotoxin specifications versus baseline industrial purity. Cost compression in technical-grade runs through acetate and phosphate buffer substitution, eroding triammonium citrate share in pH 4.5-6.5 applications. Agricultural compounders exhibit highest price sensitivity; sterile injectable drug formulators show lowest sensitivity due to qualification switching costs.
Supply Chain Analysis
Single-source vulnerability sits with ammonia feedstock from regional plant belts in China and the US Gulf Coast, where outages disrupt neutralization throughput. Manufacturing gravity centers on Jiangsu and Shandong provinces in China, with secondary capacity in Germany's Rhineland and New Jersey's biotech corridor. Raw material dependencies draw from molasses-derived citric acid, corn-sourced glucose, and ammonia solution. Tariff exposure on citrate salt imports into Europe under REACH registration thresholds strains supply continuity. Distribution runs through multi-wall bag palletization for industrial buyers and steel drum lot segregation for pharmaceutical-grade shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH Annex XV dossier requirements and ECHA respiratory sensitization guidance erect barrier-to-entry moats favoring pre-certified incumbents with extended toxicological data sets.
For Market Incumbents: Cement qualification pipelines through pre-submission of extended safety data sets ahead of ECHA formal deadlines, locking out under-resourced competitors. Anchor backward integration into citric acid feedstock to neutralize agricultural commodity volatility threatening margin predictability. Defend against acetate and phosphate buffer substitution by co-developing application-specific pH stabilization protocols with top-twenty pharmaceutical contract manufacturers. For New Entrants and Emerging Players: Southeast Asian pharmaceutical greenfield facilities in Vietnam's Ho Chi Minh City industrial zones represent the most penetrable buyer archetype, lacking qualified local buffer salt suppliers and seeking first-mover certification partners. Spray-dried granule format development for tropical climate distribution opens white-space positioning against powder-centric incumbents. Pursue ASEAN harmonization pre-validation to capture nascent biologics manufacturing demand before regulatory protocols solidify. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap technical-grade specialists in China's Jiangsu province with latent pharmaceutical-grade certification potential and captive citric acid supply. Long-term viability hinges on five-to-ten year windows for biologic drug pipeline expansion and mRNA buffer standardization. Watch ECHA hazard classification revisions as the signal to watch for regulatory-driven consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Pre-Submission | ECHA Annex XV compliance locks in European pharmaceutical contract manufacturer supply panels before formal adoption deadlines. |
| Spray-Dried Granule Development | Humidity-resistant format opens Southeast Asian distribution channels where powder caking claims disrupt pharmaceutical procurement. |
| Backward Integration into Citric Acid | Captive molasses-to-salt production neutralizes agricultural commodity cycles compressing neutralization-process margins. |
| Continuous Crystallization Technology | Inline PAT probe deployment satisfies Bayer and Boehringer Ingelheim real-time particle size distribution contractual requirements. |
| Long-Term Offtake Agreements | Eighteen-month volume-commitment clauses displace spot procurement among New Jersey and Massachusetts mRNA vaccine manufacturers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving pharmaceutical formulation scientists, citric acid plant managers, CMO procurement leads, and ECHA regulatory affairs specialists. Bottom-up capacity modeling across Jiangsu and Shandong manufacturing clusters converged with top-down demand estimation from biologic drug pipeline databases and USP monograph revision tracking.
Granularity-level modeling disaggregated volume and value across pharmaceutical grade, food grade, industrial grade, and technical grade tiers, further split by powder, granule, solution, and tablet formats. End-use segmentation captured pharmaceuticals, food and beverage, agriculture, and nutraceuticals with regional production hub differentiation. CAGRs derived from regression analysis of historical citric acid feedstock pricing and substitution elasticity against acetate and phosphate buffers throughout the projection horizon.
Revisions become necessary when REACH Annex XV hazard classification updates, ammonia plant outage disruptions, or mRNA vaccine buffer specification shifts materialize beyond current regulatory and technological baselines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Furfural Derivatives Market
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Phthalic Anhydride Market
Bulk Chemicals
Bulk Liquid Containers Market
Bulk Chemicals
Asia Pacific Dry PVC Compound Market
Bulk Chemicals
Japan Calcium Chloride Market
Bulk Chemicals
Global Bio Based and Synthetic Dimethyl Ether (DME) Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Glyceryl Triacetate (Triacetin) Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Ammonium Dichromate Market
Bulk Chemicals
Dithiocarbamates Market
Bulk Chemicals
Bulk Molding Compounds Market