
 Global Plastics Market | 2026-2036
Global Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastics Market Outlook
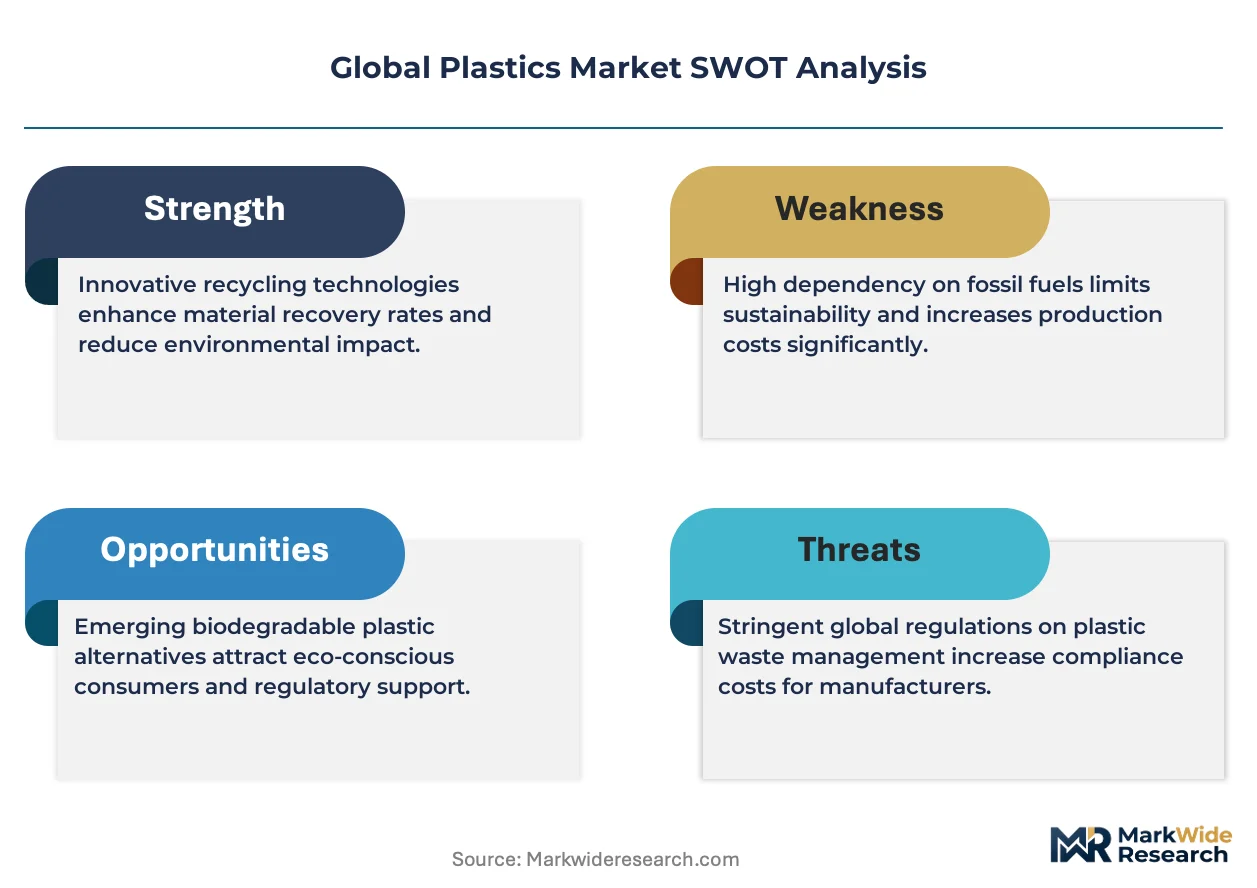
Subscription-based resin procurement and software-defined inventory management is decoupling volume commitments from spot-price exposure across the value chain. Dow leverages its integrated polyethylene platform to sustain margin stability across North American shale-advantaged operations. BASF SE anchors European engineering plastics demand through specialized polyamide and polyurethane formulations. SABIC competes in high-performance thermoplastics by controlling feedstock access across Middle Eastern petrochemical complexes.
Plastics encompass synthetic or semi-synthetic organic polymers—primarily carbon-based chains with molecular weights exceeding 10,000 g/mol—processed through extrusion, injection molding, or blow molding to achieve specific tensile strength, melt flow index, and thermal resistance properties. Their primary commercial purpose centers on substituting metal, glass, and wood with lighter, corrosion-resistant, and formable materials across industrial and consumer applications. Polyethylene dominates volume production as the workhorse commodity resin serving bulk packaging and construction films. Polypropylene captures expanding automotive and medical device applications through its sterilization compatibility and fatigue resistance. Polystyrene retains mature positions in consumer goods and insulation boards despite recycling limitations.
The EPA regulates emissions from ethylene crackers and polymerization facilities under the Clean Air Act, while REACH restricts phthalate plasticizers and persistent organic pollutants across European supply chains. China's MEE enforces dual carbon goals that cap coal-to-olefins expansion and mandate recycled content thresholds in select packaging grades. India's BIS certification requirements for food-contact plastics and construction-grade PVC create compliance gateways for import-dependent processors. Stakeholders must monitor how fragmented Extended Producer Responsibility schemes across Germany, Japan, and California reshape collection infrastructure economics and resin pricing premiums for post-consumer recycled feedstock.
Market Dynamics
EU Green Deal mandates and China's dual carbon goals are forcing parallel feedstock transitions across virgin resin supply chains while recycled content thresholds reshape procurement specifications for flexible packaging converters.
Growth Catalysts
- REACH plasticizer restrictions:Phthalate bans across European supply chains accelerate bio-based plasticizer adoption in medical tubing and food-contact films.
- Automotive lightweighting:Polypropylene compounds displace metal in electric vehicle battery housings and interior structural components.
- India's BIS certification expansion:Mandatory quality standards for food-grade polyethylene create compliance-driven replacement cycles among domestic processors.
Market Restraints
- Naphtha price volatility:Crude-linked feedstock costs compress margins for European crackers without integrated upstream positions.
- Mechanical recycling yield limits:Polyethylene terephthalate thermal degradation caps circular content rates in bottle-to-bottle applications.
- China coal-to-olefins caps:MEE enforcement of dual carbon goals restricts new methanol-based polypropylene capacity additions.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and gasification technologies unlock mixed-waste feedstocks currently excluded from mechanical streams.
- India construction-grade PVC:Infrastructure investment and urban housing drives pipe and profile demand in underpenetrated tier-2 cities.
- EU EPR scheme harmonization:Extended Producer Responsibility standardization across Germany, France, and Italy creates transparent pricing for post-consumer recycled polyethylene.
Industry Challenges
- Polymer chemist scarcity:Specialized formulation expertise for high-performance thermoplastics concentrates among retiring technical workforces in Germany and Japan.
- Multi-standard certification lag:Divergent FDA, EFSA, and BIS food-contact testing protocols extend product approval timelines for export-oriented compounders.
- Legacy extrusion retrofit costs:Capital intensity of upgrading blown film lines for recycled-content blends strains mid-scale packaging converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastics Market |
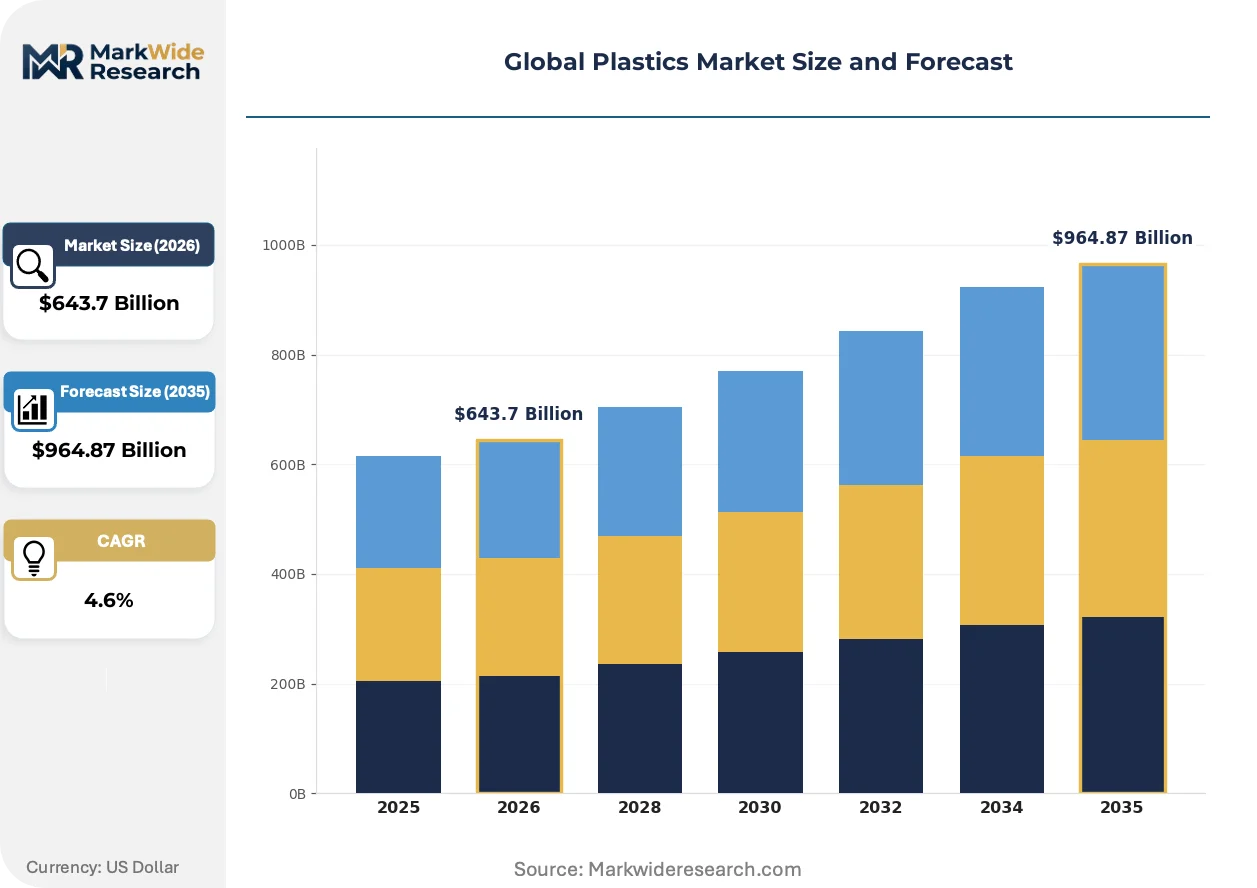
| Market Size in 2026 | $643.7 Billion |
| Market Size in 2035 | $964.87 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride Application: Packaging, Consumer Goods, Automotive Components, Medical Devices End User: Healthcare, Construction, Electronics, Agriculture Form: Granules, Sheets, Films, Foams |
| Companies Covered | ExxonMobil Chemical, SABIC, Dow, LyondellBasell Industries, BASF SE, INEOS, Borealis AG, DuPont, Formosa Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastics Market Strategic Shifts
Advanced recycling infrastructure and digital inventory platforms are converging to decouple resin procurement from spot-price volatility while enabling mass-balance tracking for sustainability claims.
Enzymatic depolymerization is unifying previously incompatible polyethylene and polypropylene waste streams into chemically identical virgin-equivalent feedstocks. Fast-moving consumer goods brands in Germany and the Netherlands are piloting offtake agreements at commercial scale. This unification collapses the historical price premium between mechanical and chemically recycled resins.
REACH authorization requirements for persistent organic pollutants in flame-retardant additives are forcing reformulation of construction-grade polystyrene insulation. Compounders serving German building markets are accelerating halogen-free alternatives through accelerated stability testing. The construction segment bears primary compliance burden through 2025-2026 certification deadlines.
Resin-as-a-service contracting is compressing traditional spot-market participation among mid-tier packaging converters. Tier-1 beverage brands in China and India now specify volume-flexible procurement with embedded sustainability verification. This model concentrates purchasing power among buyers with certified circular content targets.
Global Plastics Market Segmentation
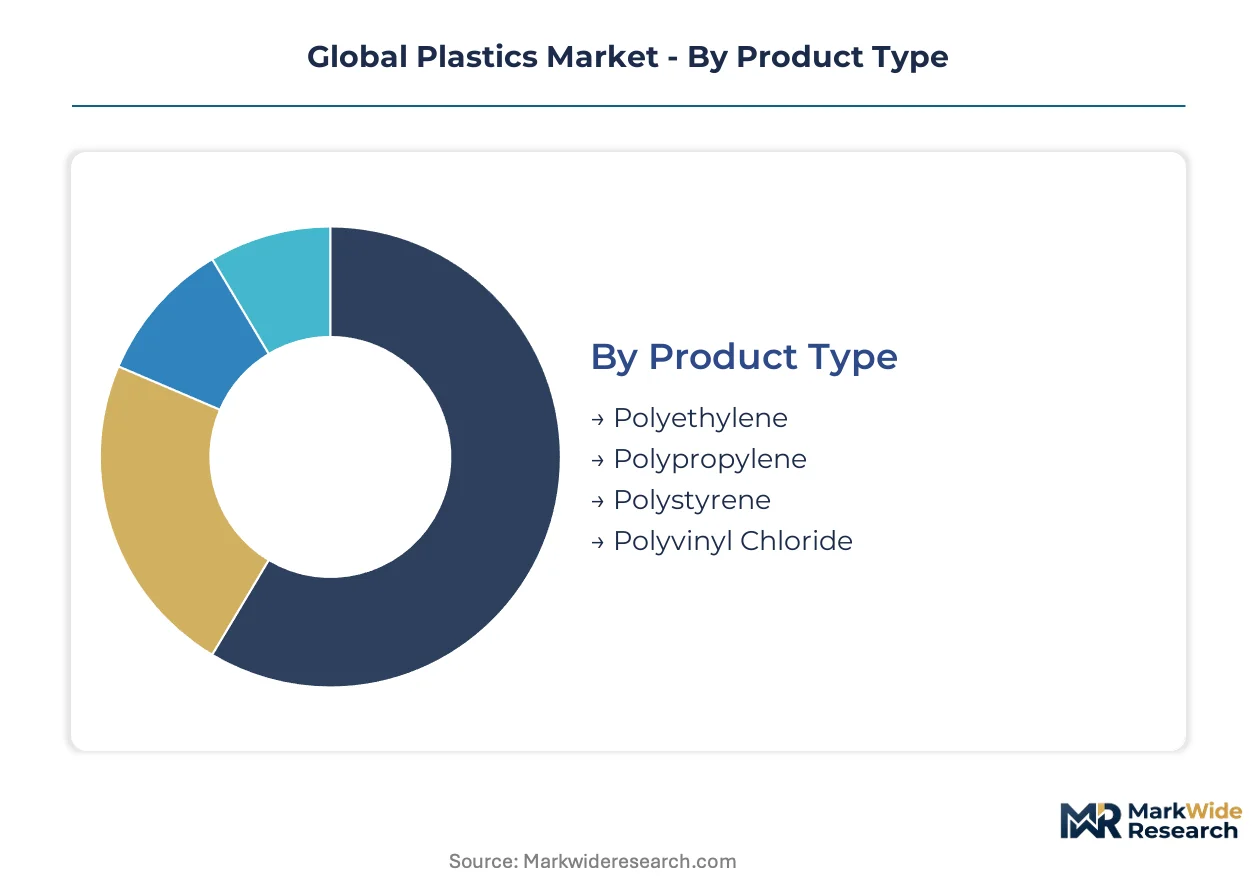
Segmentation in plastics markets reveals how resin chemistry, processing form, and end-use specifications create divergent margin profiles and procurement patterns. Understanding these divisions exposes where compounders can defend pricing power versus where commoditization pressures dominate.
Product Type:
Polyethylene functions as a standalone bulk commodity with minimal formulation complexity, while engineering thermoplastics embed deeply into customer-specific compound systems.
- Polyethylene:Linear and branched carbon-chain polymers dominate flexible packaging films and blow-molded containers through low density and moisture barrier properties. Demand concentrates in China's coastal manufacturing zones and Germany's flexible packaging corridor, driven by e-commerce shipment volume expansion and food retail format modernization.
- Polypropylene:Semi-crystalline thermoplastics with high melt flow indices serve automotive interior panels and medical sterilization trays through fatigue resistance and autoclave compatibility. German automotive Tier-1 suppliers and India's medical device exporters anchor procurement volumes, constrained by REACH authorization timelines for additive packages.
- Polystyrene:Amorphous polymers with glass transition near 100°C supply disposable foodservice items and construction insulation boards.
- Polyvinyl Chloride:Chlorinated polymers with plasticizer-dependent flexibility ranges serve pipe extrusion and cable jacketing applications.
Polyethylene leads volumes today; polypropylene is gaining share fastest.
Application:
Application segments stratify by customer concentration — beverage brand direct procurement versus fragmented converter intermediation reshapes contract structures.
- Packaging:Flexible films, rigid containers, and barrier laminates constitute the largest demand pool, with specifications tightening around recycled content thresholds in EU and Chinese regulatory frameworks. German retail chains and Indian quick-commerce platforms drive specification evolution through sustainability scorecard requirements.
- Automotive Components:Interior trim, under-hood housings, and battery structural elements demand UV-stabilized and flame-retarded grades with OEM-qualified material data sheets. China's NEV manufacturers and German premium OEMs concentrate purchasing power, constrained by polymer chemist scarcity for specialized formulation work.
- Consumer Goods:Durable household items and personal care packaging utilize commodity grades with color-masterbatch customization.
- Medical Devices:Sterilization-compatible tubing, syringe barrels, and implantable-grade resins require FDA and EMA biocompatibility certifications.
Packaging captures the widest volume base; automotive components command the steepest expansion trajectory.
End User:
End-user concentration determines inventory holding patterns — hospital system central procurement versus dispersed construction distributor networks create divergent working capital intensities.
- Healthcare:Sterile single-use devices and pharmaceutical packaging demand certified clean-room production with batch-level traceability. India's CDSCO and US FDA inspection regimes create compliance gateways that filter supplier bases.
- Construction:PVC pipe systems, insulation boards, and geomembranes serve infrastructure investment cycles with project-based volume spikes. China's tier-2 city urbanization and India's PM-Gati Shakti corridor development concentrate demand geography.
- Electronics:Connector housings and circuit board substrates require flame-retardant grades with halogen-free formulations for EU RoHS compliance.
- Agriculture:Mulch films, irrigation tubing, and greenhouse sheeting demand UV-stabilized grades with seasonally concentrated procurement timing.
Construction leads volumes today; healthcare is expanding most quickly.
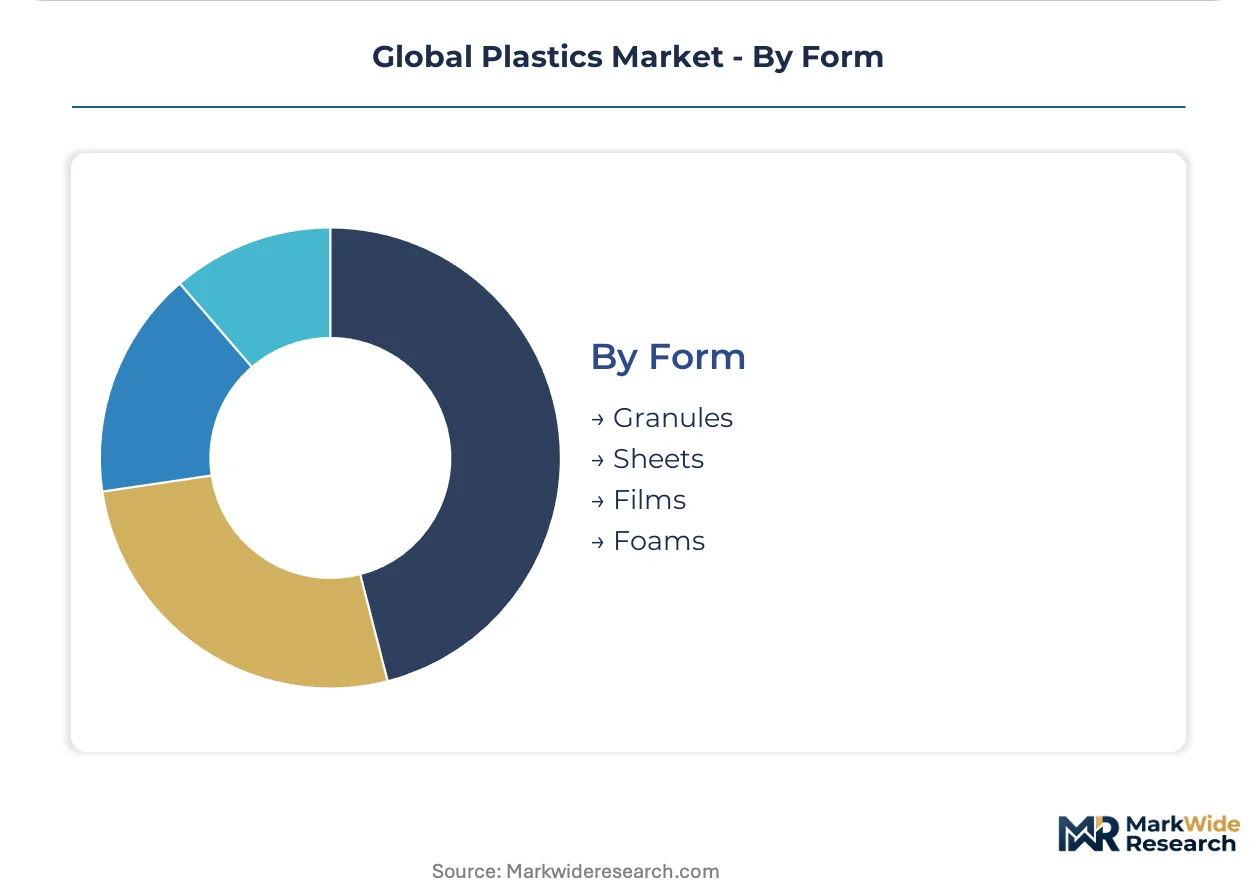
Form:
Form factor determines logistics economics — bulk granular shipment versus precision-cut sheet dimensions reshape distribution radius and customer switching costs.
- Granules:Standardized pellet form enables bulk railcar and silo-truck logistics to compounders and injection molders across North American shale-advantaged corridors and European integrated petrochemical complexes.
- Films:Blown and cast extrusion outputs serve flexible packaging converters with gauge-tolerance specifications for high-speed form-fill-seal equipment. German and Dutch advanced recycling pilots are collapsing price premiums for chemically recycled film grades.
- Sheets:Thermoforming feedstock for trays and clamshells with thickness caliper specifications.
- Foams:Expanded polystyrene and polyurethane cellular structures for protective packaging and insulation applications.
Granules lead volumes today; films are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes more virgin polyethylene than Germany and India combined, yet regulatory divergence is fragmenting procurement specifications across these three manufacturing anchors.
China
Coal-to-olefins capacity expansion faces hard caps under MEE enforcement of dual carbon goals, redirecting investment toward chemical recycling pilots in Ningbo and Shanghai. The Yangtze River Delta concentrates flexible film production for e-commerce packaging, with converters sourcing mass-balance certified resins to meet brand sustainability scorecards.
Germany
REACH authorization timelines for phthalate plasticizers and flame-retardant additives compress formulation lead times for automotive Tier-1 suppliers. The Rhine-Ruhr petrochemical corridor anchors European engineering plastics demand, while Hamburg and Rotterdam advanced recycling hubs collapse price premiums for pyrolysis-derived polyethylene.
India
BIS certification requirements for food-grade polyethylene and construction PVC create compliance gateways filtering import-dependent processors. Maharashtra and Gujarat host expanding flexible packaging converter clusters serving quick-commerce platforms, with PM-Gati Shakti infrastructure investment driving pipe extrusion demand in tier-2 cities.
United States
Shale-advantaged ethane feedstock sustains margin stability for Gulf Coast polyethylene producers despite naphtha volatility in European benchmarks. EPA Clean Air Act enforcement shapes cracker emissions compliance costs, while Texas and Louisiana chemical recycling projects target mixed-waste feedstocks excluded from mechanical streams.
Saudi Arabia
Jubail and Yanbu petrochemical complexes leverage integrated feedstock access to compete in high-performance thermoplastics exports. SABIC-controlled production clusters serve Asian automotive and European packaging specifications, with domestic consumption remaining thin relative to export orientation.
Global Plastics Market Competitive Environment
Top-tier vendors anchor integrated petrochemical platforms, while mid-scale compounders defend niche formulation expertise. The vendor base stratifies across commodity resin producers with captive feedstock, engineering plastics specialists with OEM qualification depth, and regional packaging converters with sustainability certification leverage. M&A activity concentrates on chemical recycling technology access and backward integration into pyrolysis feedstock supply.
Within the integrated petrochemical tier, ExxonMobil Chemical and SABIC exemplify scale-driven positions anchored to shale or gas-based feedstock economics. Dow and LyondellBasell Industries occupy the North American commodity polyethylene vector, while BASF SE represents European engineering plastics specialization through polyamide and polyurethane formulation depth. DuPont and INEOS sit within the performance materials archetype, with Borealis AG exemplifying regional European consolidation around advanced recycling and circular content verification systems.
| Leading Market Players |
|---|
| ExxonMobil Chemical |
| SABIC |
| Dow |
| LyondellBasell Industries |
| BASF SE |
| INEOS |
| Borealis AG |
| DuPont |
| Formosa Plastics Corporation |
| Others |
Value Chain & Pricing Dynamics
Naphtha feedstock costs transmit from European crackers through polymerization facilities into flexible packaging converter margins, with shale-advantaged North American producers operating on divergent cost curves. This input-cost fragmentation stratifies pricing power across integrated versus merchant resin suppliers.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity polyethylene grades, pressuring legacy naphtha-based producers in Germany and South Korea. Contract-based long-term offtake agreements dominate procurement between Tier-1 beverage brands and resin suppliers, with price differentiation resting on mass-balance certification tiers and recycled content verification. Cost compression in standard-grade polyethylene intensifies because coal-to-olefins expansions face MEE enforcement caps. Quick-commerce platforms in India exhibit highest price sensitivity, while German automotive Tier-1 suppliers prioritize formulation stability over unit cost.
Supply Chain Analysis
Post-consumer collection and pyrolysis-derived feedstock flows are reconfiguring raw material pathways for circular polyethylene production. Virgin resin supply concentrates in China, Saudi Arabia, and the United States, with polymerization output drawing from ethane, naphtha, and coal-to-olefins feedstocks. The supply chain hinges on cracker operating rates and MEE dual carbon enforcement. Single-source vulnerability concentrates in Middle Eastern ethane-advantaged complexes. Distribution runs through bulk railcar and silo-truck networks to compounders across North American shale corridors and European integrated petrochemical hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Plastics Market compounds steadily as packaging demand from e-commerce and food retail modernization sustains volume expansion across flexible films and rigid containers.
For Market Incumbents: Cement feedstock integration advantages through captive ethane access or chemical recycling offtake agreements. Lock in long-term supply contracts with quick-commerce platforms in India and Germany before recycled content mandates harden procurement specifications. Defend against pyrolysis-based new entrants by accelerating mass-balance certification for existing polyethylene capacity.
For New Entrants and Emerging Players: Packaging converters in India's tier-2 cities represent the most penetrable channel partner type for construction-grade PVC and food-contact polyethylene. Target BIS certification-compliant processors in Maharashtra and Gujarat with embedded sustainability verification services. Partner with advanced recycling technology licensors to bypass virgin resin scale disadvantages.
For Investors and Strategic Acquirers: Consolidation pressure builds where chemical recycling technology access concentrates among pilot-stage operators with proven pyrolysis yields. The five-to-ten year viability window favors acquisition targets with OEM-qualified material data sheets in automotive polypropylene. Monitor REACH authorization timelines for phthalate plasticizers as inflection indicators for bio-based alternative valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Feedstock | Chemical recycling scale-up unlocks mixed-waste streams excluded from mechanical recycling in Germany and the Netherlands. |
| Mass-Balance Certification Investment | EU EPR scheme harmonization creates transparent pricing premiums for post-consumer recycled polyethylene across German retail chains. |
| Long-term Supply Agreement with Quick-Commerce Platforms | Volume-flexible procurement with embedded sustainability verification concentrates purchasing power among Indian e-commerce intermediaries. |
| Joint Venture for Coal-to-Olefins Capacity | MEE dual carbon caps restrict standalone expansion, favoring partnered approaches to methanol-based polypropylene in China. |
| Green Manufacturing Transition to Bio-Based Plasticizers | REACH phthalate bans accelerate reformulation demand from German medical tubing and food-contact film compounders. |
Study Parameters
Coverage spans China, Germany, India, and the United States, with primary inputs from each region's resin procurement and converter networks. The analysis combines interviews with petrochemical plant managers, flexible packaging procurement leads, automotive Tier-1 supplier engineers, and distribution channel partners with secondary validation from customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE regulatory disclosures. Bottom-up resin demand modeling triangulates against top-down macroeconomic consumption benchmarks.
Rate-of-change decomposition separates volume drivers from price-mix effects across the projection horizon. The analytical framework segments by product chemistry, processing form, end-use application, and regional production hub, with CAGRs derived from elasticity-adjusted demand curves and capacity utilization trajectories. Forecast inputs incorporate REACH authorization timelines, MEE dual carbon enforcement intensity, and BIS certification expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to pyrolysis technology scale-up rates and EPR scheme harmonization progress. Practitioners should monitor enzymatic depolymerization pilot yields and coal-to-olefins permit approvals for early signals of feedstock transition velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
North America Potassium Formate Market
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
Lithium Bromide Market
Bulk Chemicals
United States Fumaric Acid Market
Bulk Chemicals
US Magnesium Stearate Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Nitric Acid Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
Acetyl Tributyl Citrate Market