
 Global Magnesium Hydroxide Market | 2026-2036
Global Magnesium Hydroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Magnesium Hydroxide Market Foresight
Asset-light toll manufacturing and third-party processing agreements are fragmenting capital requirements for entry into magnesium hydroxide refining. Kyowa Chemical Industry Co., Ltd. leverages proprietary precipitation technology to sustain premium positioning in pharmaceutical grades. Huber Engineered Materials anchors North American supply through integrated brine processing in the United States. Nedmag B.V. competes on scale from its Dutch magnesia operations, serving European water treatment facilities with consistent bulk chemistry.
Magnesium hydroxide is an inorganic compound with the formula Mg(OH)₂, typically produced through hydration of magnesium oxide or direct precipitation from brine sources, with purity levels varying from technical grades at 90-95% to pharmaceutical grades exceeding 99% for antacid and laxative applications. Its primary industrial purpose centers on acid neutralization, flame suppression through endothermic decomposition at 332°C releasing water vapor, and heavy metal precipitation in wastewater streams. Flame retardant grade applications dominate volume offtake as construction and electrical codes tighten smoke toxicity requirements across multiple jurisdictions. Pharmaceutical grade commands the highest margin pool due to certification complexity and limited qualified suppliers, while standard industrial grades face pricing pressure from Chinese capacity expansions.
The EPA oversees industrial chemical reporting under TSCA, while REACH in Europe mandates substitution assessments for persistent halogenated compounds, both frameworks accelerating magnesium hydroxide qualification in polymer formulations. China's MEE enforces wastewater discharge standards that elevate magnesium hydroxide demand for neutralization systems in metal finishing and chemical manufacturing. Stakeholders must monitor regulatory harmonization between EU F-Gas Regulation extensions and emerging state-level restrictions in the United States, as these will determine substitution timelines and contract structuring for flame retardant procurement.
Market Dynamics
Halogen-free flame retardant mandates are compressing substitution timelines across polymer supply chains, forcing compounders to qualify magnesium hydroxide ahead of regulatory deadlines rather than on cost parity alone.
Growth Catalysts
- REACH substitution assessments:ECHA's persistent organic pollutant restrictions are accelerating halogenated flame retardant phase-outs across EU electrical equipment manufacturing, directly elevating magnesium hydroxide procurement quotas.
- Wire and cable sector expansion:China's domestic construction boom and grid modernization are concentrating demand for low-smoke halogen-free compounds in building infrastructure applications.
- Endothermic decomposition chemistry:Magnesium hydroxide releases water vapor at 332°C without toxic byproducts, satisfying evolving smoke toxicity codes in transportation and residential sectors.
Market Restraints
- Dolomite and brine input volatility:Energy-intensive calcination of magnesium oxide precursors exposes producers to natural gas price swings, compressing margins on technical grades.
- Chinese supply concentration:Captive production scaling by domestic chemical conglomerates is crowding out merchant market pricing power for non-integrated refiners.
- Processing temperature limitations:Magnesium hydroxide's decomposition threshold restricts compatibility with high-temperature engineering polymers, capping addressable resin markets.
Strategic Opportunities
- India's industrial wastewater standards:Central Pollution Control Board enforcement of heavy metal discharge limits is opening neutralization system contracts for magnesium hydroxide suppliers.
- Pharmaceutical grade certification:USP and EP compliance complexity limits qualified suppliers, preserving margin pools for precipitation technology specialists.
- Nanoparticle surface modification:Coupling agents and compatibilizers are enabling magnesium hydroxide dispersion in polyolefins at higher loadings without mechanical degradation.
Industry Challenges
- Pharmaceutical validation timelines:FDA and EMA GMP certification cycles extend 18-24 months, delaying revenue recognition for new production facilities.
- Particle size distribution control:Consistent sub-micron precipitation requires precise pH and residence time management, constraining toll manufacturing quality yields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Magnesium Hydroxide Market |
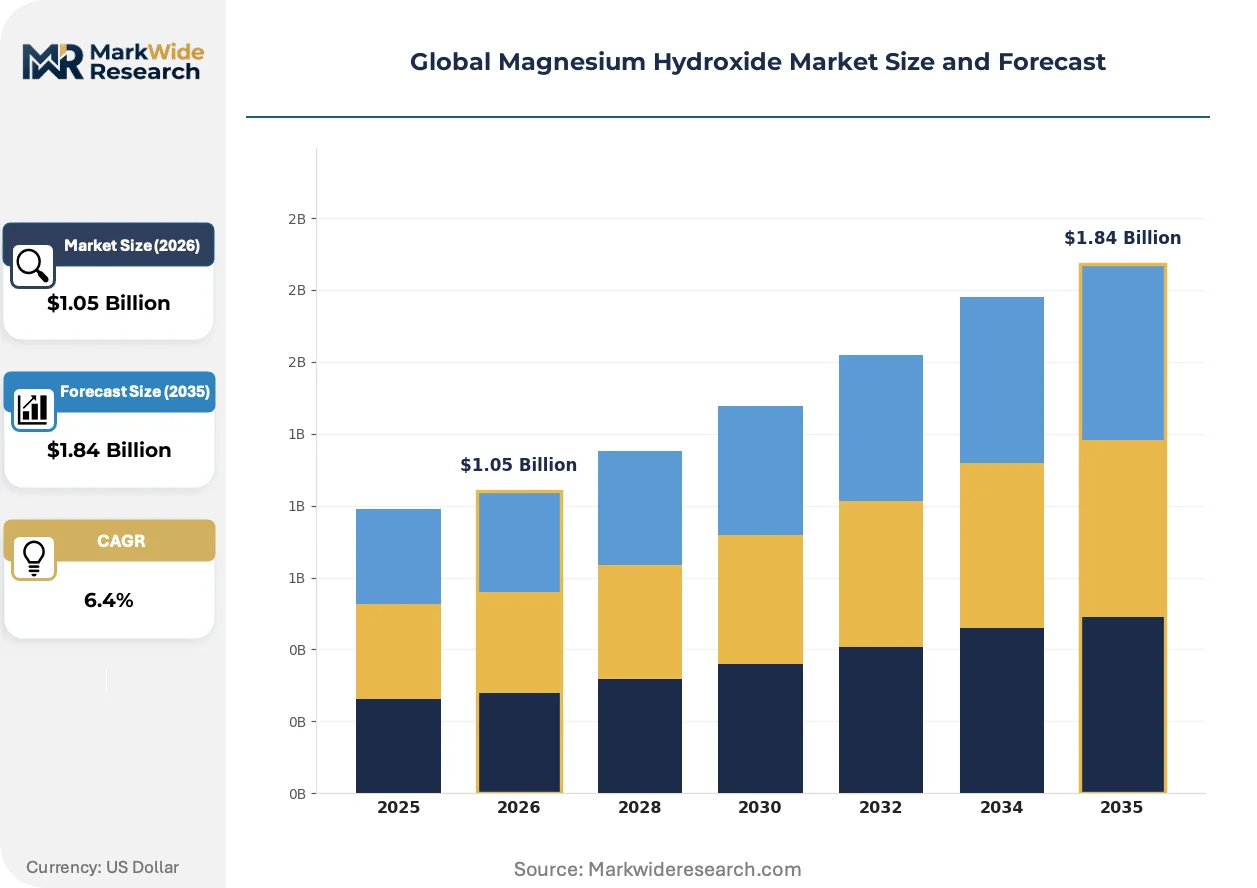
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Grade, Pharmaceutical Grade, Flame Retardant Grade, Food Grade Application: Wastewater Treatment, Flame Retardants, Paper Industry, Cosmetics, Environmental Protection End User Industry: Chemical Manufacturers, Paint Producers, Water Treatment Facilities, Paper Mills Form: Powder, Suspension, Granules, Pellets |
| Companies Covered | Kyowa Chemical Industry Co., Ltd., Huber Engineered Materials, ICL, Nedmag B.V., Konoshima Chemical Co., Ltd., Martin Marietta Magnesia Specialties, Elementis PLC, NikoMag, Ube Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Magnesium Hydroxide Market Shifts & Advancements
Process intensification and digital quality control are compressing batch-to-batch variability, enabling tighter specification contracts in pharmaceutical and electronic-grade segments previously dominated by incumbent specialists.
Continuous precipitation reactor design is virtualizing traditional batch magnesium hydroxide production. Specialty chemical manufacturers in Japan and Germany are retrofitting stirred-tank systems with real-time particle monitoring, cutting residence times by half while tightening median particle size distributions. This virtualization is collapsing the historical trade-off between throughput and pharmaceutical-grade purity, permitting mid-scale producers to contest premium segments.
EU F-Gas Regulation extensions are tightening restrictions on fluorinated compounds used in polymer processing aids, indirectly elevating magnesium hydroxide relevance in extrusion applications where alternative lubricants face scrutiny. Compounders serving automotive interior specifications are reformulating ahead of 2027 assessment deadlines, stockpiling qualified magnesium hydroxide inventories to preempt supply chain disruption.
Specification-driven supplier consolidation is compressing approved vendor lists across European wire and cable procurement. Tier-one compounders are mandating REACH-compliant full material disclosure, disqualifying traders lacking batch-level traceability. German and French electrical distributors are responding by direct-contracting magnesium hydroxide refiners with integrated brine-to-powder documentation, bypassing merchant intermediaries.
Global Magnesium Hydroxide Market Segmentation
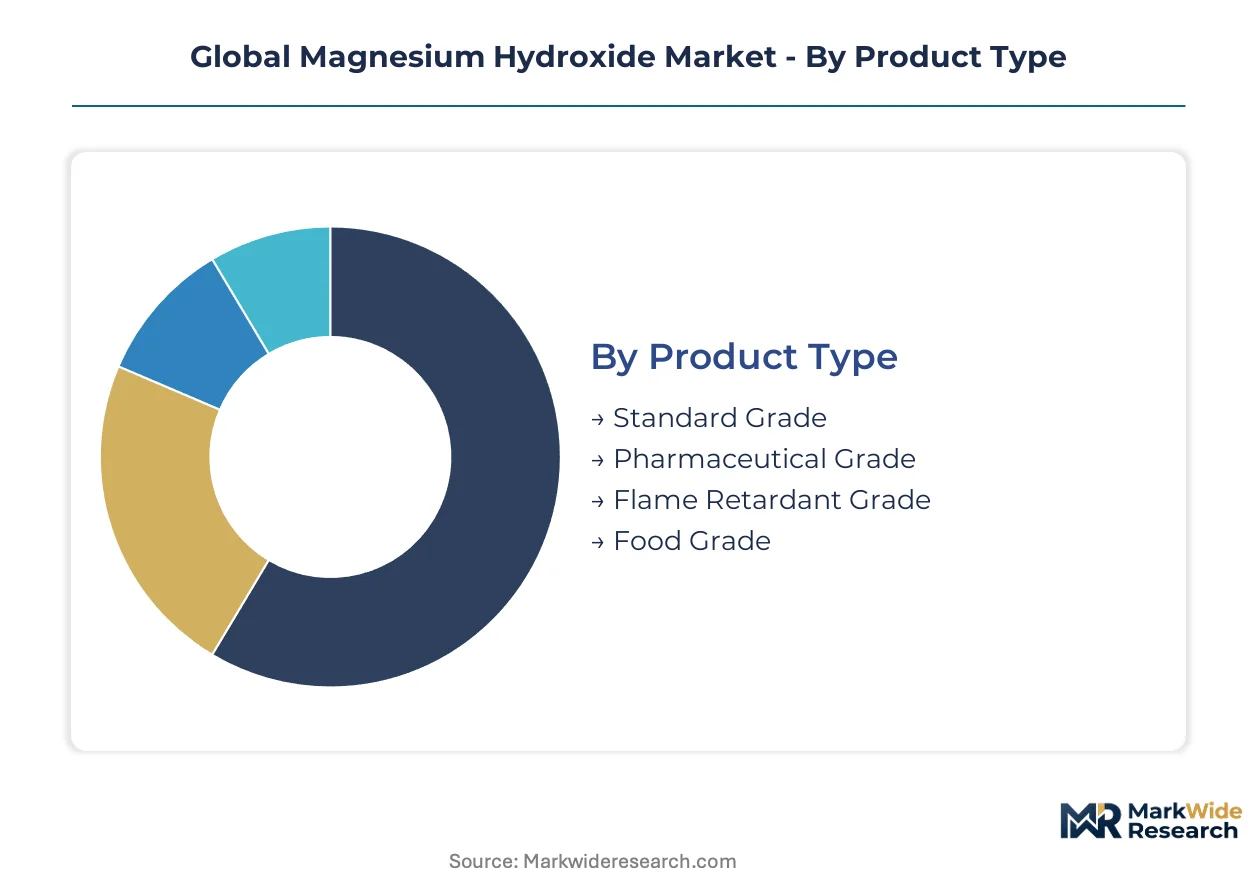
Magnesium hydroxide markets stratify sharply across purity thresholds and performance specifications. Product grades command radically different margin structures and certification requirements, while application segments diverge on regulatory drivers and substitution economics.
Product Type:
Use-case spectrum spans commodity neutralization agents through GMP-certified pharmaceuticals.
- Standard Grade:Technical purity of 90-95% serves bulk neutralization in metal finishing and chemical processing. Chinese captive producers dominate volume, compressing merchant pricing for non-integrated refiners.
- Pharmaceutical Grade:Exceeding 99% purity with USP/EP compliance, this segment commands the highest margin pool. Precipitation technology specialists in Japan and Germany limit qualified supplier count through 18-24 month FDA/EMA validation cycles.
- Flame Retardant Grade:Surface-modified variants with controlled particle size distribution address polymer compatibility requirements. REACH substitution assessments and evolving EPA standards under TSCA are accelerating procurement quotas from wire and cable compounders.
- Food Grade:Meets FCC and JECFA specifications for pH adjustment and magnesium fortification. Demand concentrates in beverage processing and nutritional supplements with stringent heavy metal limits.
Established volume favors Standard Grade; emerging adoption favors Pharmaceutical Grade.
Application:
Cost tier separation distinguishes compliance-driven substitution from discretionary process optimization.
- Wastewater Treatment:Heavy metal precipitation and pH neutralization in industrial discharge systems. China's MEE and India's Central Pollution Control Board enforcement are elevating contract volumes for metal finishing and chemical manufacturing facilities.
- Flame Retardants:Endothermic decomposition at 332°C releases water vapor without toxic byproducts. EU F-Gas Regulation extensions and state-level U.S. restrictions on halogenated alternatives are compressing qualification timelines ahead of 2027 deadlines.
- Paper Industry:Alkaline sizing and pitch control applications. Mills in Germany and Japan employ magnesium hydroxide as a milder alternative to caustic soda for fiber preservation.
- Cosmetics:Absorbent and pH buffering properties in skincare formulations. Formulators favor synthetic precipitated grades over mineral-derived alternatives for consistent heavy metal profiles.
- Environmental Protection:Flue gas desulfurization and acid rain mitigation. European power utilities and industrial boilers deploy slurry injection systems for SOx capture.
Regulatory compliance spending concentrates in Flame Retardants; operational cost savings drive Paper Industry procurement.
End User Industry:
Customer type determines contract structure, from spot chemical trading to multi-year pharmaceutical supply agreements.
- Chemical Manufacturers:Integrated producers consume captive magnesium hydroxide for derivative magnesia compounds. Merchant demand focuses on specialty precipitated grades for catalyst supports and fine chemicals.
- Paint Producers:Anti-corrosive primers and pH stabilizers in waterborne coatings. Formulators specify low-iron grades to prevent discoloration in white and pastel finishes.
- Water Treatment Facilities:Municipal and industrial plants deploy slurry systems for alkaline addition. Dutch and German utilities favor bulk deliveries from integrated brine processors with consistent bulk chemistry.
- Paper Mills:Kraft and mechanical pulp operations employ magnesium hydroxide for sulfidity control. Scandinavian mills lead adoption of closed-loop neutralization systems.
Integration economics favor Chemical Manufacturers; outsourcing trends favor Water Treatment Facilities.
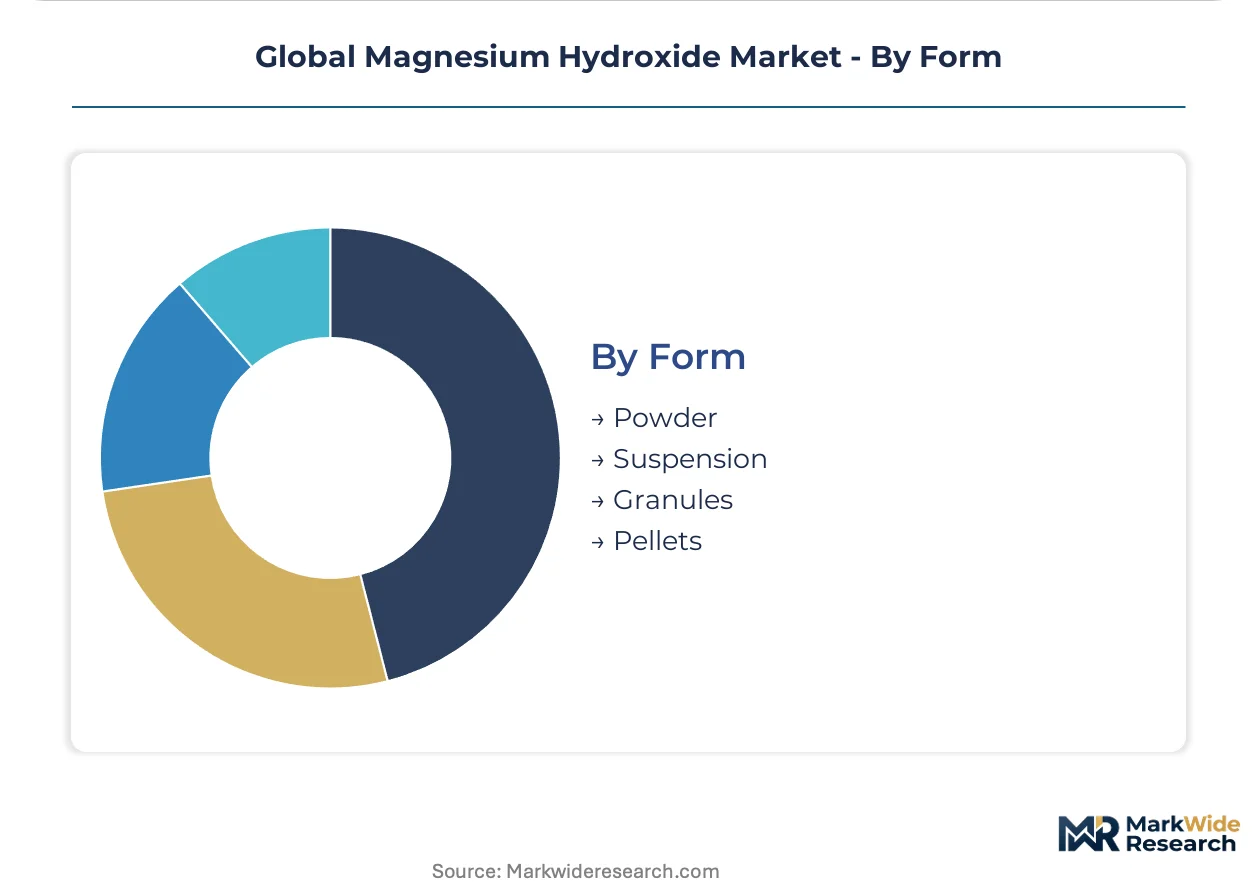
Form:
Supply concentration and logistics economics shape regional form preferences.
- Powder:Spray-dried and milled grades dominate long-distance shipping for polymer compounding and pharmaceutical tableting. Dust handling requirements limit adoption in open-system wastewater applications.
- Suspension:Aqueous slurries at 50-60% solids enable pumped delivery to water treatment and flue gas systems. Nedmag B.V. and Huber Engineered Materials anchor European and North American supply through dedicated tanker networks.
- Granules:Agglomerated forms improve flowability in automated feeding systems. Fertilizer and soil amendment applications in Brazil and Australia specify granular grades for mechanical spreading compatibility.
- Pellets:Compressed forms for controlled-release antacid and laxative formulations. Japanese pharmaceutical manufacturers specify pellet geometry for dissolution rate engineering.
Unit logistics efficiency favors Suspension; formulation flexibility favors Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China maintains a substantial export surplus in magnesium hydroxide, shipping flame retardant grades to Southeast Asian wire and cable manufacturers while importing pharmaceutical grades from Japanese precipitation specialists. The United States and Germany run structural deficits, relying on Dutch and Israeli brine processors for water treatment slurries. India's emerging neutralization demand is absorbing surplus Chinese technical grades, reshaping regional trade corridors.
China
Domestic chemical conglomerates are scaling captive flame retardant production to serve the wire and cable industry's low-smoke halogen-free compound requirements. MEE wastewater discharge standards are elevating magnesium hydroxide procurement for metal finishing neutralization systems. Shandong Peninsula chemical clusters are integrating brine-to-powder operations, displacing merchant market volumes.
United States
Electrical equipment manufacturers are accelerating magnesium hydroxide qualification ahead of evolving EPA standards under TSCA. The EPA's tightening restrictions on halogenated flame retardants are compressing substitution timelines for polymer compounders. Gulf Coast brine processors are expanding precipitation capacity to reduce dependence on Asian technical grade imports.
Germany
Wire and cable compounders are mandating REACH-compliant full material disclosure, disqualifying traders lacking batch-level traceability. ECHA's persistent organic pollutant restrictions are forcing halogenated flame retardant phase-outs across EU electrical equipment manufacturing. Rhine-Ruhr industrial corridors are direct-contracting integrated refiners with brine-to-powder documentation.
Japan
Pharmaceutical manufacturers are specifying pellet geometry for controlled-release antacid and laxative formulations requiring USP and EP compliance. METI industrial standards are tightening heavy metal limits in synthetic precipitated grades for cosmetics applications. Kansai chemical clusters are retrofitting stirred-tank systems with real-time particle monitoring to contest premium segments.
India
Central Pollution Control Board enforcement of heavy metal discharge limits is opening neutralization system contracts for magnesium hydroxide suppliers. Metal finishing facilities in Gujarat and Maharashtra are deploying slurry systems for alkaline addition ahead of regulatory deadlines. Domestic construction booms are concentrating demand for flame retardant grades in building infrastructure applications.
Global Magnesium Hydroxide Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying precipitation technology and surface modification expertise. The market structures around three tiers: integrated brine processors with captive mineral rights, toll manufacturing networks fragmenting capital requirements, and pharmaceutical-grade precipitation specialists with GMP-certified facilities. Two dominant competitive moves are reshaping positioning: backward integration into magnesite mining and brine extraction, and technology licensing agreements spreading proprietary surface modification methods.
Among Japanese precipitation specialists, Kyowa Chemical Industry Co., Ltd. and Konoshima Chemical Co., Ltd. occupy positions within the pharmaceutical-grade tier, representing the archetype of GMP-certified producers with extended validation cycles. Huber Engineered Materials exemplifies the integrated North American processor, anchoring regional supply through dedicated logistics networks. Nedmag B.V. sits within the European scale-driven segment, supplying bulk chemistry to water treatment utilities with consistent brine sourcing.
| Leading Market Players |
|---|
| Kyowa Chemical Industry Co., Ltd. |
| Huber Engineered Materials |
| ICL |
| Nedmag B.V. |
| Konoshima Chemical Co., Ltd. |
| Martin Marietta Magnesia Specialties |
| Elementis PLC |
| NikoMag |
| Ube Corporation |
| Others |
Supply & Pricing Matrix
Shandong Peninsula chemical clusters anchor global flame retardant grade capacity, with captive brine-to-powder operations compressing merchant pricing power for non-integrated refiners serving wire and cable compounders. Chinese domestic producers leverage integrated magnesia sourcing to undercut European and North American toll manufacturers on technical grades, while pharmaceutical precipitation specialists in Japan preserve premium positioning through GMP-certified scarcity.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratification across pharmaceutical, flame retardant, and standard technical grades. Price differentiation hinges on USP/EP certification tier and volume scale commitments, with pharmaceutical buyers showing least sensitivity due to 18-24 month FDA validation lock-in. Pricing pressure intensifies in standard grades as Chinese capacity additions crowd merchant spot markets, while flame retardant premiums hold firm on REACH substitution deadlines.
Supply Chain Analysis
Export control regimes on precipitation technology limit Japanese and German equipment flows to emerging producers, constraining pharmaceutical grade supply expansion. Production concentrates in China, Japan, and the Netherlands, with raw material dependencies on dolomite deposits, natural brine sources, and natural gas for calcination energy. Single-source vulnerability runs through Chinese captive production for technical grades, while distribution feeds from integrated brine processors through dedicated slurry tanker networks to water treatment utilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, EPA TSCA, and China's MEE creates niche qualification windows for specialty grade producers, fragmenting what was historically a commodity chemical market into certification-tiered segments.
For Market Incumbents: Harden supply chain documentation to meet REACH full material disclosure mandates from German and French electrical distributors, while securing captive brine rights or toll manufacturing partnerships to defend margin position against Chinese integrated producers. Prioritize precipitation technology licensing to capture revenue from entrants facing 18-24 month pharmaceutical validation barriers. For New Entrants and Emerging Players: Build out nanoparticle surface modification capabilities to serve polyolefin compounders seeking higher magnesium hydroxide loadings without mechanical degradation, targeting India's Central Pollution Control Board enforcement window for wastewater neutralization systems. Lead with slurry logistics partnerships rather than powder capacity to bypass established tanker networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because halogen-free flame retardant mandates are compressing substitution timelines faster than incumbent capacity can respond, creating acquisition value in mid-scale precipitation specialists with validated pharmaceutical pipelines. Monitor EU F-Gas Regulation extension implementation as the inflection signal for extrusion-grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Extraction | Secures magnesia supply for integrated producers competing with Chinese captive operations. |
| Pharmaceutical Grade Certification Investment | Locks in 18-24 month FDA/EMA validation barriers against commodity grade entrants. |
| Surface Modification Technology Licensing | Spreads proprietary compatibilizer methods to polyolefin compounders seeking higher loadings. |
| Slurry Logistics Network Expansion | Enables pumped delivery to water treatment facilities bypassing powder handling limitations. |
| Continuous Precipitation Reactor Retrofit | Compresses batch-to-batch variability for pharmaceutical and electronic grade contracts. |
Research Methodology
The analysis maps flame retardant, pharmaceutical, wastewater treatment, and paper processing sub-sectors, each validated through plant managers at integrated brine processors, procurement leads at wire and cable compounders, technical R&D directors at surface modification specialists, and distribution channel partners. Primary interview findings triangulate against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed chemical conglomerates, and MEE wastewater discharge enforcement records, with bottom-up grade-volume builds cross-checked against top-down end-use consumption estimates.
Assumptions held fixed include regulatory enforcement timelines for REACH substitution assessments and EPA TSCA restrictions, while natural gas input costs and Chinese capacity expansion rates varied across sensitivity scenarios. The projection framework models grade tier, end-use industry, form factor, and regional production hub segmentation, with CAGRs derived from regression against historical qualification cycle data and polymer formulation substitution elasticities. Forecast inputs incorporate wire and cable sector expansion rates in China and India, plus pharmaceutical validation queue lengths at FDA and EMA.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese chemical conglomerates or accelerated precipitation technology licensing by Japanese specialists would shift outcomes. Material shifts in EU F-Gas Regulation extension scope, EPA TSCA implementation pace, or MEE wastewater enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Hot Briquetted Iron (HBI) Market
Metals & Minerals
Cobalt Sulphate Market
Metals & Minerals
US Lithium Market
Metals & Minerals
Boron Ore Market
Metals & Minerals
Recycled Aluminum Market
Metals & Minerals
Rare Earth Elements Market
Metals & Minerals
Mineral Ingredients Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Mineral Screening Market
Metals & Minerals
Direct Reduced Iron (DRI) Market
Metals & Minerals
Laminated Steel Market
Metals & Minerals
Nickel Nano Powder Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Dead Sea Mineral Market
Metals & Minerals
Global Fabricated Metal Products Market