
 Valeric Acid Market | 2026-2036
Valeric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Valeric Acid Market Analysis
China is narrowing its dependence on imported valeric acid through domestic oxo-synthesis capacity additions in Jiangsu and Shandong provinces. OXEA GmbH leverages backward integration into petrochemical feedstocks to control cost volatility across European supply chains. Evonik Industries AG sustains R&D intensity in high-purity grades for pharmaceutical contract manufacturing. BASF SE anchors volume production through its Ludwigshafen integrated site, while Perstorp Holding AB specializes in bio-based pentanoic acid routes for fragrance applications.
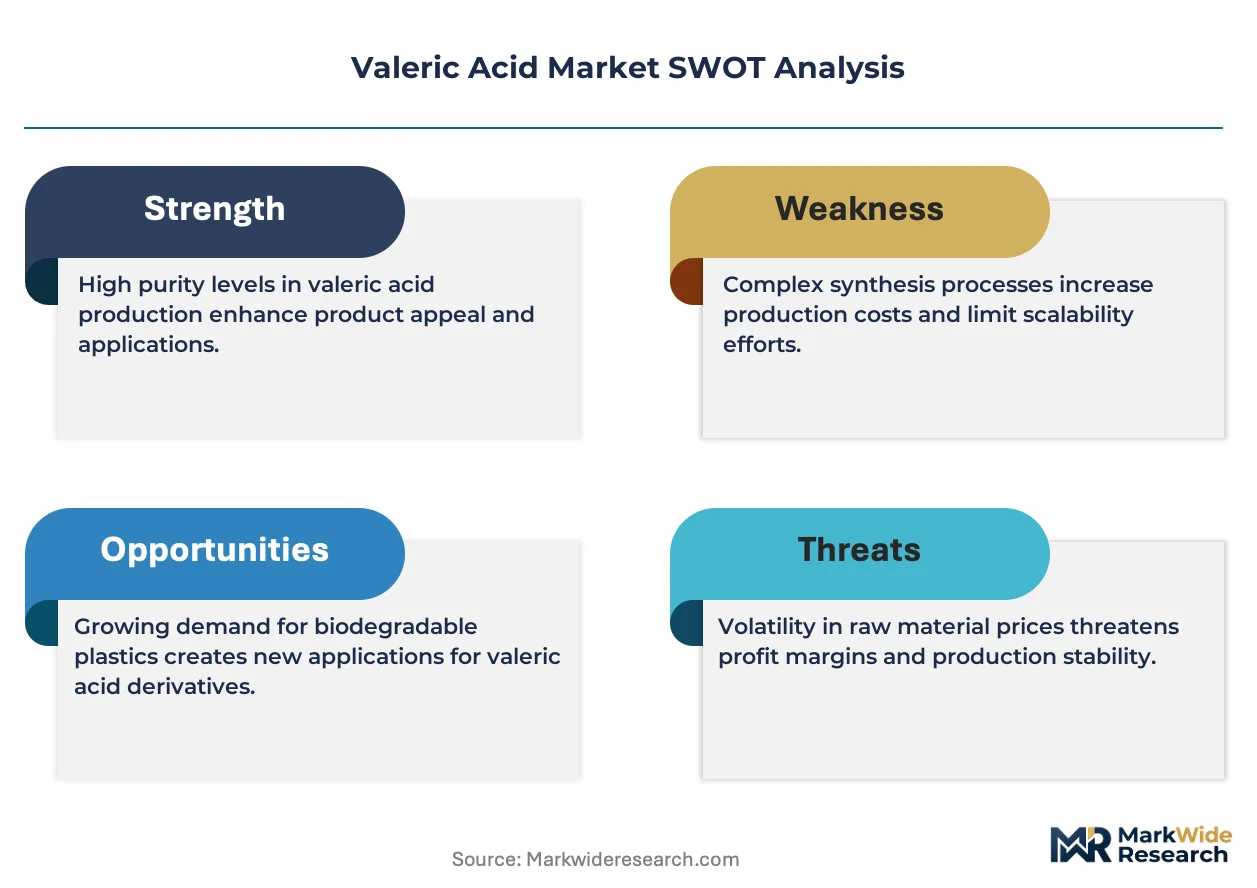
Valeric acid, also known as pentanoic acid, is a straight-chain saturated carboxylic acid with the molecular formula C₅H₁₀O₂, typically produced via oxo-synthesis from 1-butene or through oxidation of n-valeraldehyde, and serves primarily as a chemical intermediate for esters, plasticizers, and pharmaceutical active ingredients. Fragrance applications dominate value capture due to premium pricing on valerate esters used in fine perfumery and personal care formulations. Pharmaceutical end-use represents the fastest-expanding demand pool as CDMOs adopt valeric acid for prodrug synthesis and controlled-release formulations. The solvents segment remains mature, with volume growth tethered to coatings industry cyclicality rather than structural expansion.
EMA guidelines on residual solvents in APIs elevate purity requirements for pharmaceutical-grade valeric acid across European manufacturing. EPA regulations under the Toxic Substances Control Act govern import thresholds and reporting obligations for U.S.-based processors. BIS certification requirements in India constrain market access for uncertified producers of food-grade valerate salts. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with jurisdiction-specific compliance tiers.
Market Dynamics
The valeric acid market pivots on REACH compliance tightening purity specifications for cosmetic-grade imports into Europe, forcing producers to retool purification trains or exit the region entirely.
Growth Catalysts
- Pharmaceutical CDMO expansion:Contract manufacturers in Germany and Switzerland are scaling prodrug synthesis capacity, pulling high-purity pentanoic acid through qualified supplier networks.
- EMA residual solvent guidelines:Elevated purity mandates for API-grade material are compressing the qualified supplier pool and concentrating volume with certified producers.
- 1-Butene oxo-synthesis optimization:Catalyst efficiency gains at integrated petrochemical sites are lowering unit production costs for C5 carboxylic acid streams.
Market Restraints
- Feedstock volatility:Naphtha and propylene price swings transmit directly into C4/C5 aldehyde input costs, squeezing margin stability for non-integrated processors.
- German supply concentration:OXEA GmbH's dominance of European oxo-alcohol capacity creates single-source vulnerability for derivative valeric acid supply.
- Isobutyric acid substitution:Fragrance formulators in fine perfumery are partially substituting valerate esters with isobutyrate alternatives where odor profiles permit.
Strategic Opportunities
- India BIS certification gap:Domestic food-grade valerate salt production remains underdeveloped, creating first-mover advantage for certified entrants.
- Bio-based pentanoic acid routes:Fermentation-derived C5 acids from lignocellulosic feedstocks are qualifying for EU Green Deal procurement preferences in fragrance applications.
- Direct pharmaceutical distributor channels:Bypassing traditional chemical distributors to serve CDMOs through qualified direct supply agreements captures margin and locks volume.
Industry Challenges
- Pharmaceutical-grade certification timelines:EMA and FDA qualification protocols for new valeric acid suppliers extend 18-24 months, freezing out speculative entrants.
- Specialized oxidation reactor capex:Air-oxidation of n-valeraldehyde to acid requires corrosion-resistant alloy construction that multiplies capital intensity versus esterification assets.
- Cross-jurisdiction regulatory divergence:Misalignment between EPA TSCA reporting thresholds and REACH registration requirements fragments compliance resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Valeric Acid Market |
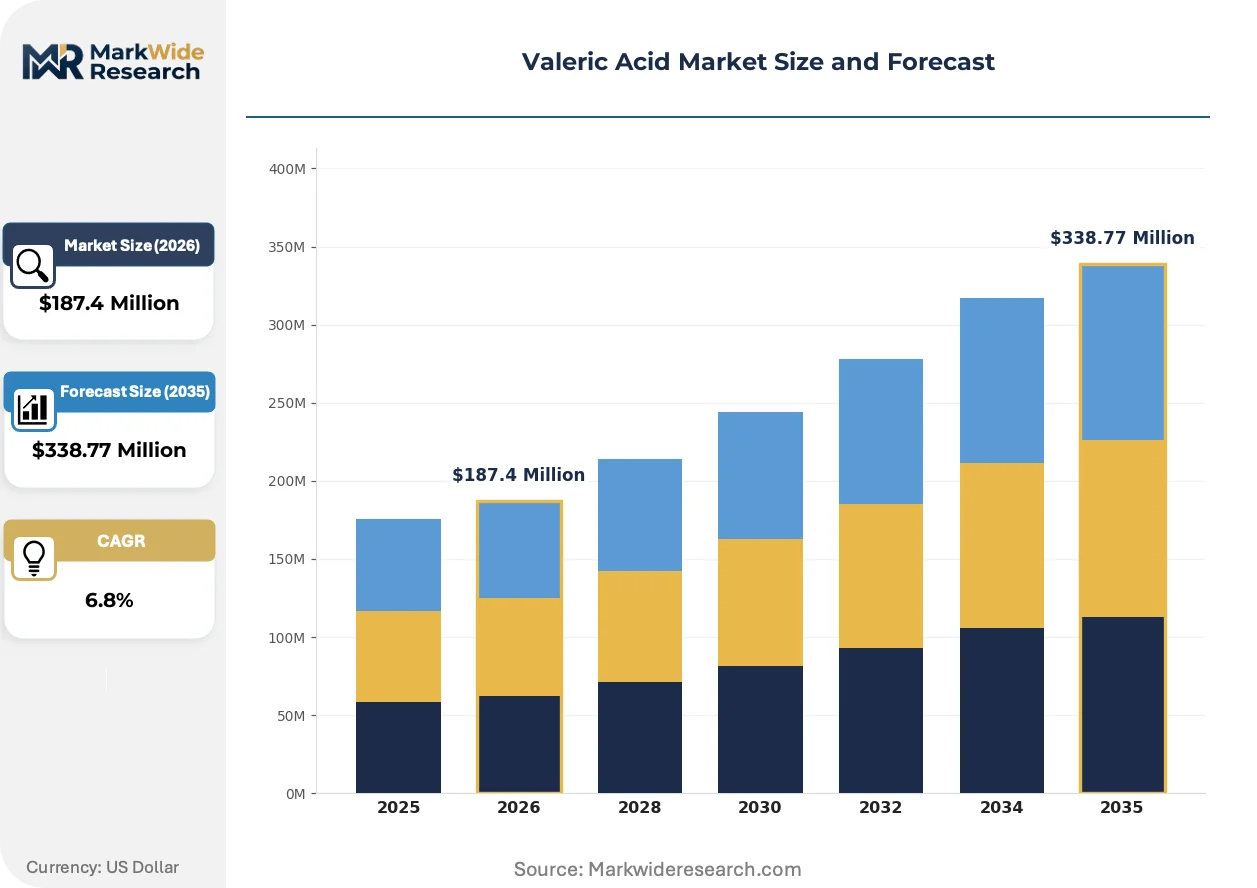
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Valeric Acid, Valerate Esters, salts, Valeroyl Chloride Application: Solvents, Plasticizers, Additives, Fragrance End User: Cosmetics, Pharmaceuticals, Food & Beverage, Agriculture Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | OXEA GmbH, Evonik Industries AG, Perstorp Holding AB, Merck KGaA, Solvay S.A., BASF SE, Eastman Chemical Company, Celanese Corporation, Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Valeric Acid Market Emerging Trajectories
Process intensification and regulatory stringency are compressing the viable technology set for valeric acid production, favoring integrated petrochemical operators over standalone specialty chemical producers.
Membrane-based reactive separation systems for oxo-synthesis product recovery are rendering obsolete traditional distillation-heavy purification trains. Pharmaceutical-grade producers in Germany and Switzerland are piloting these units to cut energy intensity. The technology is compressing capital requirements for high-purity acid production while tightening the barrier between integrated and non-integrated competitors.
REACH authorization requirements for Substances of Very High Concern are extending to residual catalyst metals in cosmetic-grade valeric acid. This forces importers into third-country supplier audits and certificate-of-analysis verification protocols. Fragrance compounders in France and Italy are responding by consolidating purchases with REACH-registered European producers.
CDMO procurement departments are compressing supplier qualification cycles from 24 months to 12 months through risk-based auditing frameworks. Traditional chemical distributors serving pharmaceutical end-uses are losing share to direct manufacturer relationships. The shift is most visible in Germany and Switzerland, where integrated oxo-alcohol producers are capturing volume through qualified direct supply agreements.
Valeric Acid Market Segmentation
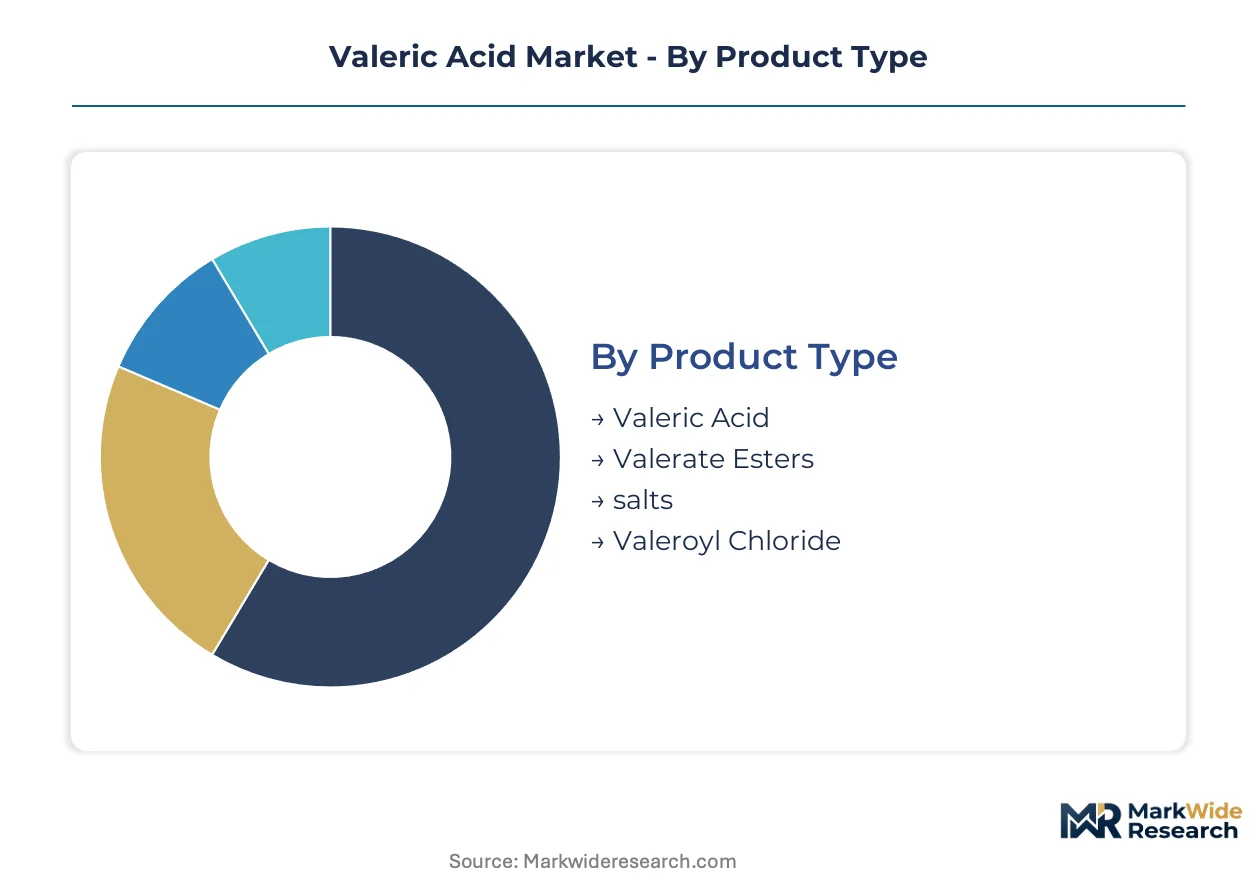
Valeric acid market segmentation reveals how purification grades and derivative forms map to divergent margin profiles across pharmaceutical, fragrance, and industrial end-uses. Structural differences between commodity acid streams and high-purity esters create distinct competitive arenas with separate qualification barriers.
Product Type:
Mature commodity acids dominate tonnage while specialty derivatives capture value expansion through functional performance differentiation.
- Valeric Acid:Straight-chain C₅ carboxylic acid produced via oxo-synthesis or aldehyde oxidation, serving as the foundational feedstock for downstream derivative production. Demand concentrates in Germany at OXEA GmbH's integrated Ludwigshafen complex, where backward integration into petrochemical feedstocks insulates margin volatility from naphtha price swings.
- Valerate Esters:Esterified derivatives including ethyl, isoamyl, and phenethyl valerate formulations prized for odor stability in fine perfumery. French and Italian fragrance compounders in Grasse and Milan drive specification tightening, pulling material through REACH-registered supplier networks with certificate-of-analysis verification for residual catalyst metals.
- Salts:Sodium and potassium valerate forms used as food-grade preservatives and feed additives, constrained by BIS certification requirements in India that limit import access for uncertified producers.
- Valeroyl Chloride:Acid chloride derivative enabling amidation reactions for pharmaceutical prodrug synthesis, with Swiss and German CDMOs qualifying suppliers through 18-24 month EMA protocols.
Valeric acid retains volume leadership; valerate esters hold the steepest expansion curve.
Application:
Cost tier stratification separates mature industrial solvents from premium fragrance formulations with tenfold pricing differentials.
- Solvents:Mature application segment for coatings and resin formulations, with volume growth tethered to construction industry cyclicality rather than structural expansion. German coatings producers at BASF SE's Ludwigshafen site consume bulk acid streams for polyester resin manufacturing.
- Plasticizers:C₅ ester plasticizers for PVC and cellulose derivatives, facing substitution pressure from bio-based alternatives in EU Green Deal procurement frameworks.
- Additives:Lubricant and fuel additive applications leveraging valeric acid's corrosion inhibition properties, with demand clustering in US Gulf Coast petrochemical corridors under EPA TSCA reporting thresholds.
- Fragrance:Premium valerate esters for fine perfumery and personal care, where odor profile specificity commands pricing multiples over industrial grades. French compounders in Grasse consolidate purchases with REACH-registered European producers to satisfy ECHA authorization requirements for Substances of Very High Concern.
Solvents retain volume leadership; fragrance holds the steepest expansion curve.
End User:
Customer type segmentation distinguishes specification-intensive pharmaceutical buyers from price-sensitive agricultural procurement.
- Cosmetics:Fragrance and personal care formulators requiring REACH-compliant cosmetic-grade material with documented purity certificates. Italian and French compounders drive supplier consolidation toward registered European producers.
- Pharmaceuticals:CDMOs and API manufacturers demanding EMA-qualified pharmaceutical-grade acid for prodrug synthesis and controlled-release formulations. Swiss and German contract manufacturers compress qualification cycles from 24 months to 12 months through risk-based auditing frameworks.
- Food & Beverage:Food-grade valerate salt applications constrained by BIS certification requirements in India, where domestic production remains underdeveloped and import access is restricted.
- Agriculture:Feed additive and crop protection intermediate uses, with procurement patterns tracking commodity chemical pricing rather than specification premiums.
Cosmetics retain volume leadership; pharmaceuticals hold the steepest expansion curve.
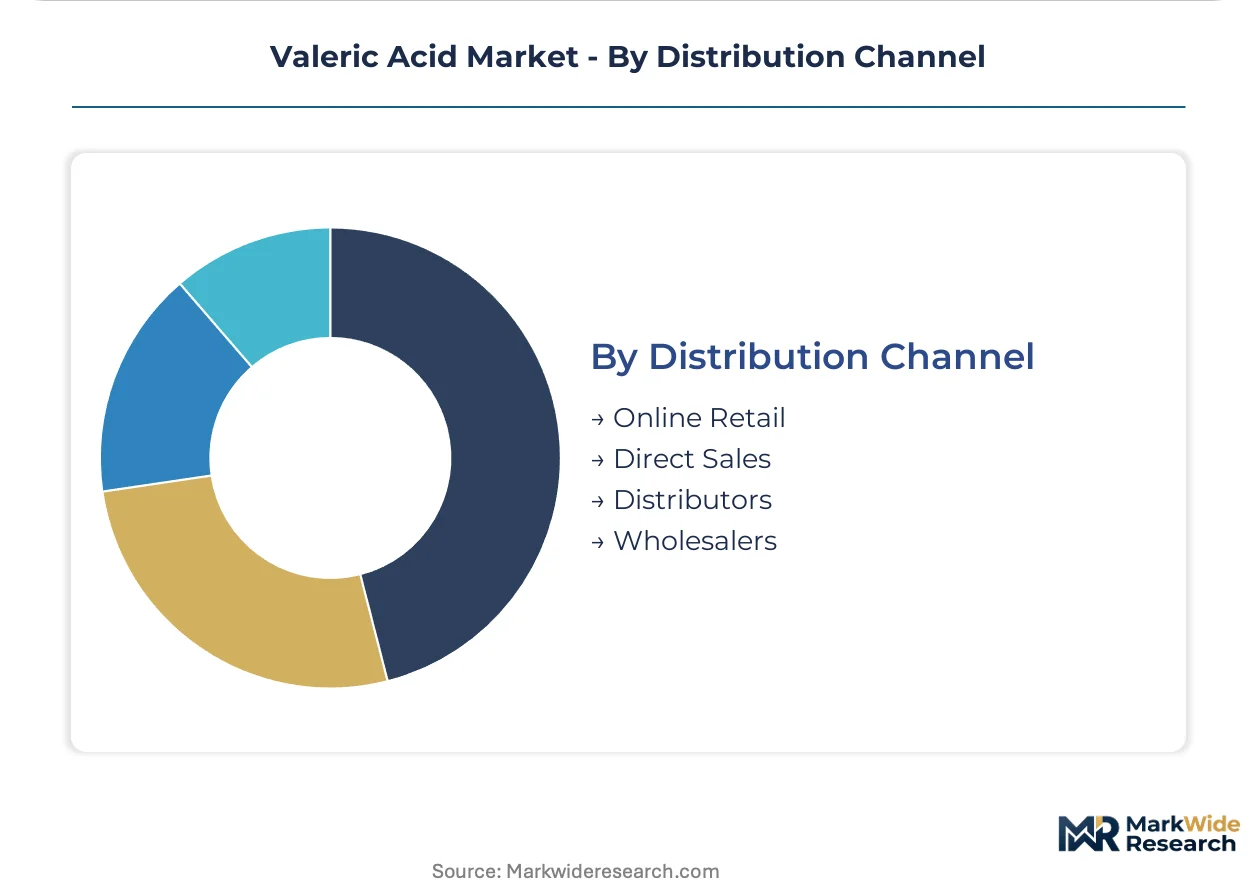
Distribution Channel:
Supply concentration patterns favor direct manufacturer relationships in pharmaceutical channels while commodity grades flow through traditional distributor networks.
- Direct Sales:Qualified supply agreements between integrated oxo-alcohol producers and pharmaceutical CDMOs, bypassing traditional chemical distributors to capture margin and lock volume. German and Swiss producers dominate this channel through EMA-registered direct relationships.
- Distributors:Traditional chemical distribution for industrial-grade acid and ester derivatives, with regional players holding inventory positions in coatings and plastics hubs.
- Online Retail:Emerging channel for laboratory-scale and specialty grade quantities, serving R&D procurement in pharmaceutical and fragrance development.
- Wholesalers:Bulk volume aggregation for agricultural and industrial additive applications, with pricing indexed to petrochemical feedstock movements.
Distributors retain volume leadership; direct sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH authorization requirements anchor European regulatory stringency, with ECHA oversight cascading into purity specifications for cosmetic-grade imports. German oxo-alcohol capacity concentrates supply-side leverage across downstream derivative markets.
Germany
Pharmaceutical CDMOs in Ludwigshafen and Leverkusen pull high-purity pentanoic acid for prodrug synthesis. EMA residual solvent guidelines compress the qualified supplier pool to REACH-registered producers. OXEA GmbH's integrated petrochemical complex anchors European C5 carboxylic acid supply through backward integration into naphtha feedstocks.
China
Jiangsu and Shandong provinces are adding domestic oxo-synthesis capacity to narrow import dependence for C5 acid streams. MIIT catalyst efficiency standards accelerate technology upgrades at integrated petrochemical sites. Yangtze River Delta chemical clusters are qualifying fermentation-derived pentanoic acid for EU Green Deal procurement preferences.
United States
Gulf Coast petrochemical corridors consume bulk acid streams for lubricant and fuel additive applications. EPA TSCA reporting thresholds govern import volumes and disclosure obligations for C5 carboxylic acid processors. Texas and Louisiana integrated sites leverage shale-derived feedstock cost advantages for oxo-synthesis operations.
Switzerland
Swissmedic pharmaceutical-grade certification protocols extend supplier qualification timelines to 18-24 months for API-grade material. Basel and Zurich CDMOs are compressing audit cycles through risk-based frameworks to secure qualified pentanoic acid supply. Swiss contract manufacturers bypass traditional distributors for direct manufacturer relationships.
India
BIS certification requirements constrain market access for food-grade valerate salt imports, with domestic production remaining underdeveloped. CDSCO pharmaceutical regulations elevate documentation burdens for API-grade acid suppliers. Maharashtra and Gujarat chemical hubs are positioning for first-mover advantage in certified domestic valerate salt manufacturing.
Valeric Acid Market Vendor Landscape
Capability concentration sits with integrated petrochemical operators; scale advantage sits with diversified chemical conglomerates. The supplier base stratifies into three tiers: oxo-alcohol integrated producers commanding feedstock cost control, specialty ester houses capturing fragrance value premiums, and pharmaceutical-grade specialists managing EMA qualification protocols. Dominant competitive moves include backward integration into naphtha and propylene feedstocks, plus direct supply agreement formation with CDMO procurement departments.
Within the integrated producer tier, OXEA GmbH and BASF SE exemplify petrochemical-backward operations with captive C4/C5 aldehyde supply chains. Evonik Industries AG occupies a position among pharmaceutical-grade specialists, representing the qualification-intensive segment serving Swiss and German CDMO networks. Perstorp Holding AB anchors bio-based pentanoic acid development, sitting within the sustainability-driven fragrance ingredient vector targeting EU Green Deal procurement channels.
| Leading Market Players |
|---|
| OXEA GmbH |
| Evonik Industries AG |
| Perstorp Holding AB |
| Merck KGaA |
| Solvay S.A. |
| BASF SE |
| Eastman Chemical Company |
| Celanese Corporation |
| Dow Chemical Company |
| Others |
Supply Flow & Price Mechanics
Rhine-Main corridor freight rates transmit petrochemical feedstock cost volatility directly into C5 acid landed costs, amplifying price spreads between integrated German producers and import-dependent compounders while forcing downstream buyers into long-term offtake negotiations to hedge margin erosion.
Pricing Analysis
Geographic price spreads between Ludwigshafen integrated supply and Asian import parity exceed transport cost differentials alone, reflecting REACH certification premiums. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade levels segments buyer pools by qualification burden. Cost compression in industrial-grade streams is intensifying because naphtha derivative oversupply is eroding spot market premiums. Agricultural feed additive buyers exhibit highest price sensitivity; Swiss CDMOs demonstrate lowest sensitivity due to prodrug synthesis value capture.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for cosmetic-grade valerate ester importers. Production gravity centers on Germany, China, and the United States, with Jiangsu province capacity additions narrowing Chinese import dependence. Raw material draws from naphtha cracking, propylene dehydrogenation, and 1-butene oxo-synthesis streams. Single-source vulnerability concentrates at OXEA GmbH's Ludwigshafen complex. Distribution runs through qualified direct supply agreements for pharmaceutical grades and traditional chemical distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is positioned for cyclical recovery as coatings industry destocking exhausts inventory overhang and restocking demand reactivates solvent-grade offtake.
For Market Incumbents: Build regulatory moats through EMA prequalification investment to compress supplier audit cycles for CDMO procurement departments. Deepen backward integration into naphtha feedstocks at Ludwigshafen-scale complexes to insulate margin volatility from propylene price swings. Defend against isobutyric acid substitution in fragrance applications by tightening odor profile specifications with Grasse compounders.
For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified food-grade valerate salt segment where domestic production gaps constrain supply. Target Maharashtra and Gujarat chemical hubs with fermentation-derived pentanoic acid routes qualifying for EU Green Deal procurement preferences. Pursue direct distributor bypass models to capture margin lost to traditional chemical distribution layers.
For Investors and Strategic Acquirers: Pharmaceutical-grade specialists with Swissmedic qualification protocols represent the most defensible acquisition archetype in this market. Long-term viability hinges on CDMO procurement consolidation toward qualified direct supply relationships. Monitor EMA residual solvent guideline enforcement intensity as the inflection signal for supplier pool compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Captive naphtha supply at Ludwigshafen insulates OXEA GmbH from propylene volatility. |
| EMA Prequalification Investment | Compresses 24-month supplier audit cycles to 12 months for German CDMO networks. |
| Fermentation-Derived Pentanoic Acid Scale-Up | Qualifies Perstorp Holding AB for EU Green Deal fragrance procurement preferences. |
| Direct Supply Agreement Formation | Bypasses traditional distributors to capture margin in Swiss pharmaceutical channels. |
| Membrane-Based Reactive Separation Deployment | Cuts energy intensity for high-purity acid production at German oxo-alcohol sites. |
Methodological Framework
Desk research of customs trade databases, ECHA registration filings, and SEC chemical segment disclosures preceded structured interviews with oxo-alcohol plant managers, fragrance compounder procurement leads, pharmaceutical CDMO technical directors, and specialty chemical distribution channel partners. Bottom-up volume modeling triangulated against top-down petrochemical derivative demand analysis validated segmentation splits across grade tiers and end-use industries.
Assumptions held fixed include REACH authorization timelines and EMA residual solvent guideline enforcement intensity; variables stress-tested included naphtha price band movements and CDMO outsourcing rate shifts. The analytical framework modeled pharmaceutical-grade, cosmetic-grade, and industrial-grade tiers across solvents, plasticizers, additives, and fragrance applications. CAGRs derived from segment-level volume build-ups incorporating oxo-synthesis capacity expansion schedules and downstream derivative demand elasticity.
Stress conditions across naphtha price volatility, REACH enforcement intensity, and CDMO procurement consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with pharmaceutical qualification timelines and bio-based route cost parity representing specific revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
Global Hydroiodic Acid (Hydriodic Acid) Market
Bulk Chemicals
South America Lactic Acid Market
Bulk Chemicals
Ferrous Oxalate Market
Bulk Chemicals
Methyl Cyclohexane Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Nonprotein Nitrogen Market
Bulk Chemicals
North America Acetic Acid Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Sulfur Palletized Plant and Granulator Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
North America and Europe Palm Derivatives Market