
 Global Bulk Ferroalloys Market | 2026-2036
Global Bulk Ferroalloys Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bulk Ferroalloys Market Foresight
The capital-intensity divergence between integrated miners and merchant producers is reorganizing competitive tiers in bulk ferroalloys. ArcelorMittal leverages captive chromite and manganese mining to sustain margin stability across volatile alloy pricing cycles. China Minmetals Corporation anchors its position through state-backed resource diplomacy and long-term offtake agreements with African ore bodies. Ferroglobe PLC differentiates via European silicon-based alloy production serving specialized foundry and chemical applications.
Bulk ferroalloys are iron-based master alloys containing high percentages of reactive elements such as manganese, silicon, chromium, or vanadium, typically produced through carbothermic reduction in submerged arc furnaces at temperatures exceeding 1,500°C. These alloys function as essential deoxidizers, desulfurizers, and alloying agents that impart tensile strength, corrosion resistance, and heat tolerance to finished steel and cast products. Ferrochrome commands the largest value share among product types due to its irreplaceable role in stainless steel metallurgy, while silicomanganese experiences the fastest trajectory as mini-mill operators substitute it for ferromanganese in cost-optimized charge mixes. Steelmaking absorbs the dominant volume of bulk ferroalloy output, though specialty metal producers generate disproportionate margins through precision-grade ferrovanadium and ferromolybdenum for aerospace and energy applications.
The European Commission's Carbon Border Adjustment Mechanism and REACH chemical compliance protocols are reshaping import competitiveness for Chinese and Indian alloy exporters into EU steel mills. India's Bureau of Indian Standards mandates quality certification for ferroalloys used in infrastructure-grade steel, tightening market access for uncertified regional suppliers. China's Ministry of Ecology and Environment enforces dual carbon goals that constrain coal-powered smelter expansion, redirecting investment toward hydropower-dependent ferroalloy capacity in Yunnan and Sichuan provinces. Stakeholders must monitor how carbon accounting rules and ore export licensing shifts in South Africa and Gabon redefine raw material security strategies.
Market Dynamics
Carbon border adjustments are forcing a structural reconfiguration of ferroalloy trade flows, with EU steel mills accelerating qualification of low-carbon alloy suppliers ahead of full Carbon Border Adjustment Mechanism enforcement.
Growth Catalysts
- Electric arc furnace expansion:Indian steelmakers are commissioning new EAF capacity that consumes silicomanganese at higher charge ratios than traditional blast furnace routes.
- REACH chemical compliance:European stainless steel producers are consolidating supplier lists to pre-qualified alloy sources that demonstrate full hazardous substance traceability.
- Hydropower-smelter coupling:Chinese producers in Yunnan province are relocating carbothermic reduction capacity to access renewable electricity, cutting embedded carbon in export-bound ferrochrome.
Market Restraints
- Chromite ore concentration:South African and Kazakh ore bodies supply over seventy percent of global ferrochrome feedstock, creating single-source vulnerability.
- Energy cost volatility:Submerged arc furnace operations face margin compression from natural gas and electricity price spikes in European smelting regions.
- Ferromanganese substitution:Mini-mill operators are replacing high-carbon ferromanganese with silicomanganese in cost-optimized charge mixes, eroding traditional product premiums.
Strategic Opportunities
- Vietnam industrial corridor:New stainless steel cold-rolling capacity in Ha Tinh province is generating uncontracted demand for precision-grade ferrochrome.
- Dual carbon goals alignment:China's Ministry of Ecology and Environment incentives are rewarding hydropower-dependent smelters with preferential export licensing.
- Digital alloy certification:Blockchain-based provenance tracking is enabling premium pricing for carbon-accounted ferroalloys in German automotive supply chains.
Industry Challenges
- Refractory engineering shortage:Submerged arc furnace rebuild cycles require specialized ceramic expertise that has not scaled with capacity expansion.
- Carbon accounting verification:Third-party lifecycle assessment protocols for Scope 3 emissions lack standardization across Indian and Chinese certification bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bulk Ferroalloys Market |
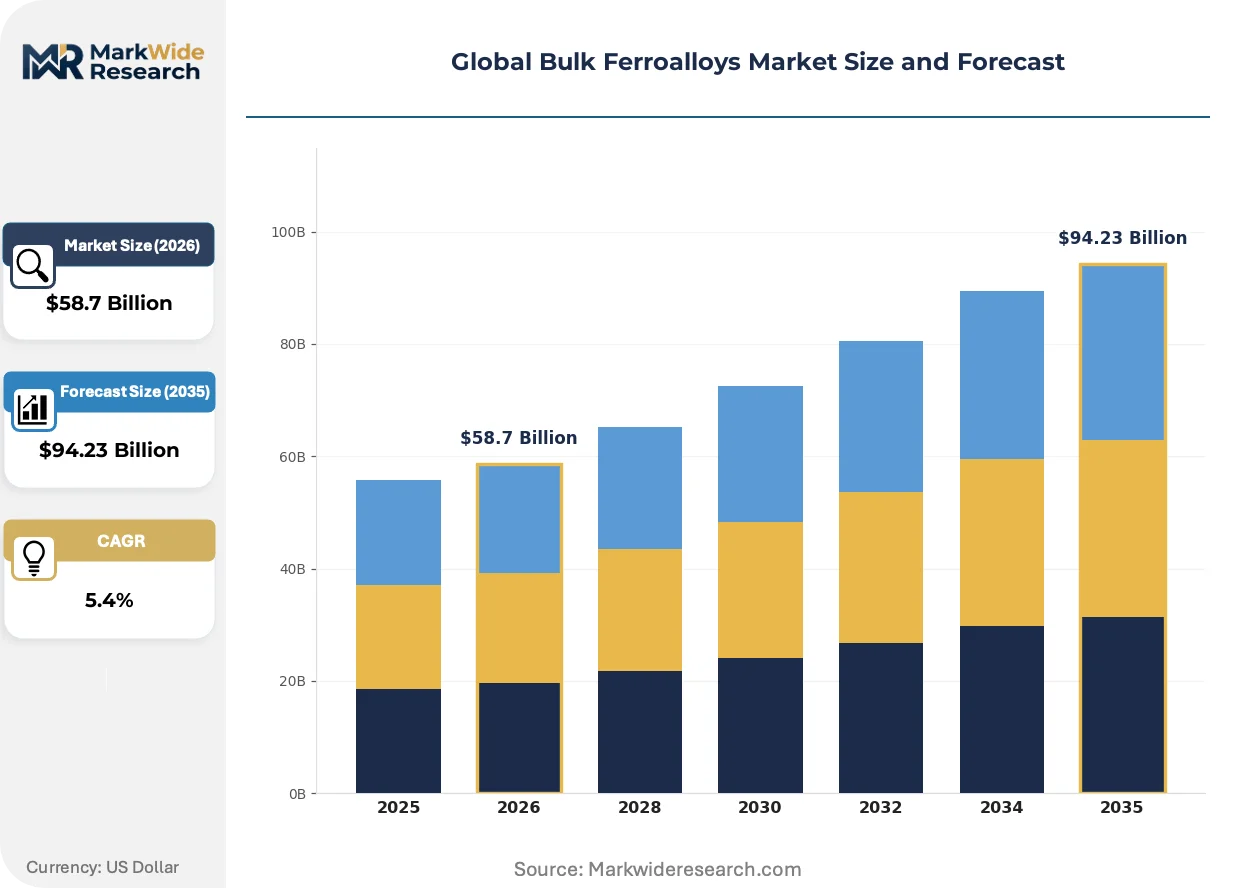
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $94.23 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferromanganese, Ferrosilicon, Ferrochrome, Ferromolybdenum, Ferrovanadium, Silicomanganese Application: Steelmaking, Foundry Alloys, Welding Electrodes, Cast Irons, High-Temperature Alloys, Chemical Industry End User: Steel Mills, Foundries, Fabricators, Welding Industries, Chemical Manufacturers, Specialty Metal Producers Distribution Channel: Direct Sales, Distributors, Online Marketplaces, Bulk Suppliers, Industrial Traders, Exporters |
| Companies Covered | ArcelorMittal, Tata Steel, China Minmetals Corporation, Gulf Ferroalloys Company, OM Holdings LTD, Pertama Ferroalloys, Nikopol Ferroalloy Plant, Brahm Group, Ferroglobe PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bulk Ferroalloys Market Shifts & Advancements
Process intensification and regulatory compliance automation are redefining how ferroalloy producers compete on cost structure and market access simultaneously.
Plasma-assisted smelting technology is fragmenting the traditional submerged arc furnace paradigm by enabling lower-temperature reduction of manganese oxide ores. Pilot installations in Nordic mining districts are demonstrating thirty percent energy savings against conventional carbothermic routes. The technology is compressing capital requirements for mid-scale alloy producers entering the merchant market.
The European Union's Carbon Border Adjustment Mechanism is imposing lifecycle emissions disclosure requirements on all ferroalloy imports from 2026. Chinese exporters are retrofitting Yunnan smelters with hydropower interconnections to preserve EU market access. Indian producers face accelerated BIS quality certification timelines to maintain competitiveness in European stainless steel supply chains.
Long-term offtake contracting is displacing spot market purchasing among major stainless steel groups seeking raw material security. ArcelorMittal and POSCO are locking in five-year ferrochrome supply agreements with embedded carbon intensity clauses. This concentration of procurement decision-making is visible across European and East Asian steelmaking clusters.
Global Bulk Ferroalloys Market Segmentation
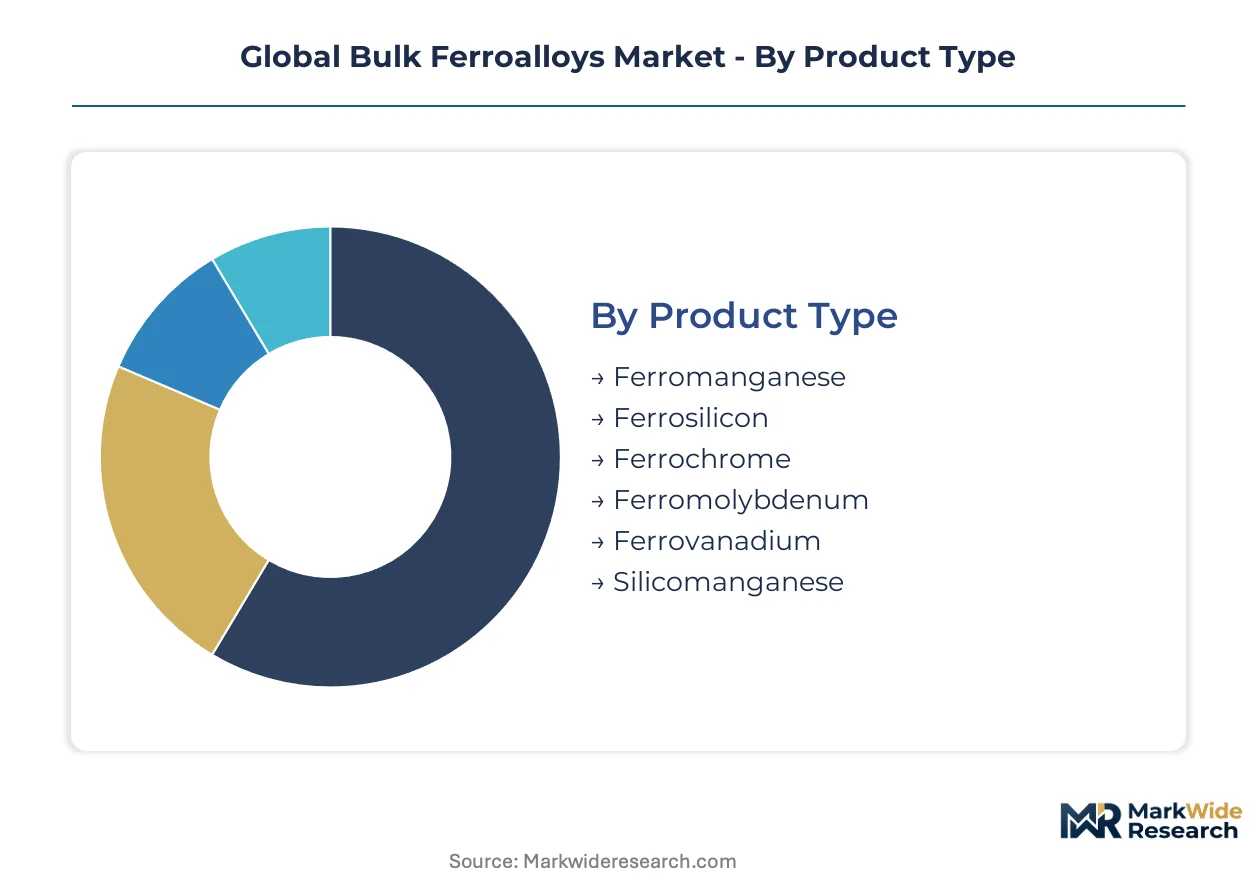
Product substitution dynamics and end-use specification requirements fragment competitive positioning across bulk ferroalloy categories. Understanding where silicomanganese displaces ferromanganese, or where precision-grade alloys command premium positioning, shapes procurement strategy and capacity investment decisions.
Product Type:
Silicomanganese substitution pressure is reshaping volume leadership within the manganese alloy family, while chromium-based products face ore concentration risks that limit supplier mobility.
- Ferrochrome:Iron-chromium master alloy containing 50-70% chromium content, produced exclusively through carbothermic reduction of chromite ore. Stainless steel mills in Indonesia and Vietnam are locking in long-term offtake agreements as new cold-rolling capacity accelerates. Ferrochrome retains volume leadership; ferrovanadium holds the steepest expansion curve.
- Silicomanganese:Dual-purpose deoxidizer and alloying agent combining 65-68% manganese with 18-20% silicon, enabling single-addition charge optimization. Indian electric arc furnace operators are substituting silicomanganese for ferromanganese at ratios exceeding 60% in cost-optimized melts.
- Ferromanganese:High-carbon variant faces demand erosion as mini-mill operators favor silicomanganese's dual-function economics; medium and low-carbon grades retain specialty positioning for ultra-low-carbon steel grades.
- Ferrosilicon:Silicon content ranging 45-90% serves foundry inoculation and steel deoxidation; Chinese hydropower-smelter coupling in Yunnan province is cutting embedded carbon for EU-bound exports.
- Ferromolybdenum:Molybdenum addition agent for high-strength low-alloy steels and stainless grades; aerospace and energy sector specifications drive precision-grade premiums.
- Ferrovanadium:Vanadium micro-alloying for high-strength rebar and structural steels; demand concentrates in infrastructure-grade specifications requiring seismic resistance.
Ferrochrome commands the largest revenue base; silicomanganese is climbing the fastest as EAF penetration accelerates.
Application:
Cost tier differentiation separates commodity steelmaking absorption from specialty alloy margins, with foundry and chemical applications generating disproportionate returns per ton.
- Steelmaking:Primary deoxidation and alloying function consumes the dominant volume of ferromanganese, ferrochrome, and silicomanganese output. European carbon border adjustments are forcing lifecycle emissions disclosure from Chinese and Indian suppliers.
- Foundry Alloys:Precision inoculation and nodularization requirements for ductile iron production favor high-purity ferrosilicon and specialized ferromagnesium variants.
- Welding Electrodes:Coating formulations require controlled manganese and silicon transfer; flux-cored wire expansion in Southeast Asian fabrication clusters is concentrating demand.
- Cast Irons:Grey iron and compacted graphite iron specifications drive ferrosilicon consumption patterns tied to automotive brake disc and engine block programs.
- High-Temperature Alloys:Nickel-based superalloy production for aerospace turbines and industrial gas turbines requires ferromolybdenum and ferrovanadium with trace-element controls.
- Chemical Industry:Ferrosilicon serves as feedstock for silicones and fumed silica production; Ferroglobe PLC's European positioning captures this specialized demand stream.
Steelmaking absorbs the highest tonnage; high-temperature alloys deliver the steepest margin expansion.
End User:
Customer type concentration determines contract structure, with integrated steel groups favoring long-term offtake and merchant mini-mills driving spot price volatility.
- Steel Mills:Integrated producers and electric arc furnace operators represent the foundational demand base, with procurement patterns diverging between captive ore strategies and merchant market exposure.
- Foundries:Ductile iron and steel casting operations require just-in-time ferrosilicon delivery with precise inoculation timing; regional distributor networks dominate supply relationships.
- Fabricators:Structural steel and pressure vessel manufacturers source alloy additions through service centers rather than direct mill relationships.
- Welding Industries:Electrode manufacturers and flux-cored wire producers specify ferromanganese and ferrosilicon with tight particle size distribution for coating uniformity.
- Chemical Manufacturers:Silicones and fumed silica producers require metallurgical-grade ferrosilicon with impurity profiles distinct from steelmaking specifications.
- Specialty Metal Producers:Titanium alloy and superalloy smelters generate premium demand for low-oxygen ferrovanadium and ferromolybdenum with aerospace certification.
Steel Mills anchor procurement volume; Specialty Metal Producers extract the highest value per kilogram.
Distribution Channel:
Supply chain configuration separates bulk commodity flows from certified precision-grade channels, with carbon accounting requirements fragmenting traditional trader relationships.
- Direct Sales:Long-term offtake agreements between alloy smelters and stainless steel groups now embed carbon intensity clauses and Scope 3 disclosure requirements.
- Distributors:Regional stockholding networks serve foundry and fabrication customers requiring smaller lot sizes and technical application support.
- Online Marketplaces:Digital platforms are emerging for standardized ferrosilicon and ferromanganese grades, though high-value alloys remain relationship-contracted.
- Bulk Suppliers:Vessel-charter and rail-car logistics specialists manage port-to-plant flows for major steelmaking complexes in India and Southeast Asia.
- Industrial Traders:Merchants with blending and screening capabilities add value through specification tailoring, though carbon border compliance is raising entry barriers.
- Exporters:Chinese and South African smelters maintain dedicated export desks managing EU CBAM registration and Indian BIS certification pathways.
Direct Sales concentrate the largest contract value; Online Marketplaces are gaining share fastest among standard grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Southeast Asia exhibit the highest price elasticity as merchant mini-mills optimize charge mixes amid volatile ore costs. European stainless steel producers show lower elasticity, prioritizing carbon-accounted supply security over spot savings.
China
Domestic steelmakers consume over half of global ferrochrome output for stainless production. The Ministry of Ecology and Environment enforces dual carbon goals that constrain coal-powered smelter expansion. Hydropower-dependent capacity in Yunnan province is cutting embedded carbon for EU-bound exports.
India
New electric arc furnace capacity in Odisha and Chhattisgarh is driving silicomanganese demand at substitution ratios exceeding 60%. The Bureau of Indian Standards mandates quality certification for infrastructure-grade steel ferroalloys. Raipur-based merchant producers are consolidating to meet BIS timelines for European market access.
South Africa
Integrated miners supply over seventy percent of global chromite ore feedstock, creating strategic leverage. Export licensing shifts under the Department of Mineral Resources and Energy are tightening raw material availability. Rustenburg smelting complexes face power reliability constraints from Eskom grid instability.
Germany
Automotive and specialty steel mills anchor premium-grade ferrovanadium and ferromolybdenum consumption. The Carbon Border Adjustment Mechanism requires lifecycle emissions disclosure from 2026, filtering supplier qualification. Duisburg-Ruhr steelmaking clusters are pre-qualifying low-carbon alloy sources ahead of full CBAM enforcement.
Vietnam
New stainless steel cold-rolling capacity in Ha Tinh province is generating uncontracted demand for precision-grade ferrochrome. The Ministry of Industry and Trade monitors ore import dependencies for smelter feedstock security. Formosa Ha Tinh Steel is expanding procurement teams to lock in five-year ferrochrome supply agreements.
Global Bulk Ferroalloys Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated miners commanding ore security and merchant producers competing on furnace efficiency. The market structures around three tiers: captive producers with chromite and manganese mining assets, hydropower-coupled smelters optimizing carbon intensity, and regional mini-mill suppliers serving spot demand. Strategic moves concentrate on long-term offtake contracting with embedded carbon clauses and relocation of carbothermic capacity to renewable electricity zones.
Within the integrated mining tier, ArcelorMittal and China Minmetals Corporation occupy positions defined by captive ore access and state-backed resource diplomacy respectively. Ferroglobe PLC exemplifies the specialized European silicon-based alloy producer serving foundry and chemical applications outside commodity steelmaking channels. These three anchors illustrate how competitive positioning fragments across ore control, energy sourcing, and end-use specialization.
| Leading Market Players |
|---|
| ArcelorMittal |
| Tata Steel |
| China Minmetals Corporation |
| Gulf Ferroalloys Company |
| OM Holdings LTD |
| Pertama Ferroalloys |
| Nikopol Ferroalloy Plant |
| Brahm Group |
| Ferroglobe PLC |
| Others |
Supply & Pricing Matrix
The EU Carbon Border Adjustment Mechanism gates both supply qualification and price differentiation simultaneously, filtering Chinese and Indian exporters into premium carbon-accounted tiers while relegating coal-powered smelters to distressed spot markets. Stainless steel mills in Duisburg and automotive supply chains in Stuttgart now pay measurable premiums for blockchain-verified low-carbon ferrochrome, compressing margins for uncertified merchant producers.
Pricing Analysis
Long-term offtake contracts with embedded carbon intensity clauses now drive lifetime value for integrated alloy producers. Pricing stratifies across carbon-certified premium, standard BIS-compliant, and uncertified economy tiers. Cost compression in the economy tier is intensifying because South African chromite export licensing tightens feedstock availability. Merchant mini-mills in Raipur and Jakarta exhibit the highest price sensitivity, while German automotive steel groups prioritize supply security over spot savings.
Supply Chain Analysis
Strait of Malacca transit underwrites the majority of chromite ore movements from South African ports to Chinese smelters in Yunnan province. Supply concentrates in South Africa, Kazakhstan, and India for ore extraction, with Chinese hydropower-coupled smelters dominating refined ferrochrome output. Raw material dependencies center on chromite lump ore, metallurgical coke, and manganese dioxide concentrate. Single-source vulnerability in South African ore bodies exposes the chain to Eskom grid instability and export licensing shifts. Distribution runs through vessel-charter bulk suppliers and direct sales agreements with stainless steel complexes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting fragmentation creates niche positioning opportunities across three distinct supply tiers. Mini-mill operators in Southeast Asia are unbundling procurement decisions, creating entry points for specialized low-carbon alloy suppliers.
For Market Incumbents: Shield margin stability by deepening captive chromite mining in South Africa and accelerating BIS certification timelines for Indian infrastructure-grade supply. Hydropower-smelter coupling in Yunnan province represents the priority capacity relocation lever against EU CBAM exclusion. ArcelorMittal-style ore integration and Ferroglobe's European silicon specialization illustrate defensible positioning archetypes. For New Entrants and Emerging Players: Carbon-accounted ferrochrome certification services for mid-tier Chinese exporters present a service-layer gap where incumbents under-serve. Target Vietnamese stainless cold-rolling capacity in Ha Tinh province as the most penetrable demand cluster. A go-to-market angle anchored in blockchain-based Scope 3 disclosure tools for German automotive supply chains bypasses direct smelter competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across plasma-assisted smelting technology pilots in Nordic districts. Long-term viability across a five-to-ten year window favors acquisition targets with hydropower interconnections or captive ore positions in South Africa. The signal to watch as inflection indicator is preferential export licensing velocity from China's Ministry of Ecology and Environment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Chromite Mining | South African ore security insulates ArcelorMittal against Kazakh export licensing volatility. |
| Hydropower-Smelter Relocation | Yunnan province interconnections preserve Chinese producers' EU market access under CBAM. |
| Blockchain-Based Carbon Certification | Digital provenance tracking commands premium pricing in German automotive supply chains. |
| Long-Term Offtake Contracting | Five-year agreements with embedded carbon clauses lock in POSCO's raw material security. |
| Plasma-Assisted Smelting Scale-Up | Nordic pilot installations demonstrate thirty percent energy savings against carbothermic routes. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with alloy smelter operations directors, stainless steel procurement leads, and submerged arc furnace engineering specialists; and secondary validation against customs trade databases, SEC filings from listed ferroalloy producers, and Bureau of Indian Standards certification registries. Bottom-up capacity modeling and top-down steel consumption forecasts were triangulated to constrain volume estimates.
Across the analysis window, projections integrated product type segmentation by alloy chemistry, application tier by end-use specification, and regional production cluster by energy source. CAGRs were derived from steelmaking intensity ratios and EAF penetration curves. Forecast inputs included chromite ore export licensing trajectories from South Africa's Department of Mineral Resources and Energy and hydropower capacity expansion timelines in Yunnan province.
Underlying assumptions cover sustained EU CBAM enforcement, Indian BIS certification adoption, and Chinese dual carbon goal compliance, with deviation risk concentrated in Eskom grid reliability and South African ore export policy shifts. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms evolve in other jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Lysine Market
Bulk Chemicals
Mercaptan Scavenger Market
Bulk Chemicals
Barium Nitrate Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Copper (II) Carbonate Basic Market
Bulk Chemicals
Furfuryl Alcohol Market
Bulk Chemicals
Lignosulfonates Market
Bulk Chemicals
Battery Grade Lithium Chloride Market
Bulk Chemicals
Global Crude Sulfate Turpentine Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
4-Diisopropylbenzene Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Glucaric Acid Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Magnesium Lactate Market