
 Sorbic Acid Market | 2026-2036
Sorbic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Sorbic Acid Market Outlook
Pharmaceutical-grade purity specifications is redrawing competitive boundaries across the sorbic acid value chain. Daicel Corporation leverages its Japanese manufacturing base to supply high-purity grades for drug formulations. Shandong Hongda Group anchors global volume through integrated ketene-based production in China's Shandong province. Celanese Corporation competes on backward integration into acetic acid feedstock, securing cost positions in synthetic sorbate manufacturing.
Sorbic acid is a straight-chain unsaturated fatty acid with the formula CH₃(CH)₄COOH, produced industrially via ketene condensation with crotonaldehyde followed by oxidation, functioning primarily as a mold and yeast inhibitor in acidic food systems. Synthetic sorbates still occupy the dominant share of production volume given established cost curves, though natural sorbates derived from rowanberry extraction are gaining traction in premium personal care formulations. Food preservation remains the largest application segment by tonnage, while pharmaceutical-grade demand captures disproportionate margin pools due to stringent USP and EP monograph compliance requirements.
FDA food additive regulations under 21 CFR 182.3089 govern sorbic acid use levels in finished foods, while REACH registration requirements in Europe shape import access for non-EU manufacturers. EFSA re-evaluations of preservative safety profiles are tightening toxicological data requirements, forcing suppliers to invest in enhanced purity analytics and migration studies. Stakeholders must monitor regulatory divergence between FDA GRAS designations and EU additive authorization renewals when allocating R&D budgets across regional formulation strategies.
Market Dynamics
Ketene-based production concentration in Shandong province chemical clusters is compressing regional cost curves while EFSA additive re-evaluations force purity investment upgrades across European supply chains.
Growth Catalysts
- Clean-label reformulation mandates:FDA 21 CFR 182.3089 compliance requirements are driving packaged food manufacturers toward sorbate-based preservation systems as synthetic alternatives face consumer scrutiny.
- Pharmaceutical-grade specification expansion:USP and EP monograph standards for drug formulations are creating premium demand pools that command enhanced purity analytics and dedicated production lines.
- Rowanberry extraction advancement:Natural sorbate recovery technologies are opening premium personal care segments where botanical provenance commands formulation preference.
Market Restraints
- Crotonaldehyde feedstock volatility:Petrochemical derivative pricing swings directly transmit to ketene condensation economics, compressing margin stability for non-integrated producers.
- Shandong-Jiangsu supply concentration:Overreliance on eastern China chemical clusters creates geopolitical and logistics vulnerability for global formulation houses.
- Benzoate substitution pressure:Lower-cost benzoic acid derivatives retain share in high-pH applications where sorbic acid efficacy degrades.
Strategic Opportunities
- India FSSAI clean-label adoption:Emerging packaged food regulatory alignment with international preservative standards is opening formulation conversion opportunities in processed dairy and bakery segments.
- Bioprocess sorbate synthesis:Fermentation-derived production pathways are approaching pilot-scale viability for carbon-accounting-sensitive European personal care brands.
- Direct-to-formulator digital channels:Specialty chemical platforms are disintermediating traditional distributor networks for mid-volume pharmaceutical compounders seeking certified batches.
Industry Challenges
- Multi-jurisdiction compliance staffing:Simultaneous FDA GRAS maintenance, REACH registration renewal, and EFSA safety profile updates require dedicated regulatory affairs specialization scarce outside major chemical conglomerates.
- Pharmaceutical-grade capital intensity:USP-compliant production suites demand stainless-steel infrastructure and isolated packaging lines that extend depreciation timelines versus food-grade assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorbic Acid Market |
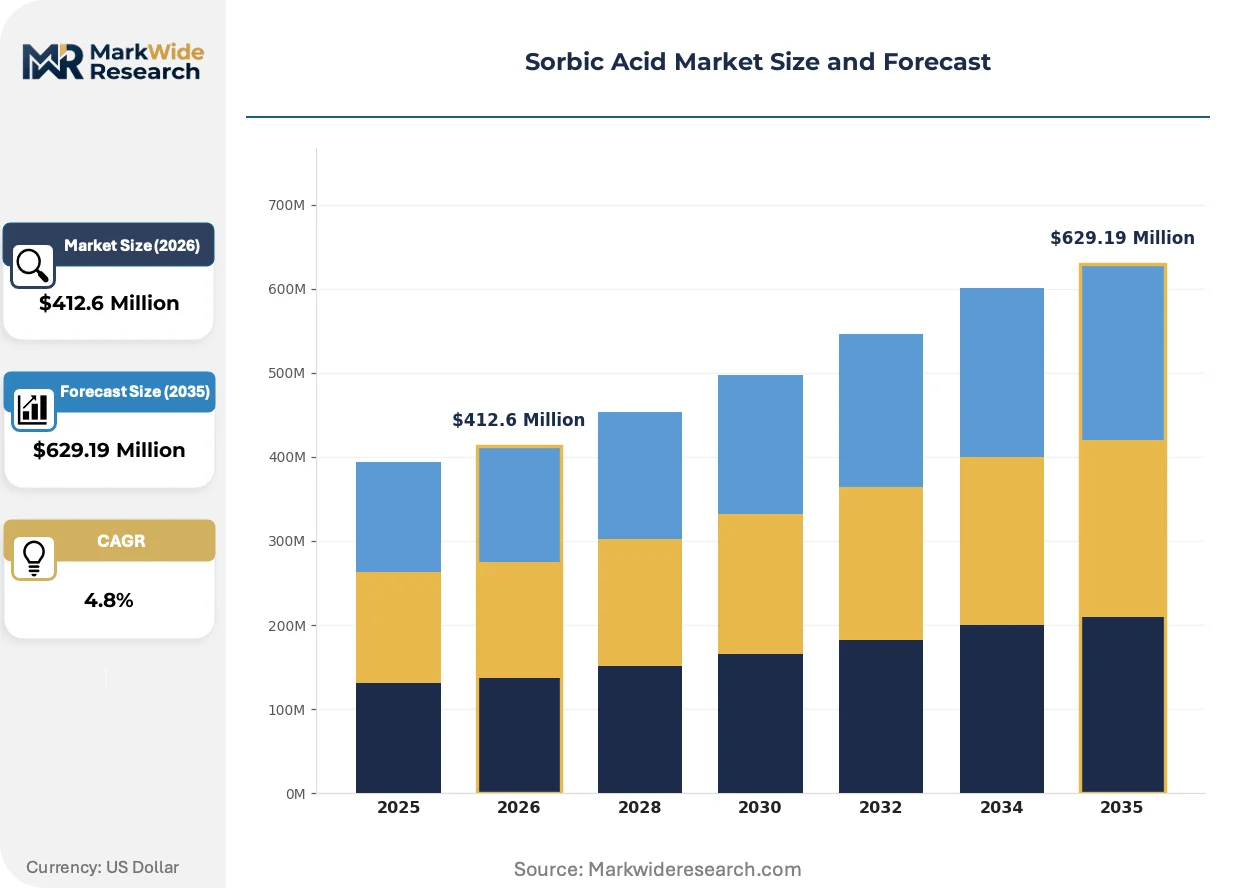
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Sorbates, Synthetic Sorbates, Potassium Sorbate, Calcium Sorbate Application: Food Preservation, Personal Care, Pharmaceuticals, Paints End User: Food & Beverage, Cosmetics, Healthcare, Chemical Manufacturing Distribution Channel: Online Stores, Distributors, Retail Outlets, Direct Sales |
| Companies Covered | Daicel Corporation, Shandong Hongda Group, Celanese Corporation, Jiangsu Mupro Ift Corp, Jinneng Science and Technology, Eastman Chemical Company, WEGO Chemical Group, Nantong Acetic Acid Chemical Co., Ltd., Wanglong Tech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorbic Acid Market Strategic Shifts
Continuous processing technology and bio-based feedstock development are restructuring sorbic acid manufacturing economics while regulatory data requirements intensify analytical capability investment.
Continuous ketene condensation reactor systems are displacing batch production configurations in integrated chemical complexes. Shandong province producers adopting flow chemistry platforms achieve tighter temperature control and reduced solvent recovery costs. This capital-intensive transition is compressing batch-operating regional competitors in eastern European and North American legacy facilities.
EFSA additive re-evaluation protocols under the 2021-2026 mandate cycle are tightening toxicological data submission requirements for existing preservative authorizations. European importers now face enhanced migration study obligations and purity certification demands that extend supplier qualification timelines. Pharmaceutical-grade sorbate manufacturers with pre-established EP compliance documentation capture accelerated access versus food-grade converters attempting segment migration.
Formulator procurement consolidation among multinational packaged food conglomerates is compressing supplier rosters and extending contract durations. Tier-one manufacturers now demand multi-year supply agreements with embedded price volatility clauses and dedicated inventory buffers. This concentration dynamic favors integrated producers with captive crotonaldehyde supply over merchant-market-dependent specialists, particularly visible in North American bakery and confectionery procurement patterns.
Sorbic Acid Market Segmentation
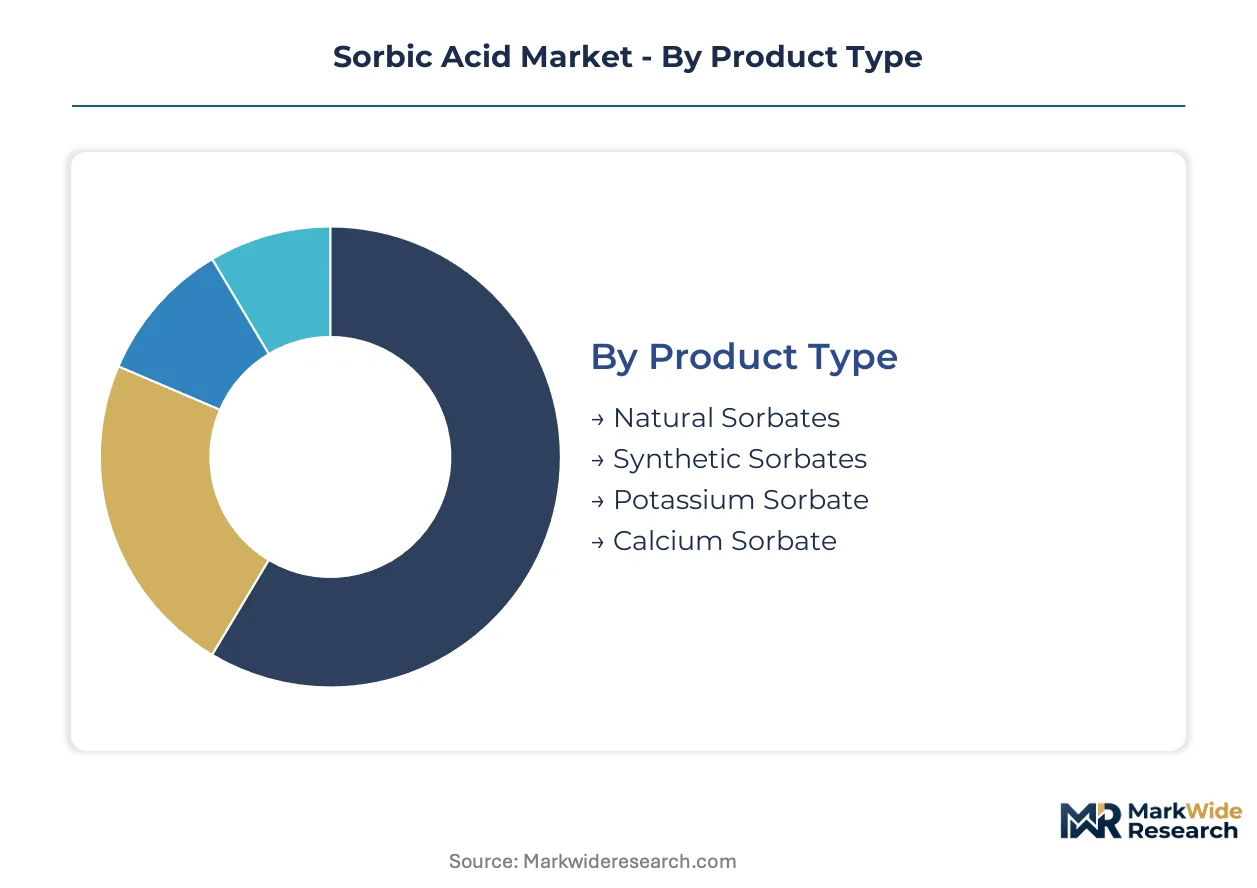
Sorbic acid market segmentation reveals how purity grades, regulatory compliance tiers, and supply chain configurations fragment commercial opportunity across distinct margin pools. Understanding these divisions clarifies why pharmaceutical-grade commands premium pricing while food-grade volumes anchor producer economics.
Product Type:
Margins concentrate sharply in pharmaceutical-grade synthetic sorbates where USP and EP monograph compliance creates supply scarcity, while natural extraction methods capture premium positioning in personal care despite volume constraints.
- Synthetic Sorbates:Ketene condensation with crotonaldehyde followed by oxidation yields industrial-scale output meeting FDA 21 CFR 182.3089 specifications. Food preservation demand in North American and European packaged goods manufacturing absorbs the majority of tonnage, though margin compression from Shandong province cost curves limits profitability for non-integrated producers.
- Potassium Sorbate:The potassium salt form delivers superior water solubility for beverage applications and acidic food systems requiring homogeneous distribution. Chinese chemical clusters in Jiangsu province dominate global supply, with formulation houses in Germany and the United States qualifying these sources against REACH migration study requirements and FDA GRAS maintenance protocols.
- Natural Sorbates:Rowanberry extraction yields botanical-provenance sorbates commanding formulation preference in premium European personal care brands with carbon-accounting sensitivity.
- Calcium Sorbate:Calcium salt variant finds niche application in reduced-sodium food formulations where potassium content requires substitution.
The dominant share belongs to Synthetic Sorbates, while Natural Sorbates is closing the gap fastest.
Application:
Cost tier stratification separates commodity food preservation from pharmaceutical-grade validation expenses, with personal care occupying a middle ground where botanical provenance justifies intermediate pricing.
- Food Preservation:Mold and yeast inhibition in acidic food systems represents the foundational demand driver, spanning bakery, dairy, and beverage sub-segments. FDA 21 CFR 182.3089 maximum use levels and EFSA additive re-evaluation protocols under the 2021-2026 mandate cycle force continuous purity investment, particularly for suppliers serving multinational packaged food conglomerates with consolidated procurement functions.
- Pharmaceuticals:USP and EP monograph standards for drug formulations mandate dedicated production lines with stainless-steel infrastructure and isolated packaging capabilities. Japanese and European manufacturers with pre-established compliance documentation capture accelerated access versus food-grade converters attempting segment migration.
- Personal Care:Premium cosmetic and skincare formulations leverage sorbic acid as a gentle preservative alternative to parabens, with natural-derived variants gaining traction.
- Paints:Industrial coating applications exploit antifungal properties in water-based formulations requiring in-can preservation.
Food Preservation retains volume leadership, though Pharmaceuticals delivers the steepest expansion trajectory in value terms.
End User:
Customer procurement sophistication varies dramatically, with healthcare and cosmetics sectors demanding certified batch documentation while chemical manufacturing prioritizes volume scale and feedstock integration.
- Food & Beverage:Multinational packaged food conglomerates drive procurement consolidation, extending contract durations and demanding multi-year supply agreements with embedded price volatility clauses. North American bakery and confectionery segments exhibit particularly concentrated buyer power.
- Healthcare:Pharmaceutical compounders and drug manufacturers require USP-compliant production suites with enhanced purity analytics, creating dedicated supplier relationships that insulate qualified vendors from food-grade margin cycles.
- Cosmetics:European personal care brands with sustainability commitments are piloting fermentation-derived sorbate pathways, opening bioprocess technology partnerships.
- Chemical Manufacturing:Industrial formulators and downstream derivative producers prioritize backward integration into acetic acid feedstock for cost position security.
Food & Beverage commands the dominant procurement volume, while Healthcare generates the most attractive margin profile.
Distribution Channel:
Digital disintermediation is restructuring mid-volume pharmaceutical compounder access, though bulk food-grade tonnage remains anchored in traditional distributor networks with regional inventory buffers.
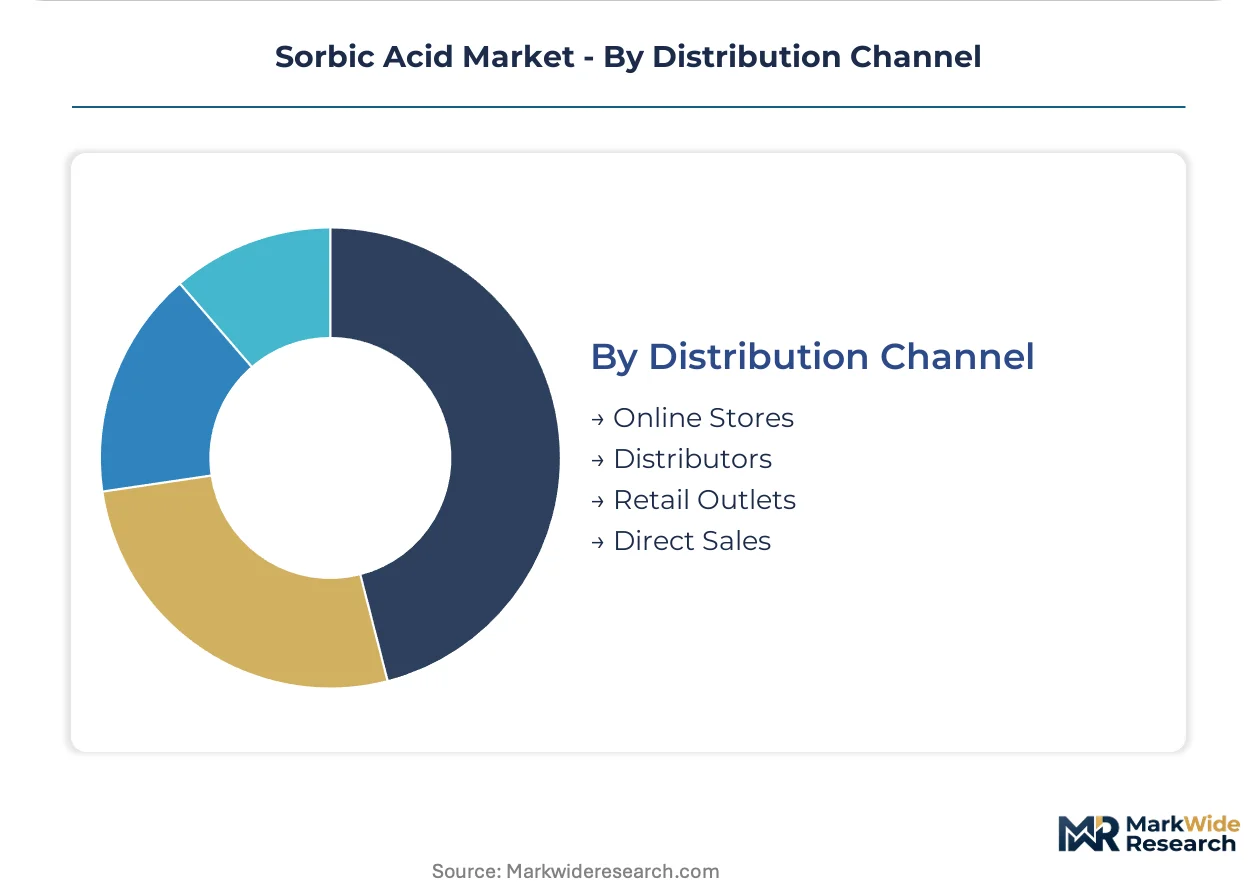
- Distributors:Traditional chemical distribution networks maintain dominance for food-grade volumes, offering regional warehousing and technical support services that multinational packaged food manufacturers require for just-in-time formulation operations.
- Direct Sales:Pharmaceutical-grade sorbate manufacturers with USP and EP compliance documentation bypass intermediary layers to serve drug formulators directly, capturing margin otherwise allocated to distribution.
- Online Stores:Specialty chemical platforms are emerging for mid-volume compounders seeking certified batches with transparent documentation.
- Retail Outlets:Small-scale food producers and artisanal formulators access sorbic acid through regional chemical supply retailers with limited technical service capabilities.
Distributors retain the dominant channel position, while Direct Sales is expanding most quickly in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese buyers exhibit extreme price elasticity in bulk food-grade procurement, while Japanese pharmaceutical compounders accept steep premiums for certified purity grades. European formulators occupy a middle tier where regulatory compliance costs filter through to moderate price sensitivity.
China
Shandong province chemical clusters supply the majority of global sorbic acid output through ketene-based production integrated with captive crotonaldehyde feedstock. SAMR food additive standards and GB quality specifications govern domestic use levels, though export-oriented producers prioritize FDA 21 CFR 182.3089 and REACH registration alignment for Western market access. Jiangsu province facilities concentrate on potassium sorbate salt variants for beverage applications.
United States
North American bakery and confectionery manufacturers drive consolidated procurement through multi-year supply agreements with embedded price volatility clauses. FDA GRAS maintenance under 21 CFR 182.3089 shapes maximum use levels in acidic food systems, while EPA oversight affects crotonaldehyde feedstock handling at integrated chemical complexes. Celanese Corporation anchors domestic synthetic sorbate capacity through backward integration into acetic acid production.
Germany
European pharmaceutical compounders demand USP and EP monograph compliance for drug formulation applications, creating premium demand pools with extended supplier qualification timelines. EFSA additive re-evaluations under the 2021-2026 mandate cycle force enhanced purity analytics and migration study investments. REACH registration requirements shape import access for non-EU manufacturers serving German formulators.
Japan
Pharmaceutical-grade specifications command the steepest regional premiums, with METI industrial standards overlapping PMDA drug substance requirements for formulation use. Daicel Corporation leverages domestic manufacturing infrastructure to supply high-purity grades with pre-established compliance documentation. Japanese buyers show minimal price elasticity for certified batches meeting dual USP-JP standards.
India
FSSAI clean-label adoption in processed dairy and bakery segments is opening formulation conversion opportunities as regulatory alignment with international preservative standards accelerates. Domestic packaged food manufacturers are shifting from benzoate-based systems toward sorbate alternatives under evolving safety guidelines. Maharashtra and Gujarat chemical processing hubs are qualifying suppliers against migration study requirements for export-oriented production.
Sorbic Acid Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with Japanese and European specialists commanding premium positioning through pharmaceutical-grade purity capabilities while Chinese integrated producers anchor global volume economics. The market structure concentrates around three strategic tiers: purity-certified specialists serving drug formulators, feedstock-integrated commodity producers, and regional distributors with technical service capabilities. Dominant competitive moves include backward integration into acetic acid or crotonaldehyde feedstock and dedicated production line investment for USP-compliant infrastructure.
Among Japanese specialists, Daicel Corporation exemplifies the pharmaceutical-grade archetype through domestic manufacturing infrastructure aligned with PMDA requirements. Shandong Hongda Group anchors the cost-driven tier as a Chinese integrated producer with ketene-based capacity in Shandong province. Celanese Corporation occupies a hybrid position as a US-based chemical conglomerate leveraging captive acetic acid supply for synthetic sorbate manufacturing.
| Leading Market Players |
|---|
| Daicel Corporation |
| Shandong Hongda Group |
| Celanese Corporation |
| Jiangsu Mupro Ift Corp |
| Jinneng Science and Technology |
| Eastman Chemical Company |
| WEGO Chemical Group |
| Nantong Acetic Acid Chemical Co., Ltd. |
| Wanglong Tech Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Shandong province ketene condensation facilities compresses regional cost curves below global benchmarks, concentrating supply-side pricing power among integrated producers while forcing merchant-market competitors toward marginal economics. This scale asymmetry propagates through to downstream formulation houses, where multinational packaged food conglomerates leverage consolidated procurement to extract contract concessions from non-integrated suppliers.
Pricing Analysis
FDA 21 CFR 182.3089 dictates the pricing tier structure across food-grade, pharmaceutical-grade, and personal care sorbate segments. Three-tier pricing stratifies across USP-certified premium batches for drug formulators, standard food-grade tonnage for bakery and dairy applications, and economy-grade industrial variants for coating preservation. Price differentiation hinges on purity certification level and dedicated production line investment, with pharmaceutical-grade capturing multiples over commodity food-grade despite lower volumes. Cost compression in Shandong-origin synthetic sorbates is intensifying because ketene-based flow chemistry platforms achieve tighter temperature control than legacy batch configurations. Food and beverage manufacturers exhibit extreme price sensitivity in bulk procurement, while Japanese pharmaceutical compounders show minimal elasticity for certified batches meeting dual USP-JP standards.
Supply Chain Analysis
Inventory buffers at European distributor warehouses extend lead times for REACH-registered pharmaceutical-grade batches versus direct-channel Asian sourcing. Geographic supply concentrates in China, Germany, and Japan, with Shandong and Jiangsu province chemical clusters anchoring global ketene-based output. Raw material dependencies rest on crotonaldehyde petrochemical derivatives, acetic acid feedstock, and rowanberry botanical extraction for natural variants. Single-source vulnerability from Shandong-Jiangsu concentration creates geopolitical and logistics exposure for global formulation houses dependent on just-in-time delivery. Distribution runs through traditional chemical distribution networks for food-grade volumes, while direct sales channels serve pharmaceutical compounders seeking certified batches with transparent documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clean-label reformulation mandates across FDA, EFSA, and FSSAI jurisdictions are transforming sorbic acid from commodity preservative to platform ingredient, with interoperability across regulatory compliance tiers determining supplier viability in consolidated procurement environments.
For Market Incumbents: Compound defensive positioning through backward integration into captive crotonaldehyde supply and dedicated USP-compliant production line investment. Shandong Hongda Group anchors global volume through ketene-based integration, while Daicel Corporation defends pharmaceutical-grade premiums through PMDA-aligned domestic infrastructure. Threat from benzoate substitution in high-pH applications demands purity analytics differentiation and migration study documentation to maintain formulation lock-in. For New Entrants and Emerging Players: Anchor in fermentation-derived bioprocess pathways approaching pilot-scale viability for carbon-accounting-sensitive European personal care brands. White-space targets include India FSSAI-aligned processed dairy conversion and mid-volume pharmaceutical compounder digital channel access. Go-to-market leverage rests on specialty chemical platform partnerships disintermediating traditional distributor networks for certified batch procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors pharmaceutical-grade purity specialists with pre-established EP compliance documentation over food-grade converters attempting segment migration. Long-term viability across the analysis window hinges on regulatory data package depth and stainless-steel infrastructure depreciation timelines. Acquisition target archetype: integrated producers with captive feedstock and multi-jurisdiction compliance staffing. Signal to watch: EFSA additive re-evaluation protocol outcomes under the 2021-2026 mandate cycle forcing purity investment upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive crotonaldehyde supply secures margin stability against petrochemical derivative volatility. |
| USP-Compliant Infrastructure | Stainless-steel production suites and isolated packaging lines unlock pharmaceutical-grade premium pools. |
| Bioprocess Development | Fermentation-derived pathways align with European personal care carbon-accounting commitments. |
| Digital Channel Expansion | Specialty chemical platforms disintermediate distributors for mid-volume compounder access. |
| Multi-Jurisdiction Compliance | Simultaneous FDA GRAS, REACH registration, and EFSA maintenance defends qualified supplier status. |
Study Parameters
A spread of perspectives from plant managers at ketene condensation facilities, procurement leads at multinational packaged food manufacturers, pharmaceutical compounder quality directors, and distribution channel partners converged on the working assumptions. Primary interviews combined with secondary validation from customs and trade data, SEC 10-K filings of listed chemical conglomerates, ACC and Cefic industry reports, and FDA GRAS notification databases. Bottom-up capacity and utilization estimates triangulated against top-down demand modeling from end-use consumption patterns.
Segmentation dimensions modeled span grade tier (food-grade, pharmaceutical-grade, natural extraction), end-use industry (food preservation, pharmaceuticals, personal care, paints), packaging format (bulk industrial, certified batch, retail), and regional production hub (Shandong province, Jiangsu province, North American integrated complexes, European REACH-registered facilities). CAGRs derived from capacity expansion pipelines, regulatory conversion timelines, and substitution elasticity estimates across benzoate-competitive applications. Industry-specific forecast inputs include crotonaldehyde feedstock pricing volatility and EFSA re-evaluation protocol compliance cost trajectories.
Material uncertainties — feedstock price swings, geopolitical disruption to Shandong-Jiangsu supply corridors, and EFSA safety profile revision outcomes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory alignment continuity and clean-label adoption velocity in emerging markets. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
2-Nitrothiophene Market
Bulk Chemicals
Cobalt (II) Sulfate Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
China Starch and Starch Derivatives Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Cyclamate Market
Bulk Chemicals
Barite Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Global Concentrated Nitric Acid Market